
 Food Authentication Testing Market | 2026-2036
Food Authentication Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Food Authentication Testing Market Analysis
Software-defined assay platforms is pivoting how laboratories contract authentication services, converting fixed equipment costs into per-test subscriptions. Eurofins Scientific leverages its distributed laboratory network to sustain high-throughput DNA barcoding capacity across multiple continents. SGS SA anchors its competitive position through specialized meat speciation protocols that comply with evolving regulatory requirements. Thermo Fisher Scientific dominates the PCR reagent supply layer, controlling critical consumables that laboratories depend upon for routine authenticity verification.
Food authentication testing encompasses analytical methodologies that verify declared identity, origin, and purity of food products through molecular, spectroscopic, or chromatographic detection of species-specific markers, adulterants, and contaminants. These systems operate at detection thresholds ranging from species-level identification to quantification of dilution percentages in processed matrices, serving industrial needs for regulatory compliance, brand protection, and supply chain integrity. LC-MS protocols command premium pricing in the testing method dimension due to their superior resolution for complex protein and metabolite fingerprinting, while rapid testing technologies represent the fastest-expanding technology category as food manufacturers seek point-of-need screening to reduce quarantine times. Blockchain-enabled traceability sits at an early stage with concentrated pilot activity among vertically integrated retailers pursuing end-to-end provenance documentation.
FDA enforcement of the Food Safety Modernization Act intensifies demand for documented authenticity verification at import checkpoints, while EFSA mandates under the EU Official Controls Regulation require member states to maintain reference laboratories with accredited species identification capabilities. REACH chemical traceability requirements and ISO 17025 laboratory accreditation standards further shape market access by defining acceptable analytical performance thresholds. Stakeholders must monitor how regulatory convergence between major food import jurisdictions affects harmonization of method validation protocols and cross-border mutual recognition of test results.
Market Dynamics
Software-defined assay platforms are converting fixed laboratory equipment costs into per-test subscriptions, fundamentally altering how food manufacturers contract authentication services and compressing capital barriers for mid-tier processors.
Growth Catalysts
- EFSA traceability mandates:European food manufacturers are expanding DNA barcoding programs to comply with evolving authenticity verification requirements under the EU Official Controls Regulation.
- Point-of-need screening:Rapid testing technologies are gaining traction as Chinese dairy importers seek to reduce quarantine times under tightened SAMR authenticity protocols.
- PCR reagent standardization:Thermo Fisher Scientific's control over critical consumables creates predictable supply chains for routine authenticity verification workflows.
Market Restraints
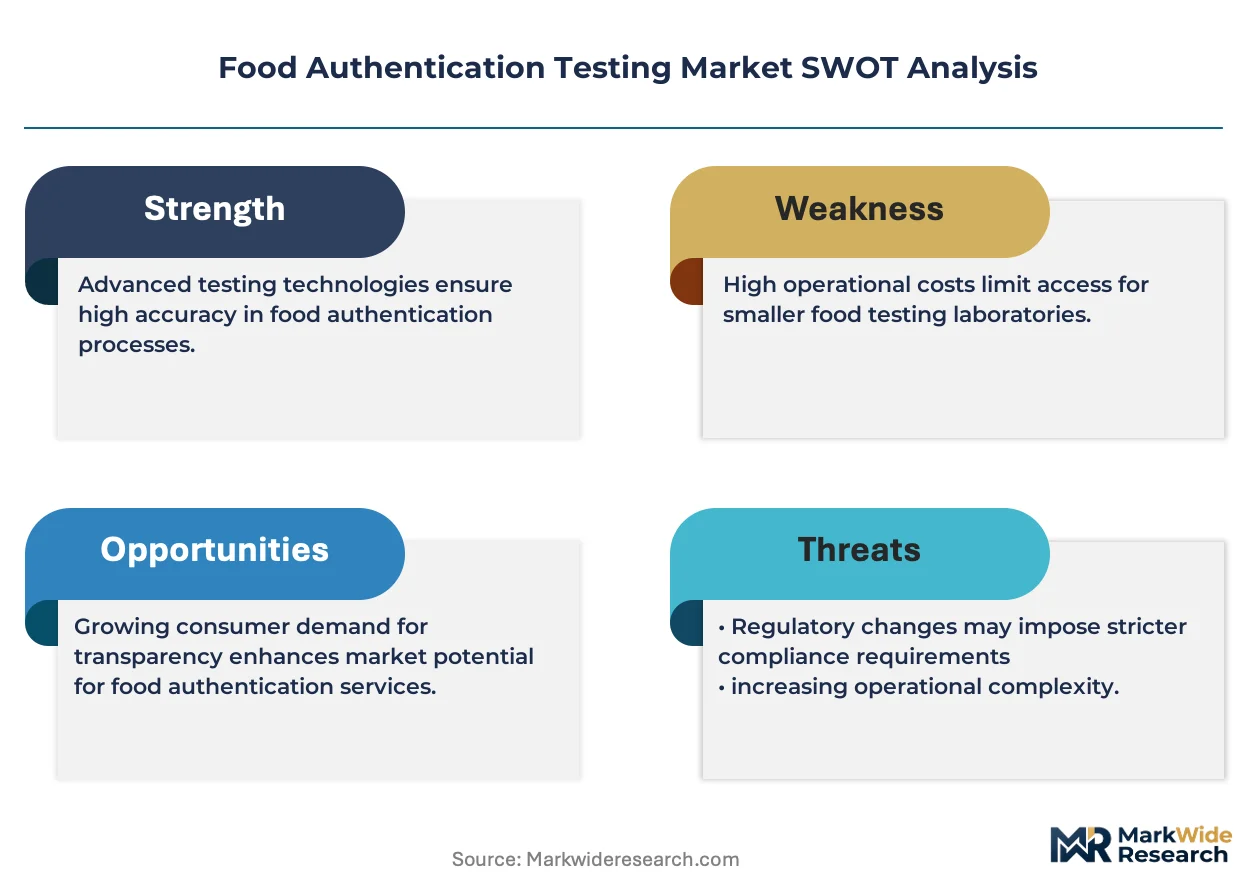
- LC-MS equipment costs:Complex protein and metabolite fingerprinting protocols require capital-intensive instrumentation that limits adoption among smaller testing laboratories.
- Reference laboratory concentration:EFSA-mandated accredited species identification capabilities concentrate in established European testing hubs, creating geographic access disparities.
- Blockchain pilot fragmentation:Vertically integrated retailers dominate early-stage traceability pilots, leaving mid-market processors without provenance documentation pathways.
Strategic Opportunities
- Subscription assay platforms:Per-test pricing models open authentication services to processors previously excluded by equipment purchase requirements.
- Meat speciation specialization:Evolving regulatory requirements create white space for laboratories developing species-specific protocols beyond standard DNA barcoding.
- Import checkpoint automation:FDA Food Safety Modernization Act enforcement intensifies demand for documented authenticity verification at US border facilities.
Industry Challenges
- ISO 17025 accreditation timelines:Method validation protocol harmonization across jurisdictions delays laboratory market entry and cross-border mutual recognition.
- Legacy system integration:Existing laboratory information management systems require reconfiguration to accommodate software-defined assay workflows and subscription billing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Authentication Testing Market |
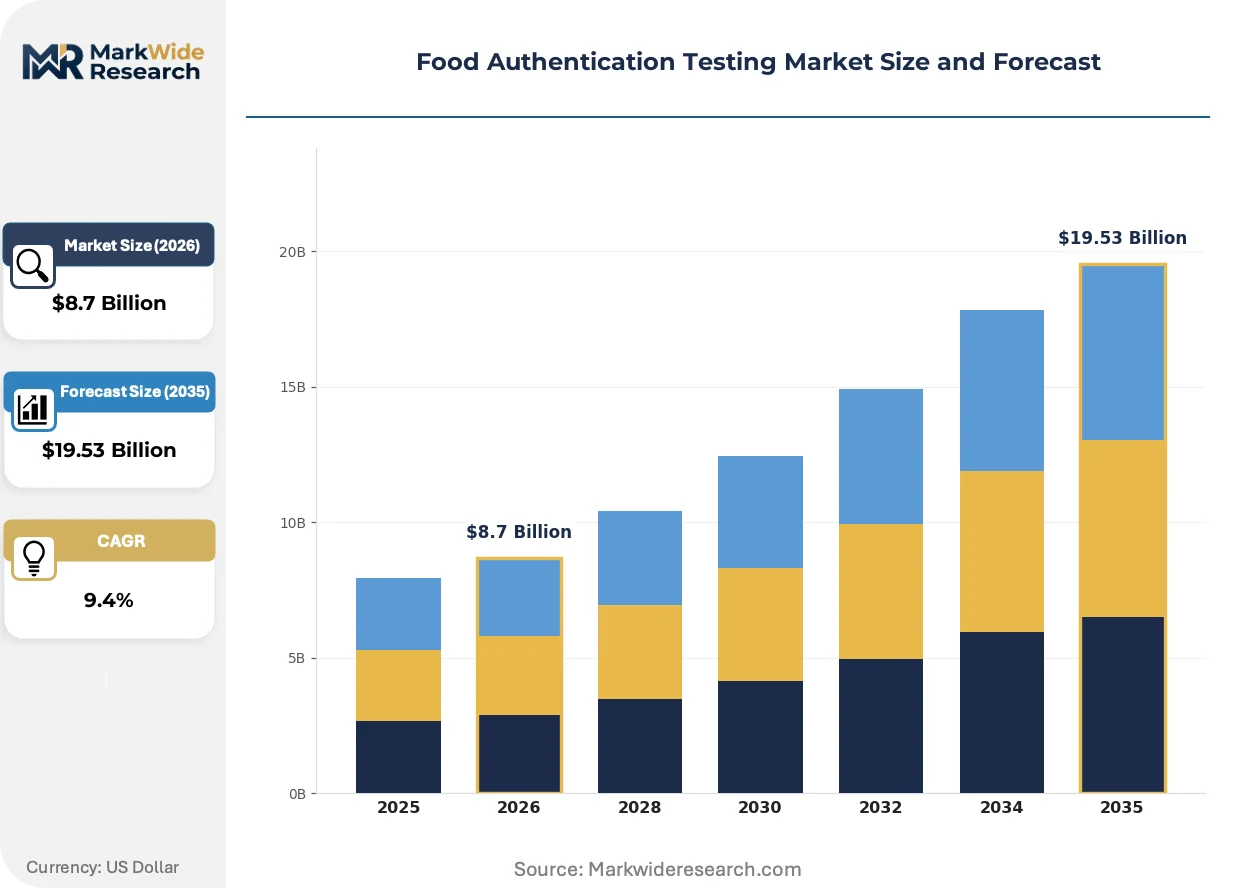
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Method: DNA Barcoding, Spectroscopy, LC-MS, PCR Sample Type: Meat, Dairy, Fruits, Grains End User: Food Manufacturers, Regulatory Bodies, Research Institutions, Retailers Technology: Rapid Testing, On-Site Testing, Lab-Based Analysis, Blockchain |
| Companies Covered | Eurofins Scientific, SGS SA, Intertek Group plc, Mérieux NutriSciences, ALS Limited, EMSL Analytical, Inc., Thermo Fisher Scientific, Bureau Veritas, Neogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Authentication Testing Market Emerging Trajectories
Authentication testing is migrating from centralized reference laboratories toward distributed, software-enabled screening points that compress turnaround times and reduce sample logistics costs for food manufacturers.
Portable spectrometry combined with cloud-based spectral libraries is decentralizing species identification capabilities from fixed laboratory sites to production facilities and import checkpoints. Mid-sized meat processors in Germany and the Netherlands are adopting handheld devices for rapid raw material screening. This technology is decentralizing quality control authority from third-party laboratories to in-house technical teams, compressing the traditional outsourcing model.
REACH chemical traceability requirements are forcing food contact material manufacturers to document authentication testing for packaging substrates that could migrate into edible products. Industrial consequence includes expanded testing scope beyond food matrices to encompass primary and secondary packaging. European dairy exporters are responding by integrating packaging authentication into existing supply chain verification protocols.
Retailer-led consortiums are consolidating procurement of authentication services around vertically integrated traceability platforms that bundle testing with blockchain documentation. Foodservice distributors and private-label manufacturers face exclusion from these closed networks. This concentration is most visible in Northern European markets where ICA Group and similar retail alliances dominate shelf-space negotiations.
Food Authentication Testing Market Segmentation
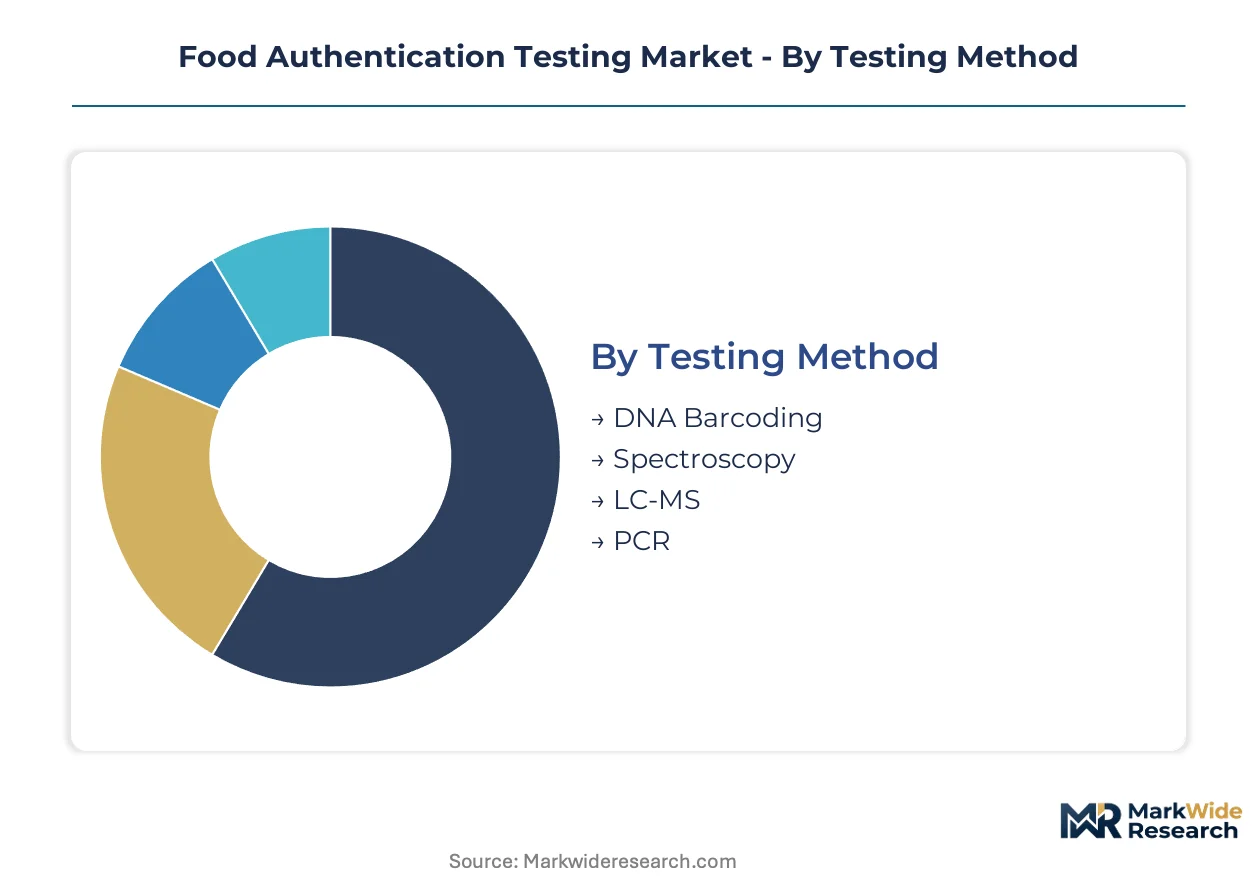
Authentication testing demand fragments across methodological capabilities, sample matrices, and deployment architectures. Laboratories and food processors select segments based on regulatory mandate specificity, capital availability, and turnaround requirements.
Testing Method:
DNA barcoding operates as a standalone verification layer requiring dedicated sequencing infrastructure, while PCR embeds into routine laboratory workflows as a consumable-driven process.
- DNA Barcoding:Mitochondrial gene sequencing delivers species-level identification with reference database matching against standardized barcode regions. European meat processors deploy this method to satisfy EFSA traceability mandates for supply chain documentation. Demand concentrates in contract laboratories serving multiple mid-tier food manufacturers lacking in-house sequencing capacity.
- Spectroscopy:Infrared and Raman techniques provide non-destructive fingerprinting of molecular composition without sample preparation. German dairy cooperatives integrate handheld near-infrared devices at receiving bays to screen milk powder authenticity before unloading. Equipment portability drives placement at import checkpoints and production facilities rather than centralized labs.
- LC-MS:Liquid chromatography-mass spectrometry couples separation science with high-resolution detection for complex protein and metabolite analysis.
- PCR:Polymerase chain reaction amplifies species-specific DNA sequences through thermal cycling with fluorescent endpoint detection.
Volume placements concentrate in PCR workflows; the faster expansion belongs to spectroscopy portability.
Sample Type:
Meat and dairy categories command premium testing expenditure due to high-value adulteration incentives, while grains operate on thinner margins with commodity-scale volume.
- Meat:Speciation testing detects fraudulent substitution of premium cuts with lower-value species or undeclared offal incorporation. Dutch pork processors run DNA verification on every incoming batch following 2013 European horsemeat scandal enforcement. Regulatory reference laboratory accreditation requirements under EU Official Controls Regulation sustain method standardization investments.
- Dairy:Protein profiling distinguishes milk origins and detects dilution with plant-based alternatives or water. Chinese importers deploy rapid protein assays at ports under tightened SAMR authenticity protocols for infant formula ingredients. Melamine screening history drives persistent surveillance infrastructure in Asian supply chains.
- Fruits:Sugar content and varietal authentication testing protects premium produce designation integrity.
- Grains:Gluten species identification and mycotoxin co-testing addresses cereal commodity verification needs.
Testing revenue concentrates in meat speciation; dairy applications are climbing the fastest.
End User:
Food manufacturers internalize testing through captive laboratories or equipment subscriptions, while regulatory bodies maintain reference capabilities for dispute resolution.
- Food Manufacturers:Brand protection investments drive authentication spending at processing facilities and supplier qualification stages. French charcuterie houses operate in-house PCR screening to verify raw material provenance claims before production. Software-defined assay platforms convert fixed equipment costs into per-test subscriptions accessible to mid-tier processors.
- Regulatory Bodies:Government laboratories maintain accredited reference methods for enforcement sampling and private laboratory audit. FDA field laboratories deploy standardized species identification protocols at US import checkpoints under Food Safety Modernization Act enforcement. EFSA-mandated capabilities concentrate in established European testing hubs with ISO 17025 accreditation.
- Research Institutions:Academic laboratories develop novel marker panels and validate emerging detection technologies.
- Retailers:Private-label quality teams and vertically integrated chains source authentication for shelf-edge provenance claims.
Procurement volume concentrates in food manufacturer quality departments; regulatory outsourcing is gaining share fastest.
Technology:
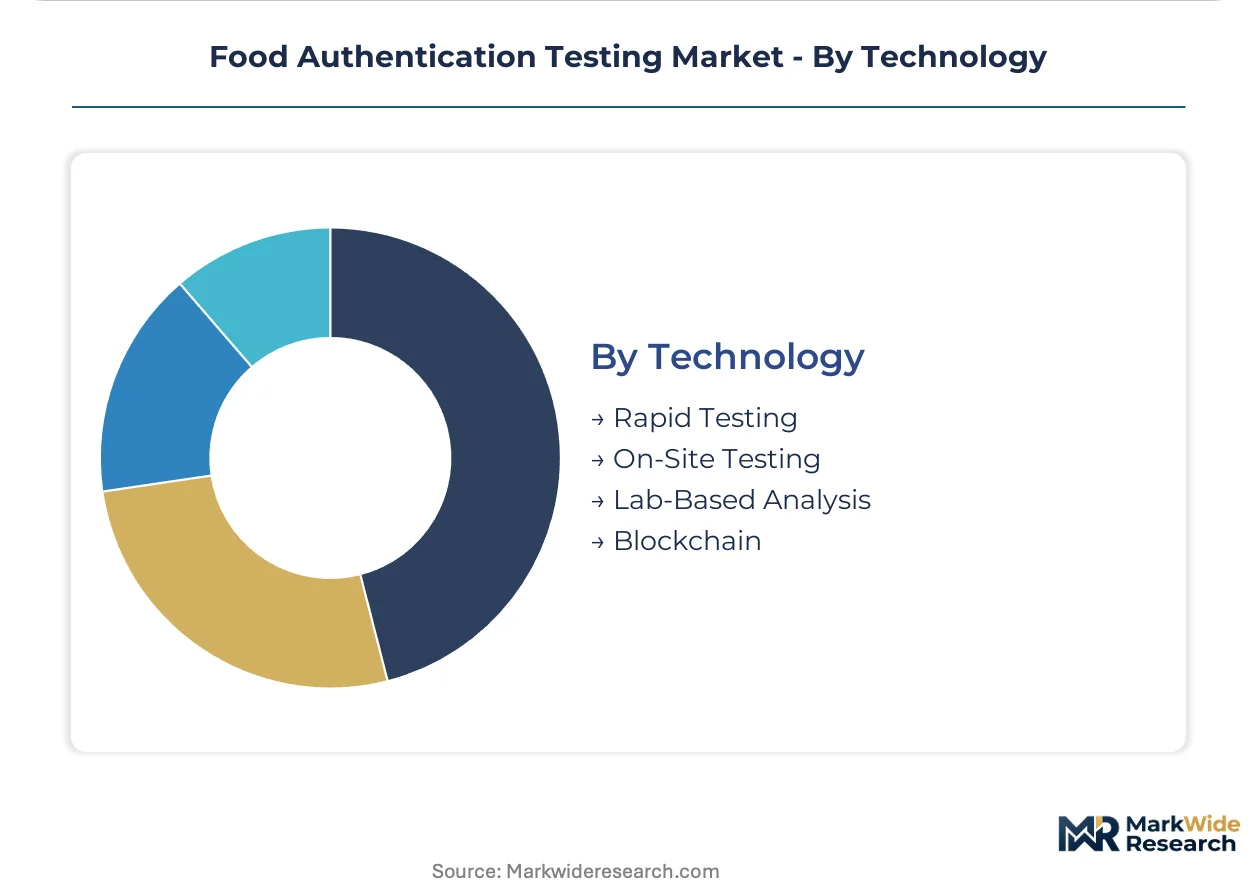
Rapid testing and on-site deployment models displace traditional laboratory submission workflows, while blockchain traceability remains pilot-stage with concentrated retailer investment.
- Rapid Testing:Lateral flow immunoassays and portable molecular devices deliver qualitative results within minutes without climate-controlled laboratory infrastructure. Brazilian beef exporters deploy handheld protein tests at slaughterhouse loading docks to pre-clear shipments for Chinese port entry. Turnaround compression justifies per-unit cost premiums over laboratory submission models.
- On-Site Testing:Containerized or mobile laboratory units bring accredited capabilities to remote production locations and border facilities. Australian wine exporters operate mobile spectrometry units for vintage authentication at multiple cellar door locations. Capital efficiency favors rental and service contracts over permanent facility construction.
- Lab-Based Analysis:Centralized reference laboratories maintain comprehensive method portfolios and accreditation scope.
- Blockchain:Distributed ledger documentation links authentication test results to immutable supply chain records.
Equipment placements concentrate in lab-based analysis; on-site deployment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing demand concentrates in importing jurisdictions with stringent authenticity mandates, while laboratory capacity clusters in established regulatory hubs. Production of analytical instrumentation remains concentrated among German, American, and Japanese manufacturers. Consumption patterns split between import checkpoint surveillance and domestic supply chain verification.
United States
FDA enforcement of the Food Safety Modernization Act drives sustained investment in documented authenticity verification at border facilities. USDA and FDA coordinate species identification protocols for meat and dairy imports. Greater Boston hosts specialized contract laboratories serving pharmaceutical-grade food ingredient manufacturers.
Germany
Mitochondrial gene sequencing capacity expanded following 2013 horsemeat scandal enforcement and sustained EFSA traceability mandates. REACH chemical traceability requirements extend authentication testing scope to food contact materials. Bavarian meat processors operate captive PCR screening for raw material qualification.
China
SAMR tightened authenticity protocols for imported dairy products after melamine screening history, compressing quarantine timelines. National food safety regulators mandate rapid testing deployment at major port facilities. Yangtze River Delta dairy importers adopted handheld protein assays to pre-clear infant formula ingredients.
Netherlands
Dutch pork processors run DNA verification on every incoming batch under EU Official Controls Regulation reference laboratory requirements. Rotterdam port facilities maintain mobile spectrometry units for rapid raw material screening. Wageningen academic cluster develops novel marker panels for emerging adulterant detection.
Australia
Wine exporters deploy mobile spectrometry units for vintage authentication at multiple cellar door locations under competitive pressure from European protected designation claims. TGA-aligned laboratory accreditation supports export certification for Asian markets. Barossa Valley cooperatives adopted subscription assay platforms to reduce capital barriers.
Food Authentication Testing Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the authentication testing landscape. Full-service contract laboratories with distributed sequencing infrastructure face competition from specialized protocol developers and equipment manufacturers. Three archetypes dominate: integrated testing networks with global accreditation, technology vendors controlling consumables supply, and regional specialists with species-specific expertise. Consolidation pressures intensify through laboratory network expansion and strategic consumables partnerships.
Within the integrated network tier, Eurofins Scientific and SGS SA exemplify geographically distributed accreditation models. Thermo Fisher Scientific occupies a position anchoring the consumables supply layer. These three entities represent contrasting strategic positions: testing service aggregation, regulatory compliance breadth, and workflow dependency creation.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS SA |
| Intertek Group plc |
| Mérieux NutriSciences |
| ALS Limited |
| EMSL Analytical, Inc. |
| Thermo Fisher Scientific |
| Bureau Veritas |
| Neogen Corporation |
| Others |
Supply Flow & Price Mechanics
Captive sequencing infrastructure at major contract laboratories anchors both supply security and pricing power for high-throughput DNA barcoding services. Eurofins Scientific and SGS SA leverage distributed laboratory networks to convert fixed equipment costs into per-test subscriptions, compressing capital barriers for mid-tier food processors while sustaining premium pricing for accredited reference methods under EFSA mandates.
Pricing Analysis
Cost-down pressure on routine PCR workflows accelerates as Thermo Fisher Scientific standardizes reagent pricing across consumables supply tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited reference laboratories from rapid screening providers and unaccredited point-of-need device operators. Quality grade and certification level drive price differentiation, with EFSA-mandated species identification commanding substantial premiums over portable spectroscopy screening. Mid-tier meat processors exhibit highest price sensitivity, while pharmaceutical-grade food ingredient manufacturers absorb premium pricing for documented chain-of-custody protocols.
Supply Chain Analysis
Dual-sourcing requirements for critical PCR reagents and sequencing consumables force laboratories to qualify multiple suppliers against ISO 17025 validation protocols. Germany, the United States, and Japan concentrate production of analytical instrumentation and thermal cycling equipment. Raw material dependencies center on fluorescent probe chemistries, polymerase enzymes, and certified reference DNA materials. Single-source vulnerability persists for specialized mitochondrial primer sets validated against EFSA barcode databases. Distribution runs through direct laboratory service contracts and equipment manufacturer channel partnerships rather than traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined assay platforms are displacing fixed-equipment laboratory workflows, creating transition-phase investment priorities for stakeholders positioning across authentication testing value chains.
For Market Incumbents: Hedge against margin compression in centralized reference testing by acquiring portable spectroscopy device manufacturers and securing subscription platform technology. Consolidate accreditation scope across multiple jurisdictions to defend against emerging regional specialists under EFSA mutual recognition expansion. Backward integration into consumables production reduces dependency on Thermo Fisher Scientific supply terms. For New Entrants and Emerging Players: Mid-sized dairy processors in China's Yangtze River Delta represent underserved buyers lacking in-house screening capabilities for SAMR port clearance protocols. Target meat speciation specialization beyond standard DNA barcoding to capture white space from evolving species substitution detection requirements. Deploy rapid testing-as-a-service models at import checkpoints to bypass capital-intensive laboratory infrastructure buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated testing networks seeking geographic accreditation expansion. Five-to-ten-year viability hinges on regulatory convergence between FDA and EFSA method validation protocols. Watch for SAMR authentication mandate expansion beyond dairy into meat and grain categories as inflection signal for Chinese market infrastructure investment.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Assay Platform Launch | Converts fixed equipment costs into per-test pricing accessible to mid-tier processors. |
| Accreditation Expansion | Extends ISO 17025 scope across multiple jurisdictions under EFSA mutual recognition. |
| Portable Device Integration | Decentralizes quality control authority from third-party laboratories to in-house teams. |
| Consumables Supply Agreement | Secures predictable PCR reagent flows for routine authenticity verification workflows. |
| Blockchain Traceability Pilot | Links authentication results to immutable supply chain records for retailer consortiums. |
Methodological Framework
Document review covered regulatory filings from FDA, EFSA, and SAMR, complemented by interviews with laboratory operations directors, food manufacturer quality managers, PCR equipment procurement officers, and contract testing sales executives. Secondary validation drew from ISO 17025 accreditation databases, EU Official Controls Regulation implementation reports, and customs authentication testing volume records. Bottom-up segmentation modeling triangulated against top-down market sizing from instrument manufacturer shipment disclosures.
Segmentation outputs across testing method, sample matrix, deployment architecture, and end-user category fed into analytical framework projections over the analysis window. CAGRs derived from instrument placement trajectories, reagent consumption patterns, and regulatory mandate expansion timelines. Industry-specific inputs included EFSA reference laboratory capacity buildout schedules and SAMR port facility rapid testing deployment mandates.
Revisions become necessary when regulatory convergence accelerates or stalls, when blockchain traceability pilots achieve scaled deployment, or when portable device accuracy achieves parity with laboratory reference methods. Deviation in FDA Food Safety Modernization Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Xylose Absorption Tests Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
Adulteration Tester Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
Food Testing Kits Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
Mercury Testing Service Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Central & South America Food Safety Testing Market