
 Saudi Arabia Hajj Tourism Market | 2026-2036
Saudi Arabia Hajj Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Hajj Tourism Market Analytics
SFDA hospitality licensing requirements and MOHAP health certification protocols is restructuring the cost-of-entry calculus for new service providers seeking to operate near the holy sites. Saudi Arabian Airlines sustains dominant airlift capacity through its dedicated Hajj terminal infrastructure at King Abdulaziz International Airport. Seera Group leverages integrated digital booking platforms to capture pilgrimage flows across multiple customer touchpoints. Elaf Group anchors its competitive position through controlled inventory of properties in the Makkah central zone.
Hajj tourism encompasses the organized provisioning of travel, lodging, nourishment, guided rituals, and logistical coordination for Muslims performing the annual pilgrimage to Makkah, requiring compliance with Saudi-specific operational permits and health screening protocols. The service type dimension splits across travel packages, accommodation services, food services, and tour guides, with accommodation services commanding the dominant margin pool due to finite room inventory within the Haram proximity zone. Customer type segmentation spans individual pilgrims, group tours, family packages, and corporate clients, where group tours generate the highest volume throughput and operational predictability for suppliers.
MOHAP enforces mandatory meningococcal vaccination verification and health screening standards that shape entry eligibility and demand timing for prospective pilgrims. The Saudi Commission for Tourism and National Heritage, now integrated under the Ministry of Tourism, sets facility classification criteria and pricing transparency rules that govern service category tiers from budget through luxury. Stakeholders must monitor visa quota allocations, Nusuk platform integration mandates, and evolving sustainability requirements for pilgrimage infrastructure development.
Market Dynamics
Saudi Vision 2030 visa liberalization is compressing pilgrimage planning cycles while expanding annual capacity ceilings, forcing accommodation providers to reconfigure inventory management systems for shorter booking windows and higher throughput volatility.
Growth Catalysts
- Nusuk Platform Integration Mandate:The unified digital pilgrimage portal streamlines visa-to-accommodation workflows, reducing administrative friction for group tour operators and accelerating booking velocity for Indonesian and Pakistani source markets.
- SFDA Hospitality Licensing Reforms:Standardized facility classification criteria near the Grand Mosque enable clearer tier positioning, allowing mid-range properties to capture pilgrims upgrading from budget segments through transparent quality signaling.
- MOHAP Vaccination Protocol Harmonization:Meningococcal verification digitization through linked health certificates reduces border processing delays, compressing arrival-to-settlement timelines and extending effective pilgrimage season length.
Market Restraints
- Finite Haram Proximity Inventory:Physical land constraints within walking distance of the Grand Mosque cap room supply expansion, concentrating pricing power among incumbent property holders and elevating entry barriers for new hospitality investors.
- Visa Quota Allocation Rigidity:Country-specific pilgrimage caps negotiated through bilateral agreements with Indonesia, Pakistan, and other source markets create demand volatility that complicates multi-year capacity planning for service providers.
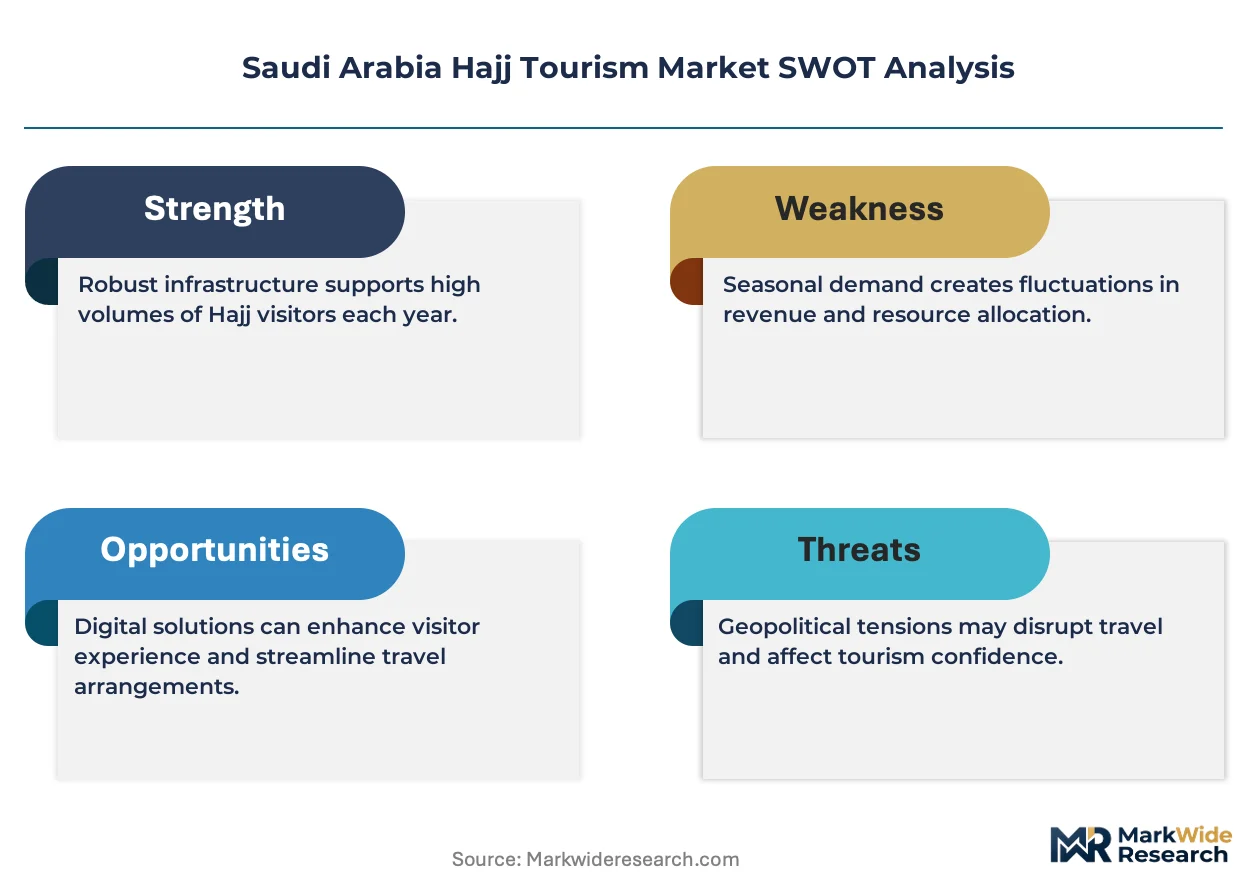
- Seasonal Revenue Concentration:Hajj's fixed Islamic calendar timing compresses revenue realization into narrow annual windows, forcing operators to absorb eleven months of fixed costs against thirty days of peak yield realization.
Strategic Opportunities
- Umrah Season Extension:The nine-month non-Hajj pilgrimage period remains underpenetrated by integrated package providers, offering volume diversification for operators capable of repositioning Hajj-optimized assets toward year-round religious tourism flows.
- Secondary City Accommodation Development:Jeddah and Madinah property clusters outside Makkah's central zone present lower land-acquisition costs for developers willing to absorb shuttle logistics complexity in exchange for margin expansion.
- Sustainability Certification Differentiation:Emerging Ministry of Tourism environmental compliance frameworks for pilgrimage infrastructure create early-mover positioning for properties achieving carbon-neutral operations ahead of mandated thresholds.
Industry Challenges
- Multilingual Guide Certification Bottlenecks:Tour guide licensing through the Saudi Commission for Tourism and National Heritage requires Arabic proficiency and ritual knowledge verification, constraining supply expansion for Indonesian, Urdu, and Malay-speaking guide services.
- Legacy Property Management System Integration:Older Makkah hotels face technical debt burdens when connecting inventory to Nusuk's real-time booking API, requiring capital deployment for middleware development or full-stack replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Hajj Tourism Market |
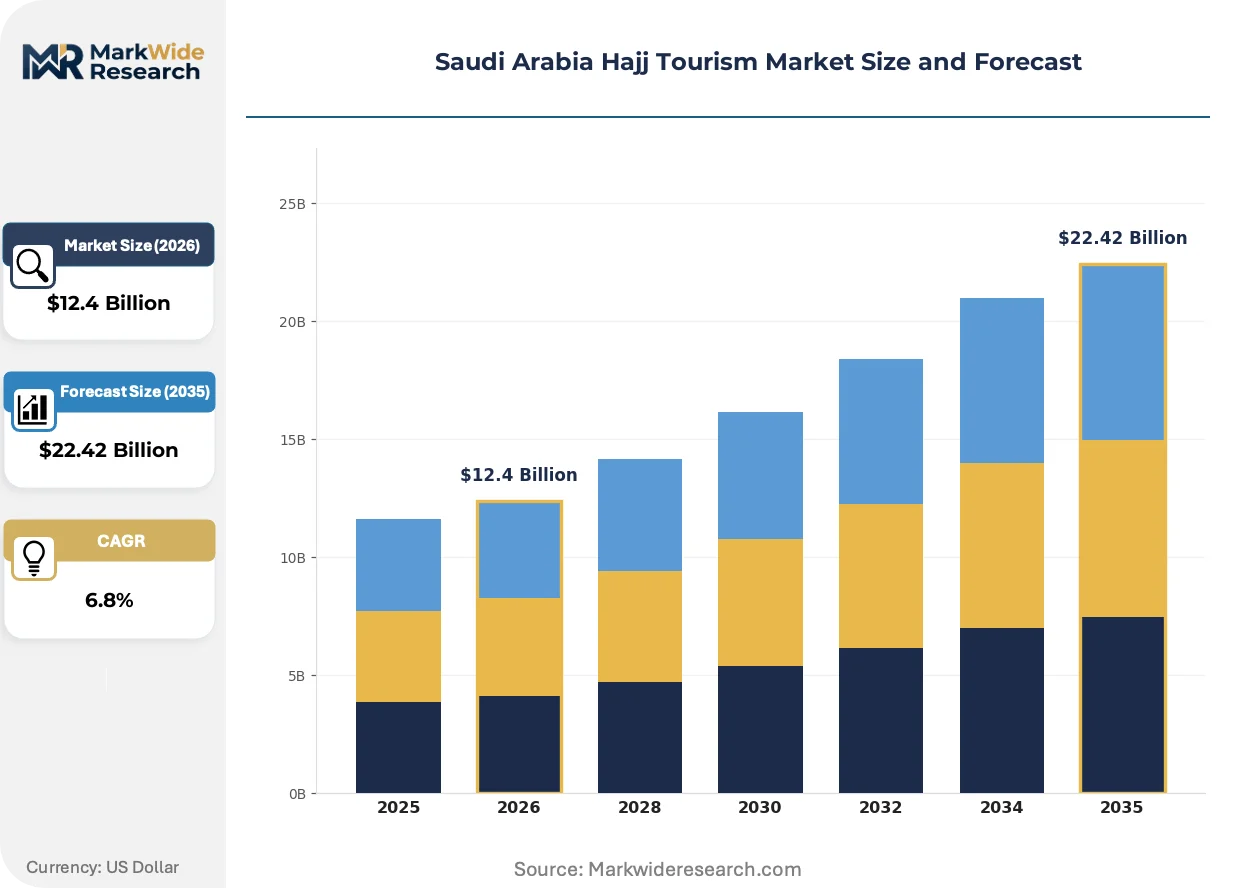
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Travel Packages, Accommodation Services, Food Services, Tour Guides Customer Type: Individual Pilgrims, Group Tours, Family Packages, Corporate Clients Booking Channel: Online Booking, Travel Agencies, Direct Booking, Mobile Apps Service Category: Luxury Services, Mid-range Services, Budget Services, Others |
| Companies Covered | Al Tayyar Travel Group, Saudi Arabian Airlines, Zahid Travel Group, Elaf Group, Seera Group, InterContinental Hotels Saudi Arabia, Wyndham Hotel Group Saudi Arabia, Avis Saudi Arabia, Saddik & Mohammed Attar Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Hajj Tourism Market Evolving Landscape
Digital infrastructure deployment is compressing coordination costs across pilgrimage value chains while regulatory transparency mandates reshape competitive positioning criteria for accommodation and transport providers.
AI-powered demand forecasting is absorbing historical booking pattern analysis to optimize room allocation across the thirty-day Hajj window. Group tour operators deploy these tools to anticipate nationality-specific arrival clustering and pre-position inventory. The technology is absorbing revenue leakage from last-minute cancellation gaps that previously forced distressed discounting.
MOHAP health certification digitization mandates are eliminating paper-based vaccination verification at King Abdulaziz International Airport. Linked biometric health records accelerate immigration processing and reduce terminal congestion during peak arrival surges. Accommodation providers in Makkah's central district face the steepest compliance timelines given their proximity to the highest-volume entry corridors.
Pilgrim preference is fragmenting away from standardized group packages toward modular service unbundling. Individual travelers from Southeast Asia now separately procure flights through airline direct channels, accommodation through property websites, and ground transport through ride-hailing platforms. This disintermediation is most pronounced among repeat pilgrims from Indonesia's urban professional segments who possess sufficient Arabic language skills to navigate independent logistics coordination.
Saudi Arabia Hajj Tourism Market Segmentation
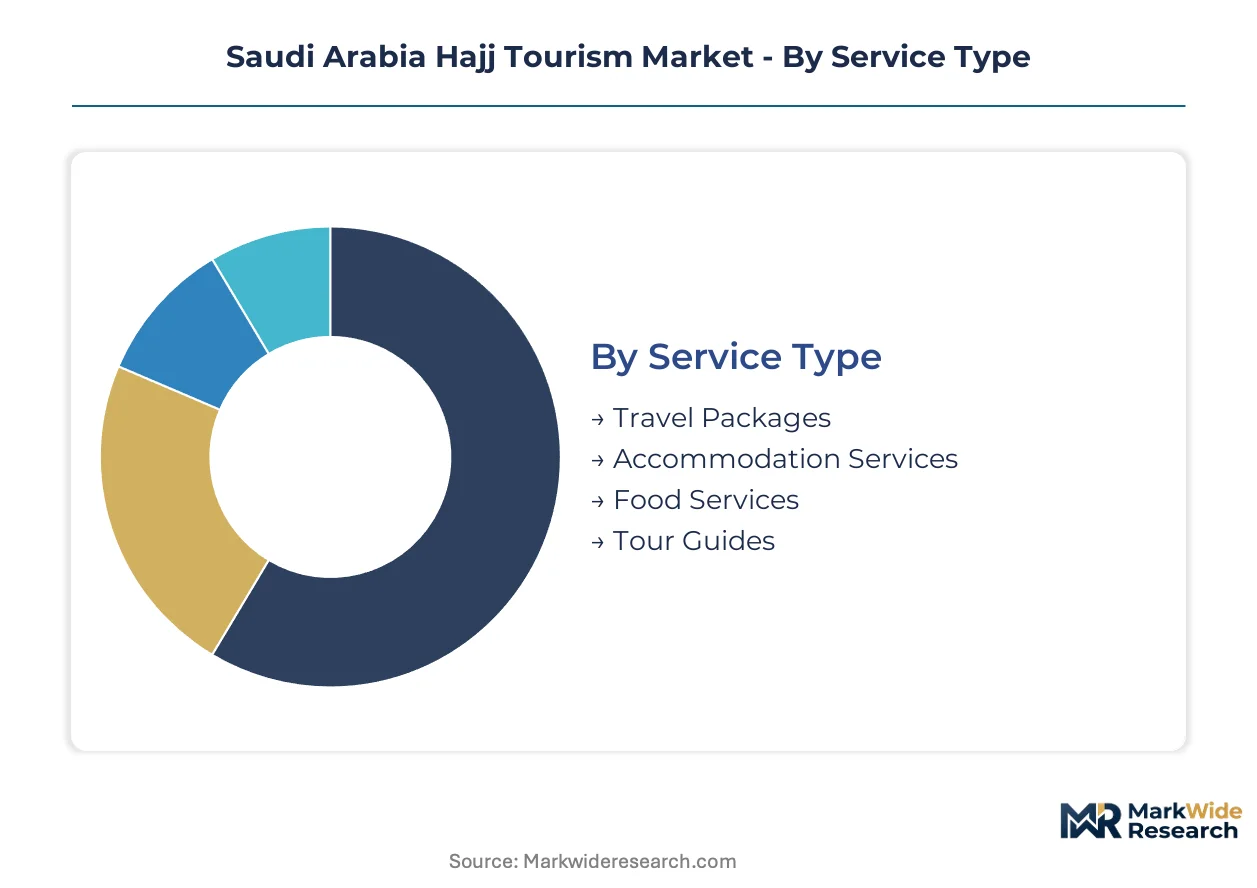
Segmentation in Hajj tourism reveals how pilgrimage demand fragments across service tiers, customer coordination modes, and booking behaviors. These divisions determine pricing power, operational complexity, and regulatory exposure for suppliers operating within Saudi Arabia's controlled pilgrimage economy.
Service Type:
Pilgrims prioritize proximity-to-ritual and logistical certainty when selecting service bundles, with accommodation commanding disproportionate attention due to finite Haram-adjacent inventory.
- Travel Packages:Bundled offerings combining flights, lodging, ground transport, and ritual coordination under single-provider accountability. Demand concentrates among first-time pilgrims from Indonesia and Pakistan seeking administrative simplification through SFDA-licensed operators.
- Accommodation Services:Room inventory within Makkah's central district and shuttle-accessible periphery, segmented by walking distance to the Grand Mosque. Properties inside the Haram proximity zone capture premium pricing during peak arrival windows when visa quotas compress demand into narrow calendar bands.
- Food Services:Catering operations ranging from centralized kitchen facilities to restaurant concessions near pilgrimage sites. MOHAP hygiene certification requirements shape supplier eligibility for group tour contracts.
- Tour Guides:Licensed ritual facilitators providing Arabic-language instruction and logistical wayfinding. Multilingual certification bottlenecks constrain supply expansion for Indonesian, Urdu, and Malay-speaking guide services.
Volume sits with Accommodation Services; growth tilts toward Travel Packages as Nusuk platform integration streamlines bundled procurement for group tour operators.
Customer Type:
Coordination scale determines operational predictability for suppliers, with aggregated demand enabling inventory pre-commitment and dispersed demand requiring flexible capacity buffers.
- Group Tours:Aggregated pilgrim cohorts moving through synchronized itineraries under operator-managed logistics. Indonesian and Pakistani source markets drive expanding volume through bilateral quota allocations that favor organized travel over independent arrangements.
- Individual Pilgrims:Self-directed travelers procuring services through fragmented channels including airline direct booking, property websites, and ride-hailing platforms. Repeat pilgrims from Southeast Asia's urban professional segments show strongest preference for unbundled service procurement.
- Family Packages:Multi-generational cohorts requiring accommodation configurations and ground transport suited to elderly and minor travelers. Demand clusters during school holiday periods preceding Hajj season peaks.
- Corporate Clients:Employer-sponsored pilgrimage programs for senior staff, typically procuring luxury-tier accommodation and dedicated guide services. Volume remains limited relative to consumer segments but yields per-pilgrim margins.
Volume concentrates in Group Tours; Individual Pilgrims are expanding most quickly as digital booking infrastructure reduces coordination barriers for repeat visitors.
Booking Channel:
Channel selection reflects pilgrim digital sophistication, repeat-visit experience, and trust in remote transaction security for high-value pilgrimage commitments.
- Online Booking:Web-based platforms including Nusuk's unified portal and operator proprietary sites. Seera Group's integrated digital infrastructure captures substantial flow through multi-touchpoint aggregation.
- Travel Agencies:Intermediary networks in source markets handling visa documentation, package assembly, and pre-departure orientation. Indonesian and Pakistani markets maintain heavy reliance on agency intermediation for first-time pilgrims.
- Direct Booking:Property-to-pilgrim transactions bypassing intermediaries, typically employed by repeat visitors with established accommodation preferences and Arabic language capability.
- Mobile Apps:Smartphone-native booking interfaces gaining traction among younger pilgrims in Southeast Asian source markets. Nusuk platform mandates accelerate mobile channel adoption through integrated visa-to-accommodation workflows.
Volume currently flows through Travel Agencies; Mobile Apps show steepest expansion trajectory as smartphone penetration deepens in Indonesian and Pakistani source markets.
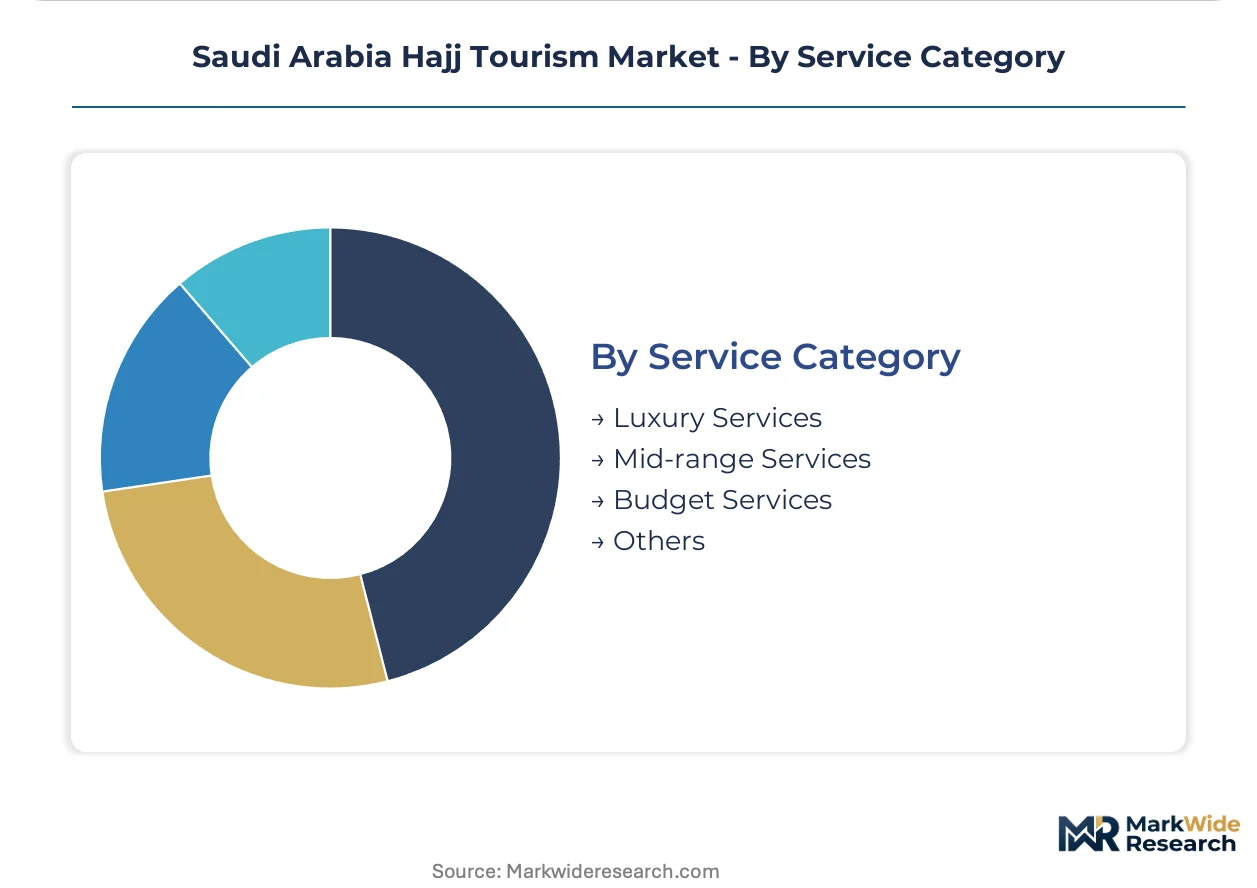
Service Category:
Price-tier selection correlates with pilgrimage frequency, income level, and sensitivity to walking distance versus shuttle dependency for Grand Mosque access.
- Luxury Services:Five-star properties within 500 meters of the Haram, dedicated concierge ritual coordination, and premium ground transport. Finite land availability in Makkah's central district restricts supply expansion and sustains pricing premiums.
- Mid-range Services:Three-to-four-star accommodation with standardized amenity packages and shuttle-coordinated mosque access. SFDA facility classification reforms enable clearer quality signaling that captures pilgrims upgrading from budget tiers.
- Budget Services:Basic lodging in peripheral zones with shared facilities and extended shuttle transit times. Demand persists among price-sensitive first-time pilgrims from lower-income source market segments.
- Others:Non-standard service configurations including dormitory-style religious institution housing and camping provisions for overflow capacity during peak demand compression.
Volume resides in Mid-range Services; Luxury Services gain share fastest as visa liberalization under Saudi Vision 2030 attracts higher-income pilgrims from emerging source markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Makkah Royal Clock Tower Hotel complex and surrounding Haram-adjacent zones concentrate premium accommodation inventory under the Ministry of Tourism's licensing framework. SFDA hospitality classifications and MOHAP health certification protocols govern service tier positioning across Saudi Arabia's controlled pilgrimage economy.
Western Region
Jeddah's King Abdulaziz International Airport processes the dominant share of international pilgrim arrivals through its dedicated Hajj terminal infrastructure. MOHAP digitized health verification systems compress immigration processing timelines during peak arrival surges. The Jeddah Islamic Port corridor anchors ground transport logistics coordination for overland pilgrim flows from regional source markets.
Central Region
Riyadh-based tour operators and travel agencies aggregate corporate pilgrimage programs and high-net-worth individual bookings through Nusuk platform integration. The Saudi Commission for Tourism and National Heritage facility classification criteria standardize quality signaling for properties seeking premium-tier positioning. Riyadh's King Khalid International Airport secondary routing absorbs overflow capacity when Jeddah terminals reach saturation.
Madinah Region
The Prophet's Mosque proximity zone attracts extended-stay pilgrims combining Hajj with ziyarat visitation, creating nine-month demand diversification outside peak Hajj windows. MOHAP vaccination verification protocols apply uniformly across entry points serving the Madinah cluster. Properties in the Quba and Airport Road corridors compete on shuttle coordination efficiency rather than walking-distance premiums.
Eastern Province
Dammam's King Fahd International Airport captures Gulf Cooperation Council source market flows through simplified visa protocols under bilateral agreements. The Khobar-Dhahran corridor hosts corporate pilgrimage procurement offices serving employer-sponsored programs. SFDA licensing requirements for group tour operators concentrate administrative functions in Dammam's commercial districts.
Saudi Arabia Hajj Tourism Market Competitive Landscape
Makkah-based property holders anchor one tier; Riyadh and Jeddah-integrated travel conglomerates hold coordination and airlift capacity. The market structures around controlled Haram proximity inventory, with finite land availability concentrating pricing power among incumbent accommodation providers. Three archetypes dominate: legacy hospitality groups with decades-long property leases, airline-affiliated travel integrators controlling vertical air-to-ground workflows, and digital platform operators aggregating fragmented supplier inventory. Competitive moves center on Nusuk API integration mandates and sustainability certification pre-positioning ahead of Ministry of Tourism environmental compliance thresholds.
Within the airline-integrated tier, Saudi Arabian Airlines exemplifies captive airlift infrastructure deployment through dedicated terminal assets. Seera Group and Elaf Group occupy positions spanning digital booking aggregation and controlled Makkah central zone property inventory respectively. These three entities represent the dominant competitive archetypes: vertical transport-to-accommodation integration, platform-based demand aggregation, and finite-location asset control.
| Leading Market Players |
|---|
| Al Tayyar Travel Group |
| Saudi Arabian Airlines |
| Zahid Travel Group |
| Elaf Group |
| Seera Group |
| InterContinental Hotels Saudi Arabia |
| Wyndham Hotel Group Saudi Arabia |
| Avis Saudi Arabia |
| Saddik & Mohammed Attar Company |
| Others |
Value Network & Pricing Analysis
Captive airlift infrastructure through Saudi Arabian Airlines' dedicated Hajj terminal anchors both supply positioning and pricing power for vertically integrated operators controlling the pilgrimage corridor from King Abdulaziz International Airport to Makkah's central district. This integration pattern concentrates margin capture among legacy hospitality groups with decades-long property leases near the Grand Mosque.
Pricing Analysis
Short lead-time bookings command substantial premiums as visa quota compressions force last-minute inventory scarcity within the Haram proximity zone. Three-tier pricing structure across luxury, mid-range, and economy levels segments pilgrims by walking-distance tolerance and amenity requirements. Price differentiation rests on SFDA facility classification tiers and MOHAP health certification status. Cost compression in peripheral accommodation is intensifying because shuttle-dependent properties compete on transport coordination rather than location premiums. First-time pilgrims from Indonesia and Pakistan show highest price sensitivity; repeat visitors from urban professional segments prioritize proximity over cost.
Supply Chain Analysis
Freight and logistics costs concentrate in the Jeddah-Makkah corridor where ground transport coordination absorbs substantial operational expenditure for shuttle-dependent properties. Geographic supply concentration centers on Saudi Arabia for accommodation inventory, Indonesia and Pakistan for pilgrim source flows, and Turkey for specialized ritual goods and Ihram textiles. Raw material dependencies include construction materials for hotel development, food service supplies for centralized catering operations, and digital infrastructure components for Nusuk platform integration. Single-source vulnerability in Haram-adjacent land availability creates structural supply risk. Distribution runs through SFDA-licensed tour operators aggregating fragmented service components into bundled packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA hospitality licensing requirements and MOHAP health certification protocols construct a cost-of-compliance moat that advantages established operators with capital reserves for regulatory navigation. This barrier-to-entry dynamic rewards early certification investment and punishes undercapitalized market aspirants.
For Market Incumbents: Lock in Haram proximity inventory through lease extensions and controlled property acquisitions before land scarcity intensifies. SFDA facility classification reforms threaten mid-range properties lacking capital for quality upgrades. Prioritize Nusuk API integration to capture Indonesian and Pakistani group tour flows through digital booking velocity.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Madinah's extended-stay accommodation offers white-space penetration for developers accepting shuttle logistics complexity. Secondary city properties in Jeddah's Islamic Port corridor present lower land-acquisition entry costs. Target repeat pilgrims from Southeast Asia's urban professional segments through modular service unbundling and direct-to-pilgrim digital channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-based demand aggregation and sustainability-certified property portfolios. Long-term viability hinges on operators capable of repositioning Hajj-optimized assets toward year-round Umrah flows. Acquisition target archetype: mid-scale properties with Nusuk integration completion and MOHAP certification compliance. Watch visa liberalization velocity under Saudi Vision 2030 as inflection indicator for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Nusuk Platform Integration | Streamlines visa-to-accommodation workflows for Indonesian and Pakistani source markets. |
| SFDA Facility Classification Upgrade | Enables mid-range properties to capture pilgrims upgrading from budget segments. |
| MOHAP Health Certification Digitization | Accelerates border processing and extends effective pilgrimage season length. |
| Secondary City Accommodation Development | Jeddah and Madinah clusters offer margin expansion through lower land costs. |
| Sustainability Certification Pre-Positioning | Creates early-mover advantage ahead of Ministry of Tourism environmental mandates. |
Research Methodology
Saudi Commission for Tourism and National Heritage facility classification databases, MOHAP health certification registries, and Nusuk platform operational disclosures formed the secondary backbone of this analysis. Primary interviews with SFDA-licensed tour operators, Makkah property management executives, and Indonesian travel agency procurement leads combined with secondary validation through customs arrival data and bilateral visa quota agreements. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Historical trendline analysis across pilgrim arrival patterns, accommodation occupancy cycles, and package pricing trajectories informed projection frameworks. Segmentation dimensions modeled include service type, customer coordination mode, booking channel, and service category tier. CAGRs were derived through regression analysis of historical growth patterns adjusted for visa liberalization impacts. Forecast inputs incorporated Nusuk platform adoption curves and SFDA licensing velocity.
Inputs from Saudi regulatory filings and source market travel agency disclosures were available through the study window; gaps in real-time inventory pricing data introduce uncertainty bands around accommodation revenue estimates. Forecasts reflect assumptions regarding visa quota negotiations and platform integration timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Europe Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Culinary Tourism Market
Destination Management and Attractions
USA Faith Based Tourism Market
Destination Management and Attractions
Cultural Tourism Market
Destination Management and Attractions
Indonesia Faith-Based Tourism Market
Destination Management and Attractions
Smart Tourism Market
Destination Management and Attractions
Vietnam Tourism Market
Destination Management and Attractions
MICE Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
Europe Winter Tourism Market
Destination Management and Attractions
South Africa Casino Tourism Market
Destination Management and Attractions
North America Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
UAE MICE Tourism Market
Destination Management and Attractions
Italy Faith Based Tourism Market
Destination Management and Attractions
Australia Adventure Tourism Market