
 Europe Museums, Historical Sites, Zoos, and Parks Market | 2026-2036
Europe Museums, Historical Sites, Zoos, and Parks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Museums, Historical Sites, Zoos, and Parks Market Insights
Buyer concentration among international tour operators and online travel platforms is repositioning how European cultural institutions negotiate group admissions and package distribution. The British Museum London leverages its permanent collection strength to sustain year-round visitor flows regardless of temporary exhibition cycles. Centre Pompidou Paris differentiates through contemporary programming that competes directly with private museum operators for younger demographics. Schonbrunner Zoo Vienna anchors its revenue model on conservation-focused educational tourism rather than conventional entertainment positioning.
Europe museums, historical sites, zoos, and parks constitute physical and digital venues that preserve, interpret, and display cultural, natural, or scientific collections through curated exhibitions, living specimens, or conserved heritage architecture, typically requiring climate-controlled environments, specialized conservation protocols, and trained interpretive staff to fulfill educational and preservation mandates. The operational model dimension reveals structural divergence where public institutions dominate visitor volume but hybrid entities capture disproportionate margin pools through commercial licensing and hospitality integration. Within the attraction feature category, interactive displays and educational programs are expanding fastest as institutions replace passive observation with participatory engagement architectures, while conservation efforts remain concentrated among zoos and botanical gardens where regulatory compliance creates funding access advantages.
EU Green Deal emission targets and CSRD sustainability disclosure rules are reshaping capital allocation for publicly funded institutions across France, Italy, and Germany, with national ministries tying restoration grants to energy performance benchmarks. EMA heritage preservation protocols and country-level monument protection laws constrain physical expansion options while creating protected revenue streams for accredited sites. REACH-compliant materials standards for exhibition construction and maintenance add compliance layers that favor established operators with dedicated conservation departments. Stakeholders must monitor how digital access mandates from European cultural policy frameworks reshape capital planning between physical infrastructure and virtual delivery platforms.
Market Dynamics
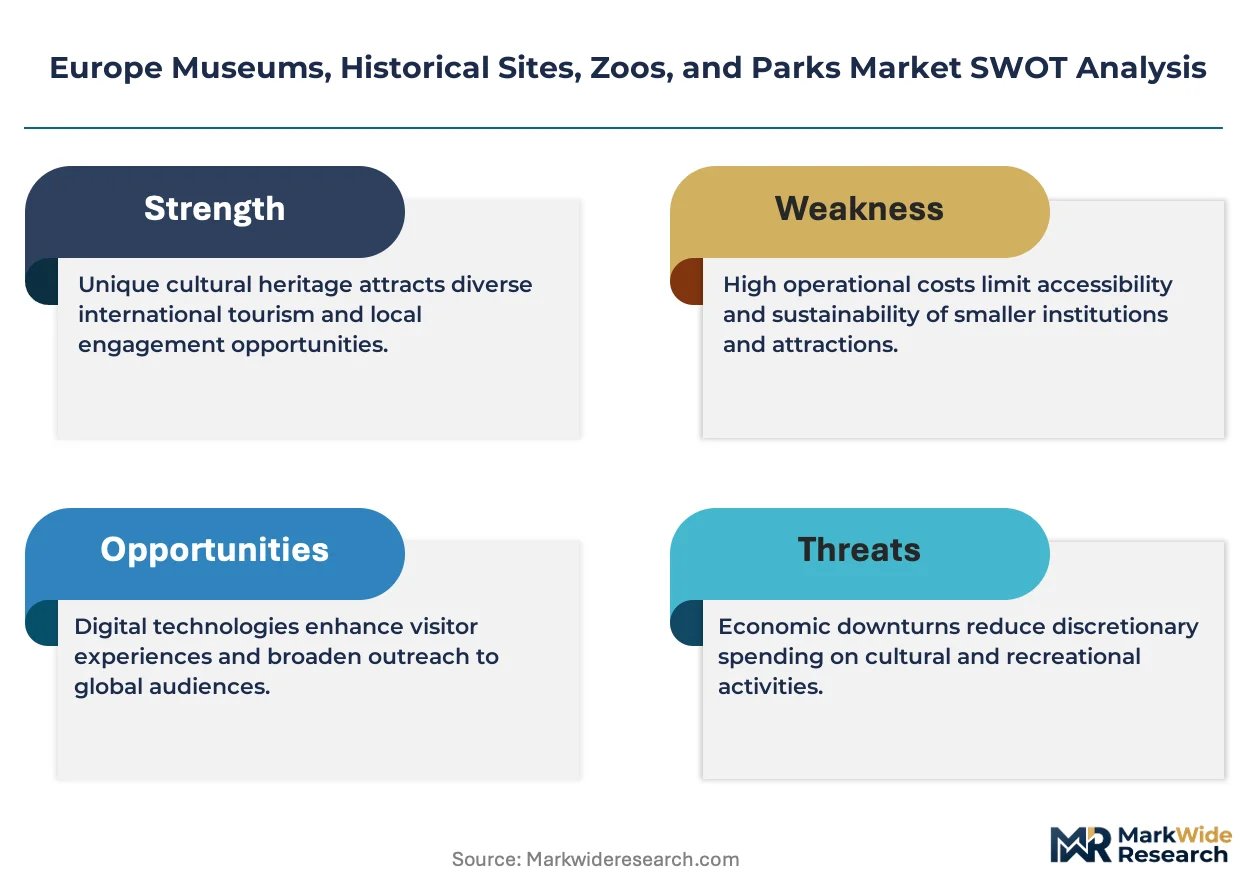
The EU Green Deal is forcing publicly funded European cultural institutions to redirect capital from exhibition programming toward building retrofitting and emissions compliance, fundamentally altering how museums, zoos, and heritage sites allocate operational budgets across the forecast period.
Growth Catalysts
- CSRD Sustainability Disclosure:Mandatory reporting rules across France, Germany, and Italy are unlocking green bond financing for accredited institutions that meet energy performance benchmarks.
- Immersive Digital Exhibition Technology:Augmented reality installations are pulling younger demographics into permanent collections at Italian and French state museums, extending dwell time and secondary spend per visit.
- Heritage Destination Packaging:International tour operators are bundling cross-border cultural circuits through Vienna, Paris, and Rome, creating predictable group revenue streams for anchor institutions.
Market Restraints
- EMA Heritage Preservation Protocols:Strict monument protection laws in Italy and France block physical expansion options for urban museums, capping visitor capacity at constrained historic sites.
- Specialized Conservation Labor Pool:The shallow supply of trained conservators and interpretive staff across Central Europe inflates personnel costs for accredited institutions.
- REACH-Compliant Materials Standards:Exhibition construction and maintenance must use certified low-emission materials, eliminating lower-cost supply alternatives for renovation projects.
Strategic Opportunities
- Virtual Delivery Platforms:EU cultural policy frameworks are mandating digital access, creating funded pathways for institutions to monetize remote collections through subscription and licensing models.
- Conservation-Focused Educational Tourism:Zoos in Austria and Germany are repositioning around biodiversity programming, accessing dedicated environmental education grants unavailable to entertainment-oriented competitors.
- Hybrid Public-Private Entities:Commercial licensing and hospitality integration at Paris and London institutions demonstrate margin capture models that public-only operators have not replicated.
Industry Challenges
- Conservation Department Scale Requirements:REACH compliance and EMA protocol adherence demand in-house technical teams that smaller municipal museums cannot staff, creating accreditation barriers.
- Physical-Digital Capital Allocation:Institutions must split limited restoration grants between climate-controlled storage infrastructure and virtual platform development without clear revenue attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Museums, Historical Sites, Zoos, and Parks Market |
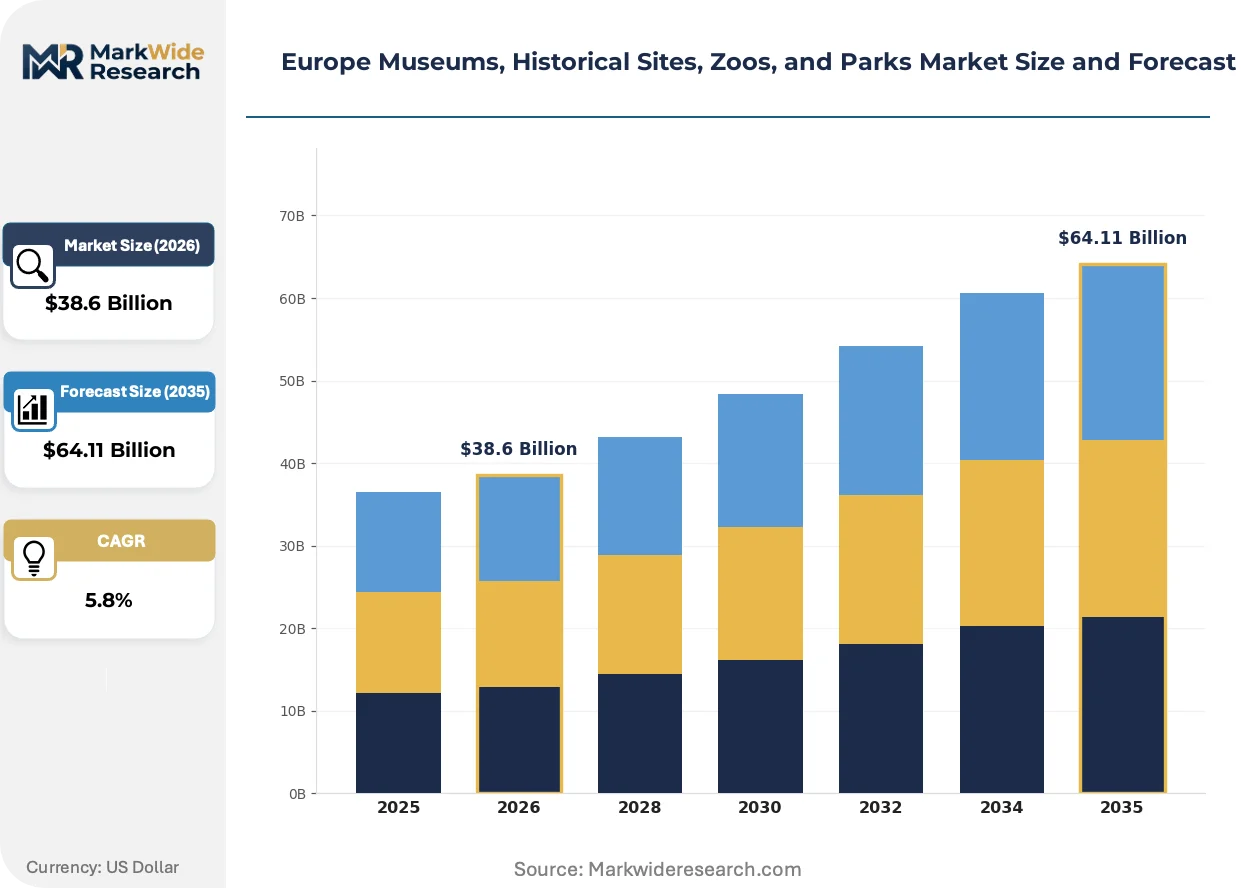
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Museums, Historical Sites, Zoos, Botanical Gardens Visitor Demographic: Families, Tourists, Students, Seniors Attraction Feature: Exhibitions, Educational Programs, Conservation Efforts, Interactive Displays Operational Model: Public, Private, Non-Profit, Hybrid |
| Companies Covered | Louvre Paris, British Museum London, State Hermitage St Petersburg, Vatican Museums Vatican, Museo Nacional Del Prado Madrid, Natural History Museum London, Centre Pompidou Paris, Schonbrunner Zoo Vienna, Zoologischer Garten Berlin AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Museums, Historical Sites, Zoos, and Parks Market Trends and Innovations
Augmented reality and haptic display systems are displacing static diorama and placard formats across European zoos and science museums, converting passive observation into participatory engagement architectures that extend visit duration.
Projection mapping and spatial audio technology is converging with conserved heritage architecture at French and Italian sites, enabling nighttime immersive programming that generates secondary revenue without expanding physical footprint. National ministries in Paris and Rome are fast-tracking permits for temporary digital installations at protected monuments. The structural consequence is compressing the exhibition development cycle from years to months for institutions with technical partnerships.
CSRD disclosure rules and EU Green Deal emission targets are reshaping capital allocation for German and French publicly funded institutions, with national ministries tying restoration grants to verified energy performance benchmarks. Accredited sites must now document carbon intensity across conservation, climate control, and visitor services to maintain eligibility for public funding. Museums with embedded energy management systems are capturing disproportionate grant flows relative to legacy-operated competitors.
Buyer concentration among international tour operators and online travel platforms is consolidating distribution power over group admissions and package sales for European heritage destinations. Schonbrunner Zoo Vienna and Centre Pompidou Paris now negotiate directly with platform aggregators rather than traditional travel wholesalers, compressing margin structures while securing volume commitments. This channel shift is most visible in Austria and France where platform penetration among inbound cultural tourism exceeds other European markets.
Europe Museums, Historical Sites, Zoos, and Parks Market Segmentation
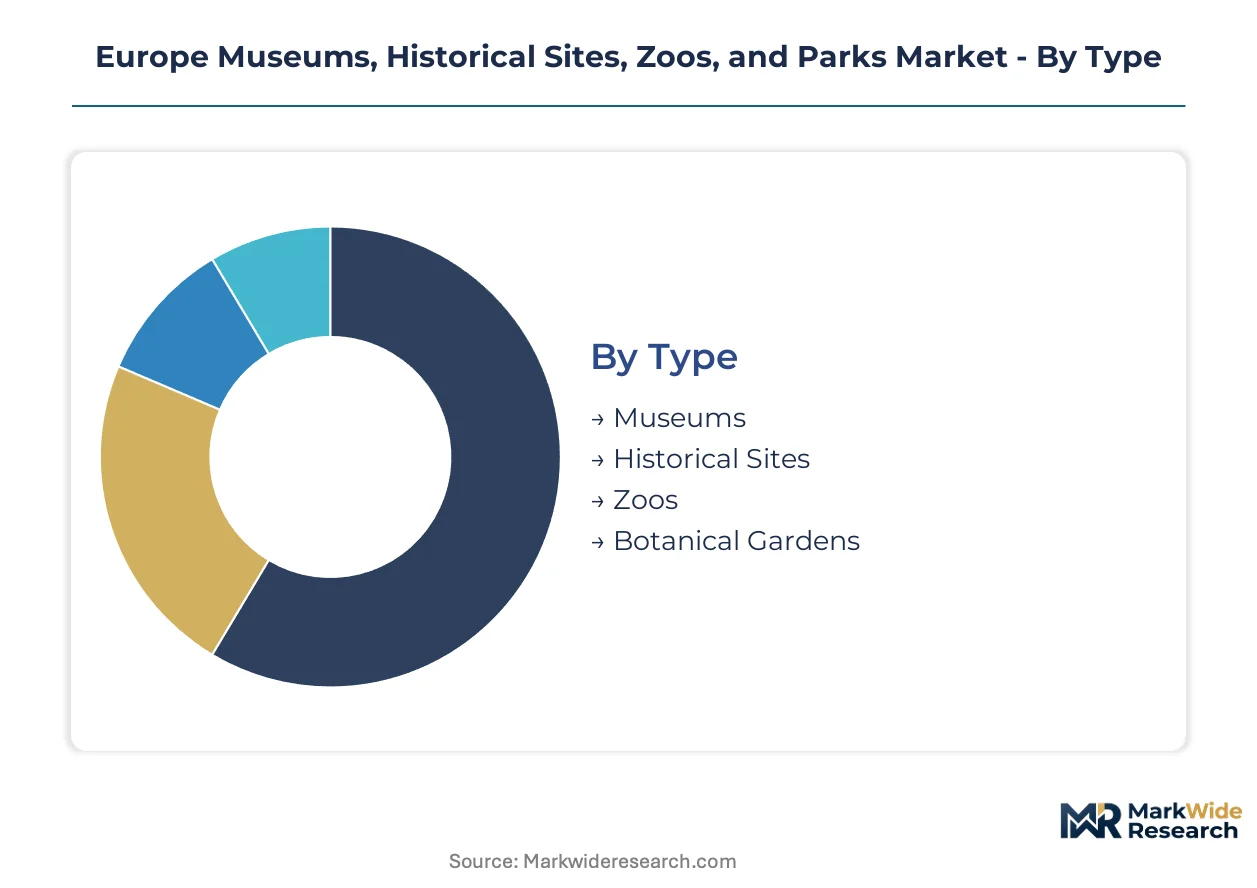
European cultural institutions deploy divergent operational architectures that reshape capital allocation, visitor engagement, and regulatory compliance. Segmentation reveals how technology integration, demographic targeting, and funding models determine competitive positioning across museums, zoos, and heritage sites.
Type:
Technical sophistication and conservation protocols differentiate venue categories, with climate control requirements and collection management systems driving facility investment priorities.
- Museums:Climate-controlled galleries and specialized conservation laboratories dominate capital expenditure for state collections in France and Italy. French state museums leverage immersive digital exhibition technology to extend dwell time among younger demographics, accessing CSRD-linked restoration grants tied to energy performance benchmarks.
- Historical Sites:Conserved heritage architecture requires EMA-compliant preservation protocols that constrain physical expansion at urban monuments in Rome and Paris. Projection mapping and spatial audio installations generate nighttime revenue without footprint expansion, compressing exhibition development cycles through technical partnerships.
- Zoos:Living specimen management demands veterinary infrastructure and biodiversity programming that qualifies for dedicated environmental education grants in Austria and Germany.
- Botanical Gardens:Specialized horticultural conservation and interpretive trail systems serve educational mandates with lower per-visitor operational intensity than zoological collections.
Mature deployment sits with Museums. Newer deployment is concentrated in Historical Sites deploying immersive nighttime programming.
Visitor Demographic:
Revenue stability hinges on demographic mix, with group bookings and repeat visitation patterns determining pricing power and secondary spend capture.
- Families:Multi-generational visit patterns drive demand for interactive displays and educational programming that extends duration across meal and retail touchpoints. Schonbrunner Zoo Vienna anchors revenue on conservation-focused educational tourism rather than conventional entertainment positioning.
- Tourists:International tour operators and online travel platforms concentrate distribution power over group admissions, with Vienna, Paris, and Rome anchor institutions negotiating directly with platform aggregators.
- Students:Curriculum-aligned programming creates predictable weekday demand with subsidized pricing tiers that trade margin for volume and grant eligibility.
- Seniors:Membership-based repeat visitation generates stable recurring revenue with lower per-visit operational intensity than casual tourists.
Volume concentration rests with Tourists. Margin expansion is climbing the fastest among Families through integrated hospitality offerings.
Attraction Feature:
Participatory engagement architectures are displacing passive observation formats, with technology integration determining capital allocation between physical and virtual delivery platforms.
- Exhibitions:Traditional curated displays with static diorama and placard formats face compression as augmented reality installations pull younger demographics into permanent collections at Italian and French state museums.
- Educational Programs:Curriculum-aligned workshops and guided interpretation create institutional differentiation that secures school group contracts and environmental education grants unavailable to entertainment-oriented competitors.
- Conservation Efforts:Biodiversity programming and specimen preservation protocols concentrate regulatory compliance costs among zoos and botanical gardens, creating funding access advantages through dedicated environmental grants.
- Interactive Displays:Haptic display systems and participatory engagement architectures extend visit duration and secondary spend per visit, gaining share fastest among technology-forward institutions.
Established infrastructure dominates Exhibitions. Investment flow is concentrating in Interactive Displays as institutions replace passive formats.
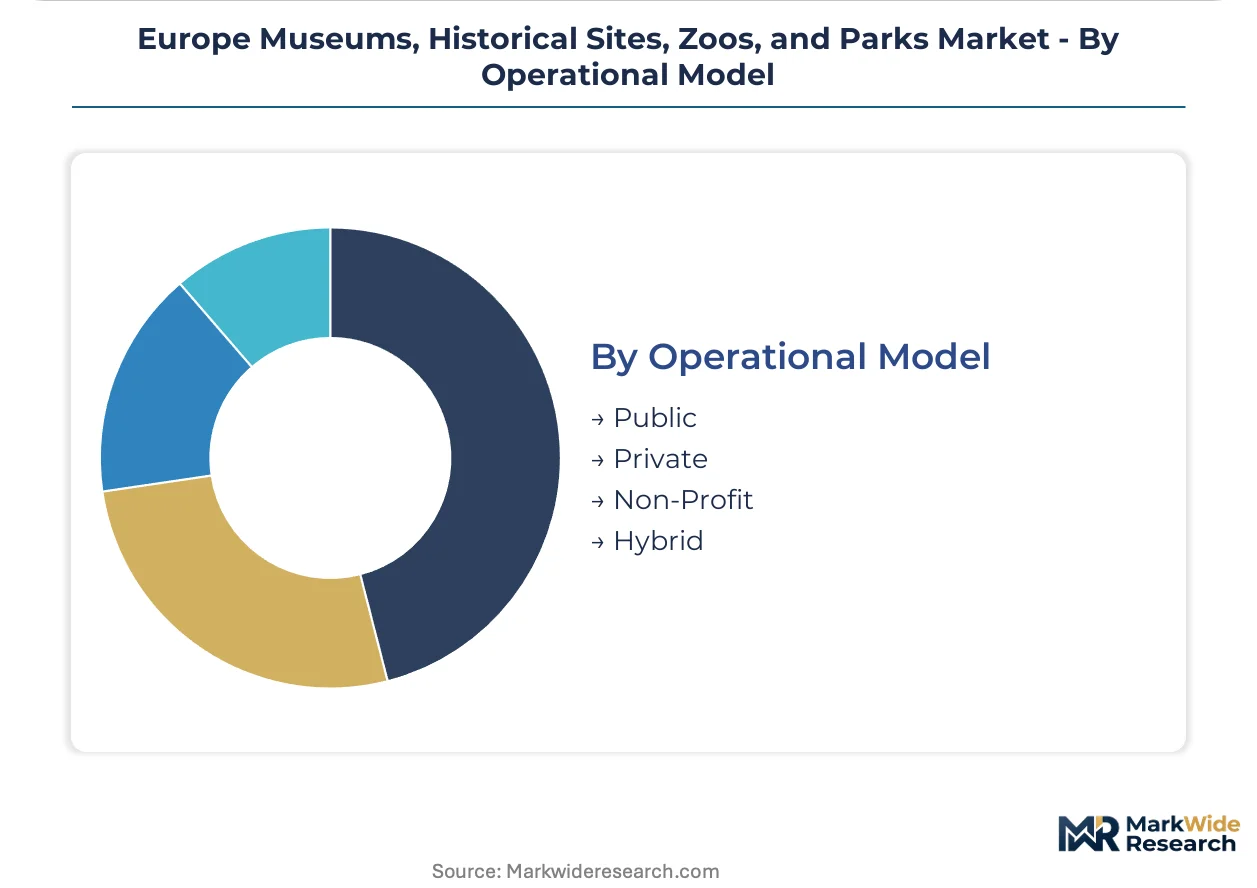
Operational Model:
Funding architecture determines margin capture potential, with hybrid structures demonstrating commercial licensing and hospitality integration models that public-only operators have not replicated.
- Public:State-funded institutions dominate visitor volume but face capital redirection from exhibition programming toward building retrofitting and emissions compliance under EU Green Deal mandates.
- Private:Commercial operators capture disproportionate margin pools through premium pricing and integrated hospitality, though with constrained access to restoration grants tied to public benefit criteria.
- Non-Profit:Donation-dependent revenue models prioritize membership retention and grant writing capacity, with conservation department scale requirements creating accreditation barriers for smaller municipal museums.
- Hybrid:Paris and London institutions demonstrate margin capture through commercial licensing and hospitality integration, accessing both public restoration grants and private revenue streams.
Institutional mass sits with Public operators. Structural innovation is expanding most quickly within Hybrid entities blending grant access with commercial agility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Visitor concentration clusters in Western European capitals with established cultural infrastructure, while regulatory divergence between EU member states creates uneven compliance burdens for cross-border operators.
France
Parisian institutions command disproportionate international visitor flows through immersive digital exhibition investments at the Louvre and Centre Pompidou. The country's national monument protection laws under EMA heritage protocols constrain physical expansion at urban historic sites. Île-de-France anchors revenue generation through nighttime projection mapping programming at conserved architectural landmarks.
United Kingdom
London museums leverage permanent collection strength to sustain year-round visitor flows regardless of temporary exhibition cycles. British CSRD-aligned sustainability disclosure rules are redirecting capital from programming toward building retrofitting for publicly funded institutions. The British Museum and Natural History Museum anchor group booking negotiations with concentrated online travel platform distributors.
Germany
Berlin and Munich zoos reposition around conservation-focused educational tourism to access dedicated environmental education grants unavailable to entertainment-oriented competitors. The EU Green Deal mandates lower-carbon operations for publicly funded cultural institutions, tying restoration grants to verified energy performance benchmarks. Bavarian and North Rhine-Westphalian heritage sites face compressed exhibition development cycles through technical partnerships for temporary digital installations.
Italy
Roman and Florentine state museums deploy augmented reality installations to pull younger demographics into permanent collections, extending dwell time and secondary spend per visit. Strict monument protection laws block physical expansion options for urban museums, capping visitor capacity at constrained historic sites. Vatican Museums anchor concentrated religious tourism demand through accredited guide licensing requirements.
Austria
Vienna institutions negotiate directly with platform aggregators rather than traditional travel wholesalers, compressing margin structures while securing volume commitments. Schonbrunner Zoo anchors revenue on biodiversity programming rather than conventional entertainment positioning. Federal ministry grants for heritage preservation require REACH-compliant materials standards for exhibition construction, eliminating lower-cost supply alternatives.
Europe Museums, Historical Sites, Zoos, and Parks Market Competitive Landscape
French and British institutions anchor one tier through permanent collection scale and hybrid public-private operational models; German and Austrian specialists hold differentiated positions through conservation-focused educational programming. Market structure concentrates around state-funded entities with embedded hospitality integration, while smaller municipal operators face accreditation barriers from conservation department scale requirements. Three archetypes dominate: collection-scale anchor museums, conservation-mandated zoos, and hybrid entities capturing commercial licensing margins. Competitive moves center on direct platform aggregator negotiations and technical partnerships for accelerated digital exhibition deployment.
Within the collection-scale tier, Louvre Paris and British Museum London exemplify permanent-collection-driven visitor retention models that sustain revenue through temporary exhibition independence. Centre Pompidou Paris occupies a position within the hybrid operational model, demonstrating margin capture through commercial licensing and integrated hospitality that public-only operators have not replicated. State Hermitage St Petersburg anchors the Eastern European vector with collection depth that supports year-round programming regardless of geopolitical access constraints.
| Leading Market Players |
|---|
| Louvre Paris |
| British Museum London |
| State Hermitage St Petersburg |
| Vatican Museums Vatican |
| Museo Nacional Del Prado Madrid |
| Natural History Museum London |
| Centre Pompidou Paris |
| Schonbrunner Zoo Vienna |
| Zoologischer Garten Berlin AG |
| Others |
Pricing and Supply Chain Analysis
Conservation-grade materials certified under REACH standards flow from specialized German and Italian chemical suppliers through exhibition construction tiers, with compliance costs stratifying final service pricing across public and hybrid operational models. Labor pools for interpretive staff and conservators in Central Europe anchor personnel cost differentials that widen margin gaps between accredited institutions and municipal operators.
Pricing Analysis
Volume concentration among international tour operators compresses group admission margins while hybrid entities capture premium pricing through integrated hospitality and commercial licensing. Three-tier pricing structure across premium, standard, and economy levels separates platform-negotiated group rates from direct-booking individual tickets and membership subscriptions. Pricing pressure stems from buyer consolidation among online travel platforms that extract volume discounts from anchor institutions. Casual tourists exhibit highest price sensitivity, while family segments with multi-generational visit patterns demonstrate lowest sensitivity due to integrated meal and retail spend capture.
Supply Chain Analysis
Freight logistics for climate-controlled specimen transport and specialized conservation materials concentrate supplier relationships across Germany, Austria, and France, with cross-border regulatory compliance adding documentation layers. Raw material dependencies center on certified low-emission construction substrates, veterinary pharmaceuticals for zoological collections, and precision climate control equipment. Single-source vulnerability sits with specialized conservator training programs that feed accredited institutions. Distribution runs through ministry procurement frameworks for public entities and direct technical partnerships for hybrid operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as institutions pursue backward control over digital exhibition technology development to escape platform margin compression. The upstream lever centers on proprietary immersive content creation capabilities that reduce reliance on external technical partnerships.
For Market Incumbents: Cement collection-scale advantages by embedding energy management systems that capture disproportionate CSRD-linked restoration grants from French and German ministries. Deepen direct platform aggregator negotiations to offset volume discount pressure with guaranteed admission commitments. Prioritize in-house conservation department scale that maintains EMA protocol accreditation barriers against smaller municipal competitors.
For New Entrants and Emerging Players: Capture white-space in conservation-focused educational tourism programming for zoos and botanical gardens, where dedicated environmental education grants remain underutilized by entertainment-oriented competitors. Target secondary European cities with heritage assets but limited technical partnership access for accelerated digital exhibition deployment. Lead with subscription-based virtual delivery platforms that monetize remote collections under EU cultural policy mandates.
For Investors and Strategic Acquirers: Accelerated permit approvals for temporary digital installations at protected Italian and French monuments is the leading indicator that technical partnership capabilities are becoming scarcer and more valuable than physical asset scale. Long-term viability favors hybrid operational models with demonstrated commercial licensing and hospitality integration. Watch for ministry grant allocation shifts between physical infrastructure and virtual platform development as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Immersive Digital Exhibition Deployment | AR installations at Italian state museums extend dwell time and secondary spend per visit. |
| Energy Performance Retrofitting | Embedded systems capture CSRD-linked restoration grants from French national ministries. |
| Platform Aggregator Partnership | Direct negotiations with online travel platforms secure volume commitments for Vienna institutions. |
| Conservation Department Scale-Up | In-house technical teams maintain REACH compliance and EMA protocol accreditation barriers. |
| Virtual Delivery Platform Launch | Subscription models monetize remote collections under EU cultural policy access mandates. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews with museum directors, heritage site conservation leads, zoo veterinary program managers, ministry cultural funding officers, and online travel platform partnership executives. Secondary sources included EU Green Deal implementation reports, CSRD disclosure filings from French and German cultural institutions, EMA heritage preservation protocol documentation, and REACH-compliant materials certification databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the European cultural tourism sector.
Granularity-level modeling deployed venue-type, visitor demographic, attraction feature, and operational model dimensions at the country level for France, United Kingdom, Germany, Italy, and Austria. CAGRs derived from historical visitor volume trajectories, expenditure patterns, and public funding allocation trends. Industry-specific forecast inputs incorporated ministry grant disbursement schedules, platform aggregator penetration rates, and digital exhibition technology adoption curves.
The model holds under stable EU cultural funding frameworks and continued platform aggregator expansion; deviation in ministry grant redirection toward emissions compliance or geopolitical constraints on international tourism would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context and regional funding exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Alternative Tourism Market
Destination Management and Attractions
Vietnam Tourism Market
Destination Management and Attractions
Italy Sustainable Tourism Market
Destination Management and Attractions
Brazil Faith Based Tourism Market
Destination Management and Attractions
Global Desert Tourism Market
Destination Management and Attractions
India Casino Tourism Market
Destination Management and Attractions
Desert Island Tourism Market
Destination Management and Attractions
Italy Tourism Market
Destination Management and Attractions
Adventure Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
Australia Adventure Tourism Market
Destination Management and Attractions
Industrial Tourism Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
North America Amusement Parks Market
Destination Management and Attractions
Theme Park Tourism Market