
 Global Offshore Software Development Market | 2026-2036
Global Offshore Software Development Market Size, Share, and Industry Trends Forecast 2026-2036
Global Offshore Software Development Market Foresight
Mid-market enterprises with limited in-house engineering capacity is redrawing demand patterns across the offshore software development landscape. BairesDev leverages its Latin American delivery centers to compete for North American clients seeking nearshore alternatives. ELEKS sustains its position through specialized fintech and healthcare vertical expertise. N-iX anchors substantial European revenue by operating engineering hubs across Poland and Ukraine.
Offshore software development encompasses the practice of contracting software engineering, quality assurance, and design services to external providers located in different countries, typically leveraging time zone differences for continuous development cycles and accessing specialized technical competencies unavailable domestically. Application development commands the largest service-type revenue pool, while cloud-based deployment models capture the fastest expansion as enterprises migrate legacy systems. SMEs represent a growing client-type segment, though enterprises still dominate absolute contract value due to multi-year transformation programs.
FDA guidelines on software as a medical device, HIPAA data security requirements, and EU GDPR cross-border transfer rules collectively shape compliance architecture for healthcare and BFSI offshore engagements. India's BIS cybersecurity standards and Poland's alignment with EU AI Act provisions further determine which delivery locations qualify for sensitive-industry contracts. Stakeholders must monitor evolving data localization mandates and AI governance frameworks when selecting offshore partner jurisdictions and structuring service agreements.
Market Dynamics
Cloud-native architecture migration is compressing delivery timelines and forcing offshore providers to restructure talent allocation toward platform engineering and DevOps automation.
Growth Catalysts
- HIPAA-compliant healthcare outsourcing:US healthcare enterprises are contracting offshore development for patient data management systems under strict HIPAA security rule adherence.
- EU AI Act alignment in Poland:Polish delivery centers are capturing sensitive-industry contracts by certifying compliance with EU AI Act provisions for algorithmic transparency.
- Generative AI code assistance:Indian engineering hubs are deploying GitHub Copilot and custom LLM tooling to accelerate application development velocity.
Market Restraints
- Data localization mandates:Vietnam's cybersecurity law and India's data protection bill are fragmenting project architectures and raising compliance overhead.
- Specialized talent scarcity:Platform engineering and MLOps expertise concentrates in Bangalore, Warsaw, and Ho Chi Minh City, creating wage inflation bottlenecks.
- Cross-border IP enforcement gaps:Weak patent recognition across certain jurisdictions exposes proprietary algorithms to misappropriation risk.
Strategic Opportunities
- Nearshore Latin American expansion:Mexico and Colombia are attracting US mid-market clients seeking timezone overlap and Spanish-language delivery.
- Software as a Medical Device (SaMD):FDA's evolving digital health guidance creates specialized demand for compliant offshore quality management systems.
- Green software engineering:EU CSRD carbon disclosure requirements are opening consulting revenue for energy-efficient code optimization services.
Industry Challenges
- Legacy system integration complexity:Mainframe and COBOL interoperability with microservices architectures requires scarce hybrid skill sets.
- Security clearance bottlenecks:FedRAMP and ISO 27001 certification timelines stretch 12-18 months, delaying contract execution for federal-adjacent work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Offshore Software Development Market |
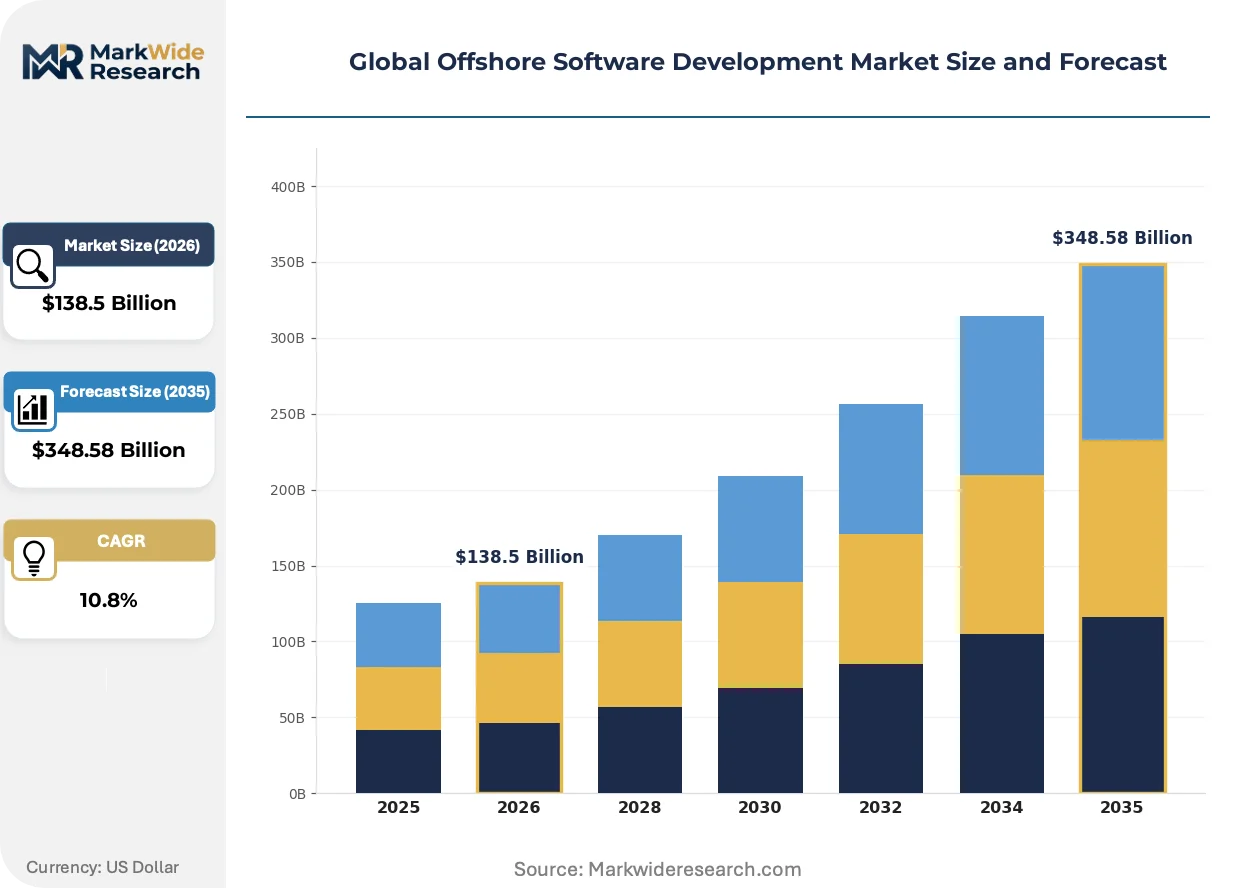
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $348.58 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Application Development, Software Testing, UX/UI Design, Maintenance Services Deployment Model: Cloud-based, On-premises, Hybrid, Managed Services Industry Vertical: Healthcare, BFSI, Retail, Telecommunications Client Type: Startups, SMEs, Enterprises, Government Agencies |
| Companies Covered | N-iX, Saigon Technology, ELEKS, eLuminous Technologies, Artkai, BairesDev, Space-O Technologies, Softura, SumatoSoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Offshore Software Development Market Shifts & Advancements
Generative AI tooling is redrawing the boundary between human engineering and automated code generation across offshore delivery models.
Low-code development platforms are fragmenting traditional application development workflows. Mid-market enterprises in financial services are adopting Mendix and OutSystems to bypass lengthy custom engineering cycles. This compression is forcing offshore providers to reposition toward platform customization and integration architecture rather than greenfield coding.
EU GDPR cross-border transfer rules are restructuring data governance architectures for European clients. Offshore providers must implement Standard Contractual Clauses and encryption protocols to legally process EU personal data outside the bloc. Healthcare and BFSI verticals are most affected, with many enterprises bifurcating data storage between EU-based instances and offshore development sandboxes.
Subscription-based engagement models are displacing fixed-price project contracts. Enterprise procurement teams favor monthly retainer structures with defined sprint velocity commitments over waterfall delivery specifications. This shift is most visible among North American technology companies seeking agile capacity augmentation rather than outsourced project completion.
Global Offshore Software Development Market Segmentation
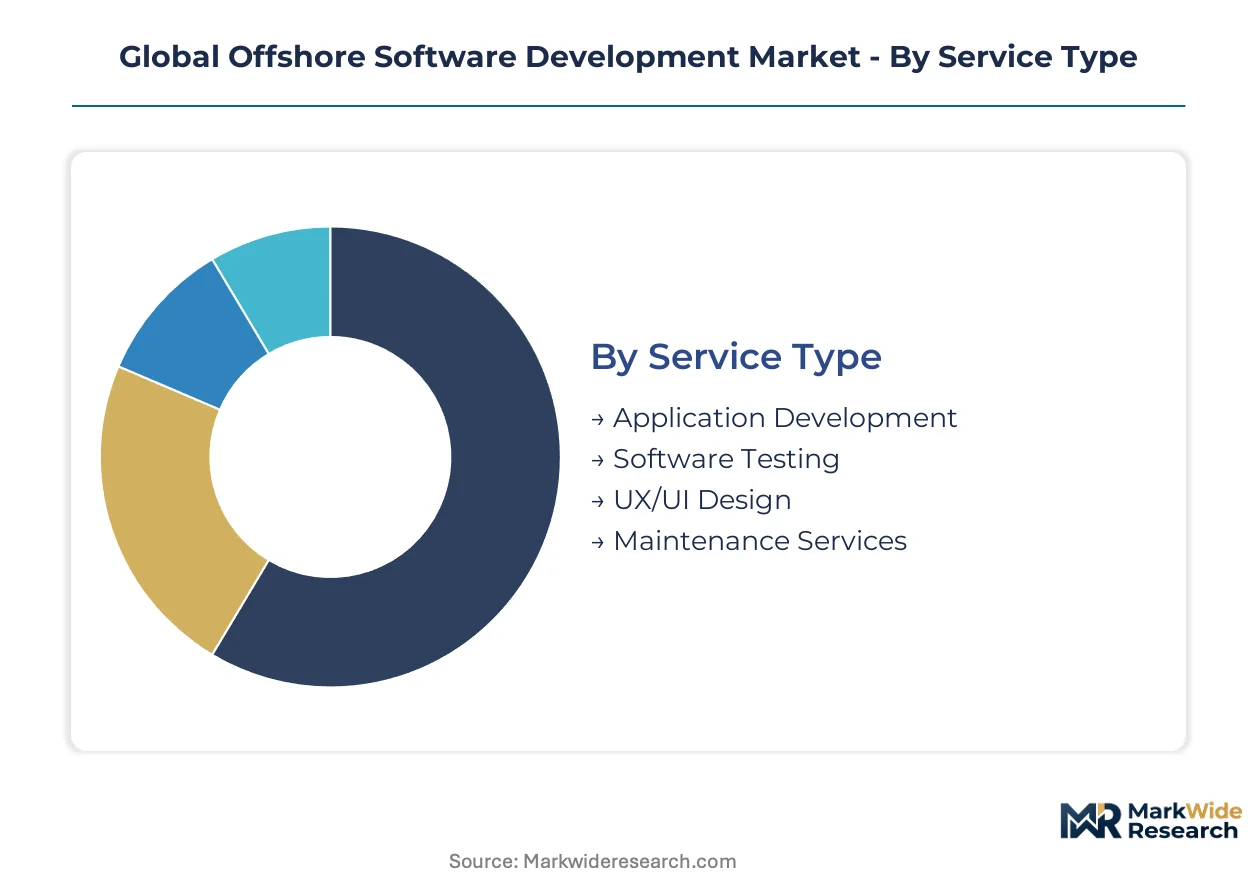
Segmentation in offshore software development reveals how procurement patterns diverge across technical complexity, regulatory exposure, and organizational scale. Buyers structure vendor selection around deployment risk tolerance and compliance jurisdiction requirements.
Service Type:
Geographic demand concentration varies sharply: application development skews toward Indian and Polish export hubs, while UX/UI design draws heavily from Latin American nearshore centers serving US clients.
- Application Development:Full-stack engineering of custom software systems using modern frameworks and microservices architectures. Healthcare enterprises in the United States contract Indian engineering centers for HIPAA-compliant patient data platforms under strict security rule adherence.
- Software Testing:Quality assurance automation, manual testing protocols, and security vulnerability assessment. Vietnamese delivery centers capture expanding North American demand for continuous testing integration within DevOps pipelines.
- UX/UI Design:User research, interface prototyping, and design system development.
- Maintenance Services:Legacy system support, bug resolution, and performance optimization.
Application Development commands the established base. The steepest expansion runs through Software Testing.
Deployment Model:
Cost tier stratification separates commodity managed services from premium cloud-native transformation engagements requiring specialized platform engineering talent.
- Cloud-based:Native AWS, Azure, or GCP application development with containerized deployment and serverless architectures. Indian engineering hubs in Bangalore and Hyderabad dominate this segment as enterprises accelerate legacy migration timelines.
- On-premises:Private data center application hosting with direct hardware control. European financial institutions in Frankfurt and Zurich retain on-premises mandates for core banking systems under ECB operational resilience requirements.
- Hybrid:Split workload distribution across cloud and private infrastructure.
- Managed Services:Fully outsourced infrastructure and application operations.
On-premises retains the established base. Cloud-based deployment is climbing the fastest.
Industry Vertical:
Application maturity determines offshore eligibility: healthcare and BFSI impose strict certification barriers, while retail and telecommunications permit faster vendor onboarding.
- Healthcare:Electronic health record systems, clinical decision support tools, and telemedicine platforms. US providers source Polish development centers for EU AI Act-aligned algorithmic transparency in diagnostic software.
- BFSI:Core banking modernization, payment processing infrastructure, and regulatory reporting systems. Singaporean banks contract Vietnamese engineering teams for ASEAN cross-border payment gateway development.
- Retail:E-commerce platforms, inventory management systems, and customer analytics tools.
- Telecommunications:Network management software, billing systems, and 5G service platforms.
BFSI commands the established base. Healthcare is gaining share fastest.
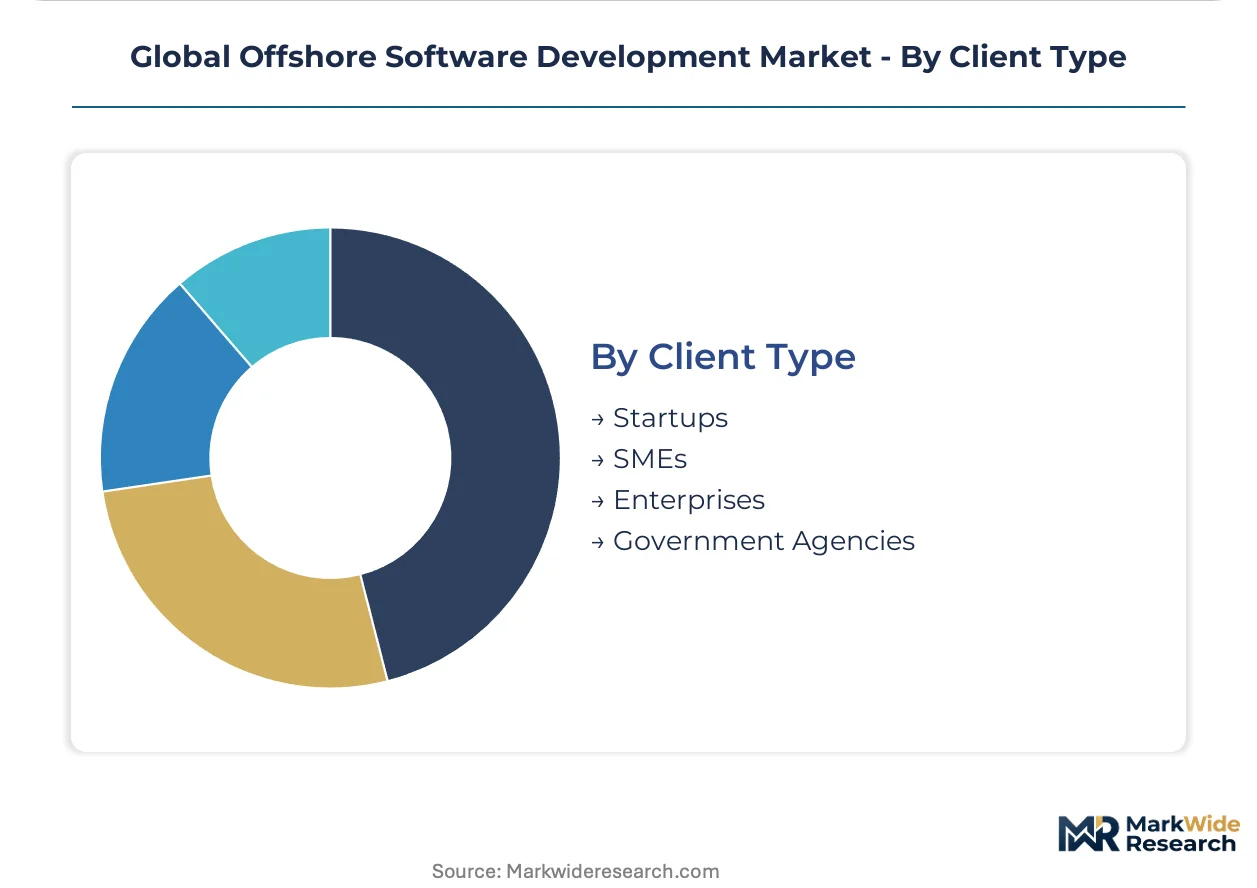
Client Type:
Volume concentration and margin profiles diverge: enterprises drive absolute contract value through multi-year transformation programs, while startups generate higher velocity but greater churn risk.
- Enterprises:Multi-year digital transformation contracts exceeding 500-person engineering allocations. German automotive manufacturers anchor Polish delivery center revenue through embedded software development for connected vehicle platforms.
- SMEs:Mid-market companies with limited in-house engineering capacity seeking agile capacity augmentation. Mexican nearshore centers capture growing US mid-market demand for Spanish-language Salesforce customization.
- Startups:Venture-backed companies requiring rapid MVP development and technical co-founding support.
- Government Agencies:Public sector IT modernization with strict security clearance and procurement compliance requirements.
Enterprises command the established base. SMEs represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian engineering hubs export application development services to North American healthcare enterprises seeking HIPAA-compliant patient data platforms. Polish delivery centers supply EU-regulated algorithmic systems to German automotive manufacturers. Vietnamese testing operations feed continuous integration pipelines for Singaporean banking infrastructure.
India
Bangalore and Hyderabad dominate cloud-native migration contracts for US technology enterprises. BIS cybersecurity standards filter which delivery centers qualify for sensitive-industry work. Hyderabad's engineering corridors concentrate DevOps automation talent as platform engineering demand accelerates.
Poland
Kraków and Wrocław capture embedded software development from German connected-vehicle programs. EU AI Act alignment certifications determine contract eligibility for diagnostic algorithm exports. Warsaw's delivery hubs specialize in fintech regulatory reporting systems under ECB operational resilience frameworks.
United States
Domestic enterprises consume nearshore alternatives from Mexico while contracting Indian centers for HIPAA-compliant healthcare platforms. FDA software-as-medical-device guidelines shape vendor selection for diagnostic tool development. Austin and Boston technology clusters drive demand for Latin American timezone-overlapping delivery.
Vietnam
Ho Chi Minh City engineering teams supply continuous testing integration for ASEAN cross-border payment gateways. The country's cybersecurity law fragments project architectures and raises compliance overhead for foreign clients. Da Nang's emerging tech corridors attract Japanese enterprise quality assurance contracts.
Mexico
Guadalajara and Mexico City nearshore centers capture US mid-market Salesforce customization demand seeking Spanish-language delivery. Timezone overlap with California technology clusters drives agile capacity augmentation contracts. Monterrey's engineering pools specialize in fintech platform customization for Texas banking clients.
Global Offshore Software Development Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and vertical expertise. The vendor base stratifies into three tiers: global scale operators with multi-country delivery footprints, regional specialists concentrating single-geography talent pools, and boutique shops serving narrow technology stacks. Dominant competitive moves include geographic expansion into nearshore corridors and strategic partnerships with cloud hyperscalers.
Within the nearshore Latin American tier, BairesDev exemplifies geographic positioning for North American timezone overlap. ELEKS and N-iX occupy positions within the European specialist tier, anchoring delivery models around EU regulatory alignment. These three represent divergent archetypes: timezone-proximity optimization, vertical certification depth, and multi-hub European coverage respectively.
| Leading Market Players |
|---|
| N-iX |
| Saigon Technology |
| ELEKS |
| eLuminous Technologies |
| Artkai |
| BairesDev |
| Space-O Technologies |
| Softura |
| SumatoSoft |
| Others |
Supply & Pricing Matrix
Generative AI code assistance tools replacing traditional manual development hours simultaneously concentrate supply geography in Indian engineering hubs and compress pricing economics for commodity application development tiers. This substitution dynamic forces mid-market buyers to recalibrate vendor selection around automation-augmented delivery models rather than headcount-based contracts.
Pricing Analysis
The cloud-native versus legacy-maintenance versus emerging AI-augmented pricing gap stratifies contract economics across offshore delivery tiers. Subscription-based engagement models with defined sprint velocity commitments now dominate enterprise procurement, replacing fixed-price waterfall specifications. Price differentiation rests on FedRAMP certification tier and vertical specialization depth, with HIPAA-compliant healthcare commands premium multiples over retail application development. Pricing pressure stems from low-code platform adoption compressing greenfield coding demand, while SMEs exhibit highest price sensitivity and government agencies demonstrate lowest.
Supply Chain Analysis
India and Poland anchor global application development capacity, while Vietnam concentrates quality assurance and testing operations. Raw talent inputs draw from Bangalore Institute of Technology pipelines, Warsaw Polytechnic programs, and Ho Chi Minh City software engineering academies. Supply chain risk centers on single-source vulnerability for platform engineering expertise concentrated in specific metropolitan corridors. Distribution runs through direct enterprise sales teams, channel partners, and cloud hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated enterprise procurement teams with multi-year transformation mandates, fragmenting vendor relationships into fewer, larger-scale engagements.
For Market Incumbents: Shield margin position by deepening EU AI Act certification investments in Polish delivery centers and accelerating DevOps automation tooling deployment. The threat of nearshore Latin American competitors capturing US mid-market timezone-overlap demand requires defensive geographic expansion into Mexico. Vertical integration into proprietary low-code platforms represents the critical lever for escaping commodity pricing tiers.
For New Entrants and Emerging Players: Anchor in Vietnamese quality assurance specialization for ASEAN banking infrastructure contracts, the most penetrable geography for testing-centric market entry. Target green software engineering consulting under EU CSRD carbon disclosure requirements as the fastest-expanding white-space segment. A channel partnership route through cloud hyperscaler marketplaces offers the most efficient go-to-market angle for unbranded engineering capacity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists holding single-geography delivery footprints and narrow vertical certifications. Long-term viability over the next decade hinges on automation-augmented delivery models and multi-jurisdiction compliance depth. Watch FDA software-as-medical-device guidance evolution as the signal indicating inflection toward specialized healthcare engineering premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Polish delivery centers capture German automotive algorithmic transparency contracts under ECB frameworks. |
| Nearshore Geographic Expansion | Mexican engineering pools secure US mid-market Salesforce customization demand with California timezone overlap. |
| Generative AI Tooling Deployment | Indian hubs accelerate application velocity through GitHub Copilot integration and custom LLM implementations. |
| HIPAA Compliance Specialization | Healthcare-focused vendors command premium pricing for patient data platform development under FDA guidance. |
| Green Software Engineering Services | EU CSRD carbon disclosure requirements open consulting revenue for energy-efficient code optimization expertise. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this analysis. CTOs at North American healthcare enterprises, IT procurement officers at German automotive manufacturers, platform engineers at Indian delivery centers, and channel partners at cloud hyperscalers provided operational perspective. Secondary sources include SEC 10-K disclosures, FDA software-as-medical-device guidance documents, EU AI Act implementation texts, and BIS cybersecurity standard publications. Bottom-up contract value aggregation and top-down market sizing triangulate volume estimates.
Sensitivity analysis around talent wage inflation rates and data localization compliance timelines informs the projection framework across the analysis window. Segmentation dimensions modeled include deployment model, organization size, industry vertical, integration complexity, and regional adoption pattern. CAGRs derive from historical contract velocity trends and forward-looking procurement intention surveys. Industry-specific inputs incorporate cloud migration pipeline disclosures and regulatory certification timeline data.
Material uncertainties — abrupt data localization mandate enforcement, generative AI capability disruption, and cross-border IP enforcement gaps — sit outside the modeled envelope. Forecasts reflect documented assumptions about talent pool expansion rates and compliance framework stability. Recalibration cycles align with material shifts in regulatory guidance and automation technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Gym Software Market
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Train Reservation Software Market
Software & Services
Cemetery Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Telecom IT Services Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
Electronic Design Automation Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
User Experience (UX) Research Software Market
Software & Services
Account Reconciliation Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Chemical Manufacturing Software Market
Software & Services
Virtual Studio Software Market