
 Luxury Watches Market | 2026-2036
Luxury Watches Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Watches Market Intelligence
The gap between artisanal haute horlogerie and mass-luxury quartz production is shifting from a price divide into a capability chasm. Rolex leverages captive foundries and in-house alloy development to control material provenance. Patek Philippe sustains multi-year waitlists through deliberate production scarcity rather than capacity constraints. Audemars Piguet differentiates via integrated manufacture of complex movements at its Le Brassus facility.
Luxury watches are precision timekeeping instruments constructed from engineered metals and synthetic ceramics, typically water-resistant to 100 meters or more, with mechanical variants housing mainsprings that deliver 38–72 hours of autonomous operation. Mechanical segments anchor margin pools through perpetual calendars and tourbillon complications that command six-figure price floors. Titanium and ceramic materials are gaining structural share as affluent consumers prioritize scratch resistance and reduced wrist weight over traditional gold investment appeal. Collector and gift buyer segments concentrate demand around limited editions with documented provenance.
Swissmedic and the Swiss Federal Customs Administration enforce origin labeling that restricts "Swiss Made" claims to watches with 60% minimum domestic manufacturing value. The EU REACH regulation and CSRD disclosure mandates compel brands to trace conflict minerals and carbon intensity through tier-three suppliers. Stakeholders must monitor how digital authentication technologies and blockchain-based provenance systems reshape secondary market liquidity and gray market arbitrage.
Market Dynamics
Mechanical complications are consolidating demand among ultra-high-net-worth collectors while EU supply-chain mandates force vertical restructuring across Swiss and German manufacturing clusters.
Growth Catalysts
- EU Green Deal mineral traceability:Mandatory conflict-mineral disclosure under REACH and CSRD is accelerating investment in blockchain-based provenance systems that authenticate heirloom-grade timepieces for secondary market liquidity.
- Titanium and ceramic material substitution:Affluent buyers prioritize scratch resistance and reduced wrist weight over traditional gold investment appeal, expanding addressable demand in sports-luxury segments.
- Geneva auction concentration:Phillips and Christie's biannual sales establish price benchmarks that validate six-figure complications as alternative-asset allocations for family offices.
Market Restraints
- Swiss Made origin thresholds:Swissmedic's 60% domestic manufacturing value requirement constrains brands seeking cost optimization through Asian component sourcing.
- Artisan skill scarcity:Master watchmakers capable of assembling tourbillon and perpetual calendar movements require 15-year training pipelines that cannot scale with collector demand.
- Quartz substitution in entry-luxury:Battery-powered alternatives from Japanese manufacturers capture wrist-share among consumers prioritizing accuracy over mechanical heritage.
Strategic Opportunities
- India's emerging HNI base:Mumbai and Delhi collector circles show underpenetrated demand for documented-provenance limited editions with sub-50-unit production runs.
- Digital authentication convergence:NFC-enabled casebacks paired with distributed-ledger records create defensible secondary-market platforms that capture gray-market arbitrage value.
- CSRD carbon-intensity disclosure:Early compliance positions brands for preferential placement in EU institutional procurement frameworks targeting ESG-mandated endowments.
Industry Challenges
- Movement-finishing skill gap:Beveling, anglage, and black-polishing expertise concentrates in Le Brassus and Vallée de Joux ateliers with no replication pathway.
- REACH chemical reauthorization timelines:Luminous compound and alloy formulation approvals delay product launches by 18-24 months.
- Heritage movement integration:Vintage calibre restoration for anniversary editions requires obsolete tooling reconstruction that strains R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Watches Market |
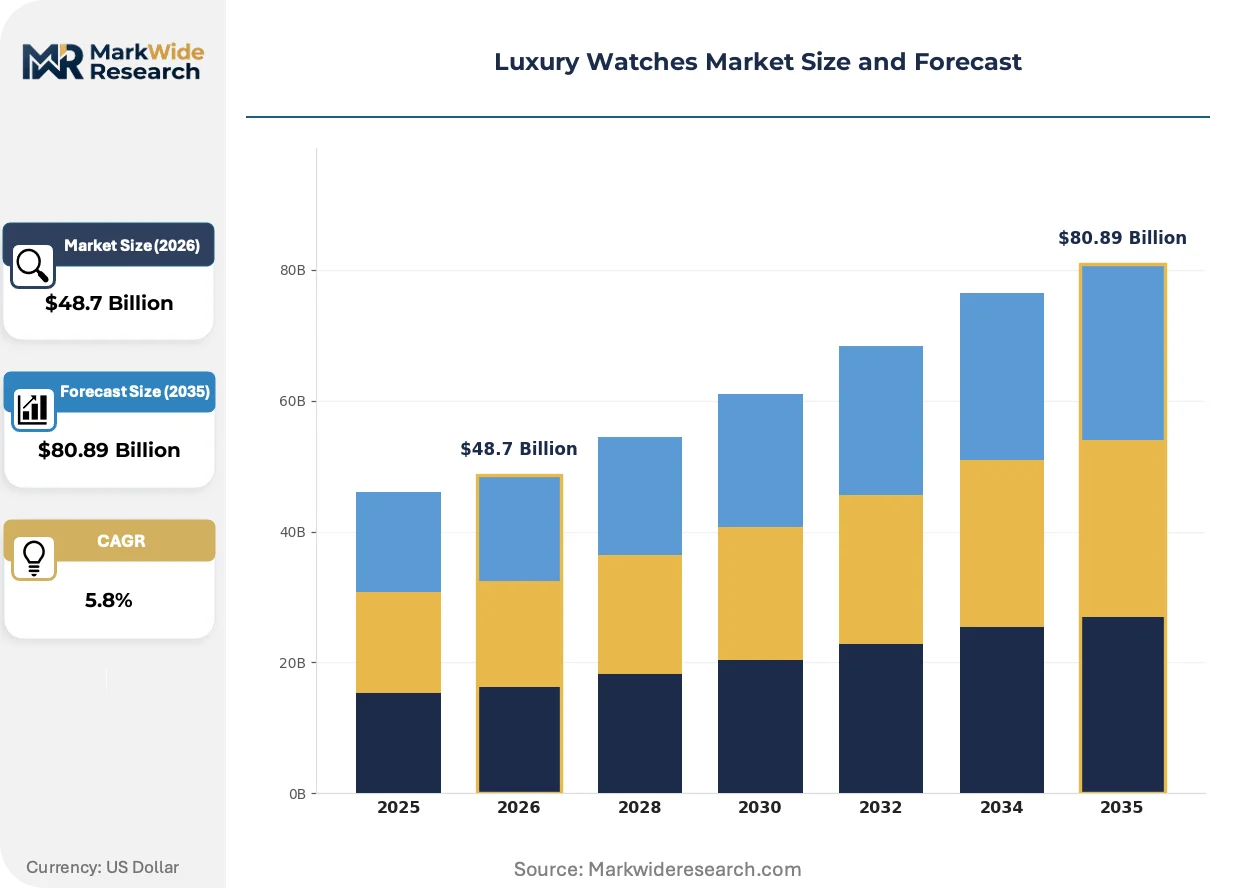
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Quartz, Smartwatch, Hybrid Material: Stainless Steel, Gold, Titanium, Ceramic Target Customer: Affluent Consumers, Collectors, Gift Buyers, Online Shoppers Distribution Channel: Luxury Retail Stores, Online Marketplaces, Department Stores, Boutiques |
| Companies Covered | Rolex, Cartier, Patek Philippe, Omega, Audemars Piguet, Vacheron Constantin, Jaeger-LeCoultre, IWC, Hublot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Watches Market Strategic Shifts & Innovations
Ceramic case construction and digital provenance infrastructure are compressing traditional metal-forming and paper-certificate value chains simultaneously.
Ceramic injection molding is overtaking CNC-machined precious metals in sports-luxury production. Younger collectors in Dubai and Singapore prioritize scratch immunity and matte finishing over patina development. This material shift is compressing margin pools historically anchored to gold and platinum case fabrication.
EU CSRD scope expansion mandates tier-three supplier carbon disclosure for all products sold in member states. Watch brands must now audit foundry energy consumption and transport emissions from raw material to finished calibre. Smaller maisons lacking compliance infrastructure face exclusion from institutional gift-buying programs.
Collector procurement now bypasses authorized dealers for direct manufacturer relationships through invitation-only salons. Waitlist management at Patek Philippe and Audemars Piguet has evolved into relationship-based allocation systems that reward prior purchase history. This disintermediation is most visible in Geneva and Le Brassus, where manufacture boutiques capture full retail margin previously shared with wholesale partners.
Luxury Watches Market Segmentation
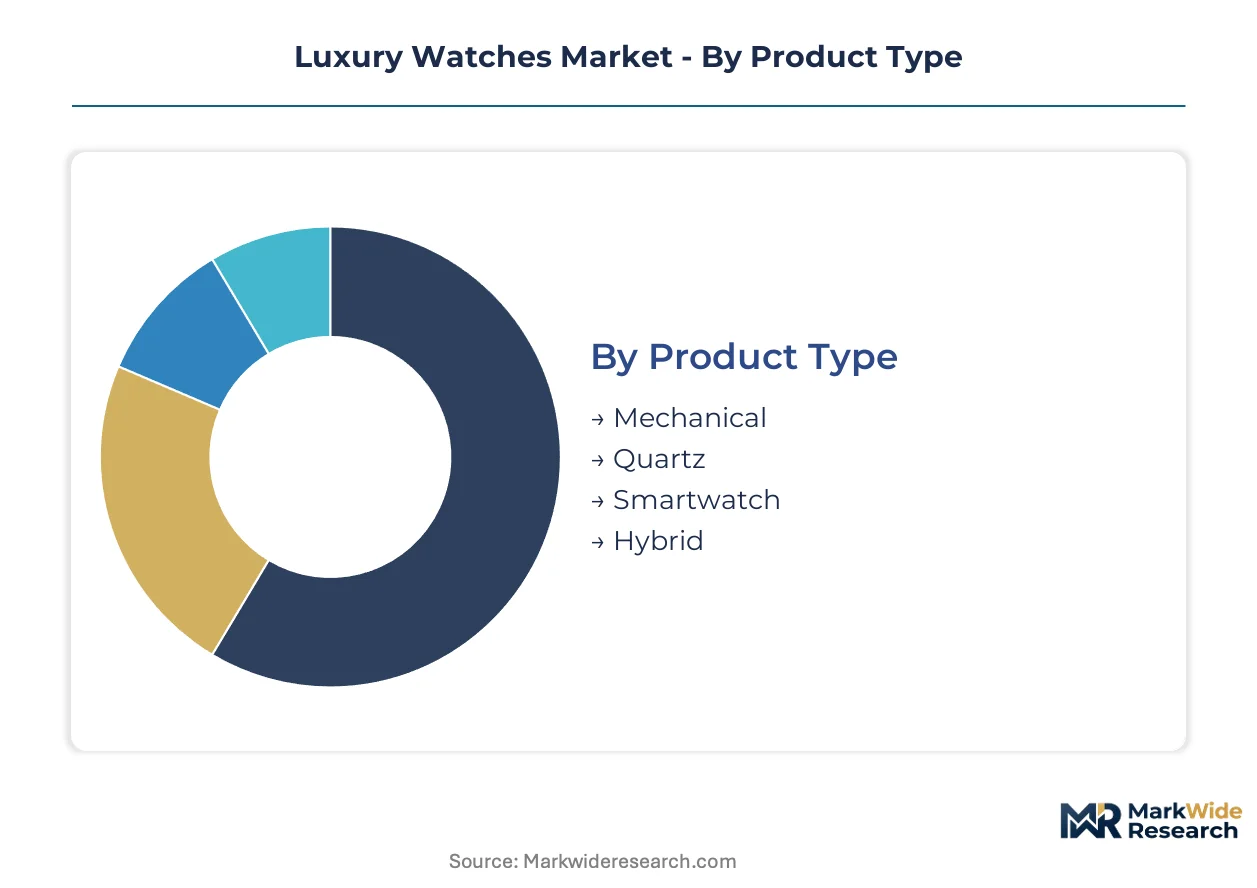
Segmentation in luxury watches separates heirloom-grade mechanical complications from mass-luxury quartz alternatives, with material and channel choices increasingly reflecting collector sophistication rather than mere price tiering. Distinct procurement behaviors among gift buyers, online shoppers, and auction-house collectors reshape how maisons allocate production and authenticate provenance.
Product Type:
The customization-to-standardization spectrum runs from hand-finished tourbillon movements requiring 15-year training pipelines to battery-powered quartz modules produced at industrial scale.
- Mechanical:Mainspring-driven calibers with 38–72 hour power reserves anchor margin pools through perpetual calendar and chronograph complications. Collector demand concentrates in Geneva and Le Brassus auction circuits where Phillips and Christie's establish six-figure price benchmarks for documented provenance pieces.
- Quartz:Battery-powered movements deliver accuracy superior to mechanical variants at entry-luxury price points. Japanese manufacturers capture wrist-share among consumers prioritizing precision over heritage, though Swiss Made origin thresholds constrain brand positioning in this tier.
- Smartwatch:Sensor-integrated wearables with fitness tracking and notification functions appeal to tech-forward affluent buyers seeking connectivity over horological tradition.
- Hybrid:Mechanical movements augmented with limited smart functionality bridge analog heritage and digital convenience for transitional consumer segments.
Leading the category by volume: Quartz. Expanding most quickly: Mechanical complications among ultra-high-net-worth collectors.
Material:
Cost tiering in this category stratifies from accessible stainless steel through precious metals to advanced ceramics commanding premium positioning through engineering rather than intrinsic value.
- Stainless Steel:316L and 904L grades provide corrosion resistance and machining compatibility for sports-luxury case construction. Rolex's Oystersteel formulation and captive foundry control create supply-side differentiation that supports multi-year waitlist management.
- Gold:18-karat yellow, rose, and white gold variants retain investment-appeal among traditional collectors, though scratch susceptibility and wrist weight drive substitution toward titanium and ceramic in daily-wear segments.
- Titanium:Grade 5 titanium alloys deliver strength-to-weight ratios approximately 40% lighter than steel with superior corrosion resistance. Dubai and Singapore collectors prioritize scratch immunity and reduced wrist mass over patina development.
- Ceramic:Zirconium oxide injection molding produces matte-finished cases with near-diamond hardness ratings. EU REACH chemical reauthorization timelines for luminous compounds and alloy formulations delay product launches by 18–24 months in this segment.
Steepest expansion trajectory: Ceramic. Maintaining revenue concentration: Gold in auction-house provenance sales.
Target Customer:
Customer-type segmentation reflects divergent procurement rituals, from relationship-based allocation systems for repeat collectors to impulse-driven online purchases requiring digital authentication infrastructure.
- Affluent Consumers:High-net-worth individuals purchasing for personal use prioritize brand heritage and resale value stability. Patek Philippe's invitation-only salons and manufacture boutiques in Geneva capture full retail margin through direct relationships.
- Collectors:Ultra-high-net-worth buyers concentrate demand around limited editions with sub-50-unit production runs and documented provenance. Mumbai and Delhi collector circles show underpenetrated demand for such pieces.
- Gift Buyers:Institutional and personal gift procurement targets recognizable brand signatures with established secondary market liquidity. CSRD carbon-intensity disclosure requirements now influence placement in ESG-mandated endowment programs.
- Online Shoppers:Digital-native affluent consumers bypass authorized dealers for direct manufacturer relationships, requiring NFC-enabled casebacks and blockchain-based provenance systems to authenticate purchases.
Highest transaction frequency: Affluent Consumers. Fastest channel shift: Online Shoppers migrating to manufacturer-direct platforms.
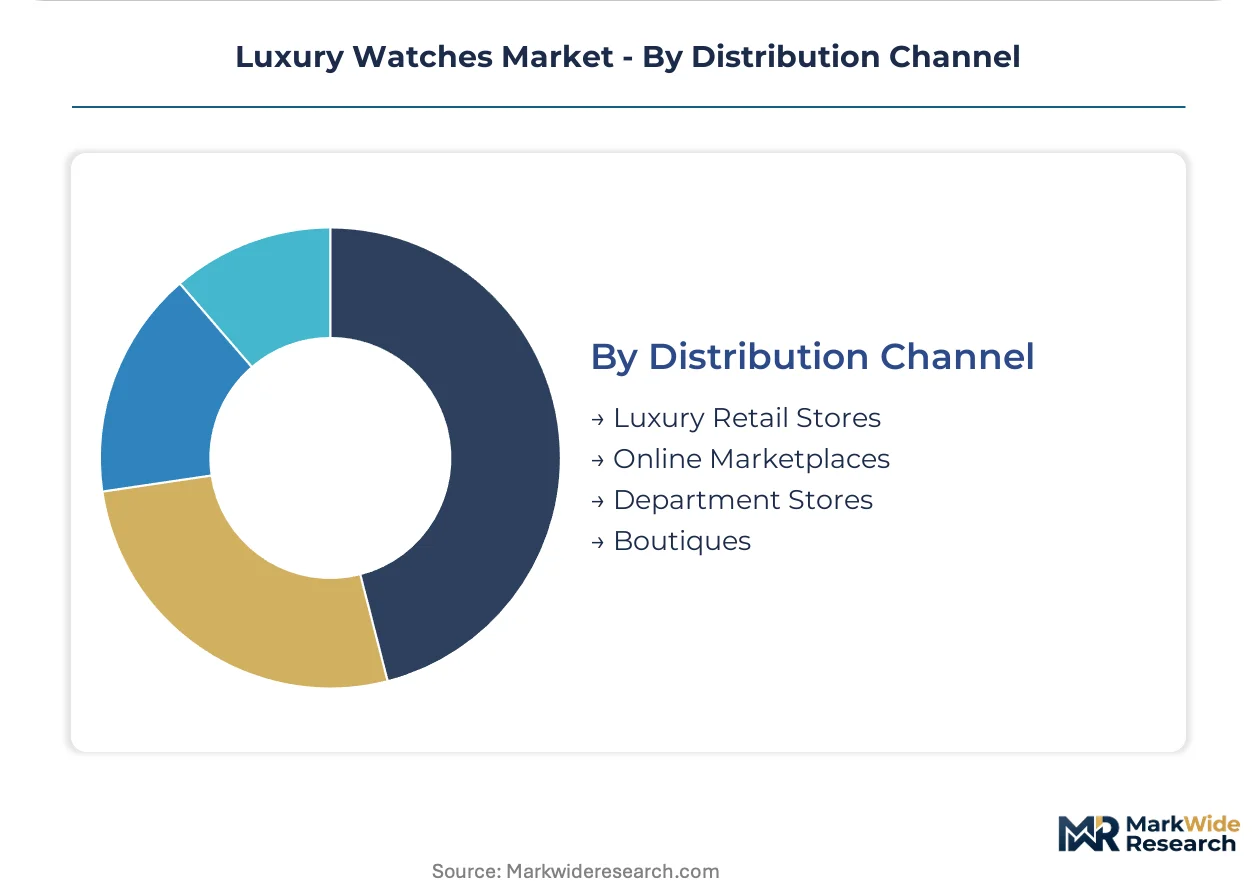
Distribution Channel:
Channel structure in this market compresses traditional wholesale relationships as manufacture boutiques and digital authentication platforms capture margin previously shared with third-party retailers.
- Luxury Retail Stores:Multi-brand authorized dealers in Geneva, Zurich, and Dubai maintain inventory breadth but face disintermediation as waitlist management evolves toward relationship-based allocation.
- Online Marketplaces:Secondary platforms with distributed-ledger provenance records create defensible liquidity for pre-owned pieces, capturing gray-market arbitrage value that previously escaped brand control.
- Department Stores:Traditional luxury concessions in Harrods, Galeries Lafayette, and Neiman Marcus serve entry-luxury segments with lower complication density.
- Boutiques:Single-brand manufacture locations in Le Brassus and Geneva enable direct collector engagement and full margin retention without wholesale partner participation.
Dominant by transaction value: Boutiques. Accelerating fastest: Online Marketplaces with integrated authentication technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geneva anchors the global luxury watches trade through Phillips and Christie's biannual auctions that establish price benchmarks for six-figure complications. Manufacturing gravity concentrates in Swiss and German clusters where REACH compliance and artisan skill scarcity reshape competitive positioning.
Switzerland
Collector demand concentrates in Geneva and Le Brassus auction circuits where documented-provenance limited editions command premium allocations. Swissmedic enforces 60% domestic manufacturing value thresholds for "Swiss Made" origin claims. The Vallée de Joux ateliers concentrate movement-finishing expertise for tourbillon and perpetual calendar complications.
United States
Family offices in New York and Los Angeles treat mechanical complications as alternative-asset allocations alongside traditional portfolios. The SEC regulates investment-advisor disclosures when timepieces appear in client holdings. Miami collector circles drive demand for titanium and ceramic sports-luxury variants with scratch-resistant properties.
United Arab Emirates
Dubai's luxury retail corridor captures Middle Eastern collector demand for limited editions with sub-50-unit production runs. MOHAP oversees product safety standards for imported timepieces. The Dubai Watch Week exhibition anchors regional manufacturer-direct engagement and invitation-only salon culture.
India
Mumbai and Delhi collector circles show underpenetrated demand for heirloom-grade mechanical complications with documented provenance. RBI foreign-exchange regulations govern cross-border purchases above specified thresholds. The Delhi-NCR corridor hosts emerging HNI acquisition patterns favoring relationship-based allocation systems.
China
Affluent consumers in Shanghai and Beijing prioritize brand heritage and resale value stability in personal-use acquisitions. SAMR enforces anti-counterfeiting measures and origin labeling requirements. The Hainan free-trade port experiment compresses import duties for luxury timepiece purchases.
Luxury Watches Market Key Industry Players
Premium-margin players sit above commodity-margin players across the capability chasm separating artisanal haute horlogerie from mass-luxury quartz production. The vendor base stratifies into vertically integrated maisons, specialist movement manufacturers, and fashion-house licensees. Three archetypes dominate: captive-foundry operators controlling material provenance, scarcity-engineered waitlist managers, and integrated manufactures of complex calibers. Competitive moves concentrate on blockchain-based provenance infrastructure and direct-to-collector boutique expansion.
Among Swiss-anchored maisons, Rolex, Patek Philippe, and Audemars Piguet exemplify distinct strategic archetypes within the premium tier. Rolex represents captive-foundry verticalization through in-house alloy development. Patek Philippe occupies the scarcity-engineered allocation position with multi-year waitlist management. Audemars Piguet anchors the integrated manufacture archetype through complex movement production at its Le Brassus facility.
| Leading Market Players |
|---|
| Rolex |
| Cartier |
| Patek Philippe |
| Omega |
| Audemars Piguet |
| Vacheron Constantin |
| Jaeger-LeCoultre |
| IWC |
| Hublot |
| Others |
Cost & Logistics Intelligence
Master watchmakers capable of assembling tourbillon and perpetual calendar movements concentrate in Le Brassus and Vallée de Joux ateliers, creating labor-cost differentials that sustain six-figure price floors for heirloom-grade complications while entry-luxury quartz variants compete on manufacturing scale rather than artisan scarcity.
Pricing Analysis
Value-based pricing anchored to documented provenance and mechanical complexity sustains premium tiers. Price differentiation separates perpetual calendar complications from standard three-hand movements based on finishing grade and waitlist scarcity. Pricing pressure stems from REACH chemical reauthorization timelines delaying product launches by 18-24 months. Gift buyers show highest price sensitivity to secondary market liquidity signals, while collectors exhibit minimal sensitivity to absolute price levels for sub-50-unit limited editions.
Supply Chain Analysis
Warehouse-distribution layers for finished timepieces center on Geneva and Dubai regional hubs serving auction houses and manufacture boutiques. Raw material dependencies include Swiss-origin gold alloys, Grade 5 titanium from specialized foundries, and zirconium oxide ceramic feedstock. Supply chain risk concentrates in single-source vulnerability for movement-finishing expertise concentrated in Vallée de Joux. Distribution runs through manufacturer-direct boutiques capturing full retail margin alongside authorized dealer networks facing disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EU CSRD carbon-intensity disclosure mandates and REACH compliance infrastructure requirements force smaller maisons toward acquisition or exit.
For Market Incumbents: Anticipate regulatory compliance costs accelerating competitive separation between vertically integrated maisons and component-dependent brands. Secure captive foundry capacity for titanium and ceramic alloy development to control material provenance narratives. Prioritize blockchain-based provenance infrastructure investment to capture gray-market arbitrage value escaping brand control. For New Entrants and Emerging Players: Capture white-space opportunity in India's Mumbai and Delhi collector circles where relationship-based allocation systems remain underpenetrated for documented-provenance limited editions. Target digital-native affluent consumers bypassing authorized dealers through NFC-enabled authentication platforms. Pursue go-to-market positioning around CSRD early compliance for preferential placement in ESG-mandated institutional procurement frameworks. For Investors and Strategic Acquirers: Re-rating potential sits with integrated manufactures possessing in-house complex movement capabilities given collector demand concentration around mechanical complications. Long-term viability favors archetypes with established Geneva auction circuit relationships and multi-year waitlist management infrastructure. Watch for inflection signals in secondary market liquidity metrics as digital authentication platforms reshape provenance verification economics.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | NFC-enabled casebacks paired with distributed-ledger records authenticate heirloom-grade pieces for institutional collectors. |
| Ceramic Manufacturing Scale-Up | Zirconium oxide injection molding capacity expansion addresses Dubai and Singapore demand for scratch-resistant sports-luxury variants. |
| Direct-to-Collector Boutique Expansion | Manufacture locations in Geneva and Le Brassus capture full retail margin previously shared with wholesale partners. |
| CSRD Compliance Infrastructure | Early tier-three supplier carbon disclosure positions brands for ESG-mandated endowment procurement frameworks. |
| Heritage Movement Restoration Capability | Vintage calibre reconstruction for anniversary editions sustains collector engagement through documented provenance narratives. |
Research Approach
Document review covered SEC filings from publicly traded luxury conglomerates, Swiss Federal Customs Administration trade statistics, and auction house transaction records, complemented by interviews with manufacture executives, master watchmakers, auction specialists, and collector circle principals. Secondary validation drew from Swissmedic regulatory guidance, EU REACH substance databases, and Phillips and Christie's catalogue archives. Bottom-up production volume estimates triangulated against top-down consumer expenditure patterns across the analysis window.
Cross-reference approaches balanced historical auction price trajectory analysis against expert panel input on collector preference shifts. Segmentation dimensions modeled include product type, material composition, target customer archetype, and distribution channel structure. CAGRs were derived through iterative reconciliation of supply-side capacity constraints with demand-side allocation system dynamics, incorporating artisan skill pipeline limitations and regulatory approval timeline inputs specific to chemical reauthorization requirements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical reauthorization delays, artisan training pipeline bottlenecks, and digital authentication platform adoption rates across secondary market participants. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
India Watch Market
Luxury Goods
Mexico Luxury Goods Market
Luxury Goods
United Arab Emirates Luxury Goods Market
Luxury Goods
Global Gold and Diamond Jewellery Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
France Luxury Goods Market
Luxury Goods
Luxury Goods Market
Luxury Goods
Spain Luxury Goods Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
China Luxury Market
Luxury Goods
Singapore Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market
Luxury Goods
United States Luxury Goods Market