
 Qatar Fruits and Vegetables Market | 2026-2036
Qatar Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Fruits and Vegetables Market Outlook
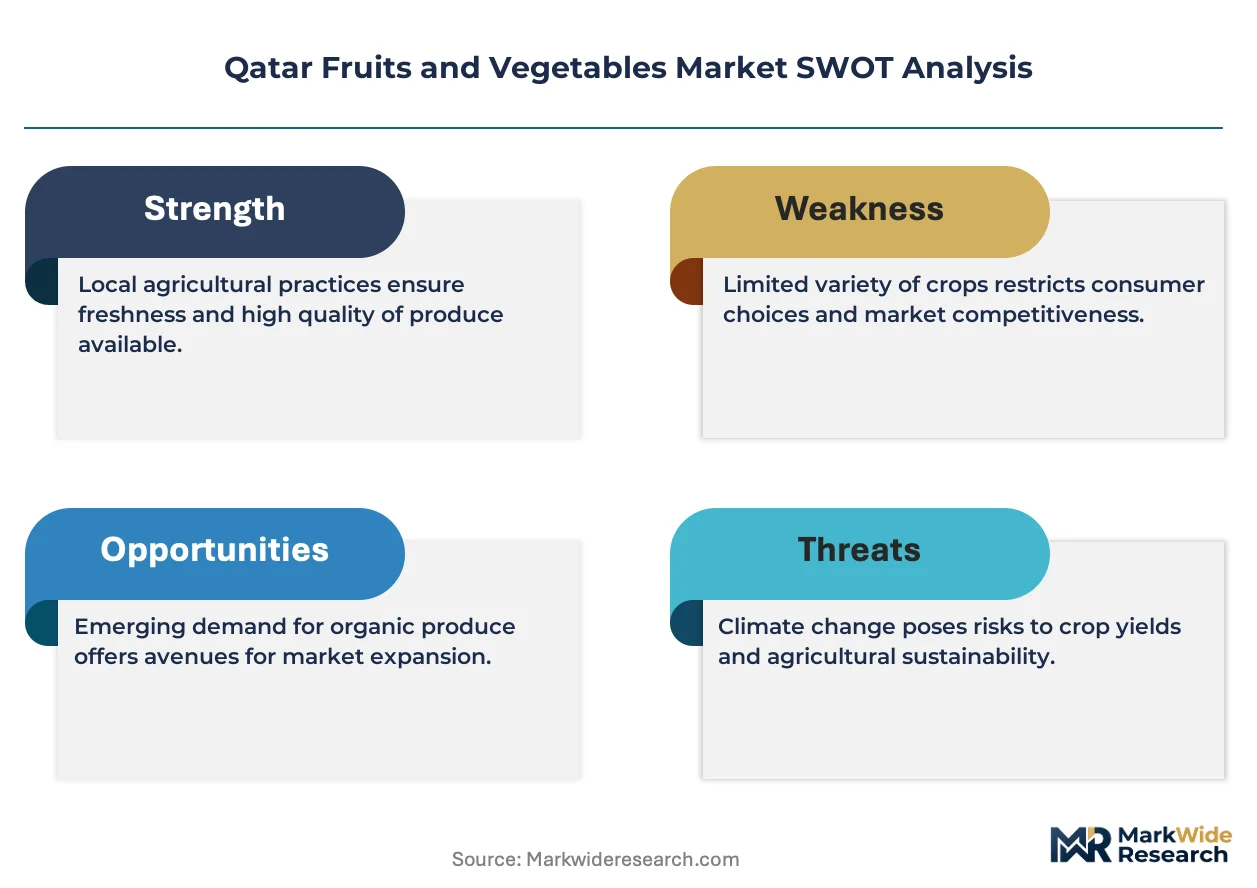
Project finance for climate-controlled greenhouse complexes is tilting competitive access toward capital-rich operators. Mahaseel leverages its state-backed funding to dominate domestic tomato and cucumber production. Al Meera Consumer Goods Company anchors retail distribution through its supermarket network across Doha and Al Wakrah. Hassad Food sustains supply security through backward integration into desert agriculture and international sourcing partnerships.
Qatar fruits and vegetables encompass fresh and minimally processed edible plant products cultivated through open-field, greenhouse, and hydroponic systems, with shelf life and phytonutrient retention determining commercial grading and pricing. The category serves household consumption, food service procurement, and industrial processing as its primary commercial purposes. Leafy Greens and Citrus command premium positioning due to perishability-driven logistics costs and import dependency. The Supermarkets channel captures the largest volume flow, while Online Retail registers the fastest expansion as delivery infrastructure matures across Doha. Restaurants and Catering Services within the End User dimension concentrate margin pools through contract-based procurement and specification buying.
Qatar's Ministry of Municipality and Environment enforces sanitary and phytosanitary standards on all inbound produce, while the Qatar General Organization for Standardization administers labeling and quality certification requirements that shape market access conditions. These frameworks elevate compliance costs for smaller traders while creating structured entry pathways for certified operators. Stakeholders must monitor regulatory adjustments to domestic cultivation incentives and import quota mechanisms as policy prioritizes food security sovereignty.
Market Dynamics
Climate-controlled greenhouse technology is concentrating production capacity among capital-rich operators in Qatar's domestic agriculture sector, reshaping competitive access and procurement patterns across Doha's food service corridor.
Growth Catalysts
- Food Security Sovereignty Mandates:Qatar's Ministry of Municipality and Environment prioritizes domestic cultivation incentives and import substitution programs. State-backed project finance flows toward controlled-environment agriculture infrastructure.
- Hospitality Procurement Expansion:Doha hotels and catering services scale fresh produce sourcing through contract-based specification buying. The capital's food service corridor drives volume concentration for premium-grade vegetables.
- Hydroponic System Diffusion:Soilless cultivation methods reduce water consumption by over 70 percent versus open-field farming. Commercial operators deploy nutrient film technique systems for year-round tomato and cucumber output.
Market Restraints
- Input Cost Volatility:Imported growing substrates and specialized nutrient solutions expose domestic producers to freight rate fluctuations and currency movements.
- Supply Concentration Risk:Perishable leafy greens depend heavily on air-freighted imports from Jordan, Lebanon, and European Mediterranean suppliers during summer months.
- Phytosanitary Compliance Friction:Qatar General Organization for Standardization labeling requirements and sanitary protocols elevate documentation burdens for smaller trading entrants.
Strategic Opportunities
- Al Wakrah Distribution Expansion:Retail infrastructure growth in Qatar's southern municipality creates underserved catchment areas for organized supermarket chains and online delivery platforms.
- Industrial Processing Integration:Minimally processed vegetable segments—pre-cut salads and ready-to-cook formats—attract contract manufacturing investment from food service distributors.
- Desert Agriculture Technology Convergence:Integration of solar desalination with greenhouse climate control enables saltwater-based irrigation at coastal production sites.
Industry Challenges
- Specialized Agronomy Talent Scarcity:Controlled-environment agriculture requires expertise in crop physiology, irrigation engineering, and integrated pest management that outpaces local training pipeline output.
- Certification Timeline Compression:Organic and GlobalGAP accreditation processes demand 18-to-24-month field audits that delay market access for new domestic entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Fruits and Vegetables Market |
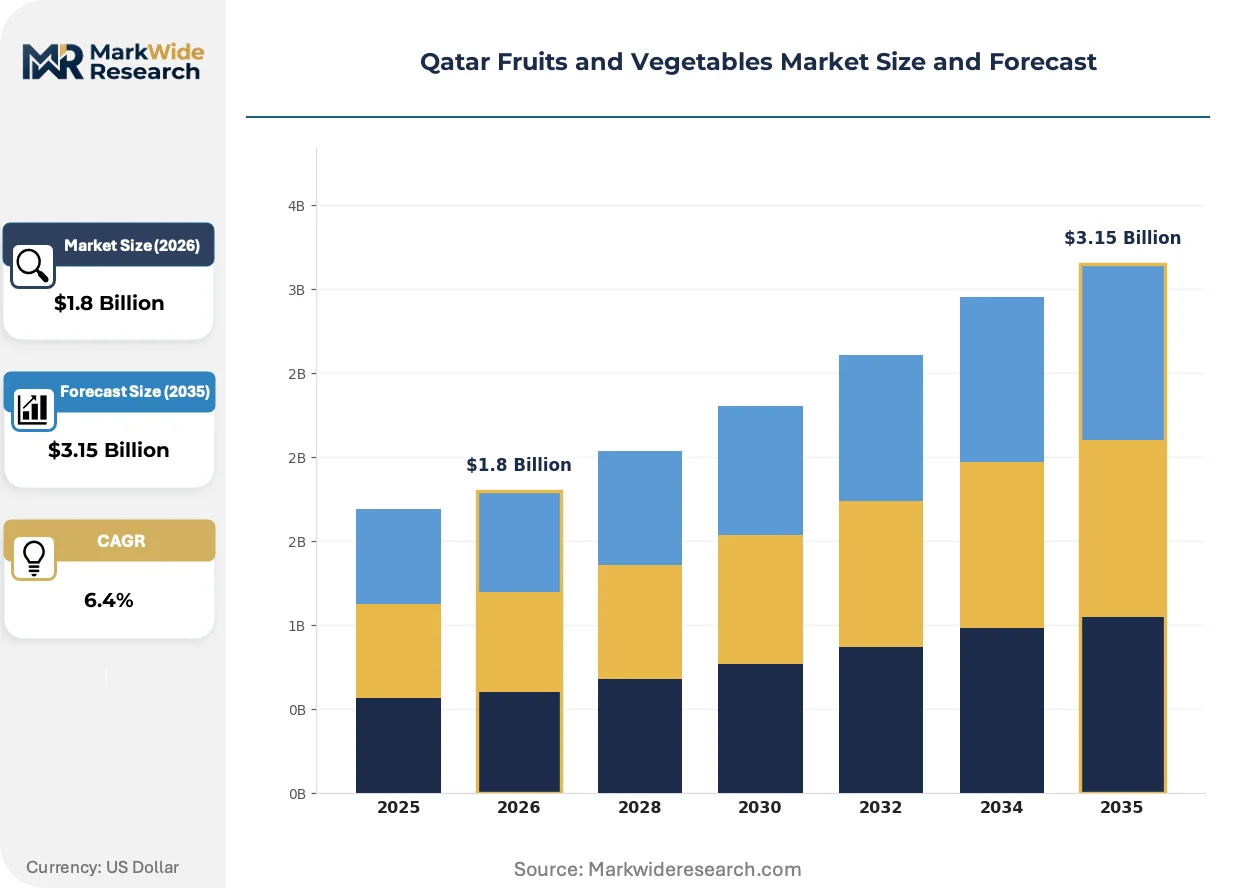
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Berries, Leafy Greens, Root Vegetables Distribution Channel: Supermarkets, Local Markets, Online Retail, Wholesale End User: Restaurants, Households, Catering Services, Food Processing Seasonality: Summer, Spring, Winter, Autumn |
| Companies Covered | Al Rawabi Projects, Mahaseel, Abu Khalifa, Al Rayyan Agricultural Company, Al Meera Consumer Goods Company, Arab Qatari Agricultural Production Company QATFA, Egy Fruit, Hassad Food, Qatarat Agricultural Development Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Fruits and Vegetables Market Strategic Shifts
Digital infrastructure is penetrating Qatar's fresh produce value chain at multiple points, from greenhouse automation to last-mile delivery optimization, compressing information asymmetries between growers and buyers.
Sensor-networked precision agriculture is virtualizing crop monitoring functions across Qatar's greenhouse complexes. Doha-based commercial tomato producers deploy IoT-enabled climate controllers that adjust humidity, light spectra, and CO2 concentration in real time. This virtualization of environmental management reduces labor input requirements while standardizing output quality grades for hospitality procurement contracts.
Qatar General Organization for Standardization tightened traceability mandates now require lot-level digital records for all imported and domestically produced fresh vegetables. The regulation forces distributors to implement blockchain-linked inventory systems that capture farm-origin data through retail point-of-sale. Supermarket operators in Doha and Al Wakrah accelerate compliance investments to avoid shipment detention at Hamad Port inspection facilities.
Specification buying now dominates procurement patterns among Qatar's hotel and catering segments. Food service buyers issue detailed quality protocols—brix levels, shelf-life minimums, cosmetic grading—that displace spot-market purchasing for core vegetable categories. This behavioral shift concentrates volume with certified domestic greenhouse operators and pre-qualified import suppliers who can document consistent compliance.
Qatar Fruits and Vegetables Market Segmentation
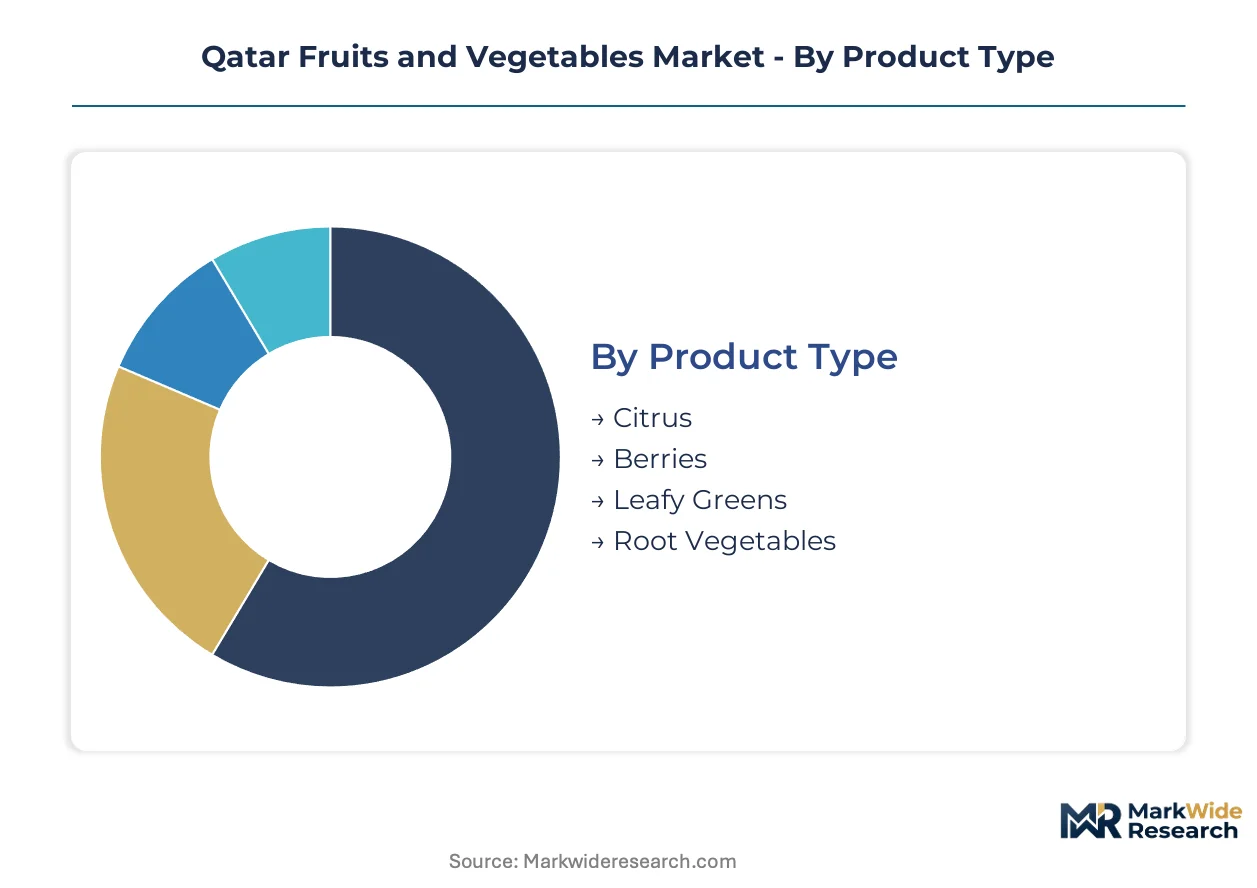
Segmentation in Qatar's produce market reveals how perishability cycles, procurement specifications, and channel infrastructure allocate margin pools across distinct commercial pathways. Each dimension exposes different pressure points for inventory management, compliance investment, and customer acquisition costs.
Product Type:
Turnover velocity varies dramatically across this dimension—leafy greens exhaust shelf life within days while root vegetables sustain weeks of storage, reshaping procurement rhythms and working capital requirements for distributors serving Doha's food service corridor.
- Leafy Greens:Highly perishable lettuce, spinach, and kale varieties demand cold-chain continuity from harvest through retail display. Qatar's hospitality procurement teams specify brix levels and cosmetic grades that concentrate orders with certified greenhouse operators near Al Wakrah who can guarantee 48-hour farm-to-kitchen cycles.
- Citrus:Oranges, lemons, and grapefruits offer extended shelf stability that reduces spoilage risk for importers navigating Hamad Port inspection delays. The Qatar General Organization for Standardization's phytosanitary documentation requirements favor established traders with blockchain-linked traceability systems for Egyptian and Spanish supply origins.
- Berries:Strawberries and blueberries command premium positioning due to air-freight dependency and temperature sensitivity during Qatar's summer months.
- Root Vegetables:Carrots, potatoes, and beetroot tolerate longer transit times and storage periods, enabling sea-freight sourcing from Indian subcontinent suppliers.
Root vegetables anchor the volume base while leafy greens gain share at the steepest rate as domestic greenhouse capacity expands.
Distribution Channel:
Cost-to-serve economics separate organized retail from fragmented trade—supermarkets absorb compliance and technology investments that informal channels cannot replicate, concentrating certified produce flows through formal infrastructure.
- Supermarkets:Al Meera Consumer Goods Company and comparable chains enforce lot-level traceability mandates from suppliers. Climate-controlled display cases and inventory management systems enable specification buying for premium produce categories that match hospitality procurement protocols.
- Online Retail:Delivery platform infrastructure matures fastest across Doha and Al Wakrah, with last-mile cold-chain investments compressing delivery windows to under two hours for perishable categories. This channel climbs fastest as smartphone penetration and subscription models reshape household replenishment behavior.
- Local Markets:Traditional souq traders dominate price-sensitive volume for staple vegetables through direct importer relationships.
- Wholesale:Centralized procurement for restaurants and catering services concentrates at dedicated produce terminals near industrial zones.
Supermarkets anchor the volume base while online retail expands most quickly as digital payment and logistics infrastructure mature.
End User:
Application requirements fragment procurement behavior—specification-driven contract buying dominates food service while households prioritize convenience and price accessibility through different channel choices.
- Restaurants:Doha's hotel and fine-dining segments issue detailed quality protocols covering cosmetic grading, shelf-life minimums, and origin documentation. This specification buying displaces spot-market purchasing and concentrates volume with pre-qualified domestic greenhouse operators and import suppliers.
- Catering Services:Large-scale event and institutional feeding operations demand consistent batch sizing and delivery scheduling that favors wholesale channel relationships with volume guarantees.
- Households:Family consumption splits between supermarket planned purchases and online impulse replenishment based on convenience positioning.
- Food Processing:Industrial users of minimally processed vegetables—pre-cut salads and ready-to-cook formats—require supply security through backward integration or long-term contracting.
Households anchor the volume base while catering services capture margin expansion through contract-based procurement consolidation.
Seasonality:
Supply geography shifts across the calendar—domestic greenhouse output peaks in winter while summer heat forces import dependency for perishable categories, restructuring logistics networks and inventory strategies.
- Summer:Extreme temperatures suspend open-field domestic production and strain greenhouse climate-control energy consumption. Air-freighted leafy greens from Jordan, Lebanon, and European Mediterranean suppliers dominate perishable supply during these months.
- Winter:Optimal greenhouse growing conditions enable peak domestic tomato and cucumber output from Mahaseel and comparable operators. Reduced cooling loads improve energy economics for controlled-environment agriculture.
- Spring:Transitional sourcing patterns blend declining import volumes with ramping domestic harvest cycles.
- Autumn:Planting schedules for winter greenhouse crops concentrate input procurement and agronomy labor demand.
Winter anchors the volume base while summer drives the steepest supply-chain cost escalation and import dependency concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's fruit and vegetable trade balance tilts heavily toward import dependency, with domestic greenhouse output covering roughly one-third of fresh produce consumption. The Ministry of Municipality and Environment channels state-backed financing toward controlled-environment agriculture to narrow this gap. Doha's food service corridor and Al Wakrah's emerging retail infrastructure concentrate demand geography.
Doha
Doha's hospitality procurement teams drive premium-grade vegetable demand through specification buying contracts with domestic greenhouse operators. The Qatar General Organization for Standardization enforces lot-level traceability mandates that favor certified suppliers with blockchain-linked inventory systems. Lusail and West Bay hotel clusters anchor the capital's food service corridor, where contract-based sourcing displaces spot-market purchasing.
Al Wakrah
Al Wakrah's retail infrastructure expansion creates underserved catchment areas for organized supermarket chains and online delivery platforms. The municipality's southern positioning near Hamad Port reduces inbound logistics costs for imported produce categories. Al Wakrah Industrial Area hosts wholesale terminals that concentrate procurement for catering services and institutional feeding operations.
Al Khor
Al Khor's coastal location enables saltwater-based irrigation integration with solar desalination for greenhouse complexes. Hassad Food maintains backward integration into desert agriculture across this northern municipality. The area's lower land costs attract capital-rich operators deploying climate-controlled tomato and cucumber production.
Al Shamal
Al Shamal's agrarian heritage supports open-field cultivation during winter months when temperatures permit reduced energy inputs. State-backed project finance flows toward coastal greenhouse development to extend growing seasons. The municipality's sparse population limits local demand, positioning production for Doha-bound distribution.
Qatar Fruits and Vegetables Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. Qatar's fruit and vegetable market concentrates around capital-rich operators with state-backed financing access and vertically integrated import distributors. Three archetypes dominate: domestic greenhouse producers with controlled-environment technology, retail-anchored distribution platforms, and sovereign wealth-linked food security vehicles. Competitive moves center on backward integration into desert agriculture and contract-based procurement consolidation with hospitality buyers.
Among state-backed cultivation platforms, Mahaseel exemplifies the capital-intensive greenhouse operator archetype through its dominance of domestic tomato and cucumber output. Hassad Food occupies a position within the sovereign wealth-linked food security tier, sustaining supply security through desert agriculture integration and international sourcing partnerships. Al Meera Consumer Goods Company represents the retail-anchored distribution archetype, anchoring volume flows through supermarket network coverage across Doha and Al Wakrah.
| Leading Market Players |
|---|
| Al Rawabi Projects |
| Mahaseel |
| Abu Khalifa |
| Al Rayyan Agricultural Company |
| Al Meera Consumer Goods Company |
| Arab Qatari Agricultural Production Company QATFA |
| Egy Fruit |
| Hassad Food |
| Qatarat Agricultural Development Company |
| Others |
Value Chain & Pricing Dynamics
Peak summer greenhouse undercapacity in Qatar's coastal production zones forces hospitality buyers toward air-freighted imports, compressing margins for domestic operators while elevating premium pricing power for certified suppliers with year-round climate-controlled output.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Qatar's food service corridor. Pricing stratifies across premium certified greenhouse grades, standard import-sourced tiers, and economy spot-market lots differentiated by traceability documentation and shelf-life guarantees. Cost compression in the standard tier is intensifying because freight rate volatility and currency movements on European and Lebanese leafy green imports erode importer margins. Quick-service restaurant chains exhibit highest price sensitivity due to volume procurement and limited specification flexibility, while five-star hotel procurement teams prioritize quality consistency over unit cost.
Supply Chain Analysis
Imported growing substrates from the Netherlands, specialized nutrient solutions from Germany, and polyethylene sheeting from China feed Qatar's controlled-environment agriculture expansion. Domestic production draws from these upstream inputs while perishable categories hinge on air-freighted supply from Jordan, Lebanon, and Spain during summer months. Single-source vulnerability concentrates in Dutch substrate suppliers, where freight rate spikes transmit directly to domestic greenhouse operating costs. Distribution runs through Al Meera's supermarket network, wholesale terminals near Hamad Port, and emerging online delivery platforms across Doha and Al Wakrah.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's fruits and vegetables sector sits in early-cycle expansion as state-backed project finance accelerates controlled-environment agriculture penetration and displaces import dependency for core vegetable categories.
For Market Incumbents: Build switching-cost moats through multi-year hospitality procurement contracts with specification protocols that lock in volume commitments. Deepen backward integration into desert agriculture at Al Khor coastal sites to secure saltwater irrigation capacity and reduce imported input exposure. Invest in blockchain-linked traceability systems ahead of Qatar General Organization for Standardization mandate expansions to preempt compliance-driven supplier displacement. For New Entrants and Emerging Players: Build out online retail infrastructure in Al Wakrah's underserved southern catchment, where smartphone penetration and subscription models outpace organized supermarket coverage. Target pre-cut salad and ready-to-cook minimally processed segments for contract manufacturing partnerships with food service distributors seeking supply security. Pursue organic and GlobalGAP certification early to capture 18-to-24-month accreditation timelines before competitor capacity saturates premium tier positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across climate-controlled greenhouse sub-segments as solar desalination integration and IoT-enabled precision agriculture become baseline competitive requirements. Focus acquisition screening on mid-scale operators with secured land tenure in Al Khor or Al Shamal and existing Qatar Ministry of Municipality and Environment cultivation licenses. Monitor state-backed financing disbursement velocity as the signal to watch for domestic production capacity inflection and import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Capacity Expansion | Mahaseel's state-backed greenhouse buildout concentrates domestic tomato and cucumber supply security. |
| Backward Integration into Desert Agriculture | Hassad Food's Al Khor coastal sites enable saltwater irrigation and reduce imported substrate dependency. |
| Blockchain Traceability Implementation | Al Meera's lot-level digital records satisfy Qatar General Organization for Standardization detention avoidance. |
| Online Retail Platform Development | Delivery infrastructure maturation across Doha and Al Wakrah captures fastest-expanding household channel. |
| Certification Pre-Investment | Early GlobalGAP and organic field audit initiation secures 18-to-24-month accreditation before competitor saturation. |
Study Parameters
Desk research of customs import records, Qatar Ministry of Municipality and Environment cultivation license databases, and hospitality procurement contract disclosures preceded structured interviews with greenhouse operations managers, food service procurement directors, supermarket category buyers, and controlled-environment agriculture technology suppliers. Secondary validation drew from Qatar General Organization for Standardization regulatory filings, Hamad Port throughput statistics, and state-backed project finance disbursement reports. Bottom-up cultivation capacity modeling and top-down consumption demand estimation were triangulated against trade balance data.
Fixed assumptions across the modeling period held Qatar's food security sovereignty mandates and phytosanitary compliance frameworks stable while varying domestic greenhouse capacity expansion rates, freight cost trajectories, and currency exchange bands. Segmentation dimensions modeled included product perishability tier, distribution channel format, end-user application, and seasonal supply geography. CAGRs were derived from capacity buildout schedules and import substitution elasticity estimates, with hospitality procurement volume growth and household online adoption curves as primary demand-side inputs.
Stress conditions across freight rate volatility, certification timeline delays, and agronomy talent pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that regulatory adjustments to import quota mechanisms or domestic cultivation incentive structures could materially revise trajectory. Cross-checking against Qatar Central Bank trade statistics and Ministry of Municipality and Environment agricultural output surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
South America Lime Market