
 Inflatable Pool Market | 2026-2036
Inflatable Pool Market Size, Share, and Industry Trends Forecast 2026-2036
Inflatable Pool Market Analytics
A shift from single-source PVC procurement to multi-source material contracts is realigning how inflatable pool manufacturers manage cost volatility and supply assurance. Bestway leverages its integrated manufacturing footprint across Guangdong to sustain margin control on family-size and kiddie pool lines. Intex competes through direct-to-consumer channel dominance in North America, while Blue Wave anchors its position via specialty retail partnerships with regional sporting goods chains.
An inflatable pool is a temporary, air-supported water containment structure typically fabricated from reinforced PVC or vinyl layers with heat-welded seams, designed for seasonal residential recreation, commercial event deployment, or institutional aquatic programs. Above-ground and portable product types currently occupy the largest volume share, though family-size units are generating expanding margin pools as consumers prioritize multi-user capacity. PVC remains the dominant material segment due to its weldability and cost structure, while nylon-reinforced variants are gaining traction in commercial and event organizer channels where puncture resistance commands price premiums.
The US Consumer Product Safety Commission and the EU's REACH regulation impose divergent phthalate and heavy-metal limits on vinyl materials, forcing suppliers to maintain dual formulation streams or migrate to compliant chemistries universally. China's GB standards for toy and recreational products add a third compliance layer for export-oriented manufacturers. Stakeholders must monitor evolving state-level chemical disclosure rules in California and pending EU F-Gas considerations for any insulated or heated inflatable spa hybrids that blur category boundaries.
Market Dynamics
REACH and California Proposition 65 are forcing PVC formulation changes that ripple through material procurement and manufacturing economics. Dual compliance streams raise working capital requirements for suppliers serving both European and North American buyers.
Growth Catalysts
- Suburban backyard recreation expansion:Residential buyers across the United States are installing larger family-size units with multi-user capacity, extending the seasonal usage window through heated variants.
- REACH-compliant chemistry migration:European regulatory pressure on phthalate content is accelerating universal formulation shifts that reduce complexity for exporters serving multiple jurisdictions.
- Nylon-reinforced commercial adoption:Event organizers and institutional aquatic programs are specifying puncture-resistant materials for high-frequency deployment cycles.
Market Restraints
- PVC resin cost volatility:Feedstock fluctuations tied to ethylene markets compress margin predictability for manufacturers without multi-year material contracts.
- Guangdong production concentration:Integrated manufacturing clusters in southern China create geographic supply risk amplified by shipping rate instability.
- Seasonal demand compression:Northern hemisphere weather patterns limit revenue recognition to discrete quarters, constraining inventory turnover efficiency.
Strategic Opportunities
- German specialty retail channel expansion:Regional sporting goods partnerships offer margin premiums unavailable through mass-market distribution.
- EU F-Gas Regulation tailwind:Insulated inflatable spa hybrids face evolving efficiency standards that favor early movers with compliant thermal designs.
- Direct-to-consumer platform scaling:E-commerce infrastructure investments enable margin capture previously allocated to wholesale intermediaries.
Industry Challenges
- Welding technician scarcity:Heat-seam certification programs have not scaled with production capacity expansion, creating quality assurance bottlenecks.
- Dual formulation inventory management:Maintaining separate REACH and Proposition 65 compliant material streams complicates production scheduling and working capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflatable Pool Market |
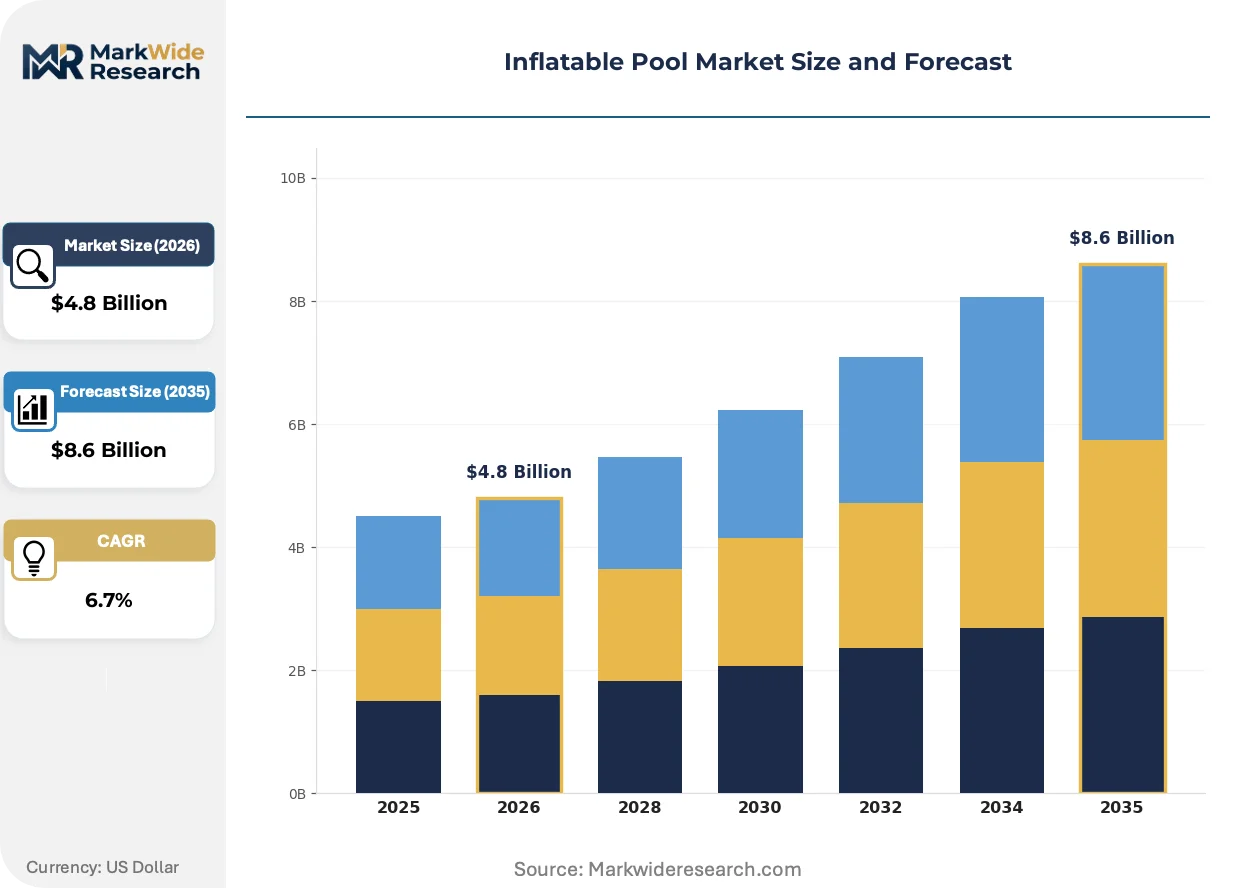
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Above Ground, Portable, Family Size, Kiddie Material: PVC, Vinyl, Rubber, Nylon End User: Residential, Commercial, Event Organizers, Schools Distribution Channel: Online Retail, Physical Stores, Distributors, Event Rentals |
| Companies Covered | Jilong, Blue Wave, Intex, EVAJOY, Summer Escapes, Bestway, Summer Waves, Members Mark, Bounce Horizon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflatable Pool Market Evolving Landscape
Material science advances and channel restructuring are compressing traditional manufacturing timelines while opening new margin pools in commercial deployment segments.
Drop-stitch construction technology is modularizing inflatable pool architecture by enabling rigid-wall designs that collapse for transport yet hold structural integrity under water load. Commercial operators in the United States are specifying these units for mobile aquatic programming. The technology is modularizing supplier relationships as specialized fabricators displace integrated manufacturers in high-performance segments.
ECHA's evolving guidance on SVHC candidate list substances is tightening disclosure obligations for vinyl product importers into the European Union. Manufacturers must now maintain granular supply chain documentation to satisfy downstream communication requirements. Family-size pool exporters to Germany and France are consolidating supplier bases to reduce traceability complexity.
Seasonal pre-order aggregation is compressing the traditional wholesale buying calendar as large-format retailers commit to volume six months ahead of delivery. Specialty sporting goods chains are displacing general merchandise distributors for premium-positioned products. This pattern is most visible in suburban United States markets where installation services bundle with product sales.
Inflatable Pool Market Segmentation
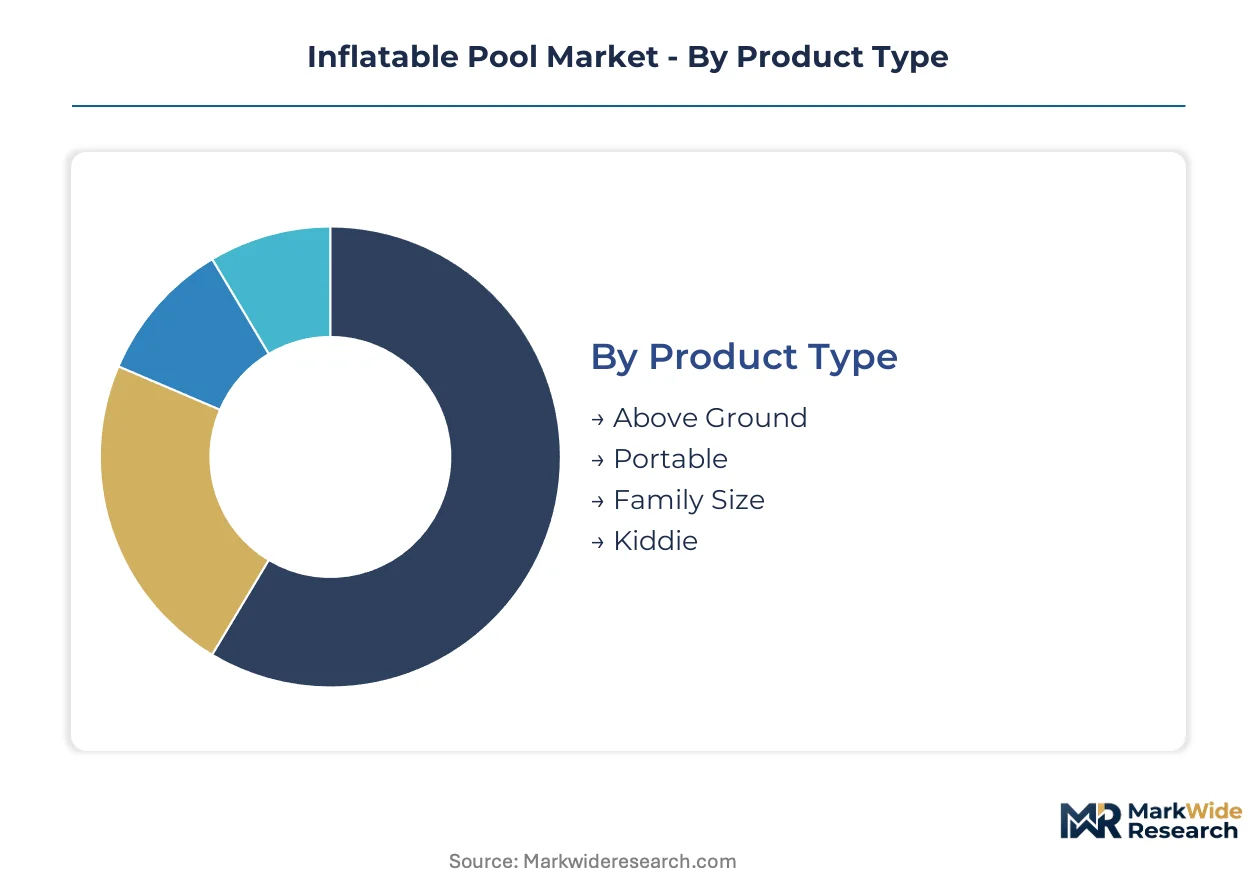
Inflatable pool procurement decisions split across four distinct category systems, each imposing unique compliance and margin structures on suppliers. Understanding how certification burdens, material specifications, and channel economics intersect within each dimension enables precise targeting of high-value customer segments.
Product Type:
REACH and California Proposition 65 compliance requirements vary sharply by product scale, with larger units triggering additional structural load-testing documentation for EU CE marking and US CPSC safety certifications.
- Above Ground:Rigid-frame designs with reinforced sidewalls support water depths exceeding 36 inches. Demand concentrates in suburban United States markets where installation services bundle with retail purchases, though seasonal inventory compression limits margin capture for distributors without pre-order aggregation capabilities.
- Portable:Collapsible designs with rapid-deflation valves target mobile deployment scenarios. Event organizers in Germany specify these units for municipal aquatic programming, with puncture-resistance requirements driving specification toward nylon-reinforced variants that command price premiums over standard PVC construction.
- Family Size:Multi-user capacity designs with integrated seating and filtration compatibility.
- Kiddie:Shallow-depth units with soft-bottom construction for toddler safety.
Above Ground sits at the top of the volume ranking, with Portable climbing the fastest.
Material:
Raw material selection determines dual-formulation inventory burdens, with phthalate-content thresholds diverging between European REACH limits and California Proposition 65 disclosure triggers.
- PVC:Thermoplastic polymer with heat-weldable seams remains the dominant substrate due to cost structure and manufacturing scalability. Guangdong-based integrated producers maintain captive resin supply to buffer ethylene feedstock volatility, though REACH-compliant formulation migration is compressing margin spreads on export-oriented production.
- Nylon:Woven reinforcement layers laminated to polymer substrates deliver puncture resistance for commercial deployment cycles. Event rental operators in the United States specify these materials for high-frequency rotation, with durability warranties becoming a decisive procurement criterion against first-cost competition.
- Vinyl:Flexible PVC formulations with plasticizer blends for cold-weather flexibility.
- Rubber:Natural and synthetic elastomer compounds for specialty chemical resistance applications.
PVC commands the largest production volume, while Nylon gains share fastest in commercial channels.
End User:
Customer type dictates warranty terms, delivery cadence, and after-sales service intensity, with institutional accounts requiring extended liability coverage that reshapes supplier working capital deployment.
- Residential:Seasonal consumers purchasing through mass-market retail and direct-to-consumer platforms. Suburban United States buyers prioritize family-size capacity with heated variant compatibility, extending usage windows into shoulder seasons and improving per-unit lifetime value calculations for manufacturers.
- Commercial:Fitness centers, campgrounds, and hospitality operators with year-round deployment requirements. These accounts specify drop-stitch rigid-wall construction for structural integrity under continuous water load, consolidating procurement with specialized fabricators who displace integrated manufacturers in premium segments.
- Event Organizers:Mobile aquatic programming specialists with rapid-setup requirements.
- Schools:Institutional aquatic programs with liability-sensitive procurement protocols.
Residential absorbs the highest unit volume, with Commercial expanding most quickly as fitness and hospitality sectors adopt aquatic programming.
Distribution Channel:
Channel selection determines margin capture versus working capital intensity, with direct-to-consumer platforms compressing wholesale intermediaries while specialty retail partnerships sustain premium positioning.
- Online Retail:E-commerce platforms enabling manufacturer-direct sales with six-month pre-order aggregation. United States market leaders leverage proprietary logistics infrastructure to control last-mile delivery costs during seasonal demand spikes, capturing margin pools previously allocated to distributor networks.
- Physical Stores:Mass-market and specialty retail with immediate fulfillment and installation service bundling. German sporting goods chains command premium positioning for family-size units through technical consultation and assembly services unavailable through pure-play digital channels.
- Distributors:Wholesale intermediaries with regional inventory positioning for rapid replenishment.
- Event Rentals:Short-term deployment specialists with fleet management and maintenance capabilities.
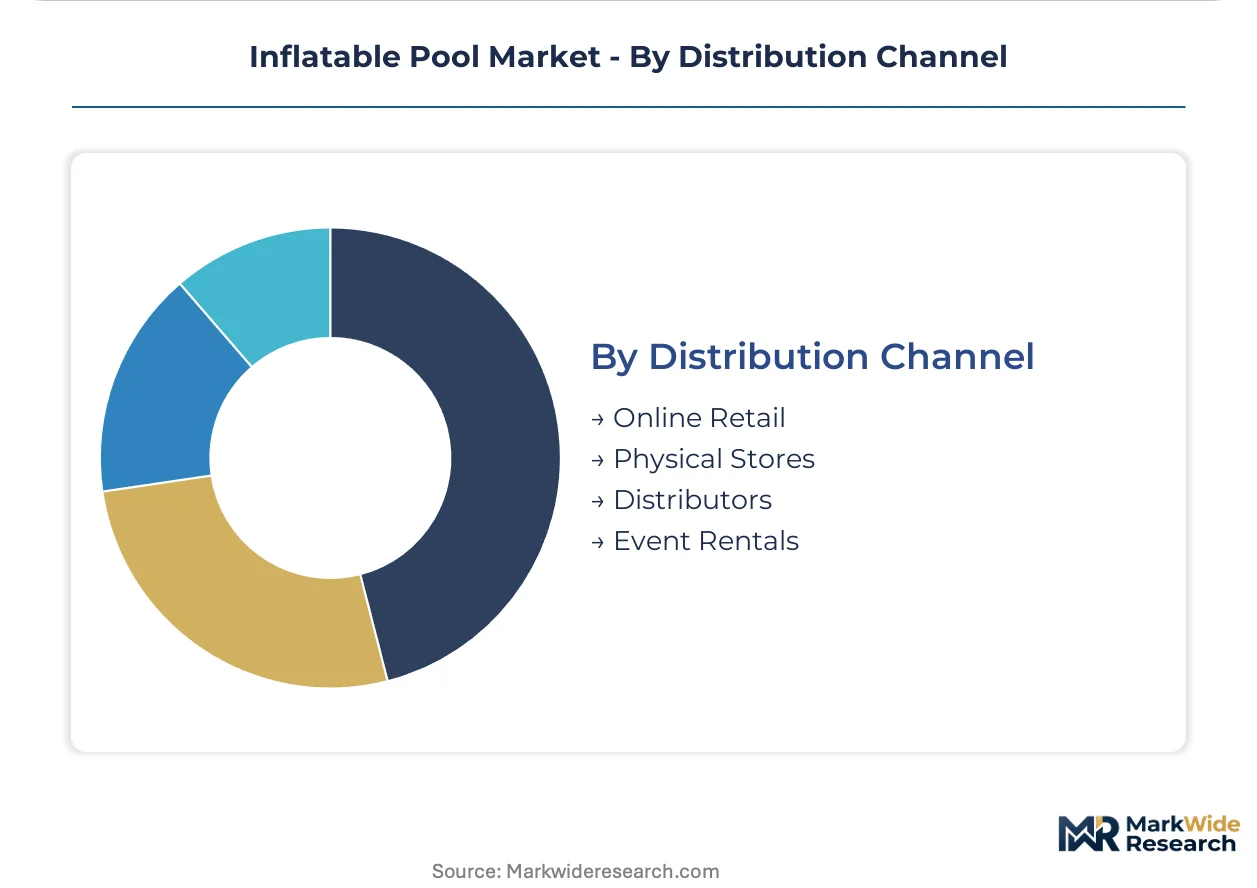
Online Retail leads transaction volume growth, with Physical Stores retaining margin superiority in premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors manufacturing capacity for inflatable pool production, with integrated clusters supplying export markets across North America and Europe. Demand concentration splits between suburban United States residential buyers and German specialty retail channels. Regulatory divergence between REACH and California Proposition 65 is reshaping supplier compliance strategies across all major consumption zones.
United States
Suburban backyard recreation drives family-size unit demand, with heated variants extending seasonal usage windows. The US Consumer Product Safety Commission enforces phthalate limits on vinyl materials that diverge from European thresholds. Installation service bundling concentrates in Sun Belt metros like Phoenix and Dallas-Fort Worth, where year-round deployment supports premium positioning.
China
Export-oriented manufacturers face dual formulation pressures from REACH migration and domestic GB standards for toy safety. Guangdong's integrated production clusters in Dongguan and Shenzhen maintain captive PVC resin supply to buffer feedstock volatility. Drop-stitch rigid-wall fabrication is modularizing supplier relationships as specialized fabricators displace integrated producers in high-performance segments.
Germany
Specialty sporting goods chains command margin premiums through technical consultation and assembly services unavailable through mass-market channels. ECHA's evolving SVHC candidate list documentation requirements tighten supply chain traceability for vinyl importers. Bavaria and North Rhine-Westphalia host distribution hubs serving EU-wide seasonal pre-order aggregation.
Canada
Health Canada and PMRA oversight on recreational product materials adds a fourth compliance layer for North American suppliers. Shorter seasonal windows in Prairie Provinces compress inventory turnover efficiency for distributors without pre-order systems. Ontario and British Columbia concentrate residential demand for family-size units with filtration compatibility.
Mexico
Proximity to United States distribution networks supports near-shoring assembly for mass-market portable units. Mexican regulatory alignment with US CPSC standards simplifies dual-market formulation strategies. Manufacturing activity concentrates in Nuevo León and Baja California for logistics access to southwestern United States retail channels.
Inflatable Pool Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue drop-stitch rigid-wall specialization and direct-to-consumer platform scaling. The vendor base arranges across three maturity tiers: integrated manufacturers with captive resin supply, specialized fabricators licensing modular construction technologies, and digital-native brands leveraging pre-order aggregation. Competitive positioning hinges on multi-source material contracts, welding technician certification programs, and seasonal inventory financing structures. Capacity expansion and strategic channel partnerships represent the dominant competitive moves as suppliers defend margin pools against feedstock volatility.
Among Asia-Pacific integrated manufacturers, Bestway and Jilong exemplify scale-driven archetypes with Guangdong-based production footprints. Intex occupies a position within the direct-to-consumer channel tier, anchoring North American e-commerce infrastructure investments. Blue Wave represents specialty retail partnership strategies, sitting within the premium-positioning archetype through regional sporting goods chain relationships. These three company structures illustrate how geographic origin and channel focus stratify competitive positioning without requiring identical compliance or sourcing architectures.
| Leading Market Players |
|---|
| Jilong |
| Blue Wave |
| Intex |
| EVAJOY |
| Summer Escapes |
| Bestway |
| Summer Waves |
| Members Mark |
| Bounce Horizon |
| Others |
Value Network & Pricing Analysis
Drop-stitch construction technology is displacing traditional heat-welded PVC fabrication, concentrating high-performance production among specialized fabricators in Guangdong while compressing margin spreads for integrated manufacturers serving mass-market segments. This method transition simultaneously elevates working capital requirements for certification-heavy rigid-wall designs and fragments supply relationships away from captive resin producers toward modular component suppliers.
Pricing Analysis
Ethylene feedstock pass-through dominates cost structures for standard PVC inflatable pools, with Guangdong-based manufacturers buffering volatility through multi-year resin contracts. Price differentiation separates REACH-certified export tiers from domestic-grade formulations, with German specialty retail channels commanding premium positioning through bundled installation services. Pricing pressure stems from seasonal demand compression in northern hemisphere markets, where inventory carrying costs intensify during off-peak quarters. Residential buyers through mass-market channels exhibit highest price sensitivity, while commercial event organizers prioritize durability warranties over first-cost considerations.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong Province's integrated manufacturing clusters, where Dongguan and Shenzhen production concentration creates geographic risk amplified by shipping rate instability. Raw material dependencies center on PVC resin, nylon reinforcement fibers, and phthalate-free plasticizer formulations. Supply chain risk manifests through dual-formulation inventory burdens as REACH and California Proposition 65 compliance streams diverge. Distribution runs through seasonal pre-order aggregation with six-month lead commitments to large-format retailers, compressing traditional wholesale buying calendars.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inflatable pool market functions as a stable compounder anchored by suburban backyard recreation expansion across the United States, where family-size unit installation sustains recurring seasonal demand with limited cyclical amplitude.
For Market Incumbents: Extend backward integration into captive resin supply to buffer ethylene feedstock volatility, while consolidating welding technician certification programs to resolve quality assurance bottlenecks threatening production scaling. Dual-formulation inventory management complexity represents the primary margin pressure point requiring automated production scheduling investment. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for insulated inflatable spa hybrids with compliant thermal designs, where early movers capture margin premiums unavailable in saturated standard pool segments. White-space targets include Bavaria specialty retail partnerships and drop-stitch rigid-wall fabrication for commercial fitness operators. Direct-to-consumer platform scaling offers the most penetrable go-to-market angle against established wholesale intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized fabricators licensing modular construction technologies, where capability scarcity in heat-seam certification and drop-stitch expertise creates defensive moats. Long-term viability frames around five-to-ten year windows as regulatory chemistry migration consolidates supplier bases. The signal to watch is pre-order aggregation volume commitments from large-format retailers, indicating channel power shifts toward manufacturers with proprietary logistics infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Material Contracting | REACH-compliant formulation migration in Germany and France reduces supplier concentration risk for export-oriented manufacturers. |
| Welding Technician Certification Scaling | Heat-seam quality assurance bottlenecks in Guangdong clusters constrain production capacity expansion without workforce investment. |
| Direct-to-Consumer Platform Investment | Proprietary logistics infrastructure in the United States captures margin pools previously allocated to distributor networks. |
| Drop-Stitch Technology Licensing | Modular rigid-wall fabrication displaces integrated manufacturers in commercial segments requiring structural integrity under continuous water load. |
| Pre-Order Aggregation Systems | Six-month volume commitments from large-format retailers compress wholesale buying calendars and improve inventory turnover efficiency. |
Research Methodology
Multiple input streams — executive interviews with manufacturing plant managers and procurement leads at downstream retailers, customs and trade flow databases, and SEC filing disclosures — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged inflatable pool product development directors, sporting goods category buyers, and commercial event rental fleet managers across the United States, Germany, and China. Secondary validation drew from CPSC safety compliance records, ECHA SVHC candidate list documentation, and Guangdong provincial industrial output statistics.
Historical volume trajectories were cross-referenced against panel-based demand indicators across the projection horizon. Segmentation modeling incorporated product type, material specification, end-user category, and distribution channel dimensions. CAGRs were derived through iterative reconciliation of production capacity expansion announcements, seasonal demand pattern analysis, and regulatory compliance cost absorption estimates. Forecast inputs included ethylene feedstock price sensitivity curves and REACH formulation migration timelines.
Revisions become necessary when phthalate regulatory thresholds tighten beyond current REACH or Proposition 65 baselines, or when shipping rate volatility disrupts Guangdong export economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Camping Utensils Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Above Ground Swimming Pools Market
Outdoor & Sports
Kids Scooter Market
Outdoor & Sports
Swimming Pool and Spa Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
Autonomous Golf Caddy Market