
 Compound Bow and Crossbows Market | 2026-2036
Compound Bow and Crossbows Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Bow and Crossbows Market Insights
United States manufacturing capacity for archery equipment is reshaping supply dynamics across North America. Bowtech leverages vertical integration to control carbon fiber limb production from raw prepreg to finished bow. TenPoint Crossbow Technologies anchors its position through in-house CNC machining of precision trigger housings. Hoyt Archery competes by sustaining R&D intensity in cam synchronization systems for tournament-grade compound bows.
Compound bows and crossbows are projectile weapons that store mechanical energy in flexed limbs, transferring it through cables, cams, or pulleys to accelerate arrows or bolts at speeds exceeding 300 feet per second; carbon fiber composite limbs now dominate premium construction for their strength-to-weight ratio and fatigue resistance. The primary commercial purpose spans regulated hunting, target archery competition, and recreational shooting sports governed by wildlife agencies and sporting federations. Product type segmentation reveals crossbows capturing disproportionate growth as aging hunters and mobility-limited archers shift toward cocking-device-assisted platforms. Material segmentation shows carbon fiber commanding margin pools in the premium tier while aluminum sustains volume in entry-level compound bows through cost-efficient extrusion processes.
Federal and state wildlife agencies across the United States set season structures and equipment specifications that directly determine addressable demand for crossbow and compound bow manufacturers. The EPA regulates finishes and coatings under volatile organic compound standards affecting manufacturing processes. ASTM International maintains equipment safety standards that influence product liability exposure and insurance costs for manufacturers. Stakeholders must monitor evolving state-level crossbow legalization trends and corresponding equipment certification requirements to anticipate demand inflection points.
Market Dynamics
Carbon fiber limb technology is virtualizing traditional aluminum extrusion in premium compound bow architectures, compressing manufacturing lead times while forcing incumbent suppliers to retool composite curing facilities or exit the premium tier entirely.
Growth Catalysts
- Expanded Crossbow Seasons:State wildlife agencies across the United States are lengthening legal hunting windows for crossbow platforms, directly enlarging the addressable hunter base for cocking-device-assisted equipment.
- REACH Compliance Migration:European archery manufacturers are reformulating limb resins and bow finishes to meet ECHA substance restrictions, accelerating adoption of pre-impregnated carbon fiber systems that inherently reduce volatile organic compound exposure.
- Aging Hunter Demographics:Mobility-limited archers in North America are gravitating toward crank-cock crossbows that eliminate the physical draw weight barrier, expanding participation among hunters over age 55.
Market Restraints
- Prepreg Carbon Fiber Concentration:Toray Industries and Hexcel Corporation control approximately 70% of aerospace-grade carbon fiber supply, exposing bow manufacturers to allocation risk during defense procurement surges.
- State-by-State Equipment Variability:Wildlife agencies in Ohio, Pennsylvania, and Texas maintain conflicting minimum draw weight and broadhead specifications, fragmenting product standardization and inflating SKU complexity.
- Airgun Substitution in Small Game:PCP air rifles are capturing varmint and small-game hunters in jurisdictions where discharge noise restrictions tighten, eroding entry-level compound bow demand among recreational shooters.
Strategic Opportunities
- 3D Archery Tournament Expansion:The International Archery Federation is formalizing compound bow divisions for Olympic-adjacent events, creating certification-driven demand for tournament-grade cam synchronization systems.
- Direct-to-Consumer Assembly Kits:Manufacturers are bypassing pro-shop intermediaries by shipping modular limb-riser packages with video-guided home assembly, capturing margin previously allocated to retail markup.
- Indian Sporting Goods Liberalization:India's DGFT is easing import restrictions on recreational archery equipment under revised sporting goods tariff codes, opening distribution channels for mid-priced aluminum-riser compound bows.
Industry Challenges
- Composite Lamination Technician Scarcity:Bow manufacturers in Utah and Wisconsin report 18-month backlogs for certified prepreg layup specialists, constraining carbon fiber limb production scaling.
- ASTM F1161 Recertification Burden:Crossbow trigger mechanism redesigns require full retesting under updated safety standards, extending product development cycles by 8-12 months for mechanical release innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Bow and Crossbows Market |
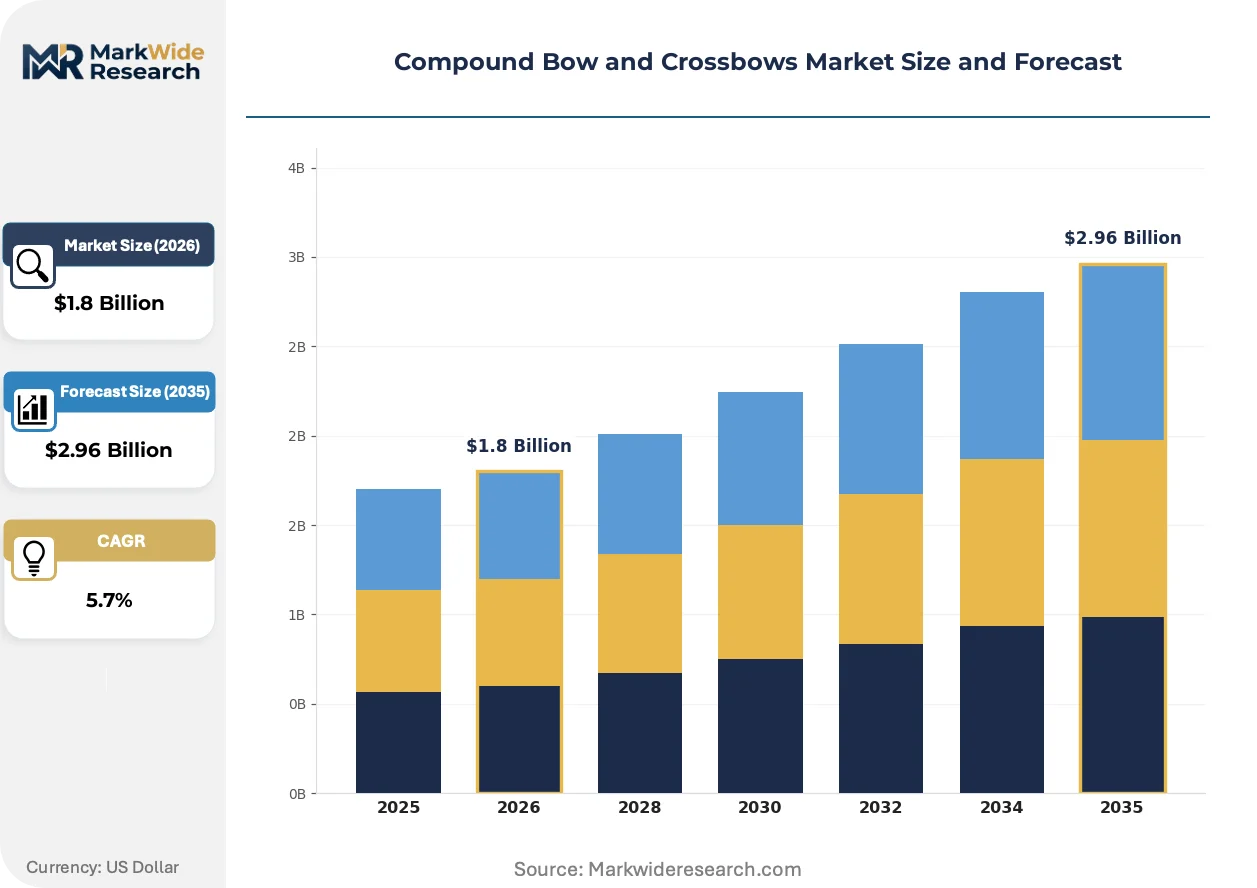
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compound Bows, Crossbows, Recurve Bows, Traditional Bows End User: Archers, Hunters, Competitors, Recreational Users Material: Aluminum, Carbon Fiber, Wood, Composite Power Source: Cocking Devices, Manual Systems, Mechanical Triggers, Electronic Systems |
| Companies Covered | Bowtech, Barnett Crossbows, TenPoint Crossbow Technologies, PSE Archery, Mathews Archery, Hoyt Archery, Excalibur Crossbow, Ravin Crossbows, Darton Archery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Bow and Crossbows Market Trends and Innovations
Digital manufacturing workflows are penetrating archery equipment production, compressing prototyping cycles and enabling mass customization of draw-length modules previously constrained by fixed tooling economics.
Carbon fiber prepreg systems are virtualizing aluminum limb fabrication across premium compound bow lines. Elite tournament archers and backcountry hunters are adopting these platforms at accelerating rates, drawn by fatigue resistance and tunable flex profiles. This shift is virtualizing the traditional foundry-to-extrusion supply chain, forcing aluminum suppliers to pivot toward entry-tier recreational markets or exit archery entirely.
The EPA's volatile organic compound standards for industrial coatings are tightening compliance windows for bow finish applications. Manufacturers are responding by migrating to water-based dip and spray systems, absorbing capital expenditure for curing oven retrofits. Crossbow producers with integrated finishing operations face the steepest adaptation costs, while outsourced coating houses gain contract manufacturing share.
After-sales service is unbundling from traditional pro-shop networks as manufacturers deploy mobile tuning applications and video diagnostic platforms. Hunters in remote western states are diagnosing cam timing issues through smartphone-guided procedures rather than traveling to authorized dealers. This behavioral pivot is compressing the independent archery retail channel, concentrating technical support capability within manufacturer direct channels and select regional specialists.
Compound Bow and Crossbows Market Segmentation
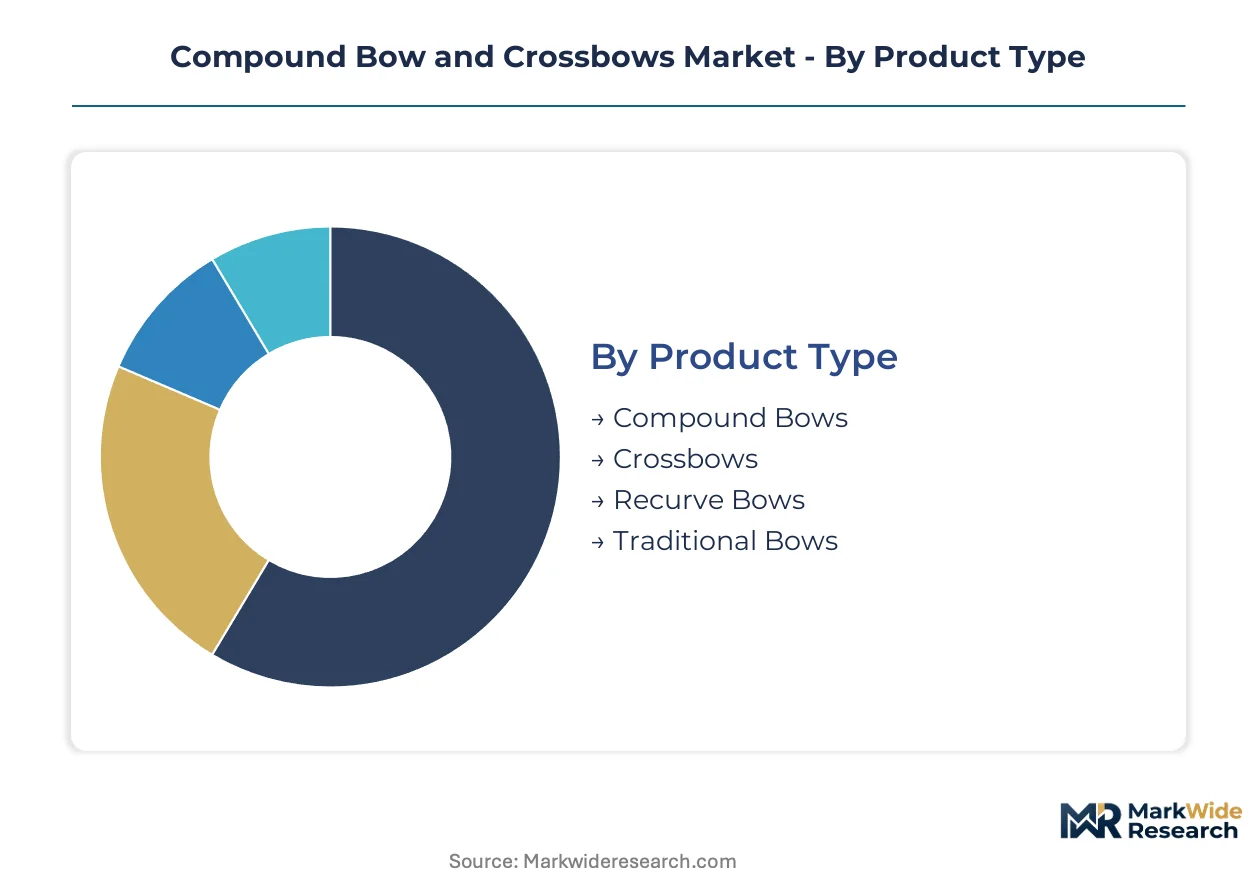
Segmentation in archery equipment markets determines pricing architecture, distribution channel selection, and regulatory compliance pathways. Manufacturers configure production lines around material tiers and power-source categories that align with divergent end-user capabilities and jurisdictional equipment standards.
Product Type:
Cost tier stratification separates premium carbon-limb platforms from entry-level aluminum alternatives, with each tier commanding distinct margin pools and certification requirements.
- Compound Bows:Eccentric cam systems store mechanical energy in flexed limbs, enabling adjustable draw weights and let-off percentages that reduce holding strain at full draw. Tournament archers in the United States and backcountry hunters across Montana and Idaho concentrate demand here, driven by cam synchronization precision for ethical shot placement at extended ranges.
- Crossbows:Horizontal limb assemblies mounted on rifle-style stocks accept crank-cock devices that eliminate physical draw barriers. Aging hunters in Ohio, Pennsylvania, and Texas rotate toward this platform as state wildlife agencies expand legal hunting seasons, making this category the fastest-expanding trajectory among product types.
- Recurve Bows:Simple curved limb geometry without mechanical advantage systems sustains Olympic competition specifications and traditional hunting rituals.
- Traditional Bows:Self-bow and longbow constructions from wood or synthetic laminates serve historical reenactment and instinctive shooting disciplines.
Compound bows hold installed capacity across North American pro-shop networks. Crossbows are rotating up the share rankings as season structures liberalize.
End User:
Application context dictates equipment specifications, with hunting regulations and competition rulesets creating non-interchangeable demand pools.
- Hunters:Harvest-ethics requirements in the United States mandate minimum kinetic energy thresholds for big-game qualification, driving specification-sensitive procurement. State wildlife agencies in Wisconsin, Michigan, and Georgia enforce these standards, with crossbow cocking-device adoption accelerating among mobility-limited participants.
- Competitors:Tournament archers require cam synchronization tolerances within thousandths of an inch for repeatable arrow flight. USA Archery and World Archery certification protocols in Arizona and California training centers enforce equipment homologation, concentrating demand for precision-machined risers and limb alignment systems.
- Archers:Technical proficiency development programs in university and club settings sustain demand for adjustable-draw compound platforms.
- Recreational Users:Casual target shooting and family-oriented range activities prioritize cost accessibility over performance optimization.
Hunters command the steepest expansion trajectory among end-user categories. Competitors maintain the highest specification sensitivity and replacement frequency.
Material:
Supply concentration and processing complexity create divergent margin structures across material categories.
- Carbon Fiber:Pre-impregnated composite layups deliver strength-to-weight ratios exceeding aluminum by factors of three, with fatigue resistance enabling decade-long service life. Backcountry hunters in Colorado and Utah and tournament competitors in South Dakota and Nebraska drive premium-tier demand, constrained by Toray Industries and Hexcel Corporation supply allocation during defense procurement surges.
- Aluminum:Extruded riser blanks and forged limb pockets sustain entry-level volume through cost-efficient processing at Midwest fabrication facilities. Youth programs and first-time buyers in Kansas and Oklahoma concentrate demand here, with pricing pressure from Asian extrusion competitors compressing domestic manufacturer margins.
- Wood:Traditional bowyers and historical reenactment practitioners sustain niche demand for Osage orange, yew, and laminated bamboo constructions.
- Composite:Glass-reinforced polymer limbs and injection-molded riser components bridge cost and performance tiers for recreational market entry points.
Carbon fiber captures margin concentration in premium tiers. Aluminum sustains volume throughput in entry-level channels.
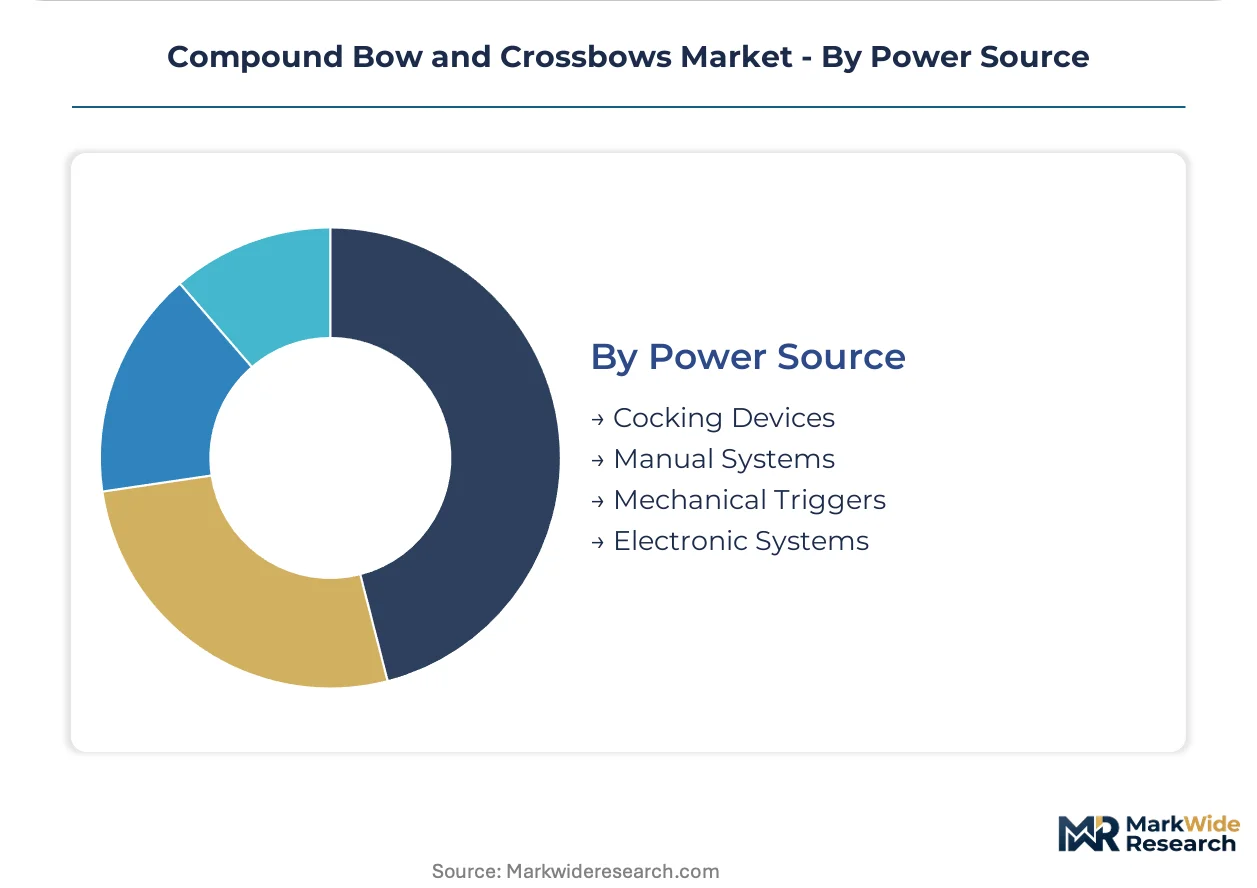
Power Source:
Customer physical capability and regulatory permissiveness determine power-source adoption patterns across jurisdictions.
- Cocking Devices:Crank mechanisms and rope-assist systems reduce draw force requirements to sub-ten-pound efforts, enabling crossbow use by hunters with shoulder limitations or reduced upper-body strength. The aging demographic in Florida, Arizona, and North Carolina expands this category fastest, with season-structure liberalization removing historical equipment restrictions.
- Mechanical Triggers:Sear-based release mechanisms with sub-three-pound pull weights and anti-dry-fire safeties dominate crossbow safety certification. ASTM F1161 testing protocols extend development cycles for trigger housing redesigns, concentrating supplier capability with CNC machining specialists in Wisconsin and New York.
- Manual Systems:Direct limb deflection by hand or foot-stirrup remains standard for traditional recurve and compound bow platforms.
- Electronic Systems:Solenoid-actuated releases and digital draw-force sensors serve experimental and accessibility-adapted applications with limited regulatory acceptance.
Cocking devices gain share fastest among power-source categories. Mechanical triggers anchor safety-critical supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber prepreg supply concentrates among Japanese and American chemical conglomerates, forcing bow manufacturers to secure long-term allocation agreements or absorb spot-market volatility during defense procurement cycles.
United States
State wildlife agencies in Ohio, Pennsylvania, and Texas are extending crossbow hunting seasons to full archery durations, directly enlarging equipment replacement cycles. The EPA regulates limb finishes and coatings under volatile organic compound standards that compress compliance windows for domestic fabricators. Wisconsin and Utah host the densest concentrations of certified composite lamination technicians, where manufacturers report 18-month hiring backlogs for prepreg layup specialists.
Germany
Precision machining clusters in Baden-Württemberg and Bavaria supply CNC-milled trigger housings to crossbow producers across Europe. ECHA substance restrictions under REACH are accelerating reformulation of limb resins and bow finishes, favoring pre-impregnated carbon fiber systems that reduce solvent exposure. Stuttgart-area fabrication facilities are retooling curing ovens to meet tightened emissions standards.
China
Domestic sporting goods consumption is expanding through municipal archery development programs in Shanghai and Beijing. MIIT oversees industrial standards for recreational equipment safety, though enforcement varies by provincial jurisdiction. The Yangtze River Delta hosts injection-molded riser production for entry-level compound bows serving Asian and export markets.
Canada
Provincial wildlife agencies in Ontario and Alberta are harmonizing crossbow equipment specifications with American state standards to simplify manufacturer compliance. Health Canada regulates product safety labeling for archery equipment sold through domestic retail channels. Manufacturing activity concentrates in Quebec, where aluminum extrusion facilities serve North American entry-tier demand.
Australia
State-level hunting regulation in Victoria and New South Wales permits crossbow use only for licensed pest control operators, constraining recreational market development. The TGA maintains equipment safety guidelines that influence insurance underwriting for domestic distributors. Distribution runs through specialized outdoor retailers in Sydney and Melbourne metropolitan corridors.
Compound Bow and Crossbows Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in limb fabrication, trigger mechanisms, and cam machining. The vendor base organizes around three capability clusters: vertically integrated archery houses controlling carbon fiber curing and final assembly; precision metalwork shops supplying CNC-machined trigger housings; and composite lamination contractors serving multiple brand labels. Consolidation pressure is accelerating as raw material allocation agreements become primary competitive moats.
Among North American platform integrators, Bowtech and TenPoint Crossbow Technologies occupy positions emphasizing in-house production control, while Hoyt Archery exemplifies the R&D-intensive tournament-grade specialist archetype. These companies represent divergent strategic postures: captive supply chain management versus precision engineering differentiation. The competitive terrain rewards either deep backward integration into carbon fiber processing or sustained investment in cam synchronization tolerances for certified competition equipment.
| Leading Market Players |
|---|
| Bowtech |
| Barnett Crossbows |
| TenPoint Crossbow Technologies |
| PSE Archery |
| Mathews Archery |
| Hoyt Archery |
| Excalibur Crossbow |
| Ravin Crossbows |
| Darton Archery |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Toray Industries and Hexcel Corporation for aerospace-grade carbon fiber prepreg determines both pricing tier spreads and supply chain shape across the compound bow and crossbows market. This concentration forces manufacturers into long-term allocation agreements or spot-market exposure during defense procurement surges, compressing margins in premium tiers while amplifying cost advantages for vertically integrated producers.
Pricing Analysis
EPA volatile organic compound standards dictate the pricing tier structure across limb finishes and coatings. Three-tier pricing structure across premium, standard, and economy levels separates carbon fiber tournament-grade platforms from aluminum recreational entry points and injection-molded youth models. Price differentiation stems from certification grade under ASTM F1161 safety protocols and geographic delivery cost from Wisconsin and Utah fabrication clusters. Cost compression in aluminum entry tiers is intensifying because Asian extrusion competitors flood North American channels. Youth programs and first-time buyers in Kansas and Oklahoma exhibit highest price sensitivity; backcountry hunters in Colorado and Utah demonstrate lowest sensitivity due to performance prioritization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for injection-molded riser components and finished assembly sourcing. Manufacturing concentrates in the United States, China, and Germany, with carbon fiber prepreg flowing from Japanese and American chemical conglomerates, precision trigger housings machined in Baden-Württemberg and Bavaria, and aluminum extrusion serving entry-tier demand from Quebec and Midwest facilities. Raw material dependencies span Toray and Hexcel carbon fiber, CNC-milled aluminum blanks, and water-based coating formulations. Distribution runs through pro-shop networks, manufacturer direct channels, and specialized outdoor retailers in Sydney and Melbourne corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compound bow and crossbows market sits in a cyclical upswing driven by state wildlife agency season liberalization, creating favorable conditions for equipment replacement cycles and premium-tier migration.
For Market Incumbents: Pre-empt carbon fiber allocation shortages by securing multi-year prepreg agreements with Toray Industries and Hexcel Corporation before defense procurement cycles tighten supply. Anchor position through backward integration into composite curing facilities in Wisconsin and Utah, neutralizing the 18-month technician hiring backlog that constrains competitor scaling. Counter airgun substitution threats among small-game recreational shooters by bundling mobile tuning applications with premium compound bow sales. For New Entrants and Emerging Players: Build out distribution presence in India under DGFT sporting goods tariff liberalization, where municipal archery development programs in Shanghai and Beijing signal adjacent Asian market expansion. Target crank-cock crossbow penetration among aging hunters in Florida, Arizona, and North Carolina as the most accessible white-space demographic. Pursue direct-to-consumer assembly kit positioning to bypass pro-shop markup capture and compress customer acquisition costs. For Investors and Strategic Acquirers: The market sits at an expansion phase that favors vertically integrated platform integrators with captive carbon fiber processing and in-house CNC trigger machining capability. Long-term viability over the next decade hinges on regulatory navigation capacity across fragmented state wildlife agency specifications. Acquisition targets should demonstrate established allocation relationships with Japanese prepreg suppliers and certified composite lamination workforces. The signal to watch is Ohio, Pennsylvania, and Texas harmonization momentum for crossbow equipment standards as inflection indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Allocation Agreement | Secures Toray and Hexcel prepreg supply against defense procurement competition. |
| Direct-to-Consumer Assembly Kit Launch | Bypasses pro-shop intermediaries to capture retail margin in remote western states. |
| Mobile Tuning Application Deployment | Compresses independent archery retail channel through smartphone-guided diagnostics. |
| Composite Curing Facility Expansion | Addresses 18-month technician backlog constraining premium limb production scaling. |
| State Season Structure Advocacy | Aligns with Ohio, Pennsylvania, and Texas wildlife agencies expanding legal hunting windows. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary source validation across regulatory and trade databases. Primary interviews encompassed composite lamination technicians in Wisconsin and Utah, CNC machining specialists in Baden-Württemberg, state wildlife agency equipment policy directors, pro-shop network operators, and tournament archery certification officials. Secondary sources included EPA volatile organic compound compliance filings, ASTM International equipment safety standards documentation, ECHA REACH substance restriction updates, state-by-state hunting regulation compendiums, and customs trade data for archery equipment imports. Bottom-up demand modeling triangulated against top-down market sizing across product type, material tier, end-user category, and power source segmentation.
Forecast inputs considered season structure liberalization trajectories, aging hunter demographic projections, carbon fiber supply allocation cycles, and regulatory harmonization patterns across state jurisdictions. Segmentation dimensions modeled spanned compound bow versus crossbow versus recurve platforms, carbon fiber versus aluminum versus composite materials, hunters versus competitors versus recreational users, and cocking device versus manual versus mechanical trigger power sources. CAGRs derived from regression analysis against historical replacement cycles and equipment penetration rates, with cross-validation against state wildlife agency permit issuance trends and pro-shop inventory turnover patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Asian entrants or airgun manufacturers targeting small-game segments would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Above Ground Swimming Pools Market
Outdoor & Sports
Inflatable Pool Market
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Portable Kayaks Market