
 France Digital Twin Market | 2026-2036
France Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
France Digital Twin Market Insights
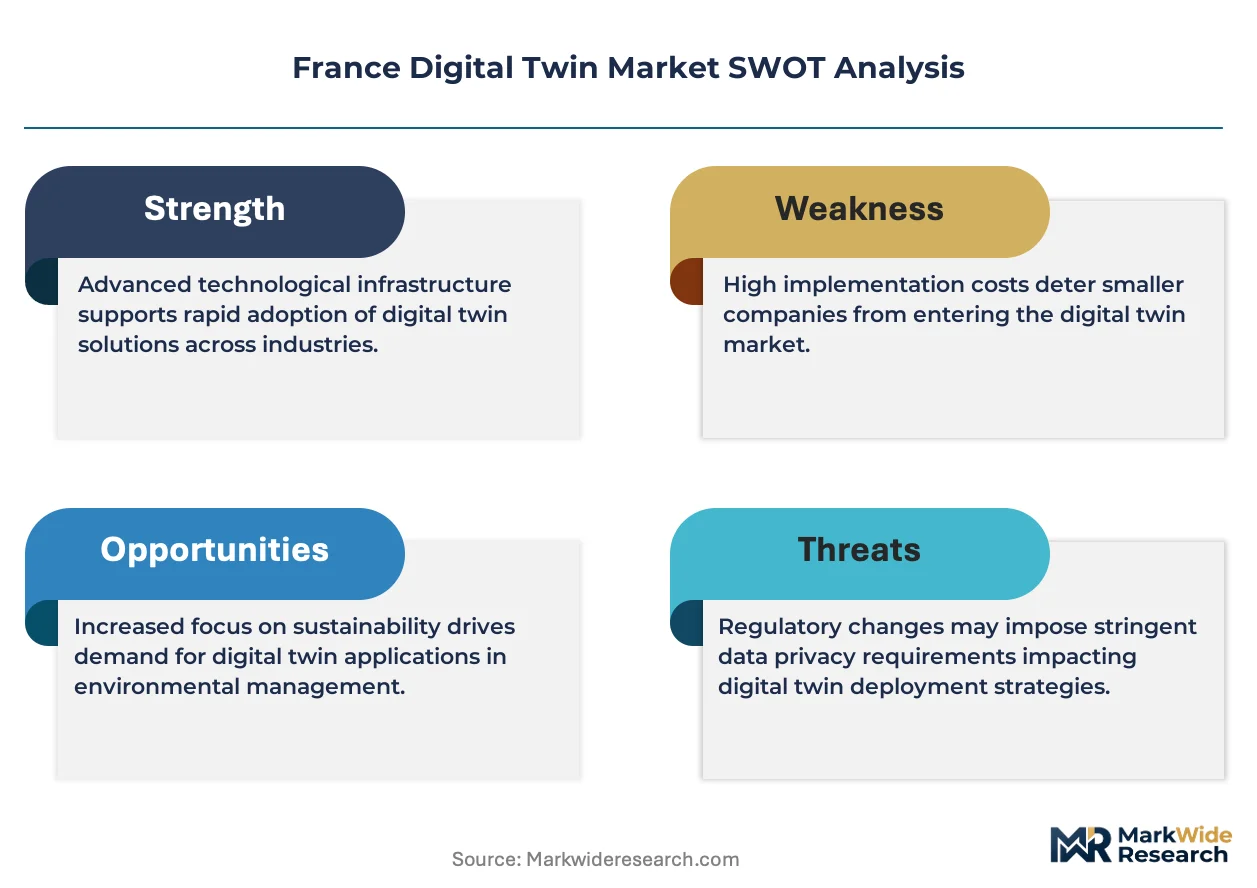
Real-time physics simulation fused with IoT sensor streams is reshaping how French industrial firms prototype and validate physical assets before capital deployment. Dassault Systèmes SE leverages its 3DEXPERIENCE platform to anchor design-to-manufacturing workflows across aerospace and automotive supply chains. Siemens AG competes through its Xcelerator portfolio, which extends digital thread capabilities from product design into operational technology layers. Schneider Electric specializes in energy management twins, positioning its EcoStruxure architecture as the control layer for smart building and grid applications.
A digital twin constitutes a dynamic virtual representation of a physical object or system, synchronized through continuous data exchange from embedded sensors, SCADA networks, or enterprise APIs, enabling predictive analytics, scenario modeling, and lifecycle optimization across engineering and operations domains. The aerospace vertical dominates value capture due to regulatory-mandated traceability requirements and the cost structure of unplanned downtime in turbine maintenance. Cloud-based deployment models represent the fastest-expanding segment as French manufacturers migrate simulation workloads away from on-premises HPC clusters to comply with evolving data residency frameworks. Integrated platforms command premium pricing by collapsing previously siloed CAD, CAE, and PLM environments into unified runtime environments.
ANSM and CNIL shape healthcare digital twin development through medical device software validation and patient data governance requirements, while the EU AI Act imposes conformity assessment obligations on autonomous decision systems embedded in industrial twins. France's national cloud strategy, reinforced by SecNumCloud certification criteria, restricts certain defense and critical infrastructure applications to sovereign hosting environments, directly influencing vendor qualification and procurement patterns. Stakeholders must monitor how forthcoming EU product liability revisions assign responsibility for twin-predicted outcomes versus actual physical failures.
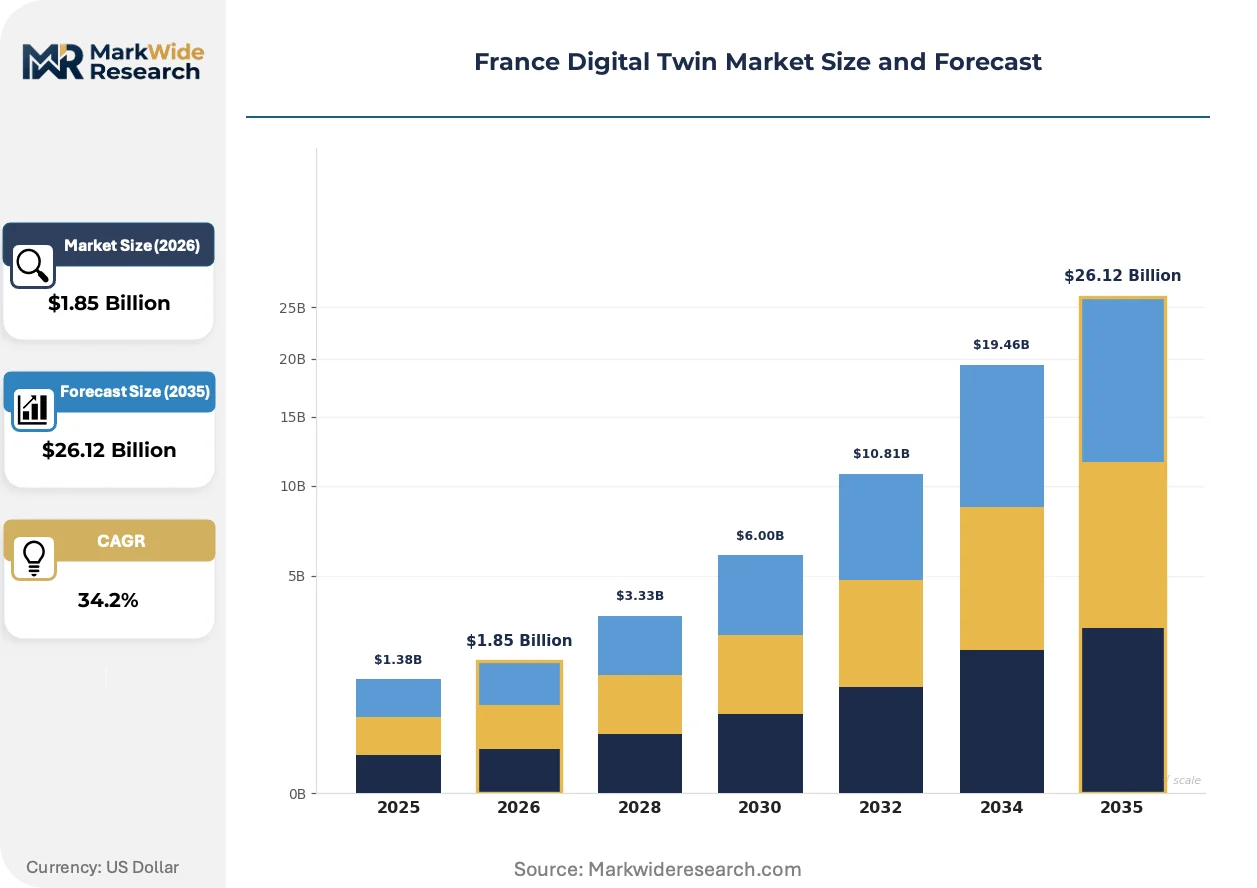
Market Dynamics
Physics-based simulation workloads are migrating from on-premises HPC clusters to sovereign cloud environments under pressure from France's SecNumCloud certification and the EU AI Act's data residency mandates.
Growth Catalysts
- Aerospace predictive maintenance:Regulatory-mandated traceability for turbine components drives digital twin deployment across French engine overhaul facilities. ANSM validation protocols for medical device software create parallel demand in healthcare equipment manufacturing.
- SecNumCloud certification:France's national cloud strategy restricts defense and critical infrastructure applications to qualified sovereign hosting providers, directly expanding addressable market for compliant platform vendors.
- Paris-Saclay research cluster:Engineering talent pipelines from this concentration feed directly into industrial R&D centers in Île-de-France, compressing workforce development cycles for complex simulation roles.
Market Restraints
- High-performance computing infrastructure costs:Real-time physics simulation requires specialized GPU clusters and low-latency networking that strain mid-tier manufacturer capital allocation.
- SCADA system fragmentation:Legacy operational technology layers in French industrial plants use proprietary protocols that resist standardized data extraction for twin synchronization.
- EU product liability uncertainty:Forthcoming revisions to liability frameworks may assign responsibility for twin-predicted outcomes versus actual physical failures, chilling deployment decisions.
Strategic Opportunities
- Smart building energy optimization:Schneider Electric's EcoStruxure architecture demonstrates scalable deployment models for grid-interactive building management twins across French commercial real estate portfolios.
- CNIL-compliant patient data twins:Healthcare digital twin development for personalized treatment planning remains underpenetrated due to stringent governance requirements that favor early compliance investments.
- Edge-to-cloud architecture convergence:Integration of 5G private networks with containerized simulation runtimes enables millisecond-latency synchronization for rotating machinery applications.
Industry Challenges
- Multiphysics simulation expertise scarcity:French engineering programs produce insufficient graduates with combined competencies in computational fluid dynamics, finite element analysis, and industrial IoT integration.
- Legacy PLM system interoperability:Decades of CAD and CAE tool accumulation in aerospace supply chains creates data model incompatibilities that resist unified twin runtime environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Digital Twin Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $26.12 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Industry Vertical: Aerospace, Automotive, Healthcare, Construction Product Type: Software, Sensors, Simulation Tools, Integrated Platforms Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Manufacturers, Service Providers, Researchers, Government Agencies |
| Companies Covered | Siemens AG, Dassault Systèmes SE, PTC Inc., ANSYS Inc., General Electric Company, IBM Corporation, Microsoft Corporation, Schneider Electric, Oracle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Digital Twin Market Trends and Innovations
Simulation fidelity standards are tightening as French regulators and prime contractors demand sub-millimeter accuracy for safety-critical component validation. Three developments dominate vendor roadmaps and procurement specifications.
AI-augmented physics solvers are migrating from academic research into production engineering workflows. These hybrid models reduce computational load for turbulence and material deformation simulations by orders of magnitude. Safran and Thales are piloting deployment for preliminary design phases, compressing iteration cycles from weeks to days.
The EU AI Act imposes conformity assessment obligations on autonomous decision systems embedded in industrial twins. French manufacturers must document algorithmic transparency and risk management protocols before deploying predictive maintenance systems. Aerospace MRO facilities face the steepest compliance burden given the safety-critical nature of turbine scheduling algorithms.
Engineering procurement patterns are fragmenting as mid-tier suppliers bypass prime contractor platforms to source direct cloud simulation capacity. This disintermediation accelerates in Occitanie and Auvergne-Rhône-Alpes, where regional competitiveness clusters subsidize independent digital infrastructure investments. Traditional PLM vendors respond with usage-based pricing to retain wallet share.
France Digital Twin Market Segmentation
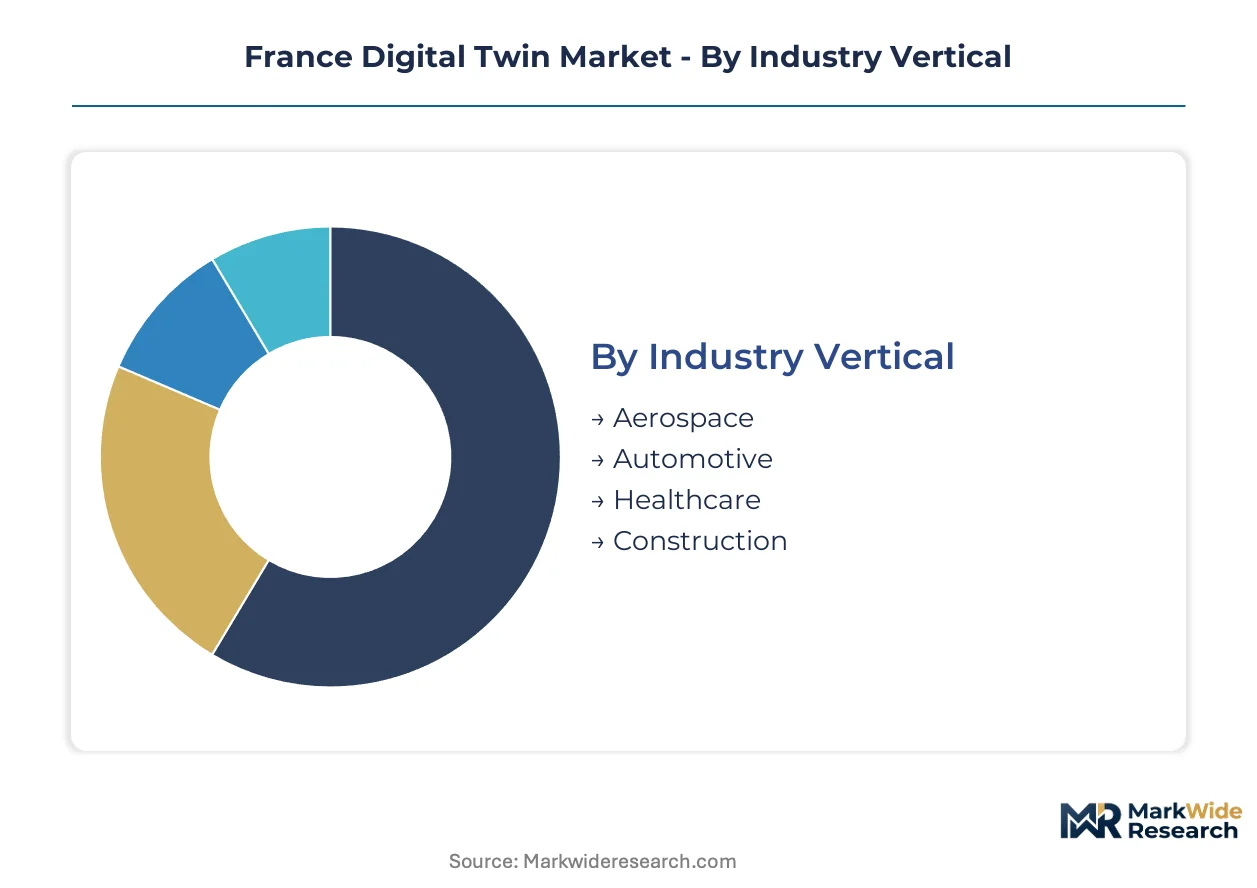
Digital twin architectures in France diverge sharply across industrial contexts, with aerospace predictive maintenance demanding physics-grade simulation fidelity while healthcare applications prioritize CNIL-compliant data governance. Segmentation reveals how vendor specialization and regulatory pressure reshape procurement patterns across Île-de-France's industrial clusters.
Industry Vertical:
Use-case spectrum spans safety-critical turbine overhaul to real-time building energy optimization, each imposing distinct computational and compliance requirements.
- Aerospace:Turbine component traceability mandates from aviation regulators drive physics-based digital twins for predictive maintenance. French MRO facilities in Île-de-France deploy these systems to compress engine overhaul cycles while satisfying airworthiness documentation requirements.
- Automotive:Supply chain traceability pressures and battery lifecycle management needs concentrate demand around Saint-Ouen and Flins manufacturing complexes. Electrification roadmaps accelerate twin deployment for thermal management and cell degradation modeling.
- Healthcare:ANSM validation protocols for medical device software and CNIL patient data governance create compliance-heavy implementation pathways.
- Construction:Smart building energy optimization and structural monitoring applications expand through Schneider Electric's EcoStruxure deployments across French commercial portfolios.
The dominant share belongs to Aerospace, while Healthcare is closing the gap fastest.
Product Type:
Cost tier stratification separates enterprise-grade integrated platforms from point solutions, with pricing reflecting data model unification depth.
- Integrated Platforms:Unified runtime environments collapsing CAD, CAE, and PLM silos command premium pricing through subscription models. These systems anchor design-to-manufacturing workflows at Dassault Systèmes and Siemens deployments across French aerospace supply chains.
- Software:Modular twin orchestration layers enable mid-tier manufacturers to compose simulation pipelines without full platform commitments. Occitanie and Auvergne-Rhône-Alpes clusters subsidize independent procurement to bypass prime contractor ecosystems.
- Sensors:IoT device layers feeding real-time physics synchronization face SecNumCloud certification requirements for sovereign infrastructure applications.
- Simulation Tools:Specialized CFD and FEA solvers persist in academic and R&D contexts despite platform consolidation pressures.
Integrated Platforms capture the largest wallet share, though Software is expanding most quickly through regional cluster subsidies.
Deployment Model:
Volume concentration tilts toward sovereign-compliant hosting as France's national cloud strategy restricts defense and critical infrastructure workloads.
- Cloud-Based:Sovereign cloud environments qualified under SecNumCloud certification absorb simulation workloads migrating from on-premises HPC clusters. EU AI Act data residency mandates accelerate this shift among manufacturers handling sensitive turbine performance data.
- Hybrid:Split architectures preserve sensitive model parameters on-premises while pushing scalable compute to qualified cloud instances. This configuration dominates at Thales and Safran pilot programs balancing latency against compliance.
- On-Premises:Legacy HPC installations persist where millisecond-latency synchronization requirements exceed network reliability.
- Edge Computing:Containerized simulation runtimes on 5G private networks enable rotating machinery applications with sub-10ms feedback loops.
Cloud-Based deployment holds the dominant position, while Edge Computing is gaining share fastest through 5G private network integration.
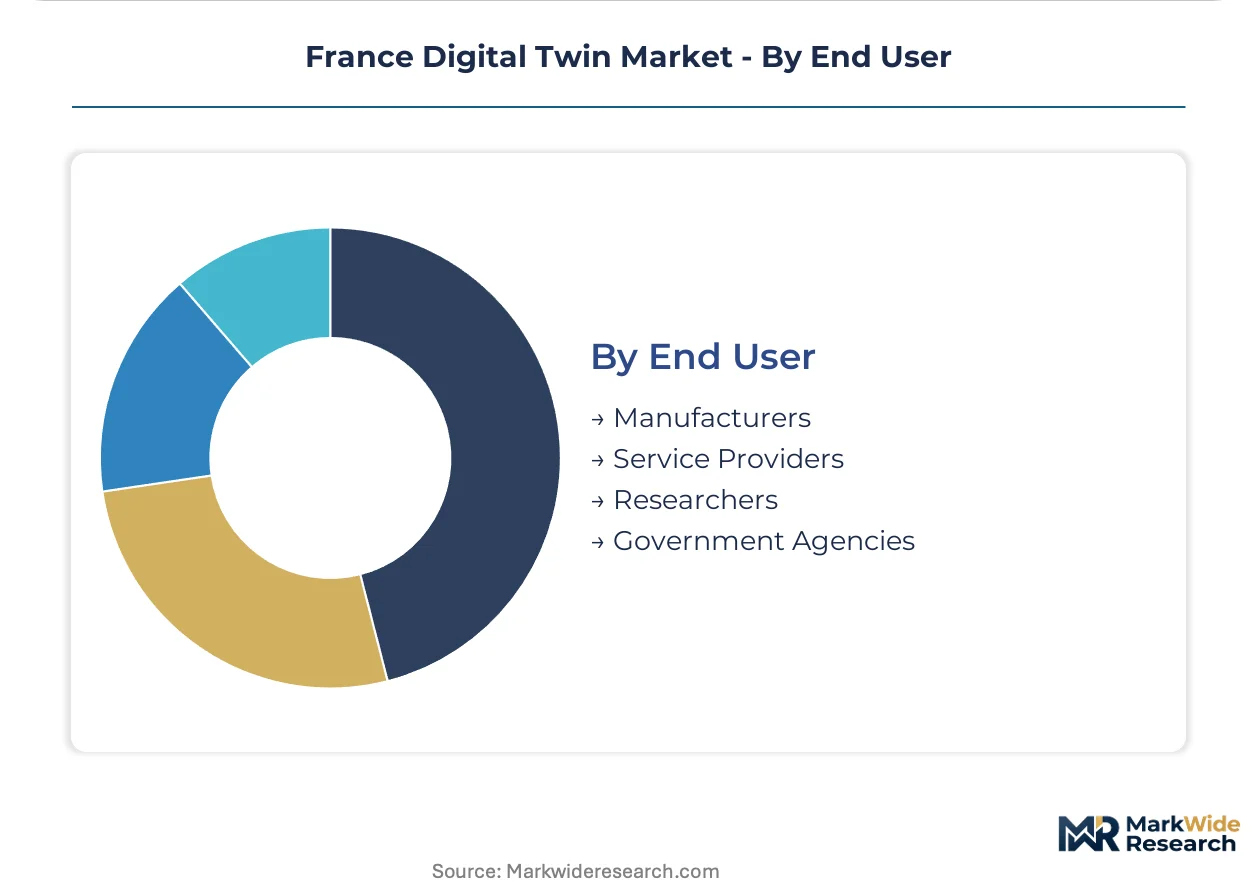
End User:
Customer type fragmentation separates prime contractor platform ecosystems from independent mid-tier supplier procurement.
- Manufacturers:Aerospace and automotive OEMs anchor demand through design-to-operations digital thread investments. These organizations consolidate supplier ecosystems around preferred platform vendors to enforce data model standardization.
- Service Providers:Independent MRO facilities and engineering consultancies disintermediate prime contractor platforms by sourcing direct cloud simulation capacity. Regional competitiveness clusters in Occitanie accelerate this procurement pattern shift.
- Researchers:Paris-Saclay and comparable academic clusters feed engineering talent into industrial R&D while advancing AI-augmented physics solver methodologies.
- Government Agencies:Defense and critical infrastructure applications face strictest SecNumCloud qualification requirements, limiting vendor pools to sovereign-certified providers.
Manufacturers retain the dominant share, though Service Providers are climbing the fastest as regional clusters subsidize independent infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prime contractors and mid-tier suppliers concentrate procurement decisions in Île-de-France, with regional competitiveness clusters in southern and eastern France accelerating independent infrastructure investments.
Île-de-France
Aerospace predictive maintenance and turbine traceability mandates drive concentrated demand around Paris-Saclay's research cluster. ANSM and CNIL regulations shape healthcare and defense digital twin deployments through medical device validation and data governance protocols. Saint-Ouen and Flins manufacturing complexes anchor automotive battery lifecycle management applications.
Auvergne-Rhône-Alpes
Regional competitiveness clusters subsidize independent cloud simulation capacity for mid-tier suppliers disintermediating prime contractor platforms. SecNumCloud certification requirements restrict defense applications to sovereign hosting providers. Lyon and Grenoble industrial zones feed engineering talent into energy management and smart building twin development.
Occitanie
Subsidized digital infrastructure investments accelerate procurement pattern shifts among independent engineering consultancies and MRO facilities. EU AI Act conformity assessment obligations impose documentation burdens on autonomous decision systems in manufacturing twins. Toulouse aerospace supply chain participants pilot edge-to-cloud architectures for rotating machinery synchronization.
Provence-Alpes-Côte d'Azur
Thales and Safran operations anchor hybrid deployment configurations balancing latency against compliance requirements. SecNumCloud-qualified sovereign cloud environments absorb physics simulation workloads migrating from on-premises HPC clusters. Sophia Antipolis technology park concentrates AI-augmented physics solver research for preliminary design phase compression.
Hauts-de-France
Legacy industrial plant SCADA fragmentation resists standardized data extraction for twin synchronization across metals and materials processing facilities. EU product liability uncertainty chills deployment decisions among capital-constrained mid-tier manufacturers. Lille metropolitan engineering schools address multiphysics simulation expertise scarcity through specialized graduate programs.
France Digital Twin Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Integrated platform vendors anchor design-to-manufacturing workflows through subscription pricing that collapses CAD, CAE, and PLM silos. Modular software specialists enable mid-tier manufacturers to compose simulation pipelines without full platform commitments. Sensor and edge hardware providers face SecNumCloud certification barriers for sovereign infrastructure applications. Competitive moves concentrate on regional cluster partnerships and usage-based pricing restructuring to retain wallet share against disintermediation.
Within the integrated platform tier, Dassault Systèmes SE and Siemens AG exemplify contrasting geographic anchoring strategies for aerospace and automotive supply chain penetration. Schneider Electric occupies a specialist position in energy management twins, representing the vertical application archetype against horizontal engineering platform vendors. These three entities collectively illustrate how vendor specialization and regulatory compliance requirements reshape procurement patterns across French industrial clusters.
| Leading Market Players |
|---|
| Siemens AG |
| Dassault Systèmes SE |
| PTC Inc. |
| ANSYS Inc. |
| General Electric Company |
| IBM Corporation |
| Microsoft Corporation |
| Schneider Electric |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in GPU cluster provisioning across Île-de-France data centers drives premium pricing for real-time physics simulation workloads while compressing margins for mid-tier manufacturers unable to secure sovereign cloud capacity under SecNumCloud certification timelines.
Pricing Analysis
Cost-plus contracts with GPU-hour indexation dominate platform vendor agreements, with Dassault Systèmes and Siemens anchoring enterprise subscriptions through unified runtime environments. Price differentiation separates SecNumCloud-certified sovereign hosting from standard cloud tiers, with certification-grade deployments commanding substantial premiums. Pricing pressure stems from regional cluster subsidies enabling independent procurement outside prime contractor ecosystems. Mid-tier service providers exhibit highest price sensitivity, while aerospace OEMs prioritize compliance over cost.
Supply Chain Analysis
Upstream feedstock for digital twin infrastructure draws from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with NVIDIA GPU supply constrained by foundry allocation priorities. Specialized edge sensors and industrial IoT gateways source from Germany, China, and Japan. Single-source vulnerability in advanced GPU supply creates procurement risk for French manufacturers scaling simulation capacity. Distribution runs through certified systems integrators and direct platform vendor relationships, with regional competitiveness clusters disintermediating traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's digital twin market represents high-growth infrastructure disruption, with EU AI Act conformity assessment obligations and SecNumCloud certification requirements creating structural advantages for compliant platform vendors.
For Market Incumbents: Entrench platform ecosystems through backward integration into sovereign cloud infrastructure and exclusive Paris-Saclay research partnerships. Lock in aerospace supply chains via ANSM-validated medical device twin modules. Prioritize SecNumCloud certification investment to exclude non-compliant challengers from defense and critical infrastructure procurement.
For New Entrants and Emerging Players: Mid-market automotive battery lifecycle management in Auvergne-Rhône-Alpes represents the most penetrable entry point, with electrification roadmaps outpacing incumbent platform coverage. Independent MRO facilities in Occitanie seeking direct cloud simulation capacity offer secondary white-space. Lead with usage-based pricing and modular software orchestration to bypass prime contractor platform commitments.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because SecNumCloud certification creates durable moats around sovereign-qualified infrastructure providers. Target acquisition archetypes include AI-augmented physics solver specialists and CNIL-compliant healthcare data governance platforms. Monitor EU product liability revision timelines as the critical inflection signal for deployment acceleration or chilling.
| Strategic Initiative | Industry Significance |
|---|---|
| SecNumCloud Certification Investment | Qualifies vendors for defense procurement under France's national cloud strategy. |
| AI-Augmented Physics Solver Acquisition | Compresses simulation iteration cycles from weeks to days for Safran and Thales. |
| Paris-Saclay Research Partnership | Feeds engineering talent directly into industrial R&D centers in Île-de-France. |
| Edge-to-Cloud Architecture Convergence | Enables millisecond-latency synchronization for rotating machinery via 5G private networks. |
| CNIL-Compliant Patient Data Platform | Opens healthcare digital twin development for personalized treatment planning. |
Research Methodology
Operator-level perspectives from aerospace MRO directors, healthcare biomedical engineers, smart building facility managers, and industrial IoT integration specialists anchored the qualitative base. Primary interviews combined with secondary validation against ANSM device registration databases, CNIL compliance bulletins, SecNumCloud certification records, and EU AI Act implementation guidance. Bottom-up demand modeling triangulated against top-down platform vendor revenue disclosures.
Scenario-bracketing framed projections across conservative, baseline, and accelerated adoption paths over the analysis window. Segmentation dimensions modeled include industry vertical, product type, deployment model, and end-user category, with regulatory compliance tier as an additional France-specific dimension. CAGRs derived from diffusion curve analysis calibrated to aerospace predictive maintenance deployment rates and sovereign cloud migration timelines.
Macroeconomic conditions sit as an overlay; deviation in defense procurement budgets, EU AI Act enforcement intensity, or GPU supply chain constraints would shift the trajectory. Cross-checking against SecNumCloud certification issuance rates and ANSM software validation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Multicarrier Parcel Management Solutions Software Market
Digital Solutions
Email Marketing Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Business Information Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
Decision Support System Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Global Enterprise Metadata Management Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Workspace As a Service Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Equipment Tracking Software Market