
 Eye Cream Market | 2026-2036
Eye Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Cream Market Analysis
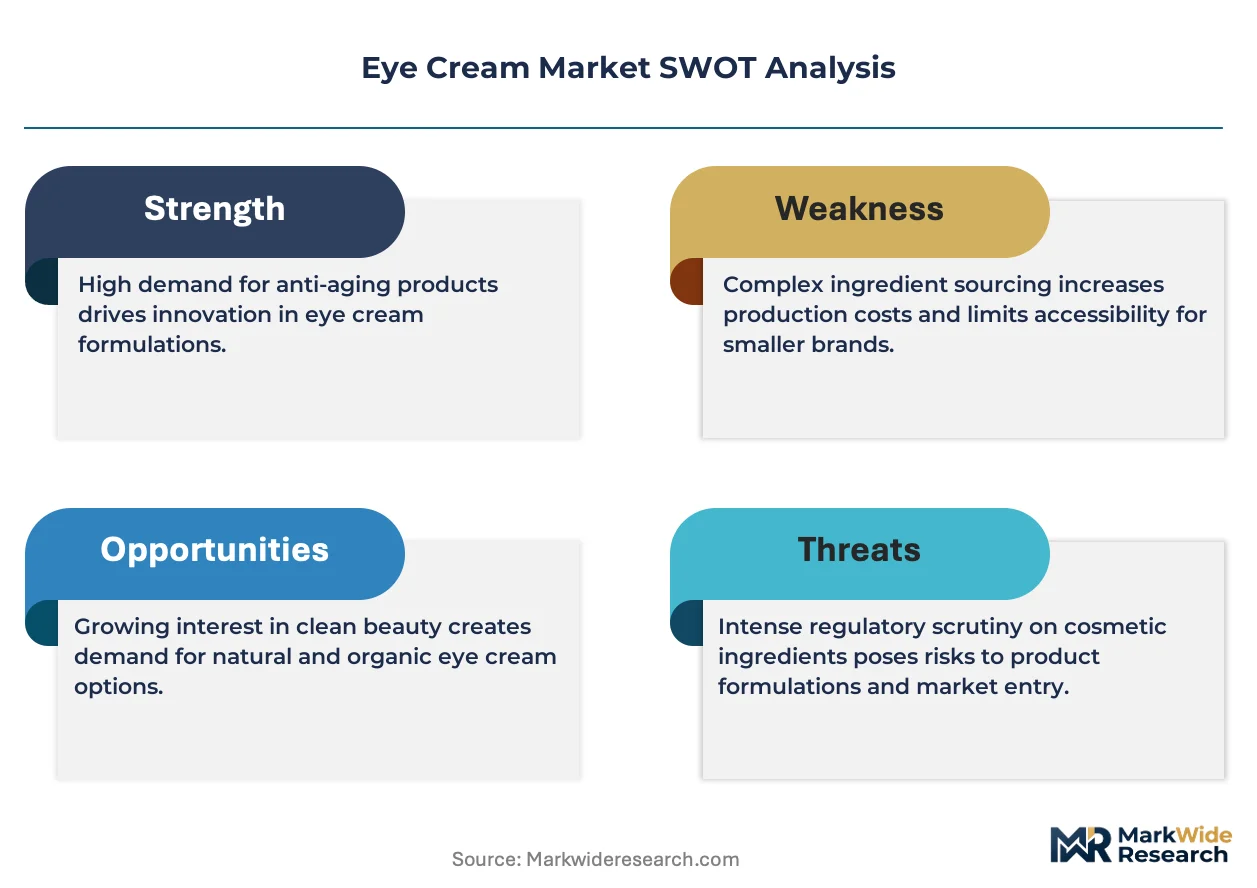
ISO 16128 natural and organic cosmetics standards is bifurcating the competitive landscape between certified clean-formulation specialists and conventional incumbents. L'Oréal S.A. leverages its dermatological research infrastructure to anchor clinical credibility across premium eye cream lines. Beiersdorf AG sustains R&D intensity through dedicated skin science centers in Germany. Shiseido Co., Ltd. competes on Asian botanical extraction expertise that differentiates its firming portfolio.
Eye cream denotes a viscous dermal preparation engineered for periorbital application, typically incorporating ceramides, retinoids, or peptides at concentrations calibrated for thin epidermal layers, with primary commercial purpose to reduce visible aging indicators or fatigue markers. The anti-aging category leads value generation as consumers prioritize peptide and retinol-based treatments over basic hydration. Brightening formulations represent the fastest-growing product type, driven by pigmentation concerns across diverse demographics. Pump packaging captures expanding share as brands emphasize dose precision and contamination prevention over traditional jar formats.
FDA cosmetic labeling requirements and the EU Cosmetics Regulation govern ingredient safety substantiation, with REACH compliance additionally constraining preservative selections for European formulations. These frameworks elevate compliance costs while rewarding brands with pre-validated clean ingredient pipelines. Stakeholders must monitor evolving state-level ingredient restrictions in the United States and pending EU microplastic ban implementations that could reshape exfoliating eye cream formulations.
Market Dynamics
ISO 16128 certification standards are bifurcating the competitive landscape, forcing brands to choose between costly clean-formulation pipelines and conventional preservative systems while men emerge as the fastest-growing demographic segment.
Growth Catalysts
- EU Cosmetics Regulation disclosure mandates:Ingredient transparency requirements are accelerating consumer trust in peptide and retinol-based treatments across premium anti-aging lines.
- Periorbital pump packaging innovation:Dose precision engineering is displacing traditional jar formats in contamination-sensitive brightening formulations.
- Men's grooming norm shifts:Male consumers are driving volume expansion in firming eye creams as gendered skincare boundaries dissolve in urban United States markets.
Market Restraints
- REACH compliance costs:European preservative restrictions are elevating formulation expenses for ceramide-based products targeting thin epidermal layers.
- Retinoid supply concentration:Active ingredient sourcing clusters with three German specialty chemical suppliers, creating input vulnerability.
- Jar format contamination risk:Repeated finger-dip application accelerates oxidative degradation in peptide concentrates, shortening effective shelf life.
Strategic Opportunities
- Underpenetrated male segments in France:Grooming retailers report minimal dedicated eye cream SKUs for men despite rising search volume.
- Asian botanical extraction convergence:Japanese fermentation science paired with Korean ginseng processing is opening novel firming mechanism claims.
- Pending EU microplastic ban:Exfoliating eye cream reformulation deadlines are creating first-mover advantage for biodegradable bead suppliers.
Industry Challenges
- Clean-formulation chemist scarcity:Brands struggle to hire specialists capable of stabilizing retinoids without conventional paraben systems.
- ISO 16128 certification timelines:Natural and organic validation processes extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Cream Market |
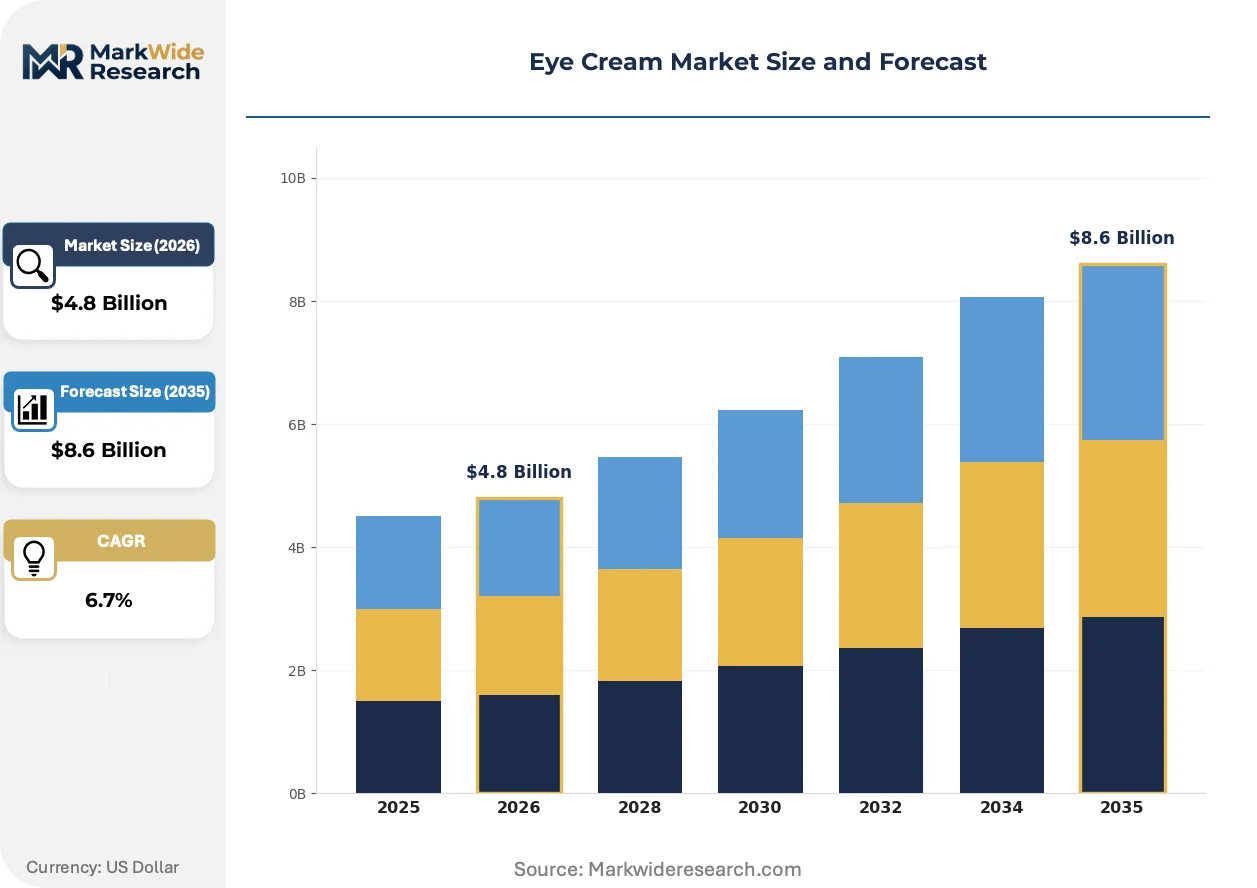
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating, Anti-Aging, Brightening, Firming Target Audience: Women, Men, Teens, Mature Adults Packaging Type: Tube, Jar, Pump, Sachet Distribution Channel: Online, Drugstores, Department Stores, Specialty Shops |
| Companies Covered | Unilever plc, Beiersdorf AG, L'Oréal S.A., Avon Products, Inc., Kao Corp., The Estée Lauder Companies Inc., Shiseido Co., Ltd., SkinCeuticals, Procter and Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Cream Market Emerging Trajectories
Biotechnology is actively decomposing traditional extraction methods across the eye cream value chain, with fermentation-derived ceramides and lab-cultured peptides displacing conventional botanical sourcing. Three interconnected shifts are compressing development cycles and rewiring competitive advantage.
Encapsulation technology is decomposing the stability limitations that have constrained retinoid concentrations in periorbital formulations. Premium dermatological brands are adopting lipid-nanoparticle delivery systems at accelerated pace. This compression of degradation risk is enabling higher-potency anti-aging claims without irritation penalties.
REACH authorization procedures are forcing preservative system overhauls in European formulations. The industrial consequence is a wholesale migration toward phenoxyethanol alternatives and self-preserving emulsion architectures. Brightening eye creams with vitamin C derivatives face the steepest compliance costs as ECHA scrutinizes antioxidant stabilizers.
Subscription direct-to-consumer models are fragmenting traditional pharmacy and department store dominance in eye cream distribution. United States millennial buyers are consolidating purchases through curated skincare boxes that emphasize clinical credibility markers. This channel rotation is compressing brand loyalty cycles and elevating influencer validation requirements over counter-based sampling.
Eye Cream Market Segmentation
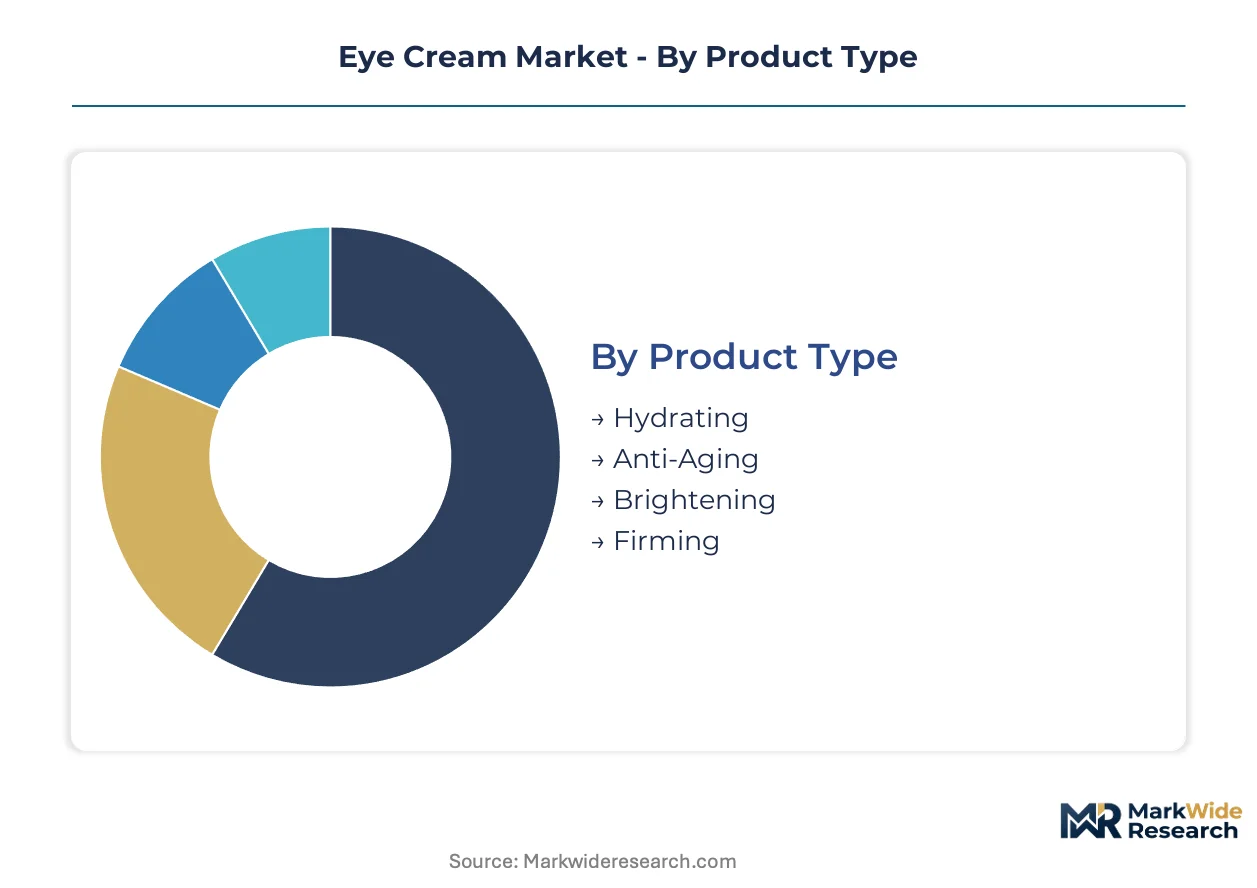
Periorbital formulations fragment across four distinct category hierarchies that determine pricing architecture, channel placement, and clinical positioning. Each dimension carries unique margin implications and regulatory exposure that shape portfolio strategy for incumbents and entrants.
Product Type:
Anti-aging concentrates command premium shelf placement in dermatologist offices and prestige e-commerce, while brightening variants flow through pharmacy chains and Asian specialty retailers. Hydrating and firming formulations occupy mid-tier positioning across mass-market channels.
- Anti-Aging:Peptide and retinoid-based concentrates engineered for collagen stimulation in thin periorbital epidermis. Demand clusters in United States urban centers among consumers prioritizing clinical credibility markers over basic moisturization. Pump packaging dominates this segment due to oxidation sensitivity of active ingredients.
- Brightening:Vitamin C derivative and niacinamide formulations targeting hyperpigmentation and fatigue-induced dullness. Korean and Japanese consumers drive volume through multi-step skincare routines, with sachet sampling accelerating trial conversion in Asian markets. REACH compliance costs pressure European formulations using certain antioxidant stabilizers.
- Hydrating:Ceramide and hyaluronic acid blends delivering barrier repair for sensitive periorbital skin.
- Firming:Botanical extract and peptide combinations addressing elasticity loss, with Japanese fermentation science differentiating premium tiers.
By volume, hydrating formulations lead. By growth pace, brightening is ahead.
Target Audience:
Cost tier stratification separates mature adult premiums from teen entry points, with gender-specific SKUs commanding 15-40% price premiums over unisex alternatives in equivalent formulations.
- Women:Historical core demographic sustaining volume across all product categories and price tiers. United States department stores and specialty shops concentrate demand for peptide-intensive treatments.
- Men:Fastest-expanding segment as grooming norms dissolve gendered skincare boundaries. Urban United States markets show particular strength in firming and anti-aging variants, with dedicated male SKUs still underrepresented in French retail.
- Teens:Entry-level hydrating formulations with simplified ingredient lists and accessible price points.
- Mature Adults:Clinical-grade retinoid and growth factor concentrates with dermatologist endorsement requirements.
Women generate the highest absolute revenue. Men are climbing the fastest.
Packaging Type:
Margin structure varies sharply by format, with airless pump systems adding 12-18% unit cost that brands recover through premium positioning and contamination-risk messaging.
- Pump:Airless and precision-dose systems preventing oxidation of retinoid and vitamin C actives. Expanding share in brightening and anti-aging categories as brands emphasize contamination prevention and dosing accuracy.
- Jar:Traditional finger-dip formats facing decline due to repeated exposure accelerating peptide degradation. Still prevalent in mass-market hydrating segments where cost minimization overrides stability concerns.
- Tube:Squeeze formats balancing cost efficiency with moderate air exposure protection.
- Sachet:Single-use samples driving trial conversion in Asian markets and subscription box channels.
Jars retain volume leadership. Pumps show the steepest expansion trajectory.
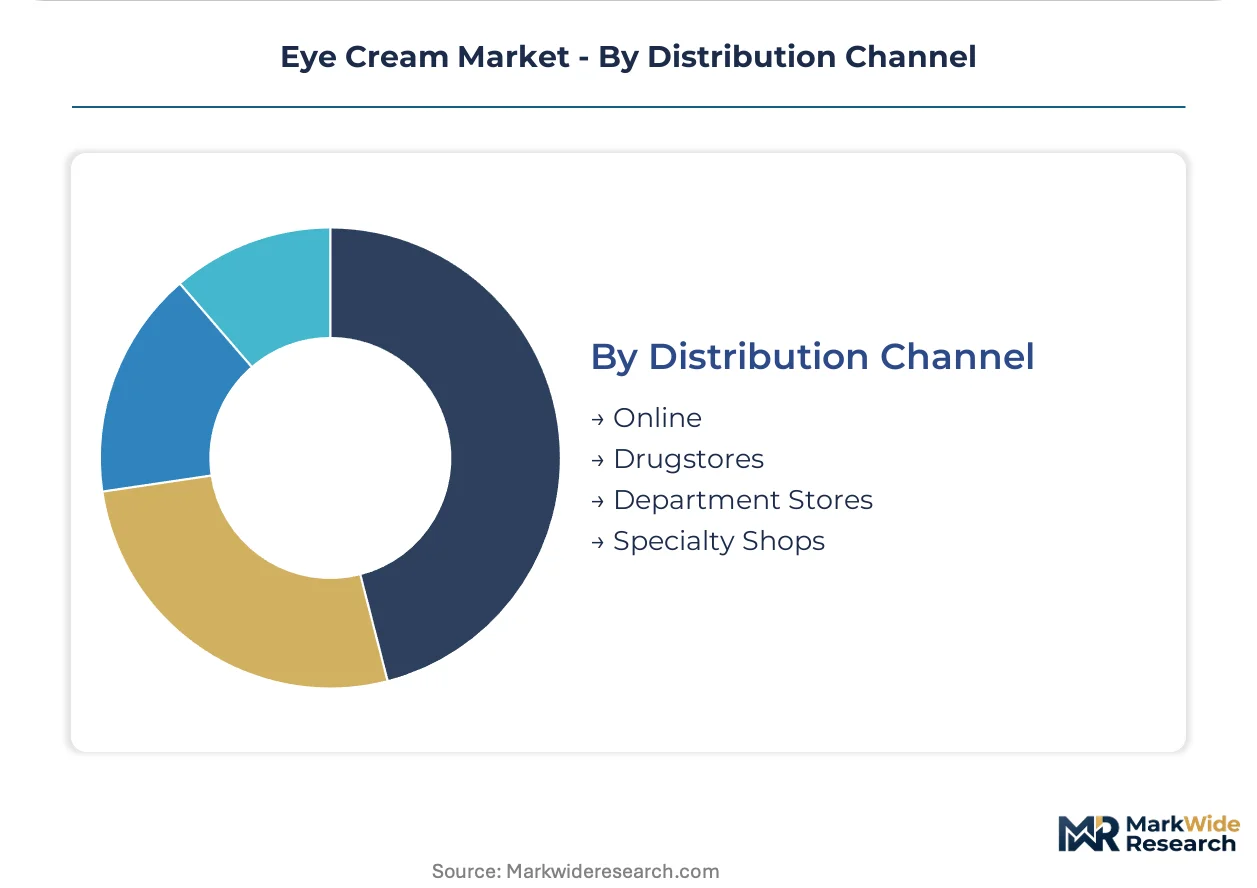
Distribution Channel:
Geographic concentration patterns diverge sharply by channel, with online aggregating fragmented demand and department stores retaining prestige-brand gatekeeper status.
- Online:Direct-to-consumer and marketplace platforms capturing millennial consolidation through curated subscription boxes. Influencer validation and clinical credibility markers displace counter-based sampling as primary purchase drivers.
- Drugstores:Mass-market hydrating and basic brightening formulations with pharmacist endorsement in European markets. REACH compliance documentation increasingly visible on shelf displays.
- Department Stores:Prestige anti-aging and firming lines with counter-based consultation services. United States locations anchor global revenue for peptide-intensive premium tiers.
- Specialty Shops:Korean beauty retailers and French parapharmacies offering expert-guided selection across all product types.
Department stores lead by value per transaction. Online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium anti-aging formulations concentrate demand in United States urban centers, while brightening variants accelerate through Asian multi-step skincare routines. Regulatory divergence between FDA cosmetic labeling and EU Cosmetics Regulation compliance costs is reshaping formulation priorities across manufacturing footprints.
United States
Urban millennial buyers consolidate purchases through curated subscription boxes emphasizing clinical credibility markers. FDA cosmetic labeling requirements govern ingredient safety substantiation, elevating documentation burdens for peptide-intensive treatments. New York Metro and Los Angeles anchor prestige-brand gatekeeper status through department store consultation services.
Germany
REACH compliance constrains preservative selections for ceramide-based products targeting thin epidermal layers. ECHA scrutiny of antioxidant stabilizers pressures vitamin C derivative formulations in brightening categories. Beiersdorf AG sustains dedicated skin science centers in Hamburg, anchoring R&D intensity for regional formulation leadership.
Japan
Korean and Japanese consumers drive brightening volume through multi-step skincare routines with sachet sampling accelerating trial conversion. METI standards intersect with ISO 16128 natural cosmetics certification timelines extending product launch cycles. Tokyo-Osaka corridor concentrates fermentation science expertise differentiating premium firming portfolios.
France
Grooming retailers report minimal dedicated eye cream SKUs for men despite rising search volume in Paris and Lyon markets. ANSM ingredient disclosure mandates align with EU Cosmetics Regulation transparency requirements. Île-de-France parapharmacies offer expert-guided selection across anti-aging and brightening product types.
South Korea
Korean ginseng processing convergence with Japanese fermentation science opens novel firming mechanism claims for Asian botanical extraction. MFDS cosmetic safety standards govern periorbital formulation approvals. Seoul Capital Area anchors multi-brand beauty retailers driving volume in hydrating and brightening categories.
Eye Cream Market Vendor Landscape
Player mix skews toward dermatological research incumbents with established clinical credibility infrastructure. The competitive structure concentrates around three strategic tiers: multinational conglomerates with dermatological research arms, Asian botanical specialists leveraging fermentation extraction expertise, and clean-formulation challengers pursuing ISO 16128 certification. Dominant competitive moves include portfolio diversification into pump-packaged brightening variants and strategic partnerships with biodegradable bead suppliers ahead of pending EU microplastic implementation deadlines.
Within the dermatological research tier, L'Oréal S.A. and Beiersdorf AG occupy positions anchored by clinical credibility infrastructure across premium eye cream lines. Shiseido Co., Ltd. represents the Asian botanical extraction archetype, sitting within the fermentation science specialization that differentiates firming portfolios in Japanese and Korean markets. These three entities exemplify how geographic R&D clustering—Paris-based dermatological research, Hamburg skin science centers, and Tokyo-Osaka fermentation expertise—shapes competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Unilever plc |
| Beiersdorf AG |
| L'Oréal S.A. |
| Avon Products, Inc. |
| Kao Corp. |
| The Estée Lauder Companies Inc. |
| Shiseido Co., Ltd. |
| SkinCeuticals |
| Procter and Gamble Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German specialty chemical suppliers and premium dermatological brands lock in retinoid access while stabilizing input cost visibility across peptide-intensive anti-aging formulations. These contractual structures insulate L'Oréal S.A. and Beiersdorf AG from spot market volatility in active ingredient markets, though REACH compliance costs continue pressuring European formulation economics.
Pricing Analysis
Cost-plus contracts with German specialty chemical indexation anchor retinoid and peptide pricing for premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 16128-certified clean formulations from conventional preservative systems, with certification grade commanding measurable premiums. Cost compression in mass-market jar formats intensifies as private-label entrants undercut established brands on basic hydration SKUs. Teen and entry-level hydrating segments exhibit highest price sensitivity, while mature adult clinical-grade concentrates retain inelastic demand.
Supply Chain Analysis
Inventory lead times for fermentation-derived ceramides stretch longer than conventional botanical extracts, compressing just-in-time flexibility for Asian botanical specialists. Active ingredient sourcing clusters in Germany, Japan, and South Korea, with peptide synthesis capacity concentrated around Hamburg and Tokyo-Osaka corridor. Raw material dependencies span retinoid precursors, fermentation-cultured ceramides, and Korean ginseng rootstock. Single-source vulnerability in German retinoid suppliers creates concentration risk. Distribution runs through pharmacy chains in Europe, department store counters in the United States, and multi-brand beauty retailers in Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eye cream market sits in a cyclical recovery phase as post-pandemic grooming norm shifts release pent-up male demand and subscription direct-to-consumer models rebuild customer acquisition economics.
For Market Incumbents: Fortify clinical credibility infrastructure against clean-formulation challengers by accelerating ISO 16128 certification pipelines and securing captive supply agreements with German retinoid specialists. Capacity addition in Hamburg skin science centers anchors European formulation leadership while countering emerging Asian botanical entrants. For New Entrants and Emerging Players: Differentiate on male-specific SKU development for underpenetrated French and urban United States grooming retail. The most penetrable white-space targets firming formulations for men in Paris and Lyon markets, paired with direct-to-consumer subscription launches emphasizing contamination-prevention pump packaging. For Investors and Strategic Acquirers: Asian botanical extraction specialists with fermentation science capabilities represent the priority acquisition archetype for portfolio diversification into brightening and firming segments. Long-term viability over the next decade hinges on clean-formulation chemist talent pipelines and biodegradable bead supplier relationships ahead of EU microplastic implementation. Watch for inflection signals in male SKU search volume acceleration and REACH authorization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 16128 Certification Investment | Clean-formulation validation unlocks premium pricing tiers against conventional preservative incumbents. |
| Pump Packaging Conversion | Airless dose-precision systems displace jar formats in oxidation-sensitive retinoid and vitamin C categories. |
| Biodegradable Bead Supplier Partnership | First-mover positioning ahead of EU microplastic ban deadlines secures exfoliating eye cream reformulation advantage. |
| Subscription Direct-to-Consumer Launch | Curated skincare boxes capture United States millennial consolidation and compress traditional pharmacy channel dominance. |
| Fermentation Science R&D Expansion | Japanese and Korean botanical extraction convergence differentiates firming portfolios against peptide-intensive Western competitors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with dermatological brand managers, cosmetic chemists at clean-formulation specialists, pharmacy category buyers, and subscription box curators. Secondary validation drew from FDA cosmetic labeling filings, ECHA REACH authorization databases, EU Cosmetics Regulation disclosure records, and ISO 16128 certification registries. Bottom-up SKU-level demand modeling triangulated against top-down market sizing from customs trade data and retail audit channels.
Across the analysis window, volume and value outputs reflect segmented modeling by product type, target audience, packaging format, and distribution channel, with additional dimensioning by regional regulatory cluster and certification status. CAGRs were derived from trend extrapolation of historical growth patterns adjusted for demographic shifts and channel migration effects. Forecast inputs incorporated male grooming norm elasticity coefficients and REACH compliance cost trajectories for European formulations.
Forecasts assume regulatory continuity in FDA cosmetic labeling and EU Cosmetics Regulation regimes; material policy shifts in preservative restrictions or microplastic implementation timelines would require re-modeling. Specific risks include retinoid supply concentration disruption, clean-formulation chemist scarcity extending launch cycles, and subscription channel saturation compressing customer lifetime value. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Cosmetics ODM Market
Cosmetics & Skincare
Loose Setting Powder Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Glow in the Dark Cosmetics Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Skin Care Products Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
Eyeliner Pen Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Thailand Skin Care Products Market
Cosmetics & Skincare
Body Blurring Cosmetics Market