
 Cosmetics OEM and ODM Services Market | 2026-2036
Cosmetics OEM and ODM Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetics OEM and ODM Services Market Insights
The buyer base for outsourced cosmetics manufacturing is broadening beyond legacy conglomerates toward indie brands, direct-to-consumer labels, and regional retail chains. Kolmar Korea Co., Ltd. leverages its integrated R&D campuses in Seoul to anchor premium skincare production for global clients. Cosmax Inc. sustains manufacturing scale across multiple continents, competing on throughput flexibility for both mass market and prestige formulations. Intercos Group differentiates through specialized color cosmetics technology, occupying leadership in makeup innovation for luxury houses.
Cosmetics OEM and ODM services encompass third-party formulation development, regulatory compliance management, and finished goods manufacturing performed under a client's brand identity, with batch consistency typically validated through ISO 22716 Good Manufacturing Practice protocols and stability testing across temperature ranges. These services enable brand owners to commercialize products without capital-intensive production infrastructure, accelerating speed-to-market for new launches. Private label and custom formulation segments command disproportionate margin pools where proprietary active ingredient delivery systems create differentiation, while indie brand clients represent the fastest-growing client type as digitally native labels outsource entire supply chains. Skincare dominates product type demand due to higher formulation complexity and regulatory scrutiny compared to color cosmetics.
EMA and REACH govern ingredient safety and environmental compliance for European market access, while FDA oversight shapes U.S. product claims and manufacturing standards; these frameworks collectively elevate barrier costs for non-compliant manufacturers. Korea's MFDS and China's NMPA impose additional testing and registration requirements that OEM/ODM partners must navigate on behalf of brand clients. Stakeholders must monitor evolving microplastic restrictions and packaging recyclability mandates across multiple jurisdictions to anticipate reformulation cycles and capital allocation priorities.
Market Dynamics
Indie brand proliferation is fragmenting demand across thousands of micro-clients while concentrating supply among Seoul-based production clusters, forcing OEM/ODM partners to reconfigure batch economics and minimum order quantities.
Growth Catalysts
- EU Green Deal compliance mandates:REACH substance restrictions and packaging recyclability targets compel brand owners to outsource formulation expertise rather than build in-house regulatory teams.
- Microbiome-targeted actives:Postbiotic and fermented ingredient platforms require specialized bioreactor infrastructure that indie brands access through contract manufacturers rather than capital investment.
- South Korea:Seoul's Songdo and Incheon production corridors aggregate raw material suppliers, testing laboratories, and MFDS-registered facilities into integrated ecosystems serving international clients.
Market Restraints
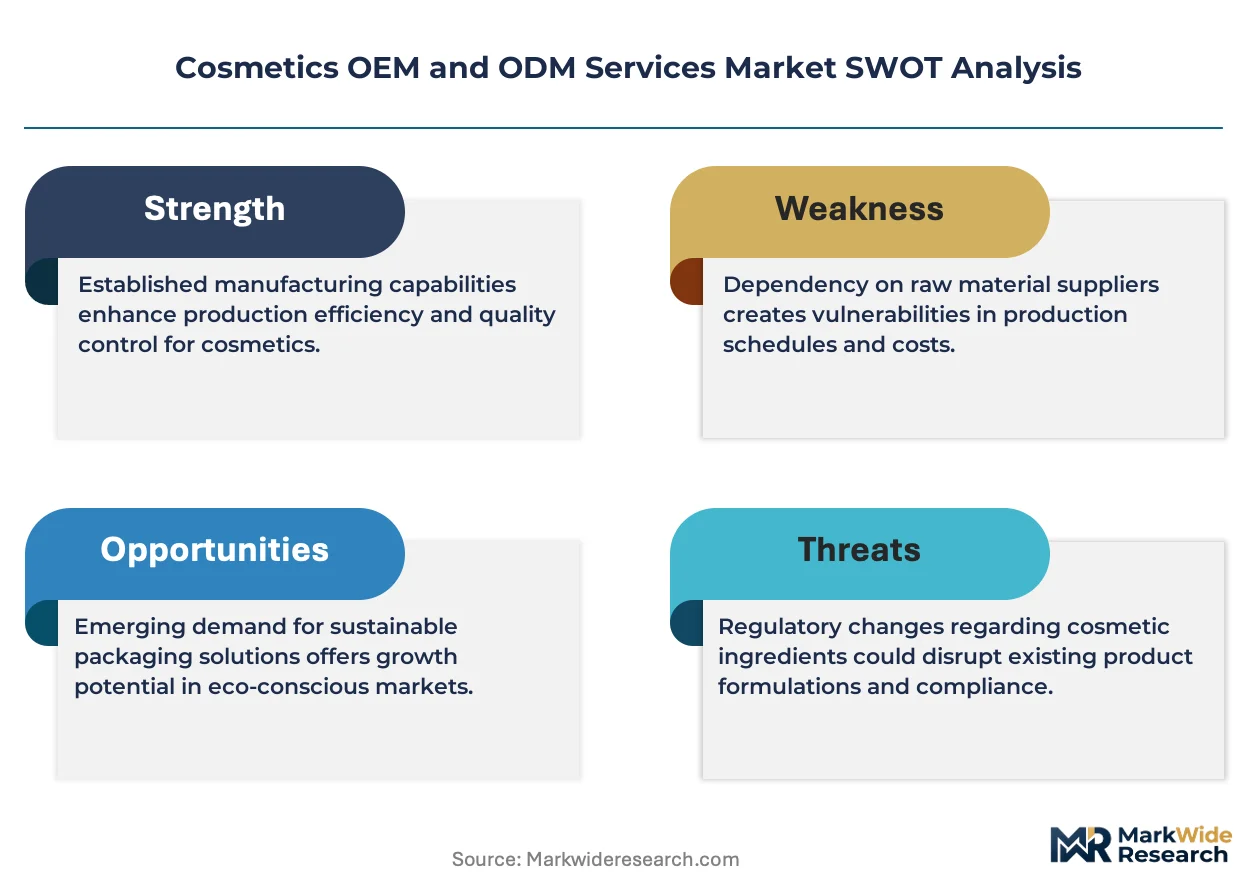
- Petrochemical derivative volatility:Surfactant and polymer input costs fluctuate with crude oil indices, compressing margin predictability for fixed-price contract manufacturing agreements.
- Single-source biotech inputs:Novel peptide and enzyme suppliers concentrate in Switzerland and South Korea, creating vulnerability to geographic disruption or capacity allocation decisions.
- Extended NMPA registration timelines:China's cosmetic ingredient filing requirements add 12-18 months to market entry, delaying revenue recognition for brand clients dependent on Chinese distribution.
Strategic Opportunities
- Waterless and solid format expansion:Concentrated balm and powder formulations reduce shipping volumes and packaging material intensity, aligning with EU microplastic restrictions.
- India's PLI scheme for personal care:Domestic manufacturing incentives attract contract manufacturers to establish Mumbai and Gujarat facilities serving regional beauty brands.
- AI-driven formulation optimization:Machine learning platforms predicting ingredient compatibility and stability are compressing R&D cycles from months to weeks.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation scientists with dual expertise in clean chemistry and regulatory navigation command premium compensation, inflating R&D overhead.
- ISO 22716 certification maintenance:GMP audit frequency and documentation requirements strain quality assurance bandwidth across multi-site manufacturing networks.
- Legacy ERP integration:Client demand for real-time batch tracking conflicts with decades-old inventory management systems requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetics OEM and ODM Services Market |
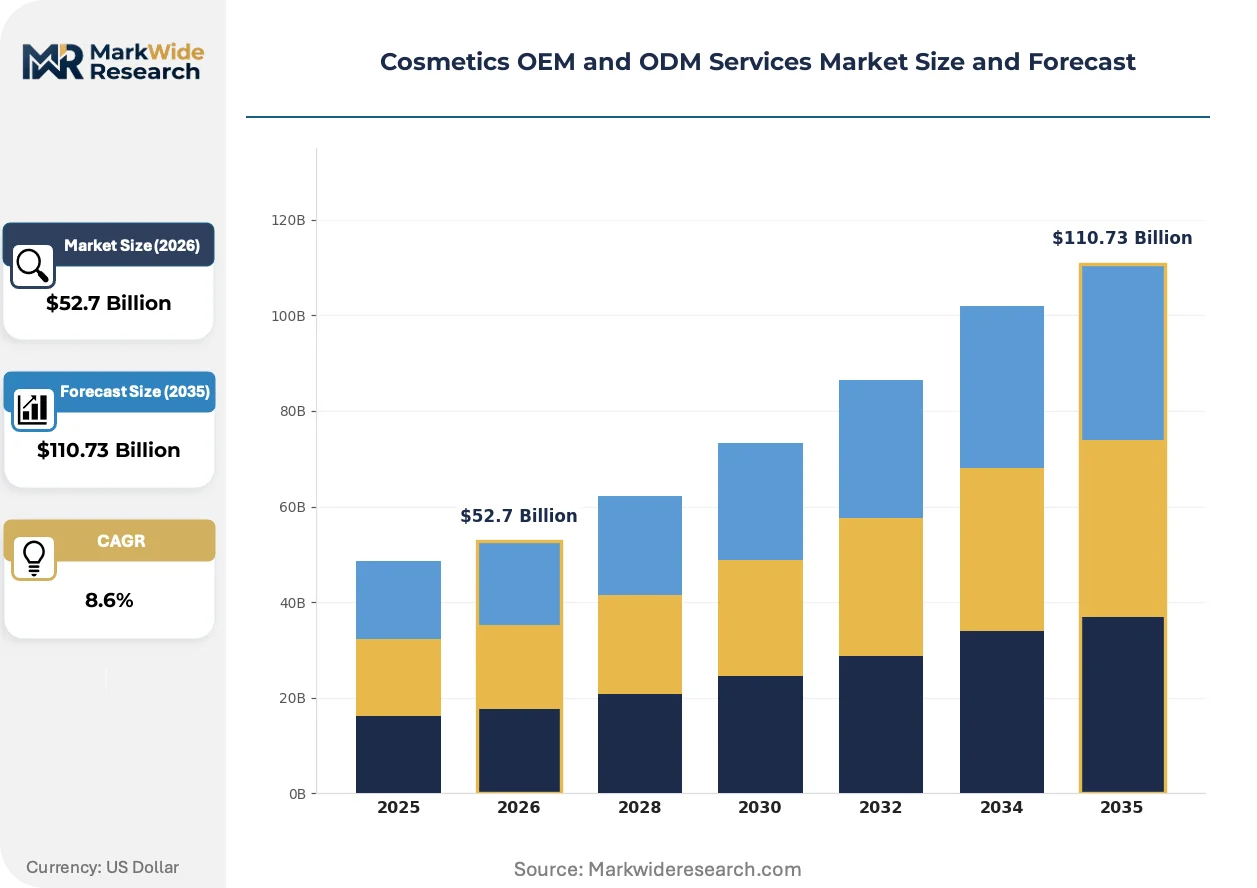
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Private Label, Custom Formulation, Contract Manufacturing, Bulk Production Client Type: Luxury Brands, Mass Market Brands, Indie Brands, Retail Chains Product Type: Skincare, Makeup, Haircare, Fragrance Packaging Type: Eco-Friendly, PET, Glass, Tubes |
| Companies Covered | Kolmar Korea Co., Ltd., Cosmax Inc., Intercos Group, Nox Bellow Cosmetics Co., Ltd., BioTruly Company Limited, Nihon Kolmar Co., Ltd., Chromavis S.p.A., Ancorotti Cosmetics S.r.l., Cosmecca Korea Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetics OEM and ODM Services Market Trends and Innovations
Biotechnology-derived actives and digital manufacturing controls are compressing development timelines while regulatory fragmentation forces specialized compliance infrastructure investments.
Precision fermentation for collagen and ceramide production is modularizing active ingredient supply chains. Indie skincare brands in North America and Europe adopt these biotech-derived materials to bypass traditional agricultural extraction dependencies. Contract manufacturers with captive fermentation capacity capture margin pools previously held by commodity chemical suppliers.
REACH microplastic restrictions and the EU Green Deal's packaging mandates are forcing reformulation cycles across color cosmetics and rinse-off products. Manufacturers must validate biodegradable glitter alternatives and solid shampoo bases ahead of 2026 enforcement deadlines. Premium brand clients absorb compliance costs; mass-market labels delay launches or exit affected categories.
Direct-to-consumer brands now specify lot-level traceability from raw material harvest to finished goods dispatch. This transparency mandate compresses supplier tiers and privileges vertically integrated OEM/ODM partners with captive ingredient sourcing. South Korean contract manufacturers lead implementation, embedding blockchain verification into client-facing quality documentation.
Cosmetics OEM and ODM Services Market Segmentation
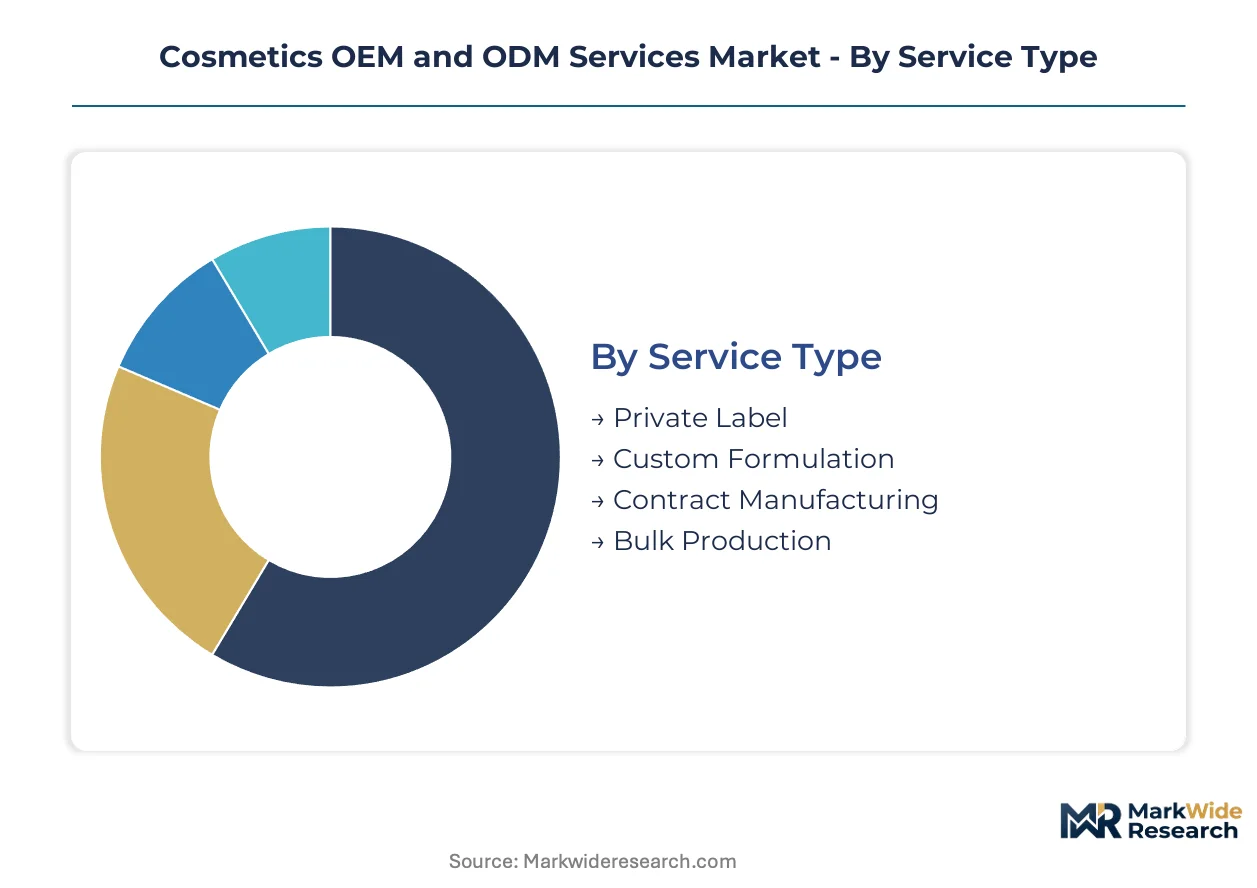
Segmentation in cosmetics OEM and ODM services reveals how regulatory burden, batch economics, and client sophistication fragment manufacturing demand. Each dimension carries distinct certification requirements and margin structures that shape partner selection.
Service Type:
ISO 22716 GMP certification applies universally, while REACH registration and MFDS facility audits concentrate in custom formulation and contract manufacturing tiers.
- Private Label:Pre-validated stock formulations with minimal modification require basic stability documentation and expedited regulatory filing. Mass market brands in India leverage these services to bypass BIS laboratory testing delays for standard moisturizer and cleanser bases.
- Custom Formulation:Proprietary active ingredient development demands full REACH dossier preparation, ECHA substance notification, and MFDS efficacy claim substantiation. Seoul-based R&D campuses anchor this segment for global skincare clients seeking microbiome-targeted actives.
- Contract Manufacturing:Turnkey production with client-supplied specifications occupies the middle tier of regulatory complexity.
- Bulk Production:Unbranded intermediate manufacturing for downstream filling and packaging operations.
Private Label sits at the top of the volume ranking, with Custom Formulation climbing the fastest.
Client Type:
Minimum order quantity thresholds and R&D co-investment requirements stratify clients across three cost tiers.
- Luxury Brands:Exclusive formulation access with dedicated production lines and batch-level traceability documentation. LVMH and Estée Lauder subsidiaries commission captive manufacturing cells in Incheon corridors, absorbing premium pricing for IP protection and supply exclusivity.
- Indie Brands:Digitally native labels with sub-10,000 unit launches drive demand for flexible batch sizes and rapid regulatory filing support. North American direct-to-consumer founders outsource entire supply chains to Seoul-based partners to access MFDS-registered facilities without capital investment.
- Mass Market Brands:High-volume, low-margin production with standardized formulation libraries.
- Retail Chains:Private label programs for drugstore and grocery channels with seasonal promotional cycles.
Mass Market Brands generate the highest absolute unit volumes, though Indie Brands are expanding most quickly.
Product Type:
Formulation complexity and stability testing intensity vary substantially across personal care categories.
- Skincare:Multi-phase emulsions with active ingredient delivery systems require extended accelerated aging studies and preservative efficacy validation. EU Green Deal microplastic restrictions and REACH substance evaluations concentrate compliance investment in this category, particularly for rinse-off exfoliants and SPF formulations.
- Makeup:Pigment dispersion technology and color consistency batch controls dominate manufacturing specifications. Intercos Group and similar specialists maintain leadership in pressed powder and liquid foundation production for luxury houses.
- Haircare:Surfactant-based cleansing and conditioning systems with lower regulatory scrutiny than skincare actives.
- Fragrance:Alcohol-based formulations with IFRA compliance and flammability handling requirements.
Skincare commands the steepest expansion trajectory as indie brands prioritize premium facial care launches.
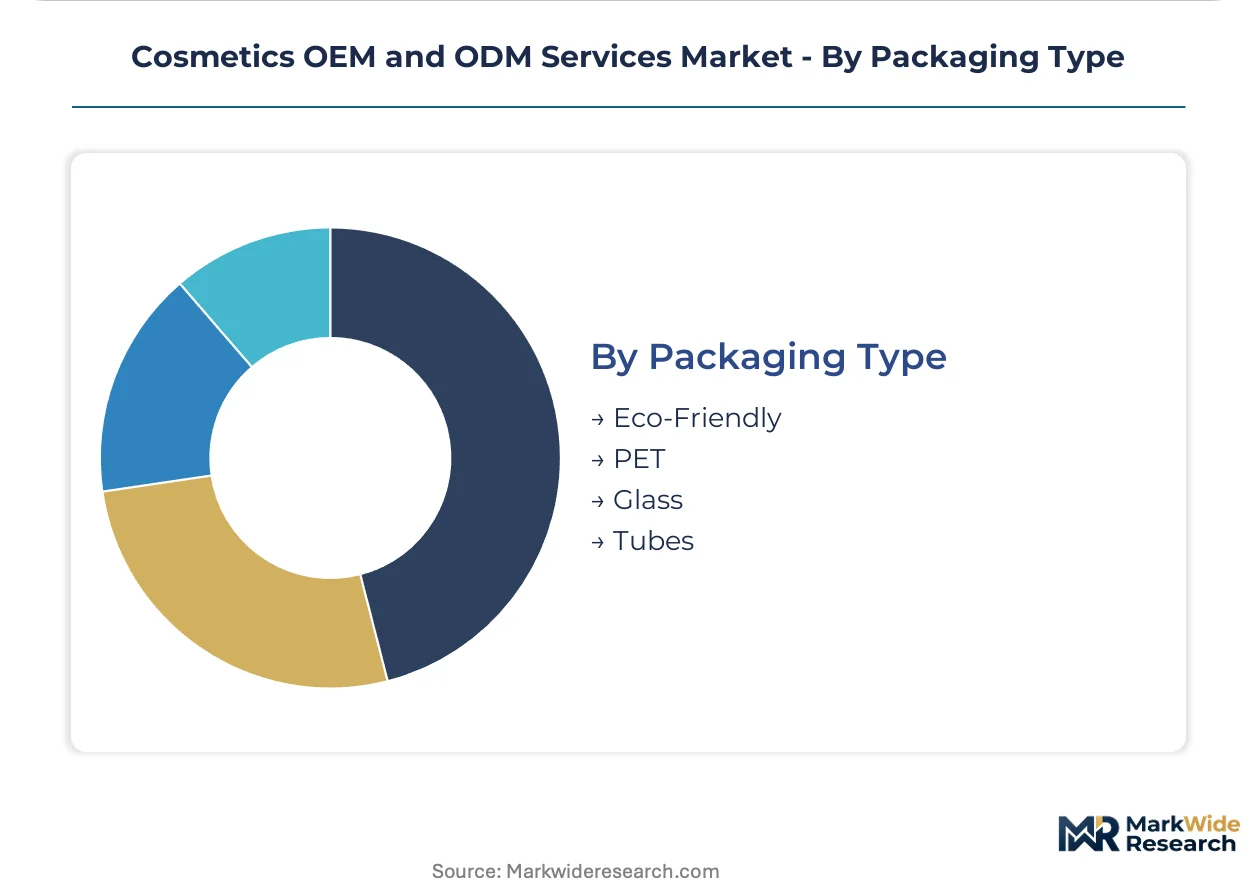
Packaging Type:
Material selection directly determines EU packaging waste directive compliance costs and shipping economics.
- Eco-Friendly:Biodegradable polymers, refillable systems, and aluminum alternatives validated against 2026 EU recyclability mandates. Waterless solid formats in concentrated balms and powder compacts reduce material intensity and align with microplastic restriction timelines.
- Glass:Premium positioning with infinite recyclability but higher shipping weight and breakage risk.
- PET:Lightweight, shatter-resistant standard for mass market personal care.
- Tubes:Flexible laminate and mono-material structures for viscous skincare and haircare products.
PET retains dominant volume share, while Eco-Friendly formats gain share fastest ahead of regulatory enforcement deadlines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic chemist talent clusters in Seoul, Milan, and New Jersey anchor regional production capabilities. Regulatory divergence between REACH, FDA, and NMPA frameworks fragments compliance infrastructure investments. Manufacturing gravity concentrates where biotech fermentation capacity co-locates with formulation science expertise.
United States
Indie brand proliferation in Brooklyn and Los Angeles drives demand for flexible batch manufacturing. FDA cosmetic facility registration requirements under MoCRA elevate compliance costs for foreign exporters. New Jersey's Raritan Valley corridor hosts concentrated contract manufacturing campuses serving direct-to-consumer skincare labels.
South Korea
Seoul's Songdo and Incheon production corridors integrate MFDS-registered facilities with captive bioreactor infrastructure. The country's national pharmaceutical regulator enforces stringent stability testing protocols that international brands leverage as quality signaling. Gyeonggi-do province aggregates raw material suppliers, testing laboratories, and finished goods manufacturers into vertically integrated ecosystems.
Italy
Luxury color cosmetics production concentrates in Lombardy and Emilia-Romagna, anchored by pigment dispersion specialists. EU Green Deal packaging recyclability mandates force reformulation investments across pressed powder and liquid foundation categories. Milan's periphery maintains leadership in makeup innovation for European heritage houses.
China
Domestic indie brand growth in Shanghai and Hangzhou accelerates demand for NMPA-registered contract manufacturing partners. The National Medical Products Administration's extended ingredient filing timelines compress speed-to-market for international entrants. Yangtze River Delta production zones specialize in mass-market skincare and haircare volume manufacturing.
Switzerland
Novel peptide and enzyme suppliers concentrate around Basel and Zurich, creating geographic chokepoints for active ingredient supply. Swissmedic oversight of cosmetic-dermatological border products elevates barrier costs for premium positioning. The country's biotech corridor supplies fermentation-derived ceramides and collagen to global OEM/ODM partners.
Cosmetics OEM and ODM Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service categories. The vendor base stratifies between Seoul-based integrated manufacturers, Italian color cosmetics specialists, and regional private-label fabricators. Three archetypes dominate: biotechnology-forward active ingredient developers, scale-driven mass-market producers, and luxury-exclusive formulation houses. Competitive moves concentrate on captive fermentation capacity acquisition and MFDS/FDA dual-registration facility construction.
Within the integrated manufacturing tier, Kolmar Korea Co., Ltd. and Cosmax Inc. exemplify Seoul-based production scale. Intercos Group occupies a position representing Italian color cosmetics specialization. These three entities anchor distinct competitive vectors: biotech R&D integration, continental manufacturing footprint, and makeup technology leadership respectively.
| Leading Market Players |
|---|
| Kolmar Korea Co., Ltd. |
| Cosmax Inc. |
| Intercos Group |
| Nox Bellow Cosmetics Co., Ltd. |
| BioTruly Company Limited |
| Nihon Kolmar Co., Ltd. |
| Chromavis S.p.A. |
| Ancorotti Cosmetics S.r.l. |
| Cosmecca Korea Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Indie brand procurement of sub-10,000 unit batches forces Seoul-based manufacturers to recalibrate minimum order economics, compressing margin buffers and privileging partners with captive fermentation capacity over pure toll manufacturers.
Pricing Analysis
Capacity additions in India's Gujarat corridor are reshaping price floors for standard emulsion bases, introducing competitive tension into fixed-price contract structures. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-registered custom formulation from private-label stock bases and unbranded bulk intermediates. Price differentiation rests on certification tier and volume scale, with REACH dossier preparation adding substantial overhead to European-bound production. Pricing pressure stems from petrochemical surfactant volatility, squeezing mass-market labels most acutely while luxury clients absorb compliance premiums with minimal sensitivity.
Supply Chain Analysis
Dual-sourcing qualification mandates from LVMH and Estée Lauder subsidiaries force contract manufacturers to maintain redundant active ingredient pipelines, elevating working capital requirements. Supply concentrates in South Korea, Switzerland, and China's Yangtze River Delta, drawing from novel peptide suppliers around Basel, bioreactor infrastructure in Songdo, and mass-market surfactant production in Zhejiang. Raw material dependencies include fermentation-derived ceramides, petrochemical polymers, and botanical extracts from single-origin agricultural zones. Single-source biotech inputs create geographic vulnerability to capacity allocation decisions. Distribution runs through vertically integrated OEM/ODM partners with blockchain-enabled lot-level traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU Green Deal compliance costs and India's PLI manufacturing incentives, with formulation expertise migrating toward regulatory complexity while volume production chases subsidy-backed capacity.
For Market Incumbents: Cement captive fermentation capacity in Gyeonggi-do province to lock in microbiome-active margins against Swiss biotech suppliers. Defend position by securing MFDS-FDA dual-registration facilities before NMPA registration timelines extend further, converting regulatory burden into client switching costs. For New Entrants and Emerging Players: Enter via waterless solid format specialization targeting EU microplastic restriction deadlines, where incumbent retooling lags create temporary white space. India's domestic indie brand segment offers the most penetrable geography, with Mumbai-based contract manufacturing gaps and PLI-backed facility economics supporting asset-light market entry through private-label stock formulation libraries. For Investors and Strategic Acquirers: Asymmetric upside sits with Seoul-integrated manufacturers possessing captive R&D campuses and bioreactor infrastructure, as biotechnology-derived actives displace commodity chemical supply chains over the coming decade. Acquisition targets should demonstrate dual-registration compliance architecture and blockchain traceability implementation. Watch for NMPA registration timeline compression as the signal indicating Chinese market re-entry feasibility for international brand portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Acquisition | Bioreactor infrastructure in Seoul secures margin pools from precision collagen and ceramide production. |
| MFDS-FDA Dual-Registration Facility Construction | Dual compliance architecture converts regulatory burden into client retention moats for premium skincare. |
| AI-Driven Formulation Platform Deployment | Machine learning compression of R&D cycles from months to weeks accelerates indie brand speed-to-market. |
| Waterless Solid Format Product Line Expansion | Concentrated balm and powder formulations align with EU microplastic restriction enforcement timelines. |
| Blockchain Lot-Level Traceability Implementation | Transparent supply chain documentation meets direct-to-consumer brand procurement specifications. |
Research Methodology
Direct dialogue with cosmetic chemists, regulatory affairs directors at MFDS-registered facilities, indie brand founders, and raw material procurement leads anchored qualitative findings, cross-referenced against MFDS facility audit records, REACH registration databases, EU Green Deal implementation directives, and customs trade data for surfactant and polymer inputs. Bottom-up volume estimates from individual manufacturing capacity filings triangulated against top-down market sizing from beauty industry association reports.
Segment-level outputs across service type, client tier, product category, and packaging material were generated through the projection horizon, with CAGRs derived from regression analysis of historical batch economics and regulatory compliance cost trajectories. Forecast inputs incorporated indie brand formation rates, bioreactor capacity expansion pipelines, and NMPA registration queue lengths.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time bioreactor utilization rates and confidential client contract pricing introduce uncertainty bands around margin structure projections. Deviation in EU microplastic restriction enforcement timing or NMPA regulatory streamlining would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
J-Beauty Products Market
Cosmetics & Skincare
Liquid Lipstick Market
Cosmetics & Skincare
Cold Pressed Soap Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
Global Cosmetic Antioxidant Market
Cosmetics & Skincare
China Cosmetic Products Market
Cosmetics & Skincare
Vietnam Skin Care Products Market
Cosmetics & Skincare
United Arab Emirates Cosmetic Products Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market
Cosmetics & Skincare
Eyeliner Pen Market