
 Gas Ranges Market | 2026-2036
Gas Ranges Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Ranges Market Analysis
Dual-fuel and precision burner technology is fragmenting traditional gas range architectures into modular, IoT-enabled cooking platforms. Wolf leverages its heritage in professional-grade craftsmanship to dominate the premium built-in segment. Samsung competes through smart home ecosystem integration that extends its kitchen appliance connectivity. Miele sustains its position via German engineering standards that anchor its high-efficiency product lines.
Gas ranges are fuel-fired cooking appliances employing sealed burners with BTU outputs typically spanning 5,000 to 22,000 units, designed for direct-flame heat distribution in residential and commercial food preparation. The freestanding category retains volume leadership due to retrofit compatibility with existing kitchen footprints, while the slide-in segment captures margin pools through seamless countertop integration demanded by renovation projects. Smart feature integration represents the fastest-growing configuration as connectivity protocols enable remote diagnostics and energy monitoring for both residential and commercial end users.
The US Department of Energy sets minimum efficiency thresholds for gas cooking appliances, while the EPA's ENERGY STAR program shapes consumer purchasing criteria through certified performance benchmarks. In Europe, the Ecodesign Directive and F-Gas Regulation constrain burner emissions and component materials, altering product development priorities for manufacturers seeking CE marking compliance. Stakeholders must monitor evolving efficiency mandates and smart appliance cybersecurity standards as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
The US Department of Energy's tightening burner efficiency standards are forcing manufacturers to re-engineer combustion architectures while commercial hospitality chains accelerate procurement of high-BTU professional units, creating simultaneous pull from regulatory compliance and operational scale demands.
Growth Catalysts
- Commercial Hospitality Expansion:Full-service restaurant chains and hotel groups in Germany, Italy, and South Korea are expanding central kitchen footprints, driving procurement of 22,000+ BTU sealed burner systems for high-throughput food preparation.
- Smart Home Protocol Convergence:Matter and Zigbee interoperability standards are enabling unified control interfaces that reduce installation friction for residential renovation projects specifying slide-in configurations.
- Ecodesign Directive Compliance:European manufacturers achieving CE marking under tightened burner emissions thresholds gain preferential access to public procurement channels in EU member states.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 430 stainless steel price fluctuations compress margin pools for mid-tier freestanding manufacturers dependent on commodity sheet metal supply.
- Ignition System Concentration:Spark module and thermocouple production concentrates in specialized East Asian component suppliers, creating single-source vulnerability for Western OEMs.
- Induction Substitution Threat:Residential builders in jurisdictions with aggressive electrification mandates are specifying induction cooktops over gas ranges for new construction permits.
Strategic Opportunities
- Underpenetrated Professional Catering:Independent food service operators in South Korea represent a white space for modular, IoT-enabled cooking platforms with remote diagnostics capabilities.
- Dual-Fuel Technology Convergence:Precision gas burners paired with electric convection ovens are capturing renovation demand from culinary enthusiasts seeking restaurant-grade temperature control.
- IRA Efficiency Incentives:US residential rebate programs for ENERGY STAR certified appliances are creating pull-through for high-efficiency sealed burner systems in replacement cycles.
Industry Challenges
- Cybersecurity Certification Complexity:Smart appliance manufacturers face fragmented IoT security standards across FCC, EU Cybersecurity Act, and South Korea's KISA frameworks, extending product launch timelines.
- Combustion Engineering Talent Scarcity:Specialized expertise in low-NOx burner design and flame stability modeling is concentrating at a small number of engineering consultancies, inflating R&D payroll costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Ranges Market |
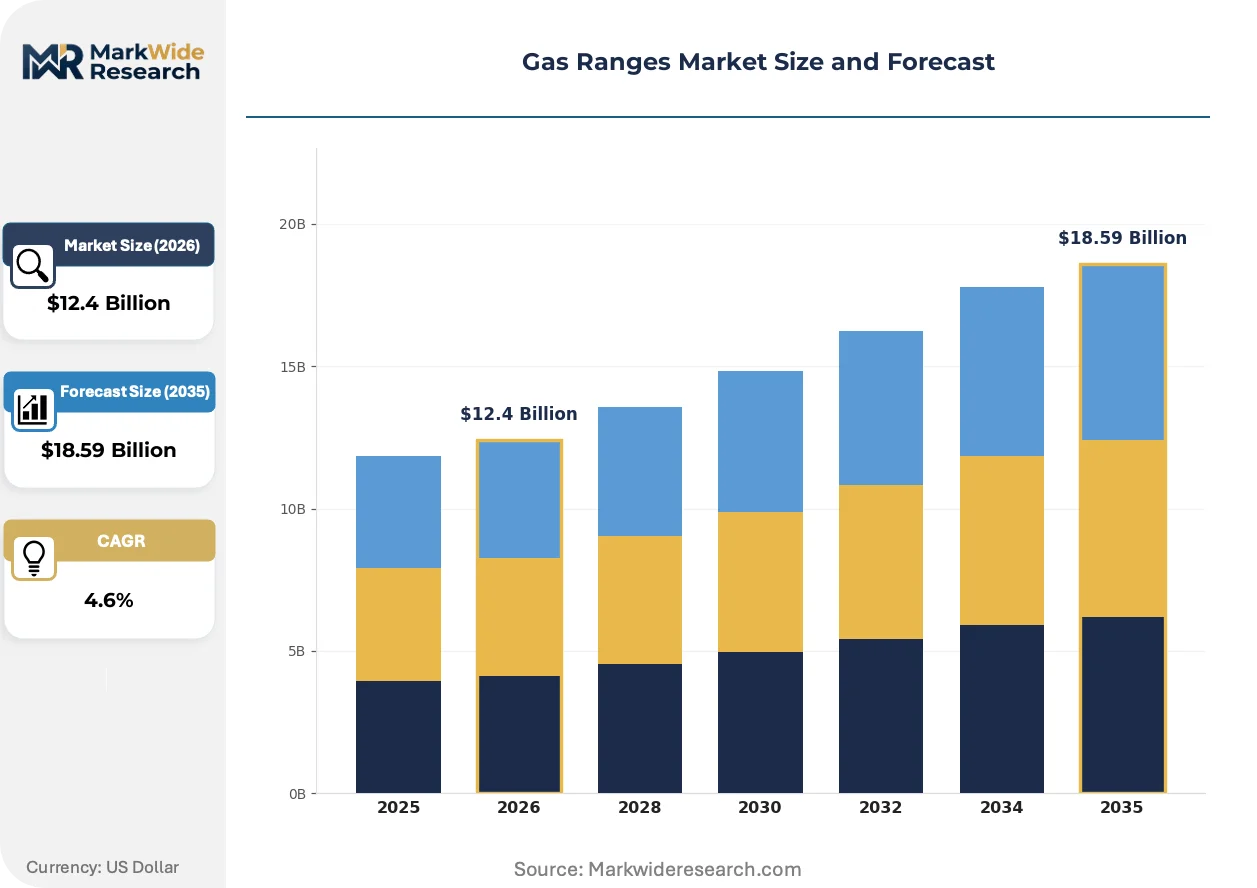
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Slide-In, Built-In, Portable End User: Residential, Commercial, Industrial, Catering Feature: Conventional, Self-Cleaning, Smart, High-Efficiency Size: 30 Inch, 36 Inch, 48 Inch, Customizable |
| Companies Covered | Wolf, LG, GE, Samsung, Bertazzoni, Viking, Miele, BlueStar, Thermador, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Ranges Market Emerging Trajectories
Connected cooking platforms and precision thermal management systems are fragmenting traditional gas range architectures, while regulatory pressure on emissions and efficiency compresses development cycles for combustion engineering teams.
Digital twin simulation software is virtualizing the traditional physical prototyping phase for burner development. Engineering teams at major OEMs are adopting computational fluid dynamics platforms to model flame geometry and heat distribution before cutting metal. This virtualization is compressing 18-month product development cycles into 10-month windows while reducing scrap rates for injection-molded burner caps and cast iron grates.
The EPA's ENERGY STAR Version 7.0 specifications for cooking products are mandating measurable efficiency gains in standby and active cooking modes. Manufacturers must demonstrate reduced gas consumption per cooking task to retain certification eligibility for federal procurement programs. Commercial kitchen operators in US school districts and hospital systems are now specifying ENERGY STAR-qualified ranges exclusively, shifting specification authority from facilities managers to sustainability officers.
Builder procurement patterns are rotating toward specification bundling with full kitchen appliance packages rather than standalone range purchases. Production homebuilders in Texas and Florida are negotiating volume contracts with distributors for coordinated refrigerator, dishwasher, and range deliveries timed to construction milestones. This consolidation concentrates purchasing power at regional distributor level, compressing available margin for standalone range specialists competing for new construction slots.
Gas Ranges Market Segmentation
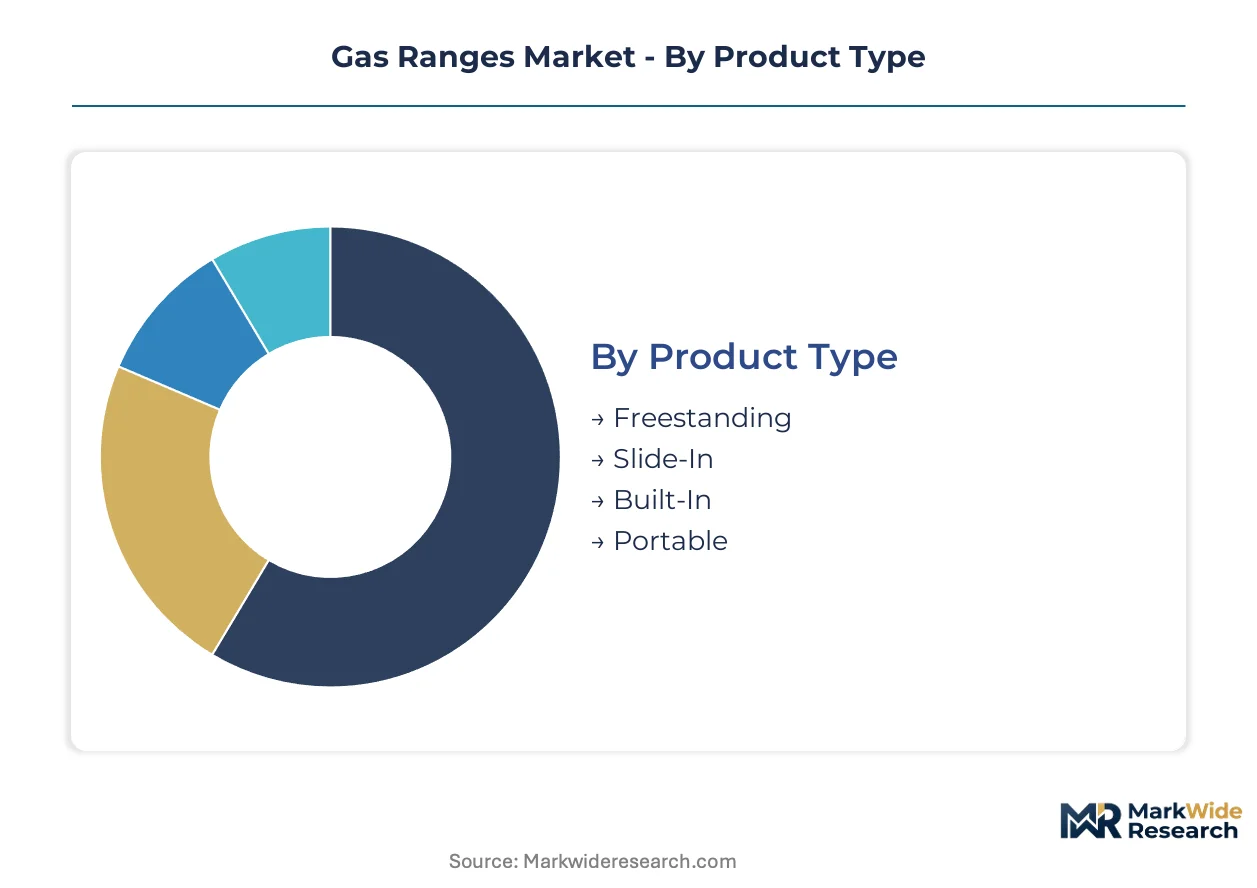
Gas range procurement cycles vary dramatically across configuration types and end-use contexts. Understanding these turnover patterns enables manufacturers to align production capacity with replacement demand and new installation flows.
Product Type:
Replacement cycles stretch from 12 years for built-in installations down to 3-5 years for portable units in food service fleets, creating distinct inventory planning rhythms for each configuration tier.
- Freestanding:Self-contained units with finished side panels designed for standalone placement against kitchen walls. Demand concentrates in US residential replacement cycles where existing cabinetry constraints limit renovation scope, driven by retrofit compatibility with legacy kitchen footprints.
- Slide-In:Front-control ranges with unfinished sides engineered for seamless countertop integration. Kitchen renovation projects across Germany and Italy specify these configurations for premium aesthetic continuity, with procurement tied to coordinated appliance package purchases.
- Built-In:Drop-in or wall-oven combinations requiring custom cabinetry support. South Korean hospitality chains specify these for flagship property installations where kitchen design flexibility warrants higher capital expenditure.
- Portable:Compact units with caster mobility for temporary or auxiliary cooking capacity. Independent catering operators deploy these for event-based food service where fixed infrastructure is unavailable.
Freestanding dominates installed base. Slide-In is where expansion concentrates.
End User:
Cost tiers separate specification authority from procurement execution, with residential buyers self-directing purchases while commercial operators delegate to facilities managers or sustainability officers.
- Residential:Individual homeowners and rental property managers purchasing for single-family or multi-unit dwellings. ENERGY STAR rebate eligibility under US IRA programs is concentrating demand in high-efficiency sealed burner configurations.
- Commercial:Full-service restaurants, hotels, and institutional food service operations. Procurement across Texas and Florida production homebuilders bundles ranges with refrigerator and dishwasher packages, shifting purchasing power to regional distributors.
- Industrial:Central commissary kitchens and food manufacturing facilities with continuous production requirements. These operators specify 22,000+ BTU burner systems for throughput maximization.
- Catering:Mobile food service operators and event-focused culinary businesses. South Korea's independent catering segment represents underpenetrated white space for modular IoT-enabled platforms with remote diagnostics.
Residential commands volume leadership. Commercial is climbing the fastest on hospitality chain expansion.
Feature:
Technology maturity curves separate legacy configurations from emerging connectivity platforms, with regulatory pressure accelerating transitions across all tiers.
- Conventional:Basic burner systems without automated cleaning or connectivity functionality. These retain share in price-sensitive replacement segments where existing ventilation infrastructure cannot support advanced features.
- Self-Cleaning:Pyrolytic or catalytic oven cleaning cycles reducing manual maintenance. European Ecodesign Directive compliance requirements are embedding these as baseline expectations for CE marking eligibility.
- Smart:IoT-enabled ranges with remote diagnostics, energy monitoring, and protocol interoperability. Matter and Zigbee convergence is reducing installation friction for renovation projects specifying unified control interfaces.
- High-Efficiency:Optimized combustion architectures meeting tightened DOE burner performance thresholds. US school districts and hospital systems now mandate these exclusively, shifting specification authority to sustainability officers.
Conventional retains legacy installed base. Smart is gaining share fastest on protocol standardization.
Size:
Volume concentration versus margin extraction separates mass-market configurations from specialized professional formats.
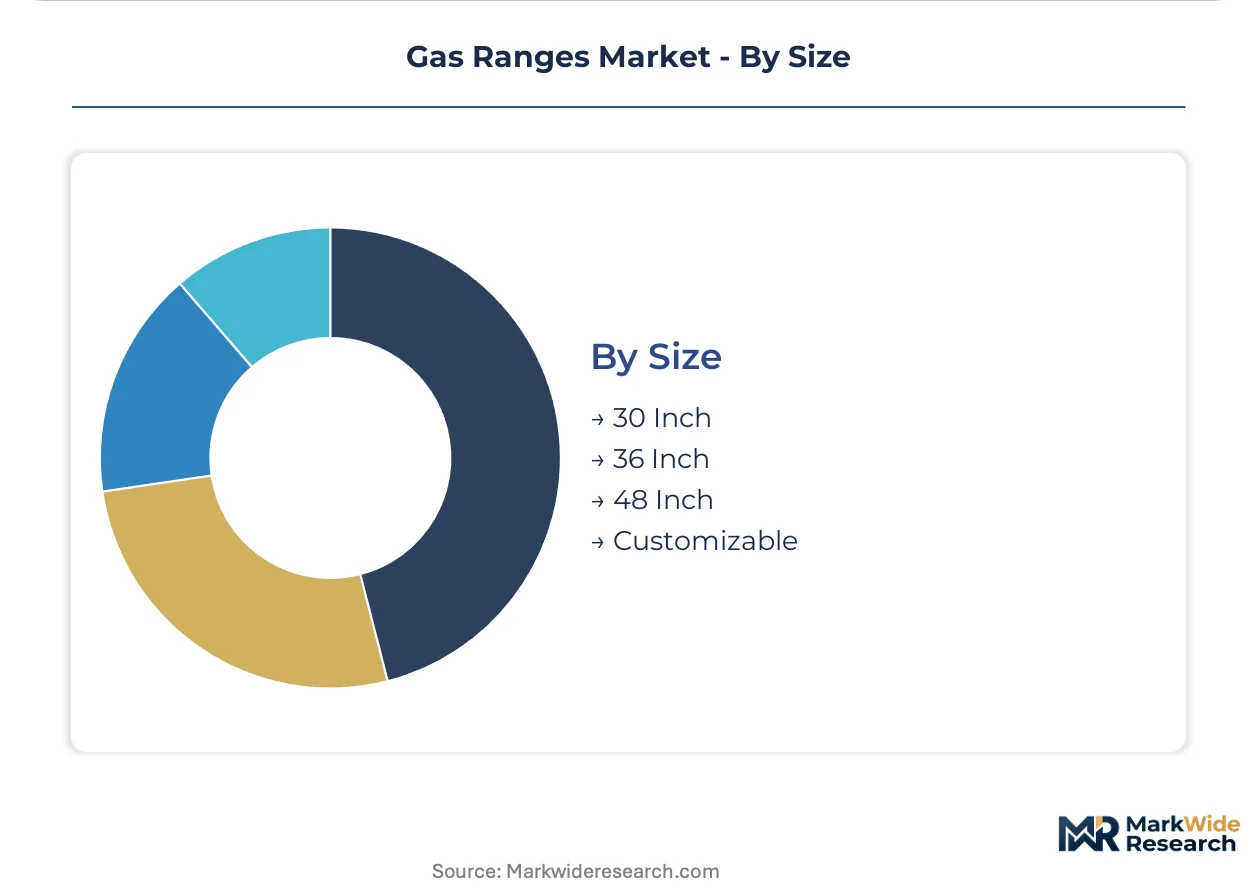
- 30 Inch:Standard width fitting residential kitchen cutouts prevalent in existing US housing stock. These configurations dominate replacement cycle procurement where cabinetry modification is cost-prohibitive.
- 36 Inch:Expanded width enabling additional burner capacity or griddle integration. Premium residential renovations and small commercial operations specify these for enhanced cooking surface flexibility.
- 48 Inch:Professional-grade widths supporting six-burner configurations or dual oven chambers. Culinary enthusiasts seeking restaurant-grade temperature control drive renovation demand for these formats.
- Customizable:Modular widths and component arrangements specified for commercial kitchen footprints. Central kitchen expansions in German and Italian hospitality chains require these for space-optimized layouts.
30 Inch commands mass-market volume. 36 Inch is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional catering operators and hospitality chains concentrate procurement authority across Germany, Italy, South Korea, and the United States, while residential replacement cycles dominate volume flows in established housing markets.
United States
Production homebuilders in Texas and Florida negotiate bundled appliance packages that compress standalone range margins, while IRA rebate programs for ENERGY STAR-certified units pull residential buyers toward high-efficiency sealed burner configurations. The Department of Energy's tightening burner performance standards force combustion re-engineering across all import and domestic production. Dallas-Fort Worth and Houston metropolitan clusters anchor distribution hub activity for regional builder supply.
Germany
Full-service restaurant chains and hotel groups expand central kitchen footprints, driving specification of 22,000+ BTU professional systems for high-throughput food preparation. Ecodesign Directive compliance requirements under CE marking protocols embed self-cleaning cycles as baseline expectations for market access. The Munich-Stuttgart corridor concentrates engineering consultancies with specialized low-NOx burner design expertise.
Italy
Kitchen renovation projects specify slide-in configurations for premium aesthetic continuity, with procurement tied to coordinated appliance package purchases across Lombardy and Veneto. The Ecodesign Directive and F-Gas Regulation constrain burner emissions and component materials, altering product development priorities for manufacturers seeking EU market entry. Bologna anchors a cluster of precision metalworking suppliers serving burner component fabrication.
South Korea
Independent food service operators represent underpenetrated white space for modular, IoT-enabled cooking platforms with remote diagnostics capabilities, while hospitality chains specify built-in configurations for flagship property installations. KISA cybersecurity frameworks for smart appliances extend product launch timelines for connected range introductions. The Seoul Capital Area concentrates procurement decision-making for both commercial hospitality and catering segments.
Gas Ranges Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered price bands, creating a structure where heritage craftsmanship anchors premium positioning while ecosystem integration drives mid-market conversion. The vendor base separates into three archetypes: professional-grade specialists commanding specification authority in commercial kitchens, smart home ecosystem integrators leveraging connectivity protocols, and efficiency-focused engineering houses optimizing for regulatory compliance. Dominant competitive moves include portfolio diversification into dual-fuel configurations and strategic partnerships with IoT protocol standardization bodies.
Within the professional-grade tier, Wolf and Miele exemplify heritage-driven positioning that commands specification authority in renovation and commercial segments. Wolf leverages its craftsmanship legacy to dominate premium built-in installations, while Miele sustains its position via German engineering standards anchoring high-efficiency product lines. Samsung occupies a distinct position as an ecosystem integrator, competing through smart home connectivity that extends kitchen appliance interoperability across residential renovation projects.
| Leading Market Players |
|---|
| Wolf |
| LG |
| GE |
| Samsung |
| Bertazzoni |
| Viking |
| Miele |
| BlueStar |
| Thermador |
| Others |
Supply Flow & Price Mechanics
Stainless steel input volatility determines both pricing tier spreads and supply chain shape across gas range manufacturing, with Grade 304 and 430 price fluctuations compressing margin pools for mid-tier freestanding producers while forcing vertical integration decisions among premium built-in specialists.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement between OEMs and stainless steel suppliers, creating transparent pass-through mechanics for commodity sheet metal. Three-tier pricing structure across premium, standard, and economy levels separates Wolf and Miele craftsmanship positioning from Samsung ecosystem bundles and entry-level freestanding imports. Cost compression in mid-tier configurations is intensifying because production homebuilders in Texas and Florida negotiate volume appliance packages that strip standalone range premiums. Residential replacement buyers exhibit highest price sensitivity, while commercial hospitality chains in Germany and Italy prioritize BTU throughput over unit economics.
Supply Chain Analysis
Export-control scrutiny on precision combustion components limits flows of specialized spark modules and thermocouple assemblies from concentrated East Asian suppliers. Manufacturing gravity centers on China for commodity burner castings, South Korea for electronic ignition systems, and Italy for precision metalworking of burner caps and grates. Raw material dependencies span nickel-bearing stainless steels, cast iron grates, and ceramic igniter elements. Single-source vulnerability concentrates in thermocouple production, where two specialized suppliers serve Western OEM demand. Distribution runs through regional appliance distributors coordinating bundled deliveries to production homebuilders and hospitality procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gas range penetration in professional catering segments across South Korea and hospitality chain central kitchens signals early-cycle expansion, with modular IoT-enabled platforms capturing specification authority previously held by conventional sealed burner systems.
For Market Incumbents: Harden combustion engineering capabilities through captive recruitment at Munich-Stuttgart corridor consultancies, insulating against talent scarcity inflating low-NOx burner design payroll costs. Secure backward integration into ignition module production to eliminate single-source exposure from East Asian component suppliers. Defend specification authority in ENERGY STAR procurement channels by accelerating Version 7.0 compliance certification ahead of federal mandate timelines.
For New Entrants and Emerging Players: Establish a beachhead in South Korea's independent catering segment, where remote diagnostics capabilities remain underpenetrated relative to hospitality chain installations. Target modular cooking platforms with Matter protocol interoperability, reducing installation friction for renovation contractors specifying unified smart home interfaces. Pursue white-label partnerships with regional distributors serving Texas and Florida production homebuilder channels, bypassing standalone brand building costs.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors engineering-heavy specialists over ecosystem integrators, with dual-fuel precision burner expertise commanding scarcity premiums. Acquisition targets should display captive low-NOx combustion design teams and established CE marking pathways under tightened Ecodesign Directive thresholds. Watch KISA cybersecurity certification timelines as inflection indicators for smart appliance launch velocity in Seoul Capital Area procurement decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Platform Development | Precision gas burners paired with electric convection ovens capture culinary enthusiast renovation demand seeking restaurant-grade temperature control. |
| Matter Protocol Certification | Interoperability standardization reduces installation friction for slide-in configuration adoption across unified smart home renovation projects. |
| Low-NOx Combustion Engineering Investment | Specialized flame stability modeling capabilities concentrate at Munich-Stuttgart consultancies, creating acquisition premiums for captive expertise. |
| Backward Integration into Ignition Components | In-house spark module production eliminates single-source vulnerability from concentrated East Asian thermocouple suppliers serving Western OEMs. |
| ENERGY STAR Version 7.0 Pre-Certification | Early compliance secures specification authority in US school district and hospital system procurement channels shifting to sustainability officers. |
Methodological Framework
The analysis maps freestanding, slide-in, built-in, and portable configuration sub-sectors, each validated through facilities managers at hospitality chains, sustainability officers at institutional food service operations, procurement leads at production homebuilders, and engineering directors at combustion component suppliers. Primary interview insights triangulate against US Department of Energy appliance efficiency filings, EPA ENERGY STAR certification databases, EU Ecodesign Directive compliance registries, and South Korea KISA cybersecurity framework documentation. Bottom-up unit shipment estimates by configuration and feature tier reconcile with top-down market value assessments across residential, commercial, industrial, and catering end-use segments.
Forecast assumptions hold fixed current DOE burner efficiency thresholds and EU Ecodesign Directive emission limits while varying smart home protocol adoption rates and hospitality chain expansion trajectories across the projection horizon. Segmentation dimensions modeled include product configuration type, end-use context, feature technology tier, and burner BTU output class. CAGRs derive from replacement cycle timing analysis combined with new installation flow projections tied to construction permit data and renovation spending indices. Industry-specific inputs incorporate stainless steel price index trajectories and ENERGY STAR rebate program enrollment velocity under IRA efficiency incentives.
Sensitivities concentrate around regulatory acceleration in electrification mandates displacing gas range specification in new construction, cybersecurity certification timeline extensions under fragmented FCC-EU-KISA frameworks, and commodity volatility in nickel-bearing stainless inputs. Forecasts reflect assumptions regarding sustained hospitality capital expenditure in Germany, Italy, and South Korea. Material shifts in US residential builder electrification requirements or EU F-Gas Regulation expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Glass Ceramic Cooktop Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Residential Vacuum Cleaners Market
Appliances
Mini Washing Machine Market
Appliances
GCC Dishwashers Market
Appliances
Smart Washing Machine Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Portable Fridges Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
French Door Refrigerator Market
Appliances
Egypt Dishwashers Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Refrigerator Door Seal Market
Appliances
Portable Mini Fridge Market
Appliances
France Household Electric Grills Market
Appliances
Saudi Arabia Dishwasher Market