
 Fitness Rings Market | 2026-2036
Fitness Rings Market Size, Share, and Industry Trends Forecast 2026-2036
Fitness Rings Market Foresight
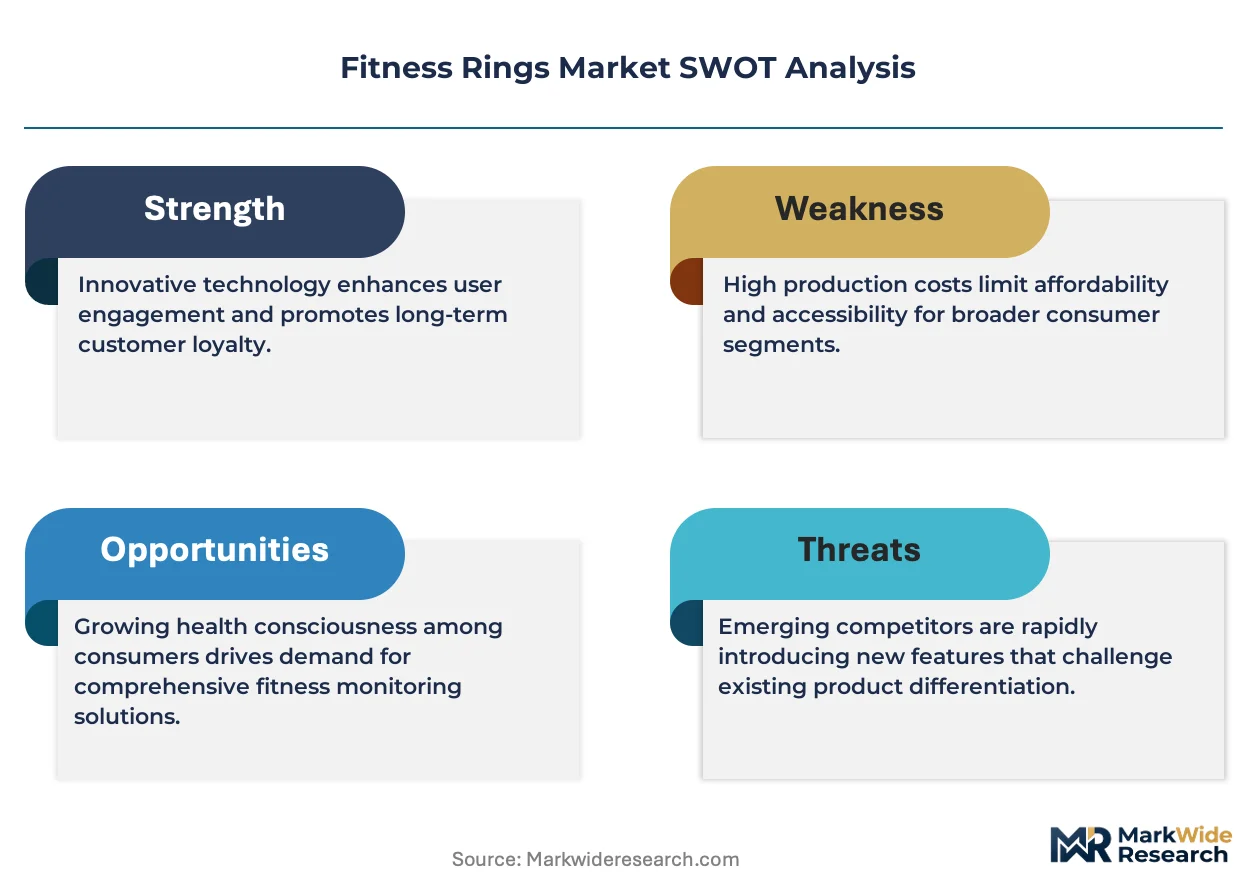
Embedded systems engineering talent scarcity is unwinding manufacturing timelines for advanced fitness rings with multi-sensor fusion. Oura leverages its Helsinki-based R&D footprint to sustain proprietary algorithm development for sleep stage classification. Samsung competes through backward integration into custom SoC design that controls power draw across optical sensor arrays. Ultrahuman differentiates by anchoring its hardware to metabolic score subscription tiers rather than one-time device margins.
Fitness rings are titanium or ceramic band-encased wearable computers integrating photoplethysmography optical sensors, three-axis accelerometers, and skin temperature detectors to capture cardiovascular, activity, and recovery metrics continuously. Smart rings with heart rate variability tracking occupy the highest-margin product tier, while sleep tracking rings face commoditization as basic optical modules drop in cost. Optical sensor technology leads unit economics through economies of scale borrowed from smartwatch supply chains, whereas NFC-enabled payment-integrated rings represent the fastest-growing technology segment as transit and retail wallet adoption accelerates.
FDA clearance pathways for photoplethysmography-based devices shape clinical credibility claims and reimbursement adjacent opportunities in the United States. CE marking under the EU MDR and GDPR biometric data processing requirements constrain how European vendors store and transmit health telemetry across cloud infrastructure. Stakeholders must monitor whether national medical device regulators reclassify continuous SpO2 monitoring as a diagnostic function rather than general wellness, which would trigger premarket submission requirements and reshape competitive moats for non-compliant hardware vendors.
Market Dynamics
Photoplethysmography optical sensor miniaturization is compressing component costs while multiplying biometric capture channels inside titanium form factors. This technical trajectory is redrawing competitive moats around algorithm development rather than hardware assembly.
Growth Catalysts
- Bluetooth Low Energy integration:Continuous data streaming from finger-based wearables to mobile health platforms enables real-time recovery coaching without battery trade-offs.
- Corporate wellness program expansion:United States employers are adding preventative biometric monitoring to benefits packages, creating institutional procurement pull for ring-based devices.
- NMPA medical device pathway:China's classification clarity for optical heart rate wearables is accelerating product registration timelines and reducing regulatory uncertainty for market entrants.
Market Restraints
- Embedded systems engineering scarcity:Multi-sensor fusion firmware development talent concentrates in Helsinki and Shenzhen, creating recruitment bottlenecks for manufacturers outside these clusters.
- Optical module supply concentration:Photodiode and LED component sourcing depends on smartwatch supply chain spillover, exposing ring makers to allocation priority shifts.
- GDPR biometric data friction:European cloud infrastructure constraints on health telemetry storage raise operational overhead for vendors serving EU consumers.
Strategic Opportunities
- NFC payment convergence:Transit and retail wallet integration is opening a hardware category distinct from health-focused rings, with faster replacement cycles.
- Subscription-anchored hardware economics:Metabolic score and sleep coaching recurring revenue models are decoupling vendor profitability from one-time device margins.
- FDA clearance pathway leverage:Photoplethysmography-based clinical credibility claims in the United States create reimbursement-adjacent positioning for compliant vendors.
Industry Challenges
- SpO2 reclassification risk:National medical device regulators may recategorize continuous blood oxygen monitoring as diagnostic, triggering premarket submission requirements for existing hardware.
- Algorithm validation timelines:Sleep stage classification accuracy claims require polysomnography ground-truth studies, extending R&D cycles before commercial launch.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fitness Rings Market |
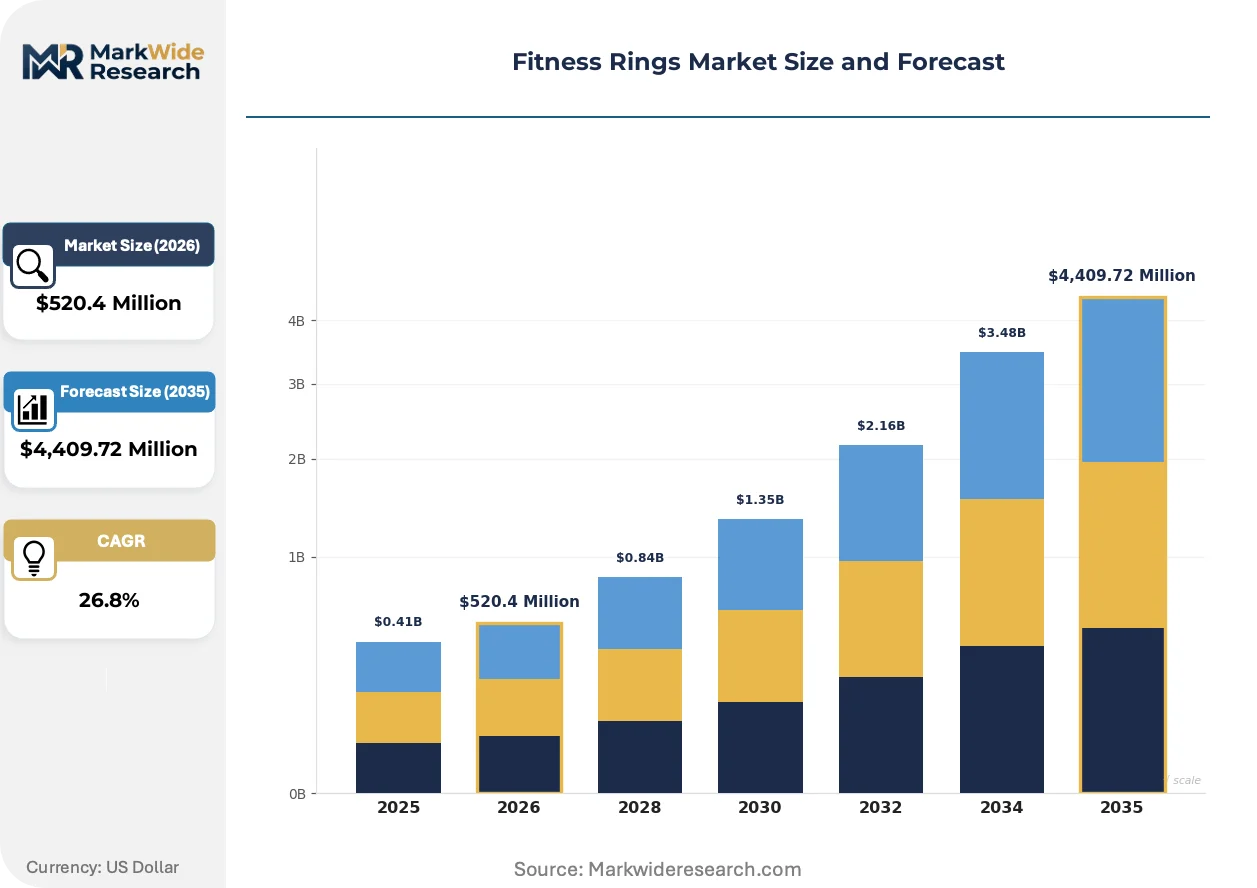
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $4,409.72 Million |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Rings, Heart Rate Monitoring Rings, Sleep Tracking Rings, Activity Monitoring Rings, Oxygen Saturation Rings Technology: Optical Sensors, Accelerometers, Gyroscopes, Bluetooth Connectivity, NFC, Haptic Feedback Application: Personal Fitness, Stress Management, Sleep Quality Analysis, Weight Management, Meditation Tracking End User: Fitness Enthusiasts, Wellness Centers, Sports Professionals, Corporate Wellness Programs |
| Companies Covered | RingConn, Prevention Circul+, Oura, Mirlray, UniJethro, Samsung, Amazfit, Herz, Ultrahuman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fitness Rings Market Shifts & Advancements
Hardware commoditization is pushing competitive differentiation toward proprietary signal processing and vertical software integration. Vendors are racing to convert biometric streams into actionable health scores before optical module costs collapse further.
Multi-wavelength photoplethysmography is supplanting single-channel optical designs for cardiovascular metric extraction. Corporate wellness buyers in the United States are specifying HRV-grade accuracy in procurement tenders. This technical escalation is compressing margins for basic sleep-tracking ring configurations while rewarding vendors with validated clinical pipelines.
CE marking under the EU MDR is tightening biocompatibility and electromagnetic compatibility requirements for skin-contact wearables. European vendors are restructuring cloud architectures to isolate biometric data processing within regional boundaries. Sleep tracking rings with cloud-dependent feature sets face the steepest compliance redesign burden.
Hardware-plus-subscription bundling is displacing standalone device sales in North American metropolitan health-tech corridors. Direct-to-consumer channels are ceding ground to employer-sponsored distribution and health insurer incentive programs. This shift is most visible in United States corporate benefits administration, where biometric engagement metrics determine vendor selection.
Fitness Rings Market Segmentation
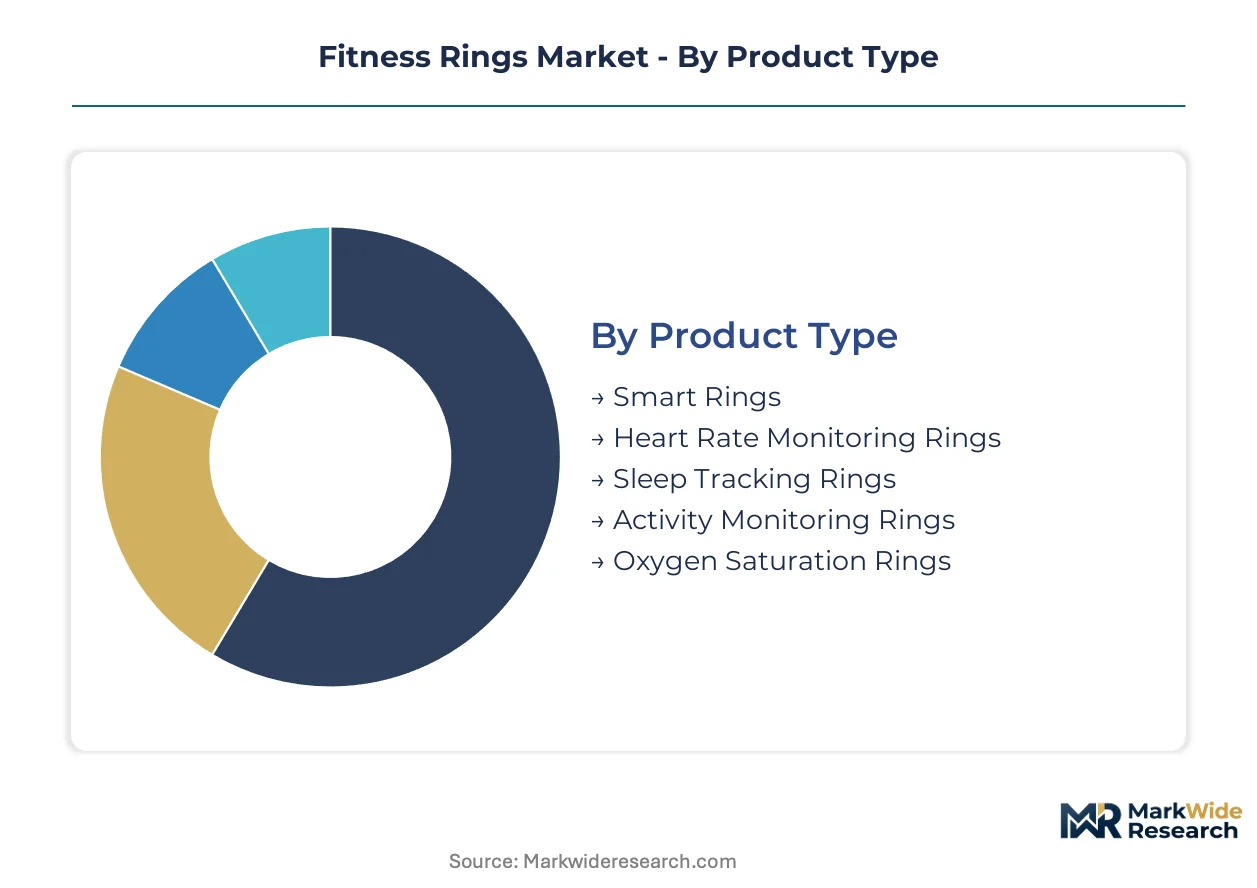
Fitness rings segment across hardware specifications, biometric capture technologies, use-case intensity, and procurement channel economics. Understanding where margin pools concentrate within each dimension reveals which product configurations command pricing power versus commodity pressure.
Product Type:
Margin pools concentrate in multi-sensor configurations that bundle cardiovascular, metabolic, and recovery metrics into subscription-linked ecosystems.
- Smart Rings:Titanium or ceramic-encased devices integrating photoplethysmography, accelerometry, and skin temperature sensing for continuous biometric streaming. Demand concentrates in United States metropolitan health-tech corridors where employer-sponsored wellness programs specify HRV-grade accuracy in procurement tenders, driven by corporate benefits administrators seeking engagement metrics for preventative health investments.
- Heart Rate Monitoring Rings:Optical sensor-dense form factors optimized for cardiovascular metric extraction through multi-wavelength photoplethysmography. Procurement pulls from sports professionals and cardiac rehabilitation programs in Germany and Japan, constrained by algorithm validation timelines requiring polysomnography ground-truth studies before clinical credibility claims.
- Sleep Tracking Rings:Basic optical module configurations facing commoditization as component costs collapse. United States direct-to-consumer channels show price compression.
- Activity Monitoring Rings:Accelerometer-forward designs prioritizing step count and calorie estimation over cardiovascular depth. Volume concentrates in entry-level Asian markets.
- Oxygen Saturation Rings:SpO2-dedicated hardware vulnerable to regulatory reclassification as diagnostic devices. China's NMPA pathway clarity is accelerating compliant product registration.
The dominant share belongs to Smart Rings, while Heart Rate Monitoring Rings is closing the gap fastest.
Technology:
Cost tier stratification separates premium multi-sensor fusion from single-function commodity modules.
- Optical Sensors:Photodiode and LED arrays capturing cardiovascular signals through tissue perfusion analysis. Supply chain spillover from smartwatch manufacturing concentrates sourcing in Shenzhen and Taipei, exposing ring makers to allocation priority shifts when smartphone demand surges.
- Accelerometers:Three-axis motion detection enabling step counting, activity classification, and sleep-wake detection. Volume demand from basic fitness ring configurations in India and Brazil keeps unit economics favorable despite margin compression.
- Gyroscopes:Angular velocity sensing for movement precision and gesture recognition. Integration lags in finger-based form factors due to power draw constraints.
- Bluetooth Connectivity:Low Energy protocols enabling continuous data streaming to mobile health platforms without battery trade-offs. United States and European wellness app ecosystems drive specification requirements.
- NFC:Near-field communication modules for transit and retail wallet integration. Transit authority adoption in London, Tokyo, and Singapore is expanding addressable market beyond health-focused buyers.
- Haptic Feedback:Vibration motors for notification delivery and guided breathing interventions. Battery life penalties limit deployment to premium tier hardware.
Optical Sensors command the highest component spend per unit, while NFC integration is gaining share fastest among technology additions.
Application:
Customer type intensity separates clinical-adjacent use cases from casual wellness tracking.
- Personal Fitness:Individual consumers pursuing activity goals and recovery optimization through biometric feedback. United States metropolitan markets show strongest willingness to pay for subscription-linked hardware.
- Stress Management:HRV-guided breathing interventions and autonomic nervous system monitoring. Corporate wellness programs in Germany and Netherlands specify stress reduction ROI metrics in vendor selection.
- Sleep Quality Analysis:Sleep stage classification and circadian rhythm tracking. Algorithm accuracy claims face polysomnography validation requirements before clinical credibility.
- Weight Management:Metabolic rate estimation and caloric expenditure tracking tied to nutrition coaching platforms. Ultrahuman's metabolic score subscription model anchors this segment.
- Meditation Tracking:Mindfulness session quality metrics through physiological arousal detection. Niche demand from wellness center partnerships in California and British Columbia.
Personal Fitness retains the largest user base, while Stress Management is expanding most quickly through employer-sponsored benefits.
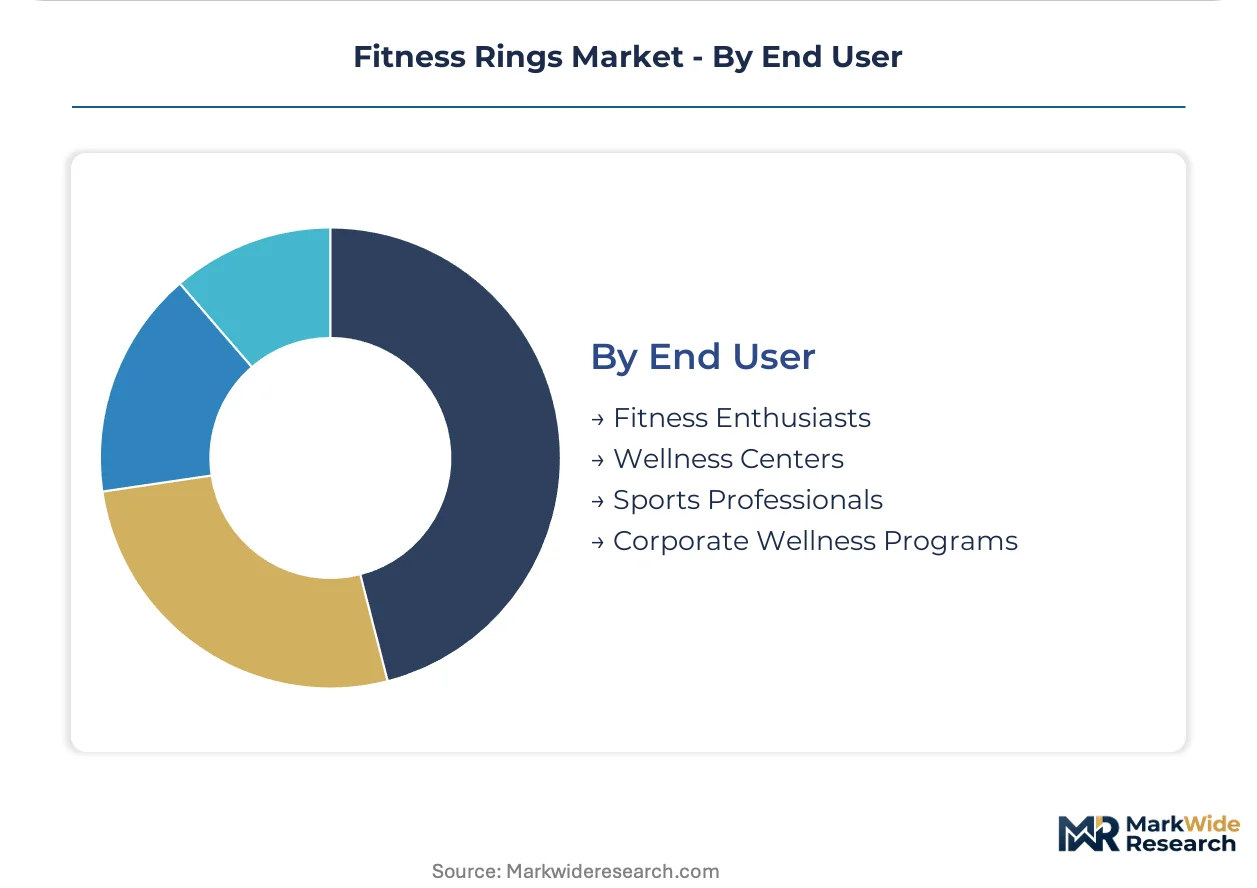
End User:
Procurement channel economics separate institutional buyers with recurring revenue potential from one-time consumer transactions.
- Fitness Enthusiasts:Early adopters and quantified-self practitioners driving premium hardware adoption. Direct-to-consumer concentration in United States coastal metropolitan areas.
- Wellness Centers:Spa and retreat operators integrating biometric feedback into guest experiences. European GDPR compliance requirements constrain cloud-dependent feature deployment.
- Sports Professionals:Teams and individual athletes requiring HRV-grade accuracy for training load management. Procurement specifications in Australia and United Kingdom mandate validated clinical pipelines.
- Corporate Wellness Programs:United States employers expanding preventative health benefits with biometric engagement incentives. Fastest-growing adoption vector with institutional procurement pull and subscription-anchored economics.
Corporate Wellness Programs capture the steepest expansion trajectory, while Fitness Enthusiasts maintain the installed base majority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States employers treat fitness rings as engagement infrastructure for preventative health benefits, while Chinese consumers prioritize clinical-grade optical validation and Japanese buyers demand polysomnography-correlated sleep accuracy.
United States
Corporate wellness programs in metropolitan health-tech corridors drive institutional procurement volumes. FDA clearance pathways for photoplethysmography-based devices shape clinical credibility claims and reimbursement positioning. Boston and San Francisco clusters concentrate algorithm development talent for HRV-grade accuracy specifications.
China
NMPA medical device classification clarity accelerates product registration timelines for optical heart rate wearables. Domestic consumers prioritize SpO2 monitoring functions that may face future diagnostic reclassification. Shenzhen anchors photodiode and LED component sourcing through smartwatch supply chain spillover.
Germany
CE marking under EU MDR tightens biocompatibility requirements for skin-contact titanium form factors. GDPR biometric data processing constraints raise cloud infrastructure overhead for health telemetry storage. Munich and Berlin wellness centers specify stress reduction ROI metrics in vendor procurement.
Japan
PMDA regulatory frameworks govern clinical-adjacent claims for cardiovascular metric extraction. Sports professionals mandate polysomnography ground-truth validation before sleep stage accuracy acceptance. Tokyo transit authority NFC integration expands addressable market beyond health-focused buyers.
United Kingdom
Corporate benefits administrators in London integrate biometric engagement metrics into preventative health investment decisions. MHRA convergence with EU MDR extends medical device compliance timelines for optical sensor wearables. Cambridge and Oxford clusters concentrate embedded systems firmware talent for multi-sensor fusion development.
Fitness Rings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that concentrates on single-function optical modules or regional subscription economics. The upper tier commands proprietary algorithm pipelines and backward integration into custom SoC design, while specialists compete on metabolic score tiering or NFC payment convergence. Strategic moves cluster around subscription-anchored hardware economics and FDA clearance pathway leverage for clinical credibility positioning.
Among Helsinki-based algorithm developers, Oura exemplifies the integrated leader archetype through proprietary sleep stage classification pipelines. Samsung Electronics Co., Ltd. anchors the scale-driven tier with captive semiconductor design capabilities. Ultrahuman occupies a position within the subscription-specialist vector, representing metabolic score tiering rather than device-margin economics.
| Leading Market Players |
|---|
| RingConn |
| Prevention Circul+ |
| Oura |
| Mirlray |
| UniJethro |
| Samsung |
| Amazfit |
| Herz |
| Ultrahuman |
| Others |
Supply & Pricing Matrix
Multi-wavelength photoplethysmography module substitution for basic single-channel optical designs is compressing component costs while redistributing manufacturing gravity toward Shenzhen and Taipei clusters where smartwatch supply chain spillover concentrates sourcing leverage.
Pricing Analysis
Long-term offtake contracts between ring manufacturers and optical component suppliers dominate procurement structures, though spot market purchases for accelerometer modules persist among smaller assemblers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical-grade devices from basic sleep-tracking configurations, with HRV-grade accuracy commanding substantial brand premiums. Pricing pressure stems from optical module commoditization as smartwatch manufacturing scales depress photodiode and LED costs. Corporate wellness programs in United States metropolitan corridors show lowest price sensitivity, while direct-to-consumer channels in Asian entry markets face acute margin compression.
Supply Chain Analysis
Inbound logistics costs from Shenzhen port congestion and transpacific container availability constraints are elevating landed costs for North American and European assembly facilities. Component sourcing draws from China for photodiode and LED arrays, Taiwan for Bluetooth Low Energy modules, and Finland for proprietary algorithm firmware development. Single-source vulnerability concentrates in optical sensor supply where smartwatch demand surges trigger allocation priority shifts. Distribution runs through employer-sponsored benefits administrators in United States health-tech corridors, direct-to-consumer e-commerce platforms, and wellness center partnerships in European metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as corporate wellness procurement specifications diverge from direct-to-consumer feature priorities, enabling specialized positioning across institutional and individual buyer archetypes.
For Market Incumbents: Secure proprietary algorithm validation pipelines through polysomnography ground-truth studies before competitors achieve clinical credibility parity. Deepen backward integration into custom SoC design to control power draw across optical sensor arrays, defending against Samsung's captive semiconductor capabilities. FDA clearance pathway investment represents the critical defensive lever against emerging entrants lacking regulatory infrastructure. For New Entrants and Emerging Players: Differentiate on metabolic score subscription tiering rather than device-margin economics, following Ultrahuman's hardware-anchored recurring revenue model. Target NFC payment convergence as the fastest-growing technology segment, exploiting transit authority adoption in London, Tokyo, and Singapore to bypass saturated health-tracking competition. Employer-sponsored distribution partnerships in United States corporate benefits administration offer the most penetrable channel architecture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wearable specialists possessing validated clinical pipelines but constrained subscription scale. Long-term viability across the projection horizon favors vendors with FDA-cleared photoplethysmography claims and backward integration into optical module sourcing. The signal to watch is NMPA medical device reclassification of continuous SpO2 monitoring as diagnostic function, which would trigger premarket submission requirements and reshape acquisition target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Clearance Pathway Investment | Photoplethysmography-based clinical credibility claims unlock reimbursement-adjacent positioning in United States employer-sponsored channels. |
| Subscription-Anchored Hardware Economics | Metabolic score and sleep coaching recurring revenue models decouple vendor profitability from collapsing optical module margins. |
| Multi-Sensor Fusion Firmware Development | Helsinki and Shenzhen talent concentration creates competitive moats around proprietary sleep stage classification algorithms. |
| NFC Payment Module Integration | Transit authority adoption in Asian and European metropolitan markets expands addressable market beyond health-focused buyer segments. |
| GDPR-Compliant Cloud Architecture Restructuring | Regional biometric data isolation reduces operational overhead for European vendor compliance under EU MDR and data processing requirements. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with wearable device engineering leads, corporate benefits administrators, biomedical firmware developers, and optical component procurement specialists; and secondary validation through FDA 510(k) filings, NMPA medical device registration databases, EU MDR CE marking documentation, and smartwatch supply chain trade data. Bottom-up unit economics modeling triangulated against top-down market sizing from employer wellness program expenditure disclosures and health insurer incentive program budgets.
Across the analysis window, the forecasting framework segmented volume and value outputs by hardware specification tier, biometric capture technology depth, procurement channel economics, and regional regulatory cluster. CAGRs derived from optical sensor cost compression curves, corporate wellness program adoption velocity, and subscription retention benchmarks modeled through the projection horizon. Algorithm validation timeline assumptions and SpO2 reclassification probability scenarios informed scenario-weighted outputs.
The analysis sits within stated boundaries; outcomes outside sustained Bluetooth Low Energy protocol standardization, stable NMPA pathway clarity, or continued employer-sponsored wellness program expansion would require recalibration. Forecasts reflect documented assumptions regarding optical module cost trajectories and regulatory classification stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
Exercise Resistance Bands Market
Fitness Equipment
South Africa Gym Accessories Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Middle East and Africa Fitness Equipment Market
Fitness Equipment
Treadmill Desks Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
Yoga and Pilates Mats Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Gymnastic Springboard Market
Fitness Equipment
Asia-Pacific Fitness Equipment Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
Push-Up Board Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Fitness Ball Market