
 Belt Trainers Market | 2026-2036
Belt Trainers Market Size, Share, and Industry Trends Forecast 2026-2036
Belt Trainers Market Insights
Heavy-duty specification tiers is rotating toward the center of procurement decisions in bulk material handling. Gates Corporation leverages polymer science expertise to dominate high-temperature conveyor applications. Continental anchors European supply through integrated manufacturing of sensor-enabled belt trainers. Fenner Drives specializes in modular polyurethane designs that compete on rapid installation cycles.
Belt trainers are mechanical devices that maintain conveyor belt alignment through pivoting frames, guide rollers, and tensioning mechanisms typically constructed from steel housings with rubber or urethane contact surfaces. Their primary industrial purpose centers on preventing belt drift, spillage, and premature edge wear in continuous material transport systems. Neoprene and mesh product types lead current volume shipments due to chemical resistance and breathability requirements in food processing and aggregate sectors. Posture correction and back support use cases command premium positioning among rehabilitation patients and fitness enthusiasts, while workout enhancement segments show faster growth trajectory in gym and fitness center distribution channels.
OSHA workplace safety directives and MSHA conveyor belt fire prevention standards shape North American demand for flame-resistant belt trainer materials and automated monitoring integration. ISO 14890 and DIN 22102 conveyor belt specifications govern European product certification requirements, with CE marking serving as mandatory market access gate. Stakeholders must monitor evolving EU machinery safety regulations and assess sensor fusion capabilities before committing to next-generation belt tracking platforms.
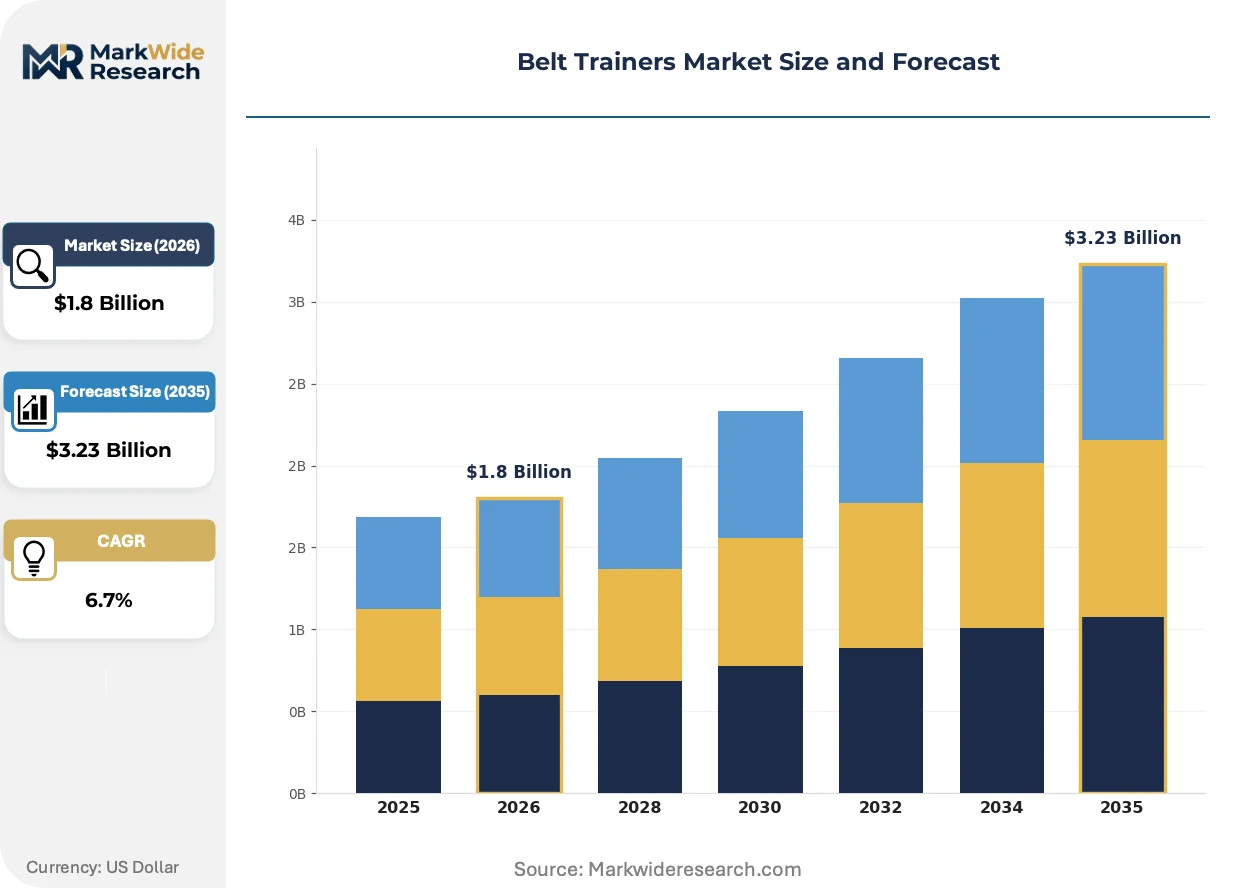
Market Dynamics
Heavy-duty belt trainer procurement is rotating around predictive maintenance integration as mining operators in Australia and bulk handlers in Germany demand sensor-enabled alignment systems that preempt drift failures before material spillage occurs.
Growth Catalysts
- MSHA conveyor belt fire prevention standards:Underground coal operations in the United States must install flame-resistant tracking systems, creating mandatory replacement cycles for legacy mechanical trainers.
- Polymer science advances:High-temperature urethane formulations now withstand continuous exposure above 150°C in cement kiln applications, opening specification tiers previously reserved for steel-on-steel designs.
- Australian iron ore corridor:Pilbara mining hubs operate 24/7 conveying systems exceeding 20 kilometers, where automated belt tracking reduces unplanned downtime worth millions per hour.
Market Restraints
- Steel input cost volatility:Pivoting frame housings and guide roller shafts depend on hot-rolled coil pricing, which fluctuates with energy costs and scrap availability.
- Specialized urethane supplier concentration:Castable polyurethane formulations for high-abrasion contact surfaces source from a limited German and Italian chemical compounder base.
- Legacy mechanical compatibility:Retrofitting sensor-enabled trainers onto 1980s-era conveyor structures requires custom fabrication, slowing upgrade adoption.
Strategic Opportunities
- India's cement sector expansion:UltraTech Cement and Ambuja Cements are commissioning greenfield clinker lines where integrated belt tracking specification occurs at design stage.
- EU machinery safety regulation updates:The 2023 Machinery Regulation mandates self-monitoring capabilities, creating compliance-driven demand for smart trainer retrofits.
- Industrial IoT convergence:Belt trainer vibration signatures fused with edge computing enable condition-based maintenance contracts, shifting revenue from hardware to service.
Industry Challenges
- Conveyor systems integration complexity:Multi-vendor PLC environments in brownfield plants resist standardized sensor communication protocols.
- ATEX certification timelines:Explosion-proof belt trainer variants for grain handling and petrochemical applications face 12-18 month approval queues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belt Trainers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex, Neoprene, Mesh, Cotton, Elastic Use Case: Posture Correction, Waist Shaping, Workout Enhancement, Back Support, Weight Loss Customer Type: Fitness Enthusiasts, Athletes, Rehabilitation Patients, Bodybuilders, Dancers Distribution Channel: Online Retailers, Specialty Stores, Gyms & Fitness Centers, Department Stores, Sports Clinics |
| Companies Covered | Gates Corporation, Continental, Habasit, Ammeraal Beltech, Fenner Drives, Nitta Corporation, Bando Chemical Industries, Forbo Holding, Dayco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belt Trainers Market Trends and Innovations
Digital twin technology and material science advances are restructuring how belt trainers are specified, procured, and maintained across heavy industry verticals.
Sensor fusion architectures are decomposing the traditional split between mechanical alignment and electronic monitoring. Mining operators in Western Australia now deploy accelerometer-equipped guide rollers that stream vibration data to centralized SCADA systems. This convergence is decomposing the historical two-step procurement pattern where mechanical and electronic systems sourced separately.
REACH substance restrictions on isocyanates and heavy metal catalysts are forcing reformulation of cast polyurethane contact surfaces. European compounders now supply bio-based prepolymer alternatives that meet DIN 22102 abrasion standards. Food processing and pharmaceutical conveying applications in Germany and the Netherlands are adopting these certified materials fastest.
Lifecycle service contracts are displacing transactional equipment sales in North American bulk terminals. Operators at Port of Long Beach and Vancouver's Neptune Terminals now pay per aligned ton rather than capitalizing trainer hardware. This model concentrates vendor relationships with firms offering remote diagnostics and rapid response field teams.
Belt Trainers Market Segmentation
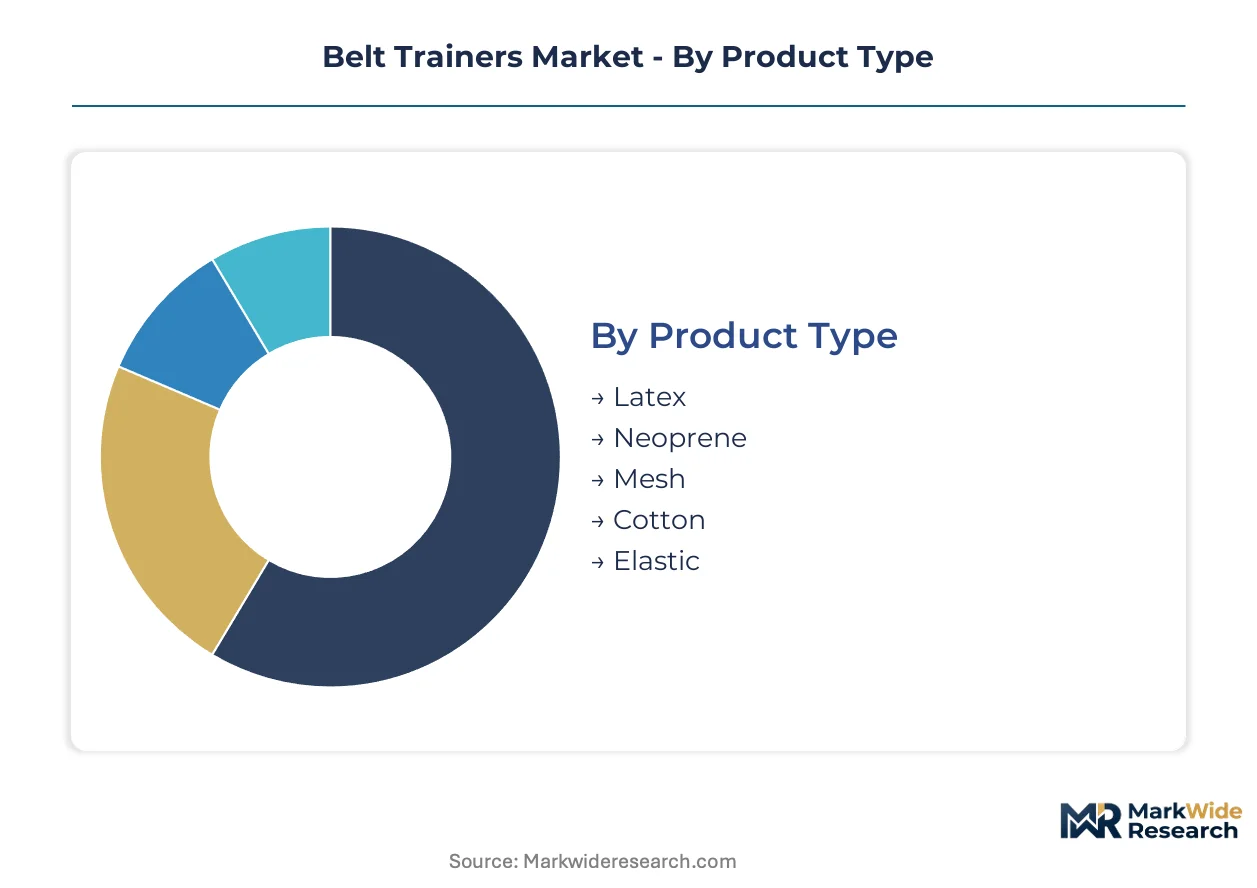
Belt trainer procurement patterns diverge sharply across material specifications, end-use applications, and channel structures. Regulatory frameworks governing workplace safety, medical device classification, and consumer product standards create distinct compliance burdens that reshape segment prioritization for manufacturers and distributors.
Product Type:
REACH substance restrictions and FDA medical device classifications split material specifications into regulated tiers with divergent certification costs.
- Neoprene:Synthetic rubber polymer construction delivers thermal retention and compression stability for therapeutic and athletic applications. Australian mining operations and German industrial facilities specify neoprene belt trainers for chemical resistance in aggregate handling and food processing environments where DIN 22102 abrasion standards apply.
- Mesh:Breathable woven synthetic fabric engineered for moisture wicking and extended wear comfort. Posture correction and back support use cases in rehabilitation clinics across the United States concentrate demand here, driven by OSHA workplace accommodation mandates and patient compliance requirements.
- Latex:Natural rubber elastic compounds offering maximum compression resistance and shape retention.
- Cotton:Natural fiber construction prioritizing skin contact comfort and hypoallergenic properties for extended daily wear.
- Elastic:Blended synthetic-nylon weave providing graduated compression adjustability across fitness and medical applications.
Established volume favors neoprene; emerging adoption favors mesh.
Use Case:
Medical reimbursement codes and fitness industry certification programs create divergent margin structures across therapeutic versus performance positioning.
- Posture Correction:Biomechanical support systems targeting spinal alignment and ergonomic positioning for seated or standing workstations. Rehabilitation patients in Germany and the Netherlands drive specification here, with physiotherapy clinics prescribing certified devices under EU medical device regulations.
- Workout Enhancement:Compression and thermal retention designs targeting core activation and sweat management during resistance training. Gyms and fitness centers in Australia and the United States stock these for member retention and ancillary revenue, with faster inventory turns than therapeutic categories.
- Waist Shaping:Aesthetic compression garments designed for temporary silhouette modification under clothing.
- Back Support:Rigid or semi-rigid structural reinforcement for occupational lifting and chronic pain management.
- Weight Loss:Thermal and compression systems marketed for localized perspiration and temporary water weight reduction.
Therapeutic positioning commands price premiums; performance segments expand most quickly through gym channel penetration.
Customer Type:
Professional credential requirements and insurance reimbursement eligibility stratify purchasing authority and specification complexity.
- Rehabilitation Patients:Post-surgical and chronic condition populations with physician-prescribed therapeutic protocols. United States demand concentrates here through Medicare and private insurance coverage for lumbar support devices meeting FDA Class I medical device standards.
- Fitness Enthusiasts:Recreational exercisers purchasing through discretionary channels without professional prescription. Australian and German gym memberships drive volume, with lower per-unit spending but higher purchase frequency than medical segments.
- Athletes:Competitive sport participants with coach or trainer-influenced equipment decisions.
- Bodybuilders:Resistance training specialists prioritizing core stability and competition-stage presentation.
- Dancers:Performing artists requiring flexibility-compatible support for rehearsal and performance.
Medical authorization stabilizes rehabilitation demand; fitness self-selection creates higher volatility but steeper expansion trajectory.
Distribution Channel:
Channel concentration reflects regulatory compliance burden and customer education requirements for proper fitting and therapeutic use.
- Specialty Stores:Dedicated orthopedic and medical supply retailers with certified fitting staff and insurance billing capabilities. German statutory health insurance reimbursement flows predominantly through this channel, creating defensible positioning against price competition.
- Online Retailers:Direct-to-consumer platforms capturing fitness-oriented segments with lower compliance overhead. United States and Australian consumers increasingly self-direct purchases here for workout enhancement categories, bypassing professional consultation.
- Gyms & Fitness Centers:Facility-based retail with impulse purchase dynamics and trainer endorsement influence.
- Department Stores:Mass retail presence emphasizing waist shaping and aesthetic positioning over therapeutic claims.
- Sports Clinics:Professional athletic facilities with integrated equipment dispensing and injury prevention protocols.
Professional channel concentration protects medical-grade margins; digital direct-to-consumer routes gain share fastest in discretionary fitness segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Australia exhibit low price sensitivity for sensor-enabled belt trainers, while procurement teams in India and Brazil prioritize cost-optimized mechanical designs. This elasticity divergence shapes vendor pricing strategies across geographies.
United States
Underground coal mining in Appalachia and bulk material terminals along the Gulf Coast drive specification of flame-resistant belt trainers. MSHA conveyor belt fire prevention standards mandate automated tracking systems in active mine operations, creating replacement demand cycles. Pittsburgh-based mining equipment distributors and Houston petrochemical clusters concentrate procurement authority for heavy-duty specifications.
Germany
Industrial manufacturing corridors in North Rhine-Westphalia and Bavaria specify sensor-integrated belt trainers for automotive and chemical processing lines. The 2023 EU Machinery Regulation mandates self-monitoring capabilities, accelerating retrofit demand across legacy installations. Cologne and Stuttgart engineering clusters anchor specification authority for DIN 22102-certified abrasion-resistant designs.
Australia
Pilbara iron ore operations and Queensland coal export terminals operate 24/7 conveying systems exceeding 20 kilometers in length. Automated belt tracking systems reduce unplanned downtime worth millions per hour, justifying premium procurement. Perth engineering offices and Port Hedland logistics hubs concentrate demand for predictive maintenance-integrated trainers.
India
UltraTech Cement and Ambuja Cements commission greenfield clinker lines where belt tracking specification occurs at design stage. BIS certification requirements and the PLI scheme for manufacturing equipment shape local sourcing decisions. Gujarat and Rajasthan cement clusters drive volume demand for cost-optimized mechanical trainers.
China
Steel mills in Hebei Province and coal handling ports in Tianjin specify heavy-duty belt trainers for high-tonnage material transport. GB standards for conveyor safety and MIIT industrial automation directives accelerate sensor-enabled adoption. Yangtze River Delta equipment distributors concentrate procurement for integrated mechanical-electronic systems.
Belt Trainers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the belt trainers market. The vendor base organizes into three tiers: integrated multinational conglomerates with polymer science capabilities, specialized conveyor component manufacturers, and regional fabrication houses serving price-sensitive bulk material sectors. Strategic differentiation concentrates on sensor fusion integration versus mechanical reliability optimization. Competitive moves cluster around backward integration into urethane formulation and geographic expansion through distribution partnerships.
Within the integrated multinational tier, Gates Corporation and Continental exemplify technology-forward positioning through captive polymer science expertise. Fenner Drives occupies a specialist position in modular polyurethane architectures. These three anchors represent divergent strategic bets: Gates Corporation leverages high-temperature material science, Continental anchors European supply through sensor-enabled manufacturing integration, and Fenner Drives competes on installation cycle velocity. Regional fabrication houses in China and India sit within a separate cost-optimization tier, supplying mechanical-only designs to cement and aggregate sectors.
| Leading Market Players |
|---|
| Gates Corporation |
| Continental |
| Habasit |
| Ammeraal Beltech |
| Fenner Drives |
| Nitta Corporation |
| Bando Chemical Industries |
| Forbo Holding |
| Dayco |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for castable polyurethane formulations concentrate pricing power with German and Italian compounders serving high-abrasion belt trainer specifications. Inventory buffers for hot-rolled coil pivot frames fluctuate with energy cost volatility, forcing buyers into longer-term offtake commitments to secure mechanical housing supply.
Pricing Analysis
Aftermarket service contracts and condition-based maintenance agreements now generate the majority of lifetime value across sensor-enabled belt trainer deployments. Three-tier pricing structure across premium, standard, and economy levels separates DIN 22102-certified European designs from BIS-compliant Indian mechanical units and unbranded Chinese fabrication. Price differentiation rests on certification grade and predictive maintenance integration. Cost compression in economy mechanical tiers is intensifying because cement sector procurement teams in India and Brazil prioritize capex minimization over lifecycle optimization. Mining operators in Australia exhibit lowest price sensitivity, while aggregate handlers in emerging markets demonstrate highest elasticity.
Supply Chain Analysis
Inventory positioning for high-temperature urethane prepolymers runs through 45-60 day cycles, exposing downstream fabricators to formulation availability constraints. Supply concentration centers on Germany, Italy, and China for cast polyurethane contact surfaces, with hot-rolled coil mechanical housings sourcing from integrated steel mills in China, India, and the United States. Raw material dependencies include isocyanate chemical feedstocks, abrasion-resistant polymer additives, and precision-machined roller bearings. Single-source vulnerability in specialized urethane compounder networks creates procurement risk for flame-resistant and food-grade specifications. Distribution runs through mining equipment distributors in Australia, industrial automation integrators in Germany, and direct OEM relationships in North American bulk terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory certification entrenchment and installed-base switching costs protect incumbent positioning against price-based disruption.
For Market Incumbents: Consolidate backward integration into urethane formulation capabilities to secure supply of high-temperature contact surfaces currently concentrated among German and Italian compounders. Deepen sensor fusion R&D partnerships with Australian mining operators to embed predictive maintenance protocols that raise switching costs for retrofit replacements. Capacity expansion in Gujarat and Rajasthan cement clusters captures greenfield specification opportunities before cost-optimized mechanical competitors establish relationships. For New Entrants and Emerging Players: Remote diagnostics service gaps in North American bulk terminals present white-space entry points where incumbent vendors under-invest in rapid-response field teams. Target India's cement sector expansion through design-stage integration partnerships with UltraTech Cement and Ambuja Cements, bypassing established aftermarket relationships. Position through lifecycle service contracts rather than transactional hardware sales to differentiate from regional fabrication houses. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because MSHA, OSHA, and EU Machinery Regulation mandates create replacement-cycle visibility independent of commodity demand cycles. Acquisition candidates with ATEX certification capabilities and established Australian mining relationships command strategic premiums. Monitor EU machinery safety regulation enforcement timelines as inflection indicators for smart trainer retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Urethane Formulation | Captive supply of high-temperature contact surfaces reduces dependency on German and Italian compounders. |
| Sensor Fusion Platform Development | Accelerometer-equipped guide rollers streaming to SCADA systems enable condition-based maintenance contracts. |
| ATEX Certification Investment | Explosion-proof variants for grain handling and petrochemical applications face 12-18 month approval queues. |
| Lifecycle Service Contract Expansion | Port of Long Beach and Vancouver's Neptune Terminals now pay per aligned ton rather than capitalizing hardware. |
| Greenfield Design-Stage Partnerships | UltraTech Cement and Ambuja Cements commission integrated belt tracking specification at project inception. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at Pilbara iron ore operations, plant engineers at German automotive manufacturing facilities, procurement leads at North American bulk terminals, and aftermarket service heads at conveyor system OEMs, and refined through secondary validation against MSHA enforcement data, EU Machinery Regulation compliance filings, DIN 22102 certification registries, and customs trade records for polyurethane chemical imports. Bottom-up demand modeling triangulated with top-down market sizing across product type, use case, and regional regulatory clusters.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation dimensions covering material specification tiers, end-use application requirements, and customer procurement authority structures. CAGRs were derived from regression analysis of historical replacement cycles and regulatory mandate implementation timelines. Industry-specific forecast inputs include Australian mining production schedules, Indian cement capacity expansion announcements, and EU machinery safety retrofit compliance deadlines.
Underlying assumptions cover MSHA enforcement continuity, REACH substance restriction stability, and steel input cost normalization, with deviation risk concentrated in ATEX certification timeline extensions and polymer science formulation disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Exercise Resistance Bands Market
Fitness Equipment
GCC Fitness Ring Market
Fitness Equipment
Fitness Rings Market
Fitness Equipment
Yoga Equipment Market
Fitness Equipment
Yoga and Exercise Mats Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
Home Fitness Equipment Market
Fitness Equipment
Middle East and Africa Fitness Equipment Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Yoga and Pilates Mats Market
Fitness Equipment
South Africa Gym Accessories Market
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
China Outdoor Fitness Equipment Market