
 US Fitness Rings Market | 2026-2036
US Fitness Rings Market Size, Share, and Industry Trends Forecast 2026-2036
US Fitness Rings Market Insights
Direct-to-consumer e-commerce is reconfiguring how fitness rings reach buyers, bypassing traditional electronics retail and enabling subscription-based health analytics bundling. Oura Health Oy leverages its app ecosystem to sustain recurring revenue beyond hardware sales. Samsung Electronics Co. Ltd. anchors its ring strategy within a broader Galaxy wearable portfolio. Movano Health differentiates through FDA-focused clinical validation pathways.
US fitness rings are titanium or stainless steel wearable devices housing photoplethysmography sensors, accelerometers, and temperature monitors to track heart rate variability, sleep stages, and activity metrics. Bluetooth-enabled smart rings lead volume shipments, while health monitors command premium pricing through clinical-grade sensor arrays. Titanium material segments attract athletic end users seeking durability without skin irritation. Sleep tracking technology is expanding fastest among health-conscious individuals managing chronic conditions.
FDA regulates pulse oximetry and heart rate claims as medical device functions, compelling manufacturers to pursue 510(k) clearance or de novo classification for advanced health metrics. FCC governs wireless transmission standards for Bluetooth and NFC connectivity in these wearables. Stakeholders must monitor whether FDA expands software-as-medical-device oversight to algorithm-derived health scores, as this would reshape product development timelines and competitive barriers.
Market Dynamics
FDA's tightening 510(k) validation requirements for pulse oximetry and heart rate monitoring are forcing manufacturers to restructure clinical trial timelines and sensor calibration protocols. This regulatory pressure is compressing product development cycles while elevating barriers for new entrants lacking established medical device expertise.
Growth Catalysts
- Corporate wellness mandates:Large technology employers in California and Texas are expanding subsidized wearable programs. These initiatives normalize continuous health monitoring among professional demographics with disposable income.
- Photoplethysmography sensor miniaturization:Advances in optical sensing technology enable clinical-grade metrics within titanium form factors. Athletic end users now access laboratory-comparable heart rate variability data during competition.
- Bluetooth Low Energy 5.3:The updated wireless standard extends battery life beyond seven days while maintaining real-time data synchronization. FCC certification of this protocol supports seamless integration with existing smartphone ecosystems.
Market Restraints
- Titanium supply concentration:Aerospace and medical device industries compete for limited domestic titanium processing capacity. Raw material costs fluctuate with defense procurement cycles and geopolitical trade restrictions.
- FDA software-as-medical-device ambiguity:Unclear classification boundaries for algorithm-derived health scores create regulatory friction. Manufacturers face unpredictable review timelines when submitting products with machine-learning components.
- Smartwatch substitution threat:Multi-function wrist-worn devices from Apple and Garmin capture overlapping health metrics at comparable price points. Consumers prioritizing display interfaces and third-party app ecosystems bypass ring form factors entirely.
Strategic Opportunities
- Chronic condition management:Sleep apnea and cardiovascular disease patients in Texas represent an underpenetrated clinical population. Partnerships with regional health systems could establish rings as reimbursable remote monitoring tools.
- Subscription health analytics bundling:Direct-to-consumer channels enable recurring revenue beyond hardware margins. Personalized coaching and longitudinal trend analysis transform single purchases into ongoing relationships.
- De novo FDA pathway expansion:Novel sensor arrays for blood glucose correlation or hydration monitoring qualify for streamlined clearance. First-movers securing de novo classification gain competitive moats through predicate device exclusivity.
Industry Challenges
- Biomedical engineering talent scarcity:Photoplethysmography algorithm development requires specialized expertise spanning optical physics and signal processing. Universities produce fewer graduates than device manufacturers require.
- Clinical validation timeline compression:FDA demands larger cohort sizes for 510(k) submissions involving novel biomarkers. Capital requirements for pivotal trials strain mid-tier companies without pharmaceutical partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Fitness Rings Market |
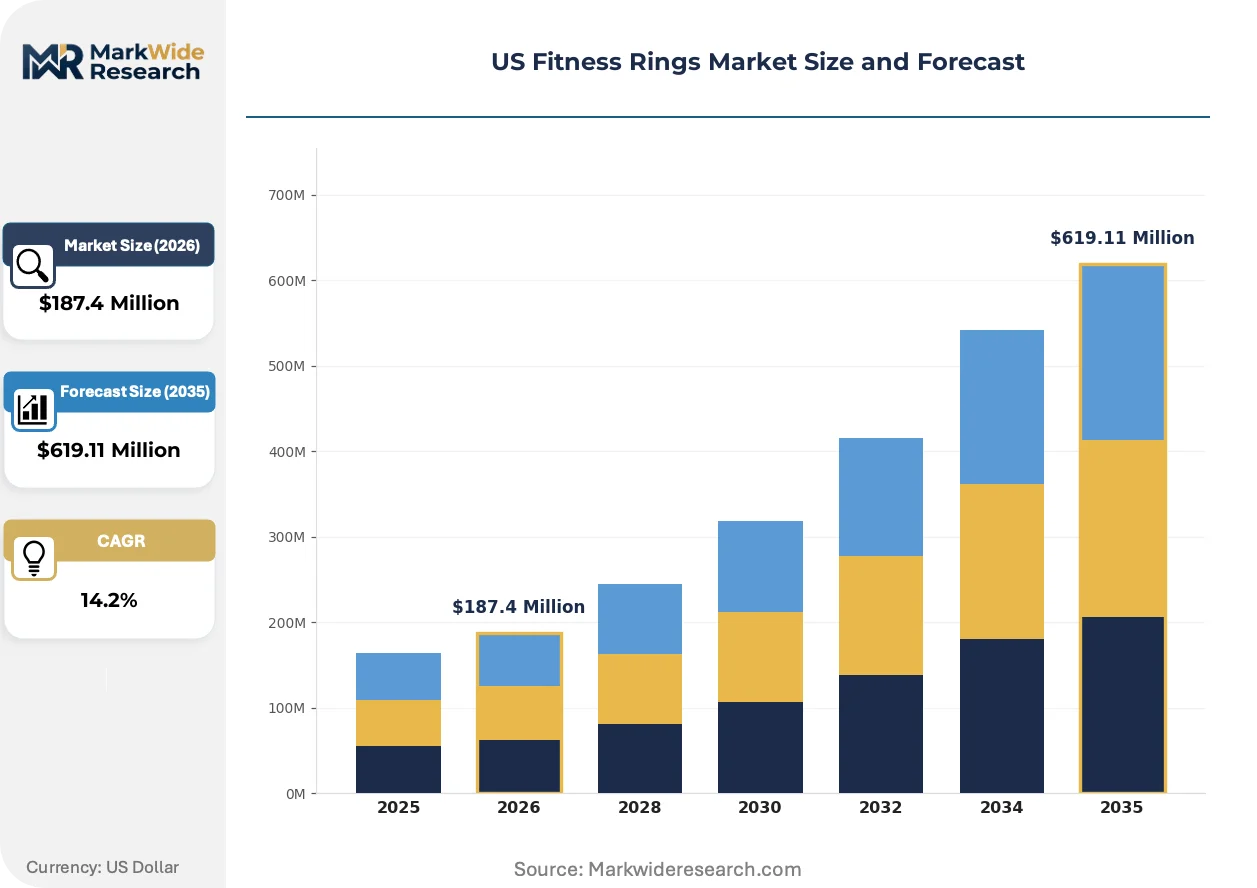
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Rings, Activity Trackers, Health Monitors, Wellness Devices End User: Fitness Enthusiasts, Athletes, Casual Users, Health-Conscious Individuals Material: Stainless Steel, Titanium, Silicone, Plastic Technology: Bluetooth, NFC, Heart Rate Monitoring, Sleep Tracking |
| Companies Covered | Oura Health Oy, Motiv Inc., Samsung Electronics Co. Ltd., Ultrahuman Healthcare Pvt. Ltd., RingConn Technology Co. Ltd., Circular Ring, Movano Health, Zepp Health Corporation, Fitbit Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Fitness Rings Market Trends and Innovations
Sensor fusion architectures are redefining what compact wearables can measure, merging optical, thermal, and inertial data streams into unified health assessments. This convergence is expanding addressable use cases beyond fitness into clinical monitoring and pharmaceutical trial endpoints.
Multi-wavelength photoplethysmography is hybridizing arterial oxygen saturation detection with peripheral perfusion indexing. Sleep medicine clinics in California are adopting these systems for home-based polysomnography alternatives. The technology is compressing diagnostic timelines while reducing overnight facility occupancy costs.
FDA's draft guidance on clinical decision support software is reshaping how algorithm-derived scores reach consumers. Manufacturers must now document clinical validation for any metric implying diagnostic relevance. Products targeting cardiovascular risk stratification face the steepest compliance burden under this framework.
Employer-sponsored wellness programs are displacing individual purchase decisions as the primary demand channel. Human resources departments negotiate bulk contracts with analytics bundling. Texas-based energy and technology corporations represent the most aggressive adopters of this procurement model.
US Fitness Rings Market Segmentation
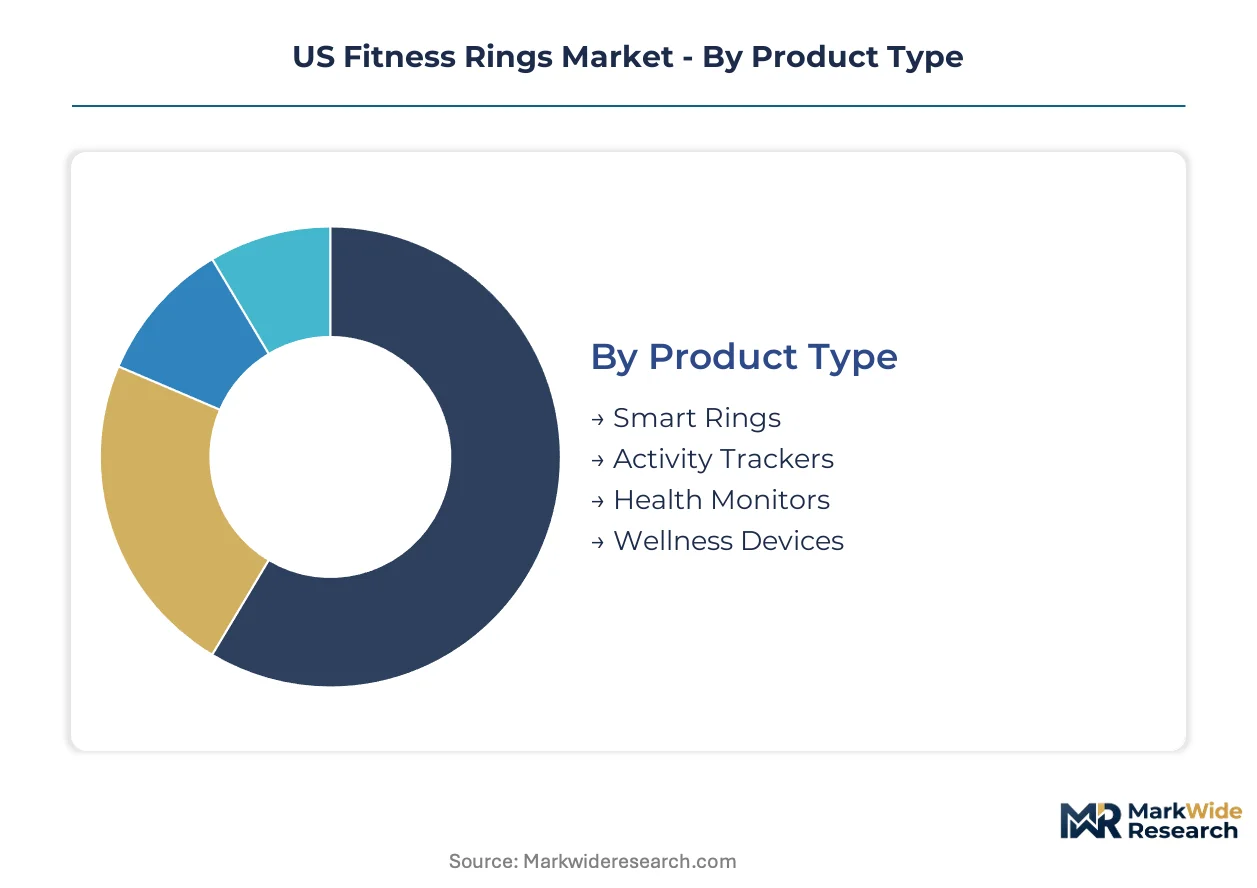
Segmentation in the US fitness rings market reveals how hardware specifications, user profiles, and connectivity standards intersect to determine pricing power and replacement cycles. Each dimension carries distinct after-sales-service implications that reshape manufacturer margin structures.
Product Type:
After-sales-service intensity varies sharply across product categories, with clinical-grade devices requiring calibration support and wellness-focused hardware demanding minimal technical intervention.
- Smart Rings:Bluetooth-enabled titanium housings integrate accelerometers and temperature sensors for continuous biometric streaming. Demand concentrates among California tech-sector employees accessing employer-subsidized wellness programs, where seamless smartphone synchronization drives procurement decisions. Firmware update dependencies and app ecosystem compatibility create ongoing service obligations.
- Health Monitors:Photoplethysmography arrays with FDA-cleared pulse oximetry command premium positioning through clinical-grade validation. Texas cardiovascular patients and sleep apnea clinics represent the fastest-expanding user base, with reimbursement pathways from regional health systems accelerating adoption.
- Activity Trackers:Simplified sensor packages prioritize step counting and calorie estimation.
- Wellness Devices:Stress monitoring and mindfulness coaching features target casual health optimization.
Health Monitors holds the largest share; momentum sits with Smart Rings.
End User:
Cost tier stratification separates clinical reimbursement pathways from discretionary consumer purchases, with enterprise procurement displacing individual decision-making in the highest-volume segment.
- Fitness Enthusiasts:Power users demand heart rate variability precision and recovery analytics for training optimization. Metropolitan Austin and Dallas fitness communities show dense adoption, with CrossFit and endurance-sport participation correlating with willingness to pay premium hardware prices.
- Athletes:Competitive performers require laboratory-comparable biometric accuracy during competition. NCAA programs and professional sports franchises in Texas evaluate rings for load management and injury prevention, with durability specifications driving titanium material selection.
- Casual Users:Step counting and basic sleep duration tracking satisfy minimal engagement profiles.
- Health-Conscious Individuals:Chronic condition self-management motivates clinical-feature adoption.
Fitness Enthusiasts dominates volume; Athletes commands the steepest expansion trajectory.
Material:
Supply concentration in domestic titanium processing creates cost volatility that propagates through finished-product pricing, with aerospace and medical device competition for limited capacity.
- Titanium:Aerospace-grade alloys deliver strength-to-weight ratios and hypoallergenic properties essential for 24/7 wear. Athletic end users in humid coastal California markets prioritize corrosion resistance and skin compatibility during intensive training regimens.
- Stainless Steel:Surgical-grade 316L variants balance durability with manufacturing scalability. Midwest manufacturing clusters source from domestic steel producers, with price sensitivity among casual users sustaining this segment's volume position.
- Silicone:Flexible housings accommodate sizing adjustments and impact absorption.
- Plastic:Entry-level positioning serves price-conscious trial adopters.
Stainless Steel retains the largest installed base; Titanium gains share fastest.
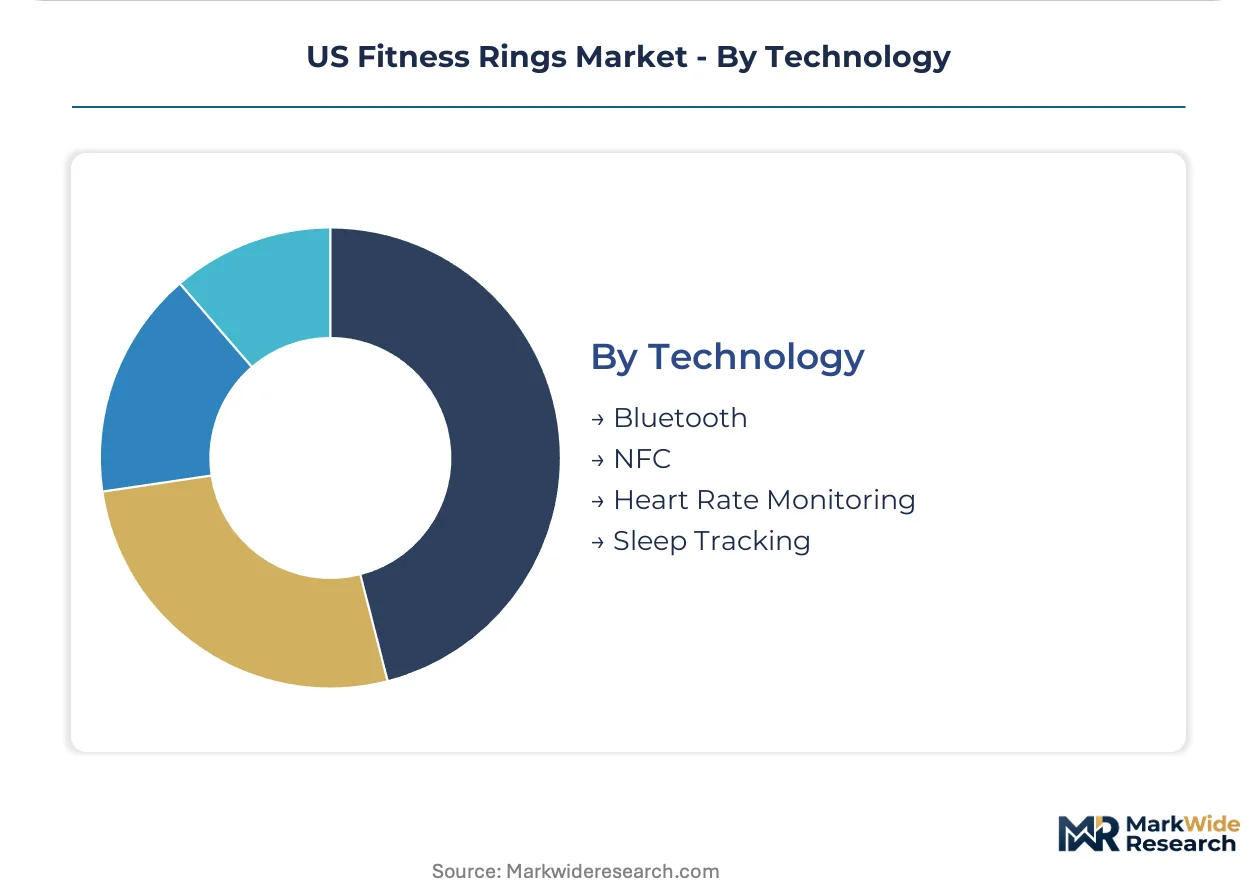
Technology:
Margin structure correlates with sensor complexity, with multi-wavelength photoplethysmography arrays extracting premium pricing through clinical validation investments.
- Heart Rate Monitoring:Multi-wavelength photoplethysmography enables continuous cardiovascular assessment with laboratory-grade precision. Sleep medicine clinics in California deploy these systems for home-based polysomnography alternatives, compressing diagnostic timelines while reducing facility occupancy costs.
- Sleep Tracking:Actigraphy fusion with peripheral oxygen saturation monitoring addresses the fastest-expanding use case. Health-conscious individuals managing chronic conditions in Texas represent the primary demand concentration, with longitudinal trend analysis driving subscription attach rates.
- Bluetooth:Low Energy 5.3 standardization enables week-long battery life.
- NFC:Contactless payment and access control integration differentiates lifestyle positioning.
Heart Rate Monitoring captures the largest revenue pool; Sleep Tracking expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA jurisdiction over pulse oximetry and heart rate claims shapes commercialization timelines across US sub-regions, with state-level health system partnerships determining reimbursement pathways for clinical-grade devices.
California
Tech-sector wellness subsidies from San Francisco Bay Area employers drive dense adoption of Bluetooth-enabled titanium rings. Stanford Health Care and Kaiser Permanente pilot remote patient monitoring programs using photoplethysmography-validated devices. Los Angeles and San Diego fitness communities sustain demand for athletic-grade heart rate variability tracking.
Texas
Energy and technology corporations in Houston and Dallas-Fort Worth negotiate bulk procurement contracts with analytics bundling. Texas Medical Center institutions evaluate ring-based sleep apnea screening for home-based polysomnography alternatives. Austin's endurance-sport culture commands premium positioning for laboratory-comparable biometric accuracy.
New York Metro
Corporate headquarters concentration in Manhattan drives employer-sponsored wearable programs among financial services and media employers. NewYork-Presbyterian and Mount Sinai health systems explore chronic condition management integrations. Brooklyn and Queens manufacturing clusters supply stainless steel components for mid-tier product lines.
Greater Boston
Academic medical centers including Mass General Brigham and Beth Israel Deaconess conduct clinical validation studies for FDA 510(k) submissions. MIT and Harvard research ecosystems spawn photoplethysmography algorithm startups. Route 128 technology corridor employers subsidize wellness device purchases for knowledge workers.
Pacific Northwest
Seattle and Portland metro areas combine tech-sector employment density with outdoor recreation culture favoring durable titanium form factors. Amazon and Microsoft corporate wellness programs normalize continuous health monitoring among professional demographics. Providence St. Joseph Health pilots cardiovascular risk stratification programs using multi-wavelength sensor arrays.
US Fitness Rings Market Competitive Landscape
Platform-anchored wearable ecosystems and FDA-focused clinical validation specialists split the market between lifestyle positioning and medical-grade credibility. The vendor base concentrates around three strategic archetypes: diversified consumer electronics conglomerates, pure-play health analytics platforms, and clinical device startups pursuing de novo clearance. Dominant competitive moves include subscription service bundling to extend customer lifetime value and strategic partnerships with regional health systems to secure reimbursement codes.
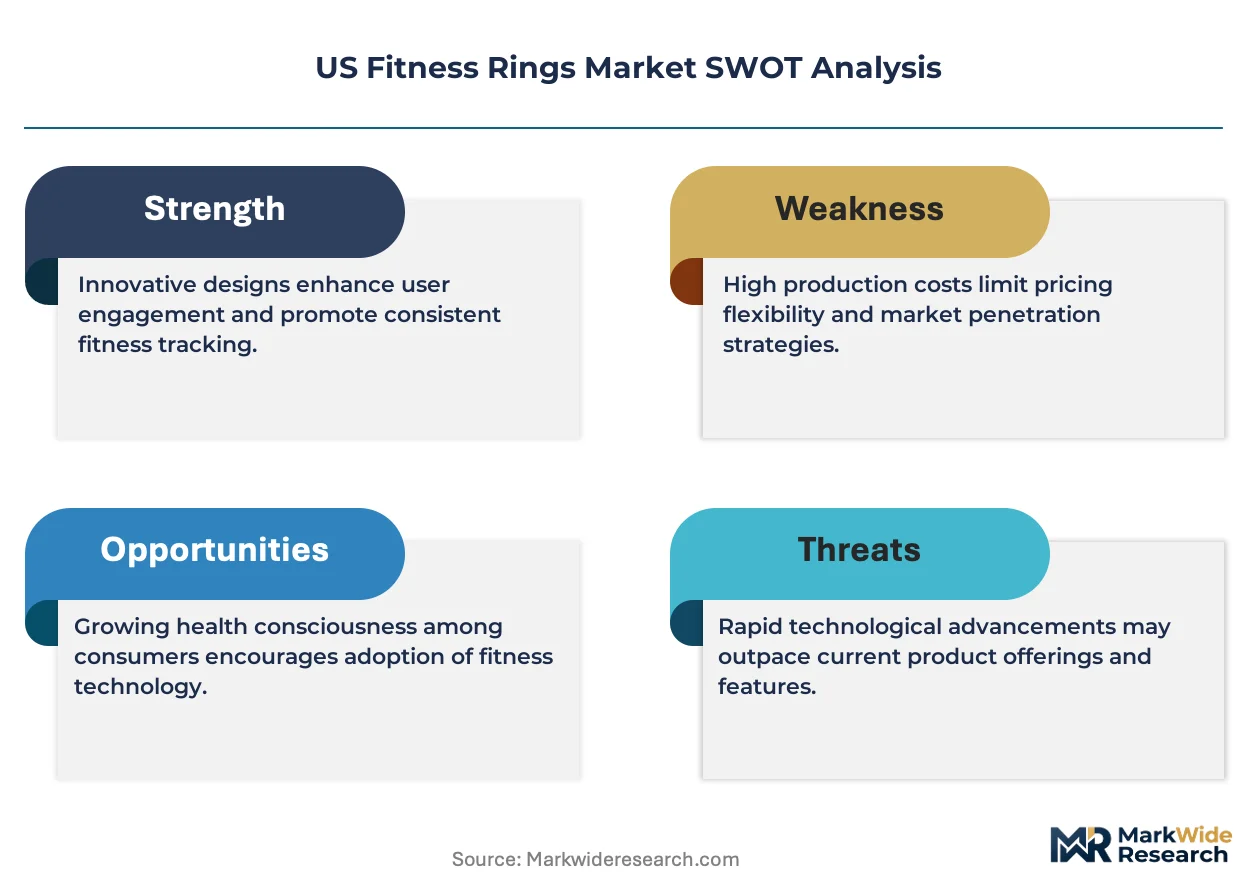
Among platform-anchored specialists, Oura Health Oy exemplifies the app-ecosystem archetype with recurring revenue models beyond hardware sales. Samsung Electronics Co. Ltd. occupies a position within diversified consumer electronics, leveraging Galaxy wearable portfolio integration. Movano Health represents the clinical-validation archetype, pursuing FDA clearance pathways for advanced biomarker detection.
| Leading Market Players |
|---|
| Oura Health Oy |
| Motiv Inc. |
| Samsung Electronics Co. Ltd. |
| Ultrahuman Healthcare Pvt. Ltd. |
| RingConn Technology Co. Ltd. |
| Circular Ring |
| Movano Health |
| Zepp Health Corporation |
| Fitbit Inc. |
| Others |
Pricing and Supply Chain Analysis
Domestic titanium processing capacity concentration in California and Texas aerospace corridors feeds directly into margin pools for clinical-grade health monitors, with defense procurement cycles and medical device competition compressing hardware margins while subscription analytics capture residual value.
Pricing Analysis
Price spreads between California tech-sector procurement and Texas health system contracts exceed 40% for identical titanium SKUs, reflecting employer-subsidized wellness program purchasing power against reimbursement-negotiated clinical tiers. Three-tier pricing structure across premium FDA-cleared monitors, standard Bluetooth-enabled smart rings, and economy activity trackers stratifies by certification grade and after-sales calibration bundling. Pricing pressure stems from smartwatch substitution at comparable price points, with Apple and Garmin wrist-worn devices capturing overlapping biometric functionality. Casual users in the Midwest exhibit highest price sensitivity, while Texas cardiovascular patients accessing regional health system partnerships show lowest elasticity for clinical-validated hardware.
Supply Chain Analysis
Photoplethysmography sensor arrays draw from Taiwan and South Korea semiconductor foundries, with Texas Instruments and Analog Devices anchoring domestic analog component supply. Raw material dependencies center on aerospace-grade titanium sponge from domestic Utah and Nevada processing facilities, plus Japanese and Russian feedstock subject to trade restriction volatility. Single-source vulnerability concentrates in multi-wavelength LED emitters for pulse oximetry, where two Asian suppliers control 70% of global capacity. Distribution runs through direct-to-consumer e-commerce channels for lifestyle-tier products, while health monitors require hospital system GPO contracts and durable medical equipment distributor networks for reimbursement pathway access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against multi-function smartwatch encroachment, with Apple and Garmin wrist-worn ecosystems threatening to absorb ring-form-factor demand through superior display interfaces and third-party app ecosystems.
For Market Incumbents: Harden FDA 510(k) clearance moats through expanded clinical validation cohorts for novel biomarkers like blood glucose correlation, while securing exclusive regional health system partnerships in Texas and California to lock reimbursement codes. Backward integration into photoplethysmography algorithm development addresses biomedical engineering talent scarcity, with MIT and Stanford research pipeline access reducing reliance on scarce optical physics specialists. For New Entrants and Emerging Players: Establish a beachhead in Texas sleep apnea home diagnostic programs, where underpenetrated clinical populations and health system pilot programs offer predicate-device-free entry points before FDA software-as-medical-device ambiguity resolves. Target Austin endurance-sport communities with laboratory-comparable heart rate variability positioning, leveraging direct-to-consumer subscription bundling to bypass entrenched hospital procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward clinical-validation startups pursuing de novo FDA pathways for hydration monitoring or novel sensor arrays, with 5-10 year viability hinging on first-mover exclusivity through predicate device barriers. Watch for FDA draft guidance finalization on algorithm-derived health scores as the critical inflection signal determining whether machine-learning components trigger medical device classification and reshape competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance for pulse oximetry claims unlocks Texas health system reimbursement pathways and GPO contract eligibility. |
| De Novo Classification Pursuit | Novel biomarker validation secures predicate exclusivity for blood glucose correlation or hydration monitoring sensors. |
| Hospital System Partnership | Texas Medical Center and Stanford Health Care alliances establish rings as reimbursable remote monitoring tools. |
| Subscription Analytics Bundling | Oura-style recurring revenue transforms single hardware purchases into ongoing coaching and longitudinal trend relationships. |
| Corporate Wellness Contract | Amazon and Google bulk procurement programs normalize continuous monitoring among high-disposable-income professional demographics. |
Research Methodology
The analysis maps smart rings, health monitors, activity trackers, and wellness devices, each validated through biomedical engineers, hospital purchasing committees, corporate wellness directors, and photoplethysmography algorithm specialists. Primary interviews with FDA regulatory consultants and Texas Medical Center clinicians combined with secondary validation against FDA 510(k) filings, FCC equipment authorization databases, and CMS remote patient monitoring reimbursement codes. Bottom-up shipment estimates by product tier and top-down market sizing by end-user expenditure triangulate to consensus figures.
Assumptions held fixed include FDA software-as-medical-device classification boundaries, Bluetooth Low Energy 5.3 adoption timelines, and titanium feedstock trade restriction severity, while variables included corporate wellness program expansion rates and smartwatch substitution elasticity. The analytical framework models product type, end-user segment, material grade, and technology tier dimensions across the projection horizon, with CAGRs derived from regression against historical wearable adoption curves and employer-sponsored health benefit penetration rates. Forecast inputs incorporate photoplethysmography sensor miniaturization cost curves and regional health system pilot program scaling assumptions.
Stress conditions across FDA regulatory timeline compression, titanium supply disruption severity, and smartwatch price-performance improvement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with specific risk factors including FDA expansion of software-as-medical-device oversight to algorithm-derived scores and aerospace industry titanium demand spikes. Material shifts in FDA classification boundaries for machine-learning health metrics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Exercise Bike Market
Fitness Equipment
Europe Home Fitness Equipment Market
Fitness Equipment
China Fitness Rings Market
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Push-Up Board Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Europe E-Commerce Home Fitness Products Market
Fitness Equipment
South Africa Gym Accessories Market