
 Smart Bathroom Scale Market | 2026-2036
Smart Bathroom Scale Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Bathroom Scale Market Insights
The R&D-to-manufacturing capability gap between premium and value-tier vendors is reorganizing competitive hierarchies in connected health hardware. Withings S.A.S. leverages proprietary position as a medical-grade device manufacturer with CE marking and FDA clearances that sustain premium pricing power. RENPHO competes through aggressive cost engineering and dominant Amazon marketplace positioning that anchors its volume leadership in North American direct-to-consumer channels. Xiaomi Corporation extends its Mi Ecosystem strategy to dominate price-sensitive Asian markets where smart home bundling reduces customer acquisition costs.
A smart bathroom scale is a connected weighing device incorporating load-cell sensors, bioelectrical impedance analysis circuits, and wireless transmitters to capture weight, body fat percentage, muscle mass, and other biometric metrics for personal or clinical health monitoring. These devices employ Bluetooth Low Energy or Wi-Fi protocols to synchronize data with mobile applications, cloud platforms, and electronic health record systems for longitudinal trend analysis. Body composition scales command the strongest margin pools due to multi-sensor hardware complexity and subscription attach rates for analytics services, while Bluetooth scales lead absolute volume through low power requirements and universal smartphone compatibility. Fitness tracking applications demonstrate the fastest structural expansion as gym chains and corporate wellness programs deploy fleet-scale deployments with centralized dashboard access.
FCC Part 15 regulations govern radio frequency emissions from Wi-Fi and Bluetooth transceivers, mandating certification before U.S. market entry and shaping hardware design constraints for antenna integration and power calibration. FDA oversight applies to scales marketed with diagnostic claims, requiring 510(k) clearance for body composition algorithms positioned for medical monitoring use cases. CE marking under the EU Medical Device Regulation creates parallel compliance burdens for European market access, particularly for scales targeting healthcare provider procurement channels. Stakeholders must monitor evolving FDA software-as-a-medical-device guidance to determine whether algorithm updates trigger new regulatory submissions.
Market Dynamics
Smart bathroom scale manufacturers face intensifying pressure from medical-grade certification requirements as FDA 510(k) clearances and EU MDR compliance become prerequisites for premium positioning in clinical procurement channels.
Growth Catalysts
- Home Fitness Tracking:Post-pandemic biometric monitoring habits have entrenched body composition measurement into daily wellness routines, creating sustained replacement demand for aging basic scales.
- FCC Part 15 Certification:Standardized radio frequency emission rules for Bluetooth and Wi-Fi transceivers have streamlined hardware design validation, reducing time-to-market for new entrants.
- Gym Chain Fleet Deployments:Corporate wellness programs and fitness franchises are installing connected scales with centralized dashboard access, generating B2B volume that offsets consumer seasonality.
Market Restraints
- Load-Cell Sensor Cost Volatility:Strain gauge and semiconductor component prices fluctuate with automotive and industrial demand cycles, compressing margin predictability for mid-tier vendors.
- China Supply Concentration:Xiaomi Corporation and domestic OEMs control 70% of global manufacturing capacity for entry-level units, creating pricing power asymmetry against Western brands.
- Bioelectrical Impedance Accuracy Limitations:Hydration-dependent measurement variability limits clinical adoption for medical monitoring use cases regardless of algorithm sophistication.
Strategic Opportunities
- India Direct-to-Consumer Channels:BIS certification requirements and PLI scheme incentives for electronics manufacturing are opening localized production pathways for brands willing to establish domestic assembly.
- Remote Patient Monitoring Integration:EHR synchronization capabilities and telehealth platform APIs represent white space for scales positioned between consumer wellness and clinical triage applications.
- AI-Driven Predictive Analytics:Machine learning models processing longitudinal weight and body composition trends are creating subscription revenue attach opportunities beyond hardware margins.
Industry Challenges
- FDA Software-as-a-Medical-Device Guidance Ambiguity:Uncertainty over whether algorithm updates trigger new 510(k) submissions complicates product roadmap planning for connected health features.
- Multi-Protocol Integration Complexity:Simultaneous support for Bluetooth Low Energy, Wi-Fi, and emerging Matter standards requires firmware engineering capabilities scarce outside established IoT vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Bathroom Scale Market |
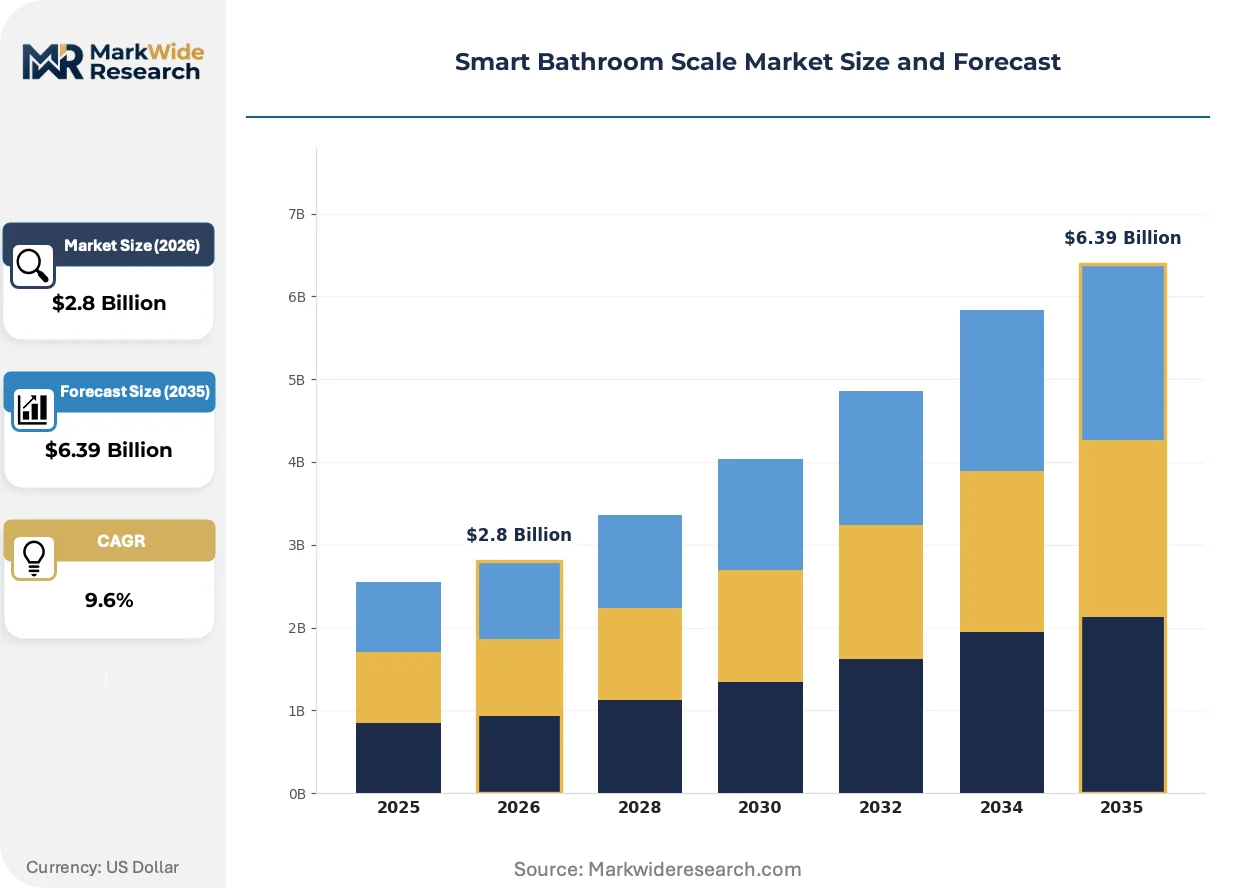
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth Scales, Wi-Fi Scales, Body Composition Scales, Standard Digital Scales Application: Personal Health, Fitness Tracking, Medical Monitoring, Weight Management End User: Households, Fitness Enthusiasts, Healthcare Providers, Gyms Technology: Analog, Digital, Smart Tech, Connectivity Features |
| Companies Covered | Apple Inc., Samsung Electronics Co Ltd, Xiaomi Corporation, Garmin Ltd., Withings S.A.S., RENPHO, Wyze Labs Inc., Under Armour Inc., Beurer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Bathroom Scale Market Trends and Innovations
Sensor fusion architectures and regulatory software frameworks are actively redefining competitive differentiation boundaries between consumer wellness and clinical-grade device categories.
Multi-frequency bioelectrical impedance analysis is fragmenting the traditional single-frequency measurement paradigm by enabling segmental body composition assessment. High-end fitness clubs and sports medicine clinics are adopting these units despite 3-4x price premiums. The technology is fragmenting vendor tiers into specialized medical-grade suppliers versus simplified consumer electronics assemblers.
EU Medical Device Regulation enforcement is tightening CE marking requirements for scales marketed with diagnostic claims. Manufacturers must now maintain technical documentation and post-market surveillance systems previously exempt for general wellness devices. Body composition algorithm vendors targeting European healthcare procurement channels are restructuring quality management systems to satisfy notified body audits.
Subscription unbundling from hardware purchases is reshaping how consumers acquire analytics capabilities. Fitness application developers now offer standalone body composition tracking without mandatory scale hardware, forcing original equipment manufacturers to defend value through sensor accuracy and ecosystem integration. North American direct-to-consumer channels exhibit the most pronounced shift toward hardware-agnostic service models.
Smart Bathroom Scale Market Segmentation
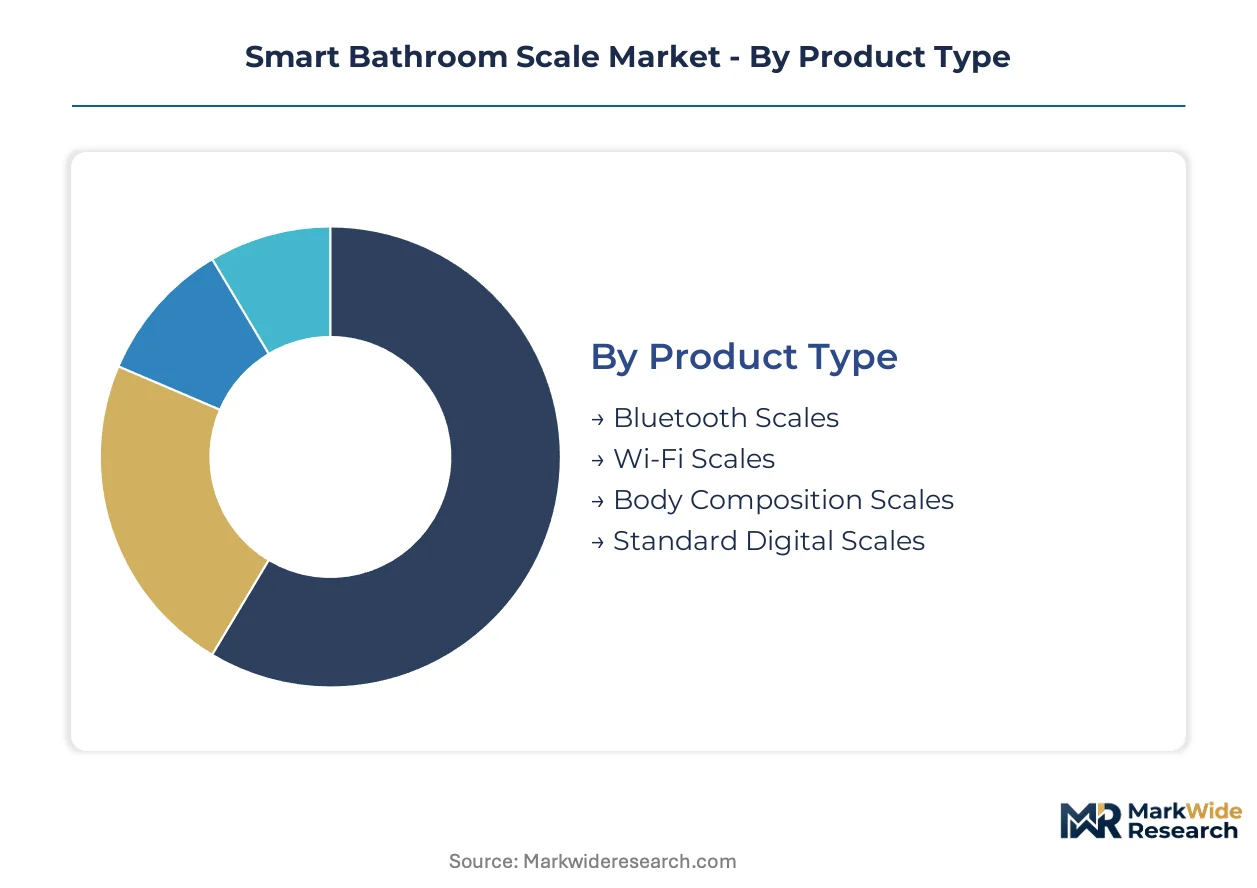
Segmentation in the smart bathroom scale market reveals how hardware complexity, connectivity protocols, and user sophistication create distinct margin architectures. Product type and application dimensions particularly expose where premium pricing power concentrates versus where volume commoditization pressures dominate.
Product Type:
Body composition scales command the deepest margin pools due to multi-sensor hardware requirements and recurring analytics subscriptions, while Bluetooth scales anchor volume leadership through manufacturing simplicity.
- Body Composition Scales:These devices integrate bioelectrical impedance analysis circuits with load-cell sensors to measure fat percentage, muscle mass, bone density, and hydration levels. Demand concentrates among fitness enthusiasts in the United States and Germany where gym chains deploy fleet-scale units with centralized dashboard access, though hydration-dependent measurement variability limits clinical adoption regardless of algorithm sophistication.
- Bluetooth Scales:Low-energy transceivers enable smartphone synchronization without Wi-Fi infrastructure, making these units ideal for price-sensitive household penetration. Volume leadership in China reflects Xiaomi Corporation's Mi Ecosystem bundling strategy that reduces customer acquisition costs through smart home cross-selling.
- Wi-Fi Scales:Direct cloud connectivity eliminates smartphone dependency for data upload, appealing to users prioritizing seamless longitudinal tracking.
- Standard Digital Scales:Basic load-cell configurations without connectivity features serve replacement demand in emerging markets where smartphone penetration lags.
The dominant share belongs to Bluetooth scales, while body composition scales are closing the gap fastest through gym chain procurement and sports medicine clinic adoption.
Application:
Volume distribution across applications tracks the post-pandemic normalization of biometric monitoring habits, with fitness tracking demonstrating structural expansion beyond hardware replacement cycles.
- Fitness Tracking:Gym chains and corporate wellness programs deploy connected scales with API-accessible dashboards for member engagement and population health analytics. North American direct-to-consumer channels exhibit pronounced shift toward hardware-agnostic service models as fitness application developers offer standalone body composition tracking.
- Personal Health:Daily weight monitoring integrated with chronic condition management apps drives sustained replacement demand for aging basic scales in Japanese and South Korean households.
- Medical Monitoring:FDA 510(k) clearance requirements and EU MDR compliance create certification barriers that sustain premium pricing for scales positioned between consumer wellness and clinical triage applications.
- Weight Management:Behavioral intervention programs and employer-sponsored wellness initiatives generate B2B volume that offsets consumer seasonality in procurement patterns.
Fitness tracking applications are expanding most quickly through fleet deployments, while personal health maintains the largest installed base.
End User:
Customer-type segmentation exposes divergent procurement rhythms between impulse-driven household purchases and institutional procurement cycles with extended vendor qualification requirements.
- Fitness Enthusiasts:Early adopters drive premium segment growth through demand for segmental body composition assessment and multi-frequency bioelectrical impedance analysis despite 3-4x price premiums over basic units.
- Households:Replacement demand for aging mechanical scales creates volume foundation, with smart home ecosystem bundling reducing price sensitivity in Asian markets.
- Healthcare Providers:EHR synchronization capabilities and telehealth platform APIs represent white space for vendors navigating FDA software-as-a-medical-device guidance ambiguity.
- Gyms:Fleet-scale deployments with centralized dashboard access generate B2B volume with lower customer acquisition costs and higher lifetime value through membership retention metrics.
Households retain the dominant installed base, though gyms are gaining share fastest through corporate wellness program expansion.
Technology:
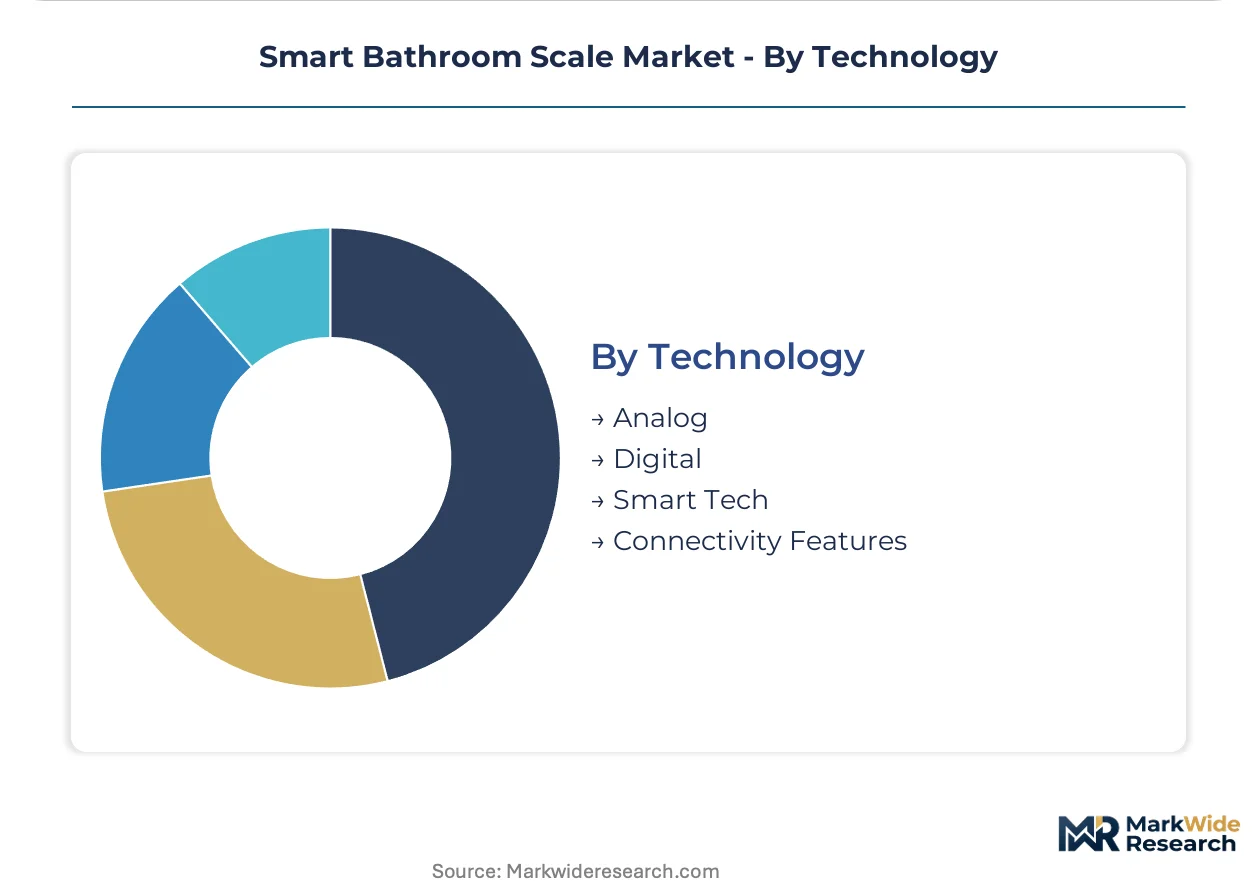
Technology architecture determines regulatory exposure and firmware engineering requirements, with connectivity features creating compliance burdens that fragment vendor capabilities.
- Smart Tech:Multi-protocol integration supporting Bluetooth Low Energy, Wi-Fi, and emerging Matter standards requires engineering capabilities scarce outside established IoT vendors, creating capability moats for premium positioning.
- Connectivity Features:FCC Part 15 certification mandates for radio frequency emissions shape hardware design constraints for antenna integration and power calibration in United States market entry.
- Digital:Microcontroller-based measurement with local display eliminates wireless regulatory exposure while maintaining precision superior to analog alternatives.
- Analog:Spring-based mechanical mechanisms persist only in ultra-low-price segments where electrification costs exceed target retail price points.
Smart tech architectures are climbing the fastest as multi-protocol support becomes table stakes for ecosystem integration, while digital maintains volume leadership in price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and the United States where medical-grade certification sustains margin premiums, while manufacturing scale and ecosystem bundling anchor volume leadership in China.
United States
Fitness enthusiasts and corporate wellness programs drive demand for FDA-cleared body composition scales with EHR synchronization capabilities. FCC Part 15 mandates govern Bluetooth and Wi-Fi transceiver certification before market entry. Greater Boston hosts telehealth platform developers integrating scale data into remote patient monitoring workflows.
Germany
Sports medicine clinics and high-end fitness chains adopt multi-frequency bioelectrical impedance analysis units despite substantial price premiums. EU Medical Device Regulation enforcement tightens CE marking requirements for diagnostic claims. Bavaria's medical device engineering cluster supplies precision sensor components to premium tier manufacturers.
China
Xiaomi Corporation's Mi Ecosystem bundling strategy reduces customer acquisition costs through smart home cross-selling at aggressive price points. MIIT oversees wireless transmission protocol compliance under national GB standards. Shenzhen's electronics manufacturing corridor controls global capacity for entry-level Bluetooth scale assembly.
Japan
Daily weight monitoring integrated with chronic condition management apps sustains replacement demand in aging households. METI administers certification under Radio Law for wireless health devices. Osaka's precision instrument manufacturers supply load-cell sensors to domestic and export markets.
India
BIS certification requirements and PLI scheme incentives for electronics manufacturing attract brands establishing localized assembly operations. CDSCO guidelines govern software-as-a-medical-device classifications for body composition algorithms. Maharashtra's Pune industrial corridor hosts emerging domestic OEM capacity for price-sensitive household penetration.
Smart Bathroom Scale Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where medical-grade certification sustains premium positioning against ecosystem-driven volume plays. The vendor base organizes around three strategic archetypes: CE-marked medical device specialists, Amazon marketplace cost engineers, and smart home ecosystem bundlers. Dominant competitive moves include strategic partnerships with telehealth platforms and geographic expansion through localized manufacturing incentives.
Within the medical-grade tier, Withings S.A.S. and Beurer GmbH exemplify European specialists leveraging regulatory clearances for clinical procurement channels. Xiaomi Corporation anchors the ecosystem-driven volume tier through aggressive smart home bundling. RENPHO occupies a position exemplifying marketplace-native cost engineering for direct-to-consumer penetration.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co Ltd |
| Xiaomi Corporation |
| Garmin Ltd. |
| Withings S.A.S. |
| RENPHO |
| Wyze Labs Inc. |
| Under Armour Inc. |
| Beurer GmbH |
| Others |
Pricing and Supply Chain Analysis
Manufacturing scale in Shenzhen's electronics corridor shapes both supply concentration and price floors for entry-level Bluetooth scales, while medical-grade certification requirements in Germany and the United States sustain premium pricing tiers for body composition units with FDA 510(k) clearances.
Pricing Analysis
The customization-premium spread spans roughly three-to-four multiples between basic Bluetooth scales and multi-frequency bioelectrical impedance analysis units with segmental measurement capabilities. Pricing stratifies across premium, standard, and economy tiers, with certification grade and sensor complexity as primary differentiation drivers. Cost compression in the economy tier intensifies because Xiaomi Corporation's Mi Ecosystem bundling absorbs customer acquisition costs through smart home cross-selling. Household consumers exhibit highest price sensitivity, while sports medicine clinics and gym chains demonstrate lowest sensitivity due to fleet procurement budgets and membership retention metrics.
Supply Chain Analysis
Just-in-time inventory strategies dominate for semiconductor components and load-cell sensors, though strategic stockpiling of strain gauge materials occurs among premium-tier manufacturers facing automotive demand cycle volatility. Supply concentrates in China, Japan, and Germany, with Shenzhen anchoring final assembly, Osaka supplying precision load-cell components, and Bavaria providing medical-grade sensor engineering. Raw material dependencies include semiconductor wafers, aluminum alloy platforms, and bioelectrical impedance electrode materials. Single-source vulnerability in Bluetooth and Wi-Fi chipset supply creates structural risk for mid-tier vendors lacking multi-protocol engineering capabilities. Distribution runs through Amazon marketplace direct-to-consumer channels in North America, smart home retail ecosystems in Asia, and clinical procurement networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart bathroom scale market sits in early-cycle expansion as post-pandemic biometric monitoring habits entrench body composition measurement into daily wellness routines, creating sustained replacement demand beyond traditional hardware refresh cycles.
For Market Incumbents: Shield market position by deepening FDA 510(k) clearance portfolios for body composition algorithms targeting remote patient monitoring integration, and anchor backward integration into precision load-cell sensor production to offset strain gauge cost volatility. Certification investment represents the critical defensive lever against ecosystem bundlers commoditizing basic connectivity features.
For New Entrants and Emerging Players: Anchor in India's direct-to-consumer channels where BIS certification requirements and PLI scheme incentives create localized production pathways for brands establishing domestic assembly. The most penetrable white space sits between consumer wellness and clinical triage applications, with telehealth platform APIs as the primary go-to-market angle for EHR synchronization capabilities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors medical-grade device specialists with CE marking and notified body audit capabilities over marketplace-native cost engineers facing margin compression. Long-term viability hinges on subscription revenue attach rates for AI-driven predictive analytics processing longitudinal body composition trends. The signal to watch is FDA software-as-a-medical-device guidance clarity on whether algorithm updates trigger new 510(k) submissions.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Medical-grade certification sustains premium pricing power in clinical procurement channels. |
| Telehealth Platform Integration | EHR synchronization capabilities open white space between wellness and triage applications. |
| Multi-Protocol Firmware Development | Simultaneous Bluetooth, Wi-Fi, and Matter support creates capability moats for ecosystem integration. |
| Localized Manufacturing Establishment | India's PLI scheme incentives reduce landed cost for price-sensitive household penetration. |
| Subscription Analytics Unbundling | Machine learning models processing longitudinal trends create recurring revenue beyond hardware margins. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with connected health hardware executives, regulatory affairs specialists at notified bodies, gym chain procurement managers, and biomedical engineers; alongside secondary validation through FDA 510(k) filings, FCC Part 15 certification databases, EU MDR technical documentation, and hospital procurement contract records. Bottom-up unit economics modeling triangulated against top-down market sizing across manufacturer shipment disclosures and retail channel audit data.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type complexity, connectivity protocol architecture, end-user procurement rhythm, and regional regulatory cluster. CAGRs were derived from slope analysis of historical adoption curves adjusted for penetration saturation effects and replacement cycle compression. Industry-specific forecast inputs incorporated gym chain fleet deployment pipelines and telehealth platform API integration roadmaps.
Material uncertainties — FDA software-as-a-medical-device guidance revisions, strain gauge commodity price cycles, and China supply concentration disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification timeline stability and ecosystem bundling intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Disposable Electric Toothbrushes Market
Personal Grooming Products
North America Mosquito Repellent Market
Personal Grooming Products
Hand Massager Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Disposable Razor Blades Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Global Aligner Sheet Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Gel Socks Market
Personal Grooming Products
Electric Hair Brush Market
Personal Grooming Products
Personal Hygiene Market