
 360 Degree Toothbrush Market | 2026-2036
360 Degree Toothbrush Market Size, Share, and Industry Trends Forecast 2026-2036
360 Degree Toothbrush Market Outlook
A capital-intensity divergence between established appliance manufacturers and emerging direct-to-consumer brands is unwinding traditional competitive boundaries in oral care hardware. Oral-B (Procter & Gamble) leverages integrated manufacturing scale across multiple continents to sustain cost advantages in electric 360-degree formats. Shenzhen Ximalong Technology Co., Ltd. competes through specialized OEM production for private-label distributors seeking rapid design iteration.
A 360 degree toothbrush employs a circular or cylindrical brush head array designed to contact all tooth surfaces simultaneously during use, typically incorporating 10,000 to 40,000 filaments arranged in a radial pattern around a central axis. The device serves consumers seeking reduced brushing time and improved plaque removal consistency, particularly among caregivers managing dependent populations. Electric and sonic variants command premium positioning due to motor-driven oscillation requirements and associated battery technology costs. The adult end-user segment anchors current revenue while the special needs category presents concentrated growth potential given institutional procurement volumes.
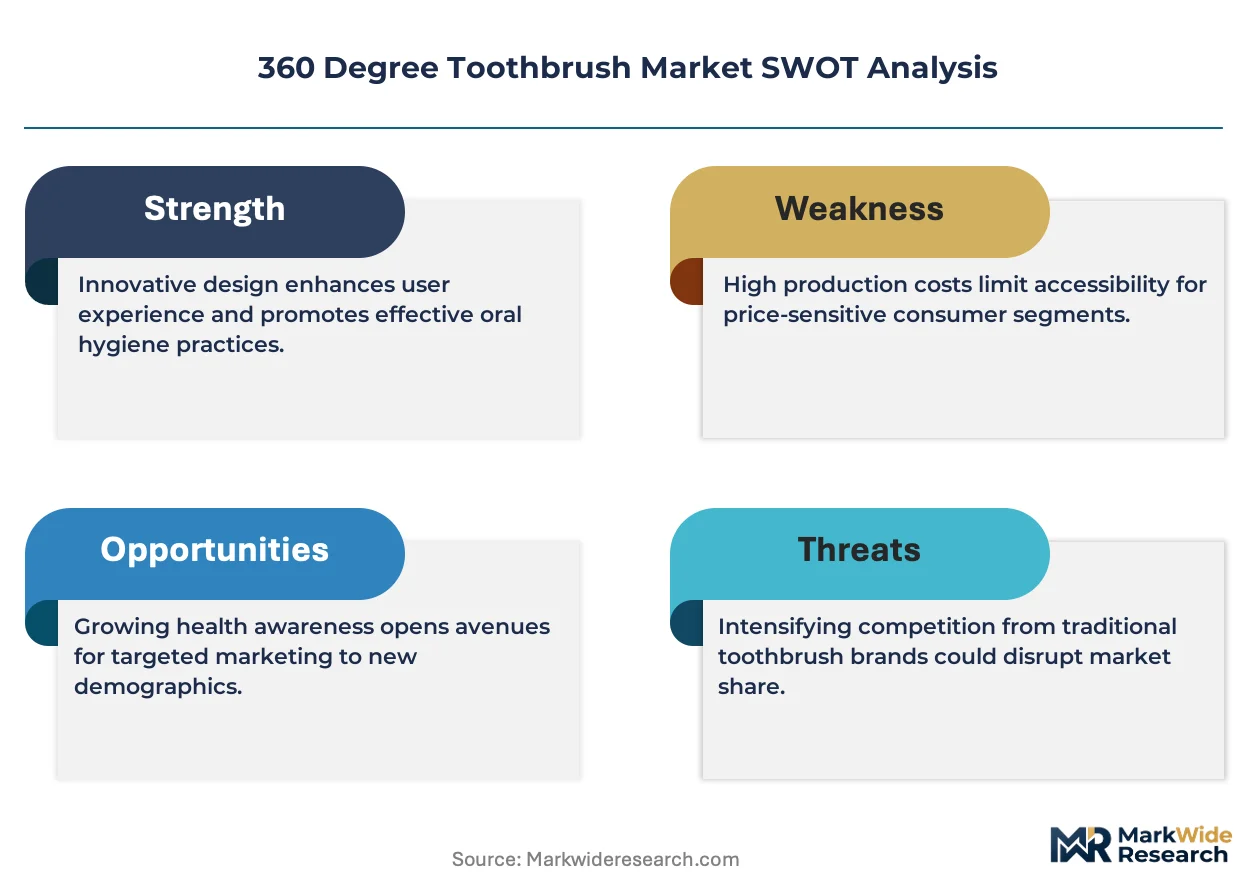
The FDA Center for Devices and Radiological Health classifies powered toothbrushes as Class I medical devices, imposing quality system regulations that elevate barriers for unvalidated entrants. ISO 20126 standards for manual toothbrush durability and safety extend to 360-degree configurations through adapted filament retention testing protocols. Stakeholders must monitor evolving antimicrobial technology claims as the Federal Trade Commission intensifies scrutiny of unsubstantiated hygiene benefit assertions in consumer marketing.
Market Dynamics
Capital deployment patterns in oral care hardware are bifurcating between integrated appliance conglomerates and agile direct-to-consumer entrants, eroding traditional competitive moats built on manufacturing scale alone.
Growth Catalysts
- Caregiver time compression:Institutional buyers managing dependent populations prioritize full-coverage brushing systems that reduce per-patient hygiene labor. This demand concentrates in German dental professional networks where endorsement rates exceed European baselines.
- ISO 20126 durability protocols:Adapted filament retention testing for radial brush configurations validates product longevity claims, accelerating retail channel acceptance for premium electric formats.
- FDA Class I pathway clarity:Quality system regulations for powered toothbrushes now explicitly accommodate 360-degree head geometries, streamlining 510(k) submissions for novel entrants.
Market Restraints
- Lithium-ion cell cost volatility:Battery chemistry fluctuations compress margins on sonic variants where motor-driven oscillation requirements mandate premium power density specifications.
- Shenzhen OEM concentration:Private-label production clusters in Guangdong Province create single-source vulnerability for rapid-iteration brands lacking captive manufacturing.
- Filament radial density limits:Current polymer extrusion tolerances cap simultaneous surface contact efficiency below theoretical optimums, constraining plaque removal consistency claims.
Strategic Opportunities
- Suburban dental clinic expansion:United States exurban markets show underpenetrated recommendation rates for full-coverage systems relative to urban counterparts.
- Antimicrobial coating convergence:Integration of copper-alloy filaments with radial head architectures addresses FTC scrutiny of unsubstantiated hygiene assertions through demonstrable microbial load reduction.
- Institutional procurement centralization:Long-term care facility group purchasing organizations in North America consolidate supplier rosters, favoring vendors with validated dependent-population efficacy data.
Industry Challenges
- Biocompatibility certification timelines:Novel polymer submissions to FDA Center for Devices and Radiological Health face 18-24 month review cycles, delaying product launches.
- Radial head IP thickets:Patent landscapes around cylindrical bristle arrays require careful freedom-to-operate analysis, particularly for entrants from jurisdictions with weaker prior-art examination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 360 Degree Toothbrush Market |
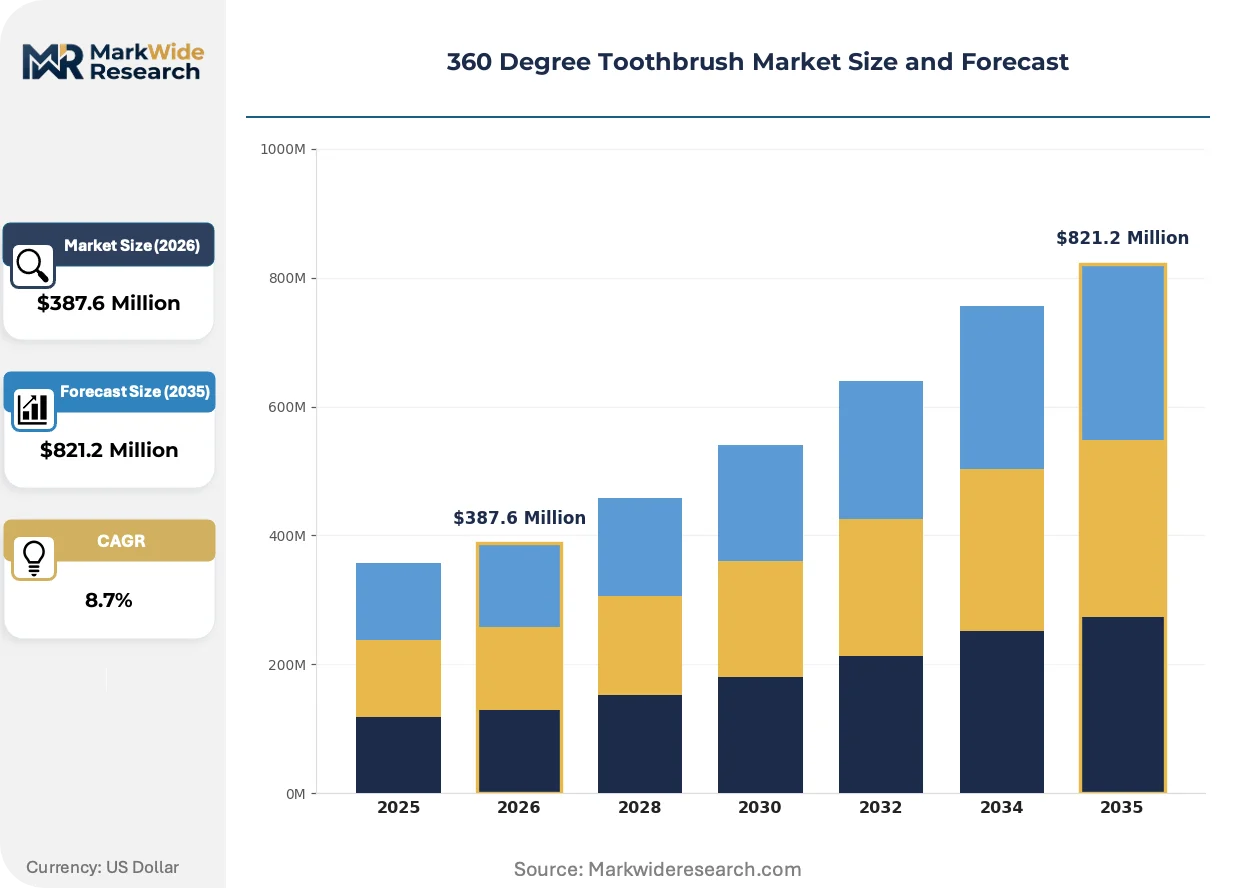
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Battery-Operated, Sonic End User: Adults, Children, Elderly, Special Needs Material: Bamboo, Plastic, Silicone, Biodegradable Technology: Smart, Traditional, Ultrasonic, Antimicrobial |
| Companies Covered | Oral-B (Procter & Gamble), Philips Sonicare, Colgate-Palmolive, Quip, RADIUS, YBrush, Shenzhen Ximalong Technology Co., Ltd., Jideng, Hammer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
360 Degree Toothbrush Market Strategic Shifts
Product architecture in oral care hardware is converging on simultaneous multi-surface contact systems, compressing traditional sequential brushing paradigms while elevating motor and materials specifications.
Sonic motor arrays with piezoelectric drive mechanisms is supplanting conventional rotary designs in premium 360-degree formats. German dental clinics now specify oscillation frequencies above 30,000 cycles per minute for professional-grade recommendations. This displacement compresses development timelines for brands lacking transducer engineering capabilities.
REACH antimicrobial substance restrictions are forcing reformulation of filament coatings across European distribution channels. Manufacturers must now substitute legacy silver-ion treatments with copper-based alternatives to maintain biocidal claims. German and French regulators are accelerating compliance deadlines, compressing product refresh cycles for established portfolios.
Subscription replenishment models for radial brush head cartridges are displacing traditional retail replenishment in North American direct-to-consumer channels. Caregiver segments managing multiple dependent patients prioritize automated delivery schedules over pharmacy pickup. This pattern concentrates in United States suburban markets where dental professional endorsement drives initial trial.
360 Degree Toothbrush Market Segmentation
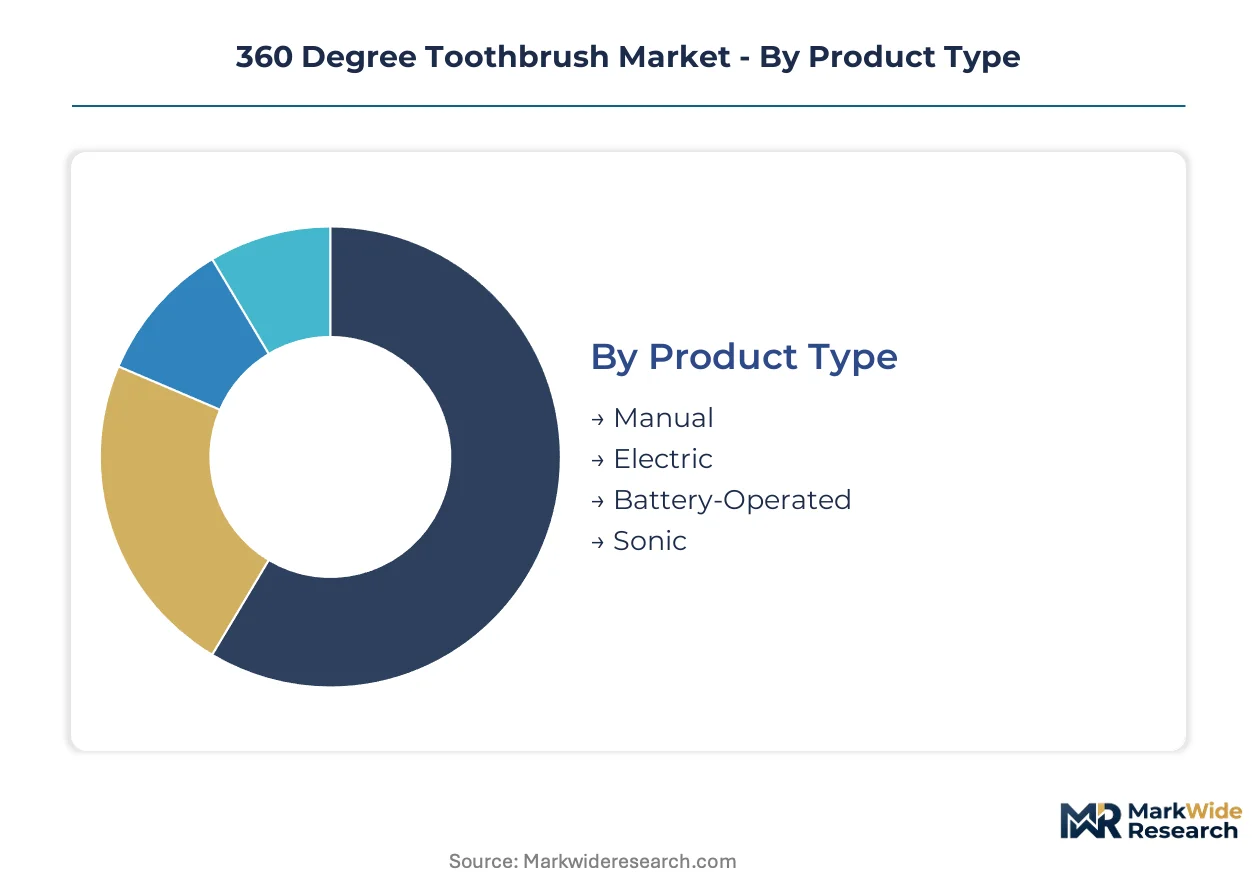
Segmentation in the 360 degree toothbrush market reveals divergent commercial logics across power source, user population, material composition, and technology integration. Each dimension carries distinct regulatory footprints, margin structures, and geographic concentration patterns that shape vendor positioning.
Product Type:
Manual variants dominate domestic consumption in price-sensitive markets, while electric and sonic formats drive export-led revenue through premium positioning in German and United States dental professional networks.
- Manual:Radial bristle arrays without motorization rely on user motion for simultaneous surface contact. Demand concentrates in emerging Asian markets where unit economics favor disposable formats over replacement head systems.
- Electric:Mains-powered or rechargeable motor drives oscillate cylindrical brush heads at calibrated frequencies. German dental clinics specify these for dependent-population protocols where caregiver labor reduction justifies acquisition cost.
- Battery-Operated:Single-use or replaceable cell configurations target travel and institutional procurement segments with lower upfront investment requirements.
- Sonic:Piezoelectric transducers generate acoustic wave propagation through fluid media for interdental cleaning efficacy. Premium positioning in United States suburban markets reflects FDA Class I pathway investments and professional endorsement density.
Electric holds the largest share; momentum sits with Sonic.
End User:
Caregiver-managed populations generate institutional procurement volumes with contracted replenishment schedules, while self-directed adult users drive retail channel velocity through pharmacy and direct-to-consumer distribution.
- Adults:Self-directed users with established brushing habits represent baseline demand for all product formats. United States exurban markets show underpenetrated recommendation rates relative to urban counterparts.
- Children:Smaller radial head geometries accommodate primary dentition dimensions with reduced filament stiffness. Parental purchase decisions prioritize safety certifications and durability claims validated through ISO 20126 protocols.
- Elderly:Arthritis-adapted grip geometries and reduced motor vibration thresholds address dexterity limitations. Long-term care facility group purchasing organizations in North America consolidate supplier rosters around this segment.
- Special Needs:Dependent populations requiring assisted hygiene drive full-coverage system adoption. German dental professional endorsement rates for 360-degree formats outpace broader European averages in this category.
Adults anchor volume; Special Needs is climbing the fastest.
Material:
Polymer selection determines regulatory compliance burden across REACH restrictions in Europe versus FDA biocompatibility timelines in the United States, with sustainability claims increasingly scrutinized by the Federal Trade Commission.
- Bamboo:Cellulose fiber handles with natural antimicrobial properties target sustainability-positioned consumers. REACH substance restrictions on preservative treatments complicate European distribution.
- Plastic:Petroleum-based polymers dominate manufacturing scale with established filament retention characteristics. Shenzhen OEM clusters concentrate production for private-label distributors seeking rapid design iteration.
- Silicone:Elastomer formulations enable flexible radial head geometries with reduced gingival trauma risk. Pediatric and elderly applications favor this material for comfort differentiation.
- Biodegradable:Polylactic acid and other compostable polymers address waste reduction mandates. Extended biodegradation certification timelines delay product launches in regulated markets.
Plastic holds the largest share; momentum sits with Biodegradable.
Technology:
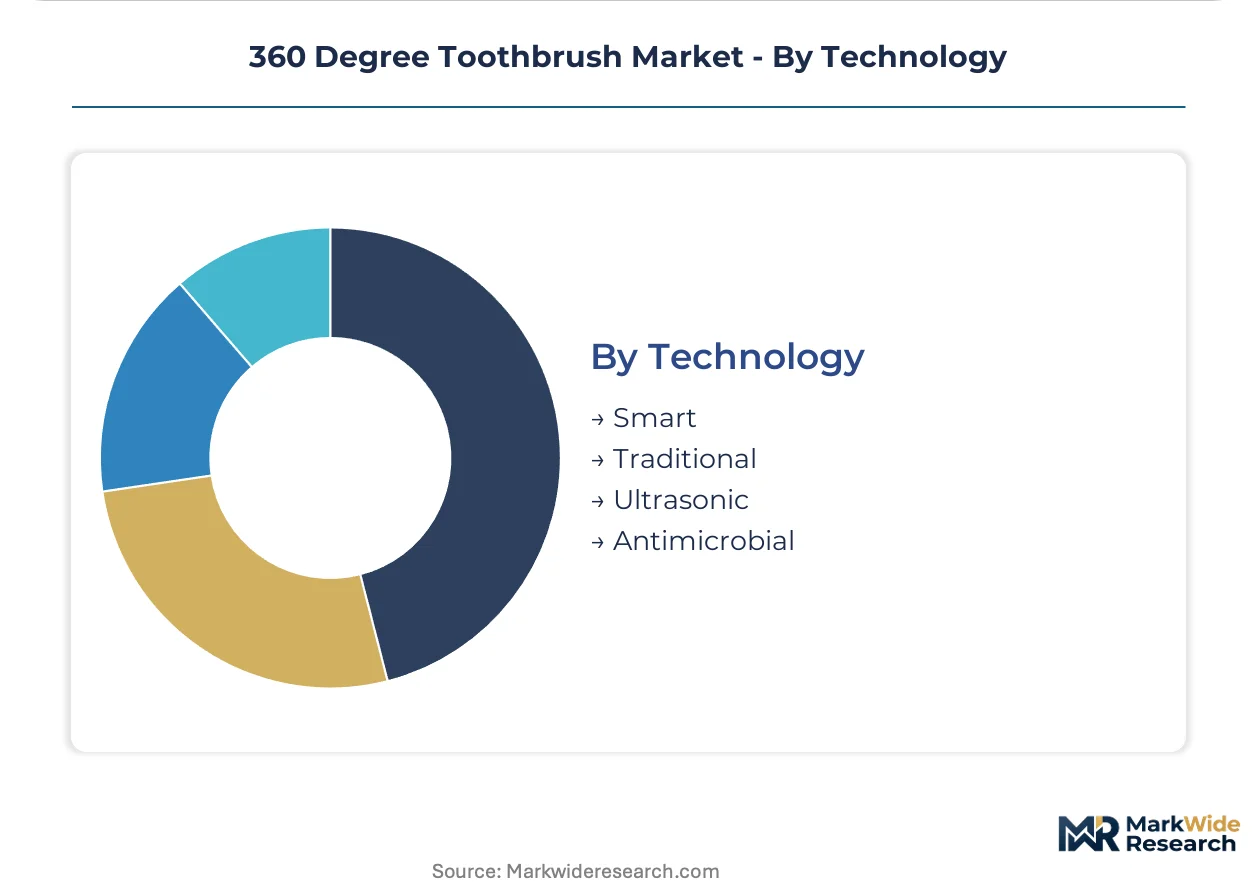
Smart connectivity and antimicrobial claims attract regulatory scrutiny disproportionate to traditional mechanical formats, with FTC substantiation requirements and FDA device classification updates reshaping competitive boundaries.
- Smart:Bluetooth-enabled brushing duration tracking and pressure sensing transmit data to mobile applications. Data privacy frameworks in European markets impose GDPR compliance costs on connected device architectures.
- Traditional:Unconnected mechanical operation without sensor arrays or data transmission. Margin compression in this segment reflects commodity positioning and limited differentiation vectors.
- Ultrasonic:Frequencies above 20,000 Hz drive fluid dynamics for plaque disruption beyond bristle contact zones. German dental clinics specify oscillation frequencies above 30,000 cycles per minute for professional-grade recommendations.
- Antimicrobial:Copper-alloy filaments or surface coatings demonstrate microbial load reduction. FTC intensifies scrutiny of unsubstantiated hygiene benefit assertions, favoring entrants with validated copper-based alternatives over legacy silver-ion treatments.
Traditional holds the largest share; Ultrasonic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows for 360-degree toothbrushes tilt toward manufacturing concentration in Chinese industrial clusters and premium consumption in Western dental professional networks. The United States and Germany absorb high-margin electric and sonic formats, while Shenzhen OEM production serves private-label distributors across price-sensitive markets.
United States
FDA Class I device classification for powered toothbrushes streamlines 510(k) submissions for 360-degree head geometries, reducing regulatory friction for novel entrants. Suburban dental clinics in exurban markets show underpenetrated recommendation rates relative to urban counterparts, creating whitespace for professional endorsement programs. The Pacific Northwest hosts direct-to-consumer brand headquarters leveraging subscription replenishment models for radial brush head cartridges.
Germany
Dental professional endorsement rates for 360-degree formats outpace broader European averages, particularly for dependent-population protocols in long-term care. REACH antimicrobial substance restrictions force rapid reformulation of filament coatings, compressing product refresh cycles for established portfolios. Bavaria-based dental supply distributors consolidate procurement for institutional buyers seeking ISO 20126-validated durability claims.
China
Shenzhen OEM clusters concentrate private-label production for rapid-iteration brands lacking captive manufacturing, creating single-source vulnerability in Guangdong Province. The country's national medical device regulator aligns with international standards for powered oral care instruments, facilitating export-oriented production. Yangtze River Delta manufacturing hubs supply polymer extrusion components for radial brush head arrays.
Japan
PMDA device standards for powered oral care instruments impose quality system requirements that elevate barriers for unvalidated entrants. Aging demographics drive institutional procurement for full-coverage brushing systems in eldercare facilities. Kansai region dental equipment distributors specialize in arthritis-adapted grip geometries for dexterity-limited users.
United Kingdom
GPR data privacy frameworks impose compliance costs on Bluetooth-enabled smart toothbrush architectures transmitting usage data to mobile applications. London-based dental professional networks pilot recommendation programs for sonic variants with oscillation frequencies above 30,000 cycles per minute. Midlands manufacturing sites produce biodegradable polylactic acid handles for sustainability-positioned export markets.
360 Degree Toothbrush Market Competitive Environment
Concentration sits with integrated appliance conglomerates leveraging multi-continent manufacturing scale, while agile direct-to-consumer entrants erode traditional moats through rapid design iteration. The vendor base separates into three strategic archetypes: multinational CPG conglomerates with captive R&D infrastructure, specialized OEM fabricators serving private-label distributors, and digital-native brands built on subscription economics. Dominant competitive moves include backward integration into polymer extrusion capabilities and technology licensing partnerships for piezoelectric transducer engineering.
Within the multinational tier, Oral-B (Procter & Gamble) and Philips Sonicare exemplify scale-driven positioning through integrated manufacturing footprints and professional endorsement density. Shenzhen Ximalong Technology Co., Ltd. represents the specialized OEM archetype, occupying a fabrication role for rapid-iteration brands seeking design agility without captive production investment. These three anchors illustrate the bifurcation between premium brand equity and manufacturing efficiency that defines current competitive dynamics.
| Leading Market Players |
|---|
| Oral-B (Procter & Gamble) |
| Philips Sonicare |
| Colgate-Palmolive |
| Quip |
| RADIUS |
| YBrush |
| Shenzhen Ximalong Technology Co., Ltd. |
| Jideng |
| Hammer |
| Others |
Value Chain & Pricing Dynamics
Multi-continent manufacturing scale at integrated appliance conglomerates creates asymmetric cost structures that compress price floors for emerging direct-to-consumer brands while elevating barriers for unvalidated entrants. Shenzhen OEM clusters concentrate radial brush head production in Guangdong Province, feeding private-label distributors with rapid iteration capabilities that undercut premium positioning.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the 360 degree toothbrush market. Sonic variants with piezoelectric transducers command premium positioning driven by FDA Class I pathway investments and German dental professional endorsement density, while manual radial arrays compete on unit economics in price-sensitive Asian markets. Cost compression in battery-operated tiers intensifies because lithium-ion cell volatility compresses margins on motor-driven formats. Caregiver-managed institutional procurement shows least price sensitivity due to labor reduction justification, whereas self-directed adult retail segments exhibit highest elasticity.
Supply Chain Analysis
Yangtze River Delta polymer extrusion capacity underwrites radial filament supply for global 360-degree toothbrush assembly, with Shenzhen fabrication clusters and South Korean piezoelectric component specialists completing the upstream map. Raw material dependencies center on medical-grade polymer feedstock, copper-alloy antimicrobial coatings, and rechargeable cell chemistry. Single-source vulnerability concentrates in Guangdong Province OEM concentration, where rapid-iteration brands lack captive manufacturing alternatives. Distribution runs through dental supply distributors in Germany, direct-to-consumer subscription platforms in United States suburban markets, and pharmacy retail channels across price-sensitive Asian geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from unconnected manual formats in emerging markets and smart-connected architectures from agile digital-native entrants. Defense requires securing professional endorsement density and manufacturing scale advantages before technology convergence erodes differentiation.
For Market Incumbents: Secure backward integration into polymer extrusion capabilities to reduce Shenzhen OEM dependency and capture margin compression from lithium-ion cost volatility. Deepen ISO 20126 validation investments to accelerate retail channel acceptance and defend against antimicrobial coating reformulation pressures under REACH restrictions. Priority lever sits with institutional procurement centralization in North American long-term care facilities.
For New Entrants and Emerging Players: Subscription replenishment service gaps in caregiver-managed dependent populations offer white-space penetration where incumbents under-serve automated delivery needs. Target United States exurban suburban dental clinics with underpenetrated recommendation rates relative to urban counterparts. Go-to-market angle leverages direct-to-consumer platform economics with radial brush head cartridge auto-ship programs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized OEM fabricators with transducer engineering capabilities and validated biocompatibility certifications. Long-term viability hinges on 5-10 year regulatory pathway clarity as FDA device classification updates reshape competitive boundaries. Acquisition target archetype combines piezoelectric sonic expertise with institutional procurement relationships. Signal to watch: German dental professional endorsement rate divergence from European baselines as inflection indicator for premium format adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Captive filament production reduces Guangdong OEM dependency and compresses unit economics for radial brush arrays. |
| Antimicrobial Coating Reformulation | Copper-alloy substitution for legacy silver-ion treatments addresses REACH compliance deadlines in German and French distribution channels. |
| Subscription Replenishment Platform Launch | Automated radial brush head delivery locks in caregiver segments managing multiple dependent patients in United States suburban markets. |
| Institutional Procurement Certification | ISO 20126 validation opens consolidated supplier rosters at North American long-term care facility group purchasing organizations. |
| Piezoelectric Transducer Licensing Partnership | Technology access accelerates sonic variant development for brands lacking in-house transducer engineering capabilities. |
Study Parameters
A spread of perspectives from dental equipment distributors, long-term care facility procurement managers, biomedical engineers at OEM manufacturers, and regulatory affairs specialists at powered oral care device firms converged on the working assumptions. Primary interview intelligence combined with secondary validation from FDA 510(k) submission databases, REACH substance restriction filings, hospital procurement contract disclosures, and customs trade records for oral care hardware. Bottom-up unit economics modeling triangulated against top-down category spend estimates across the analysis window.
Segmentation dimensions modeled include power source architecture, end-user population category, material composition, and technology integration level, with geographic regulatory cluster as an industry-specific overlay. CAGRs were derived through growth rate convergence analysis across the projection horizon. Forecast inputs incorporated caregiver labor cost compression trends, lithium-ion cell pricing trajectories, and dental professional endorsement velocity in German clinical networks.
Underlying assumptions cover stable FDA Class I pathway clarity and REACH antimicrobial compliance timelines, with deviation risk concentrated in biocompatibility certification delays and polymer extrusion tolerance breakthroughs. Practitioners should keep alternative scenarios live as piezoelectric frequency specifications and subscription platform adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Cotton Buds Market
Personal Grooming Products
Sneaker Deodorant Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Global Massage Guns Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Electric Tooth Polisher Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
Pre-Shave Products Market