
 Heated Razor Starter Kit Market | 2026-2036
Heated Razor Starter Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Heated Razor Starter Kit Market Insights
Multi-source component procurement is pivoting toward captive thermal-element production as brands seek supply security. GilletteLabs leverages in-house ceramic heating R&D to protect its premium positioning. Philips anchors European distribution through dedicated appliance retail networks. Braun sustains German engineering credibility with precision temperature calibration systems.
A heated razor starter kit comprises a powered handle with integrated thermal elements, replaceable blade cartridges, and charging or battery systems designed to deliver elevated blade temperatures during facial or body shaving. The device typically operates between 43°C and 50°C to soften keratin and reduce tug-related irritation, serving consumers who prioritize comfort over basic hair removal economics. Electric razor configurations command the dominant revenue share due to higher unit prices and recurring cartridge attachment rates. Thermal heating technology leads functional differentiation, while moisture technology variants capture faster growth among users with sensitive skin conditions. Retail box packaging retains volume leadership, though eco-friendly packaging is gaining shelf space in European and North American premium channels.
FDA oversight of electrical personal grooming devices governs thermal safety thresholds and battery stability standards in the United States. The EU Green Deal and REACH compliance requirements shape material selections for heating elements and packaging substrates across European markets. China's GB standards and SAMR product safety certifications dictate market access protocols for imported devices. Stakeholders must monitor evolving battery transport regulations and thermal burn-risk litigation trends as product liability frameworks tighten.
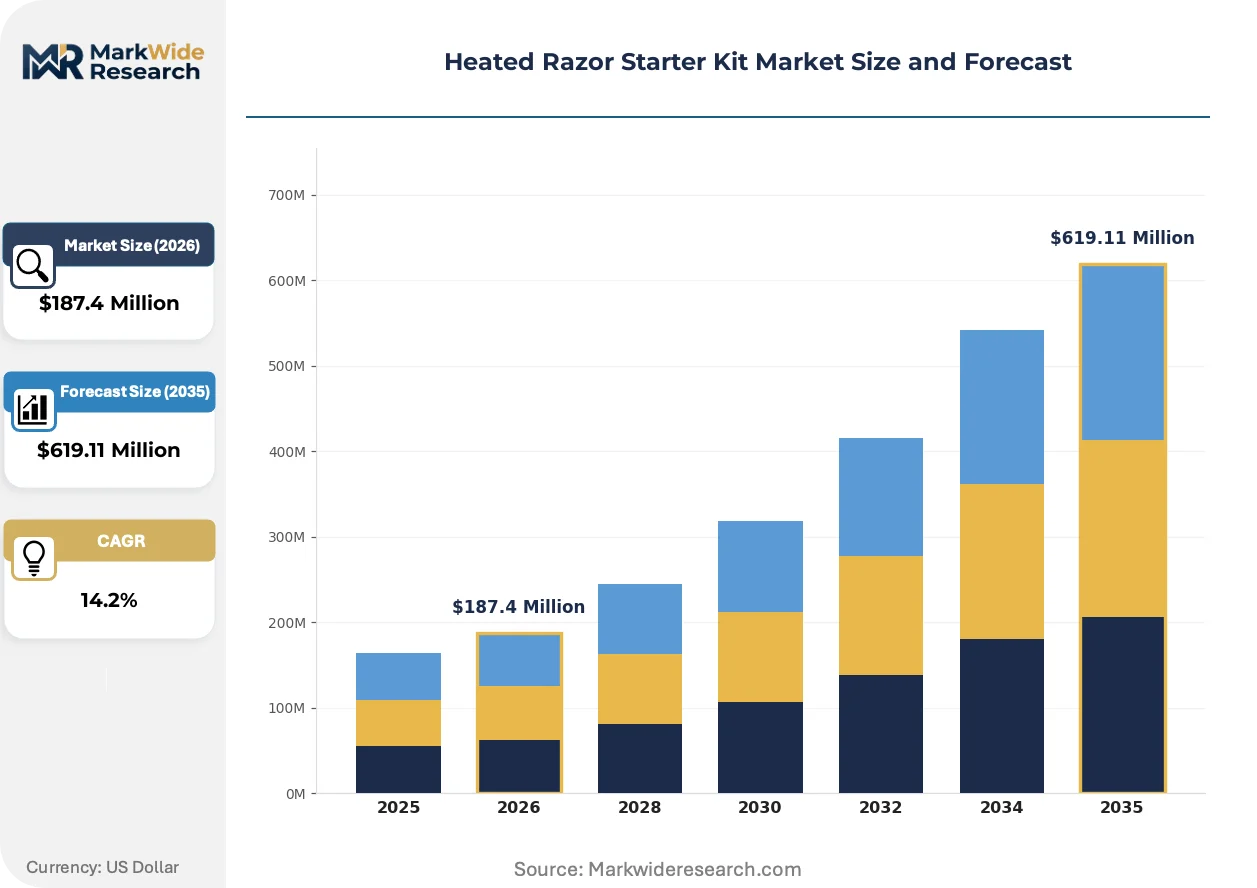
Market Dynamics
The heated razor starter kit market is experiencing a fundamental supply-side restructuring as thermal element manufacturing consolidates among captive producers, forcing brands to secure proprietary ceramic heating R&D or risk margin compression from component shortages.
Growth Catalysts
- EU Green Deal packaging mandates:European regulators are accelerating material transitions toward recyclable substrates, creating first-mover advantage for brands with compliant supply chains already operational.
- Professionalized male grooming routines:Men are expanding daily regimens beyond basic hair removal toward comfort-optimized experiences, elevating willingness to pay for thermal-assisted shaving systems.
- Ceramic heating element advances:In-house thermal R&D capabilities are differentiating premium positioning as brands protect intellectual property around precision temperature calibration systems.
Market Restraints
- Input cost volatility:Rare earth materials essential for ceramic heating elements face price instability tied to concentrated mining operations in specific Asian supply basins.
- Technical limitation:Battery thermal stability under sustained heating cycles creates engineering constraints that extend product development timelines and elevate failure-rate risks.
- Regulatory friction:FDA electrical personal grooming device standards impose thermal safety threshold testing that adds certification duration and compliance expenditure for market entry.
Strategic Opportunities
- Underpenetrated French and Italian markets:Southern European male grooming penetration remains below German and UK benchmarks, presenting expansion whitespace for premium appliance retail networks.
- Moisture technology convergence:Sensitive skin variants combining thermal heating with hydration delivery systems are capturing faster growth among dermatological-condition users.
- Subscription cartridge replenishment:Direct-to-consumer blade attachment programs are displacing traditional retail replenishment, locking in recurring revenue and reducing customer acquisition costs.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized battery-thermal integration expertise required for safe heating element design commands premium compensation and extended recruitment cycles.
- REACH compliance timeline compression:ECHA substance restrictions on heating element materials are accelerating reformulation deadlines, forcing simultaneous product redesign and certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heated Razor Starter Kit Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Razor, Electric Razor, Cartridge Razor, Disposable Razor End User: Men, Women, Professionals, Personal Use Technology: Thermal Heating, Moisture Technology, Moisturizing Strip, Vibration Technology Packaging Type: Retail Box, Blister Pack, Eco-friendly Packaging, Bulk Packaging |
| Companies Covered | GilletteLabs, Philips, Braun, Remington, Wahl, Andis, BaByliss, MANGROOMER, Schick, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heated Razor Starter Kit Market Trends and Innovations
Thermal technology architectures are fragmenting as brands pursue divergent paths toward heating efficiency, battery optimization, and regulatory compliance, creating distinct competitive moats around proprietary R&D investments.
Ceramic heating element miniaturization is decentralizing thermal control from centralized handle units toward distributed blade-cartridge integration. Premium male grooming segments in the United States are adopting cartridge-embedded heating at accelerated replacement cycles. This architecture is decentralizing manufacturing complexity toward component suppliers with precision micro-ceramic capabilities, compressing assembly margins for final-device assemblers.
REACH substance restrictions governing heating element materials are reshaping European procurement specifications. Industrial consequence includes forced transitions away from legacy thermal conductors toward compliant ceramic alternatives. Sensitive-skin product categories face the steepest reformulation burden, with brands accelerating ECHA pre-registration submissions to maintain shelf access.
Subscription-based cartridge replenishment is restructuring buyer relationships toward locked-in consumption patterns. Traditional retail pharmacy and big-box channels are losing replenishment traffic to brand-direct portals. This behavioral shift concentrates most visibly in United States urban corridors where delivery logistics infrastructure supports same-day blade replacement fulfillment.
Heated Razor Starter Kit Market Segmentation
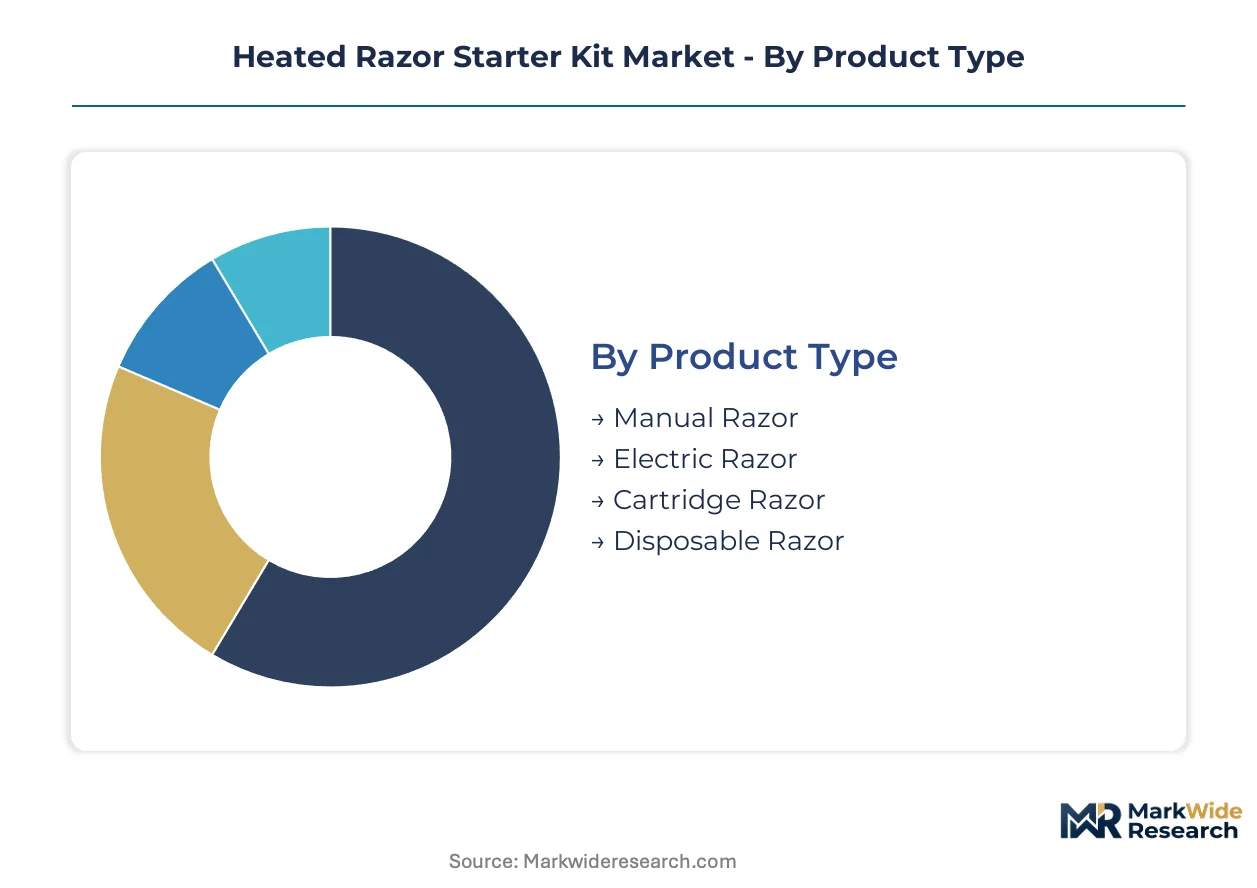
Segmentation in the heated razor starter kit market reveals divergent capital requirements and margin profiles across product architectures. Manufacturers must align R&D expenditure with the specific thermal engineering demands of each configuration to capture sustainable returns.
Product Type:
Electric razor configurations demand the heaviest upfront investment due to integrated battery systems, precision temperature calibration modules, and recurring firmware development cycles.
- Electric Razor:Powered handles with embedded ceramic heating elements and lithium-ion battery packs command premium price positioning. Demand concentrates in United States metropolitan markets where male consumers prioritize comfort-optimized grooming experiences and demonstrate willingness to pay for thermal-assisted systems.
- Manual Razor:Non-powered handles with passive thermal retention materials require minimal electronic engineering investment. Growth is accelerating in European markets subject to EU Green Deal packaging mandates, where simpler mechanical designs ease compliance transitions toward recyclable substrates.
- Cartridge Razor:Replaceable blade systems with standardized handle interfaces.
- Disposable Razor:Single-use thermal elements with limited heating duration.
Electric razor configurations absorb the bulk of installed capacity; manual razor variants are expanding most quickly in regulatory-constrained European supply chains.
End User:
Professional grooming services represent the highest-margin customer type, with barbershops and salons requiring commercial-grade durability and extended warranty terms that justify elevated procurement budgets.
- Men:The dominant consumer base for thermal-assisted shaving systems, with professionalized daily regimens driving replacement cycle compression. United States urban corridors show the steepest adoption curves as subscription-based cartridge replenishment displaces traditional retail pharmacy traffic.
- Professionals:Licensed barbers and aestheticians operating commercial establishments. Demand clusters in Germany and United Kingdom where premium appliance retail networks anchor distribution, with buyers prioritizing precision temperature calibration and extended-duty cycle reliability.
- Women:Body shaving and sensitive-skin applications.
- Personal Use:Individual consumers purchasing for non-commercial household application.
Men dominate current revenue concentration; professional end users are climbing the fastest as service-sector grooming formalization spreads across Western European markets.
Technology:
Thermal heating platforms require the most substantial R&D commitment due to ceramic element miniaturization, battery-thermal integration engineering, and FDA electrical personal grooming device certification protocols.
- Thermal Heating:Active ceramic elements delivering sustained blade temperatures between 43°C and 50°C to soften keratin and reduce tug-related irritation. Demand concentrates in United States premium channels where consumers prioritize comfort over basic hair removal economics, with brands protecting intellectual property around in-house thermal R&D capabilities.
- Moisture Technology:Hydration delivery systems combined with thermal assistance for sensitive-skin conditions. Growth is gaining share fastest among dermatological-condition users in France and Italy, where underpenetrated male grooming markets present expansion whitespace for convergent product architectures.
- Moisturizing Strip:Passive lubrication strips with limited thermal interaction.
- Vibration Technology:Oscillating mechanical assistance without active heating elements.
Thermal heating absorbs the bulk of patent activity and capital deployment; moisture technology convergence is expanding most quickly among clinically positioned product lines.
Packaging Type:
Eco-friendly packaging formats carry the steepest compliance engineering burden as REACH substance restrictions and EU Green Deal directives force material transitions away from legacy petroleum-based substrates.
- Eco-friendly Packaging:Recyclable substrates and biodegradable materials engineered for heating element protection without environmental persistence. Demand is gaining shelf space fastest in European and North American premium channels as ECHA pre-registration submissions accelerate to maintain market access.
- Retail Box:Conventional cardboard and plastic composite packaging retaining volume leadership. United States big-box and pharmacy channels continue to favor established formats, though brand-direct portals are displacing replenishment traffic in urban corridors with same-day delivery infrastructure.
- Blister Pack:Thermoformed plastic display packaging for retail visibility.
- Bulk Packaging:Commercial-quantity formats for professional establishment procurement.
Retail box formats retain the bulk of current shipment volume; eco-friendly packaging is expanding most quickly under regulatory compression across European supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers drive the majority of premium thermal-assisted grooming expenditure, with urban corridors showing the steepest adoption curves for subscription-based cartridge replenishment models.
United States
FDA electrical personal grooming device standards govern thermal safety thresholds and battery stability certification, extending market entry timelines for imported devices. New York and Los Angeles metropolitan clusters concentrate the highest subscription penetration, where same-day blade replacement logistics anchor customer retention.
Germany
REACH compliance requirements and EU Green Deal packaging mandates accelerate material transitions toward recyclable substrates across appliance retail networks. Bavaria and North Rhine-Westphalia host precision engineering clusters where temperature calibration R&D facilities supply thermal element manufacturers.
United Kingdom
Professional barbershop demand for commercial-grade durability drives procurement of extended-warranty thermal systems in Greater London and Manchester grooming service corridors. ECHA substance restrictions on heating element materials compress reformulation deadlines for brands maintaining shelf access.
France
Underpenetrated male grooming penetration relative to German benchmarks creates expansion whitespace for moisture-technology convergent products targeting dermatological-condition users. Île-de-France retail channels show accelerating eco-friendly packaging adoption under EU directive pressure.
Italy
Sensitive-skin product categories face steep REACH-driven reformulation burdens as ECHA pre-registration submissions accelerate. Lombardy and Emilia-Romagna industrial zones concentrate component suppliers with precision micro-ceramic capabilities for distributed blade-cartridge integration.
Heated Razor Starter Kit Market Competitive Landscape
Captive thermal-element production dominates the current landscape as brands secure proprietary ceramic heating R&D capabilities. The vendor base consolidates around three strategic archetypes: multinational appliance conglomerates with in-house thermal engineering divisions, specialized grooming device manufacturers reliant on external component sourcing, and component suppliers pivoting toward distributed micro-ceramic integration. M&A activity targets thermal engineering talent pools, while capacity expansion concentrates in European supply chains responding to REACH compliance timelines.
Among multinational appliance conglomerates, GilletteLabs and Philips exemplify the captive-R&D archetype, each protecting premium positioning through in-house thermal element development. Braun anchors the precision-engineering tier within German manufacturing credibility. These three entities represent distinct competitive moats around proprietary temperature calibration systems and battery-thermal integration expertise.
| Leading Market Players |
|---|
| GilletteLabs |
| Philips |
| Braun |
| Remington |
| Wahl |
| Andis |
| BaByliss |
| MANGROOMER |
| Schick |
| Others |
Pricing and Supply Chain Analysis
Captive thermal-element production anchors supply positioning and pricing power across the heated razor starter kit market, with brands controlling in-house ceramic heating R&D commanding premium positioning while outsourced component buyers absorb margin compression from concentrated rare earth supply basins.
Pricing Analysis
Extended warranty bundling separates premium electric configurations from unbundled manual alternatives, with commercial-grade durability packages justifying elevated procurement budgets among professional barbershop buyers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and after-sales service inclusion. Pricing pressure stems from rare earth material cost volatility tied to concentrated mining operations, compressing margins for brands without captive thermal R&D. Individual consumers purchasing through brand-direct subscription portals demonstrate lowest price sensitivity, while manual razor buyers in regulatory-constrained European markets exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke fulfillment patterns, with Bavarian precision engineering clusters feeding thermal element manufacturers and New York metropolitan logistics infrastructure supporting same-day blade replacement. Ceramic heating element production draws from rare earth mining operations concentrated in specific Asian supply basins, while lithium-ion battery packs rest on South Korean and Japanese cell manufacturing. Single-source vulnerability in thermal conductor materials creates structural risk exposure. Distribution runs through dedicated appliance retail networks in Europe and brand-direct portals displacing traditional pharmacy channels in United States urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
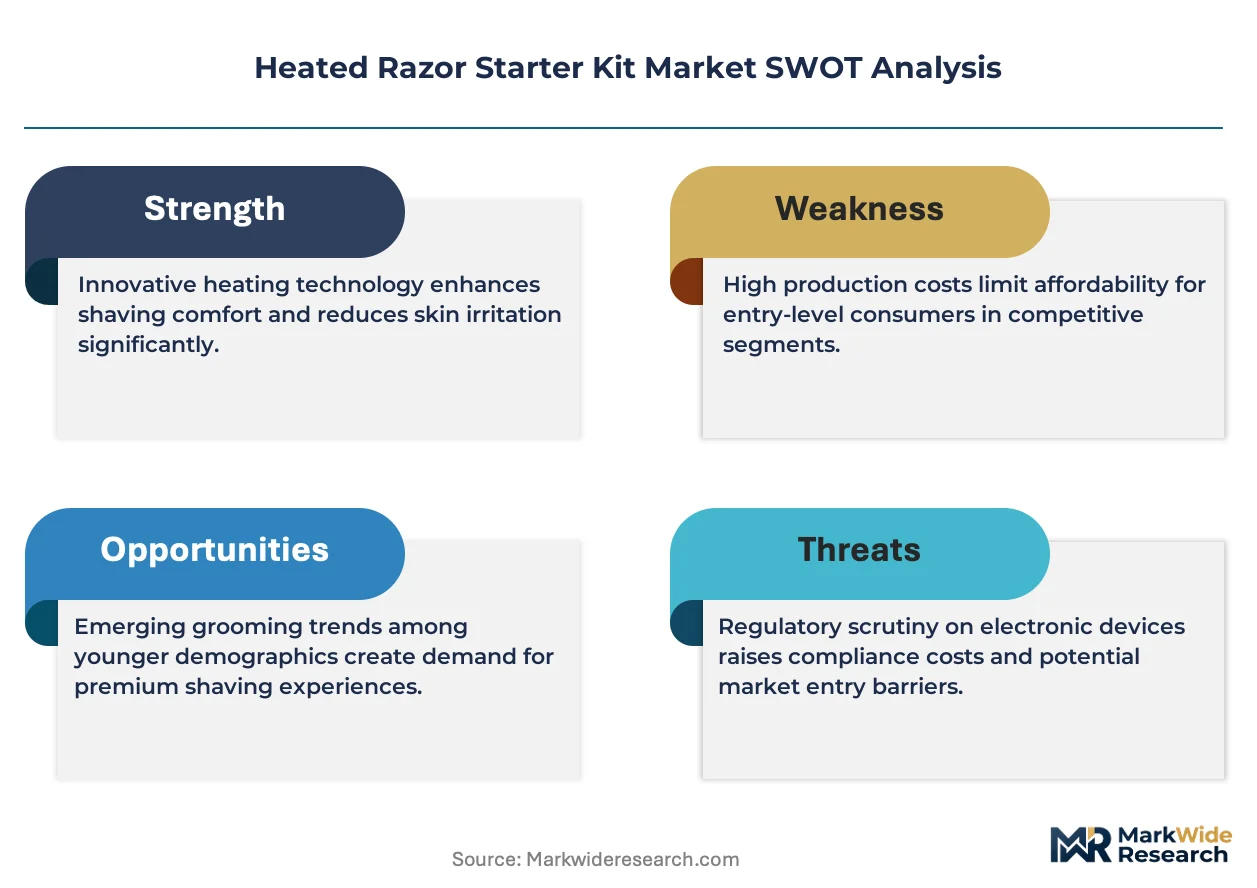
REACH compliance timelines and EU Green Deal packaging mandates have erected a cost-of-compliance barrier that favors incumbent players with established regulatory affairs infrastructure and pre-registered material portfolios.
For Market Incumbents: Anchor premium positioning through accelerated ECHA pre-registration submissions for heating element materials, protecting shelf access against reformulation-driven displacement. Deepen captive thermal R&D capabilities to defend against margin compression from rare earth price volatility, while expanding precision temperature calibration patent portfolios to create defensible moats around battery-thermal integration expertise. For New Entrants and Emerging Players: Moisture technology convergence offers a technology-first wedge into underpenetrated French and Italian male grooming markets, where dermatological-condition users remain underserved by pure thermal offerings. Target professional barbershop segments in Greater London and Manchester corridors with commercial-grade durability positioning, leveraging extended warranty terms to justify elevated procurement budgets against incumbent consumer-grade alternatives. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational appliance conglomerates seeking thermal engineering talent pools, with mid-cycle timing favoring targets with ECHA-compliant material portfolios already operational. Long-term viability hinges on subscription-based cartridge replenishment infrastructure capturing recurring revenue streams. Watch FDA thermal safety threshold litigation trends as inflection indicators for product liability framework tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Heating R&D Expansion | In-house thermal element development protects premium positioning against component shortage risks from REACH-driven supply restructuring. |
| Eco-friendly Packaging Transition | EU Green Deal compliance creates first-mover shelf access advantage in German and UK appliance retail networks. |
| Subscription Cartridge Replenishment | Direct-to-consumer blade programs lock in recurring revenue and reduce customer acquisition costs in New York and Los Angeles corridors. |
| Moisture Technology Convergence | Sensitive-skin variants capture faster growth among dermatological-condition users in underpenetrated Southern European markets. |
| Professional Channel Penetration | Commercial-grade durability positioning with extended warranties secures highest-margin barbershop procurement in London grooming service corridors. |
Research Methodology
Multi-period observation of ceramic heating element patent filings, ECHA pre-registration submission timelines, and subscription cartridge replenishment adoption rates anchored the trend analysis, supplemented by interviews with thermal engineering directors, appliance retail category managers, professional barbershop procurement officers, and regulatory affairs leads at grooming device manufacturers. Secondary validation drew from FDA electrical personal grooming device guidance documents, EU Green Deal implementation directives, REACH substance restriction updates, and customs records tracking rare earth material import flows. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from premium channel shipment data.
Segment-weighting approaches distributed value projections across electric razor configurations with embedded battery systems, manual variants with passive thermal retention, and moisture technology convergent products targeting sensitive-skin applications. Technology adoption curves, regulatory compliance timeline compression, and professional grooming service formalization patterns fed into CAGR derivation across the analysis window. Geographic clustering captured United States subscription penetration, German precision engineering concentration, and Southern European underpenetration whitespace.
Several conditions sit outside the modeled scope, including unannounced battery transport regulation revisions, thermal burn-risk litigation outcomes, and abrupt rare earth export restriction implementations. Forecasts reflect documented assumptions around REACH compliance deadline adherence and ceramic heating element miniaturization feasibility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Hand Massager Market
Personal Grooming Products
Portable Massage Devices Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Electric Hair Brush Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Toothpaste Tablet Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Latin America Hand Soap Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Facial Hair Care Wipes Market
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
Handheld Massager Market
Personal Grooming Products
Antibacterial Soap Market