
 Nose & Ear Hair Trimmers Market | 2026-2036
Nose & Ear Hair Trimmers Market Size, Share, and Industry Trends Forecast 2026-2036
Nose & Ear Hair Trimmers Market Insights
Ceramic blade materials are repositioning product economics away from traditional metal cutting systems by reducing friction heat and extending edge retention. Panasonic leverages vertical integration into motor and blade manufacturing to sustain cost advantages across Asian supply chains. Wahl anchors its competitive stance through specialized professional-grade trimmer lines that dominate barbershop procurement in North America. Philips Norelco differentiates via rotary blade platforms that occupy the premium personal-use tier across European retail channels.
Nose and ear hair trimmers are compact grooming devices employing rotary or foil blade mechanisms, typically powered by rechargeable lithium-ion cells or disposable batteries, designed for safe nasal and auditory canal hair removal without skin abrasion. Electric trimmers incorporating micro-cut technology lead volume sales through pharmacy and supermarket channels, while vacuum-assisted variants represent the fastest-growing product type by capturing shed hair for enhanced hygiene. Online stores now control the largest margin pool by eliminating distributor markups, though specialty retailers sustain higher average selling prices through hands-on demonstration.
FDA cosmetic device regulations govern blade safety and electrical compliance for products entering the United States, while CE marking under EU MDR requirements shapes European market access protocols for battery-operated personal care devices. Japan's METI enforces PSE certification for lithium-ion powered trimmers, creating additional compliance layers for imported electronics. Stakeholders must monitor evolving battery transportation regulations and blade material disclosure mandates as sustainability frameworks tighten across major consumer markets.
Market Dynamics
Stainless steel blade alloys are displacing carbon steel variants across manufacturing footprints, forcing retooling investments and reshaping supplier qualification protocols under FDA cosmetic device guidelines.
Growth Catalysts
- Rotary blade platforms:Rotary mechanisms deliver safer nasal canal insertion geometry, expanding personal-use adoption among men aged 25-45 in premium retail channels.
- FDA cosmetic device guidelines:Clear blade safety and electrical compliance standards reduce market entry friction for qualified manufacturers targeting United States pharmacy distribution.
- Lithium-ion cell chemistry:Rechargeable power systems extend operational runtime between charges, supporting cordless convenience demands in German and Japanese household markets.
Market Restraints
- Ceramic blade cost premiums:Advanced ceramic cutting materials command 40-60% input cost premiums over metal equivalents, compressing margin structures for mid-tier product lines.
- Japanese PSE certification:METI-enforced lithium-ion battery safety testing creates 90-120 day additional compliance timelines for imported electronics entering Japan.
- Manual tweezer substitution:Low-cost manual alternatives retain volume share in price-sensitive consumer segments across developing Asian markets.
Strategic Opportunities
- Vacuum-assisted capture systems:Integrated hair collection chambers address hygiene concerns in professional barbershop environments, opening premium procurement channels.
- Online direct-to-consumer channels:E-commerce platforms eliminate distributor markups, enabling margin capture previously lost to specialty retailer networks.
- EU MDR CE marking alignment:Harmonized European battery-operated device standards create pathway for unified product certification across Germany, France, and Netherlands markets.
Industry Challenges
- Micro-motor precision engineering:Miniaturized drive systems require specialized tooling expertise concentrated in Japanese and German industrial clusters, creating talent access bottlenecks.
- Blade material disclosure mandates:Evolving sustainability frameworks demand granular supply chain transparency for alloy composition and sourcing origins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nose & Ear Hair Trimmers Market |
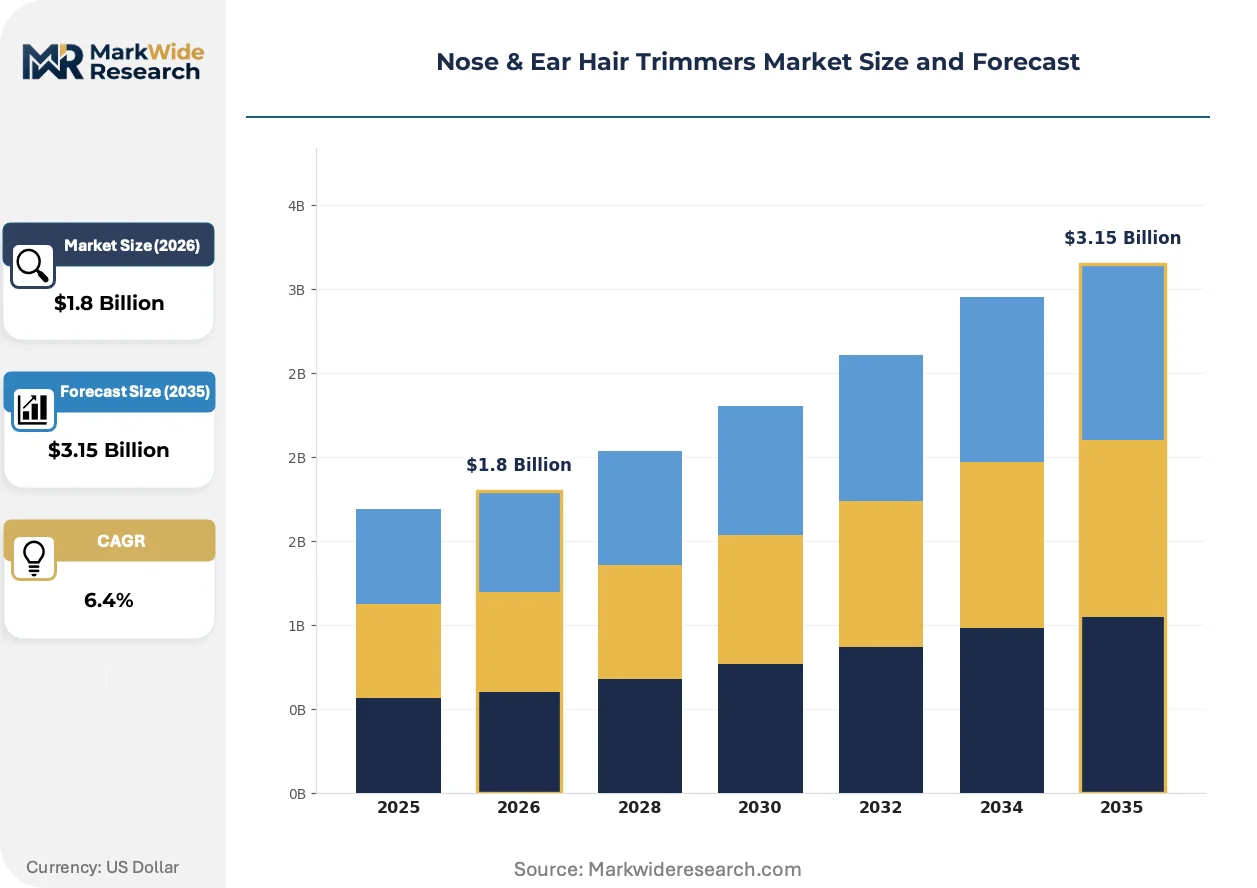
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Trimmers, Electric Trimmers, Battery-Operated Trimmers, Vacuum Trimmers End User: Personal Use, Salons, Barbershops, Dermatology Clinics Technology: Rotary Blades, Foil Blades, Laser Technology, Micro-cut Technology Distribution Channel: Online Stores, Supermarkets, Specialty Retailers, Pharmacies |
| Companies Covered | Philips Norelco, Panasonic, Conair, Manscaped, Wahl, Zorami, ToiletTree Products, LAXCARE, FlePow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nose & Ear Hair Trimmers Market Trends and Innovations
Ceramic blade materials and vacuum capture systems are compressing traditional metal-cutting value chains while opening premium tier positioning. Regulatory alignment across FDA, EU MDR, and METI frameworks is standardizing compliance investments.
Micro-cut technology is automating blade edge refinement at micron-level tolerances previously requiring manual finishing. Personal-use buyers in United States pharmacy channels are adopting these systems fastest, with rotary platform manufacturers capturing shelf space from foil alternatives. This precision automation is compressing quality variation between production batches and reducing warranty claim rates.
EU MDR requirements for battery-operated personal care devices are mandating enhanced electrical safety documentation and post-market surveillance protocols. Manufacturers serving European retail channels must now maintain technical files beyond the previous Medical Device Directive scope. German and French importers are consolidating supplier bases to reduce audit burden duplication across multiple vendor qualifications.
Specialty retailer demonstration models are losing share to pharmacy and supermarket self-selection as buyer confidence in standardized safety ratings grows. Hands-on trial environments that sustained premium pricing in urban shopping districts are being displaced by video review-driven online purchases. This channel rotation is most visible in United States and Japanese markets where e-commerce penetration in personal grooming exceeds 35% of category volume.
Nose & Ear Hair Trimmers Market Segmentation
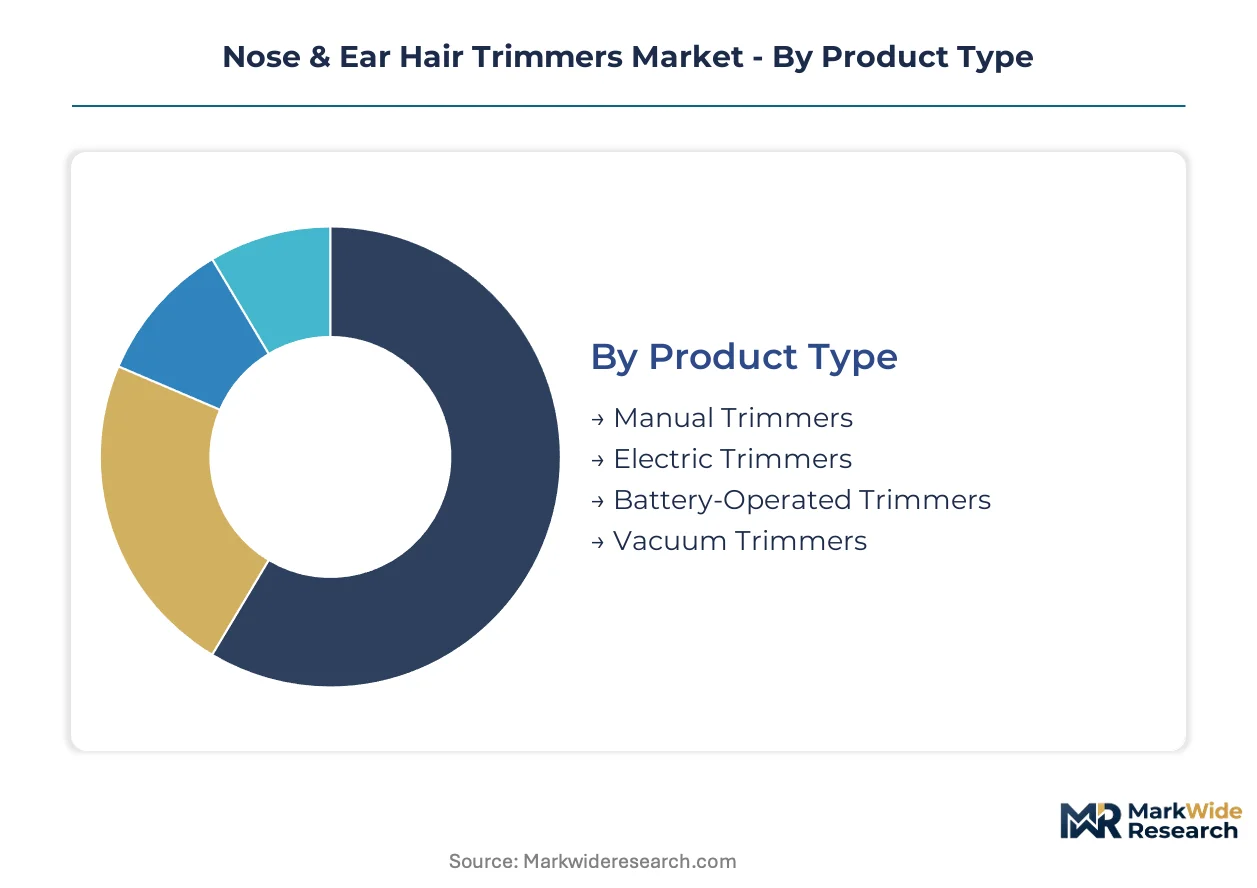
Nose and ear hair trimmers fragment across four distinct axes: cutting mechanism, power source, professional versus personal application, and blade engineering approach. Each dimension creates divergent margin profiles and compliance requirements that reshape competitive positioning.
Product Type:
Power delivery architecture distinguishes trimmer economics, with rechargeable systems commanding premium shelf placement against disposable alternatives.
- Manual Trimmers:Spring-loaded mechanical cutting heads eliminate battery dependency entirely. Demand concentrates in price-sensitive Asian markets where retail distribution favors low-unit-cost personal grooming tools.
- Electric Trimmers:Corded AC-powered motors deliver sustained torque for dense hair removal. German and Japanese household markets favor these systems for bathroom vanity installation where outlet access is standardized.
- Battery-Operated Trimmers:Disposable alkaline cell configurations dominate pharmacy impulse purchase displays across United States retail channels. Portability without recharge infrastructure drives adoption among frequent travelers.
- Vacuum Trimmers:Integrated suction chambers capture shed hair during operation, addressing hygiene concerns in professional barbershop environments. PSE certification requirements from Japan's METI add compliance complexity for imported lithium-ion variants.
Electric trimmers lead on scale; vacuum trimmers lead on momentum.
End User:
Professional service settings impose durability and sanitization standards that diverge sharply from personal-use specifications.
- Personal Use:Compact form factors prioritize single-hand operation and bathroom counter storage. United States pharmacy channels capture the largest volume share through self-selection retail formats.
- Salons:Commercial-grade motor systems withstand continuous daily operation. FDA cosmetic device guidelines govern blade safety documentation for professional equipment entering United States beauty service markets.
- Barbershops:Vacuum-assisted capture systems reduce post-service cleanup labor. Procurement concentrates through specialized beauty supply distributors rather than direct manufacturer relationships.
- Dermatology Clinics:Medical-adjacent settings demand sterilizable stainless steel construction and traceable alloy certification. EU MDR compliance documentation extends beyond standard CE marking for battery-operated personal care devices.
Personal use leads on scale; barbershops lead on momentum.
Technology:
Blade geometry and edge refinement methods determine cutting performance, skin safety margins, and manufacturing cost structures.
- Rotary Blades:Cylindrical cutting heads with circumferential edges enable safe nasal canal insertion. European retail channels favor these platforms for premium personal-use positioning.
- Foil Blades:Oscillating cutters beneath perforated metal screens deliver close trimming with reduced abrasion risk. Japanese manufacturers concentrate production expertise for micron-level foil perforation tooling.
- Laser Technology:Photonic hair reduction systems target follicle disablement rather than mechanical cutting. Regulatory classification ambiguity under FDA cosmetic device versus medical device definitions constrains United States market entry.
- Micro-cut Technology:Automated blade edge refinement achieves sub-100-micron tolerances previously requiring manual finishing. German industrial clusters supply precision grinding equipment for this manufacturing tier.
Rotary blades lead on scale; micro-cut technology leads on momentum.
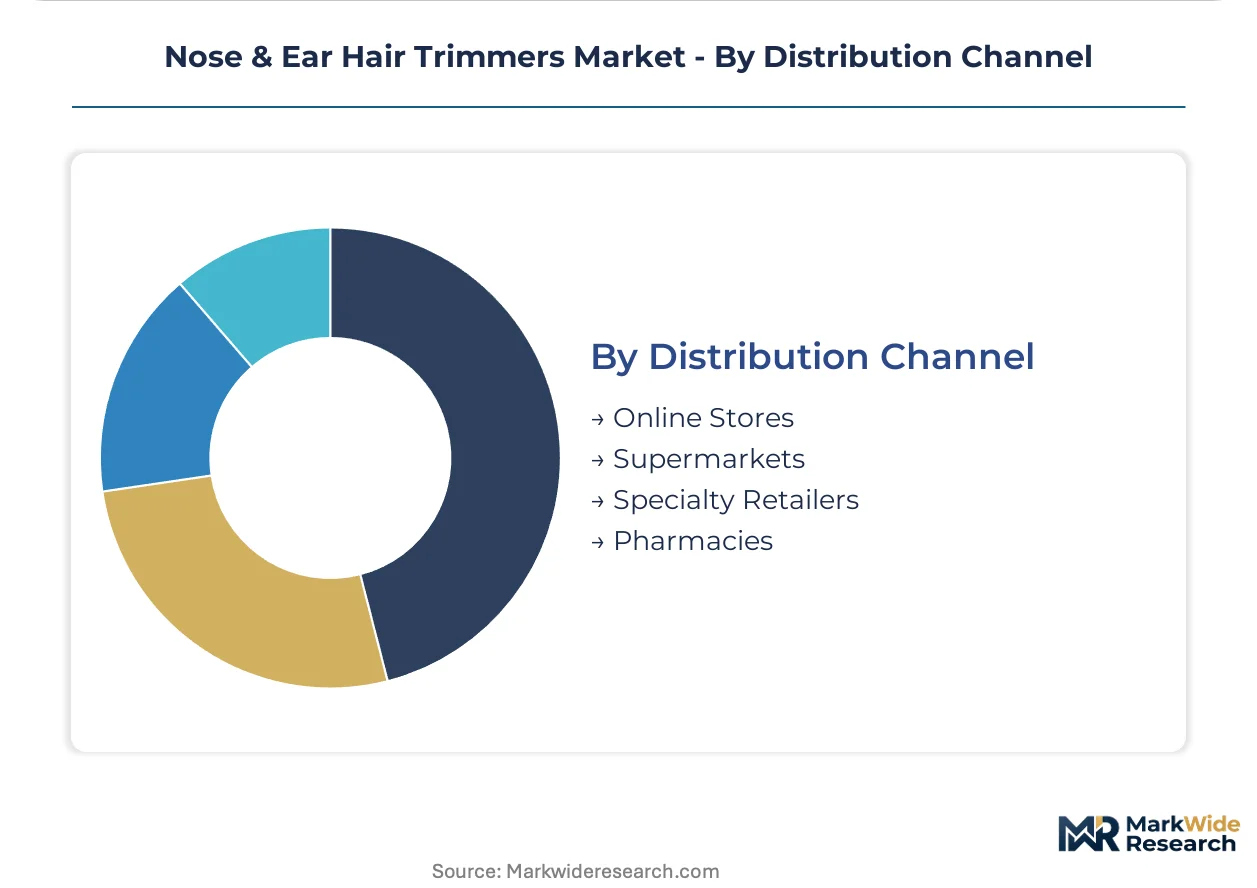
Distribution Channel:
Channel selection determines pricing power, customer education requirements, and working capital intensity for manufacturers.
- Online Stores:Direct-to-consumer platforms eliminate distributor margin stacking. Video review content substitutes for hands-on trial previously required for purchase confidence.
- Supermarkets:Mass-market placement reaches price-sensitive segments through high-frequency shopping trips. Battery-operated trimmers dominate this channel's unit economics.
- Specialty Retailers:Demonstration environments sustain premium pricing through tactile product evaluation. Urban shopping district locations in Japan and Germany retain this format's relevance.
- Pharmacies:Healthcare-adjacent positioning leverages FDA cosmetic device safety ratings for buyer reassurance. United States chains capture the largest margin pool through private label procurement.
Pharmacies lead on scale; online stores lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka-based manufacturing clusters anchor blade precision engineering for rotary and foil trimmer platforms serving premium household segments across developed economies.
United States
Pharmacy channel dominance and barbershop procurement standards drive demand for vacuum-assisted and professional-grade trimmers. FDA cosmetic device guidelines govern blade safety documentation and electrical compliance for battery-operated personal care devices. California and New York metropolitan areas concentrate e-commerce fulfillment infrastructure for direct-to-consumer grooming brands.
Germany
Bathroom vanity installation standards and cordless convenience preferences favor rechargeable lithium-ion systems in household markets. EU MDR requirements mandate enhanced electrical safety documentation and post-market surveillance for battery-operated devices. Bavarian industrial clusters supply precision grinding equipment for micro-cut blade manufacturing.
Japan
Urban shopping districts sustain specialty retailer demonstration formats alongside high e-commerce penetration in personal grooming. METI enforces PSE certification for lithium-ion powered trimmers, adding compliance timelines for imported electronics. Tokyo and Osaka metropolitan areas concentrate micron-level foil perforation tooling expertise.
United Kingdom
Self-selection retail formats in pharmacy and supermarket channels capture volume share for battery-operated impulse purchases. CE marking under EU MDR protocols shapes market access for personal care electronics despite post-Brexit regulatory divergence. Greater London anchors specialty beauty supply distribution networks serving professional salon procurement.
South Korea
Compact form factor preferences and travel-oriented portability drive demand for disposable battery configurations. MFDS oversight intersects with consumer electronics safety frameworks for lithium-ion powered grooming devices. Seoul Capital Area manufacturing bases supply precision micro-motors for Asian OEM assembly networks.
Nose & Ear Hair Trimmers Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend blade engineering expertise across adjacent personal grooming categories. The vendor base organizes around three strategic archetypes: vertically integrated electronics conglomerates with captive motor and blade production, specialized professional-grade equipment fabricators with barbershop channel lock-in, and direct-to-consumer brands leveraging video content for purchase conversion. M&A activity concentrates on acquiring precision tooling capabilities, while geographic expansion targets regulatory harmonization across FDA, EU MDR, and METI jurisdictions.
Among Japanese electronics conglomerates, Panasonic exemplifies upstream control over motor and blade manufacturing. Wahl anchors the professional-grade tier through specialized trimmer lines. Philips Norelco occupies the premium personal-use position across European retail channels.
| Leading Market Players |
|---|
| Philips Norelco |
| Panasonic |
| Conair |
| Manscaped |
| Wahl |
| Zorami |
| ToiletTree Products |
| LAXCARE |
| FlePow |
| Others |
Pricing and Supply Chain Analysis
EU battery sustainability disclosure mandates under the EU Green Deal gate qualified supply access and premium-tier pricing power for manufacturers serving European pharmacy and specialty retail channels. Compliance documentation burdens compress margin structures for mid-tier producers while rewarding vertically integrated suppliers with captive cell production.
Pricing Analysis
Input-cost pass-through from lithium-ion cell chemistry and ceramic blade materials shapes tiered pricing across personal-use, professional, and medical-adjacent segments. Price differentiation rests on FDA cosmetic device certification tier and volume procurement scale, with pharmacy private-label buyers commanding steepest discounts. Cost compression in economy-tier battery-operated trimmers is intensifying because manual tweezer substitution retains volume share in developing Asian markets. Dermatology clinics demonstrate least price sensitivity due to sterilizable stainless steel requirements and traceable alloy certification.
Supply Chain Analysis
Japan's local-content rules for PSE-certified electronics reshape sourcing patterns for lithium-ion powered trimmers entering Tokyo and Osaka metropolitan markets. Manufacturing gravity centers on China for motor assembly, Japan for micron-level foil perforation tooling, and Germany for precision grinding equipment. Raw material dependencies draw from rare earth magnet suppliers, stainless steel alloy foundries, and ceramic powder specialists. Single-source vulnerability concentrates in Japanese micro-motor precision engineering clusters. Distribution runs through pharmacy chains in the United States, beauty supply distributors for barbershop procurement, and direct-to-consumer platforms eliminating retailer markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by the demand-shift toward vacuum-assisted capture systems in professional barbershop environments. Premium specifications now dominate procurement criteria over unit-cost minimization.
For Market Incumbents: Deepen backward integration into blade alloy foundries to defend against ceramic material cost premiums compressing mid-tier margins. Lock in barbershop channel control through exclusive vacuum-trimmer distribution agreements before direct-to-consumer brands capture professional procurement. Prioritize FDA cosmetic device guideline compliance investments to maintain pharmacy shelf access against emerging Asian OEMs. For New Entrants and Emerging Players: Direct-to-consumer video marketing routes offer lowest customer acquisition cost for penetrating the United States men aged 25-45 segment. White-space targets include dermatology clinic sterilizable trimmer lines and travel-oriented disposable battery configurations for South Korean portability preferences. Launch through Amazon and TikTok Shop with influencer demonstration content substituting for hands-on trial. For Investors and Strategic Acquirers: Roll-up economics work for precision micro-motor specialists because Japanese and German industrial cluster talent access creates persistent scarcity value. Five-to-ten year viability hinges on regulatory harmonization across FDA, EU MDR, and METI jurisdictions consolidating supplier qualification burdens. Target acquisition archetype: captive foil perforation tooling expertise with existing PSE certification infrastructure. The signal to watch is lithium-ion battery transportation regulation tightening accelerating consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Blade Manufacturing Scale-Up | Panasonic's in-house ceramic production reduces friction heat and extends edge retention for premium tiers. |
| Vacuum Capture System Integration | Wahl's professional-grade lines capture shed hair, reducing barbershop cleanup labor and opening premium procurement. |
| Direct-to-Consumer Channel Launch | Manscaped's video review-driven online sales eliminate distributor markups and capture pharmacy margin pools. |
| EU MDR CE Marking Alignment | Philips Norelco's unified certification across Germany, France, and Netherlands reduces audit burden duplication. |
| Micro-Cut Technology Automation | German precision grinding equipment suppliers enable sub-100-micron blade tolerances for quality batch consistency. |
Research Methodology
Bottom-up personal-use and professional procurement modeling reconciled against top-down motor and blade manufacturing tracking forms the analytical core of this study. Primary interviews with barbershop procurement managers, pharmacy category buyers, biomedical engineers at dermatology clinics, and ceramic blade R&D directors combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, METI PSE certification registries, and pharmacy retail audit data. Triangulation across these sources ensures coverage of both demand-side adoption patterns and supply-side capacity constraints.
Historical trendline analysis of rotary versus foil blade platform adoption rates, rechargeable versus disposable battery configuration mixes, and channel shift velocities from specialty retail to online direct-to-consumer informed the projection framework. Segmentation dimensions modeled include cutting mechanism technology, power source architecture, end-use setting, and distribution channel type across the analysis window. CAGRs derive from fitted growth curves adjusted for regulatory compliance timeline impacts and ceramic material cost trajectory assumptions.
The model assumes a particular technology adoption path; alternative pathways for laser-based photonic hair reduction would alter the outlook if FDA cosmetic device versus medical device classification ambiguity resolves favorably. Forecasts incorporate assumptions regarding lithium-ion cell chemistry cost curves, stainless steel alloy price stability, and barbershop vacuum-trimmer penetration ceilings. Regulatory divergence post-Brexit, Japanese PSE certification backlog extensions, and sustainability disclosure mandate tightening represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Europe Electric Toothbrush Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Electrical Neck Warmer Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Bamboo Toothbrush Market
Personal Grooming Products
North America Hair Styling Tools Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Sexual Lubricant Market
Personal Grooming Products
Facial Hair Care Wipes Market
Personal Grooming Products
Disposable Electric Toothbrushes Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
Shoe Deodorizer Market
Personal Grooming Products
Smart Water Bottle Market