
 France Lip Care Products Market | 2026-2036
France Lip Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
France Lip Care Products Market Intelligence
Aftermarket service revenue from refillable lip care formats is tilting margin pools away from single-use disposable tubes. L'Oréal S.A. leverages its dermo-cosmetic research infrastructure to sustain premium positioning across pharmacy channels. Groupe Clarins SA anchors its lip care portfolio in botanical ingredient narratives that differentiate against synthetic competitors. Beiersdorf AG controls mass-market shelf space through Nivea's established retail presence in French supermarkets.
France lip care products encompass topical formulations designed for lip moisturization, protection, and aesthetic enhancement, typically incorporating emollients such as shea butter, beeswax, or petroleum-derived bases with SPF ratings ranging from 15 to 50. These products serve both therapeutic purposes for chapped lip remediation and cosmetic functions for color deposition and gloss enhancement. Lip balm dominates pharmacy and supermarket channels due to its functional positioning against seasonal dryness, while lip gloss captures younger demographics through social media-driven color trends. Online retail represents the fastest-expanding distribution channel as direct-to-consumer brands bypass traditional wholesale markups.
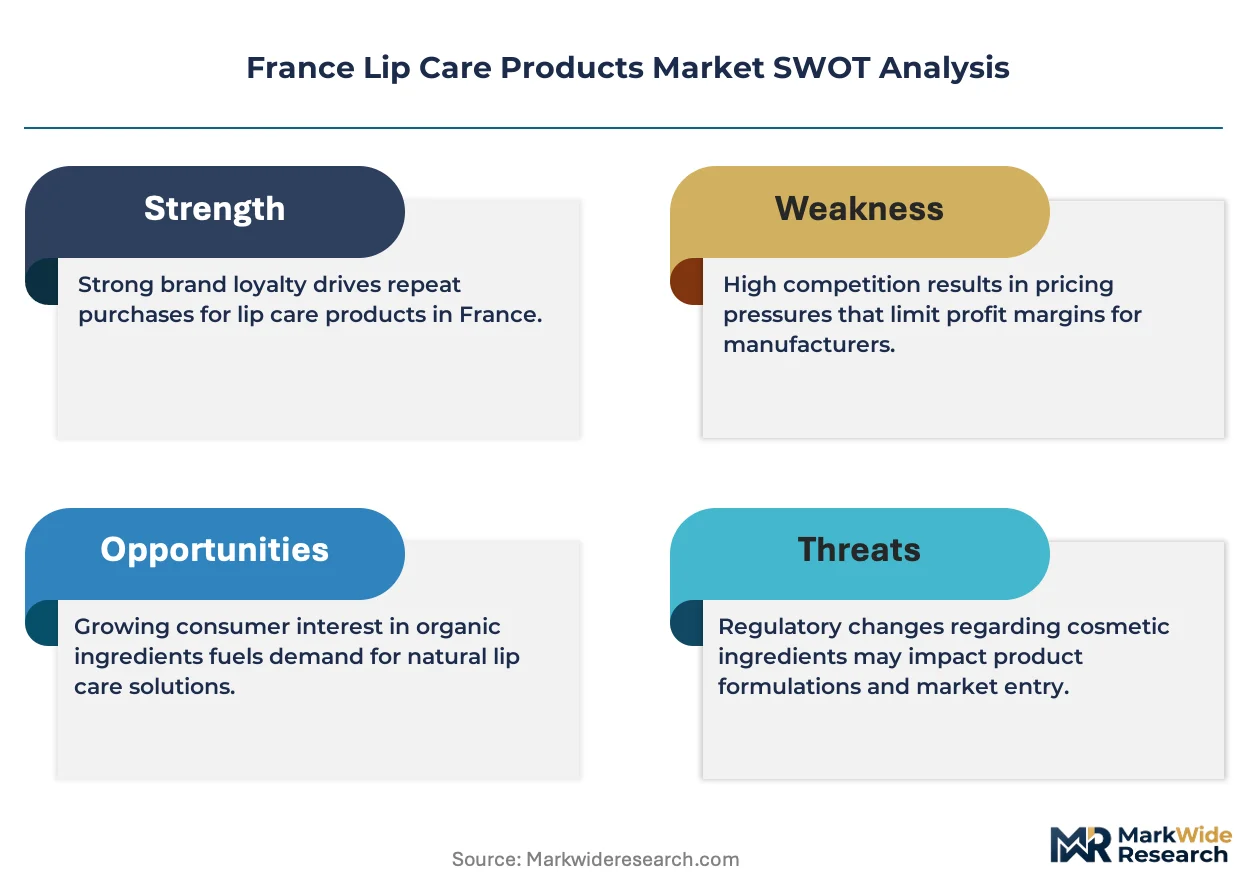
ANSM enforces cosmetic product safety standards that mandate complete ingredient transparency for lip formulations, directly elevating compliance costs for imported brands seeking French market entry. The EU Green Deal's packaging waste directives are pressuring manufacturers to transition toward recyclable or refillable container systems. REACH compliance requirements for chemical substances in cosmetics further constrain formulation choices for colorants and preservatives. Stakeholders must monitor evolving regulatory timelines for microplastic bans in rinse-off cosmetics, as these restrictions will likely extend to lip scrub formulations containing synthetic exfoliating beads.
Market Dynamics
ANSM's tightened cosmetic safety assessments are compressing formulation timelines while pharmacy retail chains expand shelf space for dermo-cosmetic lip treatments, creating a bifurcation between compliance-heavy premium channels and price-sensitive mass retail.
Growth Catalysts
- EU Green Deal packaging directives:Refillable container mandates are accelerating format innovation among domestic manufacturers seeking regulatory alignment ahead of enforcement timelines.
- Île-de-France demand concentration:Parisian premium boutique clustering generates aspirational pull effects that cascade into pharmacy channel trial across metropolitan France.
- SPF integration technology:Photostabilized organic filters are enabling functional lip balm positioning against solar exposure concerns without compromising sensorial attributes.
Market Restraints
- Shea butter price volatility:West African supply disruptions transmit directly into input cost instability for emollient-dependent formulations.
- REACH compliance burden:Colorant and preservative substance restrictions constrain R&D pipelines and extend new product introduction cycles.
- Synthetic wax substitution threat:Petroleum-derived base alternatives face displacement pressure from botanical positioning demands in pharmacy segments.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur underpenetration:Coastal tourism corridors present whitespace for travel-format lip protection with elevated SPF positioning.
- Direct-to-consumer channel innovation:Subscription-based refill programs bypass traditional wholesale markups while capturing recurring revenue streams.
- CSRD sustainability reporting:Mandatory corporate disclosure requirements create competitive differentiation for brands with verified supply chain transparency.
Industry Challenges
- Toxicological assessment talent scarcity:ANSM's enhanced allergen disclosure requirements outpace available cosmetic safety evaluator supply.
- Microplastic ban timeline uncertainty:Pending restrictions on synthetic exfoliants in rinse-off categories create formulation planning paralysis for lip scrub SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Lip Care Products Market |
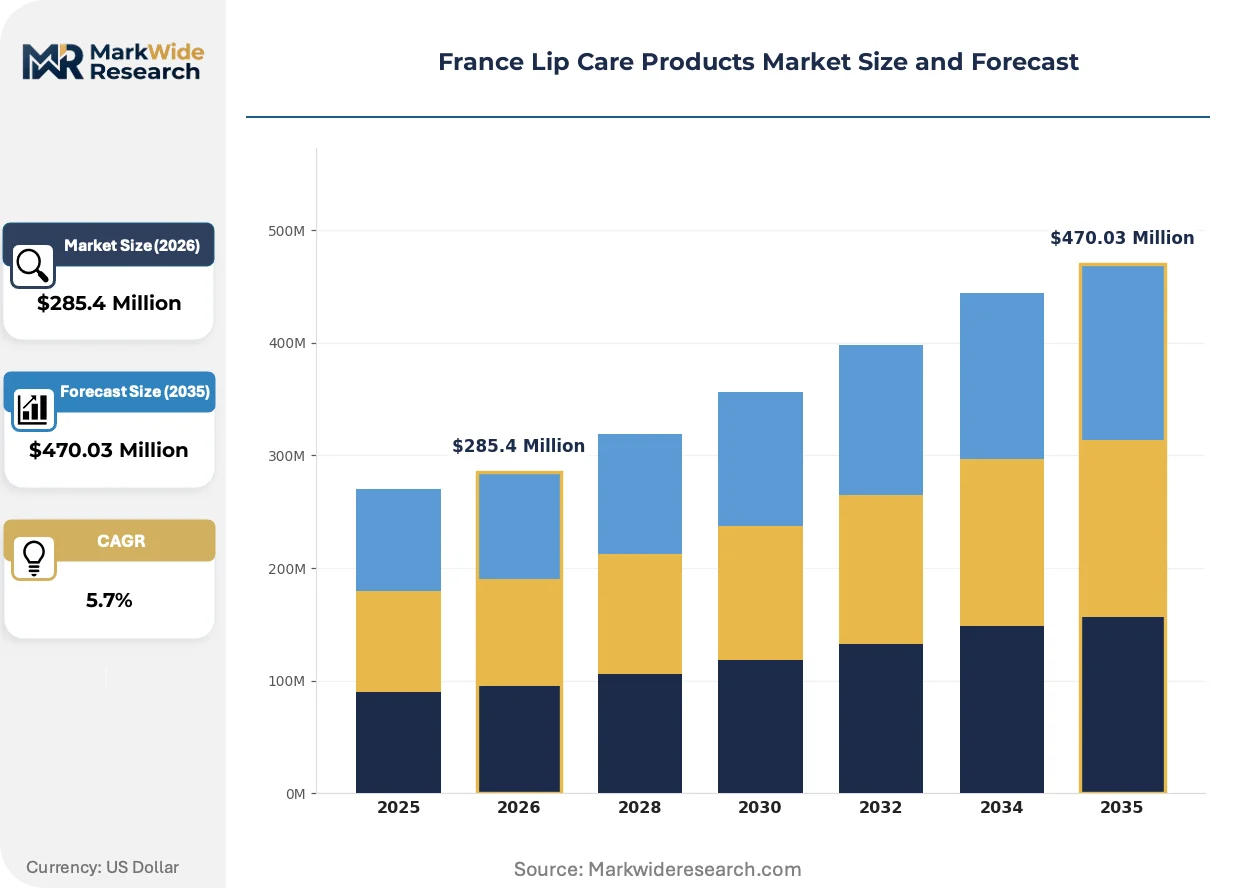
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $470.03 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lip Balm, Lip Gloss, Lip Stick, Lip Scrub Application: Moisturization, Tinting, Protection, Exfoliation End User: Women, Men, Teens, Kids Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Coty Inc., Beiersdorf AG, L'Oréal S.A., Shiseido Co Ltd, Unilever PLC, Groupe Clarins SA, LVMH Moët Hennessy Louis Vuitton, Yves Rocher, The Estée Lauder Companies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Lip Care Products Market Strategic Shifts & Innovations
Digital formulation tools are compressing development cycles while regulatory disclosure mandates and channel disintermediation reshape competitive positioning across pharmacy and direct-to-consumer segments.
Biomimetic lipid complexes are virtualizing traditional petrolatum barrier functions through plant-derived ceramide and phytosterol combinations that replicate stratum corneum architecture. Pharmacy channel buyers in Île-de-France are adopting these alternatives at accelerated pace despite premium positioning. This technology is virtualizing conventional emollient supply relationships by enabling domestic botanical sourcing that bypasses petroleum value chain dependencies.
ANSM's allergen disclosure expansion mandates complete quantitative labeling for 26 fragrance contact sensitizers in leave-on lip products. Industrial consequence includes reformulation costs and label redesign investments that disproportionately burden imported brands unfamiliar with French notification procedures. Mass-market supermarket segments are responding through private label simplification, stripping fragrance entirely to minimize compliance exposure.
Social media-driven color trend cycles are compressing lip gloss SKU lifespans from seasonal to monthly refresh rates. Direct-to-consumer brands with agile manufacturing partnerships are displacing traditional wholesale-dependent competitors unable to match velocity. This pattern concentrates in Parisian urban demographics where TikTok-originated aesthetic trends transmit fastest through peer networks.
France Lip Care Products Market Segmentation
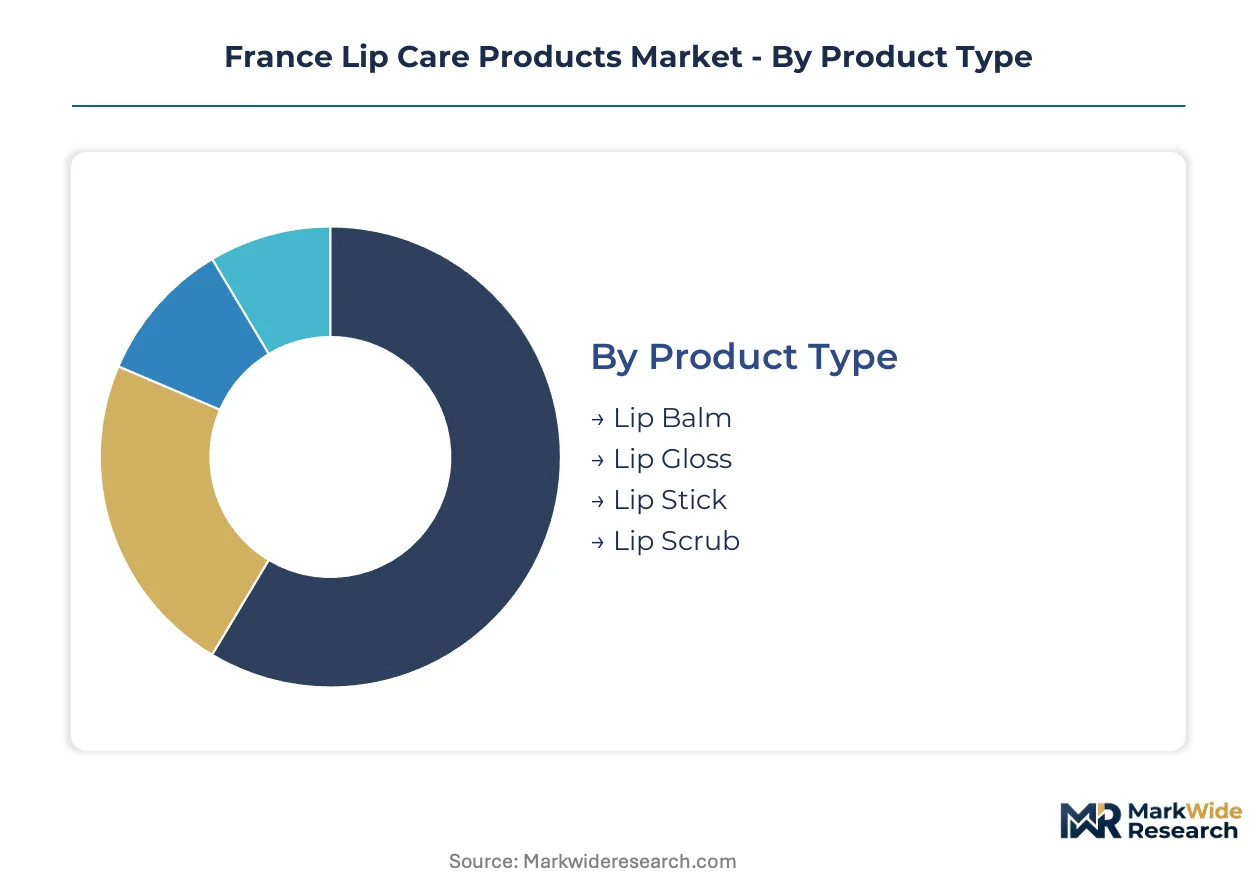
Lip care segmentation in France reveals divergent channel economics between functional pharmacy positioning and aesthetic-driven specialty retail. Each dimension carries distinct margin structures and regulatory exposure that shape portfolio allocation decisions.
Product Type:
Use cases span therapeutic remediation through color cosmetics, with formulation complexity and SPF integration driving channel placement.
- Lip Balm:Emollient-dominant formulations incorporating shea butter, beeswax, or petroleum bases with SPF ratings from 15 to 50. Demand concentrates in pharmacy and supermarket channels across metropolitan France, where seasonal dryness drives repeat purchase cycles and functional positioning justifies premium pricing over private label alternatives.
- Lip Gloss:Gloss-enhancing vehicles delivering color deposition through suspended pigments in viscous oil bases. Parisian urban demographics and teen segments in Île-de-France propel adoption, with TikTok-originated aesthetic trends compressing SKU refresh rates from seasonal to monthly cycles.
- Lip Stick:Solid wax-based color delivery systems with higher pigment load than gloss formats. Established presence in specialty store and department store boutiques.
- Lip Scrub:Exfoliating formulations containing sugar, salt, or synthetic microbeads for dead skin removal. Faces pending ANSM microplastic restrictions that threaten synthetic exfoliant variants.
Established volume favors lip balm; emerging adoption favors lip gloss.
Application:
Cost tiers separate basic hydration from multifunctional protection commanding pharmacy premiums.
- Moisturization:Barrier repair formulations targeting chapped lip remediation through occlusive and humectant combinations. Pharmacy channel concentration in Île-de-France and Provence-Alpes-Côte d'Azur drives premium positioning, with dermo-cosmetic brands leveraging clinical validation for margin protection.
- Protection:Photostabilized organic and mineral filters integrated into daily-wear bases. Coastal tourism corridors and Alpine recreational zones generate concentrated demand for elevated SPF positioning.
- Tinting:Sheer color deposition for aesthetic enhancement without full coverage. Younger demographics in urban centers favor hybrid tint-balm formats.
- Exfoliation:Mechanical or enzymatic dead cell removal preparing lips for color product application. Niche positioning in specialty channels with limited pharmacy penetration.
Pharmacy margins concentrate in protection; online velocity concentrates in tinting.
End User:
Volume distribution reflects demographic-specific channel preferences and price sensitivity differentials.
- Women:Primary volume driver across all channels, with mature segments favoring pharmacy dermo-cosmetics and younger cohorts driving specialty store and online trial. Parisian boutique clustering in Île-de-France generates aspirational pull effects cascading into mass retail.
- Teens:Social media-influenced purchase patterns with high trial frequency and low brand loyalty. Direct-to-consumer subscription models capture recurring revenue from this segment.
- Men:Emerging segment with functional positioning preference driving pharmacy and supermarket trial of unscented, matte-finish formats.
- Kids:Safety-conscious parent purchasers favoring pharmacy channels for allergen-controlled, fragrance-free formulations with gentle emollient bases.
Women anchor current revenue; teens represent the steepest expansion trajectory.
Distribution Channel:
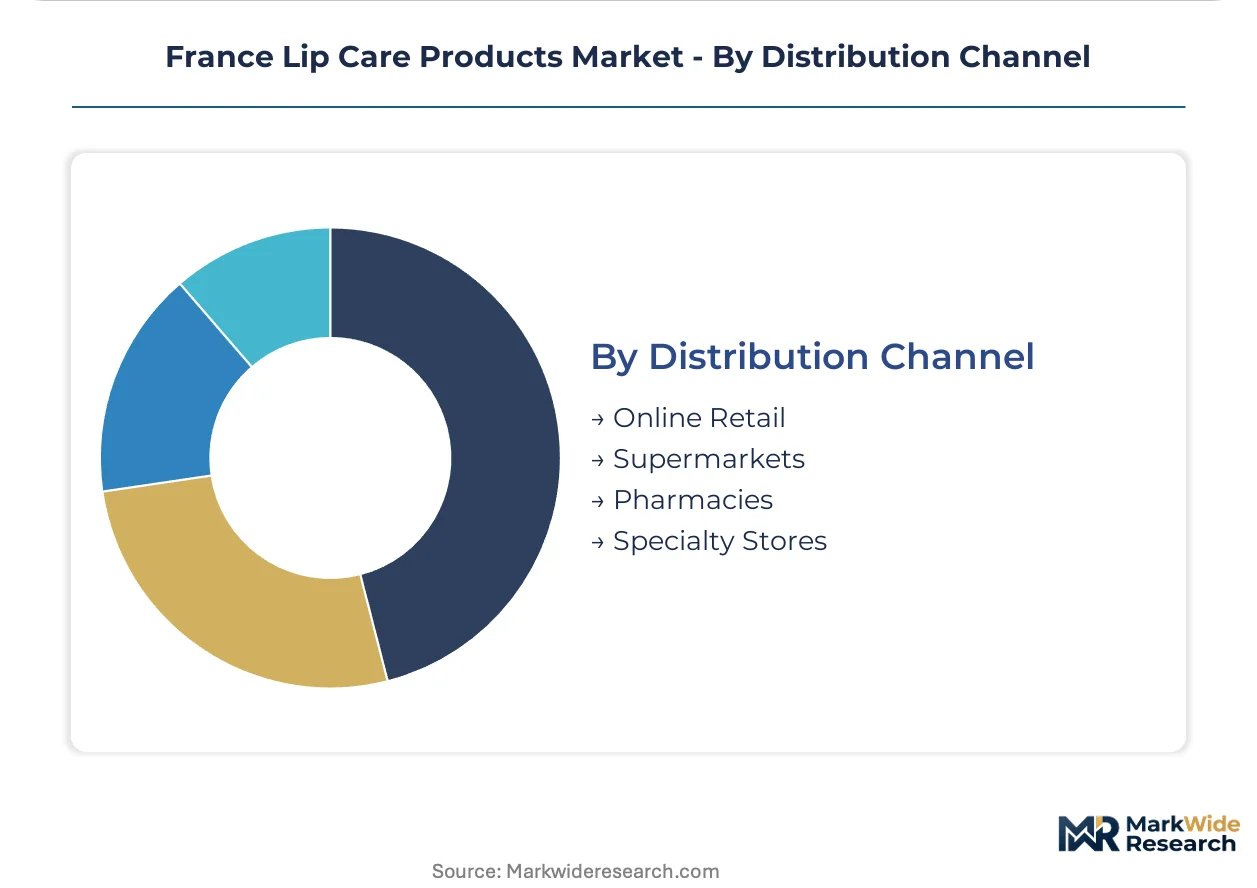
Margin structure and regulatory exposure diverge sharply between compliant pharmacy networks and disintermediated digital routes.
- Pharmacies:Dermo-cosmetic and therapeutic positioning with ANSM compliance requirements and trained staff recommendation driving conversion. Shelf space expansion for premium lip treatments continues across metropolitan France chains.
- Online Retail:Direct-to-consumer brands bypassing wholesale markups through agile manufacturing partnerships and subscription refill programs. Fastest-expanding channel with Parisian urban demographic concentration.
- Supermarkets:Mass-market volume through established brands with price-sensitive positioning and private label competition.
- Specialty Stores:Color-focused boutique experience with trend-responsive merchandising and premium pricing power.
Pharmacy defends margin; online captures growth velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France's pharmacy-dominant consumption pattern diverges sharply from coastal regions where tourism-driven SPF formats command shelf space. This geographic split shapes manufacturer portfolio allocation across metropolitan France.
Île-de-France
Parisian boutique clustering generates aspirational pull effects that cascade into pharmacy channel trial across metropolitan France. ANSM's allergen disclosure mandates elevate compliance costs for imported brands entering through this gateway region. Sephora flagship stores and dermo-cosmetic pharmacies concentrate in the 1st, 8th, and 16th arrondissements.
Provence-Alpes-Côte d'Azur
Coastal tourism corridors present whitespace for travel-format lip protection with elevated SPF positioning against Mediterranean solar exposure. EU Green Deal packaging directives pressure Marseille-based distributors to transition refillable container systems ahead of enforcement timelines. Nice-Cannes luxury retail clustering supports premium brand beach-format launches.
Auvergne-Rhône-Alpes
Alpine recreational zones generate concentrated demand for photostabilized organic filters in daily-wear bases against high-altitude UV exposure. REACH compliance requirements for chemical substances constrain formulation choices for Lyon-based cosmetic manufacturers. Grenoble's dermo-cosmetic research infrastructure anchors regional R&D activity.
Hauts-de-France
Channel price sensitivity in this industrial region favors mass-market supermarket penetration over pharmacy premium positioning. The EU Green Deal's packaging waste directives are pressuring Lille-based manufacturers toward recyclable container transitions. Calais cross-border retail corridors capture Belgian and UK tourist purchasing.
Nouvelle-Aquitaine
Bordeaux wine tourism and Biarritz coastal traffic create seasonal demand spikes for protective lip formulations. ANSM cosmetic safety assessments extend notification timelines for Spanish-imported brands entering through Bayonne-Anglet-Biarritz conurbation. Regional botanical sourcing networks support domestic manufacturer supply chain localization.
France Lip Care Products Market Key Industry Players
Capability concentration sits with dermo-cosmetic specialists; scale advantage sits with mass-market conglomerates with established retail presence. The market structures around three tiers: pharmacy-channel premium brands, supermarket mass-market incumbents, and agile direct-to-consumer entrants. Two dominant competitive moves are reshaping positioning: subscription-based refill program launches bypassing wholesale markups, and pharmacy retail chain shelf space expansion for therapeutic-positioned treatments.
Within the dermo-cosmetic tier, L'Oréal S.A. and Groupe Clarins SA anchor premium positioning through pharmacy channel concentration. Beiersdorf AG occupies the mass-market vector with supermarket shelf space control. These three exemplify the capability-scale bifurcation: Paris-headquartered specialists leverage clinical validation infrastructure while Hamburg-based scale players optimize retail logistics.
| Leading Market Players |
|---|
| Coty Inc. |
| Beiersdorf AG |
| L'Oréal S.A. |
| Shiseido Co Ltd |
| Unilever PLC |
| Groupe Clarins SA |
| LVMH Moët Hennessy Louis Vuitton |
| Yves Rocher |
| The Estée Lauder Companies |
| Others |
Cost & Logistics Intelligence
Grasse botanical extraction clusters anchor emollient supply capacity for pharmacy-channel dermo-cosmetics, translating raw shea butter and beeswax availability into downstream pricing power for premium lip balm formulations. This geographic concentration enables domestic manufacturers to command margin premiums against import-dependent competitors facing ANSM compliance cost burdens.
Pricing Analysis
Long-term offtake contracts between Provence-based botanical suppliers and Paris-headquartered dermo-cosmetic brands dominate input procurement, insulating premium tiers from West African shea butter spot price volatility. Three-tier pricing structure across premium pharmacy, standard supermarket, and economy private label levels reflects brand certification tier and distribution channel markup differentials. Cost compression in mass-market segments is intensifying because private label simplification strips fragrance to minimize ANSM allergen disclosure compliance exposure. Supermarket buyers exhibit highest price sensitivity; pharmacy consumers demonstrate lowest elasticity due to trained staff recommendation effects.
Supply Chain Analysis
EU Green Deal packaging directives function as de facto export controls limiting container system flows into France, mandating recyclable or refillable formats that constrain supplier qualification pools. Raw material sourcing draws from West Africa for shea butter, European apiaries for beeswax, and petroleum refineries in Belgium and the Netherlands for synthetic wax alternatives. Single-source vulnerability concentrates in shea butter supply chains subject to Sahel region climate disruption. Distribution runs through pharmacy retail chains for premium tiers, supermarket logistics networks for mass-market volume, and direct-to-consumer platforms for agile online entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France lip care products function as a service-attach opportunity where subscription refill programs and aftermarket replenishment revenue expand faster than single-use tube hardware sales. This recurring-revenue layer justifies customer lifetime value investments that transactional competitors cannot match.
For Market Incumbents: Build regulatory compliance moats through ANSM notification infrastructure and toxicological assessment capabilities that outpace available evaluator supply. Anchor defensive positioning by expanding pharmacy retail chain shelf space for therapeutic-positioned treatments before private label simplification erodes mass-market margins. Vertical integration into Provence botanical sourcing networks reduces petroleum value chain dependencies while supporting EU Green Deal packaging alignment. For New Entrants and Emerging Players: Pursue direct-to-consumer subscription models targeting teen demographics in Île-de-France with monthly SKU refresh rates that wholesale-dependent incumbents cannot match. Underpenetration in Provence-Alpes-Côte d'Azur coastal tourism corridors presents whitespace for travel-format SPF positioning. Social media-native go-to-market angles leveraging TikTok-originated aesthetic trends enable rapid trial generation without traditional retail slotting fee burdens. For Investors and Strategic Acquirers: Long-term, this sits as a dermo-cosmetic consolidation play because pharmacy channel concentration rewards clinical validation infrastructure over scale logistics. Acquisition target archetypes include agile direct-to-consumer brands with refill program technology and regional botanical sourcing networks. The signal to watch is ANSM microplastic ban finalization, which would force lip scrub SKU rationalization and concentrate value in exfoliant-free portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Refill Program Launch | Subscription revenue bypasses wholesale markups while capturing recurring customer relationships. |
| Botanical Sourcing Integration | Provence supply chain localization reduces petroleum dependency and supports EU Green Deal compliance. |
| Pharmacy Shelf Space Expansion | Trained staff recommendation effects defend margin premiums against supermarket private label erosion. |
| SPF Technology Licensing | Photostabilized organic filter partnerships enable functional positioning against solar exposure concerns. |
| Direct-to-Consumer Platform Buildout | Agile manufacturing partnerships compress development cycles for TikTok-originated color trends. |
Research Approach
Desk research of ANSM cosmetic safety filings, EU Green Deal packaging directive timelines, and pharmacy retail chain annual reports preceded structured interviews with dermo-cosmetic brand managers, pharmacy category buyers, botanical raw material procurement leads, and direct-to-consumer operations heads. Secondary validation drew from customs import records for shea butter and beeswax, SEPHORA and Marionnaud merchandising data, and REACH substance restriction databases. Bottom-up demand modeling across product type, application, end user, and distribution channel segments triangulated against top-down market sizing from retail audit data.
Assumptions held fixed include ANSM regulatory enforcement timelines, EU Green Deal packaging directive implementation schedules, and shea butter supply corridor stability; variables tested included social media trend velocity, pharmacy chain consolidation pace, and direct-to-consumer penetration rates. The analytical framework projected volume and value across the analysis window by modeling lip balm, lip gloss, lip stick, and lip scrub segments against moisturization, protection, tinting, and exfoliation applications. CAGRs derived from historical pharmacy and supermarket channel growth patterns adjusted for online retail acceleration and refill format adoption curves.
Macroeconomic conditions sit as an overlay; deviation in euro exchange rates affecting West African shea butter import costs or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect these documented assumptions with acknowledged sensitivity to ANSM microplastic ban timeline uncertainty and REACH substance restriction expansion. Material shifts in pharmacy retail chain consolidation or direct-to-consumer platform regulatory treatment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Camellia Skincare and Cosmetics Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Lip Products Pigment Market
Cosmetics & Skincare
UK Lip Care Products Market
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Setting Spray Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Japan Organic Cosmetics Market
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Night Cream Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Organic Soaps Market