
 Chile Cosmetics Products Market | 2026-2036
Chile Cosmetics Products Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Cosmetics Products Market Outlook
Premium clean-beauty certification is unwinding conventional mass-market positioning in Chile. L'Oréal SA leverages its dermatological research pipeline to anchor professional-grade skin care distribution through Santiago pharmacy networks. Natura &Co Holding SA sustains its Brazilian-origin sustainability narrative to differentiate refillable packaging systems in Chilean specialty retail. Shiseido Co. Ltd. competes by occupying the prestige tier with advanced fermentation-derived actives targeting metropolitan consumers.
Cosmetics products encompass chemically formulated preparations applied to human external surfaces for cleansing, beautifying, or altering appearance, with specifications governed by pH stability, preservative systems, and dermatological safety testing. These products serve commercial purposes spanning daily personal maintenance, professional service applications, and therapeutic adjunct functions. Skin Care leads product-type value generation due to higher per-unit pricing and repeat purchase frequency, while Online Retail captures the fastest-growing distribution channel as logistics infrastructure penetrates secondary Chilean cities. Professional customer segments concentrate margin pools through salon-exclusive and clinic-dispensed formulations.
Chile's Ministry of Health regulates cosmetic safety through national sanitary codes aligned with MERCOSUR technical standards, enforcing ingredient disclosure and manufacturing facility inspections. The National Consumer Service (SERNAC) monitors advertising claims compliance, shaping how brands communicate efficacy. DGAC aviation cargo rules affect temperature-sensitive import logistics for international suppliers. Stakeholders must monitor evolving MERCOSUR harmonization timelines and local enforcement intensity to calibrate product registration investments against channel expansion priorities.
Market Dynamics
Premium clean-beauty certification is unwinding conventional mass-market positioning in Chile. Professional women in Santiago are accelerating adoption of dermatologically tested formulations, forcing legacy brands to recertify ingredient portfolios under stricter Ministry of Health disclosure mandates.
Growth Catalysts
- MERCOSUR Harmonization:Chile's alignment with regional technical standards is streamlining cross-border product registrations, reducing compliance duplication for importers operating across Argentina and Brazil.
- Pharmacy Channel Expansion:Santiago's pharmacy networks are professionalizing skin care distribution, creating clinical credibility tiers that command higher per-unit pricing from metropolitan consumers.
- Fermentation-Derived Actives:Biotechnology processes producing postbiotic ingredients are enabling novel efficacy claims that differentiate prestige formulations from commodity alternatives.
Market Restraints
- Import Logistics Concentration:DGAC aviation cargo temperature requirements for active ingredients create single-point vulnerabilities for international suppliers serving secondary Chilean cities.
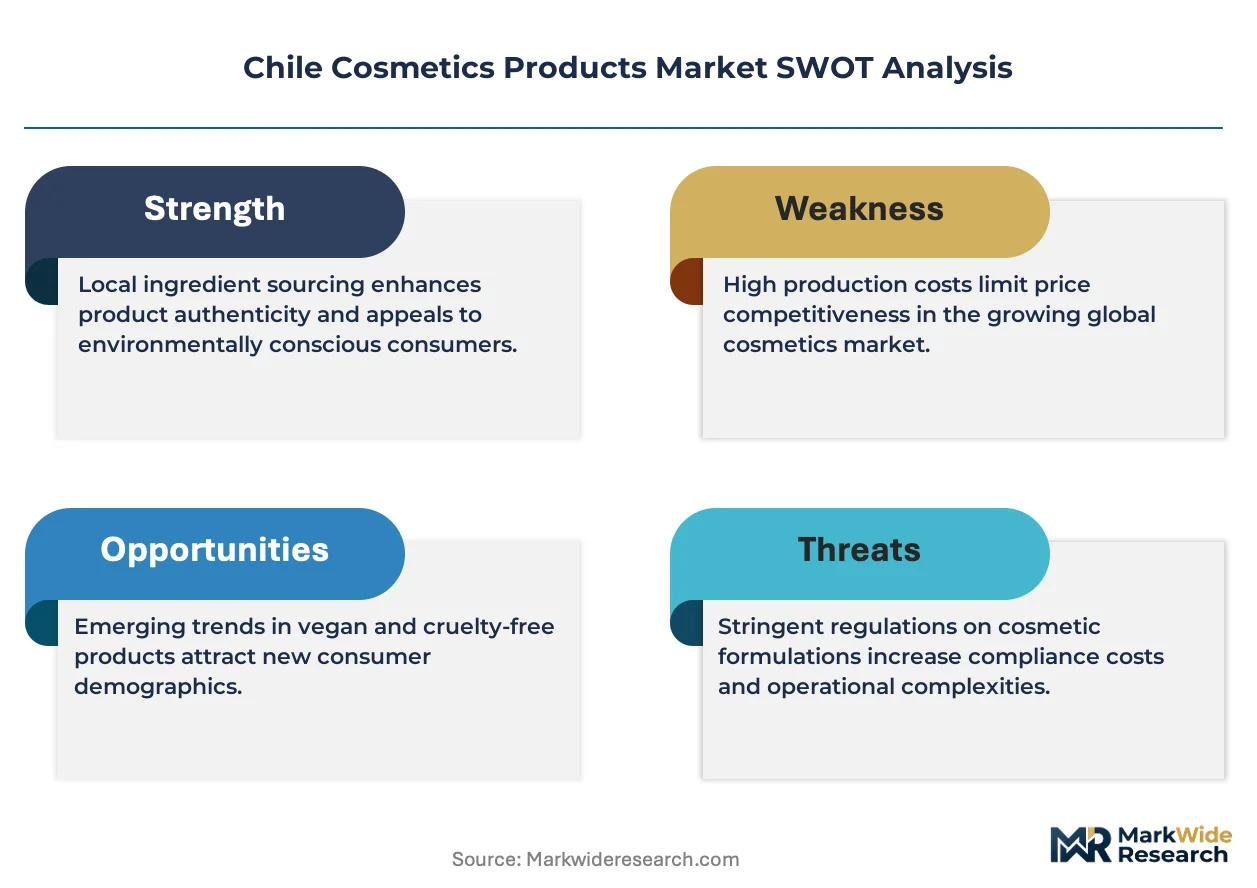
- Preservative System Costs:Clean-label reformulation demands are elevating natural preservative input costs above synthetic benchmarks, compressing margins for mid-tier brands.
- Labeling Compliance Friction:SERNAC advertising claim monitoring extends product launch timelines, requiring legal review cycles that delay market entry for innovative formulations.
Strategic Opportunities
- Secondary City Penetration:Logistics infrastructure improvements in Valparaíso and Concepción are opening pharmacy-distributed professional skin care to underserved metropolitan populations.
- Refillable Packaging Systems:Sustainability-mandated retail partnerships are creating exclusive shelf space for brands with verified closed-loop packaging, locking out conventional single-use competitors.
- Clinic-Dispensed Adjuncts:Dermatology practices in Providencia and Las Condes are expanding retail adjacencies for therapeutic skin care, bridging cosmetic and medical positioning.
Industry Challenges
- Formulation Chemistry Talent:Chile's specialized cosmetic chemistry programs produce insufficient graduates to staff quality control and R&D functions for expanding local manufacturing.
- Facility Certification Timelines:Ministry of Health manufacturing inspections for new production sites extend 14-18 months, delaying vertical integration strategies for brands seeking domestic production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Cosmetics Products Market |
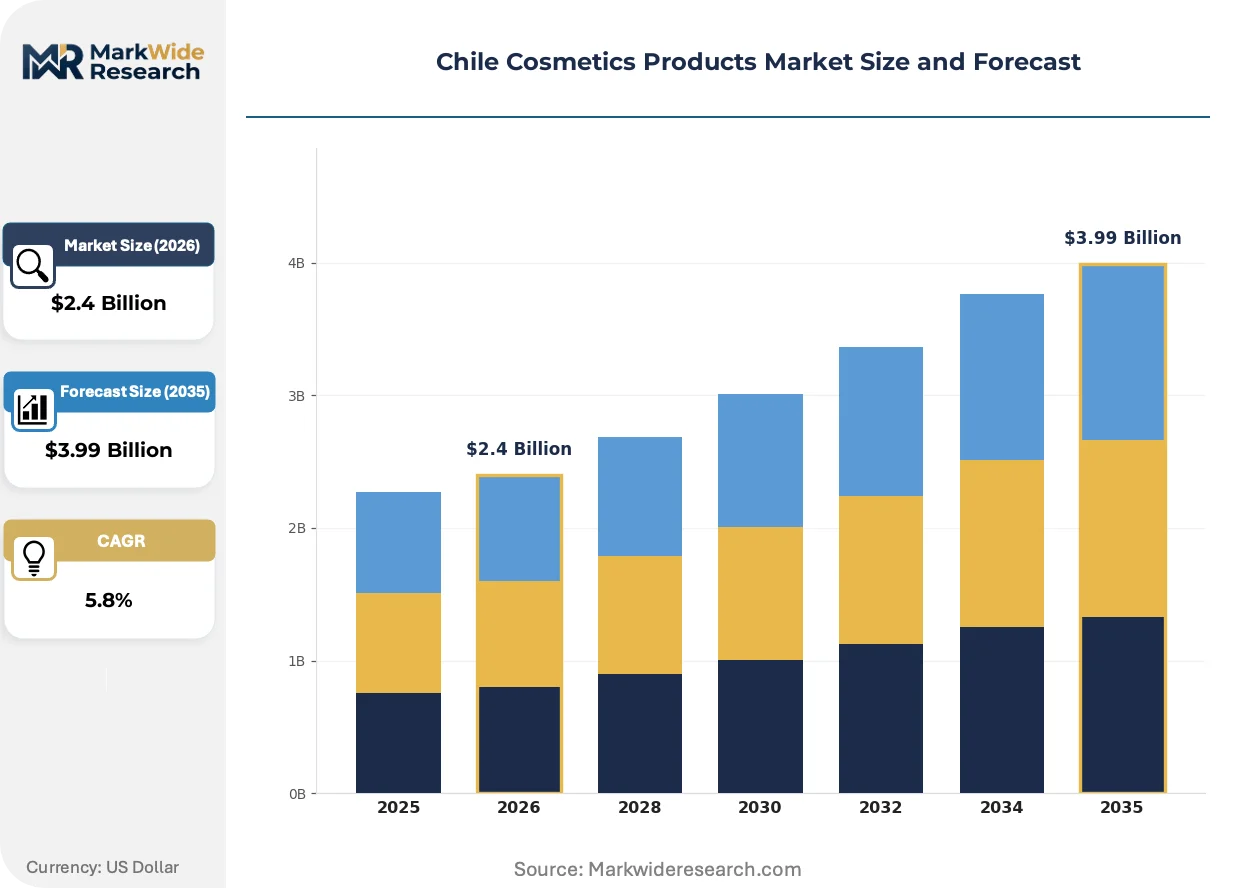
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
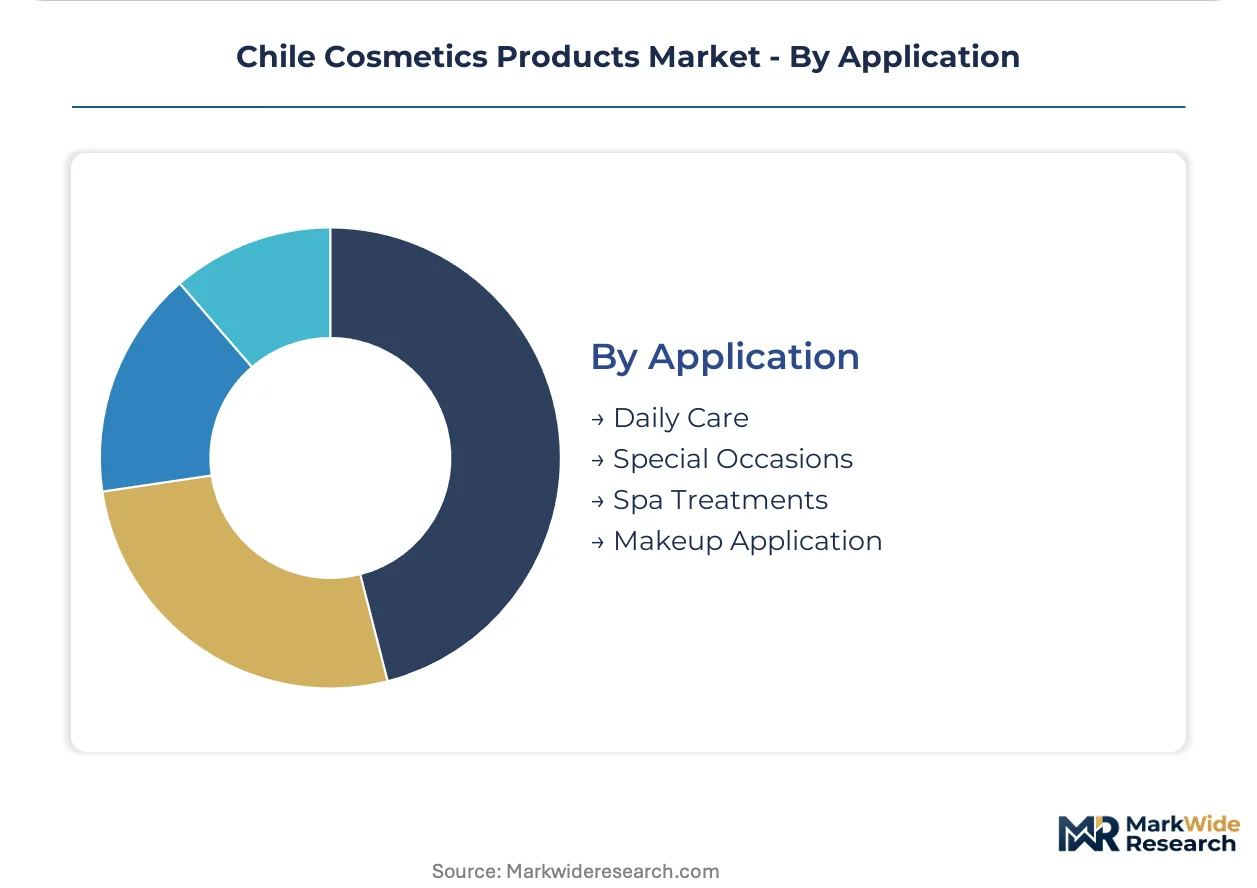
| Segmentation | Product Type: Skin Care, Hair Care, Makeup, Fragrance Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Customer Type: Women, Men, Teens, Professionals Application: Daily Care, Special Occasions, Spa Treatments, Makeup Application |
| Companies Covered | The Estée Lauder Companies Inc., Shiseido Co. Ltd., L'Oréal SA, Avon, Oriflame Cosmetics Global SA, Natura &Co Holding SA, Chanel Ltd., KVD Beauty, Beiersdorf AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Cosmetics Products Market Strategic Shifts
Biotechnology-driven ingredient sourcing and channel professionalization are restructuring how Chilean consumers access and evaluate cosmetic efficacy. Three developments are compressing the competitive window for conventional positioning.
Biotechnology is decomposing traditional botanical extraction supply chains. Precision fermentation platforms produce standardized active compounds—resveratrol, squalane, and peptide complexes—at purity grades exceeding agricultural sourcing. Professional skin care brands in Santiago's pharmacy channel are adopting these inputs to support clinical-strength concentration claims. The technology is decomposing price premiums previously attached to rare botanical provenance, forcing heritage brands to justify costs through formulation architecture rather than ingredient scarcity.
Chile's Ministry of Health is tightening cosmetic ingredient disclosure requirements under national sanitary codes. The regulatory consequence is mandatory allergen labeling expansion and prohibited substance list updates aligned with MERCOSUR technical standards. Premium skin care segments are responding fastest, reformulating preservative systems and fragrance compounds to preempt compliance-driven recalls that would damage pharmacy-channel credibility.
Metropolitan consumers are compressing purchase decision cycles through digital verification behaviors. Santiago's professional women now cross-reference ingredient lists against dermatological databases before pharmacy purchases, displacing counter-staff recommendations with self-directed research. This pattern is most visible in the 25-40 demographic concentrated in Providencia and Ñuñoa, where clean-beauty certification logos function as primary filtering mechanisms before price comparison.
Chile Cosmetics Products Market Segmentation
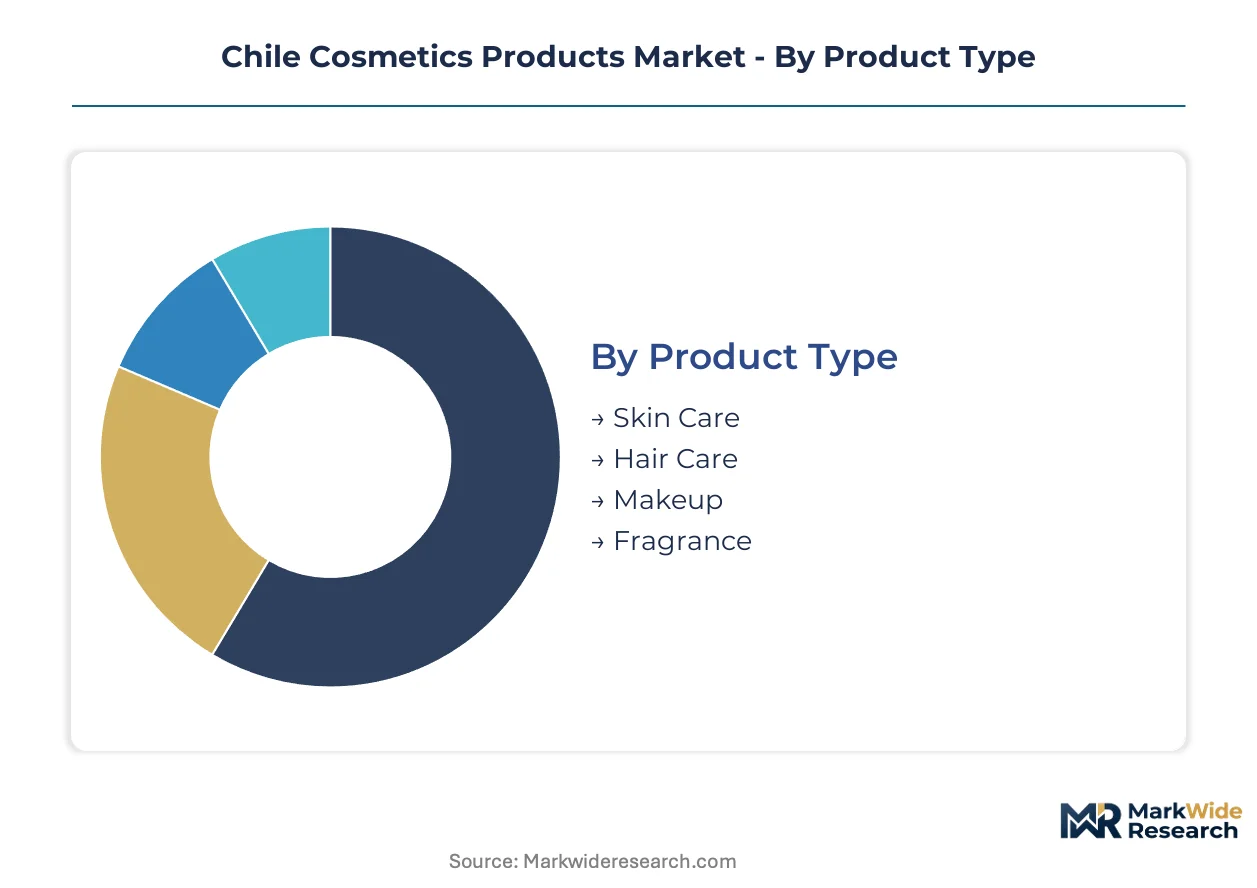
Chile's Ministry of Health enforces distinct regulatory pathways across product categories, creating compliance-driven segmentation that shapes brand positioning. SERNAC advertising scrutiny varies by distribution channel, forcing differential claim strategies. Professional customer segments concentrate margin pools through clinic-exclusive formulations.
Product Type:
Regulatory stringency from Chile's Ministry of Health diverges sharply across cosmetic categories, with dermatological safety testing mandates highest for leave-on formulations.
- Skin Care:Leave-on formulations with pH-stabilized emulsions and preservative systems face mandatory dermatological safety documentation under national sanitary codes. Demand concentrates in Santiago's Metropolitan Region among professional women seeking clinical-grade concentrations through pharmacy networks, with Ministry of Health disclosure mandates accelerating clean-beauty recertification.
- Hair Care:Rinse-off products with surfactant-based cleansing systems and conditioning polymers carry lighter regulatory burdens but growing scrutiny on colorant safety. Secondary cities including Valparaíso and Concepción show expanding pharmacy distribution for therapeutic scalp treatments, driven by dermatology practice retail adjacencies.
- Makeup:Pigment-loaded formulations with SPF additives require dual cosmetic-dermocosmetic classification review.
- Fragrance:Volatile compound blends with allergen disclosure obligations face expanding mandatory labeling.
Skin Care handles the majority of throughput; Online Retail is the fastest mover on share.
Distribution Channel:
Cost-to-serve economics stratify sharply across Chile's retail infrastructure, with cold-chain logistics requirements creating divergent margin structures.
- Online Retail:Direct-to-consumer platforms with last-mile penetration into secondary cities leverage improving logistics infrastructure. Metropolitan consumers in Providencia and Ñuñoa cross-reference ingredient databases before purchase, displacing traditional counter recommendations with self-directed verification behaviors.
- Pharmacies:Clinical-credibility distribution with trained staff consultation commands premium per-unit pricing in Santiago's professional skin care segment. Temperature-sensitive active ingredient logistics from DGAC-regulated aviation cargo create supply vulnerabilities for international brands serving this channel.
- Supermarkets:Mass-volume rotation with high-velocity replenishment cycles favors standardized formulations.
- Specialty Stores:Experience-driven retail with sustainability-mandated partnerships reserves shelf space for verified closed-loop packaging systems.
Pharmacies capture the highest margin per transaction; Online Retail is expanding most quickly.
Customer Type:
Application sophistication and repeat purchase frequency create distinct value profiles across demographic segments.
- Women:Primary decision-makers with multi-step regimen adherence and highest per-capita expenditure on professional-grade formulations. Santiago's 25-40 demographic concentrates demand for fermentation-derived actives and clean-beauty certification, filtering purchases through dermatological database verification.
- Professionals:Salon and clinic service providers with bulk procurement of adjunct therapeutic formulations. Dermatology practices in Providencia and Las Condes bridge cosmetic and medical positioning through retail adjacencies.
- Men:Simplified regimen adoption with growing interest in scalp and beard care specialization.
- Teens:Entry-level price sensitivity with social media-influenced brand discovery patterns.
Women generate the dominant revenue share; Professionals are climbing the fastest on margin contribution.
Application:
Usage occasion frequency and formulation intensity determine regulatory exposure and pricing architecture.
- Daily Care:High-frequency baseline regimens with repeat purchase cycles driving volume economics. Clean-label reformulation demands elevate natural preservative costs above synthetic benchmarks, compressing margins for mid-tier brands in this high-rotation segment.
- Spa Treatments:Professional service applications with concentrated active delivery and highest per-use pricing. Chile's specialized cosmetic chemistry programs produce insufficient graduates to staff quality control for expanding local manufacturing serving this segment.
- Special Occasions:Event-driven purchase patterns with gift-oriented packaging requirements.
- Makeup Application:Service-based consumption with professional technique dependency.
Daily Care anchors volume throughput; Spa Treatments are gaining share fastest on value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Chile's Metropolitan Region where Santiago anchors formulation demand, while secondary city logistics improvements expand pharmacy-distributed skin care reach. The Ministry of Health enforces MERCOSUR-aligned sanitary codes that shape cross-border product registration strategies for international suppliers.
Metropolitan Region
Professional women in Providencia and Ñuñoa drive fermentation-derived active demand through pharmacy networks with clinical-grade concentration expectations. The Ministry of Health mandates dermatological safety documentation for leave-on formulations under national sanitary codes. Santiago's pharmacy channel professionalization commands premium per-unit pricing for prestige skin care brands.
Valparaíso
Logistics infrastructure improvements enable temperature-sensitive active ingredient distribution to coastal metropolitan consumers previously underserved by aviation cargo-dependent supply chains. The Ministry of Health manufacturing facility inspections apply uniform standards across coastal production sites. Viña del Mar's expanding retail adjacencies bridge cosmetic and therapeutic positioning for dermatology-linked formulations.
Biobío Region
Concepción's secondary city population generates growing demand for online-retail skin care as last-mile penetration improves beyond Santiago-centric distribution. SERNAC advertising claim monitoring extends to regional consumer protection offices, shaping brand communication strategies. Local pharmacy networks professionalize consultation services to capture metropolitan-tier pricing.
Maule Region
Talca's agricultural processing heritage supports botanical ingredient sourcing for clean-beauty formulations targeting sustainability-mandated retail partnerships. The Ministry of Health ingredient disclosure requirements apply equally to domestically sourced botanical inputs. Regional manufacturing investments face 14-18 month facility certification timelines that delay vertical integration strategies.
Chile Cosmetics Products Market Competitive Environment
Concentration sits with multinational dermatological specialists commanding pharmacy channel credibility through clinical-grade formulation architectures. Three strategic archetypes dominate: fermentation-technology prestige houses, sustainability-narrative Latin American originators, and mass-market scale operators with professional line extensions. Competitive moves center on pharmacy network exclusivity agreements and clean-beauty recertification investments to preempt Ministry of Health compliance-driven recalls.
Within the prestige dermatological tier, L'Oréal SA and Shiseido Co. Ltd. exemplify clinical-credibility positioning through Santiago pharmacy networks. Natura &Co Holding SA represents the Latin American sustainability archetype with refillable packaging differentiation in specialty retail. These three anchors illustrate how geographic origin and formulation philosophy stratify competitive access to Chile's professional consumer segments.
| Leading Market Players |
|---|
| The Estée Lauder Companies Inc. |
| Shiseido Co. Ltd. |
| L'Oréal SA |
| Avon |
| Oriflame Cosmetics Global SA |
| Natura &Co Holding SA |
| Chanel Ltd. |
| KVD Beauty |
| Beiersdorf AG |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month Ministry of Health facility certification timelines concentrate supply-side pricing power among established pharmacy-channel incumbents with certified domestic manufacturing, while compressing margin recovery for new entrants forced into higher-cost import-dependent distribution models.
Pricing Analysis
Chile's national sanitary codes dictate the pricing tier structure across the cosmetics market, with dermatological safety documentation requirements separating pharmacy-distributed professional formulations from mass-market alternatives. Three-tier pricing stratifies across premium fermentation-derived actives, standard botanical-based formulations, and economy surfactant products. Cost compression in the mid-tier segment is intensifying because clean-label reformulation demands elevate natural preservative input costs above synthetic benchmarks. Metropolitan professional women in Santiago demonstrate lowest price sensitivity due to clinical-grade concentration expectations, while teens in secondary cities exhibit highest sensitivity to per-unit pricing.
Supply Chain Analysis
Strategic stockpiling of temperature-sensitive active ingredients dominates inventory strategy among international suppliers serving Chile's pharmacy channel, offsetting DGAC aviation cargo single-point vulnerabilities. Manufacturing concentration rests on Brazil, Argentina, and domestic Chilean facilities with MERCOSUR-aligned certification. Key input dependencies include fermentation-derived postbiotics, botanical extracts from Maule Region agricultural processors, and synthetic surfactant bases. Tariff exposure through regional trade agreement renegotiation presents structural supply risk. Distribution runs through Santiago-centric pharmacy networks with expanding last-mile penetration into Valparaíso and Concepción.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among professional women in Santiago's Metropolitan Region, whose self-directed ingredient verification behaviors and clean-beauty certification demands are consolidating purchase decisions around pharmacy networks with clinical credibility.
For Market Incumbents: Secure exclusive pharmacy network agreements in Providencia and Las Condes to lock out fermentation-technology challengers, while accelerating Ministry of Health clean-beauty recertification investments to preempt compliance-driven recalls. Capacity addition in certified domestic manufacturing mitigates DGAC aviation cargo vulnerability. For New Entrants and Emerging Players: Clinic-dispensed therapeutic adjunct positioning represents the most penetrable white-space, where dermatology practices in Santiago bridge cosmetic and medical positioning with limited incumbent saturation. Secondary city pharmacy professionalization in Concepción offers geographic entry with lower certification backlog. Direct-to-consumer platforms with ingredient transparency databases bypass established counter-staff recommendation channels. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because Ministry of Health facility certification timelines and SERNAC advertising compliance create durable barriers against rapid competitor replication. Acquisition targets should demonstrate certified domestic manufacturing and established pharmacy channel relationships. The signal to watch is MERCOSUR harmonization timeline acceleration, which would streamline cross-border registration and erode location-based supply advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Beauty Recertification Investment | Preemptive compliance with Ministry of Health disclosure mandates protects pharmacy channel credibility. |
| Pharmacy Network Exclusivity Agreement | Clinical-credibility distribution in Santiago commands premium per-unit pricing from professional women. |
| Domestic Manufacturing Certification | Fourteen-to-eighteen-month Ministry of Health timelines create supply-side moat against import-dependent competitors. |
| Fermentation-Derived Active Sourcing | Biotechnology platforms enable novel efficacy claims that differentiate prestige formulations from commodity alternatives. |
| Refillable Packaging System Deployment | Sustainability-mandated retail partnerships reserve exclusive shelf space for verified closed-loop systems. |
Study Parameters
Desk research of MERCOSUR technical standards documentation, Chile Ministry of Health sanitary codes, and SERNAC advertising compliance precedents preceded structured interviews with pharmacy chain procurement directors, dermatology practice retail managers, cosmetic chemistry program faculty, and logistics operators handling DGAC-regulated temperature-controlled cargo. Secondary validation drew from customs import records, pharmacy retail audit data, and national consumer protection filings. Bottom-up segment sizing and top-down macroeconomic triangulation were cross-referenced for consistency.
Variance decomposition across product type, distribution channel, customer segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Fermentation-technology adoption curves and clean-beauty certification penetration rates served as industry-specific forecast inputs alongside logistics infrastructure expansion timelines in secondary cities.
Forecasts assume regulatory continuity in Chile's Ministry of Health enforcement and MERCOSUR harmonization schedules; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Asia-Pacific Face Compact Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Asia-Pacific Cosmetics Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Bath Soap Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Halal Cosmetic Products Market
Cosmetics & Skincare
BB Cream Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Sun Care Products Market
Cosmetics & Skincare
Malaysia Skin Care Products Market