
 Non-Fuel Grade Alcohol Market | 2026-2036
Non-Fuel Grade Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Fuel Grade Alcohol Market Outlook
USP-grade and food-grade certification cycles are rotating faster than equipment depreciation schedules, forcing mid-scale distillers to choose between capex upgrades and contract exits. CropEnergies AG leverages its European biorefinery network to sustain pharmaceutical-grade ethanol output across multiple regulatory jurisdictions. Cargill, Incorporated anchors North American supply through corn-based fermentation infrastructure that competes on volume consistency. Godavari Biorefineries Ltd specializes in molasses-derived ethyl alcohol for India’s expanding pharmaceutical excipient market.
Non-fuel grade alcohol encompasses ethanol, isopropyl alcohol, methanol, and denatured formulations refined to purity thresholds above 95% by volume, with residual water and congener content controlled through molecular sieve dehydration or azeotropic distillation for pharmaceutical solvent, disinfectant, cosmetic carrier, and analytical reagent applications. Ethyl alcohol dominates volume flows due to its versatility across food-grade and medical-grade specifications, while isopropyl alcohol commands premium positioning in laboratory-grade and cosmetic-grade segments where residual impurity limits tighten. Denatured alcohol occupies a mature cost-competitive tier serving industrial solvent buyers, whereas methanol traces a narrower channel into specialized chemical synthesis.
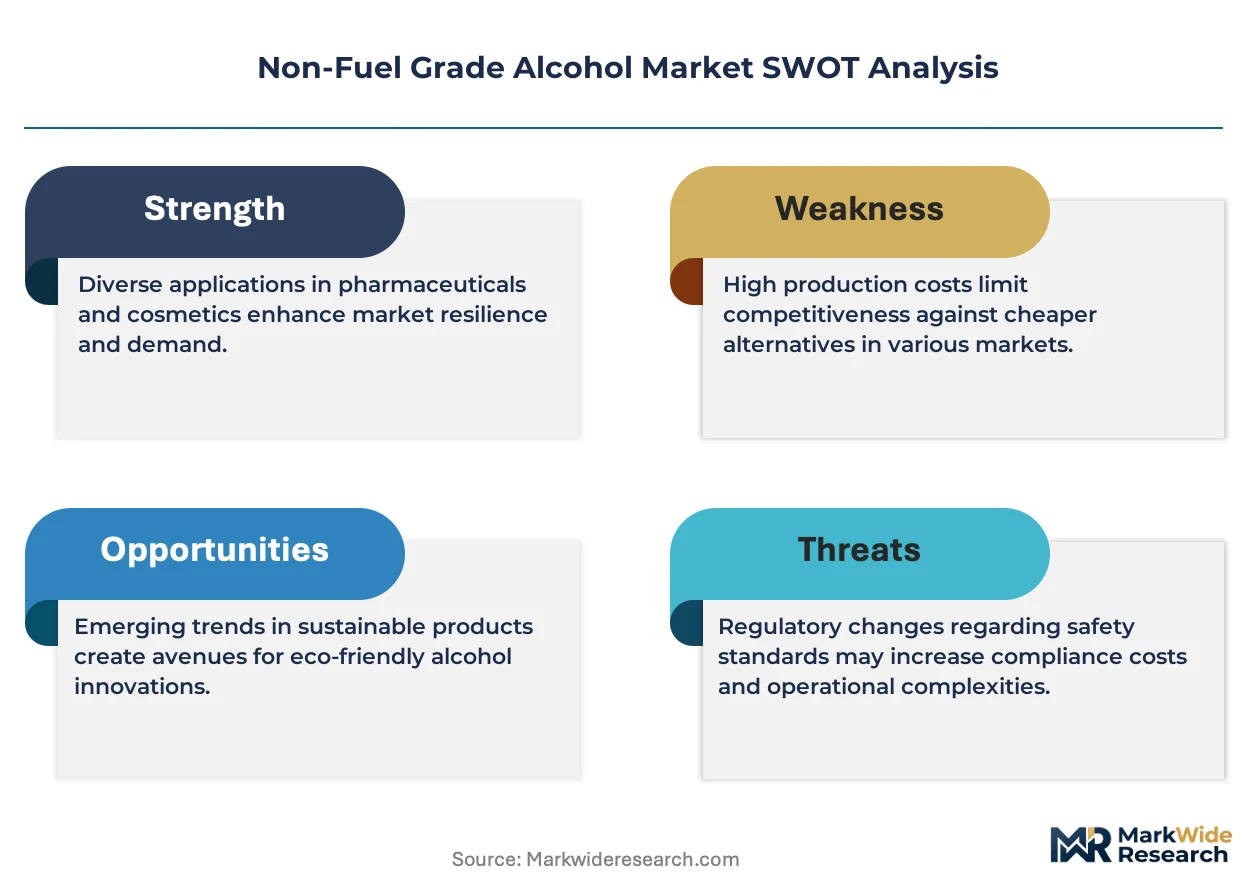
FDA purity standards under 21 CFR, REACH registration through ECHA, and CDSCO excipient guidelines collectively determine which producers qualify for pharmaceutical and personal care supply chains, with each regulator imposing distinct analytical testing protocols that fragment certification costs. ISO 9001 and EXCiPACT GMP frameworks add parallel compliance layers for suppliers targeting multinational drug manufacturers. Stakeholders must monitor regulatory divergence between USP-NF, EP, and IP pharmacopeia editions to anticipate reformulation-driven sourcing shifts before contract renewal cycles lock in multi-year supply commitments.
Market Dynamics
Pharmaceutical-grade certification cycles are compressing faster than equipment depreciation schedules, forcing mid-scale distillers to choose between capex-heavy upgrades and contract exits as USP-NF, EP, and IP pharmacopeia editions diverge on impurity thresholds.
Growth Catalysts
- CDSCO excipient mandates:India's pharmaceutical regulator is accelerating domestic capacity builds through mandatory local sourcing requirements for drug formulations.
- Molecular sieve dehydration:This purification technology is expanding pharmaceutical-grade ethanol output by enabling sub-0.5% residual water content without azeotropic agents.
- Cosmetic-grade isopropyl alcohol:Personal care formulators in South Korea are tightening residual impurity limits, pulling premium-priced supply away from industrial solvent channels.
Market Restraints
- Feedstock volatility:Corn and molasses input costs swing with agricultural commodity cycles, squeezing margin predictability for fermentation-based producers.
- REACH registration concentration:ECHA compliance costs fragment across multiple analytical testing protocols, favoring large-scale European biorefineries with dedicated regulatory affairs teams.
- Denatured alcohol substitution:Industrial buyers in packaging and coatings are shifting to bio-based glycol ethers where solvent recovery systems permit.
Strategic Opportunities
- Brazilian excipient market:ANVISA is harmonizing with USP-NF standards, creating first-mover advantage for producers achieving dual pharmacopeia certification.
- Green hydrogen integration:Biorefineries combining ethanol dehydration with electrolyzer off-gas are capturing carbon credits under EU Green Deal frameworks.
- Direct-to-laboratory distribution:Specialty chemical distributors are bypassing traditional wholesale tiers to serve analytical reagent buyers with lot-traceable documentation.
Industry Challenges
- Pharmacopeia divergence management:Quality control teams must maintain parallel testing protocols as USP-NF, EP, and IP editions issue conflicting monograph updates.
- Continuous processing capex:Batch-to-continuous fermentation upgrades demand $15-40 million per facility, straining mid-scale balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Fuel Grade Alcohol Market |
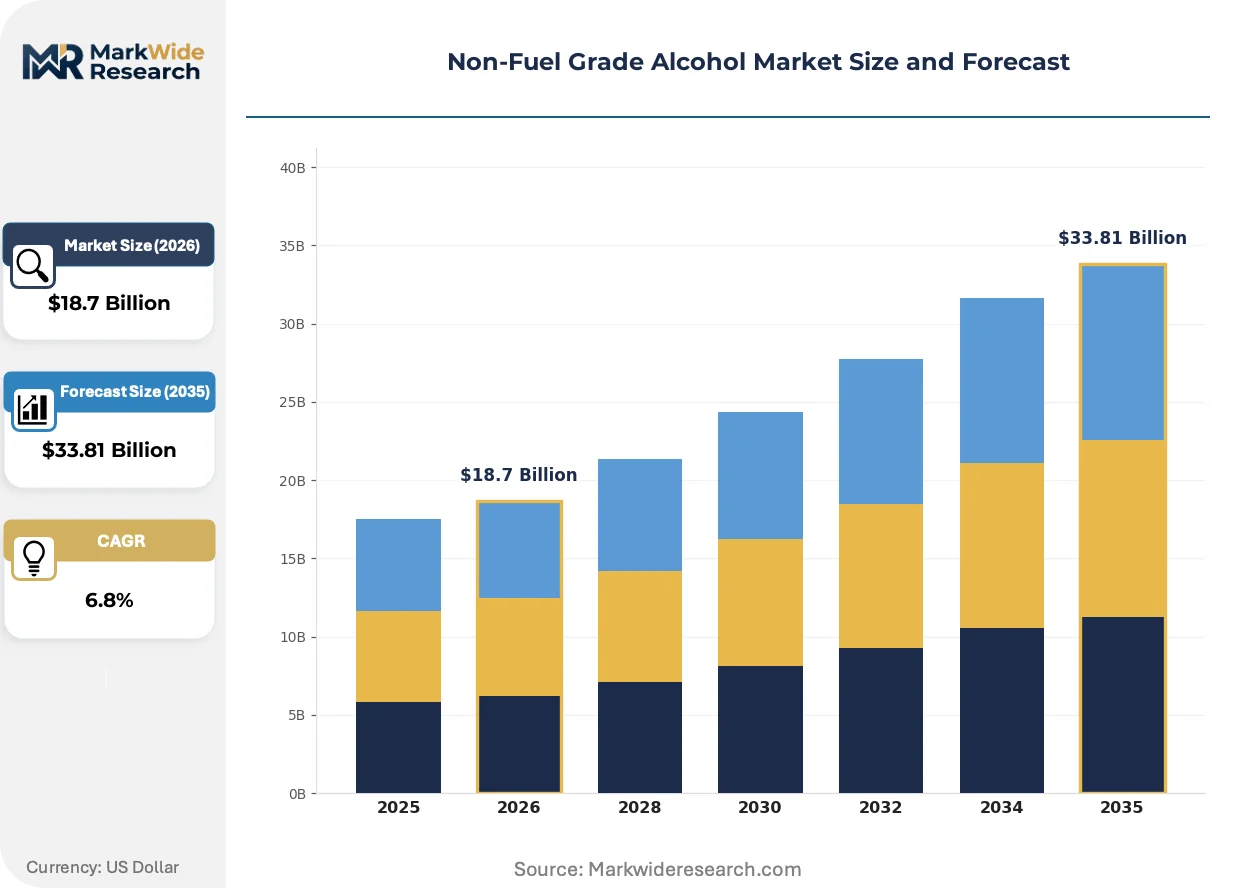
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethyl Alcohol, Isopropyl Alcohol, Methanol, Denatured Alcohol Application: Pharmaceuticals, Cosmetics, Food Processing, Industrial Solvents Grade: Food Grade, Medical Grade, Cosmetic Grade, Laboratory Grade End User: Manufacturers, Retailers, Laboratories, Healthcare Providers |
| Companies Covered | Merck KGaA, CropEnergies AG, Archer Daniels Midland Company, LyondellBasell Industries Holdings BV, Godavari Biorefineries Ltd, Cargill, Incorporated, Wilmar International, Mitsubishi Chemical Corporation, Sasol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Fuel Grade Alcohol Market Strategic Shifts
Dehydration technology trajectories are diverging between energy-intensive azeotropic systems and membrane-based molecular sieves, reshaping capital allocation across pharmaceutical-grade production networks.
Membrane-based molecular sieve technology is bifurcating the dehydration equipment market. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting electric-heated sieve systems to eliminate steam boiler dependencies. This technology is bifurcating supplier tiers into energy-integrated specialists versus conventional equipment vendors.
REACH registration deadlines under ECHA's 2024-2026 substance evaluation work program are forcing ethanol importers to submit extended safety data sets. European formulators are pre-qualifying domestic biorefineries to avoid supply interruption from third-country registration gaps. Personal care brands with EU manufacturing footprints are absorbing 8-12% cost premiums for REACH-registered supply.
Certification-driven supplier consolidation is compressing procurement cycles for multinational drug manufacturers. Quality assurance teams are reducing approved vendor lists from 15-20 ethanol sources to 3-5 strategic partners with multi-pharmacopeia coverage. This concentration is most visible among generic API producers in India, where CDSCO inspections are disqualifying smaller distillers lacking EXCiPACT GMP documentation.
Non-Fuel Grade Alcohol Market Segmentation
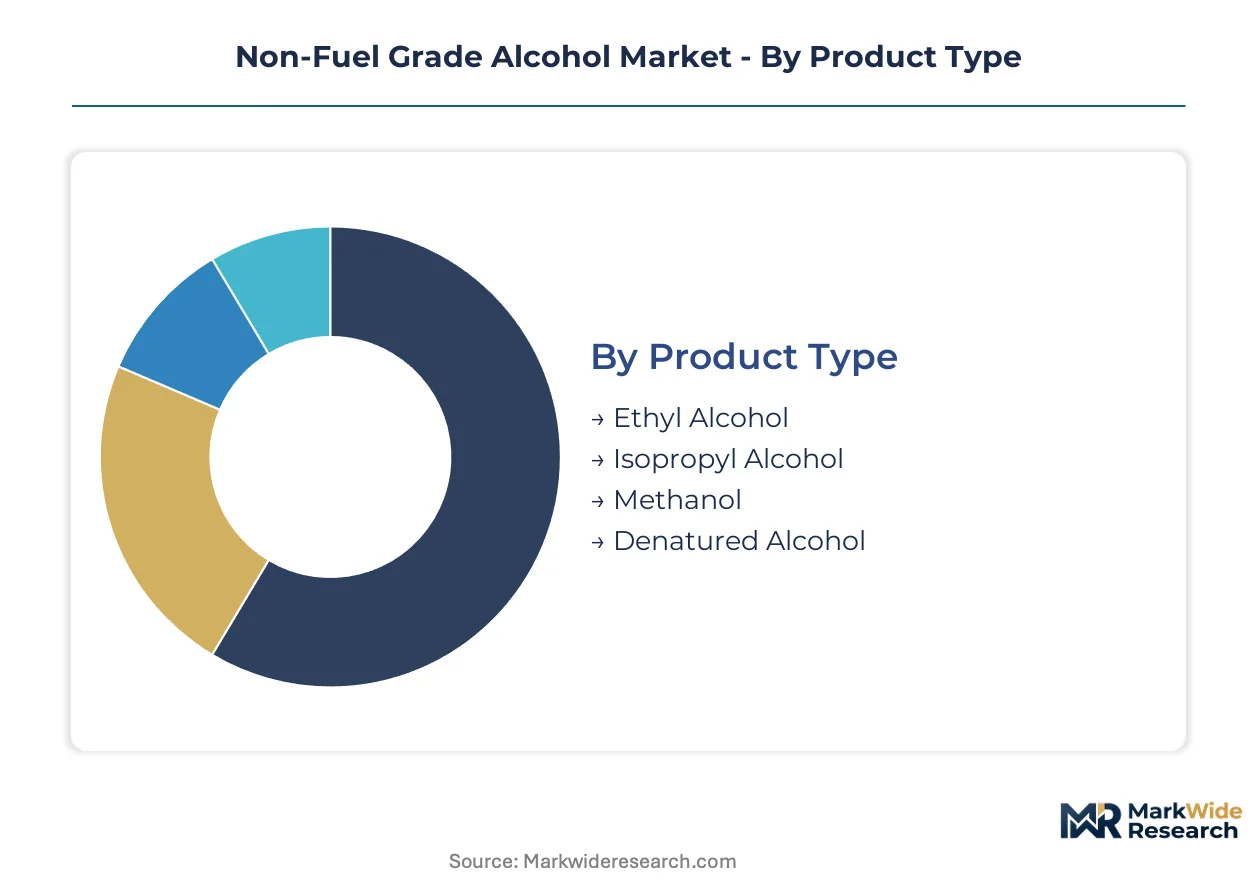
Non-fuel grade alcohol markets fragment across purity thresholds and regulatory certifications that determine supplier qualification. Each segment carries distinct margin profiles and capital requirements that reshape competitive positioning across fermentation and synthetic production routes.
Product Type:
Domestic production dominates ethyl alcohol and denatured formulations, while isopropyl alcohol and high-purity methanol flow through concentrated import channels serving pharmaceutical and laboratory buyers.
- Ethyl Alcohol:Fermentation-derived ethanol refined to 95-99.9% purity serves as the foundational solvent for pharmaceutical synthesis and beverage applications. Demand concentrates in India where CDSCO-mandated excipient rules are accelerating domestic molasses-to-ethanol capacity builds. CropEnergies AG and Godavari Biorefineries Ltd anchor regional supply networks with multi-pharmacopeia certification coverage.
- Isopropyl Alcohol:Synthetic propylene hydration yields this secondary alcohol with superior volatility control for disinfectant and cosmetic formulations. South Korean personal care manufacturers are tightening residual impurity limits below 50 ppm, pulling premium supply away from industrial solvent channels into beauty-grade certification tiers.
- Methanol:Catalytic synthesis of syngas produces this primary alcohol for specialized chemical synthesis and analytical reagent applications.
- Denatured Alcohol:Bitrex or methanol additives render this ethanol variant unfit for consumption, serving mature industrial solvent markets in packaging and coatings.
Ethyl alcohol holds the largest share; momentum sits with isopropyl alcohol as cosmetic-grade purity premiums widen.
Application:
Cost tier differentiation separates pharmaceutical buyers willing to absorb 15-25% premiums for USP-NF certification from industrial solvent purchasers optimizing for volume throughput.
- Pharmaceuticals:Active ingredient synthesis and tablet coating demand ethanol meeting USP-NF, EP, and IP pharmacopeia monographs simultaneously. FDA purity standards under 21 CFR and evolving EMA guidelines are compressing approved vendor lists to 3-5 strategic partners with dedicated regulatory affairs teams.
- Cosmetics:Personal care formulators require isopropyl alcohol with controlled residual acetone and water content for fragrance carriers and antimicrobial preservation. REACH registration through ECHA is fragmenting certification costs across analytical testing protocols that favor large-scale European biorefineries.
- Food Processing:Flavor extraction and preservation applications rely on food-grade ethanol meeting FSSAI or FDA direct additive specifications.
- Industrial Solvents:Degreasing, ink formulation, and adhesive production consume denatured alcohol where bio-based glycol ethers are displacing volumes in solvent recovery-enabled facilities.
Pharmaceuticals command the steepest margin tier; food processing is climbing fastest as clean-label extraction methods gain formulation share.
Grade:
Volume concentration tracks regulatory stringency, with medical and laboratory grades representing sub-15% of total output but 35-45% of value capture.
- Food Grade:Ethanol meeting FCC and FSSAI specifications for direct consumption or extraction applications carries residual congener limits below 10 ppm. Cargill, Incorporated anchors North American supply through corn-based fermentation infrastructure competing on batch-to-batch consistency.
- Medical Grade:USP-NF and EP compliance for antiseptic and disinfectant formulations requires sub-0.5% residual water content achievable through molecular sieve dehydration. Certification cycles are rotating faster than equipment depreciation schedules, forcing mid-scale distillers toward contract exits.
- Cosmetic Grade:Isopropyl alcohol with enhanced odor profile and ultra-low heavy metal content serves premium skincare and fragrance markets.
- Laboratory Grade:Analytical reagent specifications demand lot-traceable documentation and sub-ppm impurity profiling for chromatography and spectroscopy applications.
Medical grade captures the highest value per liter; cosmetic grade is expanding most quickly as K-beauty export demand accelerates.
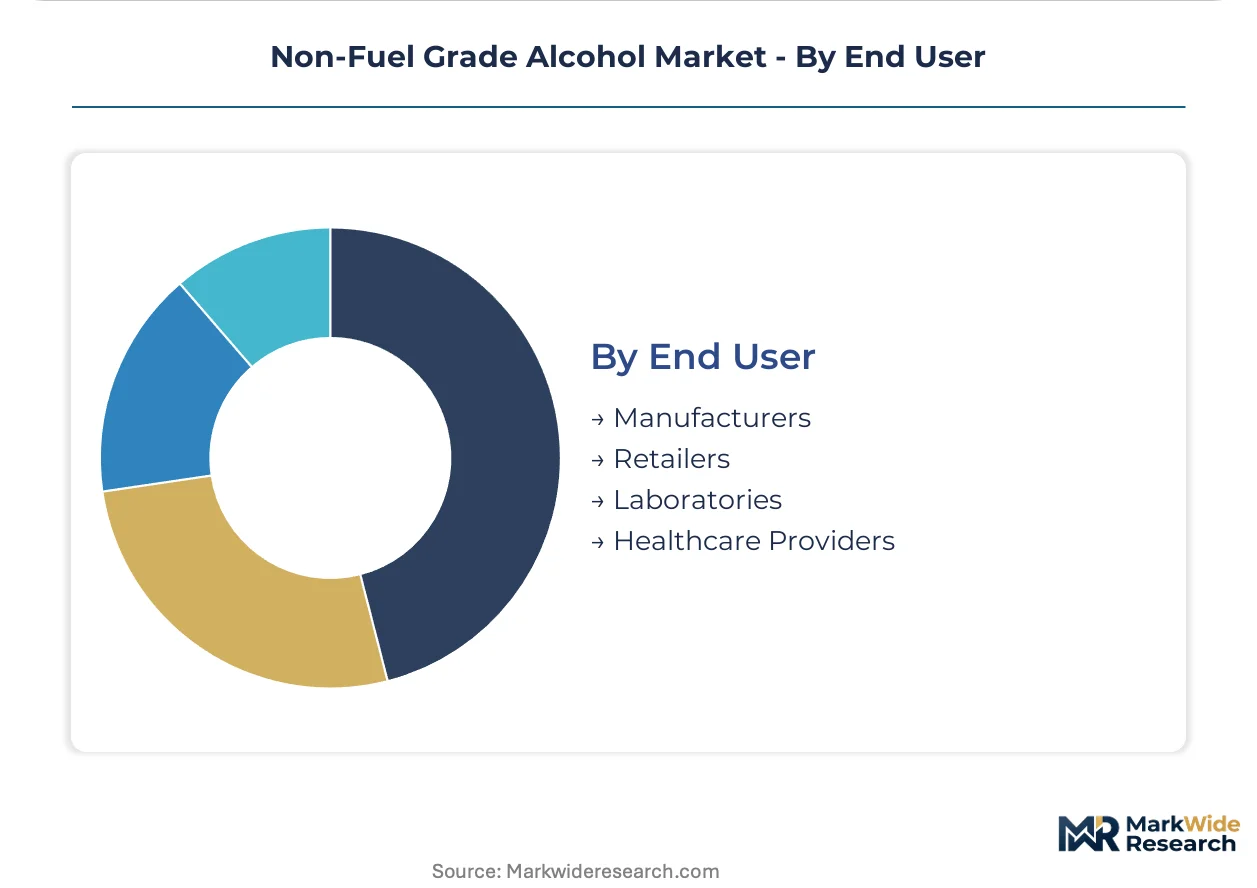
End User:
Customer type determines procurement structure, with manufacturers locking multi-year supply commitments while laboratories purchase through specialty distributors demanding documentation granularity.
- Manufacturers:Pharmaceutical and personal care formulators negotiate annual contracts with price-volume bands tied to corn or molasses feedstock indices. Generic API producers in India are consolidating from 15-20 approved ethanol sources to 3-5 strategic partners with EXCiPACT GMP documentation.
- Retailers:Pharmacy chains and cosmetic distributors stock isopropyl alcohol and denatured formulations for consumer antiseptic and cleaning applications. Direct-to-laboratory distribution channels are bypassing traditional wholesale tiers to serve analytical reagent buyers with digital lot-traceability.
- Laboratories:Academic and industrial research facilities procure laboratory-grade solvents through certified distributors with certificate of analysis documentation.
- Healthcare Providers:Hospital systems and clinics consume medical-grade ethanol and isopropyl alcohol for surface disinfection and surgical preparation.
Manufacturers represent the deepest volume commitment; laboratories are gaining procurement sophistication fastest as compliance documentation becomes a competitive filter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO-mandated pharmaceutical excipient rules are accelerating domestic capacity builds in India, while REACH compliance deadlines across Europe and evolving FDA purity standards in the United States reshape supplier qualification requirements worldwide.
United States
Pharmaceutical manufacturers are expanding solvent sourcing for active ingredient synthesis under tightening 21 CFR purity standards. FDA inspections are compressing approved vendor lists to strategic partners with dedicated regulatory affairs teams. Corn-based fermentation infrastructure in the Midwest anchors North American supply networks competing on batch-to-batch consistency.
Germany
Electric-heated molecular sieve systems are eliminating steam boiler dependencies among pharmaceutical contract manufacturers. ECHA registration deadlines under the 2024-2026 substance evaluation work program are forcing ethanol importers to submit extended safety data sets. Biorefinery clusters in Saxony-Anhalt sustain pharmaceutical-grade output across multiple regulatory jurisdictions.
India
Molasses-derived ethyl alcohol production is scaling rapidly to serve expanding pharmaceutical excipient demand. CDSCO inspections are disqualifying smaller distillers lacking EXCiPACT GMP documentation. Manufacturing corridors in Maharashtra and Karnataka concentrate multi-pharmacopeia certified capacity for generic API producers.
South Korea
Personal care formulators are tightening residual impurity limits below 50 ppm for cosmetic-grade isopropyl alcohol. MFDS cosmetic safety regulations are pulling premium supply away from industrial solvent channels. Seoul-based beauty manufacturers are absorbing cost premiums for enhanced odor profile certification.
Brazil
ANVISA harmonization with USP-NF standards is creating first-mover advantage for dual pharmacopeia certified producers. Sugar cane ethanol infrastructure in São Paulo state offers feedstock proximity for fermentation-based pharmaceutical-grade output. Domestic formulators are pre-qualifying local biorefineries to reduce import dependency.
Non-Fuel Grade Alcohol Market Competitive Environment
Listed leaders compete with private specialists across certification tiering, with public companies commanding scale advantages in multi-jurisdictional regulatory compliance while private operators capture niche premiums in single-pharmacopeia segments. Market structure concentrates around three strategic archetypes: integrated biorefinery networks with captive agricultural supply, fermentation specialists anchored to regional feedstock bases, and synthetic alcohol producers serving laboratory-grade purity tiers. Dominant competitive moves include backward integration into feedstock cultivation and strategic partnerships with pharmaceutical contract manufacturers seeking supply security.
Among European-based biorefinery operators, CropEnergies AG exemplifies the integrated network archetype spanning multiple regulatory jurisdictions, while Cargill, Incorporated represents North American scale advantages in corn-based fermentation consistency. Godavari Biorefineries Ltd occupies a position within the Asia-Pacific specialist tier focused on molasses-derived pharmaceutical excipient supply. These three anchors illustrate how geographic feedstock endowment and regulatory proximity shape competitive positioning across certification-intensive segments.
| Leading Market Players |
|---|
| Merck KGaA |
| CropEnergies AG |
| Archer Daniels Midland Company |
| LyondellBasell Industries Holdings BV |
| Godavari Biorefineries Ltd |
| Cargill, Incorporated |
| Wilmar International |
| Mitsubishi Chemical Corporation |
| Sasol |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization gaps between European biorefineries and Indian molasses distillers compress margin floors for mid-scale operators lacking multi-pharmacopeia coverage. Feedstock proximity to corn belts or sugar cane regions determines who captures contract renewals as FDA and CDSCO inspections accelerate vendor consolidation.
Pricing Analysis
Certification level (USP-NF/EP/IP-grade) creates the primary spread between pharmaceutical solvent tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies buyers: multinational drug manufacturers absorb 15-25% premiums for multi-pharmacopeia ethanol, while industrial solvent purchasers optimize for volume throughput. Cost compression in denatured alcohol runs through bio-based glycol ether substitution. Generic API producers in India exhibit highest price sensitivity; laboratory reagent buyers show least sensitivity due to documentation requirements.
Supply Chain Analysis
Strategic stockpiling dominates pharmaceutical-grade procurement as CDSCO-mandated local sourcing rules disrupt just-in-time imports into India. Supply concentrates in Germany, India, and the United States, with fermentation infrastructure drawing from corn, molasses, and sugar cane feedstocks. REACH registration concentration in Europe creates single-source vulnerability for USP-NF dual-certified ethanol. Distribution runs through specialty chemical distributors serving laboratory buyers with lot-traceable documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-pharmacopeia certification interoperability is transforming supplier selection into platform economics, where EXCiPACT GMP documentation acts as the ecosystem gatekeeper for multinational pharmaceutical procurement.
For Market Incumbents: Consolidate regulatory affairs capabilities across USP-NF, EP, and IP jurisdictions to defend against emerging Brazilian and Indian distillers achieving ANVISA-CDSCO harmonization. Deepen backward integration into feedstock cultivation to buffer corn and molasses commodity cycles. Prioritize molecular sieve dehydration upgrades to sustain pharmaceutical-grade output as electric-heated systems displace steam boiler dependencies. For New Entrants and Emerging Players: Anchor in cosmetic-grade isopropyl alcohol for South Korean personal care manufacturers tightening residual impurity limits below 50 ppm. Target direct-to-laboratory distribution channels bypassing traditional wholesale tiers with digital lot-traceability. Pursue dual pharmacopeia certification (USP-NF/ANVISA) for first-mover positioning in Brazil's harmonizing excipient market. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biorefineries combining ethanol dehydration with electrolyzer off-gas for EU Green Deal carbon credit capture. Long-term viability hinges on regulatory proximity to ECHA and FDA inspection corridors. Watch CDSCO disqualification rates among smaller Indian distillers as inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Pharmacopeia Certification Investment | EXCiPACT GMP documentation qualifies suppliers for multinational generic API producer vendor lists. |
| Feedstock Backward Integration | Corn belt proximity in the United States anchors batch-to-batch consistency for North American pharmaceutical solvent demand. |
| Molecular Sieve Dehydration Upgrade | Electric-heated systems eliminate steam boiler dependencies among German pharmaceutical contract manufacturers. |
| Direct-to-Laboratory Distribution Channel | Lot-traceable documentation serves analytical reagent buyers bypassing traditional wholesale tiers. |
| Green Hydrogen Integration | Electrolyzer off-gas capture generates carbon credits under EU Green Deal frameworks for European biorefineries. |
Study Parameters
A spread of perspectives from plant managers at fermentation facilities, procurement leads at pharmaceutical manufacturers, regulatory affairs specialists, and distribution channel partners converged on the working assumptions for capacity build trajectories. Secondary validation drew from FDA 21 CFR filings, ECHA REACH registration databases, CDSCO excipient guidelines, and customs trade data. Bottom-up ethanol volume modeling triangulated against top-down pharmaceutical solvent demand projections.
Segmentation dimensions modeled include purity grade tier, end-use application, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed capacity utilization rates and contract renewal cycle analysis. Forecast inputs incorporated molasses-to-ethanol conversion yields and molecular sieve adoption curves.
Material uncertainties — feedstock commodity volatility, pharmacopeia monograph revision timing, and ECHA substance evaluation delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory inspection intensity and certification cost trajectories. Revision becomes warranted when CDSCO disqualification rates or REACH registration gaps cross thresholds disrupting supply continuity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Nitro Cocktails Market
Alcoholic Beverages
South America Craft Beer Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
RTD Bottled Cocktails Market
Alcoholic Beverages
Hopped Malt Extract Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Beer Filter System Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Scotch Whisky Market
Alcoholic Beverages
Vodka Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Still Wine Market
Alcoholic Beverages
Gin and Tonic Tea Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market