
 Global Wax Market | 2026-2036
Global Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wax Market Outlook
China is rewriting capacity dynamics across the wax value chain as state-backed refiners expand paraffin output. Sasol Ltd. leverages its Fischer-Tropsch synthetic wax technology to dominate specialty grades for coatings. ExxonMobil Corporation anchors North American supply through integrated refinery-slack wax operations. Sinopec Corporation competes on volume, feeding Asia-Pacific packaging lines with microcrystalline streams.
Wax comprises a diverse class of lipophilic substances ranging from refined hydrocarbon distillates to naturally secreted esters, with melt points typically spanning 46°C to 68°C depending on carbon chain distribution and crystalline structure. Industrial waxes function primarily as barrier agents, lubricants, and binding matrices across formulated products. Paraffin wax still occupies the largest share of commodity volume, though synthetic wax is accelerating fastest as automotive and electronics end users demand tighter specification control. Beeswax commands premium positioning in personal care and pharmaceuticals where natural certification unlocks margin pools unavailable to petroleum-derived alternatives.
EPA guidelines on volatile organic compound emissions constrain coating formulations in the United States, pushing buyers toward low-odor microcrystalline and synthetic bases. REACH registration requirements in Europe filter out uncharacterized aromatic content, reshaping import eligibility for Asian refiners. China's GB standards on food-contact materials govern the wax grades permitted in domestic packaging applications. Stakeholders must track how diverging national chemical frameworks fragment product specifications and force parallel inventory strategies.
Market Dynamics
Refinery consolidation in Asia and tightening aromatic specifications under REACH are forcing parallel inventory strategies across the wax value chain, fragmenting product grades and reshaping supplier-buyer contracting terms.
Growth Catalysts
- Clean-label mandate:Candle manufacturers in Southeast Asia are accelerating procurement of natural wax alternatives as consumer preference shifts away from petroleum-derived bases.
- REACH aromatic limits:ECHA registration requirements are redirecting European formulation strategies toward low-aromatic synthetic and microcrystalline grades, opening specification-controlled supply contracts.
- Hot-melt adhesive scale-up:Packaging converters in China are expanding paraffin and microcrystalline consumption to serve e-commerce logistics growth.
Market Restraints
- Crude-linked feedstock volatility:Slack wax and paraffin output remains tethered to refinery economics, exposing margin compression during oil price spikes.
- Supplier concentration risk:State-backed Chinese refiners control incremental paraffin capacity, creating single-source dependency for Asia-Pacific packaging lines.
- Biopolymer substitution:Polylactic acid and starch-based alternatives are capturing food-contact barrier applications previously served by petroleum wax coatings.
Strategic Opportunities
- India packaging penetration:Underdeveloped hot-melt adhesive infrastructure in secondary cities offers first-mover positioning for synthetic wax suppliers.
- EU Green Deal tailwind:Bio-based certification incentives are unlocking premium positioning for beeswax and vegetable-derived grades in personal care.
- Digital coating formulation:AI-driven melt-point optimization is virtualizing R&D cycles, compressing time-to-specification for automotive electronics buyers.
Industry Challenges
- Fischer-Tropsch talent scarcity:Synthetic wax production requires specialized catalysis expertise concentrated at a handful of research centers.
- REACH registration timelines:ECHA dossier preparation for novel wax grades extends 18-24 months, delaying market entry.
- Legacy system integration:Refinery slack wax operations require capital-intensive retooling to meet food-contact GB standards for Chinese export eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wax Market |
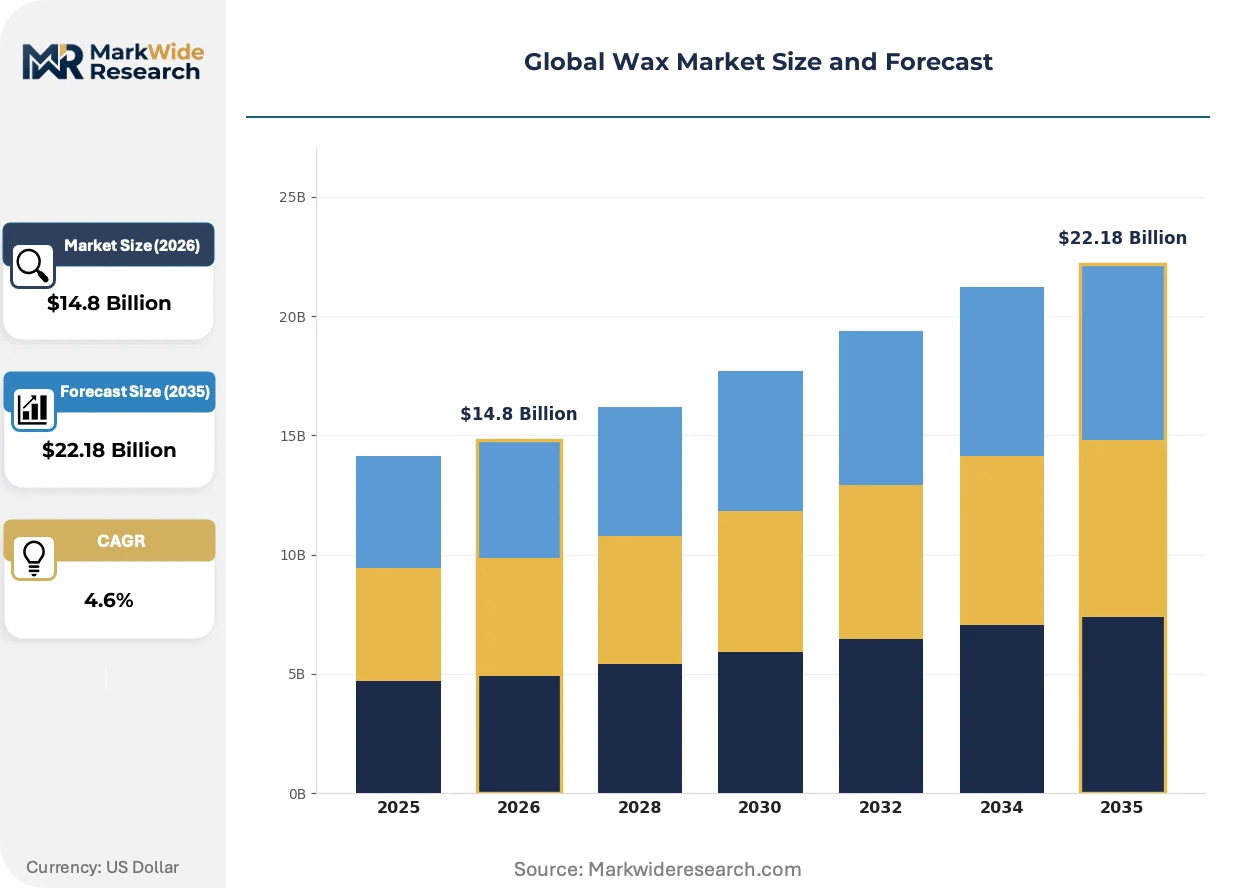
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Paraffin Wax, Microcrystalline Wax, Synthetic Wax, Beeswax Application: Candles, Coatings, Packaging, Cosmetics Form: Solid, Liquid, Emulsion, Paste End User: Food Industry, Electronics, Personal Care, Pharmaceuticals |
| Companies Covered | Sasol Ltd., China National Petroleum Corporation, ExxonMobil Corporation, The International Group, Inc., Petrobras, Sinopec Corporation, HollyFrontier Corporation, HCI Wax Co., Ltd., Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wax Market Strategic Shifts
Digital formulation tools and regulatory fragmentation are compressing product development cycles while segmenting the wax market into specification-controlled specialty tiers and undifferentiated commodity streams.
AI-driven molecular modeling is virtualizing melt-point and crystallinity prediction for synthetic wax blends. Coatings formulators in automotive electronics are adopting these platforms to reduce bench-testing iterations by half. The technology is virtualizing traditional empirical R&D, shifting competitive advantage toward data-science capabilities and away from legacy formulation expertise.
REACH aromatic content thresholds are hardening import eligibility for Asian refiners into European coatings markets. ECHA enforcement of substance characterization requirements is filtering out uncharacterized petroleum distillates. German and French coating houses are responding by dual-sourcing from Fischer-Tropsch producers and certifying low-aromatic microcrystalline grades.
Specification-based contracting is replacing volume-commitment agreements in electronics and pharmaceutical wax procurement. Buyers are unbundling after-sales technical service from material supply, compressing supplier margins on commodity grades. This pattern is most visible in South Korean and Japanese electronics clusters where incoming material certification requirements have tightened.
Global Wax Market Segmentation
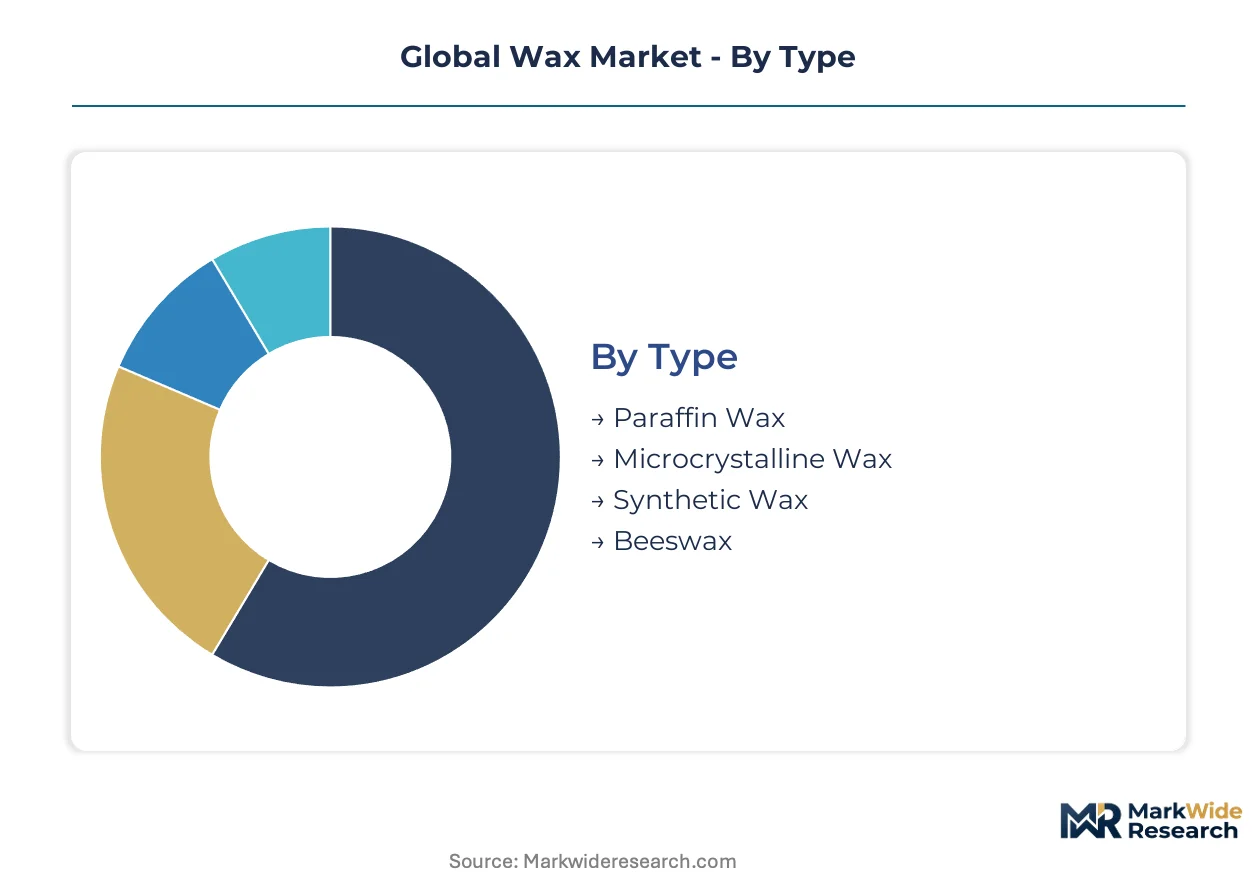
Wax segmentation tracks divergent specification requirements across petroleum-derived commodity streams and certified natural grades. Procurement strategies fragment by end-use compliance burden, with coating formulators, candle manufacturers, and pharmaceutical packagers each demanding distinct certification tiers.
Type:
Use-case spectrum spans high-volume barrier coatings to precision-certified pharmaceutical matrices, with feedstock origin determining regulatory eligibility and margin structure.
- Paraffin Wax:Refined petroleum distillate with crystalline structure optimized for hot-melt adhesives and container coatings. Packaging converters in China scale procurement to serve e-commerce logistics expansion, though crude-linked feedstock costs compress margins during oil price volatility.
- Synthetic Wax:Fischer-Tropsch catalysis yields tightly controlled carbon chain distributions for automotive electronics and specialty coatings. Demand concentrates in German and Japanese manufacturing clusters where REACH aromatic limits and JIS standards filter out uncharacterized petroleum alternatives.
- Microcrystalline Wax:Amorphous structure from heavy residual refining delivers superior flexibility for rubber and adhesive applications.
- Beeswax:Natural ester composition commands certification premiums in EU personal care markets under EU Green Deal bio-based incentives.
Established volume favors Paraffin Wax; emerging adoption favors Synthetic Wax.
Application:
Cost tier separation runs from undifferentiated commodity candles to specification-controlled pharmaceutical coatings.
- Candles:Clean-label mandates in Southeast Asia redirect procurement toward beeswax and vegetable-derived alternatives as consumer preference shifts from petroleum bases. Indonesian and Vietnamese manufacturers dual-source natural grades to serve export markets.
- Coatings:Automotive electronics and industrial barrier applications demand synthetic and microcrystalline grades with documented aromatic content under REACH and EPA guidelines. South Korean formulators unbundle technical service from material supply to compress supplier margins.
- Packaging:Hot-melt adhesive scale-up in Chinese logistics infrastructure drives paraffin and microcrystalline consumption.
- Cosmetics:EU Green Deal certification unlocks premium positioning for beeswax in lip care and emollient formulations.
Volume concentration sits with Packaging; steepest expansion trajectory belongs to Coatings.
Form:
Supply chain configuration favors solid bulk logistics for commodity grades, while liquid and emulsion forms capture formulated product integration.
- Solid:Slab and pellet formats dominate refinery-direct procurement for candle manufacturing and hot-melt compounding. Chinese state-backed refiners control incremental paraffin capacity in this form.
- Liquid:Molten bulk delivery eliminates remelt energy costs for high-volume packaging converters with dedicated storage infrastructure.
- Emulsion:Water-based dispersions serve coating formulators seeking direct integration into aqueous systems without solvent handling.
- Paste:Semi-solid consistency targets pharmaceutical and personal care compounding where precise viscosity control matters.
Operational scale favors Solid; formulation convenience favors Emulsion.
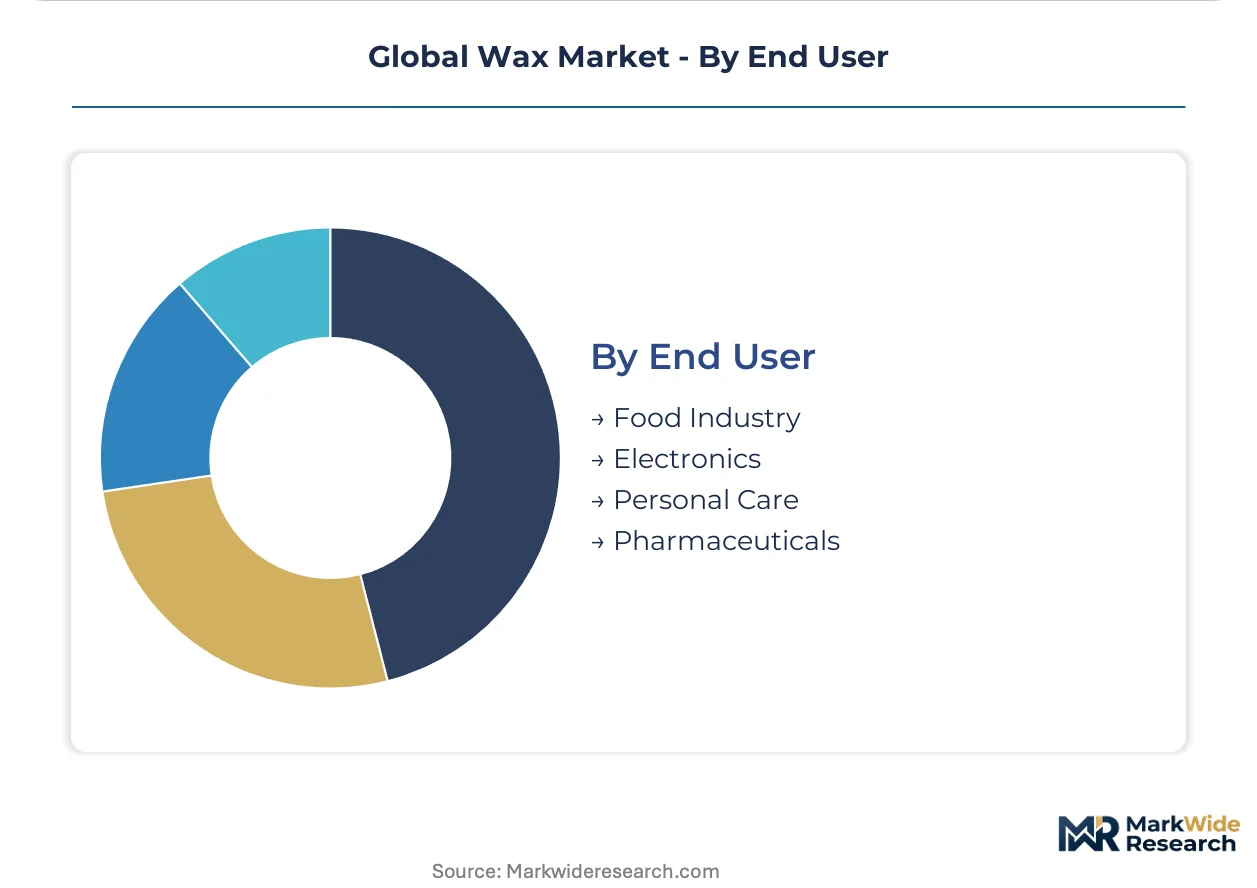
End User:
Regulatory stringency stratifies end users, with food-contact and pharmaceutical applications imposing the tightest certification requirements.
- Food Industry:GB standards in China and FDA regulations in the United States govern wax grades permitted for direct and indirect food contact. Cheese coating and produce preservation applications require documented purity tiers.
- Electronics:REACH aromatic limits and RoHS substance restrictions filter supplier eligibility for potting compounds and insulating coatings in German and Japanese manufacturing.
- Personal Care:EU Green Deal bio-based certification and ECHA registration requirements reshape beeswax and vegetable wax procurement for premium positioning.
- Pharmaceuticals:USP and EP monograph compliance creates specification-controlled supply contracts for tablet coatings and sustained-release matrices.
Certification burden is heaviest in Pharmaceuticals; volume scale concentrates in Food Industry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor underwrites Europe's wax logistics, while Chinese state refiners leverage Yangtze River Delta port infrastructure to dominate Asia-Pacific paraffin flows. Diverging regulatory frameworks fragment procurement strategies across major demand centers.
China
Packaging converters in Zhejiang and Jiangsu provinces scale hot-melt adhesive operations to serve domestic e-commerce logistics expansion. GB standards on food-contact materials govern wax grades permitted in domestic packaging applications, filtering import eligibility. State-backed refiners in Shanghai-Ningbo corridor control incremental paraffin capacity, creating single-source dependency for regional packaging lines.
Germany
Automotive electronics manufacturers in Baden-Württemberg demand REACH-compliant synthetic waxes for potting compounds and insulating coatings. ECHA registration requirements filter out uncharacterized aromatic content, redirecting formulation strategies toward low-aromatic grades. Stuttgart manufacturing cluster dual-sources from Fischer-Tropsch producers to secure specification-controlled supply contracts.
United States
Coating formulators in Texas and Louisiana face EPA volatile organic compound emission constraints, pushing procurement toward low-odor microcrystalline and synthetic bases. FDA regulations govern wax grades for direct and indirect food contact in cheese coating applications. Gulf Coast refinery-slack wax operations anchor North American supply through integrated petrochemical infrastructure.
Japan
Electronics assemblers in Kansai region enforce JIS standards alongside REACH aromatic limits, filtering supplier eligibility for precision coatings. METI industrial guidelines shape procurement protocols for automotive and electronics end users. Osaka-Kyoto manufacturing belt concentrates demand for tightly specified synthetic wax grades with documented carbon chain distributions.
India
Underdeveloped hot-melt adhesive infrastructure in secondary cities offers first-mover positioning for synthetic wax suppliers targeting packaging penetration. BIS quality standards govern industrial wax specifications for domestic manufacturing. Maharashtra and Gujarat industrial corridors attract investment in logistics-adjacent coating operations as e-commerce fulfillment networks expand.
Global Wax Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in specification-controlled supply relationships. The market structure concentrates around state-backed refiners with captive feedstock access and integrated petrochemical complexes. Three archetypes dominate: volume-driven paraffin suppliers, Fischer-Tropsch synthetic specialists, and natural wax certification players. Competitive moves center on backward integration into refinery operations and geographic expansion through distribution partnerships.
Among integrated energy majors, Sasol Ltd., ExxonMobil Corporation, and Sinopec Corporation occupy positions across the value chain spectrum. Sasol exemplifies the Fischer-Tropsch synthetic tier through catalysis-derived specialty grades. ExxonMobil anchors North American supply architecture through refinery-integrated operations. Sinopec represents state-backed volume competition feeding Asia-Pacific packaging demand. These three entities illustrate how feedstock access and regulatory compliance capabilities stratify competitive positioning.
| Leading Market Players |
|---|
| Sasol Ltd. |
| China National Petroleum Corporation |
| ExxonMobil Corporation |
| The International Group, Inc. |
| Petrobras |
| Sinopec Corporation |
| HollyFrontier Corporation |
| HCI Wax Co., Ltd. |
| Shell plc |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp pipeline corridor anchors European wax logistics costs, with freight differentials between this hub and Asia-Pacific ports directly shaping how suppliers tier pricing power across REACH-compliant specialty grades and undifferentiated commodity paraffin streams.
Pricing Analysis
Volume-discount tiering separates specification-controlled synthetic grades from commodity paraffin slabs, with Fischer-Tropsch producers commanding premium positioning for documented low-aromatic content under ECHA registration requirements. Price differentiation rests on certification grade and after-sales technical service bundling, with South Korean electronics buyers unbundling the latter to compress supplier margins. Cost compression in commodity paraffin is intensifying because Chinese state-backed refiners control incremental capacity. Packaging converters in Zhejiang province exhibit highest price sensitivity, while German automotive electronics manufacturers show lowest sensitivity due to REACH compliance mandates.
Supply Chain Analysis
Upstream slack wax feedstock availability draws from refinery economics in China, the United States, and Saudi Arabia, with crude-linked volatility tethering margin stability across derivative wax grades. Raw material dependencies center on heavy residual oil streams, Fischer-Tropsch synthesis gas, and natural ester harvests from apiculture operations. Single-source vulnerability concentrates in the Shanghai-Ningbo corridor where state refiners dominate incremental paraffin output. Distribution runs through bulk liquid terminals for high-volume packaging converters and slab/pellet logistics for candle manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as AI-driven formulation tools virtualize R&D cycles and unbundle technical service from material supply, creating interoperability standards that favor data-science capabilities over legacy formulation expertise.
For Market Incumbents:Entrench specification-controlled supply relationships by investing in REACH dossier completion for novel synthetic grades before ECHA enforcement windows tighten. Backward integration into captive Fischer-Tropsch catalysis capacity secures feedstock autonomy against crude-linked volatility. Counter biopolymer substitution threats in food-contact applications by certifying low-aromatic microcrystalline grades under GB standards for Chinese export eligibility.
For New Entrants and Emerging Players:Establish a beachhead in India's underdeveloped hot-melt adhesive infrastructure by targeting Maharashtra and Gujarat industrial corridors where logistics-adjacent coating operations are expanding. Penetrate EU personal care markets through EU Green Deal bio-based certification for beeswax and vegetable-derived alternatives. Deploy direct technical service partnerships as a go-to-market angle to differentiate against volume-committed commodity suppliers.
For Investors and Strategic Acquirers:Carve-out targets emerge from integrated energy majors seeking to divest non-core wax operations amid refinery consolidation pressures. Long-term viability favors synthetic specialists with Fischer-Tropsch expertise and natural wax certifiers with established EU bio-based positioning. Monitor ECHA registration timeline bottlenecks as an inflection indicator for supply-constrained premium grade availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fischer-Tropsch Capacity | Captures margin pool from catalysis-derived specialty grades demanded by German automotive electronics manufacturers. |
| REACH Dossier Completion for Novel Grades | Unlocks ECHA registration ahead of enforcement windows filtering uncharacterized aromatic content from European coatings markets. |
| EU Green Deal Bio-Based Certification | Positions beeswax and vegetable-derived grades for premium personal care procurement under sustainability incentives. |
| AI-Driven Formulation Platform Deployment | Compresses R&D cycles for South Korean electronics buyers seeking virtualized melt-point optimization. |
| Geographic Expansion into Indian Secondary Cities | Captures first-mover positioning in underdeveloped hot-melt adhesive infrastructure serving e-commerce logistics growth. |
Study Parameters
The analysis maps paraffin, synthetic, microcrystalline, and natural wax sub-sectors, each validated through procurement directors at packaging converters, R&D leads at coatings formulators, and regulatory affairs specialists at integrated refiners. Primary interviews with candle manufacturers, hot-melt adhesive compounders, and pharmaceutical coating houses combined with secondary validation from customs trade data, ECHA registration databases, SEC 10-K filings, and ACC industry reports. Bottom-up grade-by-grade volume builds triangulated against top-down refinery capacity assessments.
Assumptions held fixed include ECHA enforcement intensity, GB standard stability for food-contact materials, and Fischer-Tropsch catalysis yield coefficients, while crude price trajectories and biopolymer substitution rates were varied across sensitivity scenarios. Segmentation dimensions modeled span feedstock origin, application end-use, certification tier, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections incorporating e-commerce logistics expansion rates and REACH compliance cost pass-through assumptions.
Sensitivities concentrate around crude-linked feedstock volatility, ECHA registration timeline delays, and Chinese state refiner capacity allocation decisions. Cross-checking against customs trade flow data and refinery operating rate disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Global Chlorinated Paraffin Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
Triisostearyl Citrate Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
North America Alcohol Ethoxylates Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Global Decant Oil Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Glycerine Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Stearic Acid Market