
 Dot Matrix Printer Market | 2026-2036
Dot Matrix Printer Market Size, Share, and Industry Trends Forecast 2026-2036
Dot Matrix Printer Market Analysis
Buyer concentration among banking and government procurement offices is rebalancing as fragmented healthcare clinics and regional retail chains enter the installed base. Epson sustains technology leadership through piezo-impact hybrid mechanisms for high-speed transaction printing. Panasonic dominates Japanese institutional channels with ruggedized continuous-feed systems for financial clearinghouses. OKI specializes in multi-color impact heads that serve logistics firms requiring color-coded freight documentation.
A dot matrix printer forms characters and graphics by striking an ink-soaked ribbon against paper with a matrix of tiny pins, typically operating at 9-pin or 24-pin densities with print speeds ranging from 300 to over 1,000 characters per second depending on model class. Its primary commercial purpose remains producing multi-part carbonless forms, continuous tractor-feed documents, and audit-compliant hard copies in environments where digital signatures lack legal standing. High-speed impact technology anchors the largest revenue pool due to sustained demand from banks and freight operators running 24-hour print cycles. Multi-color product types capture expanding margin pools as warehousing and distribution centers adopt color-coded picking lists and shipping labels. Direct sales channels control the premium institutional segment, while distributors occupy mid-market education and small-clinic deployments.
EPA energy-efficiency guidelines shape North American procurement specifications for office equipment, pushing manufacturers toward low-power standby modes and reduced consumable waste. Ecodesign requirements under the EU Green Deal restrict hazardous substances in electronic peripherals, directly affecting ink ribbon formulations and printer chassis recyclability. India's BIS certification mandates electrical safety and electromagnetic compatibility testing for all imported printing hardware, creating a compliance threshold for foreign suppliers. Stakeholders must monitor whether emerging digital documentation mandates in banking and healthcare erode the legal necessity for physical multi-part forms.
Market Dynamics
Banking compliance mandates for physical audit trails sustain demand for impact-printed multi-part forms, even as digital documentation spreads through adjacent sectors. This tension between regulatory retention requirements and paperless transition pressures defines current market structure.
Growth Catalysts
- REACH substance restrictions:Manufacturers reformulate ink ribbons and housing plastics to meet ECHA chemical safety standards, creating compliant product lines that qualify for EU public procurement.
- Freight logistics digitization gaps:Warehousing operators in India deploy color-coded dot matrix output for picking lists where barcode scanning infrastructure remains incomplete.
- BIS certification thresholds:India's mandatory electrical safety and electromagnetic compatibility testing for imported hardware filters low-cost competitors, protecting established supplier margins.
Market Restraints
- Raw material volatility:Nylon and polyester yarn prices for fabric ribbons fluctuate with crude oil derivatives, compressing consumable margins unpredictably.
- Substitute technology encroachment:Thermal transfer and laser printers capture single-part documentation applications in healthcare clinics previously served by 9-pin impact devices.
- Component supply concentration:Piezoelectric actuator fabrication for hybrid print heads concentrates among Japanese and Taiwanese component specialists.
Strategic Opportunities
- Rural banking infrastructure:Regional cooperative banks across India's tier-3 and tier-4 cities maintain tractor-feed systems for passbook and ledger printing with minimal digital integration.
- EPA energy-efficiency procurement:US federal purchasing guidelines favor low-power standby modes, rewarding manufacturers who redesign power management circuits.
- Healthcare claims documentation:HIPAA-mandated physical record retention in US clinics preserves niche demand for carbonless form printing despite EHR expansion.
Industry Challenges
- Legacy system integration friction:New printer installations must interface with COBOL-based mainframe environments prevalent in financial clearinghouses, requiring specialized emulation firmware.
- REACH compliance timeline compression:ECHA substance restriction updates force rapid reformulation cycles for ribbon inks, straining R&D bandwidth at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dot Matrix Printer Market |
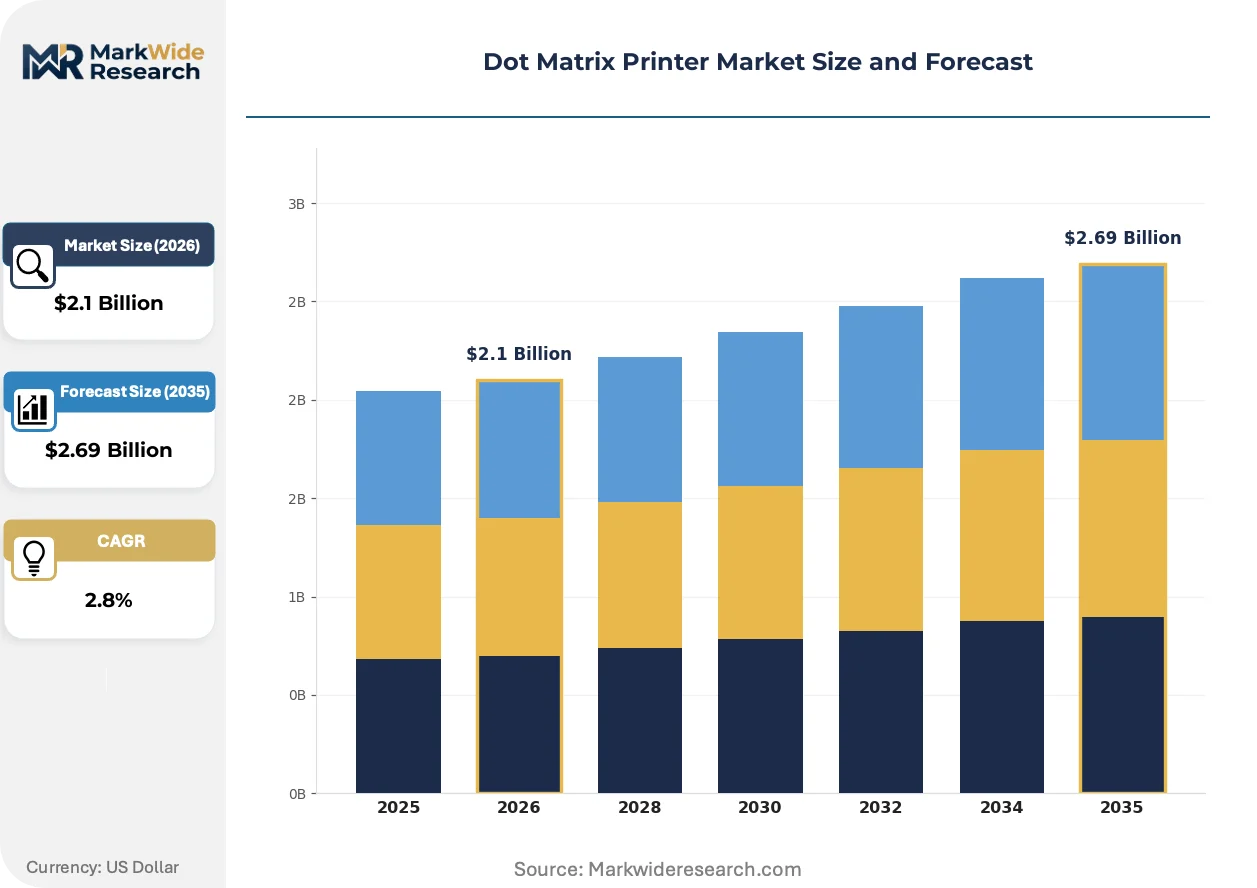
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.69 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Color, Multi-Color, High-Speed, Low-Speed End User: Retail, Banking, Healthcare, Education Technology: Impact, Non-Impact, Hybrid, Continuous Feed Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Domino Printing Sciences plc, Panasonic, Epson, Toshiba, Lexmark, OKI, Fujitsu, Markem-Imaje SAS, Videojet Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dot Matrix Printer Market Emerging Trajectories
Piezo-impact hybrid mechanisms are redrawing performance boundaries between traditional impact and non-impact technologies. Three developments are compressing the technology lifecycle and reshaping procurement patterns.
Hybrid piezoelectric actuation is decentralizing print speed capabilities across mid-range product tiers. Regional freight operators in Southeast Asia adopt these mechanisms for 24-hour dispatch documentation without premium-tier capital outlay. The technology is compressing the price-performance gap that previously separated institutional banking equipment from logistics-grade hardware.
EU Green Deal ecodesign requirements are mandating chassis recyclability percentages and restricted substance lists for electronic peripherals. Manufacturers redesign plastic housing formulations and ribbon substrate materials to satisfy circular-economy audit criteria. German automotive parts distributors now specify compliance documentation for warehouse printing equipment alongside production machinery.
Consolidated procurement through national banking consortia is displacing branch-level purchasing autonomy. India's public sector bank mergers centralize dot matrix fleet decisions to headquarters procurement cells, reducing distributor influence. Regional equipment vendors pivot toward maintenance contract bundling rather than unit sales to retain revenue attachment.
Dot Matrix Printer Market Segmentation
Dot matrix printer procurement patterns diverge sharply across product tiers and institutional buyer types. Capital allocation, compliance mandates, and legacy system compatibility each reshape which segments capture volume and margin.
Product Type:
Capital intensity concentrates in high-speed and hybrid mechanism production lines, where precision actuator fabrication and extended-duty chassis engineering demand specialized tooling investments.
- High-Speed:These units deploy 24-pin print heads with sustained throughput exceeding 800 characters per second for 24-hour banking and freight operations. Indian public sector banks and clearinghouses in Mumbai and Delhi anchor demand, driven by RBI-mandated physical audit trail retention for transaction logs.
- Multi-Color:Four-color ribbon systems enable color-coded freight documentation and warehouse picking lists. Logistics operators across Southeast Asia adopt these units where barcode infrastructure remains incomplete, particularly in Indonesian and Vietnamese distribution hubs.
- Single-Color:9-pin entry-level units serve cost-constrained education and small-clinic environments with basic receipt and form printing requirements.
- Low-Speed:Compact desktop models address intermittent printing needs in back-office administrative settings with limited document volumes.
High-speed equipment absorbs the bulk of installed capacity in financial clearinghouses; multi-color systems are expanding most quickly through logistics networks.
End User:
Application-specific durability requirements and regulatory compliance burdens segment buyer priorities across institutional categories.
- Banking:Continuous-feed tractor mechanisms handle passbook updates, multi-part loan documentation, and audit-compliant transaction logs. Cooperative banks across India's tier-3 and tier-4 cities sustain demand where digital infrastructure penetration remains shallow.
- Healthcare:HIPAA-mandated physical record retention preserves niche demand for carbonless form printing in US clinics, even as EHR systems expand. Small practices in rural Texas and Ohio maintain impact printers for claims documentation.
- Retail:Point-of-sale receipt printing and inventory documentation drive replacement cycles in regional chains with legacy POS integrations.
- Education:Administrative form printing and student record documentation sustain modest volumes in public school districts with constrained technology budgets.
Banking commands the dominant share of capital deployment; healthcare is climbing the fastest as compliance documentation requirements tighten.
Technology:
Manufacturing complexity and component sourcing constraints concentrate investment in piezoelectric hybrid and continuous-feed system production.
- Hybrid:Piezo-impact mechanisms merge impact reliability with enhanced speed precision, compressing the price-performance gap between institutional and logistics-grade equipment. Southeast Asian freight operators adopt these for round-the-clock dispatch documentation without premium-tier capital outlay.
- Continuous Feed:Tractor-feed paper handling systems serve high-volume financial clearinghouses and government ledger operations with minimal operator intervention. Japanese institutional channels specify ruggedized variants for 24-hour clearinghouse cycles.
- Impact:Conventional solenoid-driven pin arrays dominate entry-level and replacement markets with proven reliability and minimal maintenance requirements.
- Non-Impact:Thermal and inkjet alternatives capture single-part documentation applications in healthcare and retail settings previously served by basic impact devices.
Hybrid technology is gaining share fastest among mid-tier logistics operators; continuous feed retains the largest installed base in financial infrastructure.
Distribution Channel:
Customer scale and service integration requirements determine channel economics and margin capture across procurement pathways.
- Direct Sales:National banking consortia and government procurement cells negotiate fleet-wide contracts with bundled maintenance and firmware support. India's public sector bank mergers concentrate purchasing authority at headquarters level.
- Distributors:Regional equipment vendors serve mid-market education and healthcare deployments with localized technical support and consumable replenishment programs.
- Resellers:Value-added resellers integrate printers with legacy mainframe emulation software for COBOL-based financial environments.
- Online Retail:E-commerce platforms address small-clinic and individual practitioner replacement purchases with standardized configurations and rapid fulfillment.
Direct sales channels attach the highest service revenue; distributor relationships are expanding most quickly as regional healthcare networks consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nylon and polyester yarn production clusters in East Asia and South Asia anchor consumable supply chains for fabric ribbon manufacturing. Banking compliance mandates and logistics digitization gaps distribute demand across distinct national procurement patterns.
India
Regional cooperative banks across tier-3 and tier-4 cities sustain tractor-feed system deployments for passbook and ledger printing with minimal digital integration. RBI-mandated physical audit trail retention for transaction logs reinforces institutional demand. Mumbai and Delhi clearinghouses operate 24-hour high-speed impact printer fleets for financial documentation.
United States
HIPAA-mandated physical record retention in rural Texas and Ohio clinics preserves carbonless form printing demand despite EHR expansion. EPA energy-efficiency procurement guidelines favor low-power standby modes in federal purchasing specifications. Healthcare claims documentation workflows in small practices maintain niche impact printer installations.
Japan
Financial clearinghouses specify ruggedized continuous-feed systems for 24-hour transaction processing cycles. METI industrial standards shape precision actuator fabrication requirements for hybrid mechanism production. Tokyo and Osaka institutional channels concentrate procurement authority for national banking consortia.
Germany
EU Green Deal ecodesign requirements mandate chassis recyclability percentages and restricted substance lists for electronic peripherals. ECHA REACH substance restrictions force rapid reformulation cycles for ribbon ink compositions. Automotive parts distributors in Stuttgart and Munich now specify compliance documentation for warehouse printing equipment.
Indonesia
Logistics operators deploy color-coded dot matrix output for picking lists where barcode scanning infrastructure remains incomplete. Distribution hubs across Java and Sumatra adopt multi-color ribbon systems for freight documentation. Jakarta warehousing centers anchor Southeast Asian demand expansion for mid-tier logistics-grade hardware.
Dot Matrix Printer Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent industrial printing applications outside core banking segments. The vendor base stratifies across precision mechanism fabricators, consumable specialists, and system integrators serving legacy mainframe environments. Three archetypes dominate: Japanese precision electronics conglomerates, European industrial coding specialists, and diversified office equipment manufacturers with impact printing heritage. Competitive moves concentrate on REACH-compliant material reformulation and hybrid piezoelectric mechanism licensing.
Within the diversified electronics tier, Panasonic Corporation and Fujitsu Limited occupy positions anchored in institutional channel relationships. Epson exemplifies precision mechanism specialization through piezo-impact hybrid technology development. Among industrial coding specialists, Domino Printing Sciences plc and Markem-Imaje SAS represent European heritage in continuous-feed production environments. These groupings illustrate how competitive positioning fragments across mechanism sophistication, regulatory compliance capability, and legacy system integration expertise rather than concentrating in pure scale advantages.
| Leading Market Players |
|---|
| Domino Printing Sciences plc |
| Panasonic |
| Epson |
| Toshiba |
| Lexmark |
| OKI |
| Fujitsu |
| Markem-Imaje SAS |
| Videojet Technologies Inc. |
| Others |
Supply Flow & Price Mechanics
Nylon and polyester yarn prices for fabric ribbons fluctuate with crude oil derivatives, compressing consumable margins unpredictably before reaching tiered equipment pricing across banking, logistics, and healthcare procurement tiers. Manufacturers absorb input volatility through long-term resin contracts while pushing specification-grade premiums for REACH-compliant formulations.
Pricing Analysis
Warranty and firmware support bundling separates institutional direct-sales contracts from unbundled distributor transactions in mid-market education and small-clinic segments. Three-tier pricing structure across premium, standard, and economy levels reflects print speed capability, pin density configuration, and hybrid mechanism inclusion. Cost compression in entry-level 9-pin equipment is intensifying because thermal transfer substitutes capture single-part healthcare applications. Regional cooperative banks in India exhibit highest price sensitivity; Japanese financial clearinghouses accept premium positioning for 24-hour duty-cycle reliability.
Supply Chain Analysis
India's BIS certification mandates and domestic-content preferences for government procurement are reshaping sourcing toward local assembly partners for ribbon substrate and chassis fabrication. Precision actuator fabrication concentrates in Japan and Taiwan; nylon yarn production clusters in China and South Korea. Component supply rests on piezoelectric ceramic sourcing from Japanese specialists, creating single-source vulnerability for hybrid mechanism producers. Distribution runs through national banking consortia for fleet contracts and regional equipment vendors for healthcare and education deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance timeline compression and raw material volatility are forcing mid-tier manufacturers toward exit or acquisition, consolidating viable supply among precision mechanism specialists with reformulation R&D bandwidth.
For Market Incumbents: Anchor market position through captive supply of piezoelectric actuators and backward integration into ribbon substrate production. Defend against thermal transfer encroachment in healthcare by certifying multi-part form reliability under HIPAA retention mandates. Prioritize firmware emulation expertise for COBOL mainframe integration in financial clearinghouses. For New Entrants and Emerging Players: Begin with logistics-grade hybrid mechanisms for Southeast Asian freight operators where barcode infrastructure gaps sustain color-coded dot matrix demand. Target Indonesian and Vietnamese distribution hubs with mid-speed units priced below Japanese institutional tiers. Pursue maintenance contract bundling rather than unit sales to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: ECHA substance restriction announcements are the leading indicator that reformulation-capable manufacturers will capture EU public procurement share. The 5-10 year viability window favors precision mechanism specialists with hybrid technology licensing portfolios over pure consumable suppliers. Acquisition target archetype: mid-tier Japanese or Taiwanese actuator fabricators with dormant impact printing heritage and clean REACH compliance records.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA chemical safety standards qualify product lines for EU public sector banking contracts. |
| Hybrid Mechanism Licensing | Piezo-impact technology licensing compresses price-performance gaps for Southeast Asian logistics operators. |
| Backward Integration into Ribbon Substrates | Captive nylon yarn supply insulates margins from crude oil derivative volatility. |
| Firmware Emulation Development | COBOL mainframe compatibility preserves installed base in Indian and Japanese financial clearinghouses. |
| Maintenance Contract Bundling | Service revenue attachment compensates for declining unit sales as India's bank mergers centralize procurement. |
Methodological Framework
Document review covered regulatory filings from ECHA and EPA, trade customs data for nylon and polyester yarn flows, and BIS certification registries, complemented by interviews with procurement directors at Indian public sector banks, maintenance heads at Japanese financial clearinghouses, and logistics operations managers across Indonesian distribution hubs. Secondary validation drew from RBI circulars on physical audit trail mandates, EU Green Deal ecodesign specifications, and SEC disclosures from diversified electronics manufacturers. Bottom-up equipment deployment estimates triangulated against top-down consumable demand modeling.
Installed base projections and revenue estimates across the analysis window reflect segment-specific CAGRs derived from historical replacement cycles, regulatory retention mandate durability, and technology substitution elasticity. Segmentation dimensions modeled include product speed tier, end-user institutional category, mechanism technology type, and distribution channel structure. Forecast inputs incorporated ribbon consumption rates per device-class, BIS certification approval timelines for new market entrants, and hybrid mechanism adoption curves in Southeast Asian logistics.
Underlying measurement precision varies by segment; high-speed banking equipment carries tighter precision than fragmented small-clinic replacement markets due to consolidated procurement visibility. Forecasts reflect documented assumptions regarding regulatory retention mandate stability and thermal transfer substitution rates in healthcare documentation workflows. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Single Function Printer Market
Printers
Global Ticket Printers Production Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Thermal Inkjet Printer Market
Printers
Multi-Functional Printer Market
Printers
Mobile Printer Market
Printers
Global Printer Market
Printers
Inkjet Printers Market
Printers
Electrophotographic Printing Market
Printers
Inkjet Printing Market
Printers
Global Inkjet Coders Market
Printers
Thermal Printer Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Copier, MFP and Printer Market
Printers
Laser Printer Market
Printers
Global Thermal Printing Market