
 Procream Market | 2026-2036
Procream Market Size, Share, and Industry Trends Forecast 2026-2036
Procream Market Analytics
Supermarket dairy aisles are narrowing as private-label procream lines consolidate shelf space against branded alternatives. L'Oréal S.A. leverages its cosmetics-grade emulsion expertise to supply high-fat cream bases for premium skincare formulations. The Estée Lauder Companies Inc. anchors its procurement through long-term dairy co-operative contracts in Normandy. Procter & Gamble Co. competes on volume scale, diverting food-grade cream surplus into household cleaning emulsions.
Procream denotes processed cream products standardized through homogenization, pasteurization, and fat-content adjustment to specific gravity and viscosity benchmarks for industrial or consumer use. Manufacturers heat-treat raw cream to specific temperatures, then mechanically separate butterfat into whipped, sour, or heavy cream grades for bakery, food service, or retail applications. Whipped cream dominates value pools in European retail due to dessert culture penetration, while heavy cream sustains margin concentration among industrial bakery buyers requiring stable fat matrices. Sour cream extends fastest in North American food service channels where Tex-Mex and Eastern European menu expansions drive volume.
FDA pasteurization standards govern interstate cream commerce in the United States, while EFSA dairy hygiene codes shape European import eligibility and farm-to-fork traceability. India's FSSAI fortification mandates and China's SAMR dairy safety labeling rules each redirect formulation investments toward compliant fat-standardized outputs. Stakeholders must monitor how divergent shelf-life regulations between jurisdictions reshape regional production footprints and cross-border cream concentrate trade flows.
Market Dynamics
The EU Green Deal's farm-to-fork sustainability targets are compressing procurement timelines for dairy ingredient sourcing, forcing manufacturers to reconfigure supply relationships around carbon-accounted cream streams and regenerative agriculture verification.
Growth Catalysts
- ESG-linked procurement mandates:Food service operators in Germany now require Scope 3 emissions documentation for refrigerated cream purchases, redirecting volume toward certified sustainable suppliers.
- Artisanal bakery expansion:Refrigerated cream procurement concentrates in German bakery chains as premium dessert portfolios widen, pulling standardized fat-content products into regional distribution networks.
- Fortification compliance:India's FSSAI mandates redirect formulation investments toward micronutrient-enhanced cream outputs, opening export channels for compliant processors.
Market Restraints
- Butterfat input volatility:Feed cost fluctuations in key dairy regions transmit directly into cream base pricing, compressing margin stability for standardized product manufacturers.
- Supply concentration risk:European dairy co-operatives control disproportionate volumes of high-fat cream suitable for cosmetics-grade emulsion, creating procurement bottlenecks for non-integrated buyers.
- Cross-jurisdictional shelf-life divergence:FDA pasteurization standards and EFSA hygiene codes impose incompatible processing parameters, fragmenting production footprints and limiting scale economies.
Strategic Opportunities
- Underpenetrated food service channels:Tex-Mex and Eastern European menu expansions in North American food service accelerate sour cream volume, outpacing retail growth rates.
- Cosmetics-grade emulsion convergence:Skincare formulators seek high-fat cream bases with specific gravity benchmarks, creating premium tier separation from commodity food-grade streams.
- Private-label consolidation:Supermarket dairy aisle narrowing favors processors with flexible co-packing capabilities, capturing shelf space from fragmented branded alternatives.
Industry Challenges
- Carbon accounting skill scarcity:Farm-to-fork traceability systems require specialized data architecture talent that dairy processors struggle to recruit against technology sector competition.
- Legacy equipment retrofit costs:Homogenization and pasteurization lines require capital-intensive upgrades to meet divergent jurisdictional temperature standards simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Procream Market |
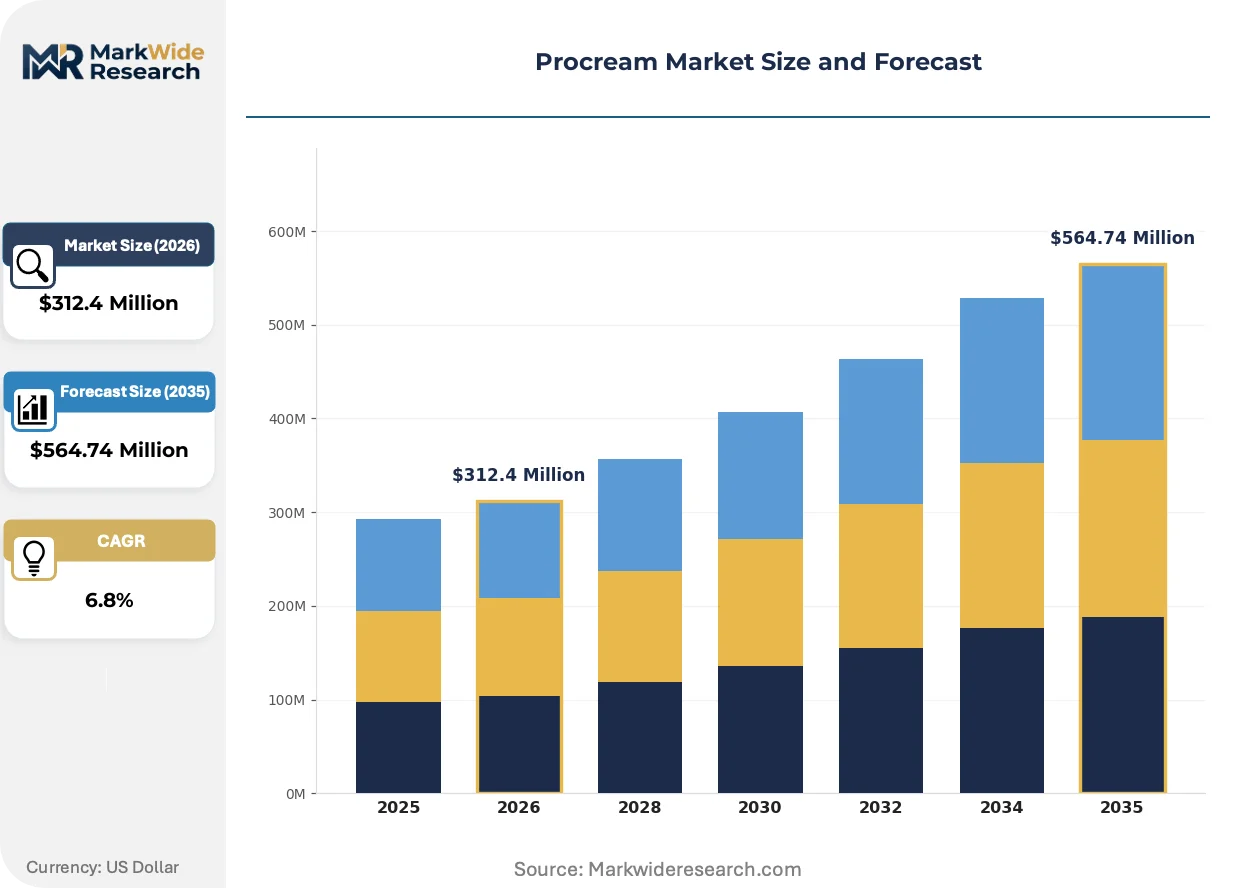
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whipped Cream, Sour Cream, Cream Cheese, Heavy Cream Packaging Type: Plastic Tub, Glass Jar, Carton, Sachet End User: Food Service, Retail, Bakery, Dairy Industry Distribution Channel: Online Stores, Supermarkets, Convenience Stores, Wholesale Suppliers |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Procter & Gamble Co., Johnson & Johnson, Unilever PLC, Shiseido Company, Limited, Beiersdorf AG, Colgate-Palmolive Company, Avon Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Procream Market Evolving Landscape
Digital traceability infrastructure is compressing verification timelines for sustainability claims, while formulation science advances enable fat-matrix stability across wider temperature ranges.
Blockchain-enabled batch tracking is virtualizing the documentation layer for cream provenance, replacing paper-based farm records with immutable ledgers. German bakery chains and Normandy dairy co-operatives pilot these systems fastest. This technology is virtualizing audit costs while accelerating ESG compliance for export eligibility.
REACH chemical safety registrations and EU Green Deal carbon-border adjustments now govern cream-derived ingredient imports into European processing facilities. Cosmetics manufacturers reformulate emulsion bases to exclude flagged substances ahead of sunset dates. Heavy cream grades for industrial bakery applications face heightened scrutiny on processing aid residues.
Direct sourcing contracts between food service operators and regional dairy processors are displacing traditional distributor intermediaries. Large bakery chains in Germany negotiate refrigerated cream procurement directly with Normandy co-operatives, compressing margin layers. This channel restructuring concentrates most visibly in premium dessert and beverage applications where temperature integrity commands price premiums.
Procream Market Segmentation
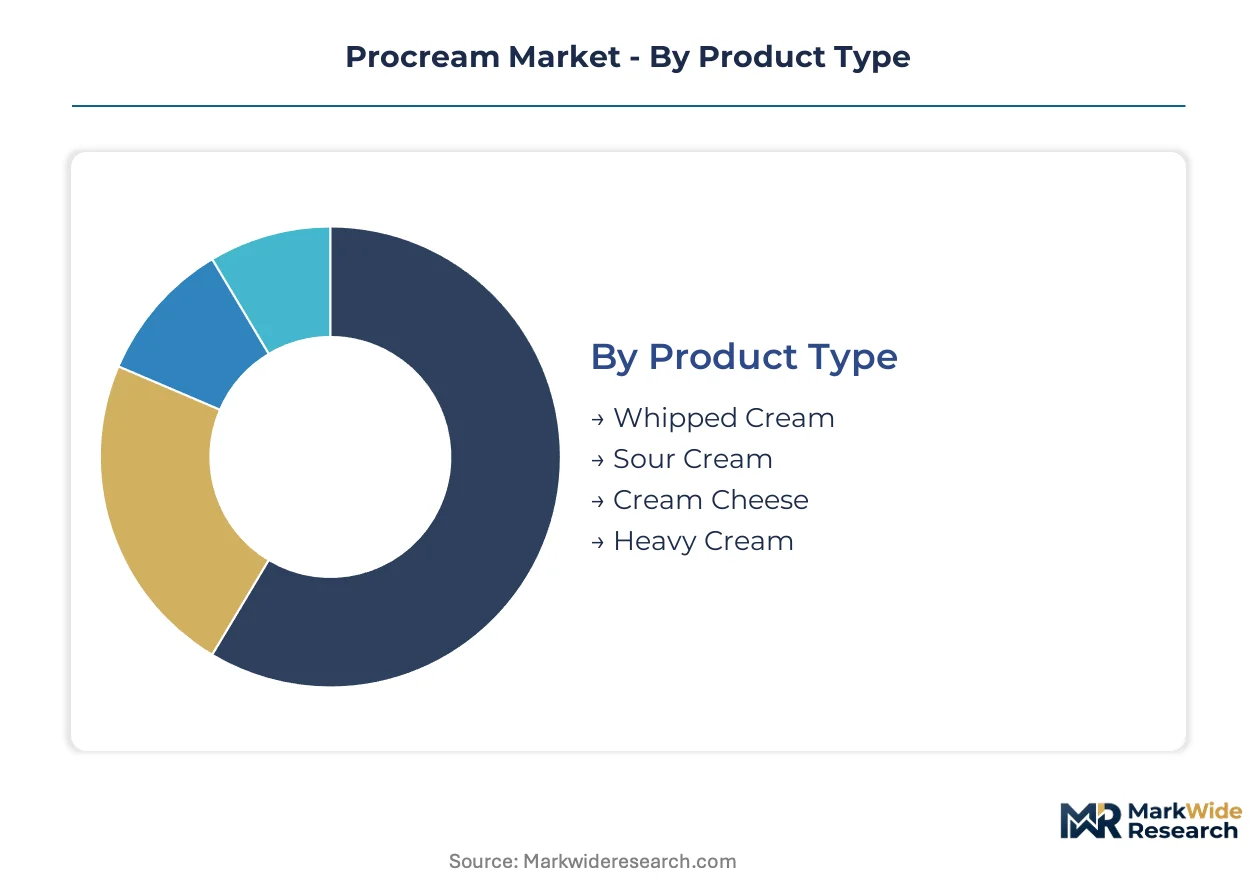
Procream manufacturers configure production lines around fat-content precision and thermal stability requirements that diverge sharply across end-use applications. Segmentation clarity enables processors to optimize homogenization parameters and pasteurization protocols for specific gravity benchmarks demanded by bakery, food service, and retail channels.
Product Type:
The use-case spectrum spans dessert culture penetration in European retail through industrial bakery fat-matrix requirements to cosmetics-grade emulsion specifications.
- Whipped Cream:Standardized to specific overrun ratios through controlled nitrogen injection, this segment commands value concentration in German and French retail dairy aisles where dessert consumption patterns sustain premium positioning. EFSA hygiene codes govern its interstate commerce within European distribution networks.
- Heavy Cream:Maintains butterfat matrices above 36% for thermal stability in industrial baking applications, with procurement concentrating among German artisanal bakery chains requiring consistent whipping performance across refrigerated logistics chains. FDA pasteurization standards fragment its cross-border production economics.
- Sour Cream:Fermented to targeted pH levels for Tex-Mex and Eastern European menu applications, accelerating fastest in North American food service channels.
- Cream Cheese:High-protein emulsion structure for spread and filling applications, with formulation adjustments for India's FSSAI fortification mandates.
Established volume favors heavy cream; emerging adoption favors sour cream.
Packaging Type:
Cost tier differentiation separates premium temperature-integrity solutions from economy formats targeting price-sensitive retail penetration.
- Plastic Tub:Multi-layer barrier construction dominates food service bulk procurement for sour cream and cream cheese, with German bakery chains specifying tamper-evident closures for direct-to-kitchen delivery. REACH chemical safety registrations now scrutinize polymer compositions for cosmetics-grade cream bases.
- Carton:Aseptic filling lines for UHT whipped cream enable ambient distribution economics, capturing supermarket shelf space consolidation in France and Benelux markets where refrigerated logistics costs pressure margins. EU Green Deal carbon-accounting requirements favor lighter-weight formats.
- Glass Jar:Premium positioning for artisanal cream cheese variants, with Normandy dairy co-operatives leveraging provenance signaling.
- Sachet:Single-serve portions for food service condiment applications, expanding in Indian institutional channels under FSSAI labeling compliance.
Carton formats dominate volume scale; glass jars concentrate margin extraction.
End User:
Customer type stratification reveals divergent specification intensity between formulation-driven industrial buyers and brand-conscious retail channels.
- Food Service:Direct procurement contracts displace distributor intermediaries for refrigerated cream with documented cold-chain integrity, with German bakery chains negotiating volume commitments to Normandy co-operatives. Scope 3 emissions documentation now gates supplier qualification.
- Bakery:Industrial buyers mandate butterfat standardization within 0.5% tolerance for automated production line consistency, with heavy cream grades sustaining margin concentration through technical specification barriers.
- Retail:Private-label consolidation narrows shelf space allocation, favoring processors with flexible co-packing capabilities over fragmented branded alternatives.
- Dairy Industry:Intermediate processing for downstream ingredient manufacturing, with cosmetics-grade emulsion specifications creating premium tier separation.
Food service channels are expanding most quickly; dairy industry intermediate demand offers premium tier access.
Distribution Channel:
Supply concentration patterns favor direct relationships in premium temperature-controlled segments while scale economies concentrate in consolidated retail intermediaries.
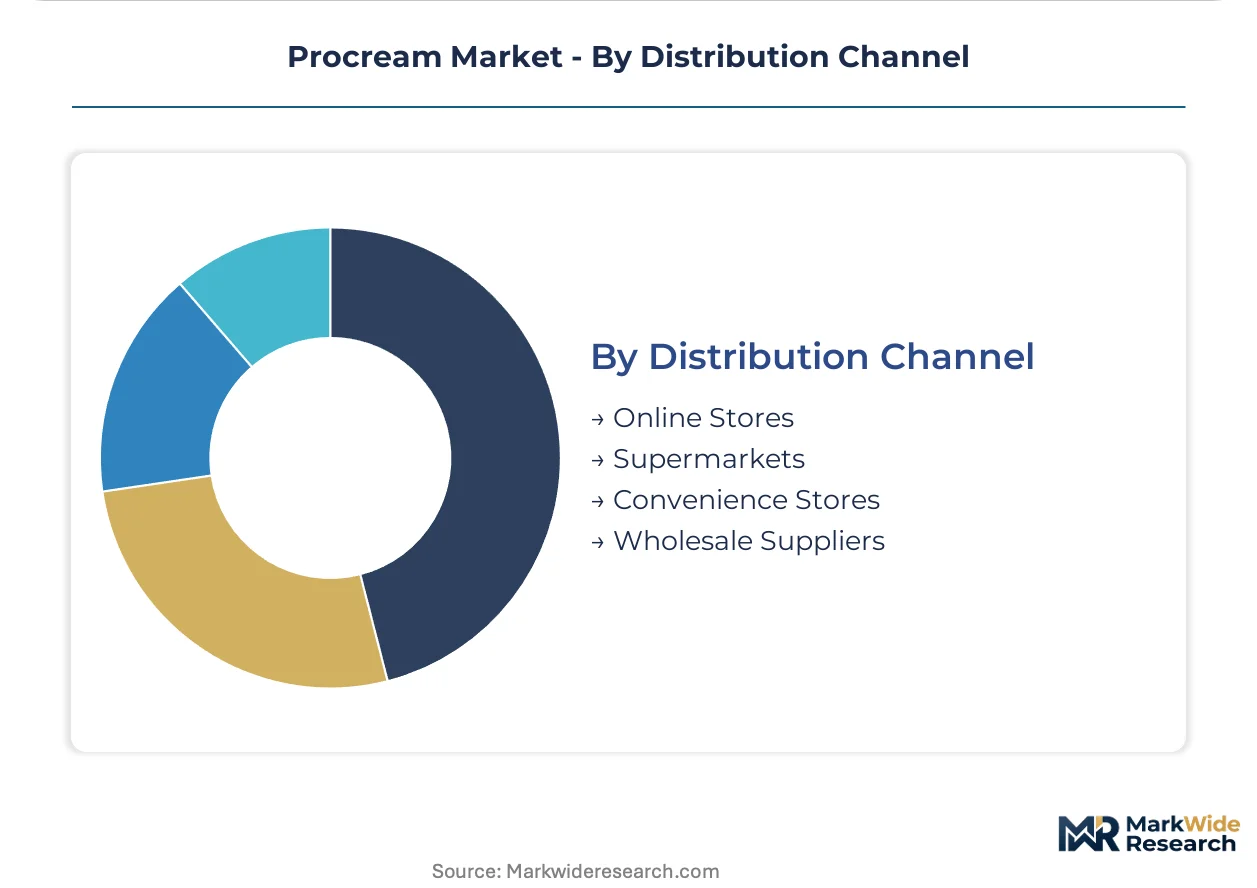
- Supermarkets:Dairy aisle narrowing consolidates procurement power among three to four retail banners in Germany and France, compressing margin layers for branded procream alternatives. Private-label lines capture shelf space through direct processor relationships.
- Wholesale Suppliers:Food service volume aggregation enables temperature-integrity premiums for refrigerated cream, with German bakery chains bypassing traditional distribution layers for Normandy direct contracts.
- Online Stores:Direct-to-consumer expansion for specialty whipped cream formats, with subscription models penetrating urban Indian markets.
- Convenience Stores:Impulse-oriented single-serve sachet placement for sour cream condiment applications.
Wholesale concentration favors volume stability; online expansion favors niche premium penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Normandy dairy co-operatives extract pricing premiums from German bakery chains that bypass intermediaries, while Indian processors absorb compliance costs for FSSAI fortification mandates without equivalent margin recovery.
Germany
Artisanal bakery chains expand refrigerated cream procurement for premium dessert portfolios, pulling standardized fat-content products into regional distribution networks. The EU Green Deal's farm-to-fork sustainability targets reshape dairy ingredient sourcing standards through Scope 3 emissions documentation requirements. Bavaria-based dairy processors negotiate direct contracts with Normandy co-operatives, compressing traditional distributor margin layers.
France
Normandy dairy co-operatives anchor cosmetics-grade emulsion supply through long-term procurement contracts with skincare formulators. EFSA dairy hygiene codes shape European import eligibility and farm-to-fork traceability verification timelines. The Île-de-France cluster concentrates whipped cream value pools where dessert culture penetration sustains premium retail positioning.
United States
Tex-Mex and Eastern European menu expansions in food service channels accelerate sour cream volume beyond retail growth rates. FDA pasteurization standards govern interstate cream commerce with temperature parameters that fragment cross-border production economics. Midwest dairy processors divert food-grade cream surplus into household cleaning emulsions to compete on volume scale.
India
FSSAI fortification mandates redirect formulation investments toward micronutrient-enhanced cream outputs, opening export channels for compliant processors. The country's national dairy regulator enforces labeling rules that reshape fat-standardized production footprints. Maharashtra-based processors pilot blockchain-enabled batch tracking for institutional channel sachet distribution under compliance documentation requirements.
China
SAMR dairy safety labeling rules redirect manufacturing investments toward compliant fat-standardized outputs for domestic retail penetration. The national market regulator's shelf-life standards impose processing parameters incompatible with export-market specifications. Yangtze River Delta processors configure homogenization lines for UHT carton formats that capture supermarket shelf space consolidation.
Procream Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fat-matrix standardization and thermal stability engineering. The vendor base separates into consolidated dairy co-operatives controlling high-fat cream volumes and fragmented private-label processors capturing supermarket shelf space. Three archetypes dominate: cosmetics-grade emulsion suppliers, food service direct-contract processors, and flexible co-packing specialists. Competitive moves concentrate on direct sourcing contract displacement of distributor intermediaries and private-label consolidation against branded alternatives.
Within the cosmetics-grade emulsion tier, L'Oréal S.A. and The Estée Lauder Companies Inc. occupy positions leveraging dairy-derived cream bases for premium skincare formulations. Procter & Gamble Co. sits within the scale-driven segment, exemplifying volume competition through surplus diversion strategies. These three anchors represent divergent procurement archetypes: long-term co-operative contracting, emulsion expertise extension, and commodity-scale reallocation.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Procter & Gamble Co. |
| Johnson & Johnson |
| Unilever PLC |
| Shiseido Company, Limited |
| Beiersdorf AG |
| Colgate-Palmolive Company |
| Avon Products, Inc. |
| Others |
Value Network & Pricing Analysis
Refrigerated logistics corridors between Normandy and Bavaria transmit feed cost volatility directly into cream base pricing, concentrating margin pressure on processors lacking direct co-operative contracts while enabling premium extraction for carbon-accounted supply streams.
Pricing Analysis
The customization-premium spread separates cosmetics-grade emulsion bases from commodity food-grade streams, with skincare formulators paying substantial premiums for specific gravity benchmarks that standard bakery applications disregard. Three-tier pricing structure across premium, standard, and economy levels reflects fat-content precision, certification grade, and cold-chain integrity documentation. Cost compression in standard grades is intensifying because European dairy co-operatives restrict high-fat cream access to non-integrated buyers. Industrial bakery chains exhibit highest price sensitivity due to volume scale and automated production tolerance requirements, while cosmetics manufacturers demonstrate lowest sensitivity given formulation-driven procurement mandates.
Supply Chain Analysis
Extended payment terms from German bakery chains to Normandy co-operatives are restructuring working capital flows across the refrigerated cream network, with supply-chain finance facilities emerging as competitive differentiators. Geographic supply concentrates in France, Germany, and India, with raw material dependencies centering on butterfat inputs, nitrogen injection systems, and multi-layer barrier packaging polymers. Single-source vulnerability runs through European dairy co-operative control of high-fat cream suitable for cosmetics-grade applications. Distribution runs through direct procurement contracts displacing traditional wholesale intermediaries in premium temperature-controlled segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized talent for farm-to-fork traceability systems remains scarce against technology sector competition, constraining ESG compliance velocity and carbon-accounting verification timelines for dairy processors.
For Market Incumbents: Pre-empt procurement bottlenecks by securing long-term co-operative contracts in Normandy before regional dairy processors exhaust available high-fat cream volumes. Backward integration into regenerative agriculture verification capabilities addresses the EU Green Deal's Scope 3 emissions documentation requirements that now gate supplier qualification for German bakery chains. Channel control through direct sourcing relationships compresses distributor margin layers and captures price premiums for temperature integrity. For New Entrants and Emerging Players: North American sour cream food service channels offer underpenetrated white-space opportunity, with Tex-Mex and Eastern European menu expansions outpacing established supply capacity. Flexible co-packing capabilities for private-label supermarket lines represent the most penetrable entry point, as dairy aisle narrowing favors processors with adaptable production footprints over fragmented branded alternatives. Go-to-market positioning should emphasize FSSAI fortification compliance for Indian institutional channel access. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer goods parents with underoptimized dairy ingredient divisions possessing co-operative relationships but lacking cosmetics-grade emulsion expertise. Long-term viability hinges on differentiation from commodity food-grade streams through technical specification barriers and sustainability certification. Blockchain-enabled traceability infrastructure deployment serves as the critical inflection signal for premium tier access and export eligibility acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Sourcing Contract Negotiation | German bakery chains bypass distributors to secure Normandy cream with documented cold-chain integrity. |
| Regenerative Agriculture Certification | EU Green Deal Scope 3 requirements redirect procurement toward carbon-accounted supply streams. |
| Cosmetics-Grade Emulsion Capacity | Skincare formulators seek high-fat cream bases with specific gravity benchmarks unavailable from commodity processors. |
| Blockchain Traceability Implementation | German chains and Normandy co-operatives pilot immutable ledgers to virtualize audit costs and accelerate ESG compliance. |
| FSSAI Fortification Compliance | Indian processors absorb micronutrient enhancement costs to open export channels for compliant outputs. |
Research Methodology
A spread of perspectives from dairy procurement managers at German bakery chains, cosmetics formulation scientists, co-operative board representatives, and refrigerated logistics operators converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from EFSA hygiene code documentation, FDA pasteurization standards, FSSAI fortification mandates, and EU Green Deal regulatory filings. Bottom-up volume modeling across product type, packaging format, and end-use segment triangulated against top-down market sizing from trade flow analysis.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning fat-content grade, thermal stability specification, distribution channel structure, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy inflection points and channel restructuring velocity. Forecast inputs incorporated butterfat input cost elasticity, ESG-linked procurement mandate adoption curves, and cosmetics-grade emulsion specification convergence rates.
Practitioners should monitor feed cost volatility transmission, EU carbon-border adjustment implementation timelines, and blockchain traceability standardization for early signals requiring forecast reassessment. This study's projections reflect documented assumptions about regulatory compliance trajectories and channel restructuring velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Amphoteric Emulsifier Market
Surfactants
Asia Pacific Surfactants Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Zeolite for Detergents Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
Alcohol Ether Sulfates Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Microemulsions Market
Surfactants
Micellar Water Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Trisiloxane Market
Surfactants
Dodecanol Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Defoamers Market
Surfactants
Natural Surfactants Market