
 Middle East and Africa Hazelnut Market | 2026-2036
Middle East and Africa Hazelnut Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hazelnut Market Foresight
Multi-source procurement from Turkish and Georgian suppliers is hardening as the dominant sourcing pattern across the Middle East and Africa hazelnut trade. Olam International leverages its integrated origination and processing infrastructure to secure consistent supply lines into Gulf markets. Cargill sustains competitive positioning through bulk handling capabilities and risk management tools for regional distributors. Besana Group anchors its presence via specialized nut processing expertise tailored to confectionery-grade specifications.
Hazelnuts are the edible kernels of Corylus avellana, typically containing 60-70% oil and 15-20% protein by weight, with blanching and dry-roasting constituting the primary processing stages for commercial food use. The application split tilts toward confectionery, where hazelnut paste demand from chocolate manufacturers commands premium pricing and volume commitments. Raw hazelnuts retain structural importance for bakery and industrial roasting channels, while the distribution channel landscape shows supermarkets consolidating share against fragmented specialty store networks across North African urban centers.
Turkey's Ministry of Agriculture and Forestry enforces export phytosanitary certification that directly conditions market access timing and lot approval for Middle East and Africa buyers. The Saudi Food and Drug Authority and South Africa's Department of Health apply aflatoxin maximum residue limits that filter supplier eligibility and elevate testing costs at port of entry. Stakeholders must monitor evolving Gulf standardization harmonization and emerging East African import substitution programs to align procurement and processing investments with regulatory trajectory.
Market Dynamics
Turkey's phytosanitary export protocols and the UAE's food safety modernization initiative are compressing supplier eligibility windows and elevating compliance costs for Middle East and Africa hazelnut procurement. These regulatory forces are reshaping sourcing patterns and import timing across Gulf Cooperation Council states.
Growth Catalysts
- SFDA Aflatoxin Standards:Saudi Arabia's maximum residue limits are filtering out marginal suppliers and consolidating procurement around certified Turkish and Georgian exporters with laboratory traceability systems.
- Chocolate Manufacturers:Premium confectionery lines across Riyadh and Jeddah corridors are locking in multi-year hazelnut paste volume commitments with advance payment structures.
- Retail Consolidation:Supermarket chains in North African urban centers are displacing fragmented specialty stores and standardizing hazelnut SKUs across private-label nut programs.
Market Restraints
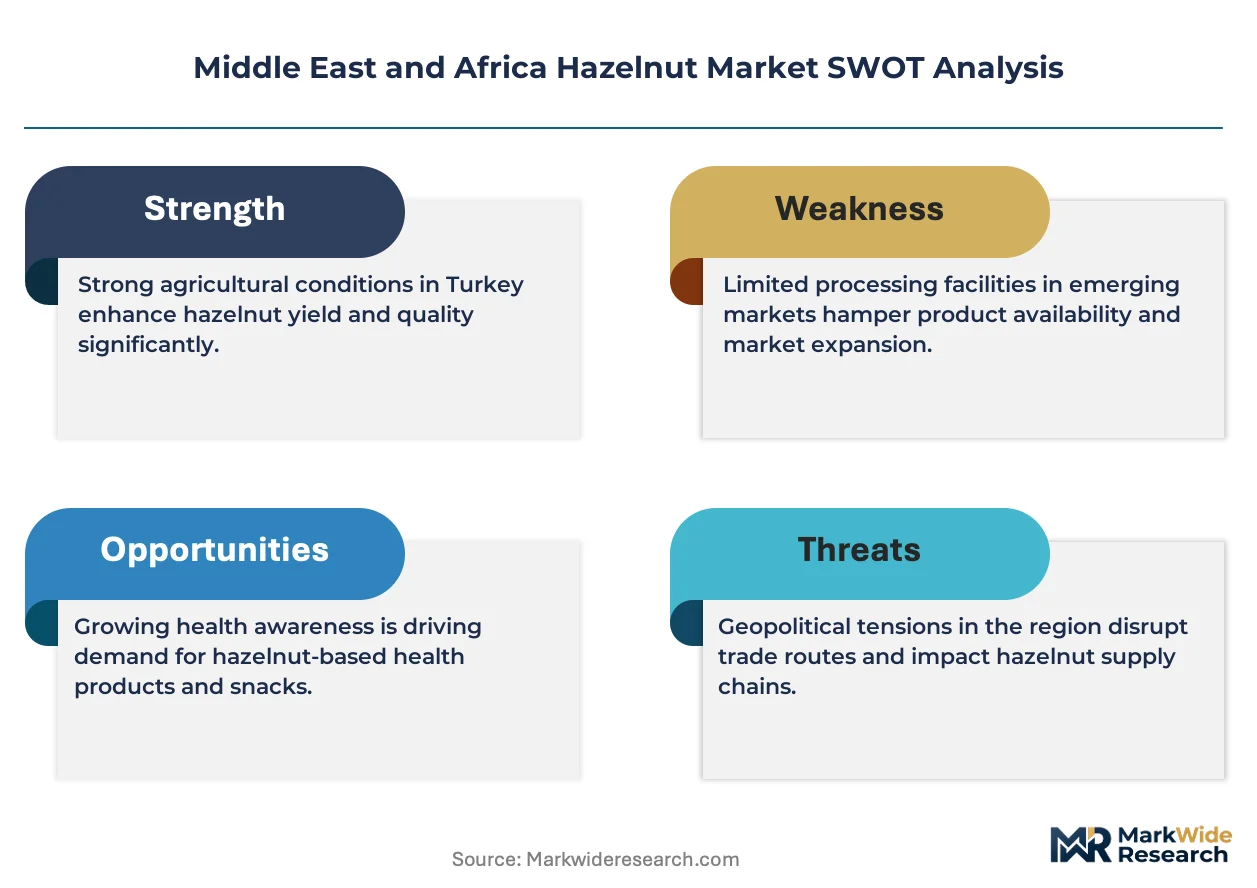
- Input Cost Volatility:Turkish lira fluctuations against Gulf currencies are injecting exchange-rate risk into contracted hazelnut pricing for UAE and Saudi importers.
- Supply Concentration:The Black Sea basin dominates raw kernel origination, exposing Middle East buyers to regional weather shocks and phytosanitary disruption cascades.
- Substitution Threat:Almond and cashew paste formulations are capturing cost-sensitive confectionery segments in South African industrial baking channels.
Strategic Opportunities
- East African Import Substitution:Kenya and Ethiopia are piloting hazelnut cultivation programs that could reduce dependence on Black Sea sourcing for regional processors.
- MOHAP Harmonization:The UAE's alignment with Gulf standardization protocols is streamlining multi-country import licensing for distributors with Dubai hub operations.
- E-Commerce Direct Channels:Specialty roasters in Cairo and Casablanca are bypassing traditional wholesale tiers through platform-direct consumer sales of premium origin-labeled kernels.
Industry Challenges
- Phytosanitary Certification Timelines:Turkey's Ministry of Agriculture and Forestry lot-approval procedures are creating port-of-entry delays that compress inventory turns for just-in-time confectionery processors.
- Blanching Equipment Capex:Food-grade kernel processing facilities in the Gulf require significant capital outlay for aflatoxin testing infrastructure and HACCP-compliant roasting lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hazelnut Market |
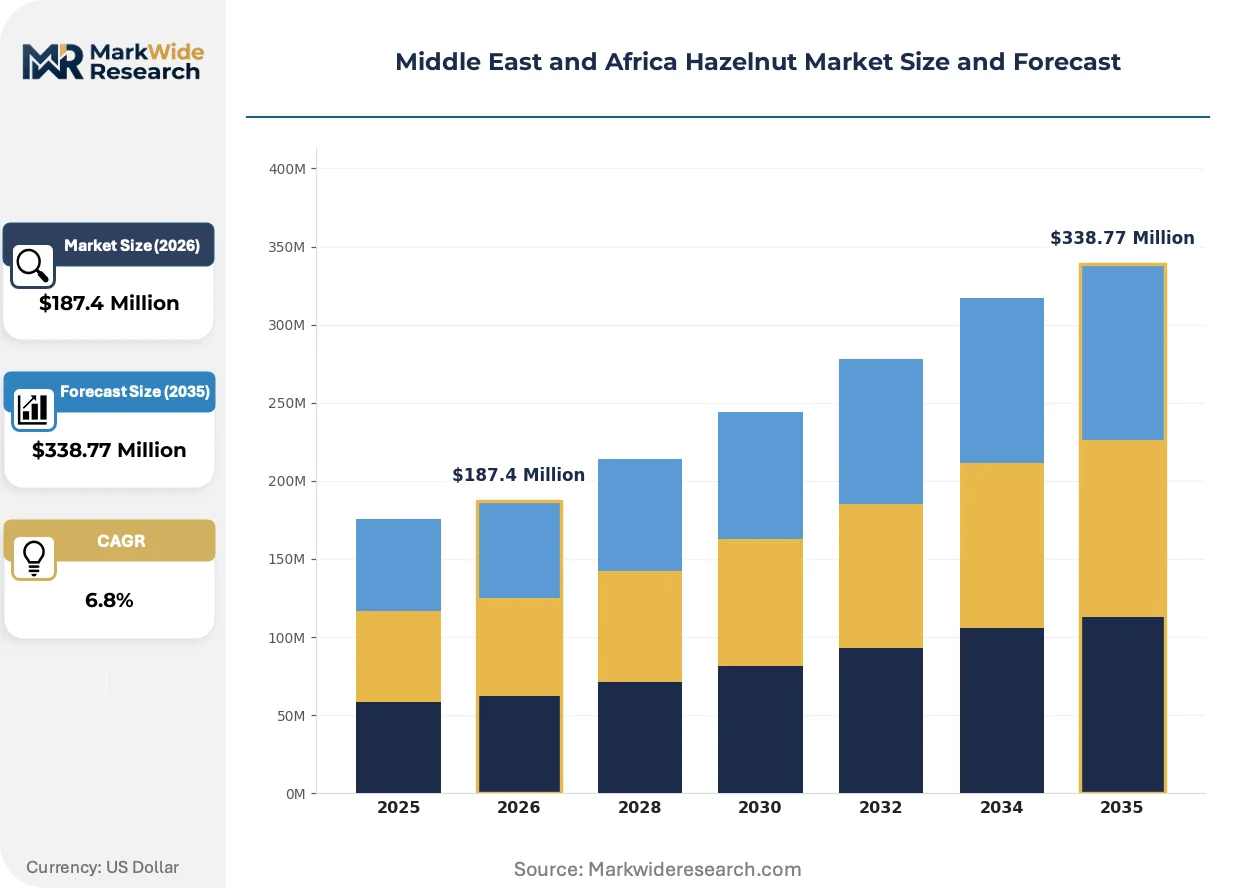
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Hazelnuts, Roasted Hazelnuts, Hazelnut Paste, Hazelnut Oil Application: Confectionery, Bakery, Spreads, Snacks End User: Food Manufacturers, Retail Consumers, Restaurants, Foodservice Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Balsu Gıda Sanayi ve Ticaret A.S., Alrifai Trading Company S.A.R.L., Olam International, Cargill, Cebon, Besana Group, Gürsoy Tarimsal Urunler Gida Sanayi ve Ticaret A.S., Arslanturk S.A., DURAK FINDIK, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hazelnut Market Shifts & Advancements
Processing technology and regulatory harmonization are compressing traditional supply tiers in Middle East and Africa hazelnut trade. These forces are enabling new procurement models while elevating compliance thresholds for market participation.
Near-infrared spectroscopy for aflatoxin detection is converging with blockchain-based lot traceability systems. Large-scale confectionery manufacturers in Saudi Arabia are adopting these integrated platforms at procurement entry points. This technology convergence is compressing laboratory testing cycles from days to hours while hardening supplier accountability documentation.
SFDA and MOHAP are aligning maximum residue limit protocols across Gulf Cooperation Council jurisdictions. This harmonization is reducing redundant testing burdens for distributors serving multiple emirates and kingdoms. Medium-scale importers with single-country certification are now consolidating Gulf-wide licensing to capture cross-border volume efficiencies.
Foodservice chains in Riyadh and Jeddah are consolidating hazelnut procurement through centralized commissary contracts rather than regional distributor fragmentation. This buyer concentration is displacing traditional wholesale tiers and standardizing kernel specifications across outlet networks. The shift is most visible in quick-service bakery and café verticals where menu consistency commands premium supplier terms.
Middle East and Africa Hazelnut Market Segmentation
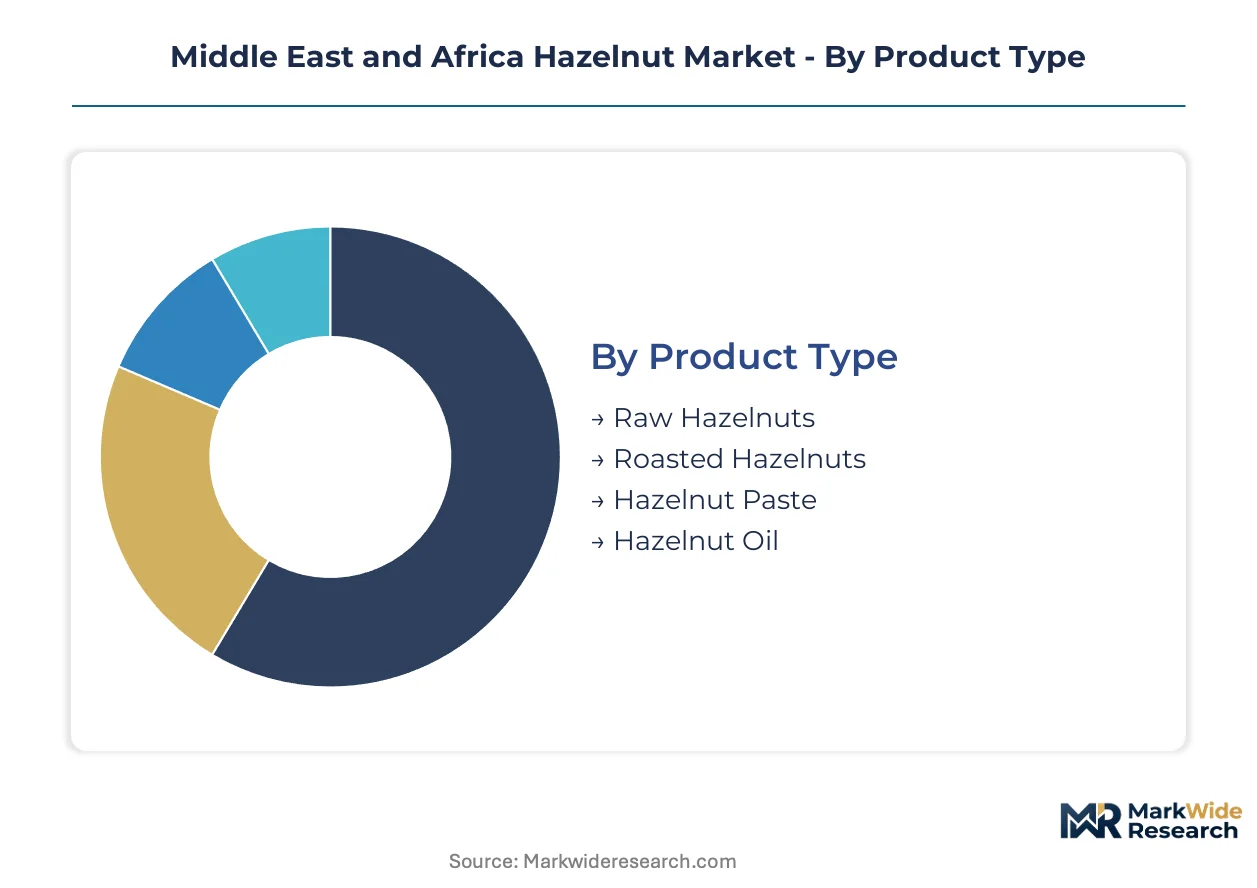
Hazelnut product flows across Middle East and Africa markets stratify sharply between industrial-grade bulk procurement and premium retail positioning. Segment boundaries are hardening as Turkish export protocols and Gulf food safety standards filter supplier eligibility across each tier.
Product Type:
Raw kernels dominate tonnage flows while processed derivatives command margin premiums across Saudi and UAE import channels.
- Raw Hazelnuts:In-shell and shelled kernels retain structural importance for industrial roasting and bakery channels across North African processing hubs. Turkish phytosanitary certification requirements from the Ministry of Agriculture and Forestry compress lot approval timelines for Egyptian and Moroccan buyers seeking just-in-time inventory.
- Hazelnut Paste:Finely ground roasted kernels with 60-70% oil content serve as the primary input for chocolate confectionery manufacturing. Riyadh and Jeddah corridors concentrate demand from premium product lines locking in multi-year volume commitments with advance payment structures.
- Roasted Hazelnuts:Dry-roasted kernels target snack and foodservice applications across Gulf urban centers.
- Hazelnut Oil:Cold-pressed oil serves cosmetic and specialty food segments in South African and UAE premium retail channels.
Mature deployment sits with Raw Hazelnuts. Newer deployment is concentrated in Hazelnut Paste.
Application:
Confectionery-grade specifications pull procurement toward certified Turkish exporters while bakery channels tolerate broader origin sourcing.
- Confectionery:Chocolate manufacturers across GCC states specify aflatoxin-tested kernels with laboratory traceability documentation. SFDA maximum residue limits filter supplier eligibility and elevate testing costs at Saudi ports of entry.
- Bakery:Industrial and artisanal baking channels across Cairo and Casablanca absorb raw and roasted kernel volumes with less stringent certification requirements than confectionery tiers.
- Spreads:Nut butter formulations capture retail shelf space in North African supermarket chains.
- Snacks:Flavored and salted roasted kernels target convenience retail across Gulf airport and fuel station networks.
Volume leadership belongs to Confectionery. Margin expansion concentrates in Spreads.
End User:
Procurement scale separates institutional buyers with direct Turkish relationships from fragmented retail and foodservice channels.
- Food Manufacturers:Chocolate and confectionery producers across Saudi Arabia and UAE maintain integrated origination contracts with Black Sea basin processors. Multi-year paste volume commitments with advance payment structures displace spot market exposure.
- Foodservice:Quick-service bakery and café chains in Riyadh and Jeddah corridors consolidate procurement through centralized commissary contracts rather than regional distributor fragmentation.
- Retail Consumers:Egyptian and Moroccan urban households purchase packaged kernels through supermarket private-label programs.
- Restaurants:Fine dining and hotel pastry operations in Dubai and Abu Dhabi source specialty-grade paste through specialty importers.
Contracted volume concentrates with Food Manufacturers. Spot purchasing dominates Restaurants.
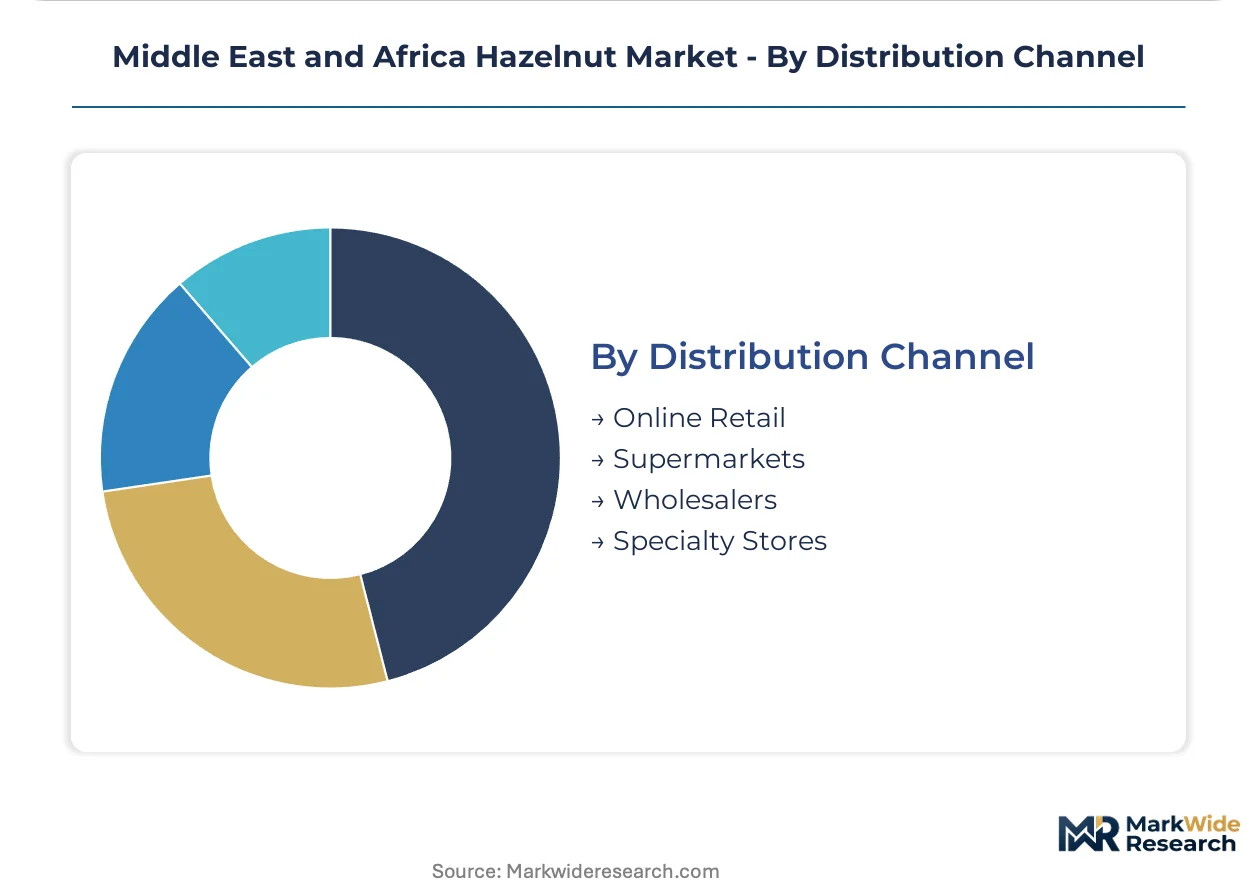
Distribution Channel:
Channel consolidation is accelerating as supermarket chains displace fragmented specialty retail across North African urban centers.
- Supermarkets:Carrefour, Lulu, and Spinneys operations across GCC and North African markets standardize hazelnut SKUs across private-label nut programs. Retail consolidation compresses supplier counts and elevates volume thresholds for shelf access.
- Online Retail:Platform-direct sales enable Cairo and Casablanca specialty roasters to bypass traditional wholesale tiers with origin-labeled premium kernels.
- Wholesalers:Traditional import distributors serve fragmented bakery and foodservice accounts across secondary Egyptian and Moroccan cities.
- Specialty Stores:Nut-specific retailers retain footholds in heritage souk districts and premium mall formats.
Scale concentration sits with Supermarkets. Channel innovation clusters in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Black Sea basin's Ordu-Giresun corridor anchors raw hazelnut origination for Middle East and Africa buyers. Turkish export protocols condition procurement timing across Gulf and North African markets. Regulatory harmonization among GCC food safety authorities is compressing supplier eligibility windows.
Saudi Arabia
Chocolate manufacturers in Riyadh and Jeddah corridors drive premium paste demand with multi-year volume commitments. The Saudi Food and Drug Authority enforces aflatoxin maximum residue limits that filter supplier eligibility at port of entry. Centralized commissary procurement by quick-service bakery chains is displacing traditional distributor fragmentation.
United Arab Emirates
Dubai-based distributors leverage the emirate's logistics infrastructure to serve multi-country Gulf markets. The Ministry of Health and Prevention's food safety modernization initiative aligns with GCC standardization protocols. Abu Dhabi and Dubai operations are streamlining import licensing for regional hub-and-spoke distribution models.
Turkey
Ordu and Giresun provinces concentrate in-shell and shelled kernel processing for export to Middle East markets. The Ministry of Agriculture and Forestry enforces phytosanitary certification that conditions lot approval timelines. Black Sea basin weather exposure and phytosanitary disruption cascades create supply volatility for contracted buyers.
Egypt
Cairo's industrial baking channels absorb raw and roasted kernel volumes with moderate certification requirements. The country's national food safety regulator applies import standards that elevate testing costs at Alexandria port. Supermarket private-label programs in Greater Cairo are consolidating procurement against fragmented specialty retail networks.
South Africa
Industrial baking channels in Johannesburg and Cape Town absorb cost-sensitive almond and cashew paste substitutes. The Department of Health applies aflatoxin limits that filter supplier eligibility for confectionery manufacturers. Premium cosmetic and specialty food segments in Cape Town retain niche demand for cold-pressed hazelnut oil.
Middle East and Africa Hazelnut Market Competitive Landscape
Global majors compete with regional champions across origination and processing infrastructure. The vendor base stratifies between integrated Turkish processors with captive Black Sea supply and Gulf-based distributors with logistics-centric positioning. Three archetypes dominate: vertically integrated originators, regional trading houses, and specialized nut processors. Competitive moves concentrate on strategic partnerships with confectionery manufacturers and certification infrastructure investments.
Among Turkish-integrated originators, Balsu Gıda Sanayi ve Ticaret A.S. and Gürsoy Tarimsal Urunler Gida Sanayi ve Ticaret A.S. occupy positions anchored in Ordu-Giresun processing corridors. Olam International exemplifies the global trading house archetype with multi-origination sourcing capabilities. These entities represent the structural tension between Black Sea supply concentration and Gulf demand consolidation.
| Leading Market Players |
|---|
| Balsu Gıda Sanayi ve Ticaret A.S. |
| Alrifai Trading Company S.A.R.L. |
| Olam International |
| Cargill |
| Cebon |
| Besana Group |
| Gürsoy Tarimsal Urunler Gida Sanayi ve Ticaret A.S. |
| Arslanturk S.A. |
| DURAK FINDIK |
| Others |
Supply & Pricing Matrix
Turkish lira volatility against Gulf currencies transmits exchange-rate risk through contracted hazelnut pricing tiers, compressing margins for UAE and Saudi importers while elevating procurement hedging costs across confectionery-grade paste commitments.
Pricing Analysis
Certification-bundled pricing separates aflatoxin-tested kernels with SFDA traceability documentation from unbundled raw grades lacking laboratory accountability. Three-tier pricing structure across premium, standard, and economy levels stratifies by volume commitment scale and phytosanitary compliance depth. Pricing pressure stems from Turkish currency instability feeding into Black Sea basin origination contracts. Food manufacturers with multi-year paste commitments exhibit lowest price sensitivity; fragmented bakery channels in secondary Egyptian cities show highest elasticity.
Supply Chain Analysis
Rejected lot flows from Turkish Ministry of Agriculture and Forestry phytosanitary holds create secondary kernel streams into North African informal processing channels. Supply concentrates in Turkey's Ordu-Giresun corridor, with Georgian Black Sea ports providing alternative origination. Raw kernel inputs, blanching equipment, and aflatoxin testing infrastructure anchor downstream dependencies. Single-source vulnerability from Black Sea weather exposure threatens contracted volume reliability. Distribution runs through Dubai-based hub-and-spoke networks serving multi-country Gulf markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SFDA aflatoxin maximum residue limits erect certification barriers that consolidate procurement around laboratory-traceable Turkish exporters.
For Market Incumbents: To counter almond and cashew paste substitution in South African industrial baking, lock in backward integration into Georgian processing corridors and deepen HACCP-compliant roasting infrastructure. Certification investment in near-infrared spectroscopy platforms hardens supplier accountability documentation against port-of-entry delays. For New Entrants and Emerging Players: Blockchain-enabled lot traceability systems offer entry wedge into Saudi confectionery procurement tiers underserved by legacy laboratory testing cycles. Target East African cultivation pilots in Kenya and Ethiopia for import substitution positioning. Direct e-commerce channels to Cairo and Casablanca specialty roasters bypass wholesale margin capture. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Turkish processors with captive Ordu-Giresun supply and dormant Gulf distribution licenses. Long-term viability hinges on regulatory harmonization completion across GCC jurisdictions. Watch MOHAP-SFDA protocol alignment velocity as inflection signal for multi-country licensing consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Phytosanitary Certification Infrastructure | SFDA traceability systems filter supplier eligibility and compress laboratory testing cycles for Riyadh confectionery manufacturers. |
| East African Cultivation Partnerships | Kenya and Ethiopia pilot programs reduce Black Sea basin concentration risk for regional processors seeking supply diversification. |
| GCC Regulatory Harmonization | MOHAP alignment with Gulf standardization protocols streamlines multi-country import licensing for Dubai hub operators. |
| Near-Infrared Spectroscopy Deployment | Blockchain-integrated aflatoxin detection hardens supplier accountability and accelerates procurement entry point validation. |
| Centralized Commissary Contracts | Quick-service bakery chains in Jeddah corridors displace regional distributor fragmentation through standardized kernel specifications. |
Research Methodology
Multi-period observation of Turkish export certification timelines, Gulf currency cross-rates, and SFDA lot approval velocities anchored the trend analysis, supplemented by interviews with Black Sea basin processors, Dubai-based distribution operators, Saudi confectionery procurement directors, Egyptian industrial baking channel managers, and North African supermarket category buyers. Secondary validation drew from Turkish Ministry of Agriculture and Forestry export statistics, Saudi Food and Drug Authority regulatory filings, UAE customs trade databases, and industry association processing capacity reports. Bottom-up volume estimates from kernel-grade procurement flows triangulated against top-down market sizing from confectionery manufacturer paste consumption patterns.
Segment-weighting applied product type stratification across raw kernels, paste, roasted derivatives, and oil fractions, crossed with application tiers spanning confectionery, bakery, spreads, and snacks, and further disaggregated by end-user scale from integrated food manufacturers to fragmented restaurant spot purchasers. CAGRs derived from fitted growth curves across the projection horizon, with explicit modeling of Turkish lira exchange-rate sensitivity and phytosanitary disruption probability. Forecast inputs incorporated Black Sea basin weather shock frequency and GCC regulatory harmonization implementation pace.
Several conditions sit outside the modeled scope, including sudden Turkish export moratoria, unilateral SFDA protocol revisions, and East African cultivation program failure rates. Forecasts reflect documented assumptions regarding currency stability and certification timeline continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Almond with Shell Snack Market
Nuts and Seeds
Blackcurrant Seed Oil Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Nut Based Spread Market
Nuts and Seeds
Cashew Roasting Machine Market
Nuts and Seeds
Asia-Pacific Hazelnut Market
Nuts and Seeds
Maca Market
Nuts and Seeds
Baru Nuts Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Global Cashew Nutshell Liquid Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Walnut Oil Market
Nuts and Seeds
Hazelnut Market