
 Visualization Instruments for MIS Market | 2026-2036
Visualization Instruments for MIS Market Size, Share, and Industry Trends Forecast 2026-2036
Visualization Instruments for MIS Market Analytics
Hospital buying group consolidation is hardening across integrated delivery networks in the United States. Olympus Corporation leverages its vertically integrated optical manufacturing to sustain margin control over rigid endoscope supply chains. Stryker Corporation anchors its visualization portfolio through dedicated surgical video tower platforms that dominate North American operating room retrofits. KARL STORZ competes on German-engineered Hopkins rod-lens systems that occupy premium positions in European academic medical centers.
Visualization instruments for minimally invasive surgery encompass camera heads, light sources, video processors, and display monitors that convert optical signals from endoscopes into real-time surgical imagery at resolutions exceeding 4K and frame rates supporting fluorescence-guided procedures. These systems enable laparoscopic, arthroscopic, and hysteroscopic interventions by collapsing the surgeon's visual field into body cavities without open incision. Cloud-based solutions within technology segmentation are capturing fastest-growing deployment interest as hospital IT departments prioritize remote surgical observation and AI-assisted image analytics. Data visualization software among product types sits at mature saturation in administrative dashboards but retains expansion runway in operative workflow integration where real-time anatomical mapping merges with preoperative imaging.
FDA 510(k) clearance pathways govern camera system and video processor introductions in the United States, while EMA medical device regulation and CE marking under MDR impose clinical evidence requirements across European markets. Japan's PMDA enforces QMS conformity for foreign manufacturers seeking reimbursement eligibility under universal health coverage. Stakeholders must monitor regulatory divergence between FDA's predicate-based framework and EMA's escalating clinical data demands when allocating R&D across geographic product registrations.
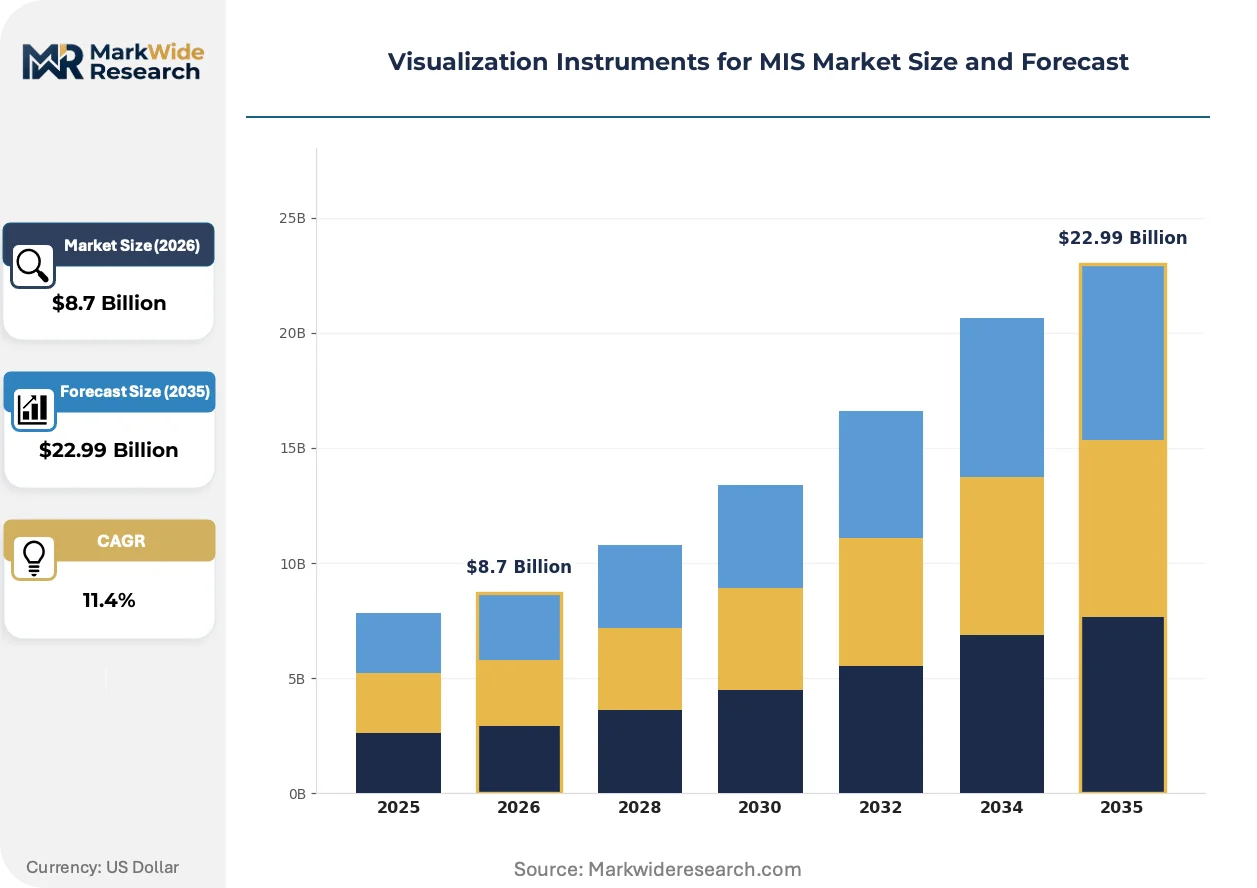
Market Dynamics
Hospital procurement coalitions across integrated delivery networks are consolidating purchasing power, compressing vendor margins and forcing visualization instrument suppliers to restructure go-to-market strategies around multi-year enterprise contracts rather than individual facility sales.
Growth Catalysts
- AI-assisted image analytics:Cloud-based platforms enable real-time surgical guidance and post-operative review, driving replacement demand for legacy camera systems lacking computational integration.
- FDA 510(k) pathway efficiency:Predicate-based clearances for camera heads and video processors accelerate product introductions compared to European clinical evidence requirements.
- German academic hospital networks:Replacement cycles for Hopkins rod-lens systems at university medical centers sustain premium equipment refresh rates.
Market Restraints
- Optical component supply concentration:Specialized glass and sapphire lens manufacturing clusters in Germany and Japan create single-source dependencies for rigid endoscope producers.
- EMA MDR clinical data escalation:European clinical evidence requirements for CE marking extend registration timelines and inflate regulatory compliance costs.
- Fluorescence imaging equipment cost:Near-infrared camera systems and specialized light sources command 3-4x pricing multiples over standard 4K visualization towers.
Strategic Opportunities
- Remote surgical observation platforms:Cloud-based solutions capture fastest-growing deployment interest as hospital IT departments prioritize centralized surgical education and quality assurance.
- Japan's universal health coverage reimbursement:PMDA QMS conformity for foreign manufacturers opens access to procedural volume in aging demographic markets.
- Operative workflow integration:Real-time anatomical mapping merging with preoperative imaging creates expansion runway beyond administrative dashboard saturation.
Industry Challenges
- Integration complexity with legacy video towers:Hospital capital equipment refresh cycles lag camera technology advancement, forcing backward compatibility engineering.
- Fluorescence-guided surgery certification timelines:Specialized training requirements for indocyanine green and methylene blue protocols delay clinical adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Visualization Instruments for MIS Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboards, Reporting Tools, Data Visualization Software, Data Analytics Platforms Technology: Cloud-based Solutions, On-Premises Solutions, Web-based Applications, Mobile Applications End User: Healthcare Providers, Financial Institutions, Educational Institutions, Government Agencies Deployment: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | Olympus Corporation, Stryker Corporation, Johnson & Johnson (ETHICON), KARL STORZ, Boston Scientific Corporation, Medtronic plc, B. Braun Melsungen AG, CONMED Corporation, Arthrex GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Visualization Instruments for MIS Market Evolving Landscape
Visualization technology is converging around computational imaging platforms that merge optical capture with real-time analytics, collapsing the traditional separation between hardware acquisition and software interpretation in surgical workflows.
4K-fluorescence hybrid camera systems is unifying standard white-light visualization with near-infrared molecular imaging in single hardware units. Academic medical centers in Germany and the United States are leading adoption, replacing separate fluorescence towers with integrated platforms. This convergence is unifying capital budgets and compressing vendor count per operating room.
EU MDR clinical evidence requirements are escalating data demands for video processor and camera head registrations. Manufacturers must now submit prospective clinical studies rather than predicate-based equivalence arguments. European markets are responding with delayed product launches and geographic prioritization toward FDA-cleared devices.
Buying group consolidation is hardening procurement leverage across North American health systems. Multi-hospital networks are unbundling after-sales service contracts from equipment purchases and mandating cloud connectivity for remote technical support. This concentration is most visible in United States integrated delivery networks negotiating five-year enterprise agreements.
Visualization Instruments for MIS Market Segmentation
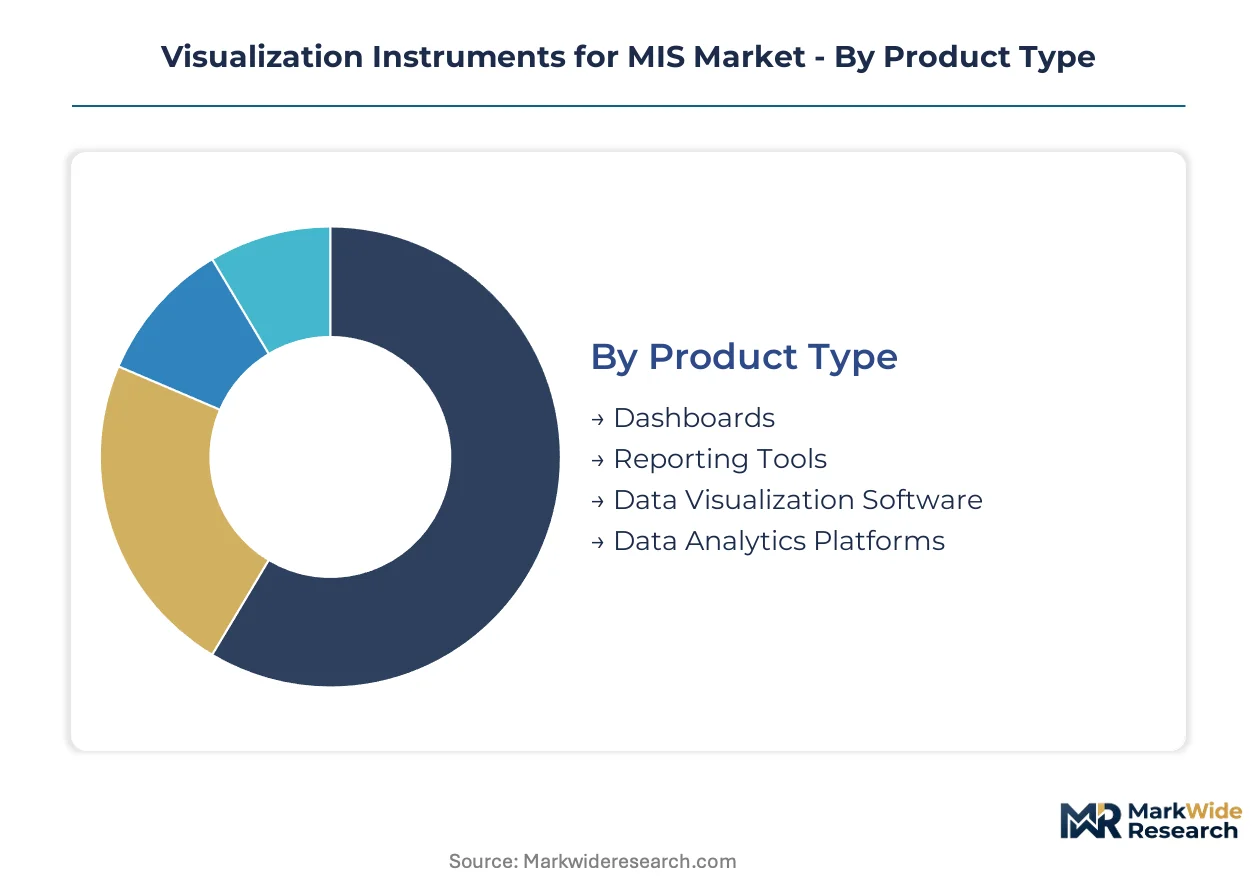
Visualization instruments for MIS fragment across hardware-software boundaries and infrastructure models that determine procurement pathways. Hospital IT departments weight interoperability against total cost of ownership when selecting across these dimensions. Each segmentation axis reveals distinct margin structures and vendor competitive dynamics.
Product Type:
Volume concentration sits in administrative dashboards while premium expansion runs through operative workflow integration. The revenue split tilts toward software layers that merge real-time surgical imagery with preoperative planning systems.
- Dashboards:Administrative visualization platforms aggregate operational metrics across surgical suites and supply chain workflows. German academic hospital networks drive replacement demand as legacy systems lack API connectivity to electronic health records. These systems dominate procurement volumes but face compression from bundled enterprise contracts.
- Data Visualization Software:Operative workflow platforms merge 4K surgical feeds with fluoroscopic overlay and preoperative CT/MRI reconstructions. United States integrated delivery networks prioritize these systems for quality assurance and remote proctoring. This segment captures the steepest expansion trajectory as AI-assisted image analytics migrate from research to standard of care.
- Reporting Tools:Compliance documentation and outcome tracking systems interface with regulatory submission requirements.
- Data Analytics Platforms:Cloud-native architectures enable population-level surgical outcome analysis across multi-hospital networks.
Today's leader: Data Visualization Software. Tomorrow's challenger: Data Analytics Platforms.
Technology:
Deployment architecture determines capital expenditure timing and cybersecurity liability exposure for hospital procurement teams.
- Cloud-based Solutions:Remote surgical observation platforms centralize video storage and enable AI processing at the edge. Hospital IT departments in United States integrated delivery networks mandate these architectures for disaster recovery and multi-site standardization. FDA 510(k) pathway efficiency accelerates vendor product introductions compared to European clinical evidence requirements.
- On-Premises Solutions:Air-gapped video processing towers satisfy data sovereignty requirements in defense and select government hospital networks. Japan's PMDA QMS conformity processes favor these systems for foreign manufacturers seeking reimbursement eligibility. This segment retains share in markets with strict patient data localization mandates.
- Web-based Applications:Browser-accessible surgical archives reduce client-side software maintenance burdens.
- Mobile Applications:Tablet-based intraoperative reference tools support bedside consultation and emergency intervention workflows.
Cloud-based Solutions currently command procurement priority. On-Premises Solutions defend position in regulated verticals.
End User:
Customer type segmentation tracks reimbursement model differences and capital availability across institutional categories.
- Healthcare Providers:Hospital systems and ambulatory surgical centers constitute the core demand base for visualization tower retrofits. United States integrated delivery networks consolidate purchasing power through multi-year enterprise agreements that compress vendor margins. Replacement cycles for 4K-fluorescence hybrid systems concentrate in academic medical centers with research funding access.
- Educational Institutions:Medical schools and simulation centers procure lower-volume configurations for training curriculum development. German university hospital networks sustain premium equipment refresh rates for Hopkins rod-lens system replacements. These buyers prioritize remote observation capabilities for distributed education delivery.
- Financial Institutions:Healthcare-focused investment funds and insurers utilize surgical outcome visualization for risk modeling.
- Government Agencies:Veterans affairs and public health systems operate under distinct procurement regulations and budget cycles.
Healthcare Providers anchor current revenue concentration. Educational Institutions present expansion runway through simulation market growth.
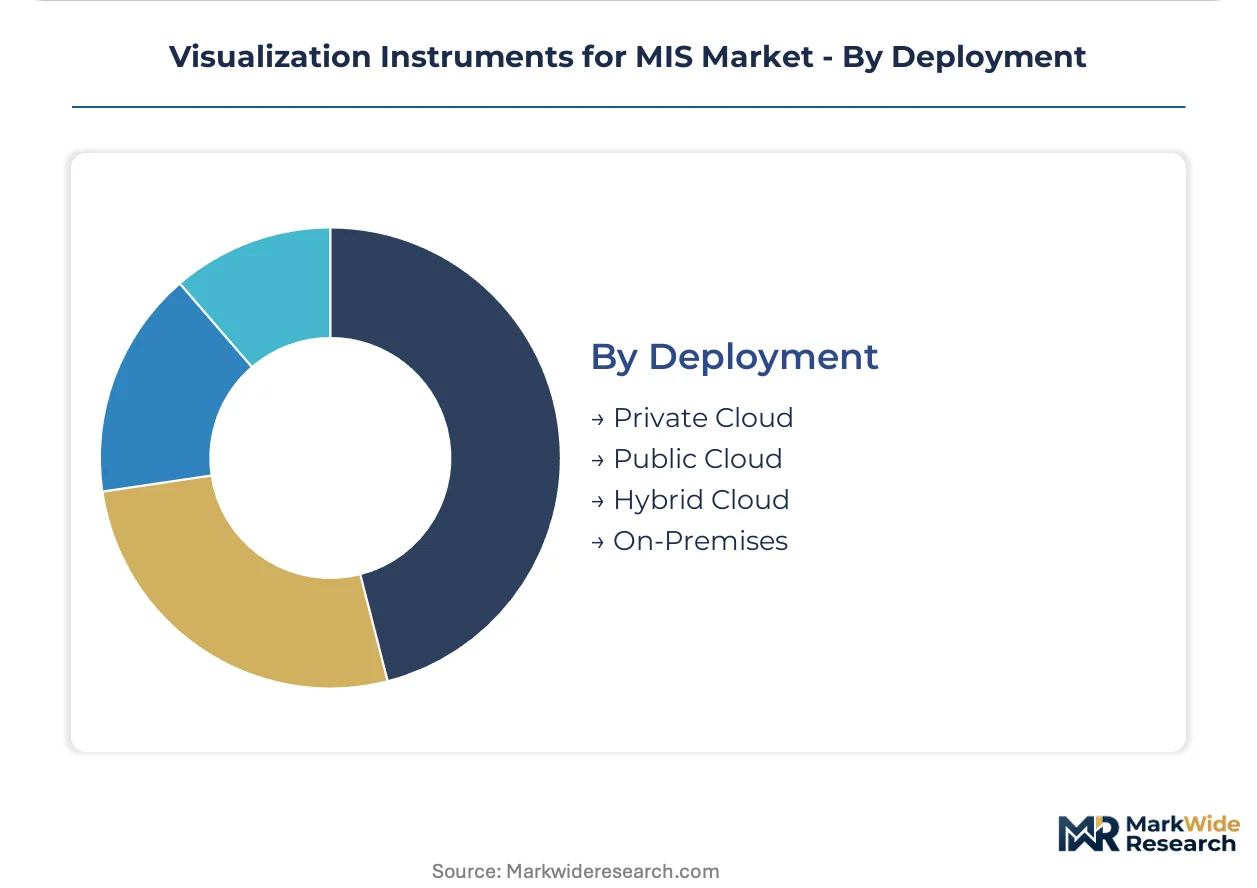
Deployment:
Infrastructure model selection reflects data gravity, latency requirements, and regulatory jurisdiction boundaries.
- Hybrid Cloud:Surgical video archiving splits between on-premises short-term storage and cloud long-term retention. Hospital IT departments prioritize these architectures to balance immediate access needs against disaster recovery requirements. EMA MDR clinical data escalation drives European preference for hybrid models that maintain local clinical evidence custody.
- Private Cloud:Dedicated infrastructure deployments satisfy data residency requirements in Germany, Switzerland, and select United States state jurisdictions. These configurations command premium pricing multiples over public alternatives due to specialized compliance engineering.
- Public Cloud:Shared infrastructure reduces capital expenditure for smaller hospital networks and ambulatory centers.
- On-Premises:Fully localized systems persist in markets with strict cybersecurity frameworks or limited connectivity reliability.
Hybrid Cloud configurations dominate new procurement decisions. Private Cloud deployments defend share in data-sovereignty-sensitive markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical engineers and optical physicists concentrate in southern Germany, suburban Tokyo, and the northeastern United States. These talent clusters anchor visualization instrument design, manufacturing, and clinical validation workflows.
United States
Integrated delivery networks in Illinois and Texas consolidate procurement through five-year enterprise agreements. FDA 510(k) clearance pathways accelerate camera system introductions compared to European clinical evidence requirements. Minneapolis and San Jose host visualization tower engineering centers serving North American operating room retrofits.
Germany
Academic hospital networks in Baden-Württemberg and Bavaria drive replacement cycles for Hopkins rod-lens systems. EMA MDR clinical data requirements extend CE marking timelines for video processor registrations. Tuttlingen anchors rigid endoscope manufacturing with vertically integrated optical glass production.
Japan
PMDA QMS conformity processes govern foreign manufacturer access to universal health coverage reimbursement. Tokyo and Osaka metropolitan areas concentrate surgical video processor R&D facilities. Aging demographics sustain procedural volume for minimally invasive interventions requiring advanced visualization.
China
NMPA medical device registration reforms streamline Class II camera system approvals for domestic manufacturers. Yangtze River Delta cities including Shanghai and Suzhou host endoscope component fabrication clusters. Local procurement preferences in tier-one hospitals favor domestic visualization tower suppliers.
Switzerland
Swissmedic conformity assessment requirements impose clinical evidence standards for CE marking under MDR mutual recognition. Zurich and Basel host precision optics manufacturing for sapphire lens components. Private hospital networks in Geneva and Lausanne prioritize 4K-fluorescence hybrid system acquisitions.
Visualization Instruments for MIS Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between full-line surgical equipment suppliers and dedicated visualization instrument manufacturers. Three archetypes dominate: vertically integrated optical conglomerates, video platform specialists, and component-focused subscale suppliers. Competitive moves concentrate on multi-year enterprise contract capture and backward integration into specialized lens manufacturing.
Within the optical conglomerate tier, Olympus Corporation and KARL STORZ exemplify European and Japanese engineering traditions in rigid endoscope production. Stryker Corporation anchors North American competitive positioning through dedicated surgical video tower platforms. These three entities occupy distinct geographic and technological positions without overlapping core competencies.
| Leading Market Players |
|---|
| Olympus Corporation |
| Stryker Corporation |
| Johnson & Johnson (ETHICON) |
| KARL STORZ |
| Boston Scientific Corporation |
| Medtronic plc |
| B. Braun Melsungen AG |
| CONMED Corporation |
| Arthrex GmbH |
| Others |
Value Network & Pricing Analysis
Performance-tier bifurcation between 4K-fluorescence hybrid systems and standard visualization towers manifests in divergent margin structures and supply chain configurations. Premium tiers command captive sapphire lens sourcing from Tuttlingen and suburban Tokyo while standard tiers draw from dispersed Asian component markets, with FDA 510(k) pathway efficiency accelerating price-to-market velocity for predicate-based clearances against EMA MDR clinical data delays.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard camera heads and video processors. Three-tier pricing structure across premium, standard, and economy levels separates Hopkins rod-lens systems with German optical glass from Asian-sourced alternatives. Price differentiation hinges on fluorescence imaging capability and CE marking tier under MDR. Pricing pressure stems from hospital procurement coalition consolidation across United States integrated delivery networks. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with research funding access show lowest.
Supply Chain Analysis
Single-source vulnerability sits with specialized sapphire lens manufacturing in Germany and Japan. Optical component supply concentrates in Tuttlingen, suburban Tokyo, and Shanghai-Suzhou clusters. Rigid endoscope production draws from German-engineered Hopkins rod-lens systems, Japanese precision glass, and Chinese metal component fabrication. Supply chain risk centers on tariff exposure for fluorescence imaging equipment crossing transatlantic routes. Distribution runs through hospital procurement coalitions and GPO contracts rather than direct facility sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in visualization instruments for MIS rests on cloud-based platform adoption compressing hardware refresh cycles and elevating software attach rates. Cost-down drivers in edge AI processing and consolidated video tower architectures enable premium-tier shifts without proportional bill-of-materials escalation.
For Market Incumbents: Lock in multi-year enterprise contracts with United States integrated delivery networks before procurement coalition consolidation hardens further. Deepen backward integration into specialized sapphire lens manufacturing to defend against single-source dependencies in Tuttlingen and Tokyo. Prioritize FDA 510(k) pathway efficiency for camera system introductions against EMA MDR clinical data delays threatening European market access. Cloud-native platform development represents the critical R&D lever for sustaining margin control. For New Entrants and Emerging Players: Capture remote surgical observation platform white space as hospital IT departments mandate cloud connectivity for disaster recovery and multi-site standardization. Target educational institutions in German university hospital networks where simulation market growth outpaces saturated healthcare provider procurement. Exploit fluorescence-guided surgery certification gaps by offering bundled training protocols with indocyanine green and methylene blue systems. SaaS-tiered pricing models penetrate price-sensitive ambulatory surgical centers. For Investors and Strategic Acquirers: Asymmetric upside sits with component-focused subscale suppliers holding captive optical glass or sapphire lens capabilities. Five-to-ten-year viability favors vendors with vertically integrated manufacturing over pure-play software entrants lacking hardware validation pathways. Acquisition target archetype: mid-tier visualization tower manufacturers with FDA clearances and stranded European registrations awaiting MDR clinical data completion. Signal to watch: hospital procurement coalition unbundling of after-sales service contracts from equipment purchases.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate-based clearances accelerate camera system introductions versus EMA MDR delays. |
| CE Marking Pathway | Prospective clinical studies under MDR extend registration timelines and inflate compliance costs. |
| Hospital System Partnership | Multi-year enterprise agreements with integrated delivery networks consolidate procurement leverage. |
| Software Companion Development | AI-assisted image analytics migration from research to standard of care drives replacement demand. |
| Reimbursement Strategy | PMDA QMS conformity opens universal health coverage access in Japan's aging demographic markets. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down optical component manufacturing tracking forms the analytical core. Primary interviews with GPO contracts managers, biomedical engineers, hospital purchasing committees, and regulatory affairs specialists at visualization instrument vendors cross-validated against secondary sources including FDA 510(k) filings, EMA MDR submission databases, hospital procurement databases, and GPO contract disclosures. Triangulation between demand-side procurement patterns and supply-side manufacturing capacity ensures segment-level precision.
Input-output matrices map camera head, video processor, and light source unit economics against replacement cycle timing across academic medical centers, community hospitals, and ambulatory surgical centers. Segmentation dimensions span product type, technology deployment architecture, end user category, and regional regulatory cluster. CAGRs derive from installed base erosion rates and fluorescence imaging adoption curves. Forecast inputs include hospital capital equipment refresh cycles and cloud connectivity mandate penetration across integrated delivery networks.
Regulatory pathway divergence, procurement coalition consolidation velocity, and fluorescence imaging training protocol standardization are the dominant revision risks. Forecasts reflect assumptions around predicate-based clearance efficiency and MDR clinical evidence escalation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Coating Thickness Measurement Instruments Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
Mass Spectroscopy Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Handheld XRF Analyzers Market
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Africa Digital Thermometer Market