
 Porcelain Tableware Market | 2026-2036
Porcelain Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Porcelain Tableware Market Analytics
The EU Green Deal's durability mandates for food-contact materials is repositioning procurement priorities across European hospitality supply chains. Villeroy & Boch AG leverages its German manufacturing heritage to sustain premium positioning in commercial channels. Bernardaud anchors artisanal production in Limoges while competing for luxury hotel contracts across Asia. Churchill China plc dominates institutional catering supply through cost-engineered vitrified porcelain lines.
Porcelain tableware comprises ceramic vessels fired at temperatures exceeding 1,200 degrees Celsius, yielding vitrified, non-porous bodies with translucency and mechanical strength suited to repeated thermal cycling in food service. The material's primary commercial purpose centers on durable, chemically inert presentation and serving platforms that withstand commercial dishwasher protocols. Dinnerware holds the largest revenue pool within product type segmentation, though specialty items command the highest unit margins through limited artisan editions. Hotels represent the fastest-growing end user channel as property renovation cycles accelerate post-pandemic asset refreshes. Modern design style leads volume in residential channels while traditional styling sustains its margin premium in heritage European markets.
REACH regulations govern chemical migration limits for glazed surfaces across European markets, while FDA compliance requirements shape export eligibility for manufacturers supplying North American food service operators. BIS certification under India's ceramic goods quality control order is tightening market access for unbranded imports. Stakeholders must monitor evolving extended producer responsibility frameworks for ceramic waste streams as jurisdictions adopt circular economy mandates.
Market Dynamics
The EU Green Deal's durability mandates for food-contact materials are redirecting procurement specifications across European hospitality supply chains, compressing demand for disposable alternatives while elevating certified porcelain specifications in contract tenders.
Growth Catalysts
- EU Green Deal procurement redirection:Durability mandates for food-contact materials are elevating porcelain specifications in institutional tenders across German and French hospitality supply chains.
- Heritage manufacturing clusters:Concentrated artisan production in Limoges and Meissen sustains export demand from Middle Eastern luxury hotel developers seeking provenance credentials.
- Vitrification technology advances:Enhanced thermal shock resistance from refined kaolin formulations is extending service life in commercial dishwasher protocols.
Market Restraints
- Energy input cost volatility:Natural gas price fluctuations directly impact firing kiln economics, compressing margins for manufacturers dependent on continuous kiln operations.
- Kaolin supply concentration:Premium ceramic-grade kaolin deposits concentrate in specific Brazilian and UK extraction zones, creating geographic vulnerability in raw material security.
- REACH compliance friction:Chemical migration testing for glazed surfaces extends product launch timelines and elevates certification costs for export-oriented manufacturers.
Strategic Opportunities
- Saudi Arabian luxury hospitality expansion:Giga-project developments in Riyadh and Jeddah are generating contract demand for artisanal tableware with documented European provenance.
- Extended producer responsibility frameworks:Emerging circular economy mandates for ceramic waste streams create first-mover advantage for manufacturers establishing take-back infrastructure.
- Digital printing convergence:Inkjet decoration technology is enabling short-run customization for boutique hotel chains seeking property-specific tableware identities.
Industry Challenges
- Master craftsperson succession gaps:Traditional hand-finishing techniques face generational transfer risks as European apprenticeship pipelines contract.
- Multi-jurisdiction certification complexity:Simultaneous FDA, REACH, and BIS compliance requirements fragment quality assurance resources for exporters serving multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Porcelain Tableware Market |
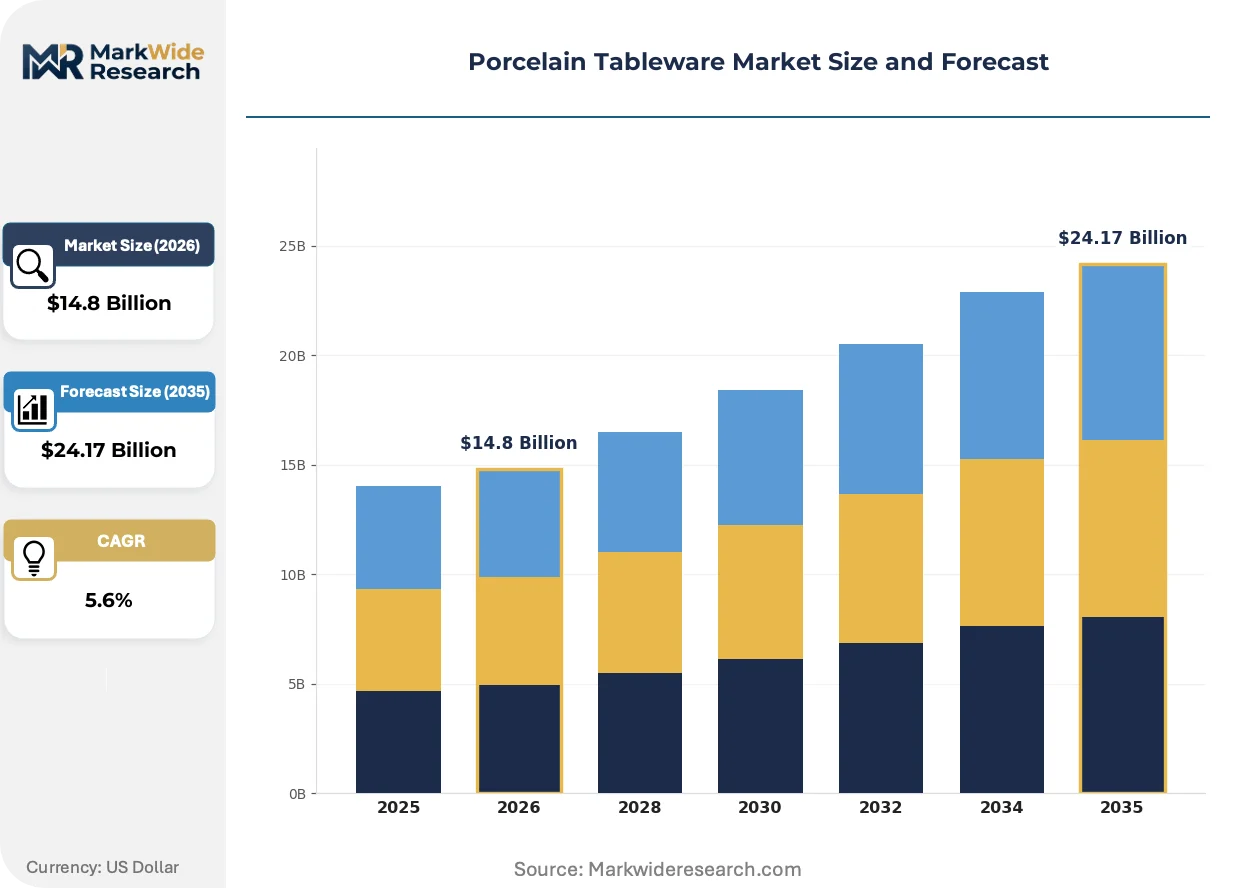
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dinnerware, Serveware, Cookware, Specialty Items End User: Residential, Commercial, Hotels, Restaurants Design Style: Modern, Traditional, Rustic, Minimalist Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesalers |
| Companies Covered | Lenox Corporation, Bernardaud, Villeroy & Boch AG, Haviland & Cie, Noritake Co., Limited, Rosenthal GmbH, Churchill China plc, Meissen Porcelain, Fiskars Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Porcelain Tableware Market Evolving Landscape
Digital decoration technologies and regulatory durability mandates are compressing traditional production timelines while elevating technical performance specifications across commercial and residential channels.
Advanced inkjet printing systems are enabling photorealistic surface decoration with lead-free glaze formulations. Boutique hotel chains in the UAE and Saudi Arabia are specifying short-run custom designs at volumes previously uneconomical for analog screen printing. This capability is converging with generative design tools to compress concept-to-production cycles from months to weeks.
REACH chemical migration limits for heavy metals in glazed surfaces are tightening testing protocols across European markets. Manufacturers must now document batch-level compliance for cobalt and cadmium content, elevating quality assurance overhead. The institutional catering segment is responding by consolidating supplier relationships toward vertically integrated producers with captive laboratory testing capacity.
Direct procurement from heritage manufacturers is displacing traditional wholesale distribution for luxury hospitality projects. Architects and interior designers for five-star hotel developments in Doha and Singapore are establishing direct supply relationships with Limoges and Meissen producers, bypassing regional distributors to secure provenance documentation and customization flexibility. This pattern is most visible in Gulf Cooperation Council markets where project scale justifies dedicated production runs.
Porcelain Tableware Market Segmentation
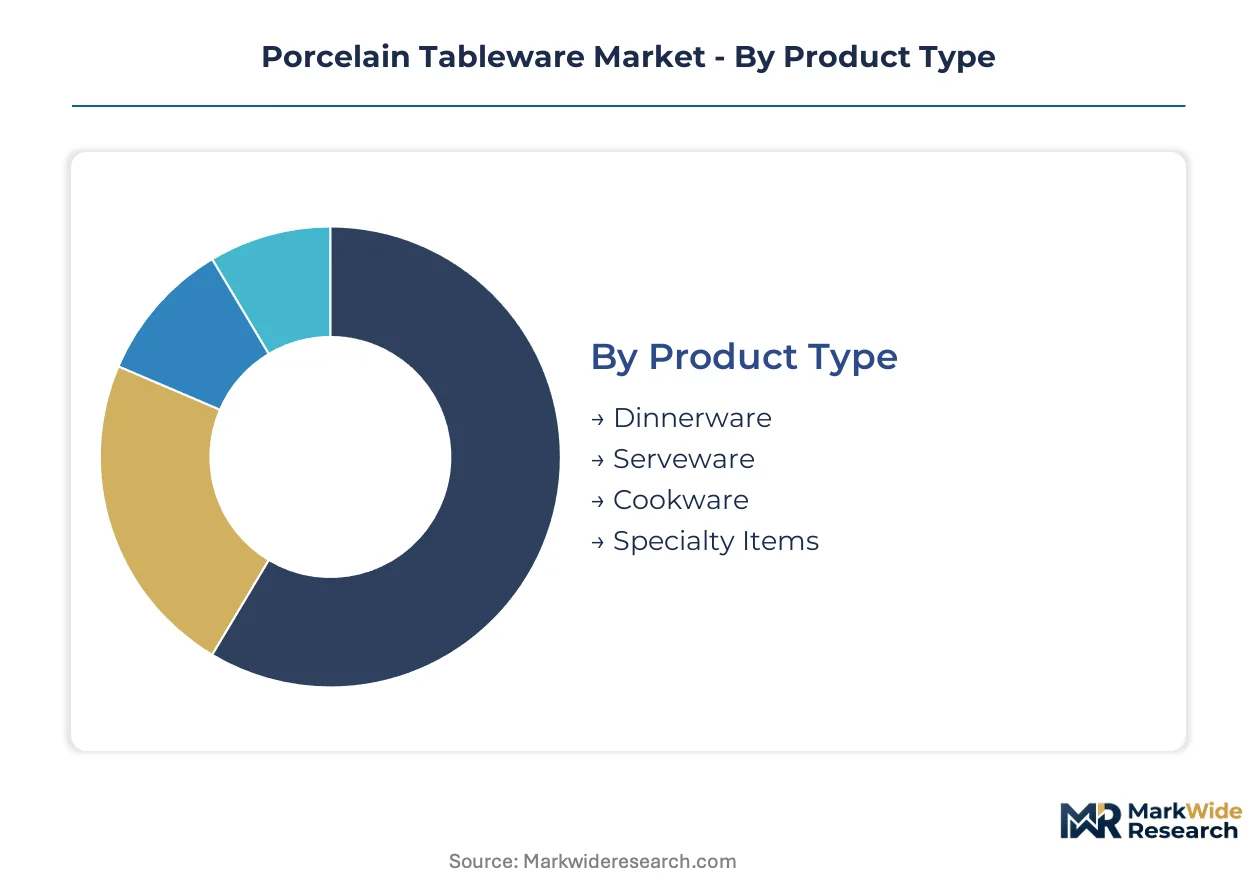
Porcelain tableware segmentation reveals divergent margin structures across commercial and residential channels. Procurement specifications, design preferences, and distribution economics create distinct competitive arenas requiring targeted positioning strategies.
Product Type:
Buyers in this category differentiate primarily by usage intensity and replacement frequency, with commercial operators prioritizing durability metrics over aesthetic differentiation.
- Dinnerware:Plates, bowls, and flatware collections constitute the foundational revenue base, with vitrified bodies engineered for thermal shock resistance. Demand concentrates in institutional catering contracts across Germany and France, where EU Green Deal durability mandates favor certified porcelain over disposable alternatives.
- Specialty Items:Limited artisan editions and commissioned pieces command the highest unit margins through documented provenance credentials. Luxury hotel developers in Saudi Arabia and the UAE source directly from Limoges and Meissen producers, bypassing wholesale channels to secure customization flexibility and heritage documentation.
- Serveware:Platters, tureens, and presentation vessels designed for buffet and banquet service. Commercial hospitality operators in North America specify these for fine-dining quality elevation.
- Cookware:Flameproof porcelain casseroles and baking vessels with thermal expansion coefficients matched to stovetop and oven cycling. Residential channels in heritage European markets sustain demand for traditional forms.
Volume sits with Dinnerware; growth tilts toward Specialty Items.
End User:
Application context dictates performance specifications, with food service operators enforcing dishwasher protocol compatibility that residential buyers rarely demand.
- Hotels:Property renovation cycles accelerated post-pandemic are driving contract demand for coordinated tableware programs. Five-star developments in Doha and Singapore specify property-specific identities through direct manufacturer relationships.
- Restaurants:Fine-dining establishments across North America and Europe are replacing stainless steel and melamine with porcelain for perceived quality elevation. REACH compliance requirements for glazed surfaces extend procurement evaluation timelines.
- Commercial:Institutional catering and corporate food service operations prioritize cost-engineered vitrified lines with standardized replacement protocols.
- Residential:Individual consumers purchasing through retail channels, with modern design styling leading volume and traditional styling sustaining margin premiums in heritage markets.
Procurement volume clusters in Restaurants; expansion rates are steepest in Hotels.
Design Style:
Aesthetic positioning separates premium heritage producers from cost-competitive manufacturers, with regional taste formations creating geographic demand concentration.
- Modern:Clean lines and neutral palettes dominate residential channel volume in North American and Northern European markets. Generative design tools and inkjet printing enable rapid concept-to-production compression for boutique hotel chains.
- Traditional:Ornamented forms with documented craft heritage sustain margin premiums in German and French domestic markets. Bernardaud and Meissen producers anchor this segment through artisanal production clusters.
- Rustic:Textured surfaces and earth-tone glazes appealing to farm-to-table restaurant concepts and casual dining environments.
- Minimalist:Reduced form vocabulary emphasizing material translucency and precise proportion, concentrated in Scandinavian-influenced markets and contemporary luxury hospitality.
Modern styling captures the broadest volume base; Traditional commands the highest margin premiums.
Distribution Channel:
Channel selection reflects order scale, customization requirements, and provenance documentation needs, with direct procurement displacing intermediaries in luxury hospitality.
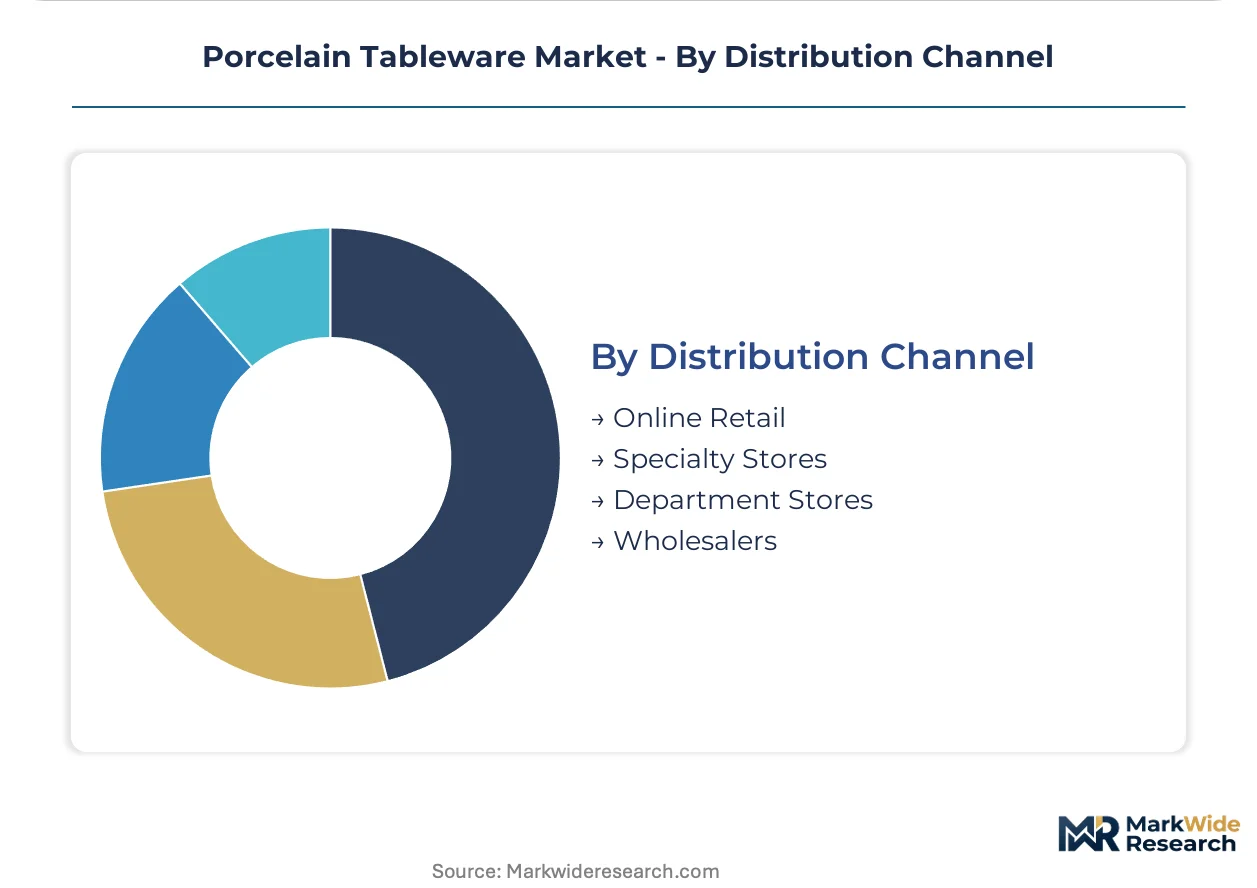
- Wholesalers:Traditional intermediaries serving mid-scale hospitality and institutional catering with standardized product lines. Margin compression from direct procurement trends is forcing consolidation toward value-added services.
- Online Retail:E-commerce platforms capturing residential demand through expanded assortment access and visual merchandising capabilities. Churchill China plc and similar producers leverage digital channels for institutional client acquisition.
- Specialty Stores:Curated physical retail environments emphasizing tactile evaluation and staff expertise, concentrated in heritage European markets with established ceramic consumption cultures.
- Department Stores:Multi-category retailers serving gift purchase occasions and entry-level premium positioning, with declining foot traffic shifting volume toward digital integration.
Transaction volume flows through Wholesalers; channel expansion is most rapid in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Meissen anchors the most concentrated heritage production cluster for porcelain tableware, with artisan workshops sustaining export demand from luxury hospitality developers across the Middle East and Asia.
Germany
Fine-dining restaurants in Berlin and Munich are replacing stainless steel service with porcelain for perceived quality elevation. The EU Green Deal's durability mandates for food-contact materials redirect procurement specifications toward certified vitrified lines in institutional tenders. Saxony's Meissen and Thuringia's porcelain workshops anchor artisan production clusters supplying heritage-documented tableware to Saudi Arabian giga-projects.
France
Luxury hotel developers in Paris and Lyon specify property-specific tableware identities through direct manufacturer relationships. REACH chemical migration limits for heavy metals in glazed surfaces tighten testing protocols across French hospitality supply chains. Limoges maintains its concentrated artisan production base, with Bernardaud anchoring export demand from Doha and Singapore five-star developments seeking provenance credentials.
United States
Fine-dining establishments in New York and Chicago are elevating service quality through porcelain replacement of melamine and stainless steel alternatives. FDA compliance requirements for food-contact surfaces shape export eligibility for European manufacturers supplying North American operators. California's hospitality procurement channels concentrate demand for vitrified dinnerware compatible with commercial dishwasher protocols.
China
Domestic hospitality renovation cycles accelerate post-pandemic asset refreshes across Shanghai and Beijing hotel properties. The country's national quality standards for ceramic goods tighten market access specifications for imported tableware. Jingdezhen's historic porcelain production cluster sustains artisan capacity while industrial manufacturers in Guangdong supply cost-engineered vitrified lines for institutional catering.
Saudi Arabia
Giga-project developments in Riyadh and Jeddah generate contract demand for artisanal tableware with documented European provenance. SFDA food-contact material regulations align procurement specifications with durability and chemical safety mandates. The Kingdom's luxury hospitality expansion redirects direct procurement relationships toward Limoges and Meissen producers, bypassing traditional wholesale distribution channels.
Porcelain Tableware Market Competitive Landscape
The competitive structure tilts toward heritage manufacturers with documented artisan credentials and vertically integrated testing capacity. Tiered positioning separates premium provenance-focused producers from cost-engineered vitrified line specialists. Three archetypes dominate: European heritage houses with direct luxury hospitality relationships, scale-driven institutional catering suppliers, and regional fabricators serving domestic wholesale channels. Capacity consolidation and digital decoration technology licensing represent the dominant competitive moves across the analysis window.
Within the heritage manufacturer tier, Bernardaud and Meissen Porcelain exemplify provenance-driven positioning through concentrated artisan production in Limoges and Saxony respectively. Villeroy & Boch AG occupies a position bridging premium residential and commercial hospitality channels through its German manufacturing base. Churchill China plc represents the scale-driven institutional catering archetype, with cost-engineered vitrified lines dominating standardized replacement protocols.
| Leading Market Players |
|---|
| Lenox Corporation |
| Bernardaud |
| Villeroy & Boch AG |
| Haviland & Cie |
| Noritake Co., Limited |
| Rosenthal GmbH |
| Churchill China plc |
| Meissen Porcelain |
| Fiskars Group |
| Others |
Value Network & Pricing Analysis
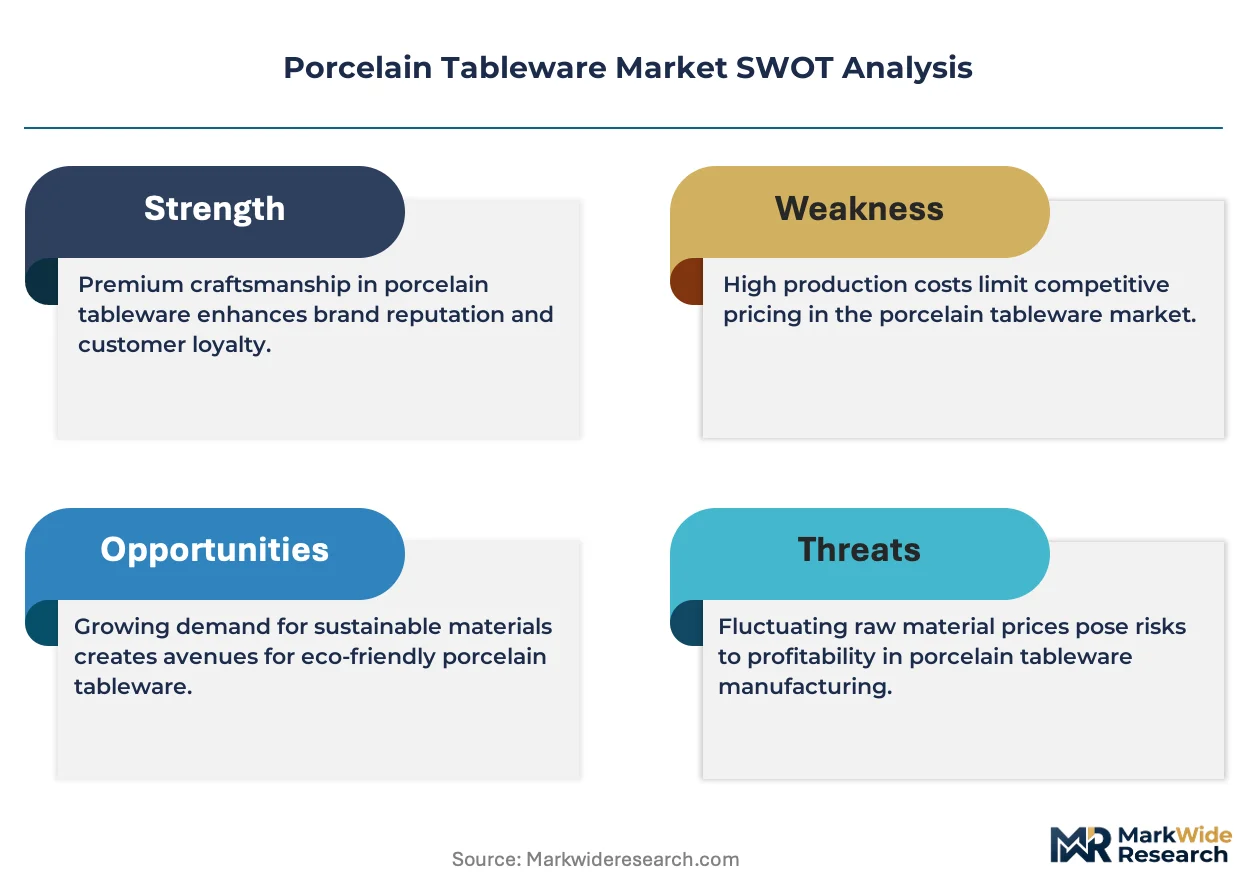
Natural gas input costs cascade through kiln-fired production economics, compressing margins for continuous-firing manufacturers while elevating price premiums for batch-operating artisan workshops in Meissen and Limoges. This cost divergence stratifies end-market positioning, with energy-intensive vitrified lines facing pricing pressure against heritage-documented specialty items commanding provenance premiums.
Pricing Analysis
Value-based pricing anchored on documented craft heritage and thermal performance durability separates premium artisan producers from cost-engineered competitors. Three-tier pricing structure across heritage artisan, commercial vitrified, and economy ceramic lines reflects certification grade and customization depth. Pricing pressure stems from natural gas cost volatility squeezing continuous kiln operations. Institutional catering buyers exhibit highest price sensitivity, while luxury hospitality developers in Saudi Arabia and the UAE prioritize provenance documentation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian ceramic-grade kaolin deposits, where premium extraction zones feed European and Asian manufacturing clusters. Raw material security rests on UK kaolin alternatives and refined clay formulations from specific German extraction sites. Geographic supply concentration spans Brazil, the United Kingdom, and Germany for critical inputs. Tariff exposure on glazed ceramic imports into North American markets elevates landed cost uncertainty. Distribution runs through direct manufacturer relationships displacing traditional wholesale intermediaries in luxury hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The porcelain tableware sector is transitioning from analog decoration to digital inkjet printing, with generative design tools compressing concept-to-production cycles and enabling short-run customization previously uneconomical at scale.
For Market Incumbents: Anticipate margin compression in standardized vitrified lines as digital printing lowers customization barriers for mid-tier competitors. Consolidate supplier relationships toward vertically integrated producers with captive laboratory testing capacity for REACH, FDA, and BIS compliance. Deepen backward integration into premium kaolin sourcing to secure raw material security against Brazilian supply concentration. For New Entrants and Emerging Players: Launch via direct-to-hospitality digital channels targeting boutique hotel chains in the UAE and Saudi Arabia seeking property-specific tableware identities. White-space opportunity concentrates in short-run customized serveware for farm-to-table restaurant concepts. Penetrate through inkjet decoration technology licensing partnerships with established European heritage manufacturers seeking capacity expansion without capital deployment. For Investors and Strategic Acquirers: Direct procurement relationships between Limoges producers and Saudi giga-project developers signal accelerating demand for documented European provenance in Middle Eastern luxury hospitality. Long-term viability favors heritage manufacturers with concentrated artisan production clusters and established export channels to Gulf Cooperation Council markets. Target acquisition archetype: mid-scale European producers with untapped digital decoration capabilities and dormant brand equity in Asian hospitality markets.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Decoration Technology Licensing | Enables short-run customization for boutique hotel chains seeking property-specific identities. |
| Backward Integration into Kaolin Sourcing | Secures raw material security against Brazilian deposit concentration and price volatility. |
| Direct Hospitality Procurement Relationships | Bypasses wholesale intermediaries to capture margin and secure provenance documentation. |
| Captive Laboratory Testing Capacity Investment | Accelerates REACH, FDA, and BIS compliance timelines for multi-jurisdiction exporters. |
| Take-Back Infrastructure for Ceramic Waste | Positions first-mover advantage under emerging extended producer responsibility frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with ceramic production managers, hospitality procurement directors, heritage manufacturer export specialists, and commercial kiln engineering consultants. ECHA REACH documentation, FDA food-contact surface compliance databases, and Saudi SFDA regulatory filings provided standardization benchmarks. Bottom-up volume estimates from identified manufacturer capacities reconciled against top-down demand segmentation across hospitality and residential channels.
Reconciliation of production capacity disclosures, import-export trade flows, and end-user procurement survey data shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user application, design style positioning, and distribution channel structure. CAGRs derived from fitted trend extrapolation validated against historical growth patterns in adjacent ceramic goods categories. Forecast inputs incorporated EU Green Deal durability mandate implementation timelines and post-pandemic hotel renovation cycle intensity.
The model assumes a particular technology adoption path; alternative pathways for digital inkjet decoration penetration would alter the outlook for artisan production cost structures and customization economics. Forecasts reflect assumptions regarding natural gas price stabilization, kaolin supply security, and regulatory harmonization across REACH, FDA, and BIS jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Remote Control Holder Market
Household Items
Global Paper Towels Market
Household Items
Party Supplies Market
Household Items
Netherlands Cookware Market
Household Items
Towel Warmers Market
Household Items
Insulated Drinkware Market
Household Items
Leaf Blower Market
Household Items
Portable Steamers Market
Household Items
UK Digital Showers Market
Household Items
Paper Towel Dispenser Market
Household Items
Ironing Boards Market
Household Items
Soap Tablet Market
Household Items
Tablet Tissue Paper Market
Household Items
Thermos Bottle Market
Household Items
Drinkware Accessories Market
Household Items
Oman Gas Hobs Market