
 Pizza Foodservice Market | 2026-2036
Pizza Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Foodservice Market Analytics
Gourmet pizza tiering is unwinding across the Pizza Foodservice Market as consumers trade up from value offerings to chef-crafted and artisanal formats. Domino's Pizza leverages its fortressing strategy and technology infrastructure to tighten delivery radius economics in suburban markets. Yum! Brands anchors Pizza Hut's turnaround through asset-light international franchising and digital-first repositioning in emerging markets.
Pizza foodservice denotes prepared-to-order or ready-to-heat pizza sold through commercial food and beverage establishments, typically involving high-temperature baking in deck, conveyor, or wood-fired ovens at temperatures exceeding 450°F to achieve characteristic crust texture and Maillard browning. The distribution channel dimension shows online delivery commanding margin pools through aggregator commissions and native app economics, while food trucks represent the fastest-growing physical format due to low capex entry and mobility-driven demand capture. Quick service dominates volume, though full-service gourmet positioning extracts premium pricing through experiential dining and ingredient provenance storytelling.
The FDA's Food Code and menu labeling requirements shape portion transparency and allergen management across US pizza chains, while the EU's F-Gas Regulation and REACH standards constrain refrigerant choices and food-contact material composition for European operators. State-level health departments and municipal grading systems further fragment compliance burdens. Stakeholders must monitor labor automation thresholds and third-party delivery fee caps as these policy levers directly compress unit economics and dictate technology investment pacing.
Market Dynamics
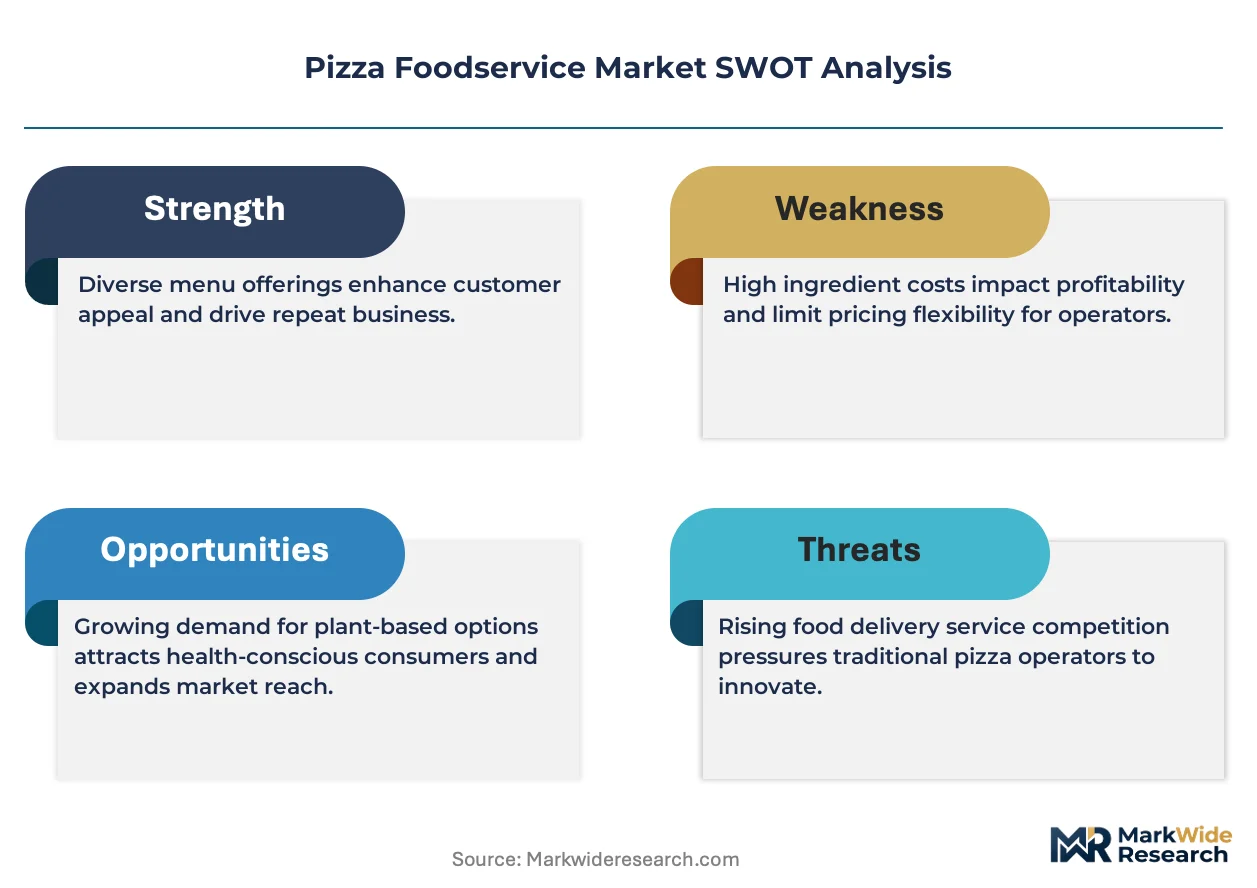
Quick-service chains and ghost kitchens are compressing traditional full-service pizza economics through centralized production and aggregator-dependent distribution, forcing legacy operators to reconfigure capital deployment toward smaller-footprint formats and technology infrastructure.
Growth Catalysts
- Third-party delivery platform penetration:Aggregator apps expand addressable demand for independent pizzerias beyond traditional trade zones, capturing incremental occasion-based consumption in suburban and exurban clusters.
- FDA menu labeling mandates:Standardized calorie and allergen disclosure requirements create compliance-driven technology adoption that improves operational transparency and consumer trust metrics.
- Wheat and cheese futures volatility hedging:Large-scale operators deploy commodity risk management tools to stabilize input costs across quarterly procurement cycles.
Market Restraints
- mozzarella supply concentration:Wisconsin and California dairy cooperatives control domestic cheese curd supply, creating geographic vulnerability to climate-driven production shocks.
- Deck oven manufacturing bottlenecks:Italian and German equipment suppliers face 12-18 month lead times for high-capacity stone hearth installations, constraining expansion velocity.
- Natural gas price exposure:Conveyor and wood-fired oven operations face energy cost volatility that compresses margin at high-temperature baking intensities.
Strategic Opportunities
- Plant-based protein integration:Pea and mycoprotein pepperoni alternatives attract flexitarian demographics in coastal metropolitan markets without full vegan positioning.
- Municipal food truck permitting liberalization:Chicago, Austin, and Portland have streamlined mobile food unit licensing, enabling low-capex market entry and demand testing.
- Carbon offset certification alignment:EU Green Deal supply chain disclosure requirements create first-mover advantage for operators documenting sustainable wheat and tomato sourcing.
Industry Challenges
- Pizza chef certification scarcity:Traditional dough fermentation and wood-fire temperature management skills face generational attrition as training programs contract.
- Point-of-sale integration complexity:Native app ordering systems must reconcile with third-party aggregator tablets, creating order management friction and inventory synchronization errors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Foodservice Market |
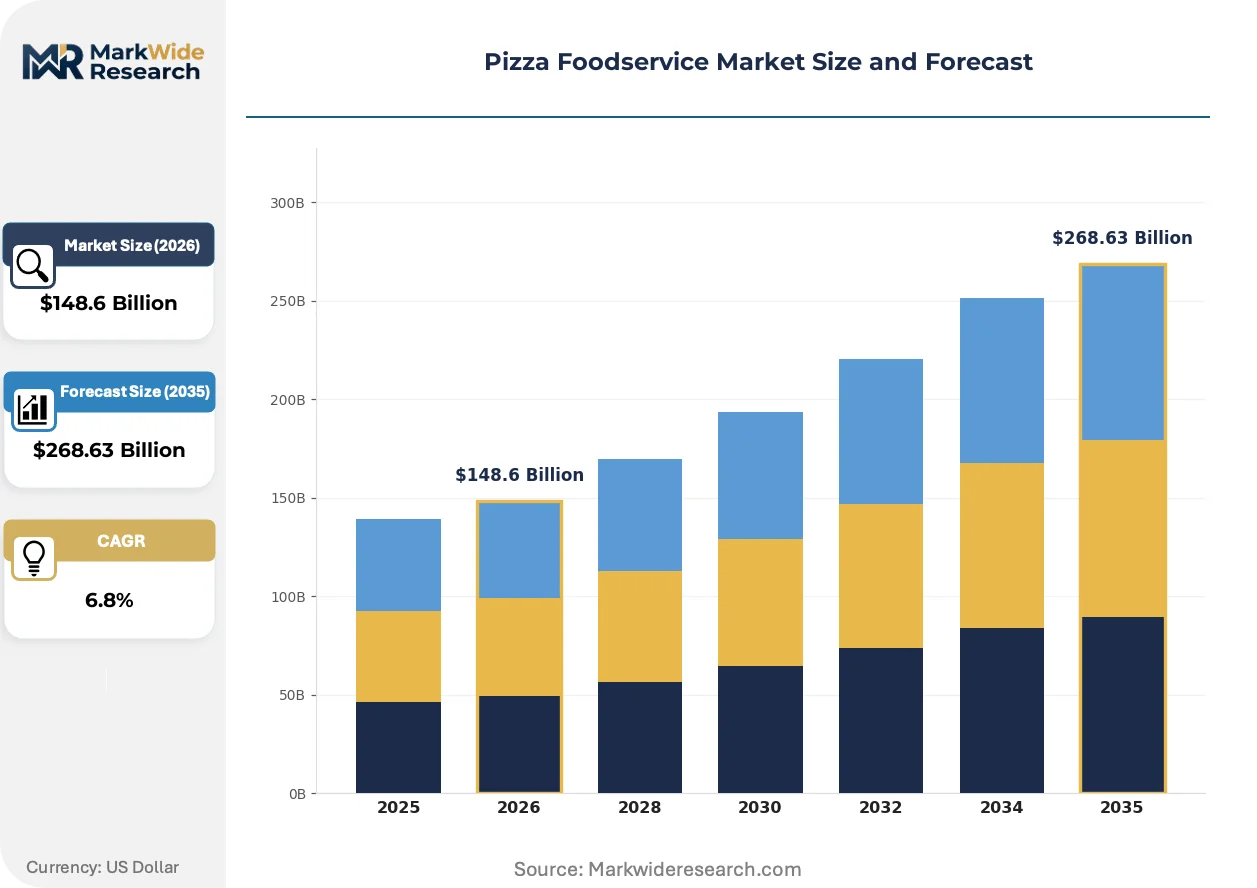
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $268.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Pizza, Gourmet Pizza, Frozen Pizza, Gluten-Free Pizza Distribution Channel: Online Delivery, Dine-In, Takeaway, Food Trucks End User: Households, Restaurants, Cafes, Corporate Offices Service Model: Full-Service, Quick Service, Self-Service, Catering |
| Companies Covered | Little Caesars, Marco's Pizza, Domino's Pizza, Blaze Pizza, California Pizza Kitchen, Yum! Brands (Pizza Hut), MOD Pizza, Jet's Pizza, Papa John's International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Foodservice Market Evolving Landscape
Automation and alternative protein formulation are compressing labor intensity and ingredient cost structures simultaneously, while regulatory disclosure requirements accelerate digital infrastructure investment across independent and chain operators alike.
Robotic dough stretching and sauce dispensing systems are displacing manual prep line positions in high-volume quick-service environments. Chains with 50-plus unit footprints deploy these installations to reduce per-unit labor hours and standardize crust consistency. The technology is displacing traditional kitchen brigade structures and enabling 24-hour production cycles without shift premium costs.
EU F-Gas Regulation phase-down schedules constrain hydrofluorocarbon refrigerant choices for European pizza cold chain operations. Operators must retrofit walk-in coolers and display cases with natural refrigerant alternatives or face equipment replacement mandates. Italian and Spanish markets show accelerated adoption of CO2 transcritical systems despite higher upfront capital requirements.
Subscription-based meal kit pizza components are capturing occasion-based demand from scratch-averse home cooks. Pre-portioned dough balls, sauce sachets, and topping combinations ship direct-to-consumer, bypassing traditional restaurant channel economics. This model shows strongest traction in United Kingdom and Australian metropolitan markets where delivery aggregator fatigue has set in among affluent households.
Pizza Foodservice Market Segmentation
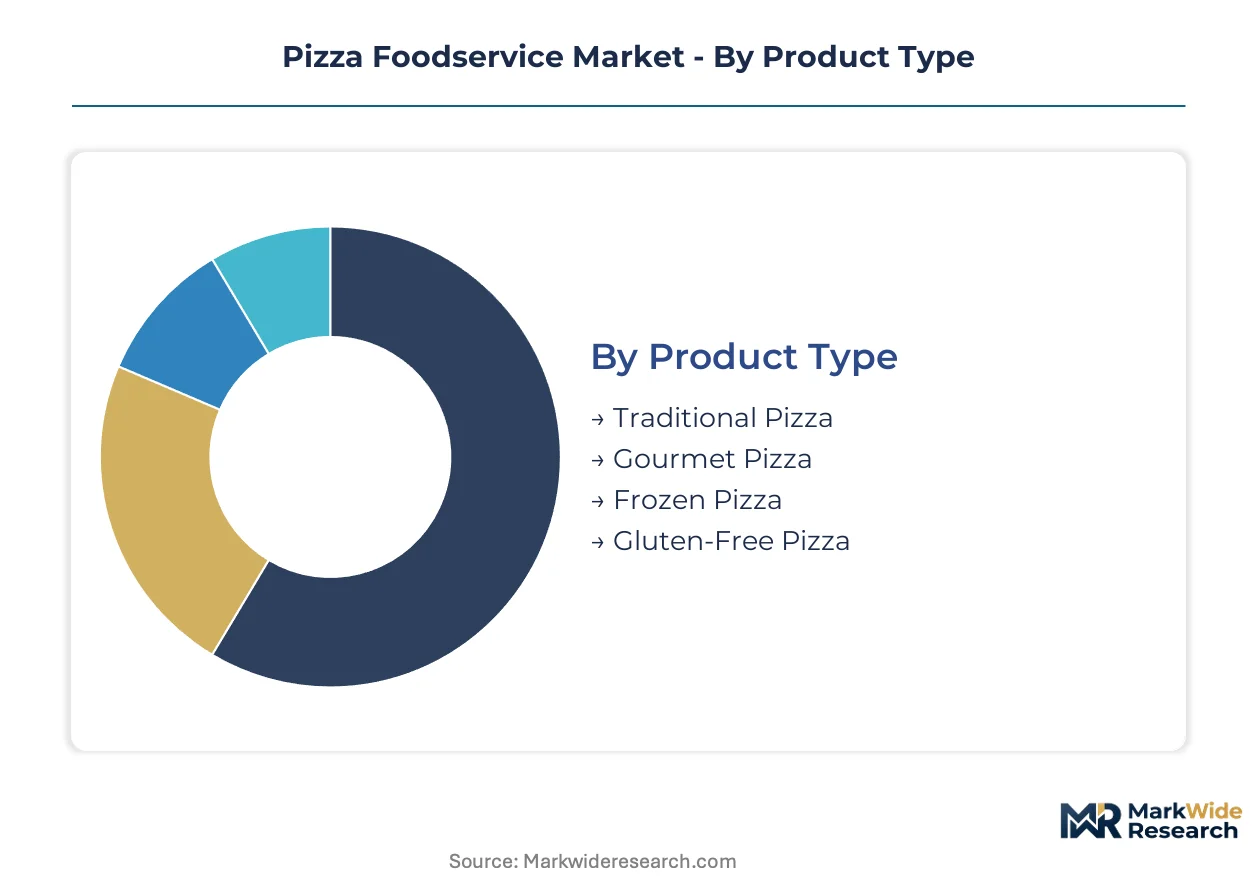
Pizza foodservice segmentation reveals how preparation methods, delivery mechanisms, and consumption occasions fragment procurement patterns and margin structures across operator types. Understanding these divides exposes where technology investment and regulatory compliance concentrate capital deployment.
Product Type:
FDA menu labeling requirements apply differentially across preparation tiers, with calorie disclosure mandates tightening most acutely on standardized formats while artisanal positioning claims exemption through variable portion sizing.
- Traditional Pizza:Tomato sauce and mozzarella-based preparations dominate volume through standardized recipes that optimize kitchen throughput. Quick-service chains in the United States deploy these formats to maximize conveyor oven utilization during peak hours.
- Gourmet Pizza:Chef-crafted preparations featuring imported ingredients and extended fermentation protocols command premium pricing through experiential positioning. Italian operators leverage DOP certification requirements to differentiate provenance storytelling in domestic and export markets.
- Frozen Pizza:Par-baked and blast-chilled preparations extend shelf life through modified atmosphere packaging, serving institutional procurement channels with predictable portion costs.
- Gluten-Free Pizza:Alternative flour formulations using rice, tapioca, or almond bases address celiac and wheat-sensitive demographics, requiring segregated prep lines to prevent cross-contamination under FDA allergen rules.
Established volume favors traditional formats; emerging adoption favors gluten-free alternatives.
Distribution Channel:
Aggregator commission structures compress margins most severely on digital-native orders, while physical format selection determines real estate intensity and labor scheduling flexibility.
- Online Delivery:Third-party platform dependence concentrates demand capture in suburban clusters where delivery radius economics favor centralized kitchen locations. Native app investments by Domino's Pizza demonstrate how vertical control over ordering infrastructure protects margin pools from aggregator extraction.
- Dine-In:Full-service experiential formats extract premium pricing through beverage attachment and extended table turns. Italian trattoria positioning in Brazil leverages wood-fired oven visibility to justify higher check averages.
- Takeaway:Counter-service formats minimize front-of-house labor while capturing impulse demand through high-traffic locations.
- Food Trucks:Mobile permitting liberalization in Austin, Chicago, and Portland enables low-capex market entry with mobility-driven demand capture at event venues and business districts.
Platform-dependent channels dominate transaction volume; mobile formats are gaining share fastest.
End User:
Procurement scale and contract structure vary sharply across institutional versus residential demand, with corporate accounts demanding nutritional transparency that exceeds baseline regulatory floors.
- Households:Occasion-based consumption concentrates on weekend evenings and sporting events, with aggregator fatigue driving subscription meal kit adoption in United Kingdom metropolitan markets.
- Restaurants:Independent pizzerias and small chains represent fragmented procurement with limited commodity hedging capability, exposing operators to mozzarella price volatility from Wisconsin and California dairy cooperatives.
- Cafes:Daypart extension strategies incorporate flatbread and breakfast pizza formats to utilize existing oven infrastructure during morning hours.
- Corporate Offices:Contract foodservice providers demand consistent portion specification and allergen documentation for cafeteria and catering operations.
Fragmented restaurant procurement sustains supplier diversity; corporate concentration drives standardization.
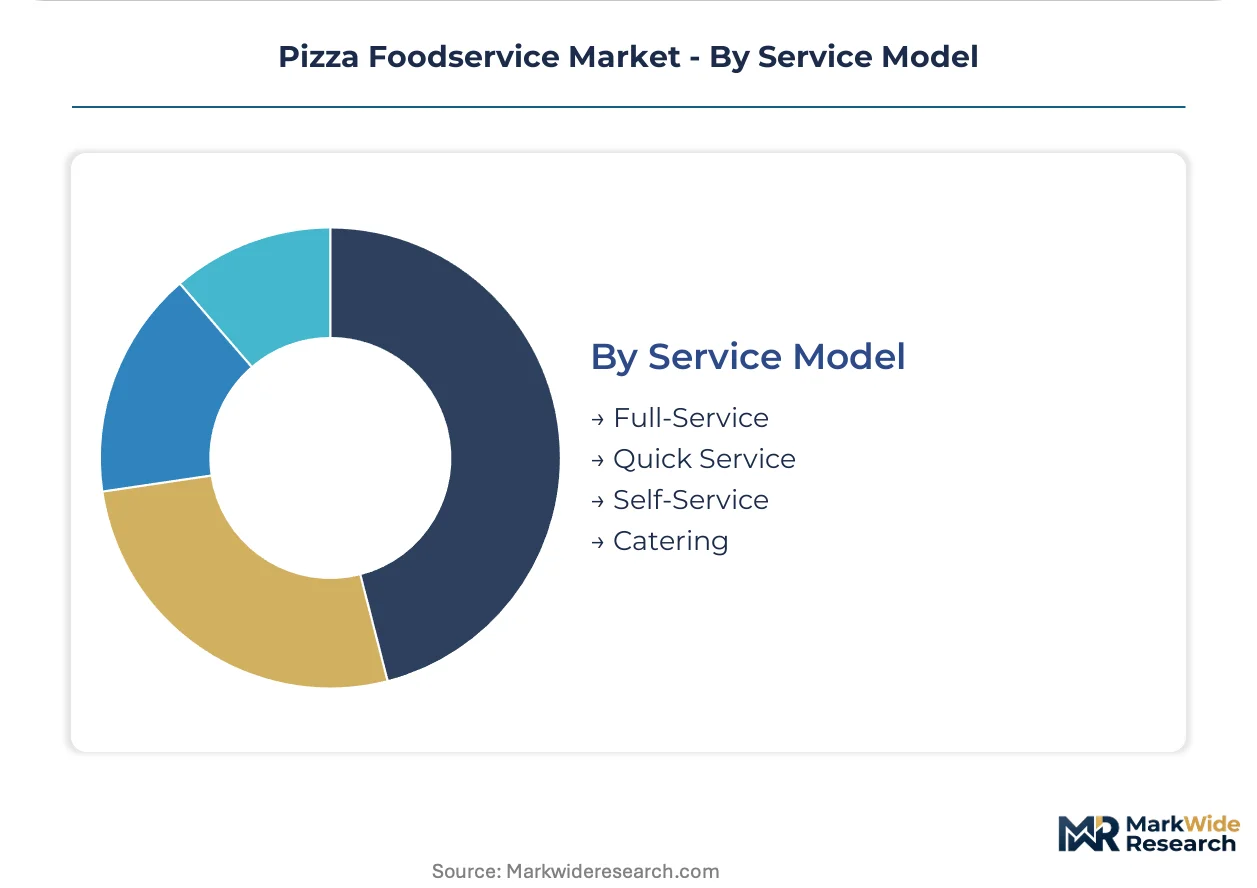
Service Model:
Labor automation thresholds and real estate intensity diverge across service tiers, with quick-service formats deploying robotic prep lines to displace manual positions in high-volume environments.
- Full-Service:Table-turn management and beverage programming maximize revenue per square foot through experiential positioning. Pizza Hut's international repositioning demonstrates how asset-light franchising preserves capital for digital infrastructure rather than dining room buildout.
- Quick Service:Conveyor oven standardization and limited menu breadth enable 24-hour production cycles without shift premium costs. Ghost kitchen operators compress real estate further through delivery-only formats.
- Self-Service:Kiosk ordering and grab-and-go heated display cases reduce front-of-house labor in transportation hub and campus locations.
- Catering:Large-format preparation and holding equipment address event-based demand with advance-order economics that smooth kitchen utilization curves.
Quick-service formats anchor transaction volume; catering operations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Brazilian consumers show acute price sensitivity in value-tier pizza procurement, while Italian buyers sustain premium positioning through provenance-based differentiation. The United States occupies the middle ground, where technology-enabled convenience commands loyalty independent of modest price premiums.
United States
Aggregator platform penetration has suburbanized pizza demand beyond traditional urban trade zones. The FDA's updated menu labeling rules mandate calorie disclosure for chains with twenty or more locations, compressing compliance costs onto mid-size operators. Chicago's municipal food truck permitting reforms have enabled mobile pizza units to capture lunch-hour demand in the Loop business district.
Italy
Protected designation of origin certification for mozzarella di bufala and San Marzano tomatoes anchors export pricing power. The EU F-Gas Regulation constrains refrigerant choices for cold chain operations, forcing retrofit investments in walk-in cooler infrastructure. Naples maintains concentrated artisanal production, where AVPN-certified pizzerias supply training and equipment standards to global franchise operations.
Brazil
Quick-service chains dominate volume through localized topping configurations targeting price-sensitive household segments. ANVISA allergen disclosure requirements align with Mercosur food safety harmonization, creating compliance templates for regional expansion. São Paulo's ghost kitchen clusters in Pinheiros and Vila Madalena aggregate delivery-only brands to minimize real estate intensity.
Germany
Wood-fired oven adoption in full-service formats extracts premium pricing through experiential dining positioning. The ECHA REACH framework governs food-contact material composition for pizza boxes and serving equipment, constraining supplier selection. Berlin's Kreuzberg district hosts independent pizzeria density that tests fermentation-forward concepts before national rollout.
Australia
Subscription meal kit pizza components capture occasion-based demand from scratch-averse metropolitan households. The TGA nutritional labeling framework applies to prepared food retail, though enforcement thresholds favor independent operators. Melbourne's inner-north precinct sustains food truck permitting liberalization that enables low-capex market entry for mobile pizza concepts.
Pizza Foodservice Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Pizza Foodservice Market. The vendor base shows moderate consolidation at the chain level, with independent pizzerias sustaining fragmentation in local markets. Three archetypes dominate: aggregator-dependent ghost kitchens, technology-integrated quick-service chains, and provenance-positioned artisanal operators. Competitive moves concentrate on native app infrastructure investment and asset-light international franchising.
Among US-based quick-service operators, Domino's Pizza and Papa John's International exemplify technology-forward positioning through proprietary delivery infrastructure. Yum! Brands occupies a position representing asset-light international expansion through franchised Pizza Hut operations. Little Caesars anchors the value-tier archetype with streamlined production formats that minimize labor intensity.
| Leading Market Players |
|---|
| Little Caesars |
| Marco's Pizza |
| Domino's Pizza |
| Blaze Pizza |
| California Pizza Kitchen |
| Yum! Brands (Pizza Hut) |
| MOD Pizza |
| Jet's Pizza |
| Papa John's International |
| Others |
Value Network & Pricing Analysis
FDA allergen disclosure mandates gate supply qualification for mozzarella and wheat flour suppliers while simultaneously enabling price differentiation through certified gluten-free and organic ingredient tiers. Operators must absorb compliance-driven segregation costs or pass them through to health-conscious buyer segments, tightening margin pools for undifferentiated traditional formats.
Pricing Analysis
After-sales subscription revenue through native app loyalty programs and meal kit components drives lifetime customer value beyond transactional pizza sales. Three-tier pricing structure across gourmet, traditional, and value levels separates wood-fired artisanal positioning from conveyor-oven quick service and frozen retail alternatives. Pricing pressure stems from third-party aggregator commission extraction, which compresses net margins on digital-native orders by fifteen to thirty points. Households in Brazilian and exurban US markets exhibit acute price sensitivity, while Italian provenance-certified buyers sustain premium tolerance for DOP-ingredient formats.
Supply Chain Analysis
Strategic stockpiling of mozzarella curd and specialty wheat flour dominates inventory strategy given Wisconsin and California dairy cooperative concentration and climate-driven production volatility. Raw material dependencies center on durum wheat from North Dakota and Kansas, mozzarella from domestic dairy cooperatives, and San Marzano tomato imports from Campania. Single-source vulnerability in deck oven manufacturing from Italian and German suppliers creates twelve-to-eighteen-month equipment procurement bottlenecks. Distribution runs through third-party delivery aggregators for suburban demand capture, with ghost kitchen clusters emerging as alternative downstream nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pizza foodservice operates within a cyclical recovery phase as post-pandemic occasion-based consumption normalizes and commodity input volatility moderates through hedging instrument adoption.
For Market Incumbents: Compound fortressing density in suburban trade zones through technology-enabled delivery radius optimization, while accelerating native app infrastructure investment to disintermediate aggregator-dependent margin extraction. Ghost kitchen entrants threaten quick-service volume capture; defend through backward integration into dough production facilities that standardize quality and reduce per-unit input cost exposure. For New Entrants and Emerging Players: AVPN certification fast-tracks credibility in artisanal positioning, enabling market entry through mobile food truck formats in Austin, Chicago, and Portland where permitting liberalization reduces capital barriers. Target corporate office catering contracts with allergen-transparent procurement specifications, leveraging subscription meal kit components as the go-to-market angle for scratch-averse metropolitan households in United Kingdom and Australian markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ghost kitchen and food truck sub-segments as equipment leasing and shared commissary infrastructure displace owned real estate. Long-term viability favors operators with vertical control over ordering technology and provenance-certified ingredient sourcing. Watch aggregator commission rate regulatory caps as the inflection signal for margin pool redistribution toward native-app operators.| Strategic Initiative | Industry Significance |
|---|---|
| Native App Infrastructure Investment | Domino's Pizza demonstrates how proprietary ordering platforms protect margins from third-party aggregator extraction. |
| AVPN Certification Acquisition | Naples-based training standards enable global franchise expansion through authenticated artisanal positioning. |
| Ghost Kitchen Cluster Formation | São Paulo's Pinheiros district aggregates delivery-only brands to minimize real estate intensity. |
| Commodity Hedging Program Deployment | Large-scale operators stabilize mozzarella and wheat input costs across quarterly procurement cycles. |
| CO2 Transcritical Refrigeration Retrofit | EU F-Gas Regulation compliance creates first-mover advantage in sustainable cold chain operations. |
Research Methodology
Desk research of FDA Food Code filings, EU F-Gas Regulation implementation reports, and municipal food truck permitting databases preceded structured interviews with quick-service chain procurement directors, ghost kitchen operators, Italian artisanal pizzeria owners, and third-party delivery platform account managers. Secondary validation drew from SEC 10-K disclosures of publicly traded operators, commodity futures exchange data, and equipment manufacturer order backlogs. Bottom-up unit economics modeling triangulated against top-down market sizing from national restaurant association statistics.
Variance decomposition across product type, distribution channel, service model, and regional regulatory cluster dimensions informed the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated wheat and cheese futures volatility patterns, ghost kitchen permitting velocity in metropolitan markets, and aggregator platform penetration saturation curves.
Underlying assumptions cover normalized commodity price corridors and regulatory enforcement continuity, with deviation risk concentrated in climate-driven dairy production shocks and third-party delivery fee cap legislation. Revision becomes warranted when aggregator commission structures or mozzarella supply concentration thresholds cross disruptive levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Online Food Delivery Market
Food Service
Africa Foodservice Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Restaurants and Mobile Food Services Market
Food Service
Online Catering Market
Food Service
Meal Kit Delivery Services Market
Food Service
Commercial Air Fryer Market
Food Service
Vietnam Online Food Delivery Market
Food Service
Europe Pizza Oven Market
Food Service
Food Service Pasta Market
Food Service
Canada Food Service Market
Food Service
Gas Floor Fryers Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Europe Airline Catering Services Market
Food Service
Bar Refrigeration Market
Food Service
Restaurants in Belgium Market