
 Pet Transporting Service Market | 2026-2036
Pet Transporting Service Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Transporting Service Market Analytics
Certified pet handlers and veterinary technicians is reorganizing how service tiers scale across domestic and international routes. AirPets International leverages its IATA-compliant crate protocols to dominate transoceanic segments. CitizenShipper anchors its marketplace model on independent driver networks, competing on price elasticity for ground transport. Royal Paws specializes in white-glove door-to-door delivery, sustaining premium positioning through dedicated climate-controlled fleets.
Pet transporting service encompasses the commercial coordination of live animal movement via ground, air, and intermodal channels, requiring temperature-controlled environments, species-specific containment systems, and health documentation verification. The primary purpose is to relocate companion and commercial animals while maintaining welfare standards across jurisdictional boundaries. Door-to-door service captures the largest revenue pool by absorbing documentation burden from owners, while specialized pet van deployment within vehicle type segments shows the fastest equipment growth due to custom ventilation and crating density. Individual clients within client type segments generate the highest volume, though veterinary clinics yield superior per-transaction margins through emergency and post-surgical transport needs.
The US DOT mandates commercial motor vehicle operator qualifications for interstate pet transport, while the FAA governs live animal acceptance policies and cabin hold specifications for air carriers. USDA APHIS administers health certificate requirements under the Animal Welfare Act, creating compliance costs that filter out informal operators. Stakeholders must monitor pending state-level legislation on driver background checks and animal liability insurance thresholds as these rules will reshape market entry requirements and operational overhead structures.
Market Dynamics
Employee relocation packages now systematically incorporate pet transport, converting a discretionary expense into a standardized corporate benefit that reshapes volume forecasting and service tier design across domestic and international corridors.
Growth Catalysts
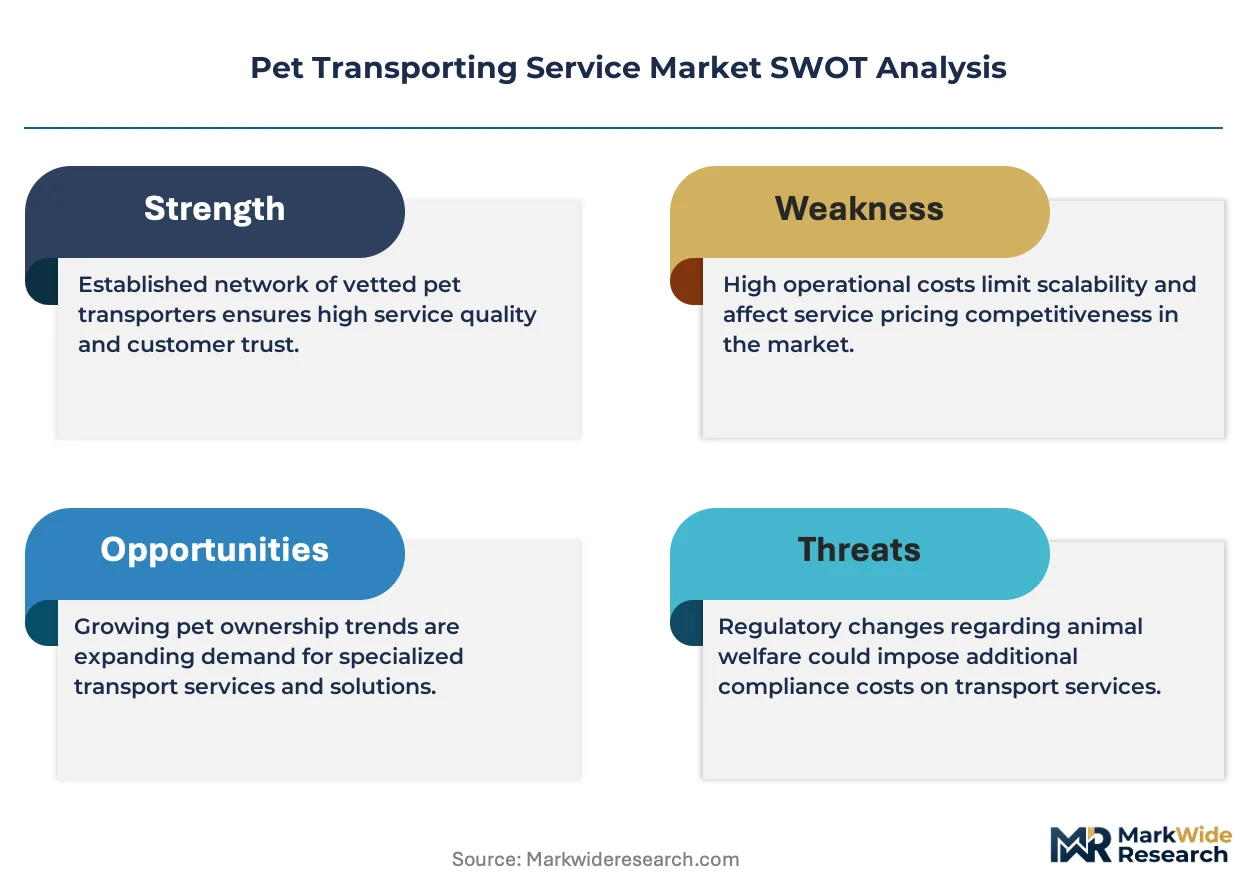
- US DOT Commercial Operator Mandates:Federal qualification requirements for interstate drivers professionalize ground transport, filtering out informal competitors and consolidating revenue toward certified fleet operators.
- Corporate HR Policy Integration:Relocation coordinators at Fortune 500 firms now negotiate annual pet transport contracts, generating predictable recurring revenue streams that stabilize capacity planning.
- Temperature-Controlled Fleet Deployment:Specialized van construction with custom ventilation and crating density enables higher animal throughput per vehicle while maintaining IATA welfare standards.
Market Restraints
- USDA APHIS Health Certificate Compliance:Interstate and international movement requires veterinary documentation that creates administrative bottlenecks and owner abandonment of transport plans.
- Aviation Fuel Cost Volatility:Air cargo rates fluctuate with jet fuel indices, compressing margins on transoceanic segments where ground alternatives do not exist.
- Concentrated Corridor Dependency:Demand clusters along Texas-Florida-California routes, leaving return legs underutilized and forcing deadhead repositioning costs onto pricing structures.
Strategic Opportunities
- Veterinary Clinic Emergency Transport:Post-surgical and critical care animal movement commands premium per-transaction margins with minimal price sensitivity from institutional buyers.
- State-Level Driver Background Check Legislation:Pending mandates in multiple jurisdictions will erect compliance barriers that favor incumbent operators with established screening infrastructure.
- Telematics-Enabled Route Optimization:Real-time GPS and environmental sensor integration allows dynamic scheduling that reduces transit stress and insurance liability exposure.
Industry Challenges
- Certified Handler Talent Pipeline:Veterinary technician cross-training programs remain underdeveloped, constraining service expansion during peak seasonal demand windows.
- FAA Live Animal Hold Specifications:Aircraft cabin temperature and pressure requirements limit carrier options and force complex intermodal handoffs on long-haul routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Transporting Service Market |
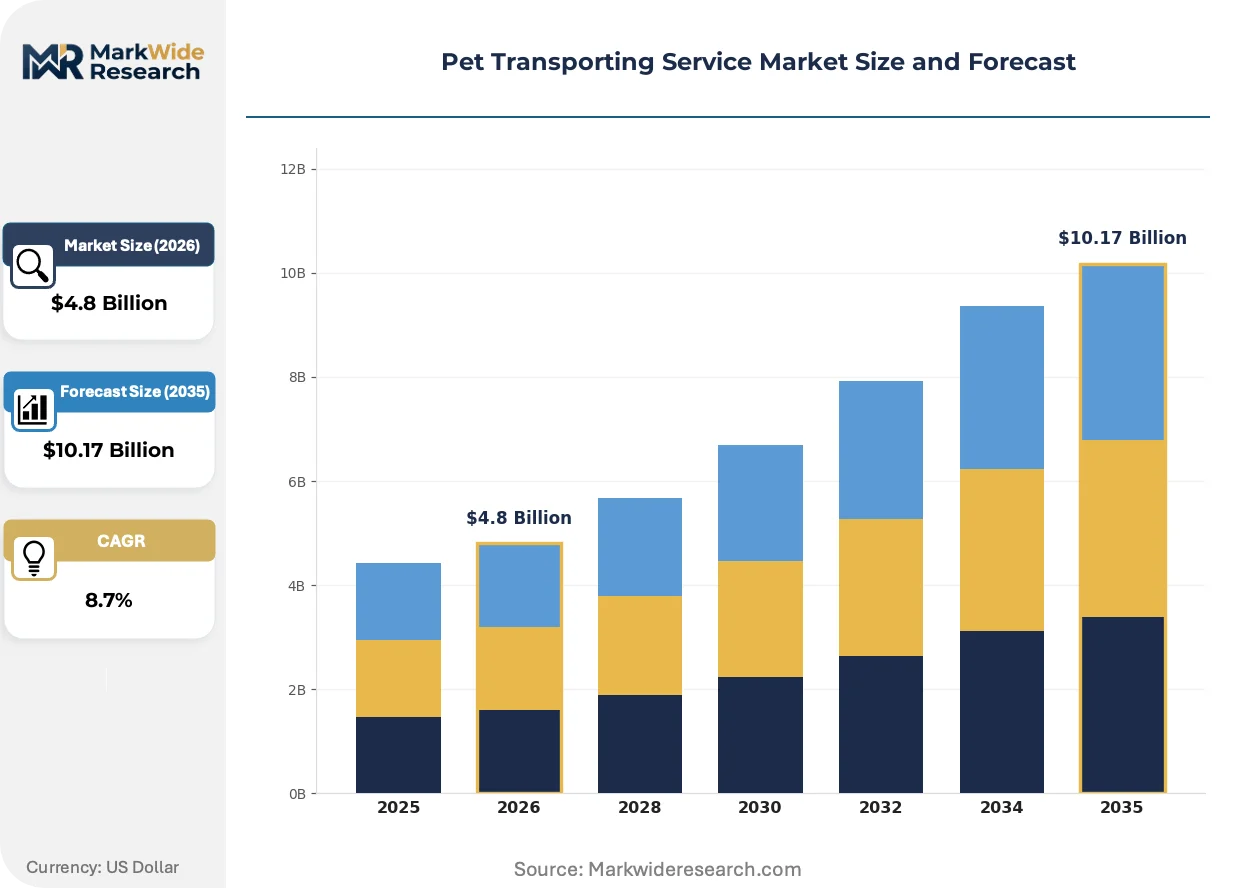
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Door-to-Door, Airport Pickup, Pet Taxi, Animal Boarding Vehicle Type: Minivan, SUV, Specialized Pet Van, Trailer Animal Type: Dogs, Cats, Birds, Reptiles Client Type: Individuals, Breeders, Pet Shops, Veterinary Clinics |
| Companies Covered | AirPets International, Air Animal, Inc., Happy Tails Travel, Inc., Royal Paws, Bluecollar Pet Transport, CitizenShipper, Starwood Pet Travel, World Care Pet Transport, LLC, PetRelocation, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Transporting Service Market Evolving Landscape
Digital coordination platforms are compressing the matching timeline between shippers and transport providers while sensor networks enable real-time welfare verification that replaces manual checkpoint reporting.
Portable environmental monitoring systems is miniaturizing. These battery-powered units track temperature, humidity, and air quality inside transport crates, transmitting data to owner smartphones via cellular networks. Individual pet owners booking door-to-door services now expect continuous visibility as a baseline feature. This capability is compressing insurance underwriting cycles and enabling dynamic pricing tied to verified welfare outcomes rather than static route classifications.
USDA APHIS is expanding digital health certificate verification through its online portal infrastructure. Veterinary clinics must now submit documentation through centralized systems that flag discrepancies before animals reach port of entry. International routes and species with complex quarantine requirements face the steepest compliance learning curves, prompting specialized software vendors to integrate directly with USDA databases.
Relocation benefit administrators are unbundling pet transport from lump-sum relocation packages. Corporate buyers now solicit separate RFPs for animal movement, treating it as a distinct spend category with dedicated vendor scorecards. This procurement model shift is most visible among technology and pharmaceutical firms with dense concentrations of H-1B visa holders, where pet ownership rates exceed national averages and failure to arrange transport triggers employment offer withdrawals.
Pet Transporting Service Market Segmentation
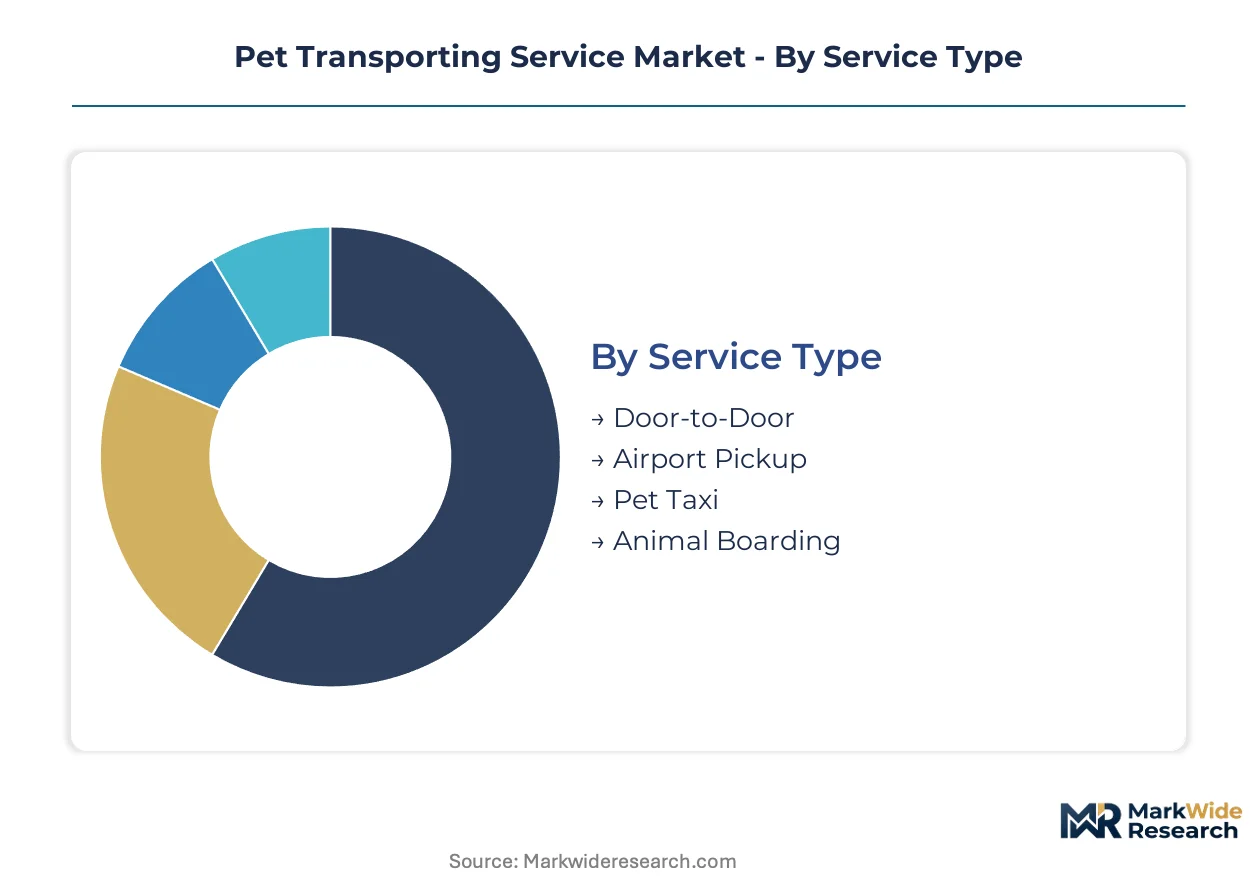
Segmentation in pet transporting services determines regulatory exposure, equipment specialization, and margin structure across distinct operational profiles. Service providers configure fleet and staffing models differently for each segment combination.
Service Type:
Door-to-Door dominates domestic corridors across Texas, Florida, and California, while Airport Pickup concentrates on international gateway cities with USDA APHIS inspection facilities.
- Door-to-Door:Comprehensive coordination including documentation, crate provision, and terminal-to-terminal handoffs. Demand clusters among corporate relocation packages along high-volume interstate corridors where deadhead repositioning costs challenge unit economics.
- Airport Pickup:Terminal retrieval and final-mile delivery after air cargo release. Concentrates at Dallas-Fort Worth, Miami International, and Los Angeles International where USDA APHIS maintains animal inspection stations.
- Pet Taxi:Short-distance urban transport for veterinary appointments and grooming services. Municipal licensing requirements vary across city jurisdictions.
- Animal Boarding:Temporary holding with transport integration for complex multi-leg itineraries. Facility licensing under state agricultural departments creates compliance overhead.
Door-to-Door commands the established base. The steepest expansion runs through Airport Pickup.
Vehicle Type:
Equipment selection tracks route distance and animal density requirements, with climate control specifications tightening under state animal welfare statutes.
- Specialized Pet Van:Custom ventilation systems and modular crating configurations enable 12-20 animal capacity per vehicle. IATA-compliant construction supports both ground and air cargo feeder operations.
- Minivan:Entry-level fleet option for individual and small-breeder clients. Limited climate redundancy restricts deployment to temperate corridors and short-haul routes.
- SUV:Premium positioning for single-animal transport with owner-accompanied options. Higher per-mile operating costs limit scale.
- Trailer:Multi-animal capacity for commercial breeding operations and shelter transfers. Requires commercial driver's license classification in multiple states.
Specialized Pet Van captures volume leadership. Trailer configurations gain share fastest among commercial breeding clients.
Animal Type:
Species-specific handling protocols and containment standards segment operational expertise and insurance underwriting categories.
- Dogs:Largest volume segment with established crate sizing standards and veterinary sedation protocols. Demand concentrates among individual relocations and breeder networks.
- Cats:Stress-sensitive transport requiring pheromone diffusion and minimal handling protocols. Veterinary clinic emergency referrals drive premium pricing.
- Birds:Temperature and air quality specifications exceed mammalian requirements. USDA APHIS interstate movement permits add documentation complexity.
- Reptiles:Specialized heating and humidity control with species-specific containment. Limited carrier availability creates supply concentration.
Dogs anchor the revenue base. Reptile transport shows the steepest margin expansion trajectory.
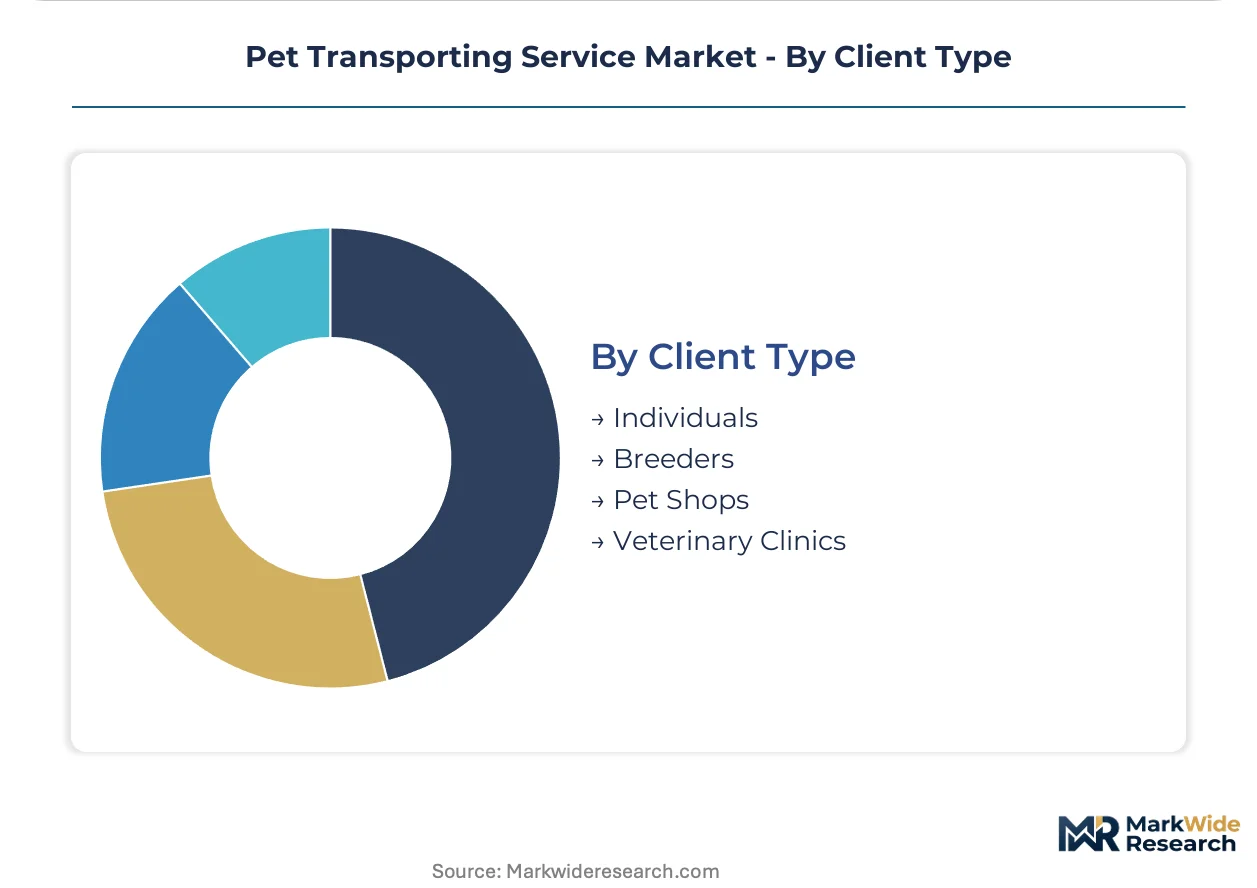
Client Type:
Procurement patterns diverge sharply between individual discretionary spend and institutional contract arrangements.
- Individuals:Price-sensitive bookings through digital marketplaces with seasonal concentration around summer relocation windows. Customer acquisition costs pressure margins.
- Veterinary Clinics:Emergency and post-surgical transport with minimal price sensitivity. Recurring referral relationships stabilize capacity utilization.
- Breeders:Volume contracts with predictable scheduling for puppy delivery to retail channels. Interstate health certificate requirements filter informal operators.
- Pet Shops:Commercial wholesale logistics with consolidated multi-animal shipments. Regulatory compliance with state retail animal sourcing laws shapes vendor selection.
Individuals generate the volume base. Veterinary Clinics deliver the steepest per-transaction margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US DOT and FAA anchor regulatory oversight across the largest revenue geography, with corridor concentration along Texas, Florida, and California driving equipment specialization and fleet deployment patterns.
United States
Corporate relocation packages and H-1B visa holder density generate sustained volume across domestic corridors. The USDA APHIS Animal Welfare Act mandates health certificate verification for interstate movement. Dallas-Fort Worth, Miami, and Los Angeles form the dominant triangle where specialized pet van fleets concentrate for door-to-door service delivery.
Canada
Cross-border pet movement with the United States sustains demand for documentation-heavy international coordination. Health Canada and the CFIA administer import permit requirements and quarantine protocols. Toronto Pearson and Vancouver International anchor the gateway infrastructure where airport pickup services cluster for trans-Pacific and trans-Atlantic routing.
Germany
Intra-EU pet relocation and Middle East expatriate return traffic generate premium service demand. The KBA enforces commercial vehicle operator qualifications for interstate animal transport. Frankfurt and Munich serve as the primary logistics hubs where IATA-compliant crate protocols concentrate for air cargo feeder operations.
United Kingdom
Post-Brexit pet travel scheme complexity has elevated demand for documentation coordination services. DEFRA administers the pet travel scheme with enhanced rabies vaccination and tapeworm treatment requirements. London Heathrow and Gatwick concentrate specialist handlers for transatlantic and Middle East corridor routes.
Australia
Stringent biosecurity quarantine requirements create extended holding and intermodal coordination needs. The Department of Agriculture enforces minimum 10-day quarantine for companion animals arriving from non-approved countries. Sydney and Melbourne anchor the eastern seaboard infrastructure where animal boarding and transport integration services concentrate.
Pet Transporting Service Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through dedicated climate-controlled fleets and IATA certification depth. The middle tier fragments across digital marketplace models and independent driver networks competing on price elasticity. Three archetypes define competitive positioning: integrated international operators with proprietary crate protocols, domestic ground transport specialists with regional fleet density, and platform-based aggregators matching shippers with independent carriers. Consolidation pressure favors M&A activity targeting veterinary clinic referral networks and technology licensing for telematics-enabled route optimization.
Within the integrated international tier, AirPets International exemplifies the archetype of proprietary protocol dominance, while Royal Paws occupies a position in premium door-to-door service delivery. CitizenShipper anchors the platform-based aggregation model, representing the price-competitive vector that compresses matching timelines between individual shippers and independent transport providers.
| Leading Market Players |
|---|
| AirPets International |
| Air Animal, Inc. |
| Happy Tails Travel, Inc. |
| Royal Paws |
| Bluecollar Pet Transport |
| CitizenShipper |
| Starwood Pet Travel |
| World Care Pet Transport, LLC |
| PetRelocation, Inc. |
| Others |
Value Network & Pricing Analysis
IATA-compliant crate certification gates both supplier qualification and price differentiation simultaneously, as only certified operators can access corporate relocation contracts while uncertified competitors remain trapped in price-elastic consumer segments. This regulatory threshold compresses margins at the economy tier while enabling premium capture through documented welfare compliance.
Pricing Analysis
Long-term offtake contracts with Fortune 500 relocation coordinators now anchor revenue planning for certified fleet operators, displacing spot-market dependency. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and real-time visibility integration. Cost compression in the economy tier is intensifying because digital marketplaces aggregate independent drivers into price-transparent bidding environments. Individual consumers booking through platforms exhibit highest price sensitivity, while veterinary clinics demonstrate minimal elasticity for emergency transport.
Supply Chain Analysis
The United States anchors specialized pet van manufacturing and climate-control system fabrication, while Germany and China produce IATA-compliant crate assemblies and sensor monitoring hardware. Fleet operators draw from aluminum crating, GPS telematics modules, and veterinary pharmaceutical inputs for sedation protocols. Single-source vulnerability concentrates in custom ventilation component suppliers serving the Texas-Florida-California corridor. Distribution runs through corporate procurement channels, veterinary clinic referral networks, and digital marketplace aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate benefit administrators are systematically expanding pet transport coverage, representing early-cycle penetration with H-1B visa holder density as the adoption tailwind.
For Market Incumbents: Compound fleet utilization through telematics-enabled route optimization that reduces deadhead repositioning costs along corridor routes. Deepen backward integration into veterinary technician training pipelines to constrain certified handler scarcity during peak seasonal windows. Defend against platform-based price compression by locking multi-year corporate contracts with dedicated capacity guarantees. For New Entrants and Emerging Players: Anchor in reptile and avian transport segments where specialized climate requirements limit incumbent coverage and command premium positioning. Target municipal pet taxi licensing gaps in secondary cities where regulatory barriers remain lower than major metropolitan markets. Pursue direct veterinary clinic partnerships as the go-to-market anchor for emergency referral revenue. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across specialized van deployment and sensor integration infrastructure, favoring scaled operators over asset-light models. Long-term viability across the projection horizon rests on regulatory compliance depth rather than price competitiveness alone. Acquisition targets should display established USDA APHIS documentation infrastructure and veterinary clinic referral density. Monitor pending state-level driver background check legislation as the signal for compliance barrier timing.| Strategic Initiative | Industry Significance |
|---|---|
| IATA Certification Investment | Unlocks corporate relocation contracts and transoceanic routing access through compliance depth. |
| Veterinary Clinic Network Acquisition | Captures emergency transport referrals with premium pricing and minimal customer acquisition cost. |
| Telematics Platform Integration | Enables real-time welfare verification that compresses insurance cycles and supports dynamic pricing. |
| Specialized Van Fleet Expansion | Increases animal throughput per vehicle while maintaining temperature compliance across corridor routes. |
| Corporate Relocation Partnership | Secures predictable recurring revenue through annual contracts with Fortune 500 benefit administrators. |
Research Methodology
Initial hypotheses were tested against primary input from relocation benefit administrators, fleet operations directors, veterinary clinic practice managers, and corporate HR procurement leads and refined through secondary validation. Primary fieldwork combined structured interviews with secondary sources including USDA APHIS regulatory filings, FAA live animal transport guidelines, corporate relocation policy disclosures, and interstate commerce documentation databases. Bottom-up segment sizing triangulated against top-down market reconstruction across service type, vehicle configuration, and client category dimensions.
Variance decomposition separated volume drivers from pricing dynamics across the projection horizon. Segmentation modeling incorporated service tier, animal type specialization, client procurement pattern, and geographic corridor density as structural dimensions. CAGRs derived from fitted growth curves applied to disclosed fleet capacity, corporate contract values, and platform transaction volumes. Industry-specific forecast inputs included H-1B visa issuance trends and corporate relocation package standardization rates.
Decision-makers should treat outputs as directional under stable regulatory enforcement and corridor demand concentration assumptions; material deviation would warrant model refresh. Forecasts embed assumptions regarding FAA live animal hold specification continuity and fuel cost volatility ranges specific to air cargo segments. Recalibration cycles align with material shifts in state-level driver qualification mandates and corporate benefit administrator procurement policy updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Pet Supplement Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Pet Feeder Market
Pet Care Products
Cat Collar Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
India Pet Clothing Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
South America Cat Food Market