
 Dog Biscuit Market | 2026-2036
Dog Biscuit Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Biscuit Market Analytics
Asset-light contract manufacturing and co-packing arrangements are narrowing the capital barrier for mid-tier entrants in dog biscuit production. Mars Petcare leverages global procurement networks to sustain ingredient cost advantages across multiple geographies. General Mills anchors its competitive position through refrigerated supply chain integration for fresh-format biscuits. Nestle SA differentiates via veterinary endorsement channels that command premium shelf positioning in specialty retail.
Dog biscuits comprise baked or extruded cereal-based treats formulated with protein meals, fats, binders, and functional additives, typically dried to moisture levels below 10 percent to ensure shelf stability and dental abrasion benefits. Their primary commercial purpose centers on reward-based training reinforcement, dental hygiene maintenance, and supplemental nutrition delivery between meals. Crunchy biscuits dominate volume throughput due to lower per-unit production costs and extended ambient shelf life, while grain-free and organic variants capture disproportionate margin pools as pet owners scrutinize ingredient provenance. Online retail channels are expanding fastest, though pet stores retain higher basket values through cross-selling of premium treat assortments.
FDA Center for Veterinary Medicine oversight, Association of American Feed Control Officials nutrient profiles, and state feed control official inspections collectively govern ingredient safety claims and manufacturing facility standards in the United States. These frameworks elevate compliance costs for imported products while creating preferential market access for domestic producers with established quality systems. Stakeholders must monitor evolving clean-label certification requirements and veterinary channel gatekeeping dynamics that will determine which formulation portfolios sustain pricing power.
Market Dynamics
Pet humanization among urban millennials and Gen Z owners is compressing demand toward premium formulations with clean-label ingredient disclosure, forcing manufacturers to reconfigure procurement networks and reformulate legacy portfolios faster than shelf-life cycles typically allow.
Growth Catalysts
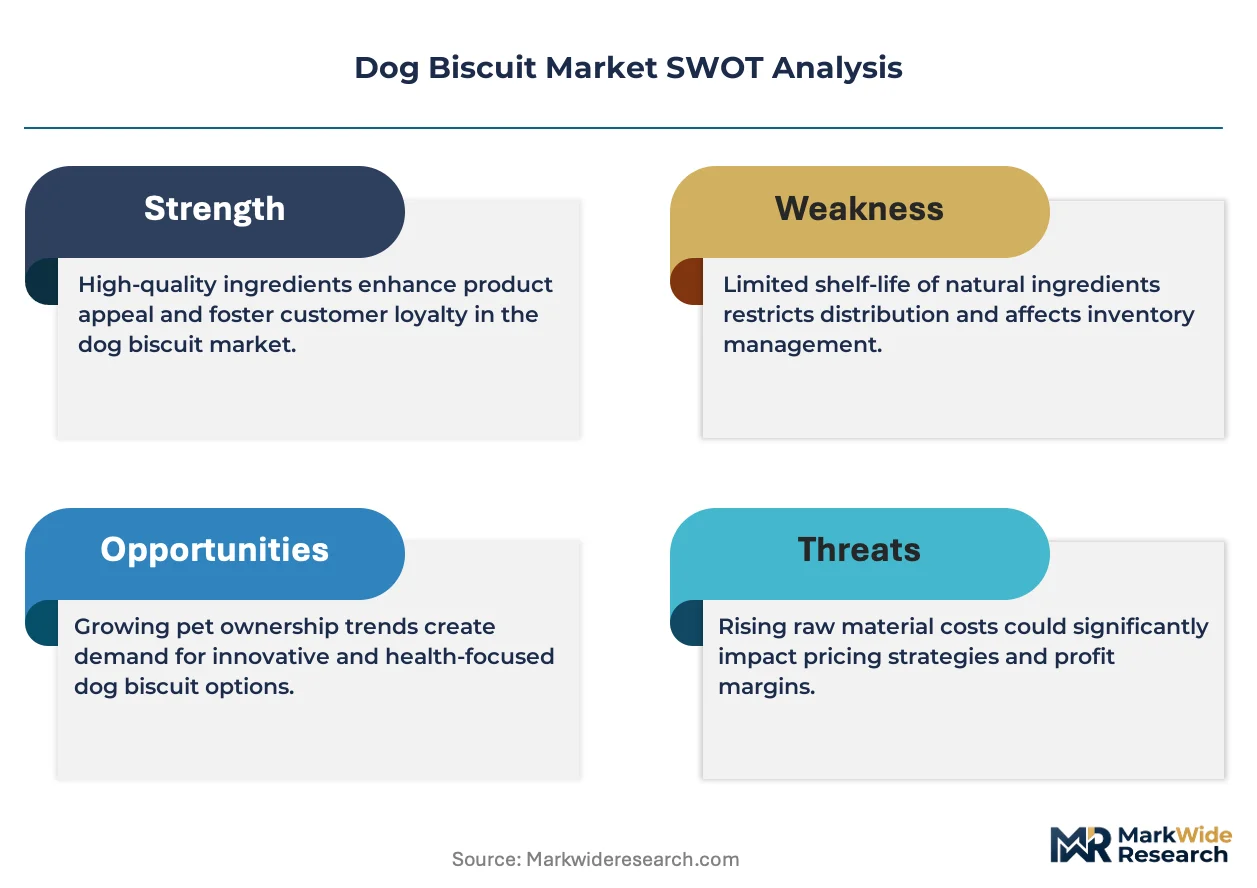
- AAFCO Nutrient Profiles:Standardized ingredient safety frameworks in the United States reduce formulation ambiguity for domestic producers, accelerating new product clearance timelines relative to import-dependent competitors.
- Urban millennial pet ownership:Dense metropolitan clusters in Shanghai, Berlin, and Dallas generate concentrated demand for training-format biscuits with portion-controlled packaging and functional dental claims.
- Refrigerated supply chain expansion:Cold-chain infrastructure investments by pet specialty retailers enable fresh-format biscuit segments that command shelf positioning unavailable to ambient-stable competitors.
Market Restraints
- Grain price volatility:Wheat and corn input costs fluctuate with commodity futures, compressing margin predictability for mid-tier producers without forward-contracting capabilities.
- Single-source protein concentration:Premium grain-free formulations depend on concentrated poultry meal supply from southeastern US rendering facilities, creating geographic vulnerability to regional disease outbreaks.
- FDA import inspection backlogs:Foreign manufacturers face extended detention timelines at US ports, elevating working capital requirements and eroding price competitiveness against domestic co-packers.
Strategic Opportunities
- Veterinary endorsement channels:Prescription-format biscuits distributed through clinic networks capture recurring purchase patterns with higher switching costs than retail impulse buys.
- India urban pet adoption:Emerging middle-class households in Mumbai and Bangalore represent underpenetrated demand for branded training treats as nuclear family structures displace traditional outdoor dog-keeping.
- E-commerce subscription models:Direct-to-consumer auto-replenishment platforms bypass pet specialty retail slotting fees while capturing lifetime value data for personalized formulation recommendations.
Industry Challenges
- Clean-label certification timelines:USDA Organic and Non-GMO Project verification processes extend 14-18 months, delaying premium positioning for reformulated SKUs against faster-moving competitors.
- Extrusion equipment retooling:Grain-free formulations require modified screw configurations and die geometries that demand capital expenditure beyond the reach of asset-light contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Biscuit Market |
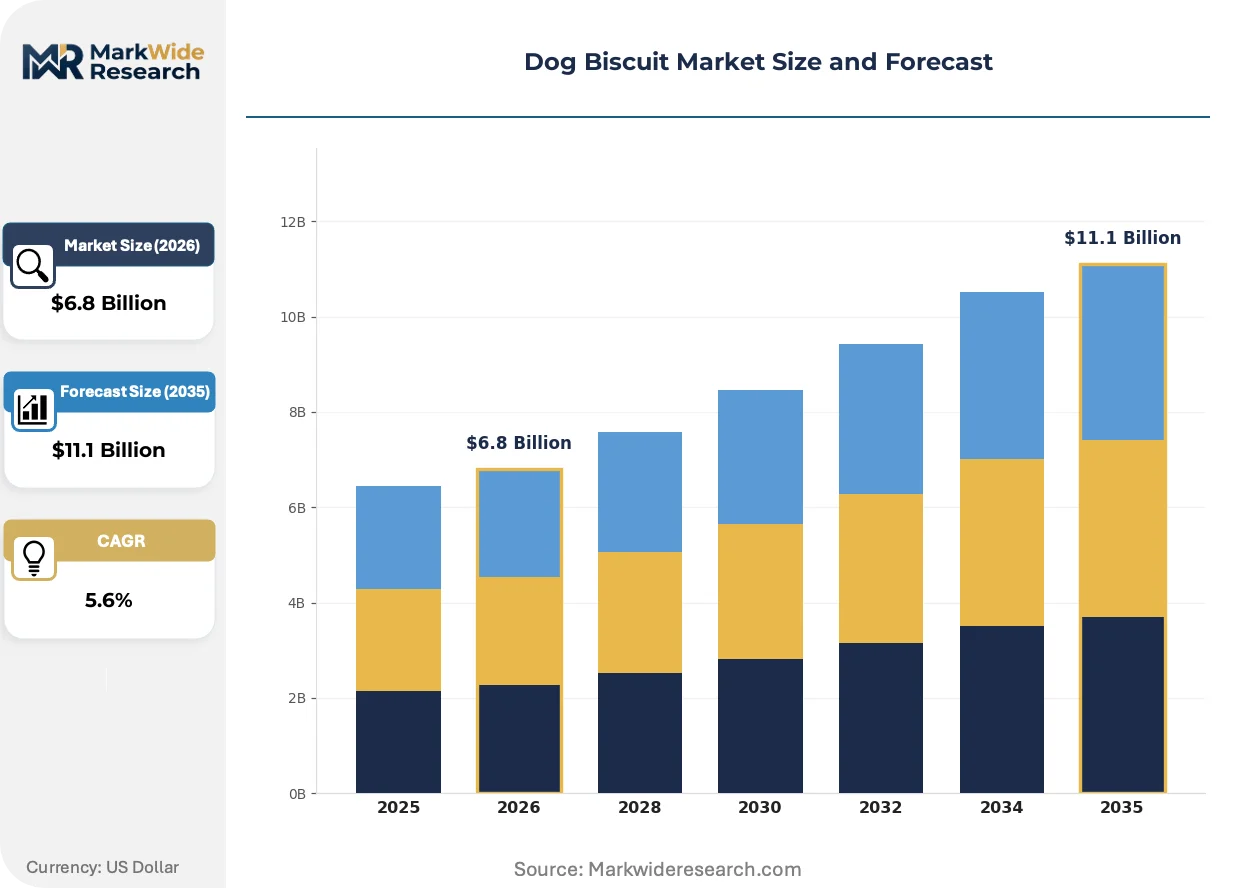
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.1 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Biscuits, Crunchy Biscuits, Grain-Free Biscuits, Organic Biscuits Ingredient Type: Meat-Based, Vegetable-Based, Fruit-Based, Synthetic Target Size: Small Breeds, Medium Breeds, Large Breeds, All Sizes Distribution Channel: Online Retail, Pet Stores, Supermarkets, Specialty Shops |
| Companies Covered | Colgate-Palmolive, General Mills, Mars Petcare, Hill's Pet Nutrition, The J.M. Smucker Co, Nestle SA, Royal Canin SAS, PureBites, Spectrum Brands Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Biscuit Market Evolving Landscape
Digital traceability systems and novel protein sourcing are restructuring how manufacturers validate ingredient provenance and differentiate formulation portfolios against commodity alternatives.
Blockchain-enabled supply chain verification is virtualizing quality assurance workflows for premium biscuit producers. Mars Petcare and Nestle SA have deployed distributed ledger pilots linking Australian lamb meal suppliers to US packaging facilities. This technology is virtualizing the audit burden that previously required physical site inspections, compressing compliance costs while expanding the geographic radius of qualified ingredient suppliers.
REACH chemical substance registration in the European Union is tightening contaminant thresholds for imported pet food ingredients. Manufacturers exporting to Germany and France must now document heavy metal and mycotoxin levels below previous detection limits. Small and mid-sized US co-packers without in-house analytical laboratories are outsourcing testing to third-party certifiers, adding 8-12% to per-batch compliance costs.
Subscription-based replenishment is displacing episodic retail purchasing among premium biscuit buyers. Chewy and Amazon Pet automate recurring deliveries of dental and training formats, capturing household-level consumption data that informs personalized product recommendations. This shift is most visible in coastal US metropolitan markets where delivery density supports same-day fulfillment economics unavailable in suburban or rural zip codes.
Dog Biscuit Market Segmentation
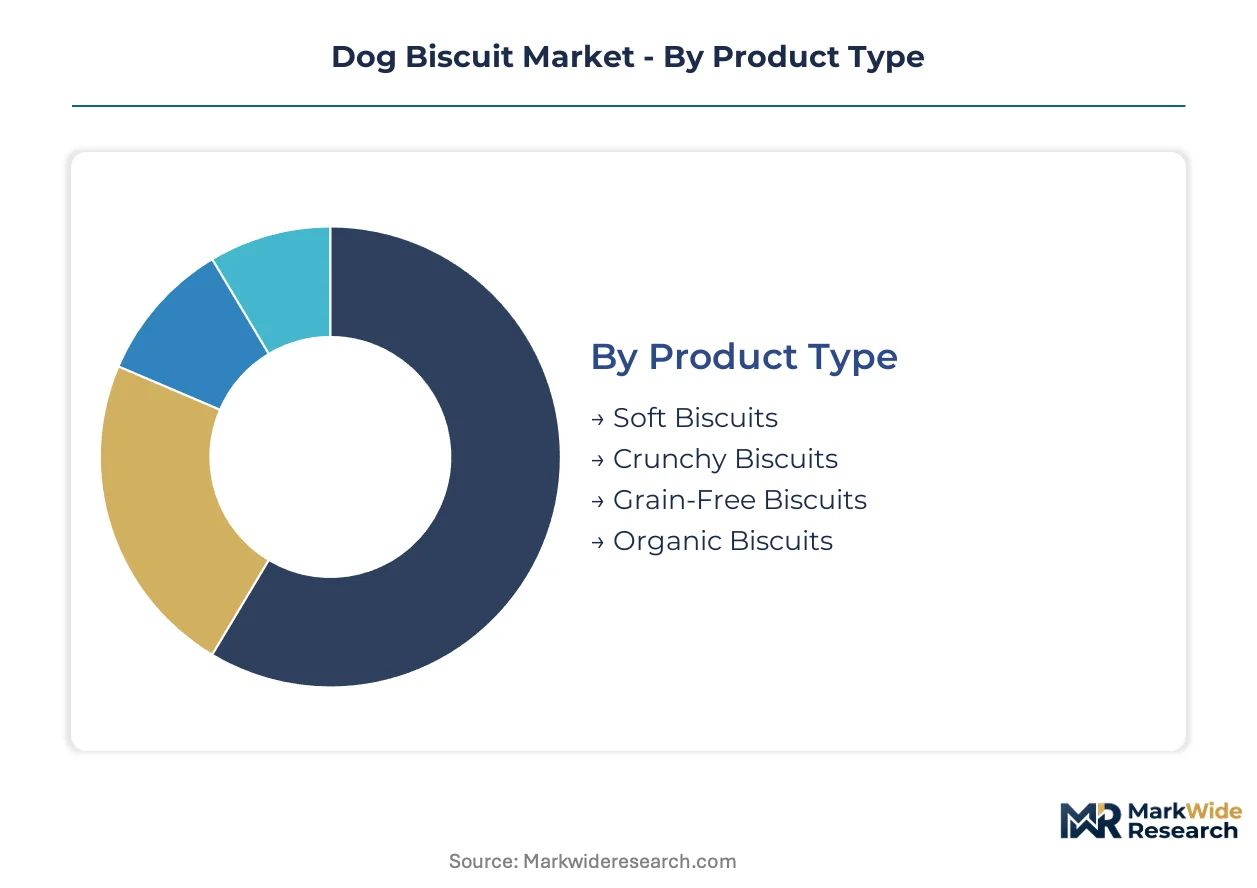
Dog biscuit segmentation reflects divergent owner priorities across functional needs, ingredient philosophy, and purchase context. Manufacturers configure production lines and procurement networks around these divides, as margin profiles and shelf-life requirements vary substantially by category.
Product Type:
Mature formats dominate volume throughput while emerging variants capture premium positioning through certification claims.
- Soft Biscuits:Higher moisture content (15-25%) requires modified atmospheric packaging and shorter distribution windows. Demand clusters in puppy training segments and senior dog dental-sensitive households across urban Japan and South Korea.
- Crunchy Biscuits:Extruded and dried below 10% moisture, these formulations deliver dental abrasion benefits and 18-month ambient stability. Mass-market penetration remains deepest in Germany and the United States where price-per-treat metrics dominate household purchase calculations.
- Grain-Free Biscuits:Potato and pea starch substitutes command ingredient cost premiums of 20-40% over wheat-based equivalents. AAFCO labeling scrutiny has intensified following FDA dilated cardiomyopathy investigations.
- Organic Biscuits:USDA Organic or EU Organic certification restricts synthetic additive use and mandates feed-grade ingredient traceability. Verification timelines of 14-18 months constrain new entrant speed-to-market.
Crunchy biscuits retain volume leadership; grain-free formulations hold the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates commodity protein meals from novel and synthetic alternatives with divergent supply security profiles.
- Meat-Based:Poultry meal, beef meal, and fish meal deliver complete amino acid profiles with high palatability acceptance. Rendering facility concentration in the southeastern United States creates geographic supply vulnerability to avian influenza outbreaks.
- Vegetable-Based:Pea protein, potato protein, and sweet potato formulations address vegetarian owner preferences and certain protein sensitivity cases. European demand concentrates in the Netherlands and Germany where plant-forward human diets extend to pet purchasing.
- Fruit-Based:Blueberry, apple, and pumpkin inclusions provide antioxidant marketing claims with lower protein density. Functional positioning targets senior dog cognitive health segments.
- Synthetic:Laboratory-cultured proteins and precision-fermented ingredients remain nascent, with regulatory approval pending at FDA and EFSA. Cost structures currently exclude mass-market viability.
Meat-based formulations dominate current revenue; synthetic alternatives are expanding most quickly as regulatory pathways clarify.
Target Size:
Application-specific caloric and dimensional requirements drive packaging and formulation differentiation across breed categories.
- Small Breeds:Bite-sized formats (under 5 grams) with elevated caloric density address metabolic needs of dogs under 10 kilograms. Urban apartment dwellers in Shanghai and New York City generate concentrated demand for portion-controlled training assortments.
- Medium Breeds:Standard-format biscuits balance durability for dental benefits against swallow-ability safety concerns. Volume concentration reflects the demographic breadth of retriever and shepherd ownership patterns.
- Large Breeds:Oversized formats (15+ grams) with reinforced structural integrity withstand aggressive chewing mechanics. Hip and joint functional additive incorporation is most prevalent in this segment.
- All Sizes:Breakable scored formats attempt cross-segment coverage with inherent compromise on optimal dental abrasion geometry for any specific weight class.
Medium breed targeting captures the widest household penetration; small breed specialization gains share fastest through urban density effects.
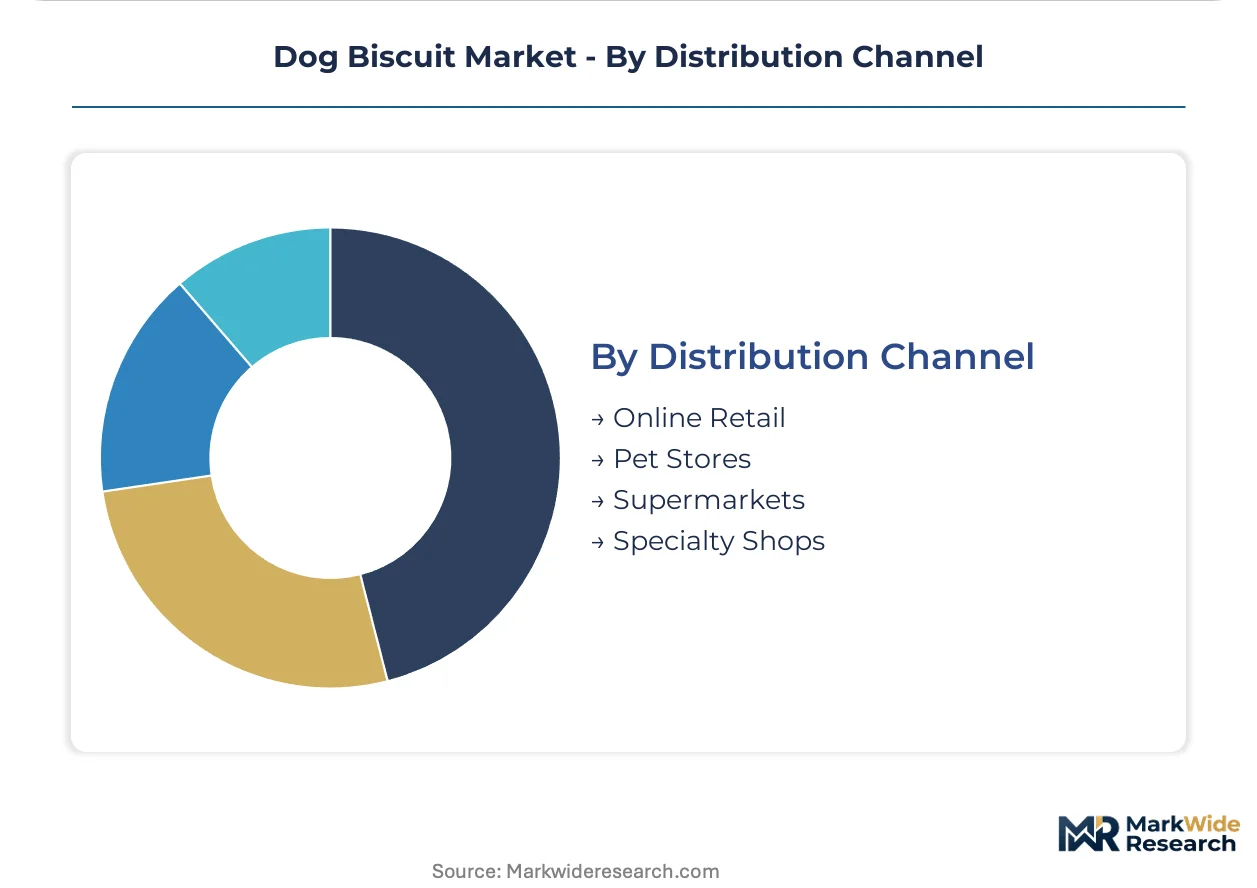
Distribution Channel:
Customer type and purchase occasion separate impulse retail from planned replenishment and professional endorsement contexts.
- Online Retail:Chewy, Amazon Pet, and direct-to-consumer platforms capture subscription auto-replenishment with household-level consumption data. Same-day fulfillment economics concentrate in coastal US metropolitan markets and Chinese tier-1 cities.
- Pet Stores:Petco, PetSmart, and independent specialty retailers sustain higher basket values through cross-selling and staff recommendation influence. Premium assortment breadth exceeds mass retail capabilities.
- Supermarkets:Walmart, Kroger, and Tesco leverage traffic density for impulse treat purchases alongside routine grocery shopping. Price-per-ounce sensitivity peaks in this channel.
- Specialty Shops:Veterinary clinics and groomer retail capture professional endorsement credibility with prescription-format and dental therapeutic positioning.
Pet stores retain margin leadership; online retail demonstrates the steepest expansion trajectory through subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial and Gen Z pet owners in Shanghai, Dallas, and Berlin generate concentrated demand for premium training biscuits with functional dental claims and portion-controlled packaging formats.
United States
Specialty retail chains in Dallas and Los Angeles metro areas sustain the highest basket values through cross-selling premium treat assortments. FDA Center for Veterinary Medicine oversight and state feed control official inspections elevate compliance costs for imported products. Mars Petcare leverages global procurement networks from its Arkansas manufacturing cluster to sustain ingredient cost advantages.
China
Shanghai and Beijing tier-1 cities concentrate demand for imported grain-free formulations as nuclear family structures displace traditional outdoor dog-keeping. SAMR and GB standards govern pet food safety labeling alongside provincial-level quality inspections. Zhengzhou and Shandong Peninsula manufacturing clusters supply domestic brands competing on price-per-treat metrics.
Germany
Berlin and Munich urban households drive disproportionate demand for organic-certified biscuits with EU Organic traceability requirements. REACH chemical substance registration tightens contaminant thresholds for imported ingredients. Bavaria-based co-packers serve private-label programs across European pet specialty retail.
India
Mumbai and Bangalore emerging middle-class households represent underpenetrated demand for branded training treats. FSSAI feed-grade regulations and BIS standards are tightening ingredient disclosure requirements. Maharashtra industrial corridors host contract manufacturers supplying domestic biscuit brands.
Japan
Tokyo and Osaka metropolitan areas generate concentrated demand for soft-format biscuits targeting senior dog dental-sensitive segments. METI and JIS standards govern manufacturing facility certifications. Kanto region distribution centers enable same-day fulfillment economics for e-commerce subscription models.
Dog Biscuit Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into three structural tiers: multinational consumer goods conglomerates with veterinary endorsement networks, mid-tier co-packers with refrigerated supply chain capabilities, and niche specialists with clean-label certification positioning. Dominant competitive moves include portfolio diversification into fresh-format segments and strategic partnerships with e-commerce subscription platforms.
Within the multinational tier, Mars Petcare, Nestle SA, and General Mills exemplify divergent strategic archetypes. Mars Petcare represents global procurement network optimization across multiple geographies. Nestle SA occupies a position anchored on veterinary endorsement channels that command premium shelf positioning. General Mills exemplifies refrigerated supply chain integration for fresh-format biscuit differentiation. These three players collectively illustrate how scale, channel control, and format specialization define competitive positioning in premium treat segments.
| Leading Market Players |
|---|
| Colgate-Palmolive |
| General Mills |
| Mars Petcare |
| Hill's Pet Nutrition |
| The J.M. Smucker Co |
| Nestle SA |
| Royal Canin SAS |
| PureBites |
| Spectrum Brands Holdings |
| Others |
Value Network & Pricing Analysis
Shandong Peninsula manufacturing clusters anchor global biscuit production capacity, with Zhengzhou extrusion facilities feeding domestic Chinese brands and export-oriented co-packers. This geographic concentration grants incumbent producers leverage over ingredient procurement terms, while mid-tier entrants face working capital compression from extended payment cycles and commodity hedging requirements.
Pricing Analysis
Cost-plus contracts with Chicago Board of Trade wheat futures indexation dominate procurement agreements for mid-tier producers lacking Mars Petcare's global sourcing scale. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic certified SKUs from conventional grain-based formulations and private-label economy packs. Pricing pressure stems from corn and poultry meal input volatility, with grain-free formulations absorbing 20-40% ingredient cost premiums. Supermarket channel buyers exhibit acute price-per-ounce sensitivity, while veterinary clinic networks sustain premium tolerance through endorsement-mediated switching costs.
Supply Chain Analysis
REACH chemical substance registration and FDA import inspection protocols restrict ingredient flows from non-compliant rendering facilities and unverified grain suppliers. Raw material sourcing draws from southeastern US poultry meal rendering clusters, Australian lamb meal suppliers, and Shandong wheat processing mills. Single-source protein concentration in Georgia and Alabama rendering infrastructure creates geographic vulnerability to avian influenza containment measures. Distribution runs through pet specialty retail cold-chain networks for fresh-format segments, with ambient-stable crunchy biscuits flowing through mass retail and e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dog biscuit market operates as a regulatory-entrenchment story, where FDA Center for Veterinary Medicine oversight and AAFCO nutrient profile compliance create structural barriers that domestic incumbents exploit against import-dependent competitors.
For Market Incumbents: Entrench competitive position through backward integration into rendering facility partnerships that secure poultry meal supply amid southeastern US geographic concentration risk. Expand refrigerated supply chain capacity in Dallas and Los Angeles metro clusters to capture fresh-format premium positioning unavailable to asset-light contract manufacturers. Prioritize veterinary endorsement channel control to maintain prescription-format SKU pricing power against retail impulse competitors. For New Entrants and Emerging Players: Mumbai and Bangalore urban pet adoption curves represent the most penetrable white-space geography for branded training treat launches targeting nuclear family households displacing traditional outdoor dog-keeping. Grain-free biscuit segments with modified extrusion equipment requirements remain vulnerable to mid-tier disruption through co-packer partnerships that bypass capital-intensive screw configuration retooling. E-commerce subscription auto-replenishment platforms offer the optimal go-to-market angle for direct household consumption data capture and personalized formulation recommendations. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because refrigerated supply chain capabilities and veterinary channel gatekeeping relationships concentrate in a narrow tier of multinational consumer goods conglomerates. Acquisition targets should emphasize mid-tier co-packers with clean-label certification positioning and established SAMR or BIS compliance frameworks for Asia-Pacific expansion. The signal to watch is FDA dilated cardiomyopathy investigation outcomes, which could force grain-free formulation recalls and redistribute market share toward conventional wheat-based portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Endorsement Channel Expansion | Clinic network partnerships with Hill's Pet Nutrition and Royal Canin SAS lock in recurring purchase patterns with professional credibility. |
| Refrigerated Supply Chain Integration | Cold-chain infrastructure investments by Petco and PetSmart enable fresh-format shelf positioning unavailable to ambient-stable competitors. |
| Blockchain Traceability Deployment | Distributed ledger pilots linking Australian lamb meal suppliers to Arkansas packaging facilities compress compliance audit burdens. |
| E-commerce Subscription Platform Partnership | Chewy and Amazon Pet auto-replenishment models capture household-level consumption data for personalized product recommendations. |
| Clean-Label Certification Investment | USDA Organic and Non-GMO Project verification timelines of 14-18 months create first-mover premium positioning against reformulation laggards. |
Research Methodology
Cross-validation between primary interviews with pet food brand managers, veterinary clinic procurement officers, and pet specialty retail category buyers anchors the qualitative findings against secondary validation from FDA Center for Veterinary Medicine filings, AAFCO official publication nutrient profiles, and Nielsen retail audit data. Bottom-up demand modeling triangulates household pet ownership surveys with SKU-level velocity data, while top-down market sizing reconciles manufacturer production disclosures with customs trade records.
Calibration against historical CAGRs and elasticity-adjusted demand curves shapes the analytical framework across the projection horizon. Segmentation dimensions include product type (soft, crunchy, grain-free, organic), ingredient philosophy (meat-based, vegetable-based, fruit-based), target breed size, and distribution channel concentration. Forecast inputs incorporate urban millennial pet ownership density metrics and refrigerated supply chain infrastructure buildout trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational conglomerates into veterinary prescription formats or synthetic protein platforms would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Australia Pet Food Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
Cat Massage Comb Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Pet Stairs Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Cat Food Toppers Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Cat Harness Market