
 Pet Collar Market | 2026-2036
Pet Collar Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Collar Market Analytics
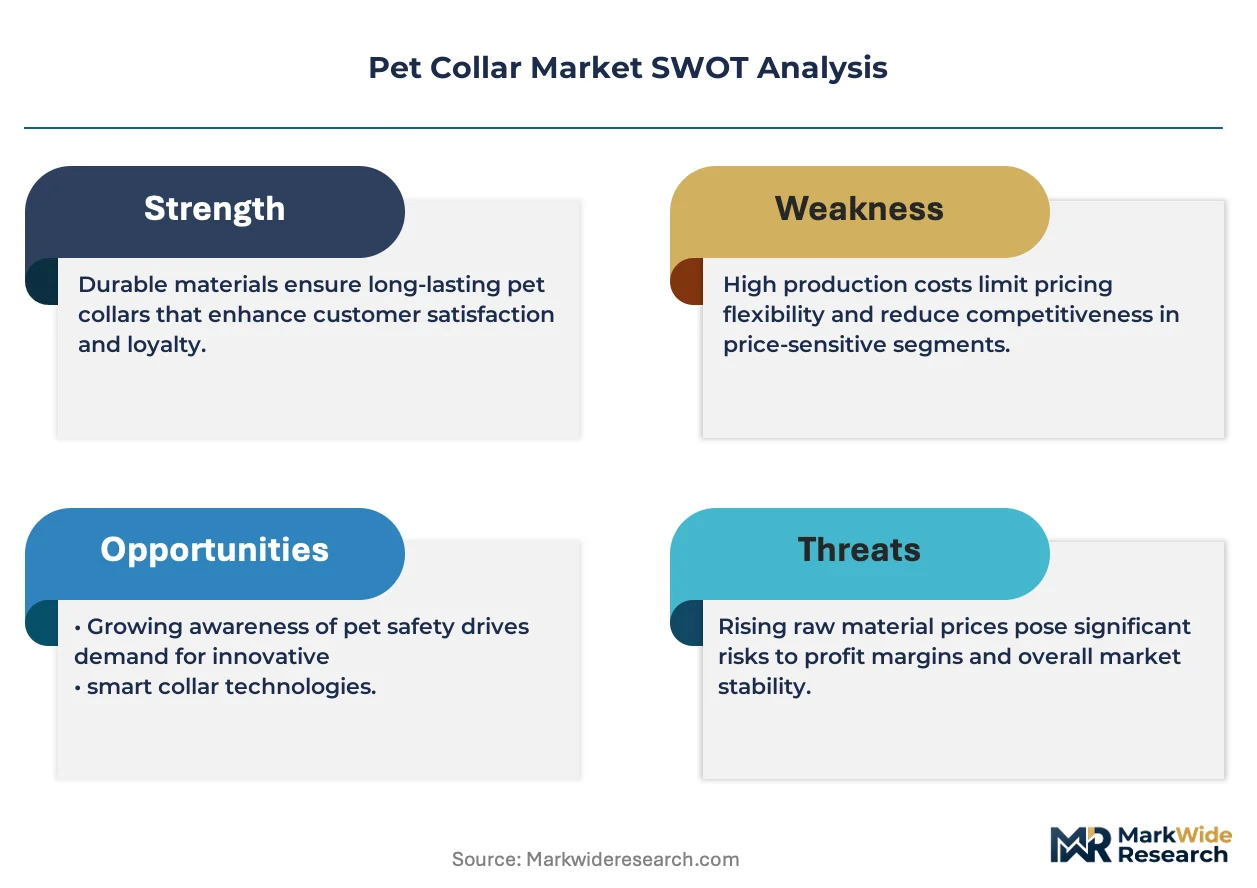
The gap between premium smart-enabled collars and commodity nylon straps is restructuring how manufacturers allocate capital and inventory. Coastal Pet Products anchors its position through deep distribution into mass retail and independent pet stores across the United States. Fi differentiates by embedding proprietary GPS and activity-tracking firmware into hardware that commands recurring subscription revenue. Lupine Pet sustains brand equity through lifetime replacement guarantees and domestic manufacturing of woven nylon designs.
A pet collar is a wearable restraint and identification device, typically constructed from nylon webbing, full-grain leather, or coated steel chain, designed to secure a leash attachment point and display license or owner-contact tags while distributing pressure across the animal's neck. Standard collars remain the volume foundation across mass-market channels, though GPS tracker collars are capturing disproportionate growth as cellular module costs decline and pet owners prioritize location security. Leather and reflective-featured SKUs concentrate margin pools in specialty retail, where material authenticity and nighttime visibility justify price premiums over basic PVC alternatives.
The United States Food and Drug Administration oversees animal health device claims when collars incorporate biometric sensors, while the Federal Communications Commission regulates radio-frequency emissions from GPS and Bluetooth transmitters. The Consumer Product Safety Commission monitors choking and strangulation hazards, particularly for breakaway mechanisms intended for cats and small breeds. Stakeholders must monitor how impending battery-safety standards and right-to-repair legislation reshape hardware design cycles and aftermarket service obligations.
Market Dynamics
Smart collar firmware integration with cellular GPS modules is compressing replacement cycles and shifting manufacturer revenue models toward recurring subscription streams, fundamentally altering how brands allocate R&D capital between hardware and software stacks.
Growth Catalysts
- Pet Humanization Spending:Millennial and Gen Z households now direct discretionary income toward premium pet accessories, expanding addressable spend per animal across specialty retail channels.
- REACH Substance Restrictions:European chemical safety mandates on phthalates and heavy metals in pet products are accelerating material substitution toward bio-based polymers and food-grade silicones.
- Veterinary Endorsement Channels:Clinical recommendation networks in the United States are converting health-monitoring collar adoption among aging pet populations with chronic conditions.
Market Restraints
- Lithium-Ion Cell Volatility:Battery raw material price swings and thermal runaway risks constrain smart collar unit economics and shipping classification costs.
- Asian Module Concentration:GPS and cellular chipset fabrication concentrates in Taiwan and mainland China, exposing brands to single-source supply disruptions.
- Biometric Sensor Accuracy Limits:Optical heart-rate monitoring through fur and varying coat thickness degrades signal reliability in large-breed applications.
Strategic Opportunities
- Indian Urban Pet Adoption:Tier-1 cities like Mumbai and Bangalore exhibit rising dog ownership rates with minimal smart collar penetration, creating first-mover whitespace for cellular-enabled entry products.
- EU AI Act Compliance:Predictive health algorithms embedded in collar firmware will require conformity assessments, favoring vendors with early algorithmic transparency documentation.
- Telemedicine Platform Integration:Direct data feeds from collar sensors to veterinary telehealth portals enable new B2B2C revenue splits with pet insurance underwriters.
Industry Challenges
- Firmware Engineering Talent Scarcity:Embedded systems developers with low-power Bluetooth and LTE-M expertise command premium compensation, stretching mid-tier manufacturer payroll structures.
- Multi-Regulatory Certification Timelines:Simultaneous FCC radio approval, FDA health-claim review, and CPSC mechanical safety testing extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Collar Market |
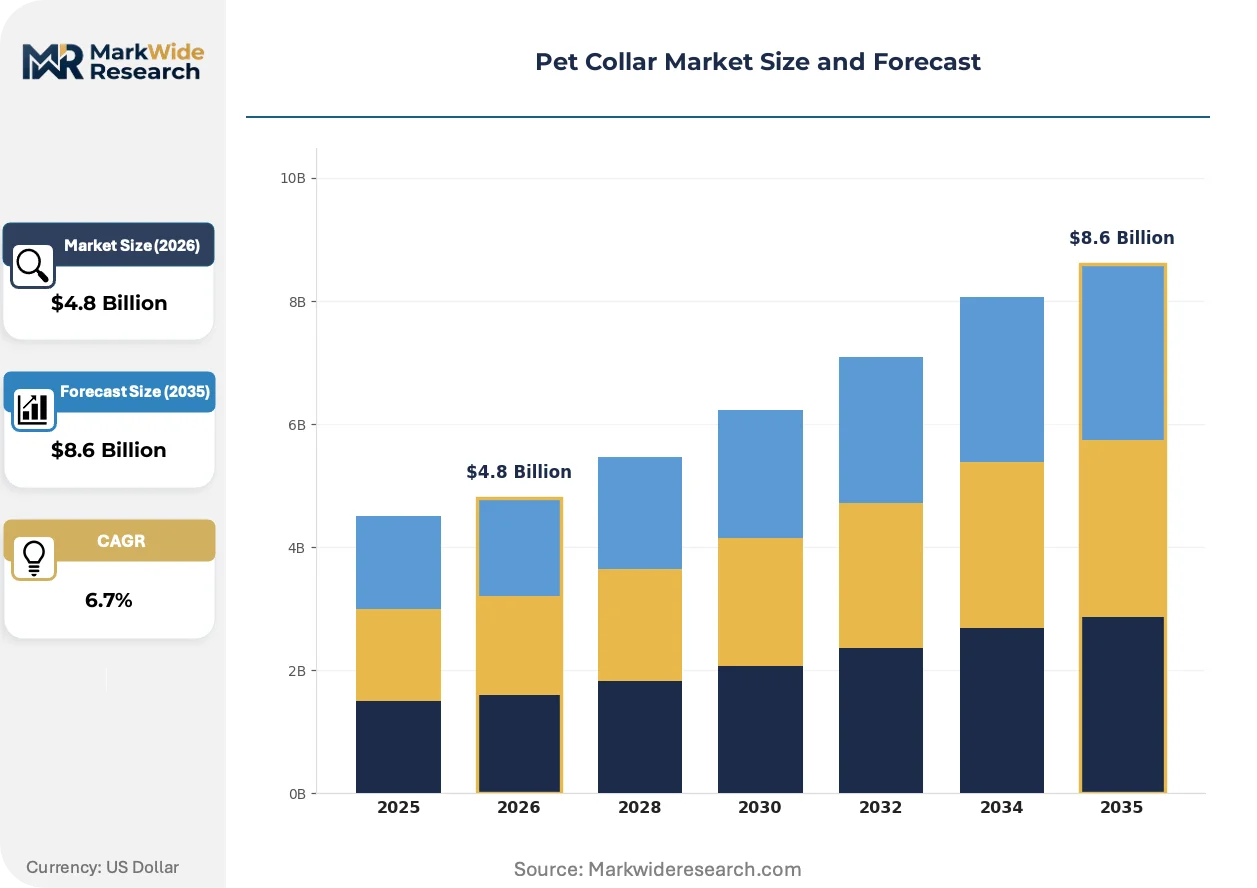
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Collar, Martingale Collar, Training Collar, GPS Tracker Collar Material: Nylon, Leather, Metal, PVC Size: Small, Medium, Large, Extra Large Feature: Reflective, Waterproof, Decorative, Adjustable |
| Companies Covered | Red Dingo, TIZE Technology Co., Ltd, Coastal Pet Products, Fi, PETKIT, Lupine Pet, Rogz, Kong, Ruffwear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Collar Market Evolving Landscape
Hardware-software convergence in wearable pet technology is collapsing traditional category boundaries between identification, restraint, and medical monitoring functions, forcing manufacturers to choose specialization depth versus platform breadth.
Ultra-wideband (UWB) positioning chipsets are consolidating indoor location accuracy to within 10 centimeters, enabling room-level pet tracking in multi-story dwellings. Premium smart collar brands in the United States and Germany are embedding UWB alongside GPS for seamless handoff between outdoor and indoor environments. This dual-radio architecture is consolidating technical differentiation around spatial computing rather than basic geofencing alerts.
The EU Battery Regulation mandates replaceable power cells and recycled content disclosures for portable electronics, directly impacting smart collar design cycles. Manufacturers must now engineer tool-free battery compartments and establish reverse-logistics partnerships for end-of-life collection. Veterinary-grade collar SKUs face the steepest compliance burden given their higher cell capacities and clinical use claims.
Subscription bundling with pet insurance policies is displacing standalone hardware purchases in North American markets. Lemonade and Trupanion policyholders receive discounted or subsidized Fi and Whistle devices, embedding collar costs within monthly premium flows. This channel integration concentrates volume through insurer procurement departments rather than traditional retail, compressing brand-direct margins while securing guaranteed install bases.
Pet Collar Market Segmentation
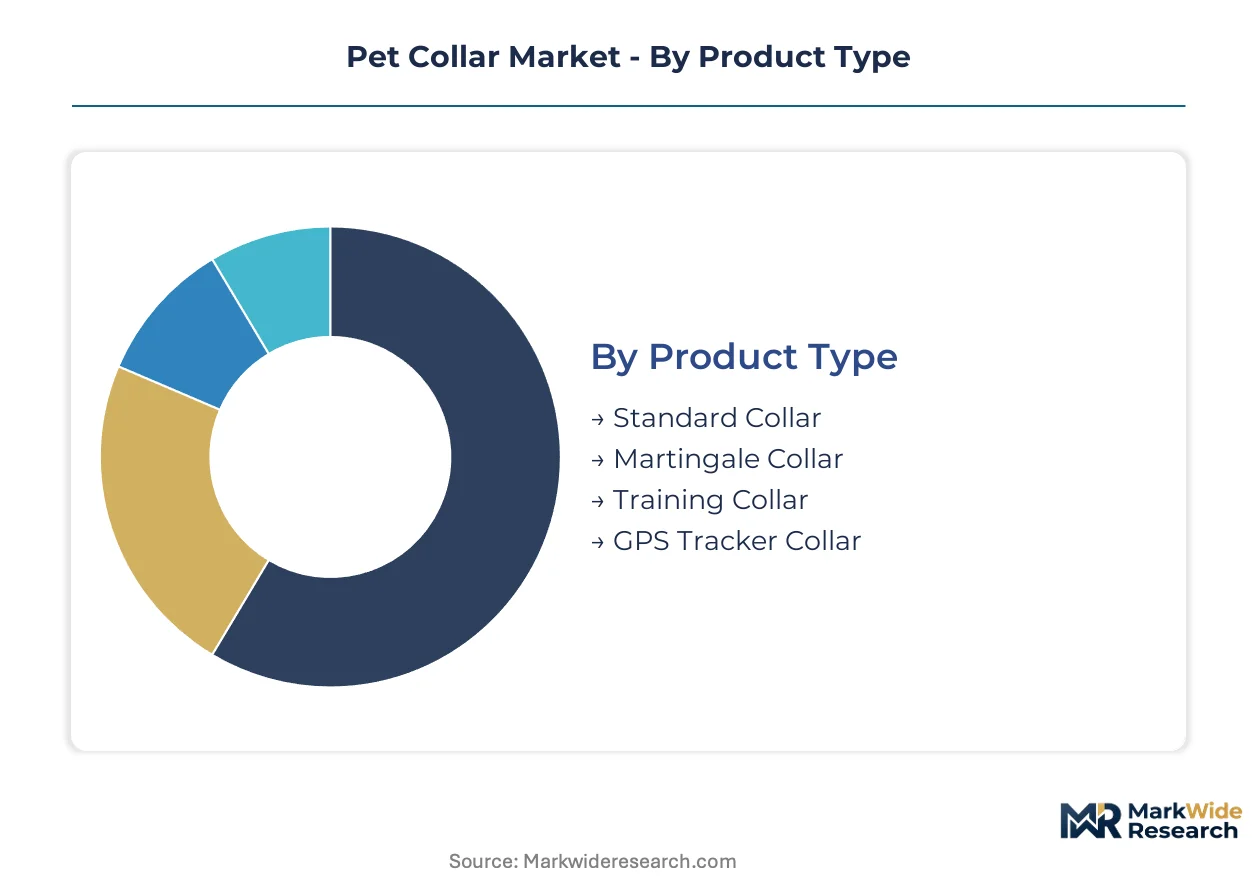
Pet collar segmentation reveals divergent margin structures across hardware complexity tiers. Manufacturers optimize portfolio mix between high-volume commodity SKUs and subscription-linked smart devices with divergent working capital requirements.
Product Type:
Volume concentrates in basic restraint designs while premium economics shift toward cellular-enabled tracking hardware with recurring revenue attachment.
- Standard Collar:Nylon webbing or leather construction with buckle closure serves mass-market retail and veterinary bulk procurement. Demand clusters in United States big-box channels where replacement frequency drives inventory velocity.
- GPS Tracker Collar:Embedded LTE-M modules with geofencing firmware command hardware-plus-subscription pricing models. United States and German markets show strongest penetration as cellular coverage density supports reliable location services.
- Martingale Collar:Limited-slip nylon design prevents escape in sighthound breeds without choking risk. Concentrated in specialty breed clubs and rescue organization procurement.
- Training Collar:Electronic stimulation or vibration modules for behavioral modification. Faces regulatory scrutiny under FCC Part 15 emissions rules and state-level animal welfare restrictions.
Mature deployment sits with Standard Collar. Newer deployment is concentrated in GPS Tracker Collar.
Material:
Cost tier and durability expectations split procurement patterns across retail channels and end-use applications.
- Nylon:Woven polyamide webbing dominates unit volume through color customization and washability. Coastal Pet Products and mass-market private labels source from domestic cut-and-sew operations to reduce tariff exposure.
- Leather:Full-grain vegetable-tanned hides command 3-4x nylon pricing in specialty pet boutiques. Italian and Argentinian tanneries supply premium brands targeting humanization-driven discretionary spend.
- Metal:Coated steel chain and prong designs concentrate in working dog applications—police K9 units, livestock protection breeds—where bite resistance outweighs comfort priorities.
- PVC:Coated webbing offers waterproof performance for hunting and water-sport companion dogs. Lower material cost supports entry-tier pricing in emerging markets.
Volume leadership belongs to Nylon. Margin expansion concentrates in Leather.
Size:
Anatomical variation across breeds creates SKU proliferation challenges with inventory carrying cost implications.
- Small:Under 12-inch neck circumference for toy breeds and cats. Breakaway safety mechanisms required per CPSC guidelines dominate feature specifications.
- Medium:12-18 inch range captures highest absolute unit volume across retriever and shepherd breeds. Adjustable slide designs reduce fit-related returns.
- Large:18-24 inch necks in mastiff and large working breeds stress hardware durability. Metal D-rings and reinforced stitching justify material cost premiums.
- Extra Large:24+ inch specialty sizing for giant breeds and livestock guardian dogs. Limited distribution through veterinary and direct-to-breeder channels.
Medium sizing carries broadest distribution. Extra Large remains specialty-channel dependent.
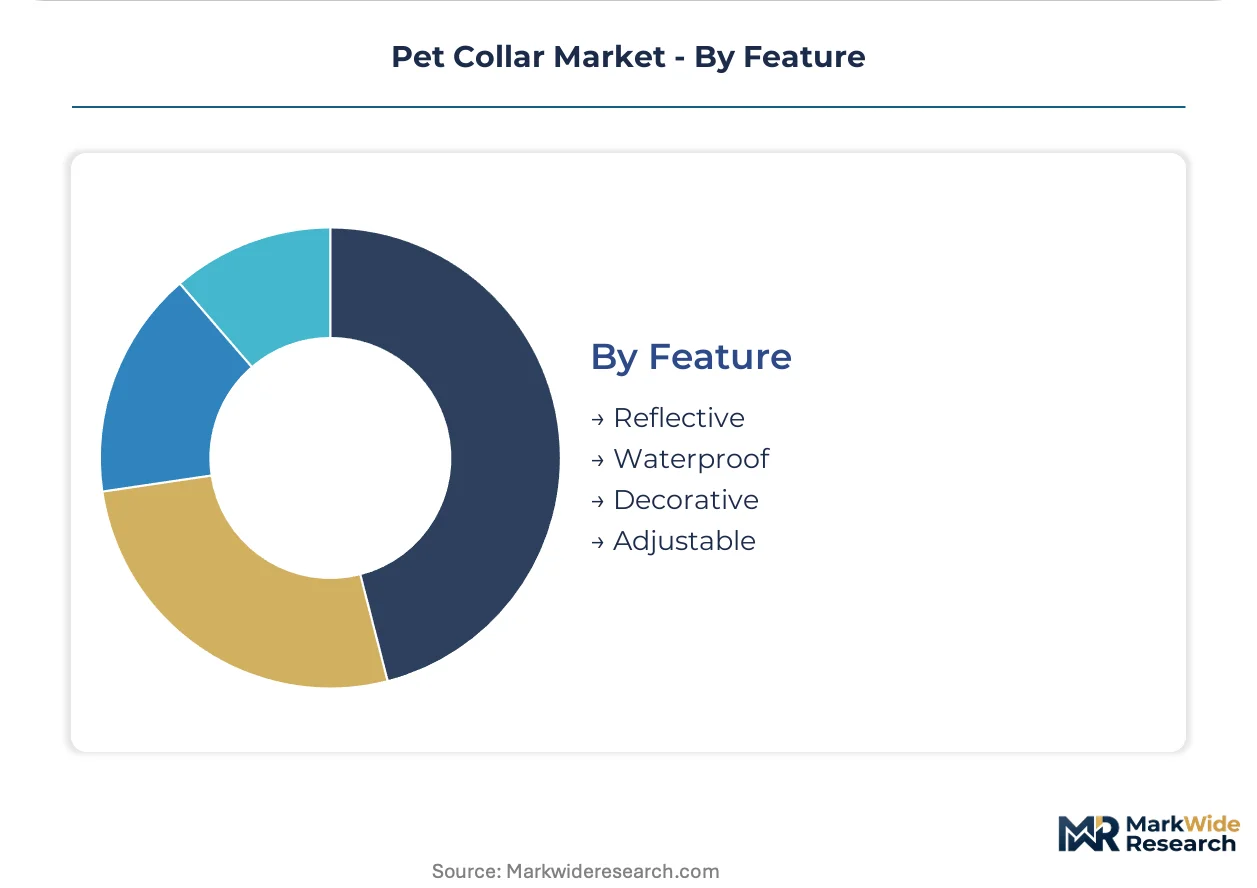
Feature:
Functional differentiation drives price tier separation and seasonal demand patterns.
- Reflective:Retroreflective thread integration or sewn-on tape addresses nighttime visibility liability concerns. Urban dog ownership in United States and United Kingdom markets shows strongest attachment rates.
- Waterproof:Coated fabrics and sealed electronics enable marine and all-weather deployment. Hunting dog segments in Scandinavia and Pacific Northwest United States prioritize this specification.
- Decorative:Embroidered patterns, crystal embellishments, and designer collaborations target gift purchase occasions and social media visibility. Margin structures resemble fashion accessories rather than functional pet equipment.
- Adjustable:Slide buckle or martingale mechanisms accommodate growth phases and weight fluctuation. Standard inclusion in puppy starter kits reduces customer acquisition friction.
Adjustable feature penetration nears saturation. Reflective specification shows steepest expansion trajectory in urban safety-conscious segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European smart collar engineering, where Bosch Sensortec and Continental AG supply MEMS accelerometers and LTE-M modules to premium wearable brands. The city's automotive electronics heritage translates directly into pet tech supply chains.
United States
Millennial pet ownership in Austin, Denver, and Portland drives premium collar spend toward GPS-enabled SKUs. The FDA regulates biometric health claims under animal device provisions, while the FCC manages radio-frequency emissions from cellular trackers. San Francisco Bay Area startups concentrate firmware talent for subscription-based location services.
Germany
REACH substance restrictions on phthalates accelerate bio-based polymer adoption across Bavarian manufacturing clusters. Munich-based distributors command veterinary endorsement channels for health-monitoring collars. The EU AI Act conformity requirements favor early algorithmic documentation from Stuttgart-area engineering houses.
China
Shenzhen's electronics ecosystem dominates GPS and cellular module fabrication for global smart collar brands. MIIT radio-type approval timelines extend product launch windows for foreign vendors. Yangtze River Delta cut-and-sew operations supply woven nylon webbing at scale for mass-market private labels.
United Kingdom
London's urban dog density prioritizes reflective-featured collars for nighttime visibility compliance. The Office for Product Safety and Standards monitors breakaway mechanism standards for feline applications. Midlands-based leather tanneries serve boutique pet accessory brands targeting humanization-driven discretionary spend.
India
Mumbai and Bangalore exhibit rising companion animal adoption with minimal smart collar penetration. BIS certification requirements for electronic pet devices create entry barriers for unbranded imports. Delhi-NCR veterinary chains represent conversion opportunities for health-monitoring hardware.
Pet Collar Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. Coastal Pet Products anchors mass-market distribution through domestic manufacturing and deep retail relationships. Fi exemplifies subscription-linked hardware economics. Lupine Pet sustains brand equity through lifetime guarantees. Consolidation pressures concentrate among mid-tier nylon specialists facing raw material volatility. Strategic moves emphasize veterinary channel partnerships and telemedicine platform integration.
Among Asia-Pacific module suppliers, TIZE Technology Co., Ltd. and PETKIT occupy positions within the electronics fabrication tier. Red Dingo and Rogz represent design-centric specialists competing on material authenticity and breed-specific ergonomics. These players exemplify the geographic split between hardware engineering concentration and brand-facing product development.
| Leading Market Players |
|---|
| Red Dingo |
| TIZE Technology Co., Ltd |
| Coastal Pet Products |
| Fi |
| PETKIT |
| Lupine Pet |
| Rogz |
| Kong |
| Ruffwear |
| Others |
Value Network & Pricing Analysis
Captive module sourcing from Shenzhen electronics clusters anchors both the cost position and subscription pricing power for cellular-enabled collar brands. This integration choice separates hardware-plus-recurring revenue models from commodity nylon competitors tethered to volatile petrochemical feedstocks and tariff-exposed Asian cut-and-sew operations.
Pricing Analysis
Subscription-linked uptime guarantees anchor value-based pricing for GPS tracker collars, with Fi and Whistle commanding monthly fees tied to location service reliability rather than hardware depreciation alone. Three-tier pricing structure across premium smart-enabled, standard leather-nylon, and economy PVC levels reflects certification grade divergence—FDA health-claim review for biometric sensors versus CPSC mechanical safety for basic restraint. Cost compression in economy nylon runs through Yangtze River Delta material oversupply and mass-retail procurement consolidation. Veterinary endorsement channels show least price sensitivity due to clinical workflow integration, while mass-market big-box buyers drive hardest unit-cost negotiations.
Supply Chain Analysis
Dual-sourcing requirements from Tier 1 smart collar brands mandate simultaneous qualification of MediaTek and Qualcomm cellular module variants to mitigate single-source vulnerability. GPS and LTE-M chipset fabrication concentrates in Taiwan, mainland China, and South Korea, with woven nylon webbing drawing from Yangtze River Delta and Bangladesh cut-and-sew clusters. Lithium-ion cell supply rests on South Korean and Chinese cathode material flows exposed to commodity price volatility. Distribution runs through pet specialty retail, veterinary procurement departments, and insurer-embedded subscription channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from firmware engineering talent scarcity and multi-regulatory certification timelines will force mid-tier nylon specialists toward exit or acquisition over the projection horizon.
For Market Incumbents: Anticipate subscription platform competition from telemedicine-integrated entrants by deepening veterinary channel control and accelerating EU AI Act algorithmic documentation ahead of conformity assessment deadlines. Prioritize backward integration into domestic cut-and-sew operations to reduce tariff exposure on nylon webbing imports from China. Defensive patent positioning around UWB indoor positioning firmware represents the critical lever against modular hardware commoditization. For New Entrants and Emerging Players: Enter via Mumbai and Bangalore veterinary chain partnerships where cellular-enabled health monitoring shows minimal penetration against rising companion animal adoption. Target first-mover positioning in BIS-certified entry-tier smart collars before established brands localize India-specific SKUs. Go-to-market execution should embed insurer policy bundling from launch rather than retrofitting subscription economics post-hardware deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to pet insurance underwriters and telemedicine platforms seeking captive device install bases. Long-term viability favors brands with recurring revenue attachment above hardware depreciation cycles and algorithmic health-claim substantiation for FDA review. Watch for FCC Part 15 enforcement actions against uncertified training collar imports as inflection signal for regulatory barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Clinical endorsement from Banfield and VCA networks converts aging pet owner adoption for biometric monitoring SKUs. |
| Telemedicine Platform Integration | Direct sensor-to-portal data feeds enable Lemonade and Trupanion policyholder acquisition cost reduction. |
| EU AI Act Compliance Investment | Early algorithmic transparency documentation from Stuttgart engineering houses accelerates premium SKU market access. |
| Domestic Manufacturing Footprint | In-house cut-and-sew operations in North Carolina and Ohio reduce tariff exposure on Chinese nylon imports. |
| Subscription Bundling Repositioning | Hardware cost absorption into monthly premium flows displaces retail margin capture with guaranteed install bases. |
Research Methodology
Independent corroboration across pet industry executives, veterinary procurement managers, cellular module suppliers, and specialty retail buyers underwrites the qualitative findings. Primary fieldwork engaged firmware engineering leads at Stuttgart wearable tech clusters, Shenzhen electronics manufacturing services, and North Carolina domestic cut-and-sew operations. Secondary validation drew from FCC equipment authorization databases, FDA animal health device listings, CPSC mechanical safety recalls, and pet insurance policy filings. Bottom-up SKU-level demand modeling triangulated against top-down demographic pet ownership projections.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, material tier, feature specification, and regional regulatory cluster. CAGRs derive from installed base penetration curves for cellular-enabled collars versus replacement frequency assumptions for commodity restraint designs. Modeled inputs include REACH substance restriction compliance costs, EU Battery Regulation reverse-logistics requirements, and veterinary telemedicine platform partnership velocity.
Revisions become necessary when lithium-ion cell supply disruptions, FCC enforcement action escalations, or insurer policy bundling adoption rates materially diverge from baseline assumptions. Deviation in BIS certification timelines for Indian market entry would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Dog Life Jacket Market
Pet Care Products
Smart Pet Camera Market
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Dog Seat Covers Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
Saudi Arabia Pet Boarding Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Dog Bowl Market
Pet Care Products
Dog Brush Market
Pet Care Products
Dog Shampoo Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Pet Car Seat Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Malaysia Pet Food Market