
 UAE Cat Food Market | 2026-2036
UAE Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Cat Food Market Intelligence
A capital-intensity divergence between multinational manufacturers and local distributors is rotating competitive dynamics in the UAE cat food sector. Nestlé Purina Petcare leverages its global R&D infrastructure to sustain premium formulation leadership across Gulf retail channels. Dubai Pet Food anchors its position through localized supply chain control and rapid last-mile delivery capabilities. Royal Canin differentiates via veterinary-exclusive distribution partnerships that limit price-based competition.
Cat food encompasses nutritionally complete and complementary formulations manufactured through extrusion, retorting, or cold-pressing processes, with protein content typically ranging from 25% to 45% on a dry matter basis to meet feline obligate carnivore metabolic requirements. Wet food occupies the fastest-expanding margin pool as pet humanization trends elevate palatability and hydration preferences among UAE owners. Grain-free ingredient positioning captures premium shelf space in Dubai's pet specialty retailers, while veterinary clinic distribution channels concentrate prescription and therapeutic diet volumes.
MOHAP enforces pet food import registration and label compliance requirements that shape product availability timelines for international suppliers entering the UAE. The country's national standards body applies labeling and safety testing protocols that manufacturers must navigate before commercialization. Stakeholders should monitor evolving halal certification expectations for meat-based formulations and the expansion of online retail fulfillment infrastructure as decisive variables for market positioning.
Market Dynamics
MOHAP's tightening import documentation requirements are compressing product availability timelines for international suppliers while accelerating localized supply chain investments by established distributors.
Growth Catalysts
- Pet Humanization Trajectory:High-income expatriate households in Dubai and Abu Dhabi are elevating palatability and hydration preferences, accelerating wet food category expansion across veterinary clinic networks.
- MOHAP Registration Framework:The ministry's pet food safety standards are formalizing quality benchmarks that reward compliant manufacturers with faster market access and retail shelf priority.
- Grain-Free Formulation Innovation:Cold-pressing and retorting process advances are enabling protein-dense recipes that capture premium positioning in Dubai's pet specialty retail corridors.
Market Restraints
- Import Documentation Friction:MOHAP's evolving label compliance protocols extend product registration timelines, creating inventory planning complexity for European and North American suppliers.
- Protein Input Cost Volatility:Global meat and fish meal price fluctuations transmit directly to formulation costs, compressing margin pools for mid-tier product lines.
- Veterinary Channel Concentration:Prescription diet distribution concentrates through clinic-exclusive partnerships, limiting price-based competition and new entrant access.
Strategic Opportunities
- Halal Certification Tailwinds:Evolving consumer expectations for halal-compliant meat-based formulations create differentiation potential for suppliers with certified supply chains.
- Last-Mile Infrastructure Expansion:Rapid delivery capability investments by Dubai-based distributors are opening direct-to-consumer channels that bypass traditional retail markup structures.
- Therapeutic Diet White Space:Underpenetrated renal and digestive health segments within UAE veterinary networks offer margin expansion for clinically validated formulations.
Industry Challenges
- Feline Nutrition Specialist Scarcity:Veterinary formulation expertise and regulatory affairs talent command premium compensation, constraining R&D scaling for mid-size manufacturers.
- Retort Equipment Capex Burden:Wet food production capacity expansion requires specialized sterilization infrastructure, locking capital for extended depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Cat Food Market |
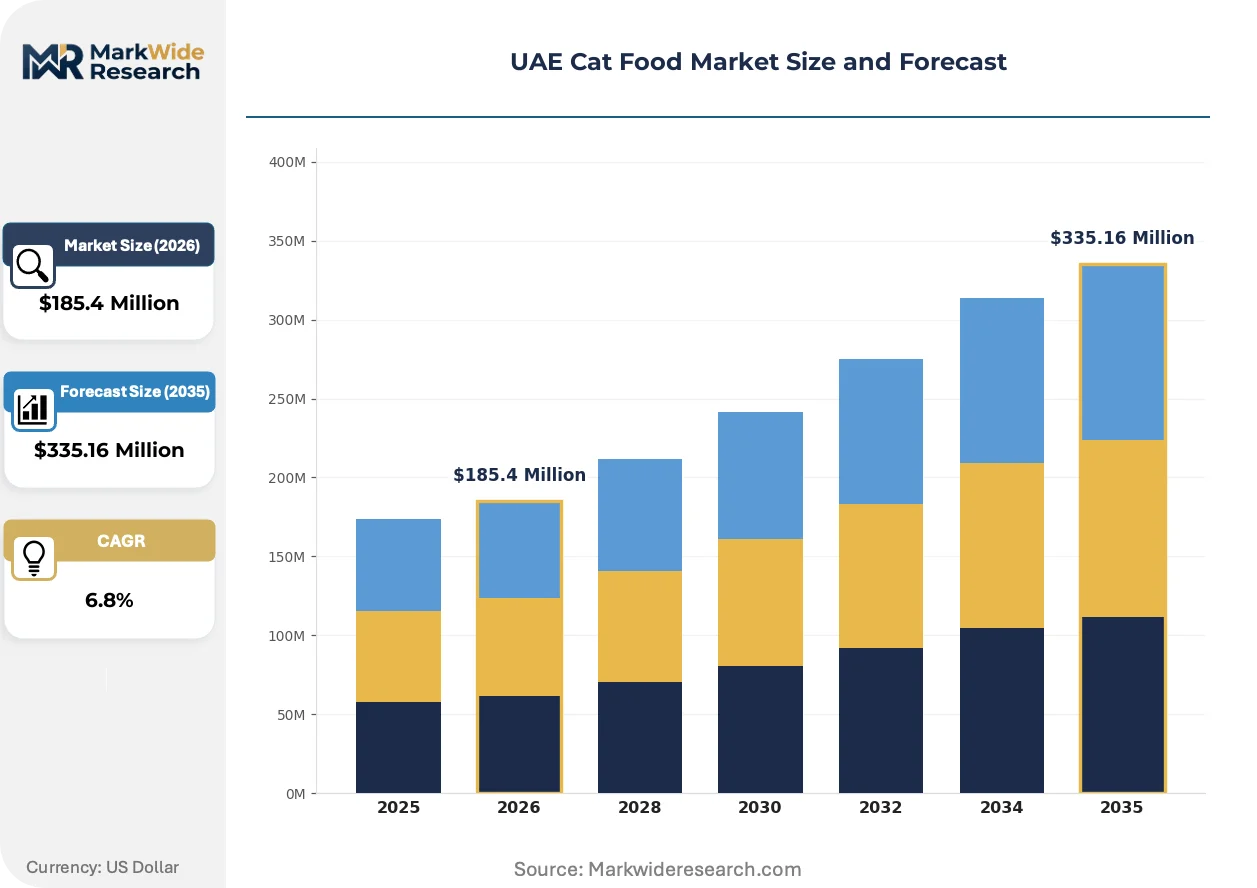
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Meat-Based, Grain-Free, Organic, Hypoallergenic Packaging Type: Bags, Cans, Pouches, Boxes Distribution Channel: Online Retail, Supermarkets, Pet Shops, Veterinary Clinics |
| Companies Covered | Nestlé Purina Petcare, Dubai Pet Food, Royal Canin, Beco Pets, Zabeel Pets, Hill’s Pet Nutrition, Zoetis, Pet Zone, Mars Petcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Cat Food Market Strategic Shifts & Innovations
Cold-pressed and minimally processed formulations are disrupting conventional extrusion dominance while regulatory transparency mandates and channel fragmentation are reshaping how products reach UAE cat owners.
High-pressure processing (HPP) technology is displacing traditional thermal sterilization in premium wet food manufacturing. Dubai's upscale pet retailers are adopting HPP-treated products to meet humanization-driven freshness expectations. This shift is compressing shelf-stable product margins while rewarding localized production investments with shorter distribution loops.
MOHAP's pet food import registration requirements are tightening documentary evidence standards for ingredient traceability. Manufacturers must now submit comprehensive supply chain audits before commercialization approval. Veterinary-exclusive distributors are responding by consolidating supplier relationships to reduce compliance administration burden.
Subscription-based replenishment models are capturing recurring revenue from multi-cat households in Abu Dhabi's high-density residential zones. Traditional pet specialty retailers are losing traffic to platforms offering automated delivery scheduling and veterinary consultation bundling. This behavioral pivot is most pronounced among British and South African expatriate communities with established online purchasing habits.
UAE Cat Food Market Segmentation
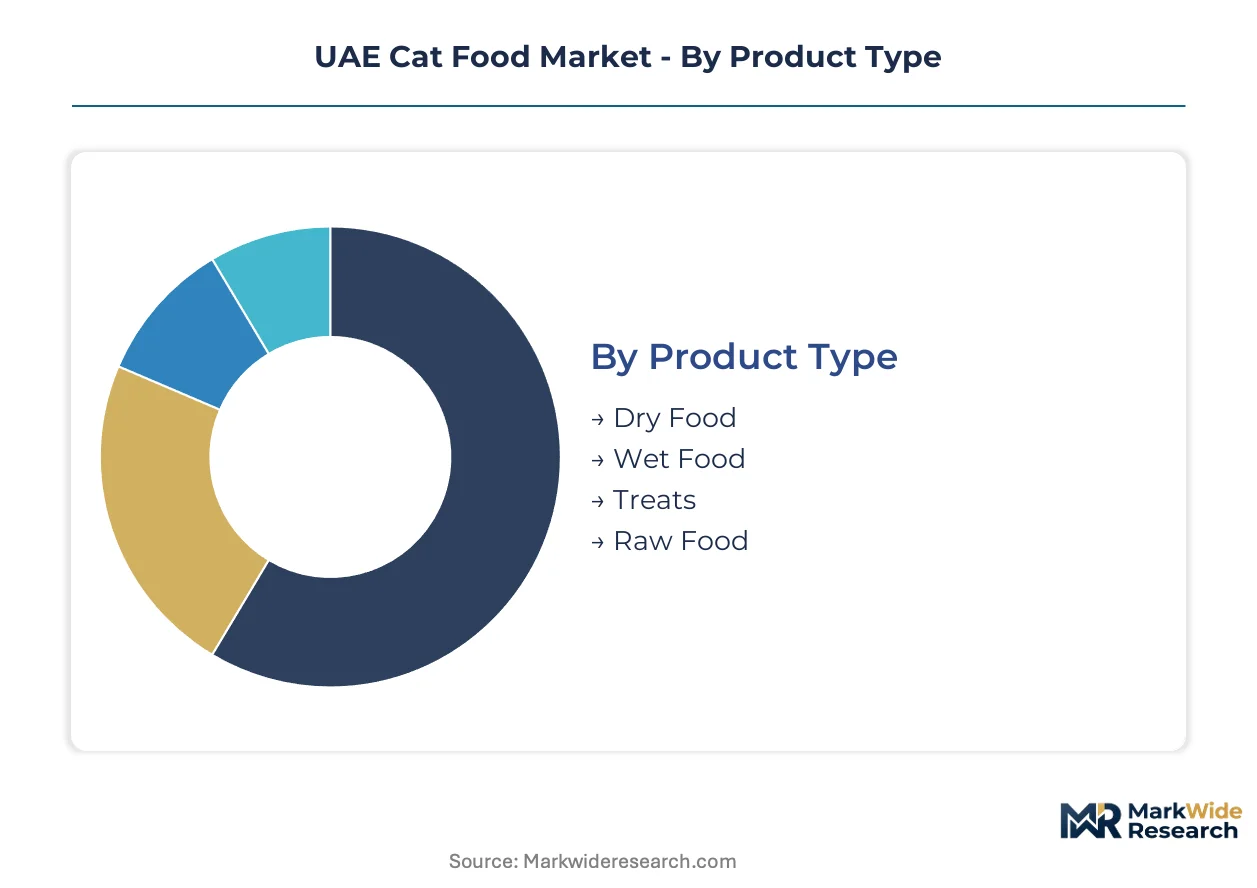
Segmentation in the UAE cat food market reveals how purchasing power, religious dietary requirements, and channel access patterns fragment demand across Dubai and Abu Dhabi's distinct consumer clusters.
Product Type:
Wet food and dry food command divergent channel strategies, with veterinary networks and pet specialty retailers respectively dominating volume flows.
- Wet Food:Retort-processed formulations with 75-85% moisture content address feline hydration requirements in arid climates. Dubai's high-income expatriate households in Jumeirah and Downtown Dubai concentrate demand through veterinary clinic subscriptions, driven by palatability preferences and humanization trends.
- Dry Food:Extruded kibble with 6-10% moisture offers shelf stability and cost efficiency for multi-cat households. Abu Dhabi's Al Reem Island and Khalifa City residential clusters source primarily through hypermarket bulk purchasing, constrained by storage space limitations in apartment dwellings.
- Treats:Complementary formulations with elevated palatability enhancers capture impulse purchasing at pet specialty checkout counters.
- Raw Food:Frozen or freeze-dried minimally processed diets with uncooked protein content appeal to niche humanization extremists in Dubai's Al Barsha and Arabian Ranches communities.
Dry food dominates installed base across UAE households. Wet food is where expansion concentrates.
Ingredient Type:
Cost tier stratification separates mass-market formulations from veterinary-prescribed therapeutic diets, with halal compliance emerging as a non-negotiable mid-tier filter.
- Meat-Based:Poultry, fish, and red meat protein sources constitute the nutritional foundation for obligate carnivore metabolism. Dubai's British and South African expatriate communities drive volume through premium wet food subscriptions, with MOHAP import documentation requirements creating compliance friction for European suppliers.
- Grain-Free:Formulations excluding corn, wheat, and rice appeal to digestive sensitivity concerns among Persian and British Shorthair owners. Abu Dhabi's Al Maryah Island and Saadiyat Island high-net-worth households purchase through veterinary-exclusive channels, constrained by protein input cost volatility.
- Organic:Certified ingredient sourcing with prohibited synthetic additives targets sustainability-conscious consumers in Dubai's Sustainable City and Al Barari developments.
- Hypoallergenic:Limited-ingredient diets with novel protein sources address feline food allergies diagnosed through veterinary dermatology referrals.
Meat-based formulations anchor volume. Grain-free is climbing the fastest.
Packaging Type:
Volume-to-value ratios and last-mile logistics constraints determine packaging selection, with single-serve formats gaining traction in dense urban zones.
- Pouches:Flexible laminated film with tear-notch convenience features dominates wet food single-serve consumption. Dubai's DIFC and Business Bay professional households purchase through subscription platforms, driven by portion control and refrigerator space optimization.
- Cans:Metal containers with easy-open lid technology sustain multi-cat household economics. Abu Dhabi's Mohammed Bin Zayed City and Mussafah residential areas source through Carrefour and Lulu Hypermarket promotions, constrained by recycling infrastructure limitations.
- Bags:Multi-layer plastic with resealable zipper closures protects dry food freshness in humid coastal conditions.
- Boxes:Corrugated or rigid packaging for treat assortments and subscription bundle configurations.
Cans dominate installed base. Pouches are gaining share fastest.
Distribution Channel:
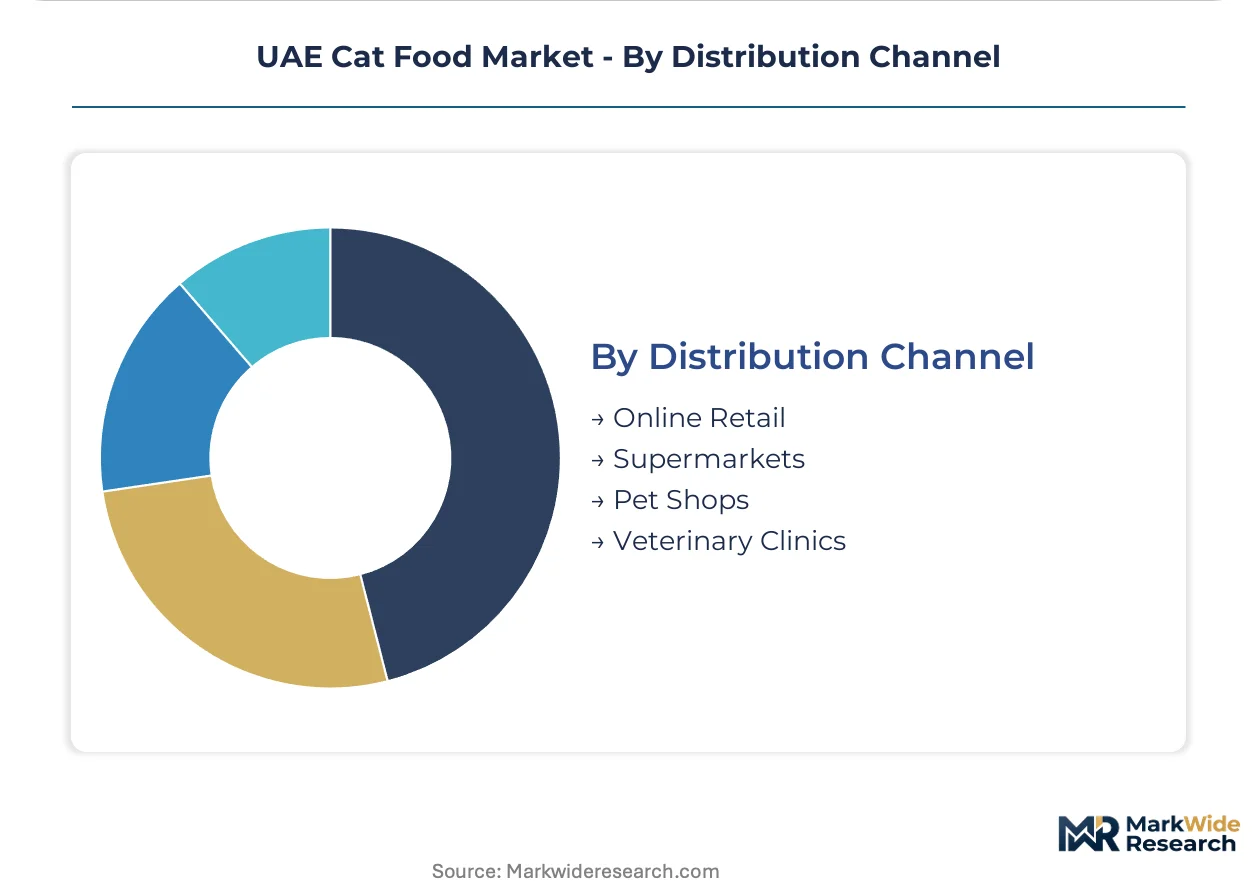
Customer type fragmentation separates transactional purchasers from relationship-driven subscribers, with channel loyalty correlating to pet health engagement intensity.
- Veterinary Clinics:Prescription and therapeutic diet distribution through Dubai's British Veterinary Hospital and Abu Dhabi's Canadian Veterinary Hospital networks. High-margin recurring revenue from renal and digestive health formulations, constrained by feline nutrition specialist scarcity limiting formulation scaling.
- Online Retail:Dubai Pet Food and Amazon.ae platforms with automated replenishment and veterinary consultation bundling. British and South African expatriate communities in Dubai Marina and JBR adopt fastest, driven by established e-commerce purchasing habits.
- Pet Shops:The Pet Shop Dubai and Pets Plus outlets in Mall of the Emirates and Yas Mall capture premium grain-free and treat impulse purchasing.
- Supermarkets:Carrefour, Lulu, and Union Coop hypermarkets anchor dry food volume through promotional pricing and bulk formats.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency defines the UAE cat food sector's regional configuration, with Dubai and Abu Dhabi serving as the primary consumption hubs while European and North American suppliers navigate MOHAP registration protocols. Domestic formulation capacity remains limited, concentrating value-added activities in distribution and last-mile logistics rather than manufacturing.
Dubai
High-income expatriate households in Jumeirah and Downtown Dubai drive wet food premiumization through veterinary clinic subscriptions. MOHAP's import documentation requirements create compliance friction for European suppliers seeking shelf space in Mall of the Emirates retail corridors. The Dubai Pet Food platform anchors online distribution with rapid delivery infrastructure targeting British and South African expatriate communities in Dubai Marina.
Abu Dhabi
Al Reem Island and Khalifa City residential clusters source dry food through hypermarket bulk purchasing constrained by apartment storage limitations. The emirate's veterinary networks concentrate prescription diet volumes through Canadian Veterinary Hospital partnerships. Grain-free positioning captures premium demand from Al Maryah Island and Saadiyat Island high-net-worth households.
Sharjah
Mid-tier product lines dominate consumption patterns in Mohammed Bin Zayed City and Mussafah residential zones with price-sensitive multi-cat households. Carrefour and Lulu Hypermarket promotions sustain dry food economics across the emirate's hypermarket-dense retail landscape. Recycling infrastructure limitations favor can formats over flexible packaging in bulk purchasing behavior.
Northern Emirates
Ras Al Khaimah and Fujairah present underpenetrated white space for subscription-based replenishment models targeting emerging pet ownership. Traditional trade channels retain dominance over organized retail in these emirates. Logistics cost structures constrain premium wet food distribution beyond urban coastal corridors.
UAE Cat Food Market Key Industry Players
Concentration sits with multinational manufacturers leveraging global R&D infrastructure against localized distributors controlling last-mile fulfillment. Three archetypes define the competitive terrain: global formulation leaders with veterinary-exclusive channels, regional distributors with supply chain control, and specialty retailers with subscription-based customer relationships. Competitive moves center on halal certification acquisition and direct-to-consumer platform investments that bypass traditional retail markups.
Among global manufacturers, Nestlé Purina Petcare exemplifies the R&D-driven archetype with premium formulation leadership, while Royal Canin occupies a position within veterinary-exclusive distribution partnerships that limit price-based competition. Dubai Pet Food represents the localized distributor archetype with rapid last-mile capabilities.
| Leading Market Players |
|---|
| Nestlé Purina Petcare |
| Dubai Pet Food |
| Royal Canin |
| Beco Pets |
| Zabeel Pets |
| Hill's Pet Nutrition |
| Zoetis |
| Pet Zone |
| Mars Petcare |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between European manufacturers and UAE distributors lock in protein supply access while stabilizing landed cost visibility against MOHAP registration delays. These contracts tether pricing power to import documentation compliance timelines rather than spot market fluctuations.
Pricing Analysis
High-income expatriate households anchor a subscription-based pricing structure across Dubai's veterinary clinic networks. Pricing stratifies across premium therapeutic tiers, halal-certified mid-market formulations, and economy dry food bulk formats. Cost compression in mid-tier wet food is intensifying because protein input volatility transmits directly to formulation economics. Multi-cat households in Abu Dhabi's apartment clusters exhibit highest price sensitivity, while single-cat owners in Jumeirah demonstrate lowest elasticity for palatability-driven premiums.
Supply Chain Analysis
Jebel Ali port clearance bottlenecks underwrite inventory holding cost structures for international suppliers navigating MOHAP's documentary evidence requirements. Protein sourcing concentrates in Thailand, France, and the Netherlands for fish meal and poultry meal inputs. Supply chain risk centers on single-source vulnerability for retort equipment sterilization technology. Distribution runs through Dubai Pet Food's last-mile infrastructure and veterinary-exclusive channel partnerships that bypass traditional retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as subscription bundling with veterinary telehealth creates interoperability lock-in between nutrition and diagnostics ecosystems.
For Market Incumbents: Compound your formulation leadership by acquiring halal certification capabilities before regulatory expectations harden. Deepen backward integration into cold-pressed production infrastructure to offset retort equipment capex burdens. Channel control through Dubai Pet Food's rapid delivery network represents the critical defensive lever against direct-to-consumer entrants. For New Entrants and Emerging Players: Veterinary telehealth integration gaps in Abu Dhabi's Al Reem Island corridor present the most penetrable white space for subscription-based therapeutic diet launches. Target renal and digestive health segments where incumbent presence remains underdeveloped. A go-to-market angle bundling automated replenishment with remote feline nutrition consultations bypasses clinic-exclusive distribution barriers. For Investors and Strategic Acquirers: Regional distributors with captive last-mile logistics and MOHAP compliance expertise represent the priority acquisition archetype. Long-term viability hinges on platform consolidation dynamics where veterinary network partnerships determine customer lifetime value capture. Watch halal certification adoption rates among European suppliers as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acquisition | MOHAP's evolving meat-sourcing standards reward early compliance with retail shelf priority. |
| Direct-to-Consumer Platform Launch | Dubai Pet Food's subscription infrastructure demonstrates bypass potential for veterinary clinic markups. |
| Cold-Pressed Production Investment | High-pressure processing technology displaces thermal sterilization in premium wet food manufacturing. |
| Veterinary Network Partnership | Canadian Veterinary Hospital and British Veterinary Hospital channels concentrate prescription diet volumes. |
| Last-Mile Infrastructure Expansion | Rapid delivery capabilities in Abu Dhabi's high-density zones open recurring revenue from multi-cat households. |
Research Approach
Cross-validation between distributor procurement data and veterinary clinic dispensing records anchors the qualitative findings on channel concentration patterns. Primary interviews with pet food brand managers, MOHAP regulatory affairs specialists, Dubai-based category buyers, and feline veterinary nutritionists combined with secondary validation from customs import databases, MOHAP registration filings, and Nielsen retail audit data. Bottom-up volume estimates from product-level SKU data and top-down market sizing from household pet ownership statistics were reconciled through iterative triangulation.
Sensitivity analysis across protein input cost scenarios and MOHAP registration timeline variations frames the projection boundaries. The analytical framework segments by product type, ingredient positioning, packaging format, and distribution channel across the modeling period. CAGRs were derived from trend extrapolation of wet food premiumization trajectories and dry food bulk purchasing stability. Forecast inputs include expatriate household income elasticity estimates and veterinary clinic network expansion plans.
Underlying assumptions cover stable MOHAP regulatory enforcement intensity and continued pet humanization behavioral patterns, with deviation risk concentrated in halal certification mandate timing and global meat meal price volatility. Practitioners should keep alternative scenarios live as protein supply chain reconfigurations and platform consolidation dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Raincoats Market
Pet Care Products
Global Flea and Tick Product Market
Pet Care Products
Pet Treats Market
Pet Care Products
Pet Care Market
Pet Care Products
Mink Oil Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
US Pet Treats Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Toy Dog Market
Pet Care Products
South Africa Pet Boarding Market
Pet Care Products
Pet Noise Anxiety Market
Pet Care Products
UK Dog Food Market
Pet Care Products
Tofu Cat Litter Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Pet Relaxants Market