
 Pet Grooming Market | 2026-2036
Pet Grooming Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Grooming Market Outlook
Subscription-based leasing of mobile grooming vans is rewriting competitive entry dynamics for independent operators. PetSmart LLC leverages its captive real estate network to sustain high-margin service attach rates in big-box formats. Petco Animal Supplies, Inc. anchors its grooming revenue through veterinary clinic co-location, blurring the retail-healthcare boundary. Spectrum Brands, Inc. competes in the consumables layer with concentrated R&D on pH-balanced formulations for sensitive skin.
Pet grooming encompasses the hygienic maintenance and aesthetic care of companion animals through bathing, brushing, nail trimming, and coat conditioning, typically employing species-specific pH formulations between 6.2 and 7.5 to preserve epidermal barrier function. The practice serves both preventive health objectives and owner-driven aesthetic standards across residential and commercial settings. Shampoos and conditioners carry the deepest margin pools due to repeat purchase frequency and formulation differentiation, while mobile grooming represents the fastest-expanding distribution channel as convenience-seeking owners bypass brick-and-mortar constraints. Brushes and grooming tools occupy a more mature segment where price competition limits premium extraction.
The FDA Center for Veterinary Medicine regulates topical pet care ingredients for safety, while state-level occupational licensing boards govern facility sanitation and practitioner certification. ISO 9001 quality management standards increasingly appear in supplier requirements from large retail chains, raising barriers for unaccredited manufacturers. Stakeholders must monitor how veterinary clinic consolidation reshapes referral flows for medical-adjacent grooming services.
Market Dynamics
Veterinary-adjacent grooming services are consolidating referral flows as clinic networks acquire standalone operators, compressing the independent channel's access to high-margin medical grooming revenue.
Growth Catalysts
- Pandemic-Elevated Pet Humanization:Remote work normalized constant companion presence, sustaining premium spending on coat conditioning and spa treatments among dual-income households.
- ISO 9001 Accreditation Mandates:Large retail chains now require supplier quality certification, filtering out unaccredited manufacturers and concentrating contract volumes with compliant producers.
- Mobile Van Subscription Leasing:Asset-light fleet models lower capital barriers for independent groomers entering suburban markets without brick-and-mortary overhead.
Market Restraints
- State Licensing Fragmentation:Facility sanitation and practitioner certification requirements vary across US state boards, creating compliance complexity for multi-location operators.
- Specialized Labor Scarcity:Certified master groomers command wage premiums that compress margins in price-sensitive service tiers.
- Ingredient Safety Scrutiny:FDA Center for Veterinary Medicine oversight of topical formulations extends development timelines for new shampoo introductions.
Strategic Opportunities
- Veterinary Clinic Co-Location:Medical-adjacent grooming stations capture referral traffic from wellness exams and dermatology consultations.
- pH-Balanced Sensitive Skin Formulations:R&D investment in species-specific epidermal barrier science opens premium positioning in the consumables layer.
- Urban Convenience Channels:Apartment-dwelling pet owners in dense metropolitan areas favor on-demand mobile services over destination retail.
Industry Challenges
- Certification Pipeline Bottlenecks:Master groomer programs require 400-600 training hours, constraining workforce expansion to match service demand.
- Facility Capex Escalation:Hydraulic grooming tables, specialized ventilation systems, and wastewater compliance equipment strain independent operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Grooming Market |
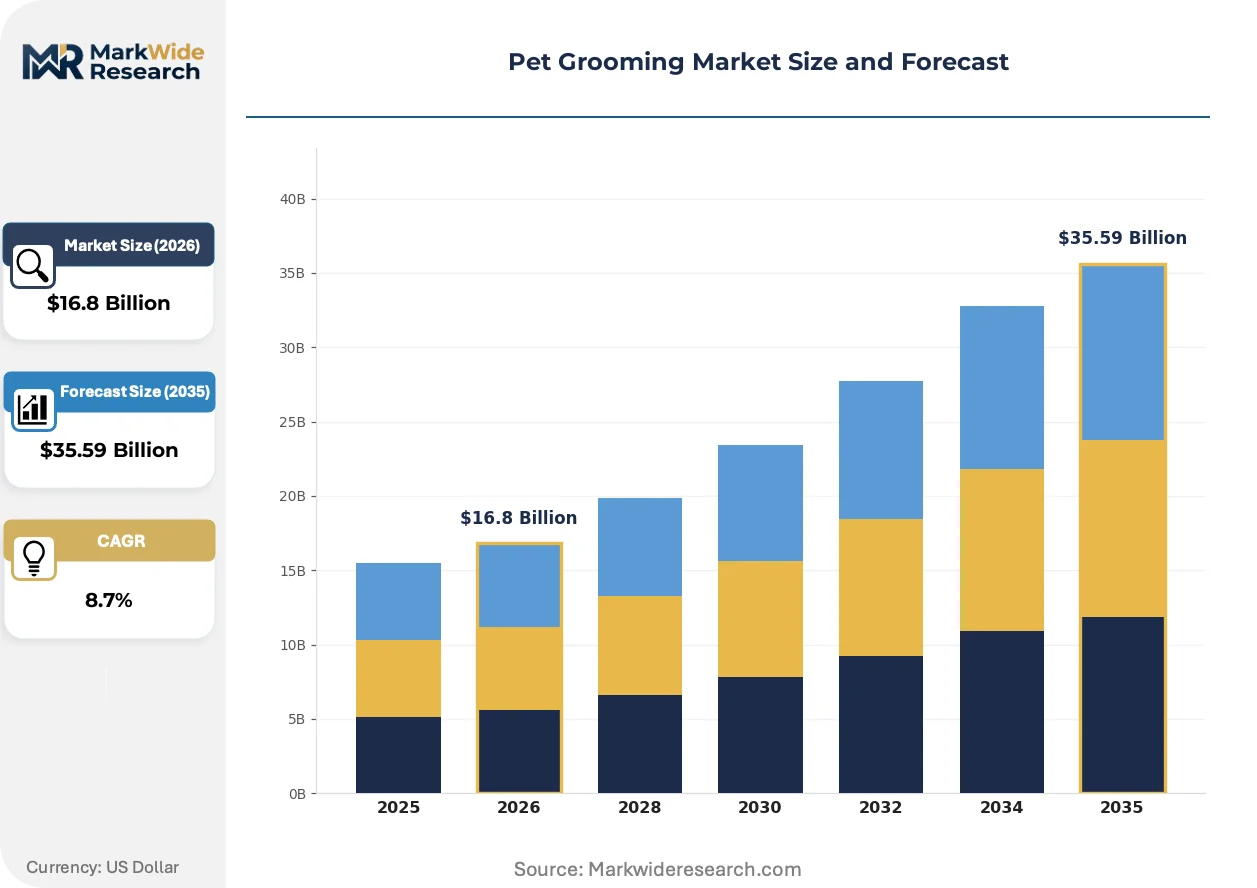
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $35.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bathing, Haircut, Nail Trimming, Ear Cleaning Product Type: Shampoos, Conditioners, Brushes, Grooming Tools Pet Type: Dogs, Cats, Rabbits, Guinea Pigs Distribution Channel: Online Retail, Pet Shops, Veterinary Clinics, Mobile Grooming |
| Companies Covered | 4-Legger, SynergyLabs, PetSmart LLC, Coastal Pet Products, Resco, Petco Animal Supplies, Inc., Bio-Derm Laboratories, Inc., Spectrum Brands, Inc., Pets At Home Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Grooming Market Strategic Shifts
Digital booking platforms and telemedicine integration are compressing the traditional appointment-to-service cycle, while formulation science advances target species-specific dermatological needs.
AI-powered skin assessment tools are digitizing the intake diagnostic process for grooming appointments. High-volume salon chains deploy tablet-based coat condition scoring to standardize service tier recommendations. This standardization is digitizing variability out of pricing conversations and reducing disputes over service scope.
EU REACH chemical registration requirements are tightening disclosure obligations for imported pet care formulations. Manufacturers must now document full substance inventories for shampoos entering European distribution. Smaller US-based suppliers are responding by exiting the EU market rather than absorbing compliance costs.
Subscription-based consumables bundling is displacing single-unit retail purchasing among multi-pet households. Automated reorder algorithms tied to coat length and bathing frequency data reduce stockout friction. This pattern concentrates most visibly in US metropolitan markets with high purebred dog ownership density.
Pet Grooming Market Segmentation
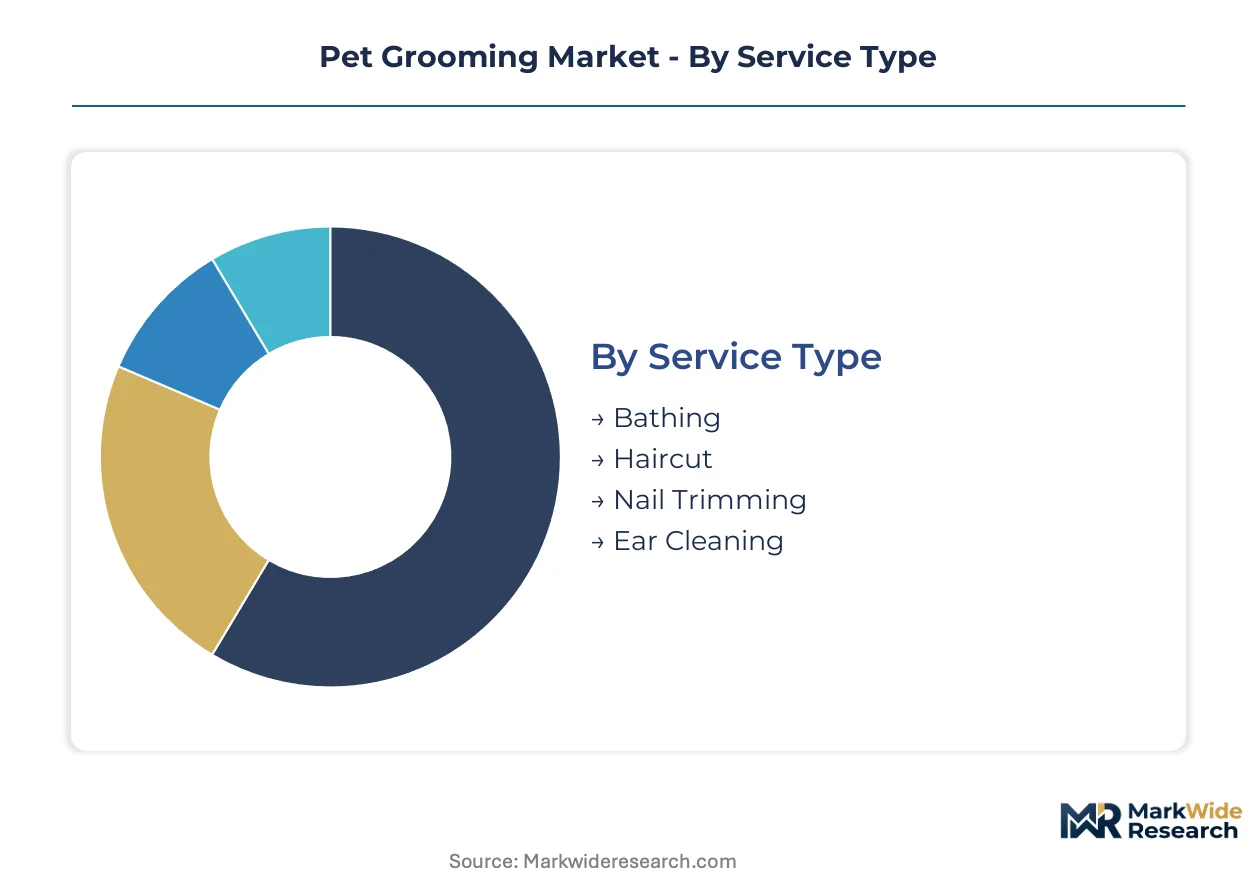
Pet grooming segmentation reveals how service delivery models, product formulations, and channel economics fragment across owner preferences and animal physiology. Understanding these divides exposes where margin pools concentrate and which technology investments reshape competitive position.
Service Type:
Service intensity spans from routine maintenance to specialized medical-adjacent procedures, with labor skill requirements and pricing power varying sharply across the spectrum.
- Bathing:Core service involving pH-balanced cleansing formulations between 6.2 and 7.5 to preserve epidermal barrier function. Demand concentrates in urban United States markets where apartment-dwelling owners lack home washing facilities, with mobile van operators capturing premium pricing for door-to-door convenience.
- Haircut:Breed-specific styling requiring 400-600 hour certified master groomer training for complex coat patterns. Veterinary clinic co-location in US suburban corridors captures referral traffic from dermatology consultations, attaching high-margin medical grooming to wellness exams.
- Nail Trimming:Quick-turn maintenance service with lower labor barriers and compressed pricing power.
- Ear Cleaning:Preventive hygiene procedure often bundled into subscription packages at premium salons.
Established volume favors bathing; emerging adoption favors haircut services attached to veterinary workflows.
Product Type:
Margin architecture separates consumables with repeat purchase cycles from durable equipment with extended replacement horizons.
- Shampoos:Highest-frequency consumable with formulation differentiation commanding premium positioning. FDA Center for Veterinary Medicine oversight of topical ingredients extends development timelines, concentrating contract manufacturing among ISO 9001-accredited suppliers serving large US retail chains.
- Conditioners:Coat conditioning agents targeting specific dermatological needs including sensitive skin and allergen resistance. pH-balanced sensitive skin formulations attract premium pricing in high purebred dog ownership density metropolitan markets.
- Brushes:Mature segment where price competition limits premium extraction.
- Grooming Tools:Durable equipment category facing margin compression from commoditized import supply.
Repeat purchase velocity favors shampoos; R&D differentiation favors conditioners.
Pet Type:
Animal physiology and owner spending behavior fragment addressable market economics across species lines.
- Dogs:Dominant service volume driven by larger coat surface area and established grooming culture. United States urban pet ownership rates sustain the largest national grooming economy with dual-income households sustaining premium spending on spa treatments.
- Cats:Lower service frequency due to self-grooming behavior, though specialized sedation protocols open veterinary-adjacent revenue. Mobile grooming represents the fastest-expanding channel for feline services as stress-reducing home environments improve compliance.
- Rabbits:Niche segment requiring species-specific handling expertise.
- Guinea Pigs:Small-animal maintenance with limited professional service penetration.
Service infrastructure depth favors dogs; channel innovation favors cats.
Distribution Channel:
Physical footprint requirements and customer acquisition economics determine competitive entry barriers across routes to market.
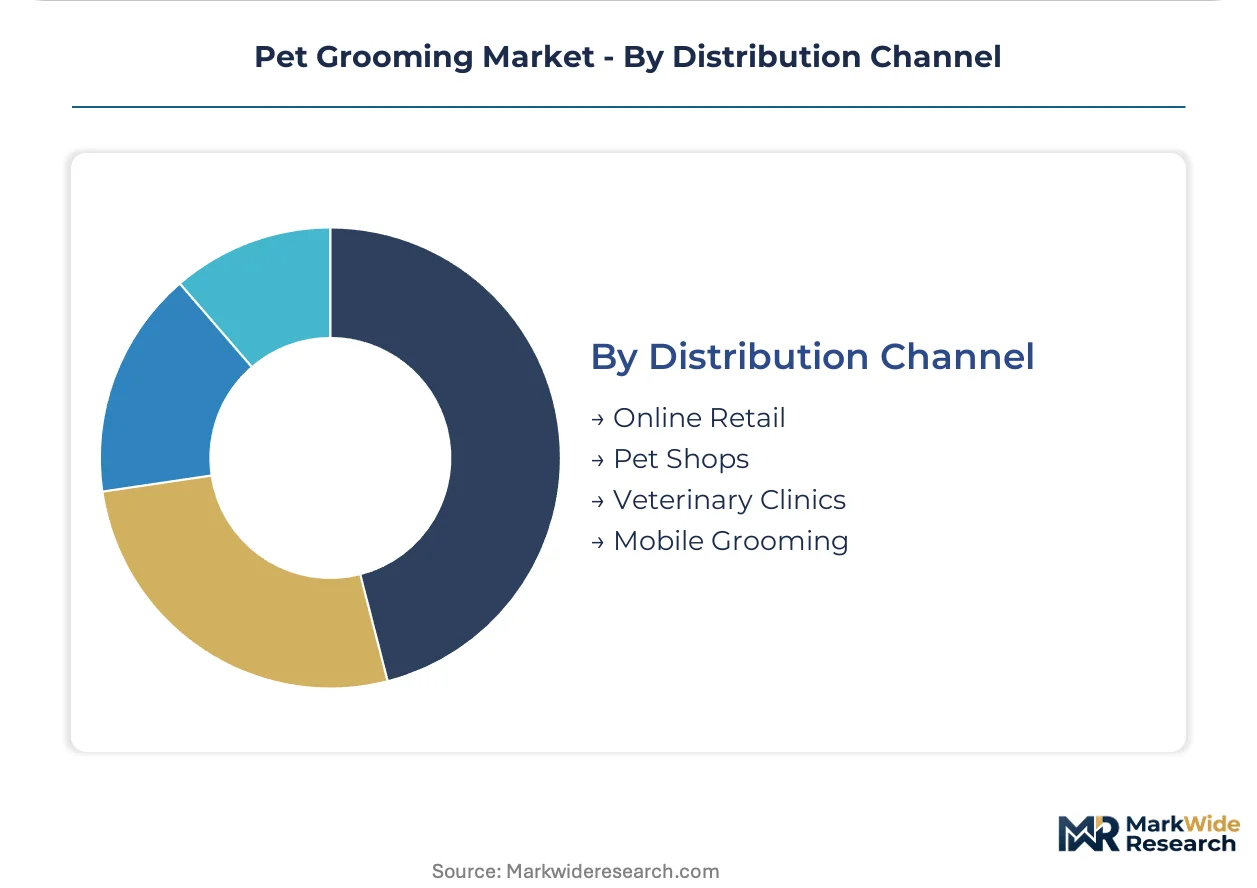
- Online Retail:Subscription-based consumables bundling displaces single-unit purchasing among multi-pet households. Automated reorder algorithms tied to coat length and bathing frequency data reduce stockout friction in US metropolitan markets.
- Pet Shops:Big-box formats leverage captive real estate networks to sustain high-margin service attach rates.
- Veterinary Clinics:Medical-adjacent grooming stations capture referral traffic from wellness exams, blurring retail-healthcare boundaries.
- Mobile Grooming:Asset-light fleet models lower capital barriers for independent operators entering suburban markets without brick-and-mortar overhead. Subscription-based van leasing is rewriting competitive entry dynamics.
Scale concentration favors pet shops; capital efficiency favors mobile grooming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet grooming services and consumables flow predominantly from developed manufacturing bases toward high-spending urban markets, with the United States running a substantial services surplus while importing specialized formulations from European chemical producers.
United States
Urban pet ownership rates and dual-income household density sustain the world's largest national grooming economy, with mobile van operators capturing premium pricing in apartment-heavy metropolitan corridors. The FDA Center for Veterinary Medicine oversees topical ingredient safety, extending development timelines for new shampoo introductions. Greater Los Angeles and New York City anchor the highest service density, where subscription-based consumables bundling concentrates among multi-pet households.
United Kingdom
Premium pet salon expansion among high-income households drives service revenue growth, particularly in London and Southeast England where convenience-seeking owners favor on-demand mobile booking. EU REACH chemical registration requirements tighten disclosure obligations for imported formulations, prompting some US suppliers to exit European distribution. The Midlands region hosts ISO 9001-accredited contract manufacturers supplying large retail chains with pH-balanced sensitive skin formulations.
Germany
Veterinary clinic consolidation reshapes referral flows for medical-adjacent grooming, with clinic networks acquiring standalone operators in Bavaria and North Rhine-Westphalia. The KBA and federal state veterinary boards enforce facility sanitation standards that elevate compliance costs for multi-location operators. Berlin-Brandenburg emerges as a testing ground for AI-powered skin assessment tools deployed by high-volume salon chains.
Japan
Metropolitan Tokyo and Osaka sustain dense networks of premium pet spas serving shrinking household sizes with elevated per-pet spending. METI guidelines on quality management standards increasingly appear in supplier requirements from large retail chains. The Kanto region concentrates formulation R&D investment targeting species-specific dermatological needs for purebred dog ownership clusters.
Australia
Urban convenience channels favor mobile grooming expansion in Sydney and Melbourne, where apartment-dwelling pet owners bypass brick-and-mortar constraints. The TGA regulates topical pet care ingredients with disclosure requirements that filter unaccredited manufacturers from supply chains. New South Wales hosts the largest concentration of certified master groomer training programs, though 400-600 hour certification requirements constrain workforce expansion.
Pet Grooming Market Competitive Environment
On the supply side, the industry is bifurcated between capital-intensive service networks and formulation-focused consumables manufacturers, with scale advantages concentrating in distinct pockets. Large retail chains leverage captive real estate for service attach rates, while mobile fleet operators exploit asset-light subscription leasing to penetrate suburban markets. Three archetypes dominate: big-box retailers with veterinary co-location, independent mobile groomers, and ISO-accredited chemical formulators. Competitive moves center on veterinary clinic acquisition for referral flow control and pH-balanced formulation R&D for premium consumables positioning.
Within the big-box retail tier, PetSmart LLC and Petco Animal Supplies, Inc. exemplify divergent real estate strategies—PetSmart leveraging standalone big-box formats while Petco anchors through veterinary clinic co-location. Spectrum Brands, Inc. occupies the consumables manufacturing position, representing the ISO 9001-accredited supplier archetype that large retail chains require for contract volumes. These three entities illustrate how scale concentration in services runs parallel to quality certification barriers in chemical supply.
| Leading Market Players |
|---|
| 4-Legger |
| SynergyLabs |
| PetSmart LLC |
| Coastal Pet Products |
| Resco |
| Petco Animal Supplies, Inc. |
| Bio-Derm Laboratories, Inc. |
| Spectrum Brands, Inc. |
| Pets At Home Inc. |
| Others |
Value Chain & Pricing Dynamics
ISO 9001-accredited contract manufacturers in the US Midwest and Germany's chemical corridor control pH-balanced formulation supply, concentrating margin capture among large retail chains while squeezing independent groomers into price-taker positions on consumables.
Pricing Analysis
Multi-pet households anchor subscription-based consumables bundling across premium, standard, and economy tiers. Price differentiation rests on certification grade—FDA-reviewed formulations command premiums over unaccredited imports—and volume scale through automated reorder algorithms. Cost compression in the standard tier intensifies because commodity shampoo imports from unaccredited Asian suppliers flood e-commerce channels. Price-sensitive independent mobile groomers face the steepest margin pressure, while veterinary clinic co-location operators exhibit the least sensitivity due to medical-adjacent service attach rates.
Supply Chain Analysis
Tier-one contract manufacturers including Spectrum Brands' ISO-accredited facilities hold concentrated capacity for pH-sensitive formulations. Supply concentrates in the United States, Germany, and Japan for active ingredient synthesis, with surfactant chemistry and botanical extracts as critical raw material dependencies. Single-source vulnerability runs through FDA-preferred supplier lists for topical pet care actives. Distribution runs through big-box retail networks and mobile fleet operators, with direct-to-consumer subscription channels displacing single-unit purchasing in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across service delivery models—brick-and-mortar, mobile, and veterinary-adjacent—creates niche opportunities as convenience-seeking pet owners splinter across channel preferences.
For Market Incumbents: Entrench veterinary clinic referral flows by acquiring standalone grooming operators in suburban US corridors before clinic networks consolidate access. Invest in AI-powered skin assessment tools to standardize service tier recommendations and reduce pricing disputes. ISO 9001 accreditation serves as the priority lever to lock out unaccredited consumables competitors from large retail chain contracts.
For New Entrants and Emerging Players: Mobile grooming subscription leasing in US apartment-heavy metropolitan corridors represents the most penetrable entry point, bypassing brick-and-mortar capex barriers entirely. Feline-specific sedation protocols at veterinary-adjacent locations capture underserved cat owner demand. A go-to-market angle emphasizing stress-reducing home environments outperforms destination retail for compliance-sensitive species.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mobile fleet operators and regional veterinary clinic networks seeking grooming service tuck-ins. Long-term viability over a 5-10 year window favors consolidators controlling referral flow rather than standalone equipment manufacturers. Watch master groomer certification pipeline bottlenecks as the inflection signal—constrained workforce expansion relative to service demand indicates pricing power inflection for accredited operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinic Co-Location | Captures referral traffic from wellness exams, blurring retail-healthcare boundaries for premium attach rates. |
| pH-Balanced Formulation R&D | Opens premium positioning in consumables through species-specific epidermal barrier science investment. |
| Mobile Fleet Subscription Leasing | Lowers capital barriers for independent groomers entering suburban markets without brick-and-mortar overhead. |
| AI-Powered Skin Assessment Deployment | Standardizes service tier recommendations across high-volume salon chains, digitizing pricing variability. |
| ISO 9001 Quality Certification | Filters unaccredited manufacturers from large retail chain supplier requirements, concentrating contract volumes. |
Study Parameters
A spread of perspectives from master groomer certification program directors, veterinary clinic network operators, retail chain category buyers, and pH-balanced formulation chemists converged on the working assumptions. Primary interviews combined with secondary validation from FDA Center for Veterinary Medicine filings, state occupational licensing board records, and ISO 9001 accreditation databases. Customs data on topical pet care ingredient imports, SEC 10-K disclosures from listed retailers, and EU REACH chemical registration filings anchored supply-side quantification. Bottom-up service location counts and top-down consumables revenue estimates underwent triangulation across independent verification sources.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include service type intensity, product formulation tier, pet species physiology, and distribution channel economics. CAGRs derived from cohort-based growth rate analysis applied to certified master groomer workforce expansion, mobile fleet subscription uptake curves, and consumables repeat purchase velocity in metropolitan purebred ownership clusters. Veterinary clinic consolidation velocity and FDA ingredient review timeline extensions served as industry-specific forecast inputs.
Practitioners should monitor state licensing board harmonization efforts, FDA topical ingredient safety alerts, and master groomer program graduation rates for early signals. Forecasts reflect assumptions about pandemic-elevated pet humanization persistence and subscription model adoption saturation. Quarterly review of mobile fleet operator bankruptcy filings and veterinary clinic network acquisition announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Small Dog Harness Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
GCC Cat Food Market
Pet Care Products
Global Flea and Tick Product Market
Pet Care Products
Dog Seat Covers Market
Pet Care Products
Cat Accessories Market
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
United Kingdom Cat Litter Market
Pet Care Products
Pet Slow Feeder Bowl Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
Raw Meat Pet Food Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Mexico Pet Food Market