
 Disposable Absorbent Pet Pad Market | 2026-2036
Disposable Absorbent Pet Pad Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Absorbent Pet Pad Market Insights
Multi-source raw material procurement is pivoting toward captive polymer supply as manufacturers seek insulation from virgin SAP price cycles. Hartz (Unicharm) leverages its parent company's superabsorbent polymer R&D infrastructure across Osaka and regional technical centers. IRIS USA anchors North American distribution through big-box pet retail partnerships and direct-to-consumer fulfillment networks. Jiangsu Zhongheng competes on converted non-woven throughput, operating some of the largest thermal-bond lines serving private-label programs.
Disposable absorbent pet pads are engineered multilayer hygiene products combining a fluid-permeable top sheet, a superabsorbent polymer core, and a waterproof polyethylene backsheet, manufactured through spunbond-meltblown-spunbond lamination and hot-melt adhesive bonding. Their primary commercial purpose is localized excrement containment for domesticated animals in indoor, travel, or post-operative settings. Ultra Absorbent variants command disproportionate margin pools as SAP loading rates climb and pet owners trade up from standard products. Eco-Friendly segments remain structurally constrained by composting infrastructure gaps and certification costs, though polymer-based pads dominate unit economics at scale.
The EPA oversees landfill leachate implications of saturated pad disposal, while state-level extended producer responsibility proposals in California and New York threaten to internalize end-of-life collection costs. The FDA's Center for Veterinary Medicine influences product claims around antimicrobial additives and odor-control chemistry through feed-contact and device-adjacent pathways. Stakeholders must monitor whether biodegradable certification schemes from BPI or TÜV Austria achieve retail gatekeeping status before committing capital to non-polymer core transitions.
Market Dynamics
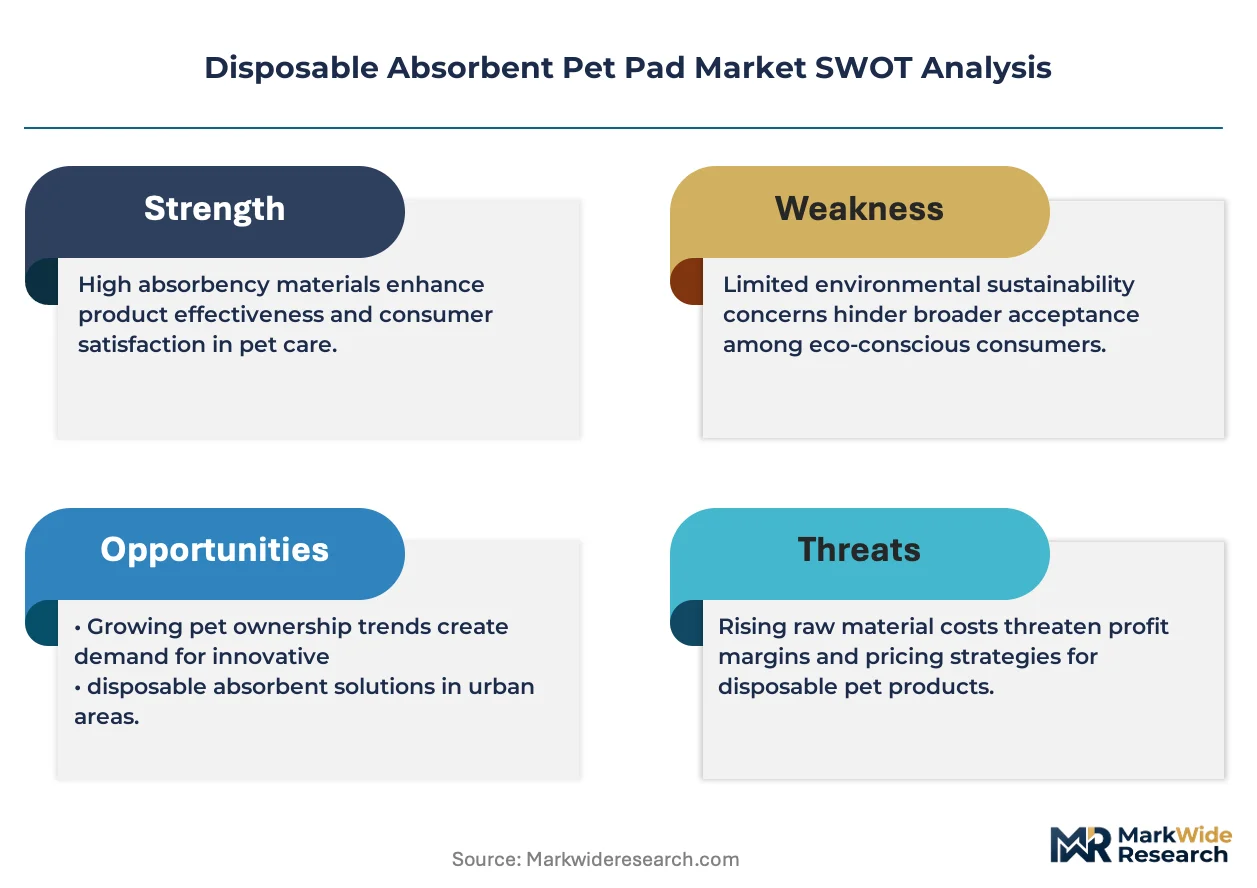
Biodegradable certification schemes are fragmenting competitive positioning as manufacturers weigh capital commitments against uncertain retail gatekeeping status for non-polymer core alternatives.
Growth Catalysts
- Post-surgical protocol standardization:Veterinary clinics and animal hospitals are systematizing recovery workflows, creating institutional demand for ultra-absorbent variants with higher SAP loading rates.
- Extended producer responsibility frameworks:California and New York state-level proposals are accelerating manufacturer investment in end-of-life collection infrastructure.
- Superabsorbent polymer R&D spillover:Parent company technical centers in Osaka are transferring polymer science advances to pet pad applications, compressing development cycles.
Market Restraints
- Virgin SAP price cycle exposure:Superabsorbent polymer feedstock costs fluctuate with acrylic acid and propylene supply, squeezing margin pools for non-integrated converters.
- Composting infrastructure gaps:Eco-friendly segments face structural constraint as municipal facilities lack capacity to process certified biodegradable absorbent cores at scale.
- Polyethylene backsheet substitution limits:Waterproof barrier alternatives with equivalent fluid containment performance remain commercially immature, locking most volume into fossil-derived films.
Strategic Opportunities
- Multi-pet household formation:United States residential patterns show sustained growth in homes with three or more companion animals, expanding addressable unit demand per customer.
- Direct-to-consumer fulfillment networks:Bypassing big-box retail gatekeepers allows private-label programs to capture margin previously allocated to slotting fees and promotional allowances.
- BPI and TÜV Austria certification pre-positioning:Early alignment with emerging biodegradable standards creates first-mover advantage if retail buyers adopt these schemes as sourcing filters.
Industry Challenges
- Thermal-bond line reconfiguration:Converting non-woven capacity from hygiene to pet-specific dimensions requires tooling investment and line downtime that private-label suppliers struggle to absorb.
- Antimicrobial additive compliance:FDA Center for Veterinary Medicine scrutiny of odor-control chemistry claims forces reformulation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Absorbent Pet Pad Market |
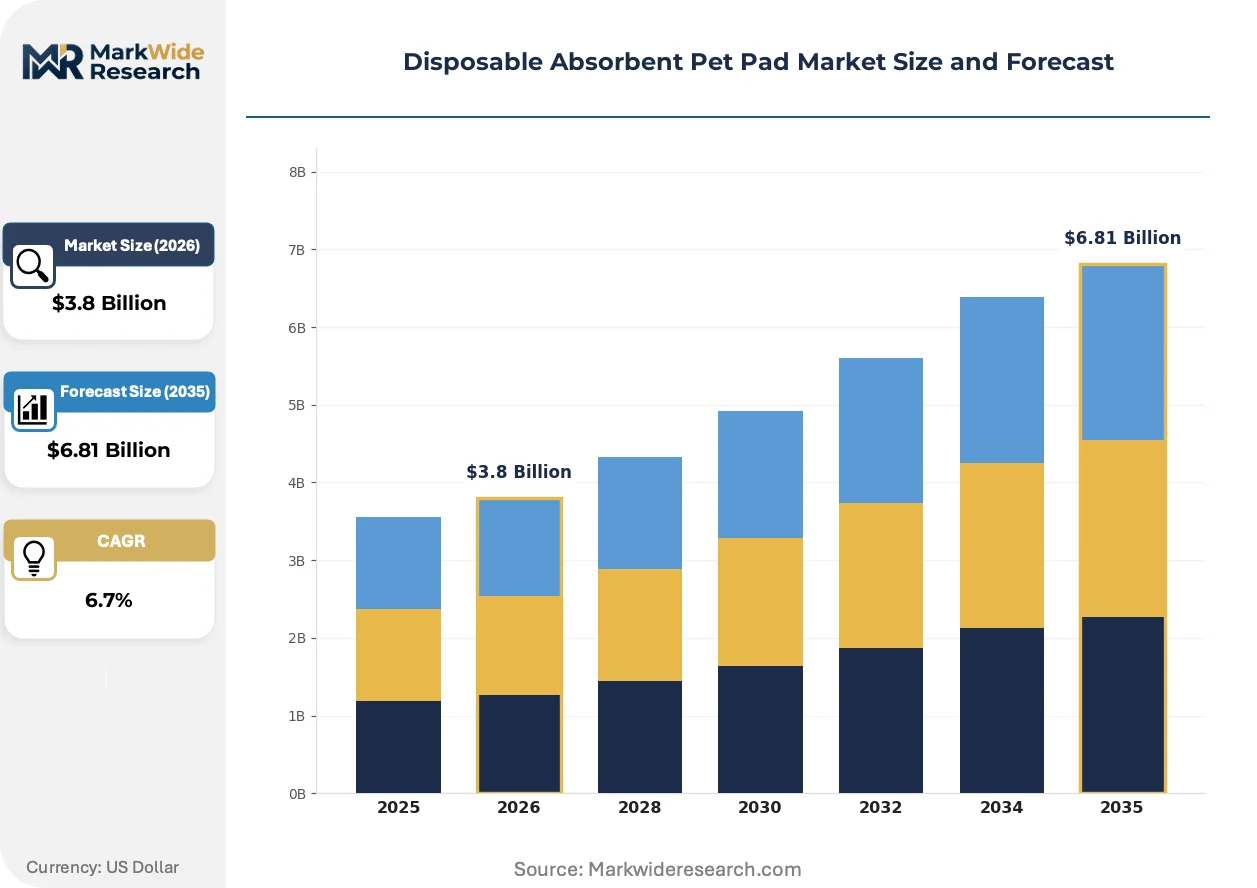
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Ultra Absorbent, Multi-Layer, Eco-Friendly Material: Disposable Non-Woven, Plastic, Cotton, Polymer Size: Small, Medium, Large, Extra Large End User: Pet Owners, Veterinarians, Pet Stores, Shelters |
| Companies Covered | Tianjin Yiyihygiene, Hartz (Unicharm), Jiangsu Zhongheng, DoggyMan, Richell, IRIS USA, U-PLAY, JiangXi SenCen, Four Paws, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Absorbent Pet Pad Market Trends and Innovations
Spunbond-meltblown-spunbond lamination advances are compressing the performance gap between standard and premium tiers while regulatory pressure on end-of-life disposal reshapes material selection priorities.
Plant-based superabsorbent polymers derived from cellulose and starch grafting are unifying sustainability positioning with functional performance in next-generation cores. Premium pet care retailers in the United States are piloting these materials for their private-label programs. The technology is unifying previously separate supply chains for biodegradable and conventional absorbent products, forcing converters to dual-source or commit to single-material strategies.
REACH restrictions on persistent organic pollutants are tightening specifications for adhesive chemistries used in hot-melt bonding layers across European supply chains. Manufacturers serving EU markets must reformulate or source alternative bonding systems to maintain market access. Veterinary clinic buyers in Germany and France are beginning to specify REACH-compliant pads in procurement tenders, transferring compliance burden upstream.
Subscription-based replenishment models are displacing episodic retail purchasing among urban multi-pet households. Direct-to-consumer channels capture recurring revenue streams that big-box partnerships cannot replicate. This pattern concentrates in coastal United States metropolitan markets where delivery density supports unit-economics viability.
Disposable Absorbent Pet Pad Market Segmentation
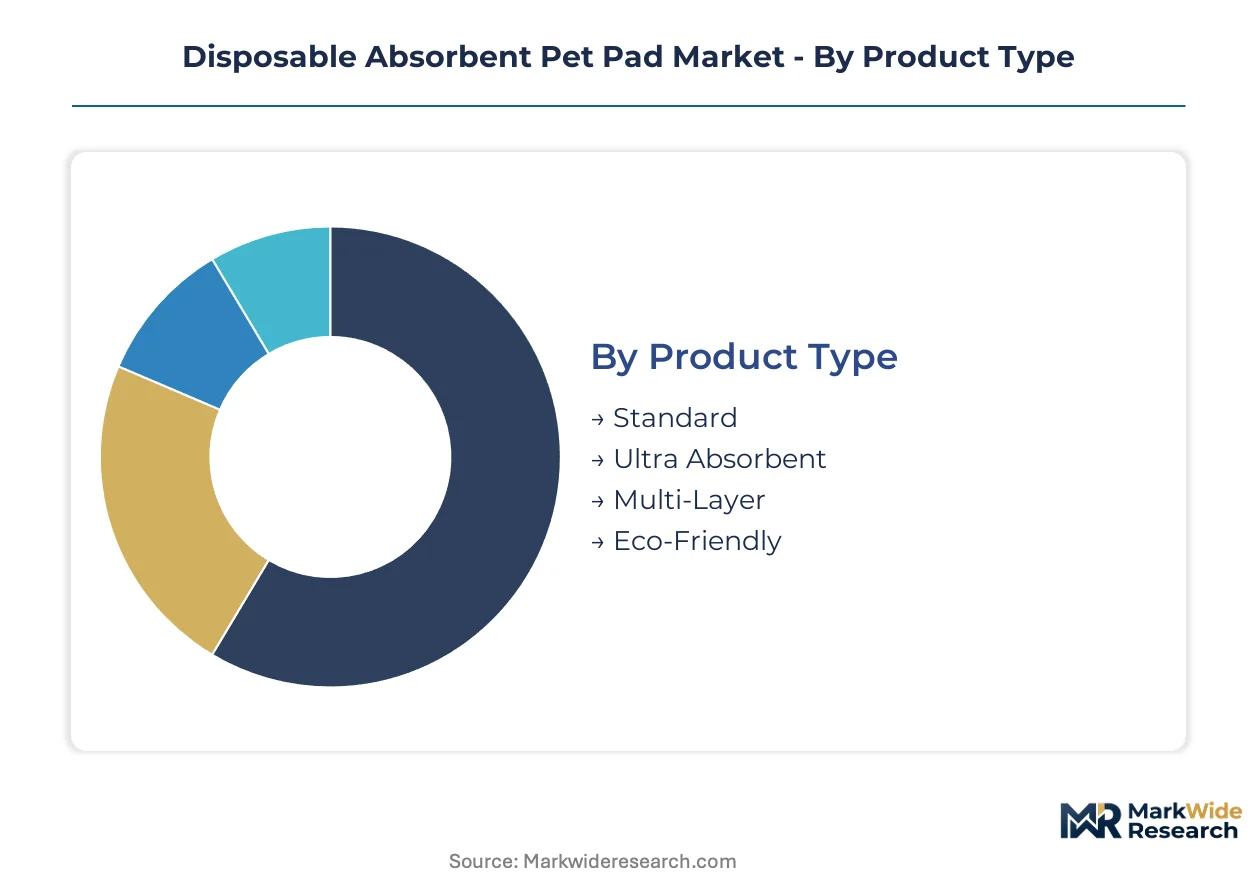
Product differentiation in disposable absorbent pet pads tracks closely to pet owner willingness to pay for performance tiers and disposal convenience. Manufacturers configure line equipment around segment-specific absorbency specifications and dimensional requirements.
Product Type:
Customization intensity spans from commodity standard pads to engineered multi-layer constructions with proprietary core formulations.
- Standard:Basic spunbond-meltblown-spunbond construction with moderate SAP loading targets price-sensitive bulk purchasers. Demand concentrates in municipal shelter systems and large-format pet retail where unit cost drives procurement decisions.
- Ultra Absorbent:Elevated superabsorbent polymer density and optimized fluid distribution layers command premium positioning. Veterinary clinics in the United States specify these variants for post-surgical recovery protocols where leakage prevention reduces bedding change frequency.
- Multi-Layer:Engineered stratification separates acquisition, distribution, and retention functions across distinct non-woven substrates.
- Eco-Friendly:Biodegradable certification pursuit and compostable backsheet alternatives attract sustainability-positioned retailers.
Most installed capacity flows through Standard. Expansion is steepest in Ultra Absorbent.
Material:
Cost tier alignment separates commodity petrochemical inputs from specialty fiber alternatives with certification premiums.
- Polymer:Superabsorbent polymer cores dominate functional performance with acrylic acid-derived sodium polyacrylate matrices. United States premium pet care channels absorb price volatility through brand equity transfer.
- Disposable Non-Woven:Thermal-bond and spunbond polypropylene top sheets provide fluid penetration control at scale. Jiangsu Zhongheng's throughput leadership in converted non-woven supply anchors private-label economics.
- Plastic:Polyethylene backsheet films deliver waterproof barrier performance with established converting infrastructure.
- Cotton:Natural fiber alternatives target allergen-sensitive pet owner segments with limited volume penetration.
Polymer captures the dominant share of material value. Cotton alternatives are gaining share fastest among certification-driven assortments.
Size:
Volume scale and margin profile diverge sharply across dimensional segments tied to animal species and multi-pet household configurations.
- Large:Optimized for medium-to-large breed canines with extended surface coverage and elevated fluid capacity. Multi-pet households in United States suburban markets drive repeat purchase velocity.
- Extra Large:Maximum dimensional formats serve giant breeds and multi-dog containment scenarios. Veterinary hospitals standardize on these formats for kennel recovery wards.
- Medium:Mid-range dimensions balance portability and coverage for single-pet urban apartments.
- Small:Compact formats target toy breeds, cats, and travel applications with reduced SAP loading.
Large formats absorb the majority of production line hours. Extra Large climbs the fastest as multi-pet household formation accelerates.
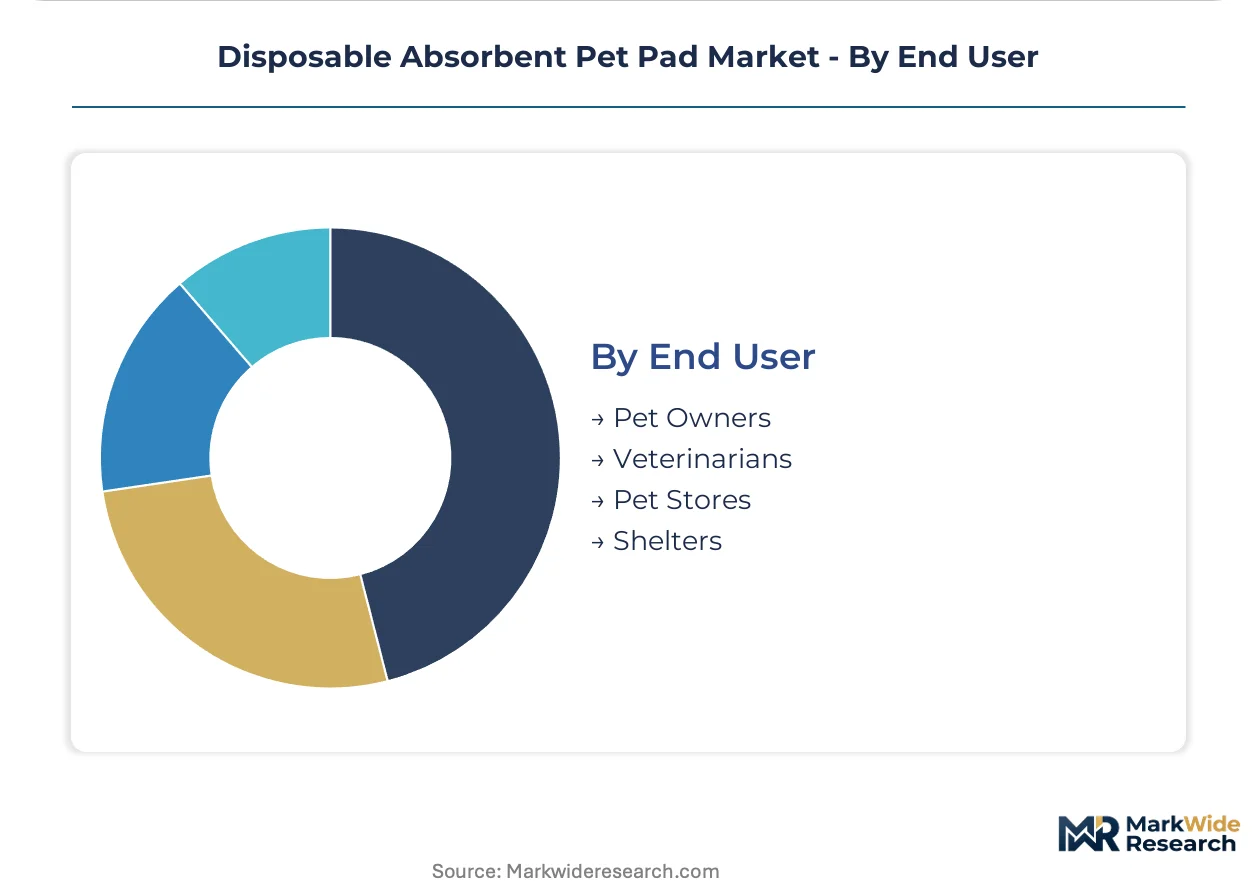
End User:
Customer type determines packaging configuration, purchase frequency, and regulatory exposure across the value chain.
- Pet Owners:Direct-to-consumer subscription models and big-box retail episodic purchasing dominate this fragmented base. Coastal United States metropolitan markets show highest subscription adoption.
- Veterinarians:Institutional procurement with standardized specifications and compliance documentation requirements. FDA Center for Veterinary Medicine oversight of antimicrobial claims shapes vendor qualification.
- Pet Stores:Assortment breadth requirements and private-label program participation drive converter relationships.
- Shelters:Volume purchasing with minimal performance differentiation and maximum unit economy constraints.
Veterinarians concentrate the highest value per transaction. Pet Owners are expanding most quickly through direct channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Osaka's polymer science infrastructure anchors functional material development for absorbent hygiene products across East Asian supply chains. Veterinary protocol standardization in developed markets and extended producer responsibility frameworks in North America reshape procurement patterns. Multi-pet household formation in suburban corridors drives dimensional requirements toward larger formats.
United States
Premium pet care spending and direct-to-consumer subscription adoption concentrate in coastal metropolitan markets. The EPA's emerging landfill leachate frameworks pressure manufacturers toward biodegradable core alternatives. Dallas-Fort Worth distribution clusters anchor big-box retail fulfillment networks serving multi-pet households.
China
Converted non-woven throughput leadership and thermal-bond line scale dominate private-label supply economics. The country's national environmental regulator advances circular economy targets affecting single-use product waste streams. Jiangsu province manufacturing corridors concentrate spunbond-meltblown-spunbond lamination capacity for export markets.
Japan
Parent-company R&D spillover from superabsorbent polymer infrastructure compresses development cycles for veterinary-grade variants. The Ministry of Economy, Trade and Industry influences industrial material standards for hygiene applications. Osaka technical centers transfer acrylic acid-derived polymer advances to pet pad specifications.
Germany
Veterinary clinic procurement tenders increasingly specify REACH-compliant adhesive chemistries in bonding layers. The European Chemicals Agency restrictions on persistent organic pollutants tighten hot-melt formulation requirements. Bavaria-based converters reformulate supply chains to maintain EU market access for certified products.
Canada
Animal hospital standardization of post-surgical recovery protocols creates institutional demand for ultra-absorbent variants. Health Canada and the Pest Management Regulatory Agency oversee antimicrobial additive claims in odor-control chemistry. Ontario distribution networks bridge US big-box retail and domestic veterinary procurement channels.
Disposable Absorbent Pet Pad Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable certification and direct-to-consumer channels. The market structures around three player tiers: integrated polymer suppliers with captive R&D infrastructure, specialized converters with thermal-bond line scale, and private-label assemblers serving retail gatekeepers. Strategic moves concentrate on backward integration into superabsorbent polymer supply and pre-positioning for extended producer responsibility compliance.
Among Asia-Pacific-based fabricators, Tianjin Yiyihygiene, Jiangsu Zhongheng, and JiangXi SenCen occupy positions within the high-throughput converter archetype. Hartz (Unicharm) exemplifies the integrated polymer science model through parent-company technical center access. IRIS USA anchors the North American distribution-focused tier through retail partnership and fulfillment network scale. These three archetypes represent the competitive structure without exhaustive player enumeration.
| Leading Market Players |
|---|
| Tianjin Yiyihygiene |
| Hartz (Unicharm) |
| Jiangsu Zhongheng |
| DoggyMan |
| Richell |
| IRIS USA |
| U-PLAY |
| JiangXi SenCen |
| Four Paws |
| Others |
Pricing and Supply Chain Analysis
Acrylic acid price volatility cascades through sodium polyacrylate procurement into tiered margin structures, with integrated polymer suppliers insulating premium positioning while converters absorb spot-market squeezes in standard-tier private-label programs.
Pricing Analysis
Input-cost pass-through from virgin superabsorbent polymer feedstock compresses margins for non-integrated converters serving municipal shelter systems and bulk retail channels. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-grade ultra-absorbent variants with elevated SAP loading from commodity spunbond-meltblown-spunbond constructions. Pricing pressure stems from propylene supply tightness and acrylic acid derivative costs, with standard-tier buyers exhibiting highest price sensitivity while veterinary clinics absorb premiums for protocol-standardized performance.
Supply Chain Analysis
Reverse-logistics flows remain underdeveloped for saturated pad collection, though California and New York extended producer responsibility proposals are forcing pilot infrastructure investments. Manufacturing gravity centers on China, Japan, and the United States, with Jiangsu province thermal-bond lines and Osaka polymer R&D hubs anchoring upstream capacity. Superabsorbent polymer cores, spunbond polypropylene top sheets, and polyethylene backsheet films constitute critical input dependencies. Single-source vulnerability concentrates in acrylic acid-derived sodium polyacrylate supply. Distribution runs through big-box retail partnerships and direct-to-consumer fulfillment networks serving coastal metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA landfill leachate frameworks and state-level extended producer responsibility mandates are accelerating capital allocation toward biodegradable core alternatives and collection infrastructure.
For Market Incumbents: Hedge against virgin SAP price cycle exposure through backward integration into captive polymer supply or long-term offtake agreements with acrylic acid producers. Accelerate BPI and TÜV Austria certification pre-positioning before retail buyers adopt these schemes as sourcing filters, defending margin pools from emerging biodegradable specialists.
For New Entrants and Emerging Players: Capture white-space opportunity in subscription-based direct-to-consumer channels serving urban multi-pet households with three or more companion animals. Target eco-friendly segments where composting infrastructure gaps have constrained incumbent investment, leveraging plant-based superabsorbent polymer pilots to differentiate from fossil-derived core incumbents.
For Investors and Strategic Acquirers: Asymmetric upside sits with thermal-bond line converters with scale sufficient to serve private-label programs across multiple retail gatekeepers. Long-term viability hinges on dual-sourcing capability for both conventional and biodegradable core materials. Monitor whether BPI or TÜV Austria certification achieves retail gatekeeping status as the inflection signal for non-polymer core transition economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Core Certification | BPI or TÜV Austria alignment creates first-mover advantage if retail buyers adopt filtering criteria. |
| Captive Polymer Supply Integration | Osaka technical center access insulates Hartz from virgin SAP price cycles compressing converter margins. |
| Direct-to-Consumer Fulfillment Scale | IRIS USA's subscription networks capture recurring revenue streams unavailable to big-box retail partnerships. |
| Thermal-Bond Line Reconfiguration | Jiangsu Zhongheng's throughput leadership anchors private-label economics for multi-pet household demand. |
| REACH-Compliant Adhesive Reformulation | Bavaria-based converters maintain EU market access as ECHA restrictions tighten hot-melt specifications. |
Research Methodology
Bottom-up veterinary clinic and pet owner demand modeling reconciled against top-down converter capacity and polymer supply tracking forms the analytical core. Primary interviews with procurement managers at animal hospitals, category buyers at big-box pet retailers, plant managers at thermal-bond line facilities, and R&D directors at superabsorbent polymer technical centers combined with secondary validation from EPA landfill framework documents, FDA Center for Veterinary Medicine guidance, state-level extended producer responsibility proposals, and customs records of spunbond-meltblown-spunbond lamination equipment imports.
Historical trendline analysis of absorbent hygiene product pricing and volume trajectories informed projection modeling across product type, material composition, dimensional format, and end-user segments. CAGRs derived from segment-level growth rate reconciliation against macro pet ownership demographics and regulatory implementation timelines. Veterinary protocol standardization intensity and multi-pet household formation patterns served as industry-specific demand inputs.
Underlying measurement precision varies by segment; ultra-absorbent and eco-friendly categories carry tighter precision than commodity standard pads due to concentrated buyer identification. Forecasts reflect documented assumptions regarding EPA framework finalization and state EPR adoption timelines. Practitioners should monitor biodegradable certification scheme retail adoption and composting infrastructure buildout for early signals of core material transition economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Cat Collar Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Smart Connected Pet Collar Market
Pet Care Products
Pet Tag Market
Pet Care Products
Pet Care Market
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
Dog Pad Market
Pet Care Products
Outdoor Pet Backpack Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Dog Carrier Bags Market
Pet Care Products
Large Breed Dog Food Market