
 Canned Dog Food Market | 2026-2036
Canned Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Dog Food Market Analytics
Market Context
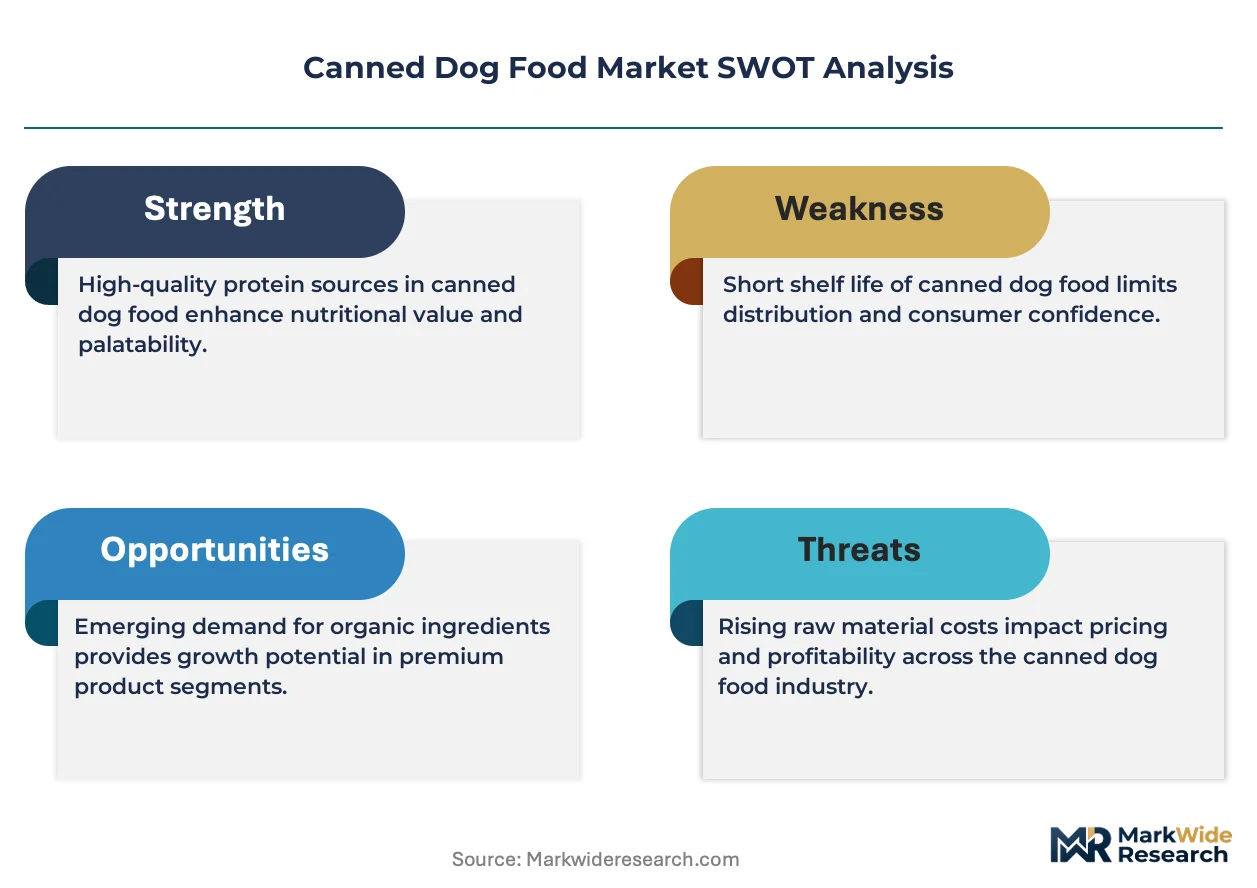
Pet specialty retail is narrowing as e-commerce platforms and veterinary clinics capture higher-margin canned formats. Mars, Incorporated leverages its global manufacturing footprint to sustain shelf presence across mass and premium channels. Nestlé Purina PetCare anchors its position through breed-specific formulations that command loyalty among discerning owners. Hill's Pet Nutrition, Inc. differentiates via prescription-grade canned diets distributed through veterinary networks.
Technical Definition and Segment Structure
Canned dog food denotes thermally processed, shelf-stable pet nutrition sealed in metal containers or alternative barrier packaging, typically achieving commercial sterility through retort processing at temperatures exceeding 116°C to ensure microbial elimination and extended ambient stability. The category serves industrial and commercial purposes by delivering complete canine nutrition with controlled moisture content, palatability enhancement, and precise caloric density for health management. Pâté and stew formulations lead volume contribution due to their texture versatility across breed sizes, while meat-based ingredient types capture the dominant margin pool as protein provenance becomes a primary purchase criterion. Small breed targeting exhibits the fastest structural expansion as urbanization concentrates dog ownership in compact living environments.
Regulatory Frame and Outlook
FDA Center for Veterinary Medicine enforces ingredient safety and labeling accuracy for canned dog food manufactured and distributed in the United States, while AAFCO establishes model nutritional adequacy profiles that most states adopt into feed control statutes. The USDA inspects facilities processing meat-derived ingredients under the Federal Meat Inspection Act, creating overlapping compliance obligations that elevate barriers for new entrants. Stakeholders must monitor evolving state-level raw material traceability mandates and emerging packaging sustainability directives that could reshape cost structures and sourcing decisions.
Market Dynamics
Pet humanization intensity in metropolitan United States is compressing purchase cycles and forcing manufacturers to retool formulation pipelines toward veterinary-grade positioning, while e-commerce logistics reshape channel economics.
Growth Catalysts
- Veterinary channel premiumization:Urban pet owners now demand prescription-aligned nutrition, driving specialty clinic distribution expansion.
- AAFCO nutritional adequacy protocols:Tightened formulation standards elevate barriers for commodity producers, concentrating margin with compliant manufacturers.
- Small breed urbanization:Compact living environments accelerate demand for portion-controlled, high-moisture formats.
Market Restraints
- Aluminum can cost volatility:Metal packaging input fluctuations compress margin stability for mid-tier producers.
- Midwest meat processing concentration:Supply of USDA-inspected protein inputs clusters geographically, creating disruption exposure.
- Retort processing capex thresholds:Commercial sterility equipment requirements block small-scale market entry.
Strategic Opportunities
- Subscription direct-to-consumer models:Recurring revenue platforms bypass traditional retail slotting fees.
- Sustainable packaging mandates:Emerging state-level circular economy directives favor alternative barrier material innovators.
- Raw material traceability integration:Blockchain-enabled supply chain verification commands price premiums in coastal metropolitan markets.
Industry Challenges
- Veterinary nutritionist talent scarcity:Formulation expertise gaps delay prescription-grade product development timelines.
- Multi-jurisdiction labeling compliance:Divergent state feed control statutes create SKU proliferation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Dog Food Market |
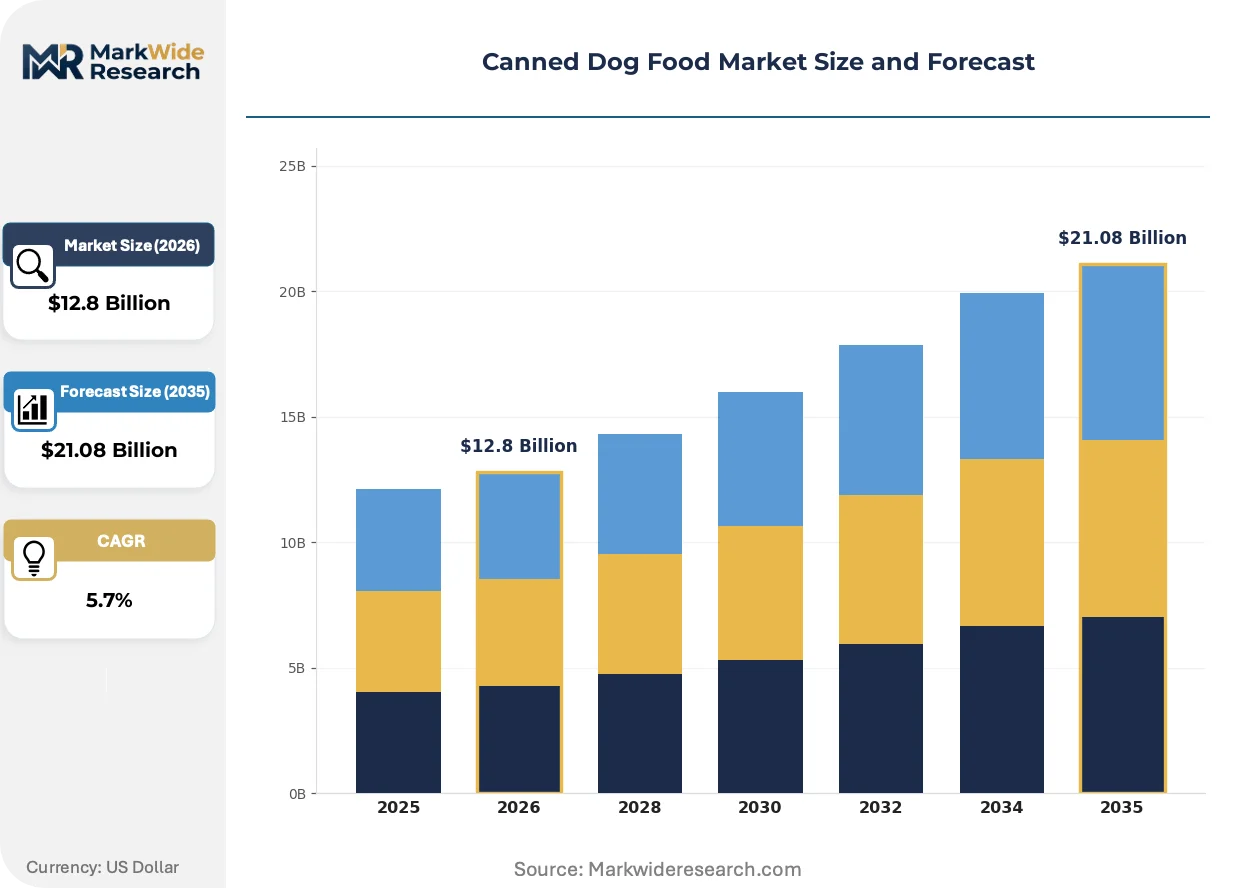
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Food, Stew, Pâté, Chunks Ingredient Type: Meat-Based, Vegetables, Grains, Fish-Based Target Size: Small Breed, Medium Breed, Large Breed, Giant Breed Packaging Type: Cans, Pouches, Tubs, Sachets |
| Companies Covered | Mars, Incorporated, Nestlé Purina PetCare, Hill's Pet Nutrition, Inc., The J.M. Smucker Company, General Mills, Inc., Spectrum Brands Holdings, Inc., WellPet LLC, Blue Buffalo Co., Ltd., Diamond Pet Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Dog Food Market Evolving Landscape
Thermal processing alternatives and digital supply chain tools are compressing traditional manufacturing advantages while reshaping how formulations reach end users.
High-pressure processing (HPP) technology preserves nutrient bioavailability without retort temperatures. Premium manufacturers in California and New York metropolitan corridors are adopting HPP at accelerating rates. This cold-pasteurization method is rendering obsolete the flavor degradation trade-offs that previously constrained high-moisture shelf-stable nutrition.
California's Proposition 12 implementation and pending FDA Center for Veterinary Medicine enforcement discretion updates are tightening cage-free and welfare-verified sourcing requirements. Protein ingredient procurement now requires documented supply chain audits. Breed-specific formulation lines face the steepest compliance cost escalation as they rely on specialized animal-derived inputs.
Subscription replenishment models now capture significant volume from mass retail channels. Urban millennial and Gen Z pet owners in Austin, Seattle, and Denver metros favor algorithm-driven portion customization over in-store assortment browsing. Veterinary clinics respond by launching proprietary auto-ship programs to defend patient retention against platform intermediation.
Canned Dog Food Market Segmentation
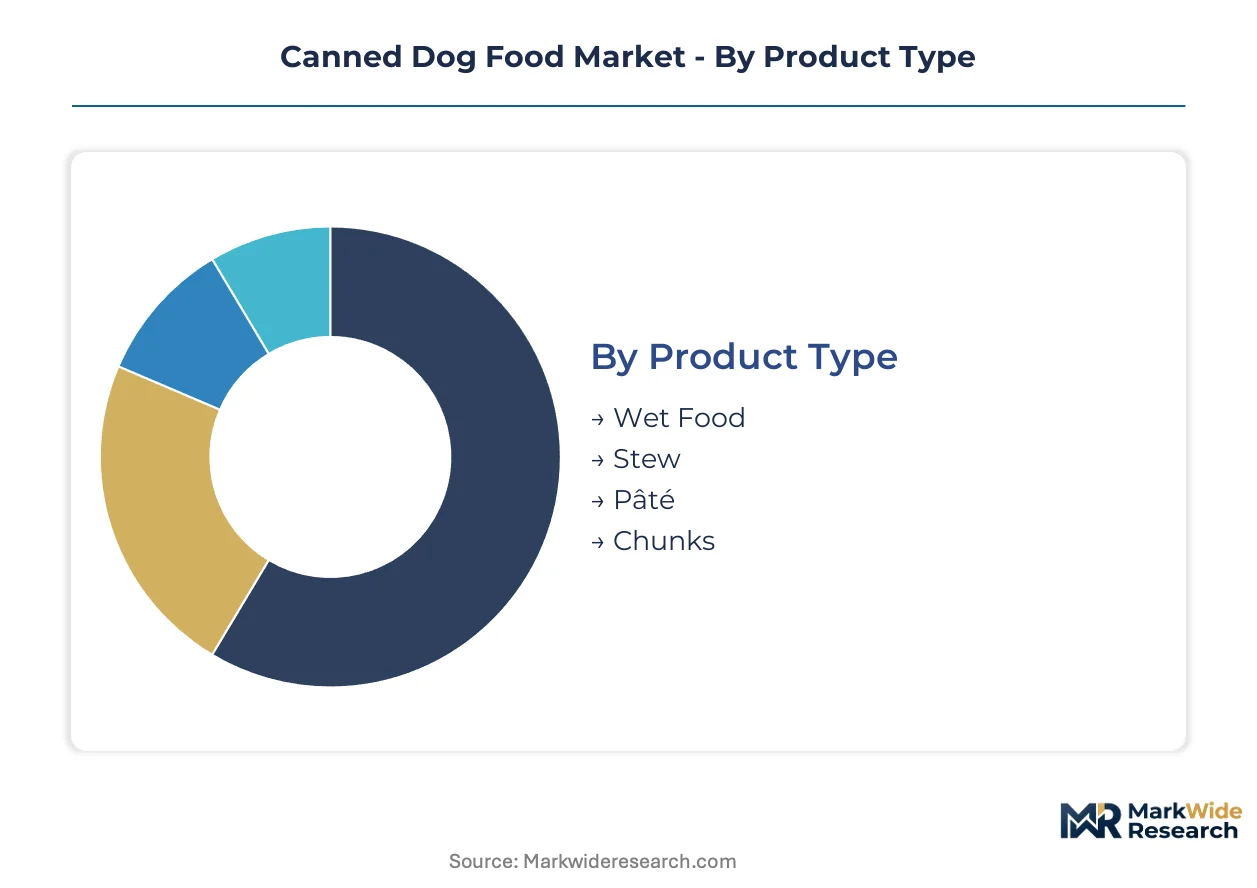
Segmentation in canned dog food determines formulation complexity, thermal processing requirements, and channel access. Manufacturers align production lines to specific texture profiles and breed-size caloric densities, while packaging format selection dictates distribution economics and shelf-life engineering.
Product Type:
After-sales intensity varies sharply across texture formats, with veterinary-directed lines requiring nutritional consultation support that commodity wet food avoids entirely.
- Pâté:Uniform emulsified texture achieves smooth consistency through fine particle size reduction and stabilizer integration. Demand concentrates in veterinary clinics and specialty retail across metropolitan United States, driven by palatability requirements for senior dogs and post-surgical recovery feeding.
- Stew:Visible meat and vegetable particulates suspended in gravy demand precise viscosity control and gentle retort protocols to maintain ingredient integrity. Growth accelerates in premium subscription channels serving urban millennial owners seeking human-grade visual cues.
- Wet Food:Standard moisture-rich formulations with homogenized texture serve mass-market volume requirements.
- Chunks:Discrete meat pieces in gel or gravy target larger breed owners prioritizing chewing satisfaction.
By volume, Wet Food leads. By growth pace, Stew is ahead.
Ingredient Type:
Cost tier stratification separates protein-forward premium positioning from carbohydrate-inclusive economy formulations.
- Meat-Based:USDA-inspected muscle tissue and organ meats deliver complete amino acid profiles with high biological value. Demand clusters in coastal metropolitan markets where pet humanization rates drive rejection of plant-primary alternatives.
- Fish-Based:Marine protein sources provide omega-3 fatty acid enrichment for dermatological and joint health positioning. Adoption concentrates in Pacific Northwest and Northeast corridors with established seafood processing infrastructure and consumer preference for novel proteins.
- Vegetables:Fiber and micronutrient supplementation supports digestive health claims in wellness-focused lines.
- Grains:Corn, wheat, and rice serve as cost-controlled carbohydrate bases for price-sensitive mass channels.
Meat-Based commands the dominant revenue share. Fish-Based is expanding most quickly in premium positioning.
Target Size:
Application-specific formulation scales nutrient density and kcal per ounce to metabolic requirements across canine body mass ranges.
- Small Breed:Concentrated caloric density in reduced portion sizes addresses elevated metabolic rates and dental constraints. Demand surges in urban apartment markets from New York to Los Angeles where space limitations concentrate toy and small breed ownership.
- Large Breed:Controlled calcium and phosphorus ratios support orthopedic development in growing dogs. Growth concentrates in suburban family households prioritizing joint health maintenance through extended lifespans.
- Medium Breed:Flexible formulation specifications serve the broadest owner demographic with standard nutritional profiles.
- Giant Breed:Specialized growth-rate management protocols reduce developmental orthopedic disease risk in breeds exceeding 100 pounds.
Medium Breed generates the highest absolute volume. Small Breed is gaining share fastest through urbanization tailwinds.
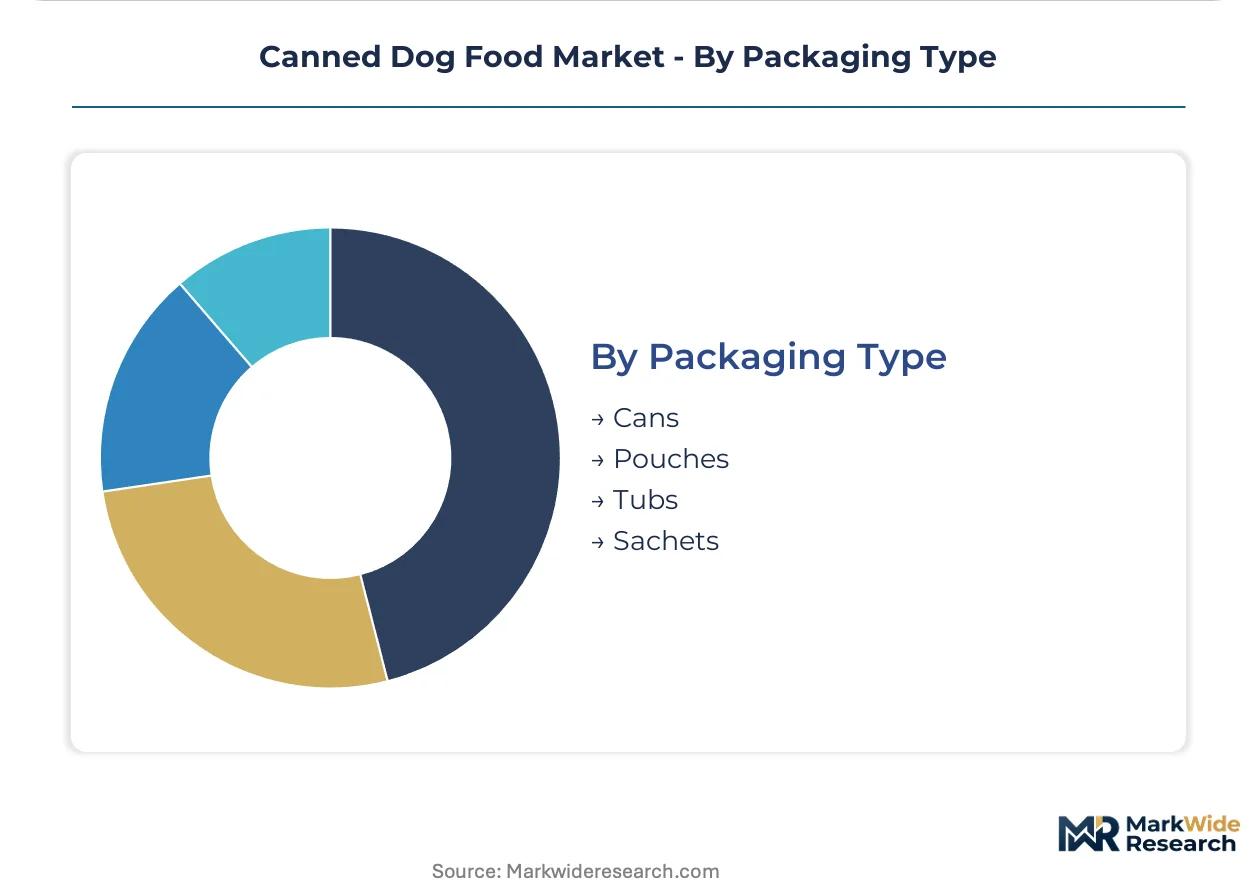
Packaging Type:
Customer type and purchase occasion dictate barrier material selection, with convenience-seeking subscribers favoring flexible formats over traditional metal.
- Cans:Aluminum and steel containers deliver maximum shelf stability through hermetic sealing and retort compatibility. Volume concentrates in mass retail and veterinary clinics where established supply chains and consumer familiarity sustain dominance.
- Pouches:Multi-layer flexible films reduce shipping weight and storage footprint while enabling single-serve portioning. Adoption accelerates in direct-to-consumer subscription models serving space-constrained urban apartments.
- Tubs:Rigid plastic containers with resealable lids target multi-meal usage in medium and large breed households.
- Sachets:Ultra-lightweight portion packs serve trial-size sampling and travel-oriented purchase occasions.
Cans retain volume leadership. Pouches show the steepest expansion trajectory in digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors North American distribution for imported protein inputs, while Rotterdam's pet food processing cluster underwrites European supply security through integrated cold-chain infrastructure.
United States
Metropolitan pet humanization concentrates demand in New York, Los Angeles, and Chicago corridors where veterinary clinic networks expand prescription-grade offerings. FDA Center for Veterinary Medicine enforces nutritional adequacy protocols that elevate compliance costs for imported formulations. Austin and Denver metro areas drive subscription channel growth through millennial and Gen Z ownership clusters.
Germany
Specialty retail consolidation in Munich and Hamburg sustains premium wet food demand despite e-commerce displacement pressure. EFSA guidelines on animal-derived ingredient safety create harmonized standards across EU member states, reducing cross-border friction. The Baden-Württemberg industrial belt hosts concentrated co-manufacturing capacity serving private-label brands.
United Kingdom
London and Southeast England exhibit elevated small-breed ownership rates that accelerate portion-controlled format adoption. Post-Brexit UK REACH adaptations impose divergent chemical safety assessments on packaging materials. The Midlands manufacturing corridor retains retort processing infrastructure serving both domestic and Irish export markets.
Japan
Tokyo and Osaka metropolitan areas sustain super-premium positioning through aging pet demographics and extended canine lifespans. METI's sustainable packaging directives accelerate aluminum alternative trials among domestic processors. The Chubu region's Nagoya industrial zone concentrates barrier film innovation for single-serve pouch formats.
Australia
Sydney and Melbourne coastal markets drive marine-protein formulation demand through established seafood processing infrastructure. TGA-aligned import inspection protocols for animal-derived ingredients create non-tariff barriers for non-ANZ suppliers. Queensland's protein rendering cluster supplies domestic canned manufacturers with welfare-verified inputs.
Canned Dog Food Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational conglomerates with veterinary channel dominance, mid-scale specialists with subscription-native positioning, and private-label co-manufacturers serving retail banners. Vertically integrated protein sourcing and prescription-grade formulation expertise constitute the primary competitive moats. Capacity expansion through retort line automation and strategic partnerships with veterinary clinic networks represent the dominant competitive moves reshaping market access.
Within the multinational tier, Mars, Incorporated and Nestlé Purina PetCare occupy positions defined by global manufacturing scale and mass-premium portfolio breadth. Hill's Pet Nutrition, Inc. exemplifies the veterinary-exclusive archetype through prescription-grade distribution networks. These three entities anchor competitive dynamics through divergent channel strategies rather than direct product confrontation.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition, Inc. |
| The J.M. Smucker Company |
| General Mills, Inc. |
| Spectrum Brands Holdings, Inc. |
| WellPet LLC |
| Blue Buffalo Co., Ltd. |
| Diamond Pet Foods |
| Others |
Value Network & Pricing Analysis
Midwest meat processing concentration in USDA-inspected facilities anchors protein input costs, concentrating margin capture with manufacturers commanding backward integration into rendering and cold-chain logistics. Aluminum can volatility and retort processing capex thresholds stratify pricing power across tiered manufacturer scale.
Pricing Analysis
Volume-discount tiering structures separate veterinary-grade prescription lines from mass-market commodity formats, with certification-aligned AAFCO nutritional adequacy and breed-specific formulation commanding premium positioning. Price differentiation rests on protein provenance documentation and veterinary consultation bundling. Pricing pressure stems from aluminum input volatility compressing mid-tier margins. Mass-channel buyers exhibit highest price sensitivity; veterinary-direct purchasers show lowest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration sits with Midwest co-packers serving private-label retail banners and specialty veterinary formulators. Protein supply draws from USDA-inspected Midwest rendering clusters and Pacific Northwest seafood processing infrastructure. Raw material dependencies center on cage-free poultry, welfare-verified beef, and marine protein inputs. Single-source vulnerability concentrates in aluminum can sheet supply. Distribution runs through veterinary clinic networks, mass retail DCs, and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canned dog food operates as a service-attach opportunity where subscription auto-ship programs and veterinary consultation bundling expand recurring revenue faster than transactional can sales alone.
For Market Incumbents: Build prescription-grade formulation moats through captive veterinary nutritionist teams and AAFCO-compliant pilot facilities. Mars and Nestlé Purina should deepen backward integration into protein rendering to defend margin against Midwest supply disruption. Hill's Pet Nutrition must expand proprietary clinic auto-ship platforms before platform intermediaries capture patient retention.
For New Entrants and Emerging Players: Pursue white-space in sustainable pouch formats for urban subscription channels, where space-constrained millennial owners in Austin and Denver metros show lowest incumbent loyalty. Target fish-based premium positioning in Pacific Northwest corridors with established seafood processing infrastructure. Launch algorithm-driven portion customization as primary go-to-market wedge.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale specialists holding subscription-native positioning and HPP technology adoption. Long-term viability favors manufacturers integrating raw material traceability verification and veterinary channel access. Monitor FDA enforcement discretion updates on cage-free sourcing as inflection signal for compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Expansion | Prescription-grade distribution through AAFCO-compliant clinic networks captures highest-margin recurring revenue pools. |
| High-Pressure Processing Adoption | Cold-pasteurization HPP technology in California and New York metros eliminates nutrient degradation trade-offs. |
| Subscription Platform Launch | Algorithm-driven auto-ship models bypass retail slotting fees and capture urban millennial ownership clusters. |
| Sustainable Packaging Transition | Multi-layer flexible pouches respond to California circular economy mandates and reduce shipping weight. |
| Raw Material Traceability Integration | Blockchain-enabled supply chain verification commands price premiums in coastal metropolitan markets. |
Research Methodology
A spread of perspectives from veterinary nutritionists, pet specialty retail buyers, co-manufacturing operations managers, and FDA regulatory affairs specialists converged on the working assumptions. Primary interviews with formulation scientists and cold-chain logistics providers combined with secondary validation from AAFCO model regulations, USDA facility inspection records, and Nielsen retail audit data. Bottom-up SKU-level volume builds triangulated against top-down manufacturer capacity assessments.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include texture format, protein source type, breed size targeting, packaging material, and channel distribution mode. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated veterinary clinic network expansion rates and metropolitan pet humanization indices.
Macroeconomic conditions sit as an overlay; deviation in aluminum commodity pricing and Midwest protein processing capacity utilization would shift the trajectory. Forecasts reflect documented assumptions on AAFCO protocol adoption timing and state-level packaging sustainability mandate implementation. Quarterly review of veterinary channel prescription volume and HPP equipment installation permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Parrot Cage Market
Pet Care Products
Cat Litter Boxes Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Cat Scratchers and Trees Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Global Pet Carriers Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Australia Pet Food Market
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
Elevated Dog Bowls Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Asia Pacific Dog Food Market