
 Pet Daycare Market | 2026-2036
Pet Daycare Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Daycare Market Outlook
The gap between premium and commodity tiers is expanding as luxury boarding facilities with webcam monitoring and personalized play programs command premium pricing while basic home-based operators compete on proximity and cost. Dogtopia Enterprises leverages its franchise network to sustain national coverage across North American urban centers. PetSmart LLC anchors its position through co-location with retail veterinary and grooming services in high-traffic commercial corridors. Rover.com competes via its digital marketplace model that connects pet owners with vetted independent caregivers.
Pet daycare encompasses supervised daytime care, overnight boarding, behavioral training, and hygiene grooming services delivered through licensed facilities or certified in-home providers, typically requiring staff ratios of one handler per ten to fifteen dogs and climate-controlled environments with designated rest zones. The primary commercial purpose centers on enabling pet owners to maintain employment and travel schedules while ensuring animal welfare and socialization. Daycare services dominate transaction volume due to recurring weekly usage patterns among working professionals, while luxury boarding captures disproportionate margin pools from extended-stay and holiday demand. Home-based facilities represent the fastest-growing facility type as low overhead and neighborhood accessibility attract solo entrepreneurs entering the market.
FDA guidelines on pet food safety and sanitation intersect with state-level Department of Agriculture kennel licensing and local animal control ordinances to shape operational compliance costs and facility design standards across the United States. OSHA workplace safety rules and municipal zoning boards further constrain site selection and staffing models for brick-and-mortar operators. Stakeholders must monitor evolving definitions of pet custody and emotional support animal classifications that could expand liability frameworks and insurance requirements for service providers.
Market Dynamics
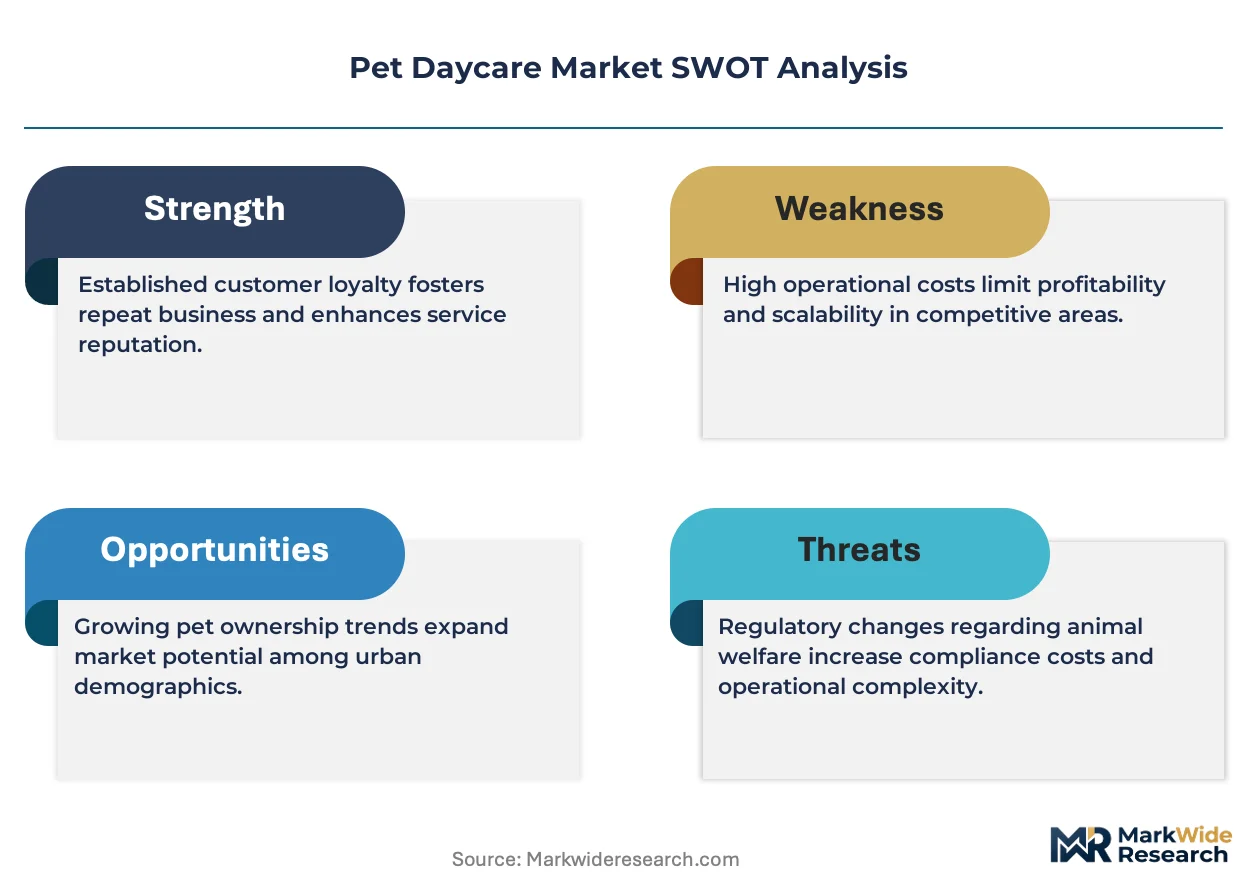
Urban dual-income households intensify demand pressure on licensed facilities while municipal zoning ordinances tighten site availability and operational standards across metropolitan corridors.
Growth Catalysts
- Pet Humanization Trajectory:Emotional attachment patterns among working professionals drive recurring weekly daycare bookings and premium service upgrades.
- OSHA Workplace Safety Alignment:Standardized handler protocols reduce liability exposure and enable franchise scalability across state lines.
- Metropolitan Density Concentration:High pet ownership rates combined with limited residential square footage create captive demand in urban cores.
Market Restraints
- Labor Cost Escalation:Mandatory staff ratios of one handler per ten to fifteen dogs compress margins during wage inflation cycles.
- Real Estate Scarcity:Municipal zoning boards restrict facility placement to industrial corridors distant from residential demand clusters.
- Climate Control Infrastructure:Year-round HVAC requirements for designated rest zones impose fixed overhead regardless of seasonal occupancy.
Strategic Opportunities
- Home-Based Facility Expansion:Solo entrepreneurs exploit neighborhood accessibility and lower overhead to capture proximity-sensitive demand.
- Behavioral Training Bundling:Integration of obedience programs creates stickier customer relationships and higher per-visit revenue.
- Webcam Monitoring Services:Real-time visual access commands subscription premiums from anxious pet owners during work hours.
Industry Challenges
- Veterinary Technician Recruitment:Licensed animal health professionals command wages that small operators struggle to match.
- Multi-Jurisdictional Licensing:State-level Department of Agriculture kennel requirements vary, complicating franchise standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Daycare Market |
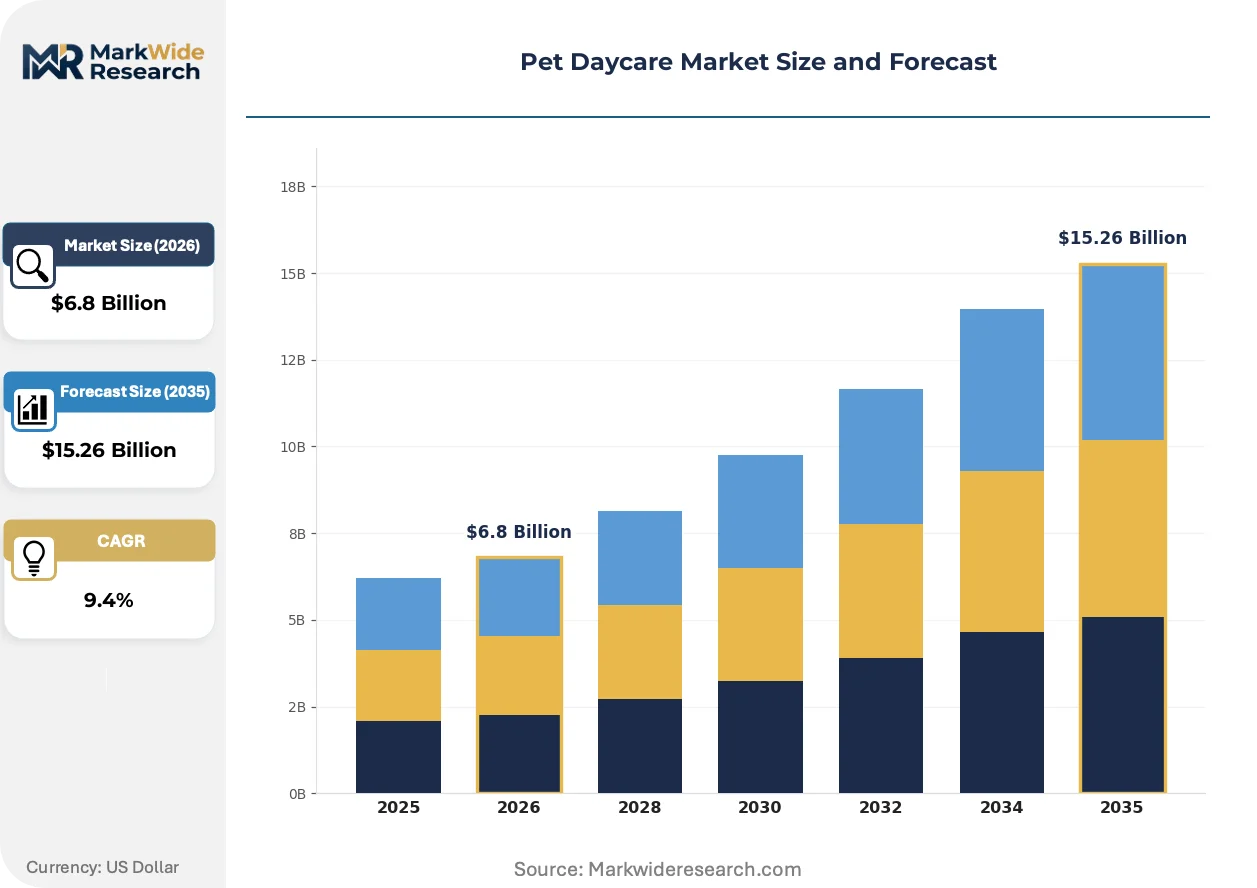
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Daycare, Boarding, Training, Grooming Animal Type: Dogs, Cats, Birds, Rabbits Facility Type: Indoor Facility, Outdoor Facility, Home-Based, Luxury Boarding Customer Segment: Pet Owners, Breeders, Veterinary Clinics, Shelters |
| Companies Covered | PetSmart LLC, Rover.com (A Place for Rover, Inc.), Dogtopia Enterprises, Propelled Brands (Camp Bow Wow), Best Friends Pet Care, Paradise 4 Paws, LLC, Fetch! Pet Care, Come Sit Stay, Wag Hotels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Daycare Market Strategic Shifts
Facility operators deploy sensor networks and automation to reduce labor dependency while regulatory bodies tighten welfare standards.
Live video streaming infrastructure is integrating into standard facility builds. Premium boarding operators deploy cloud-connected camera arrays accessible through mobile applications. This capability is integrating remote oversight as a baseline expectation, compressing differentiation timelines for laggard facilities.
Local animal control ordinances in municipalities across the United States, Germany, and Japan mandate enhanced ventilation and surface sanitation protocols. Facility redesign costs concentrate in legacy buildings lacking modern HVAC infrastructure. Urban operators in Tokyo and Los Angeles respond by prioritizing new construction over retrofitting.
Subscription-based membership models displace transactional day-rate structures among working professionals. Corporate benefits programs now include pet daycare allowances, redirecting individual purchasing decisions through employer channels. This pattern concentrates in technology sector employment clusters where remote-work hybrid schedules create irregular but consistent demand.
Pet Daycare Market Segmentation
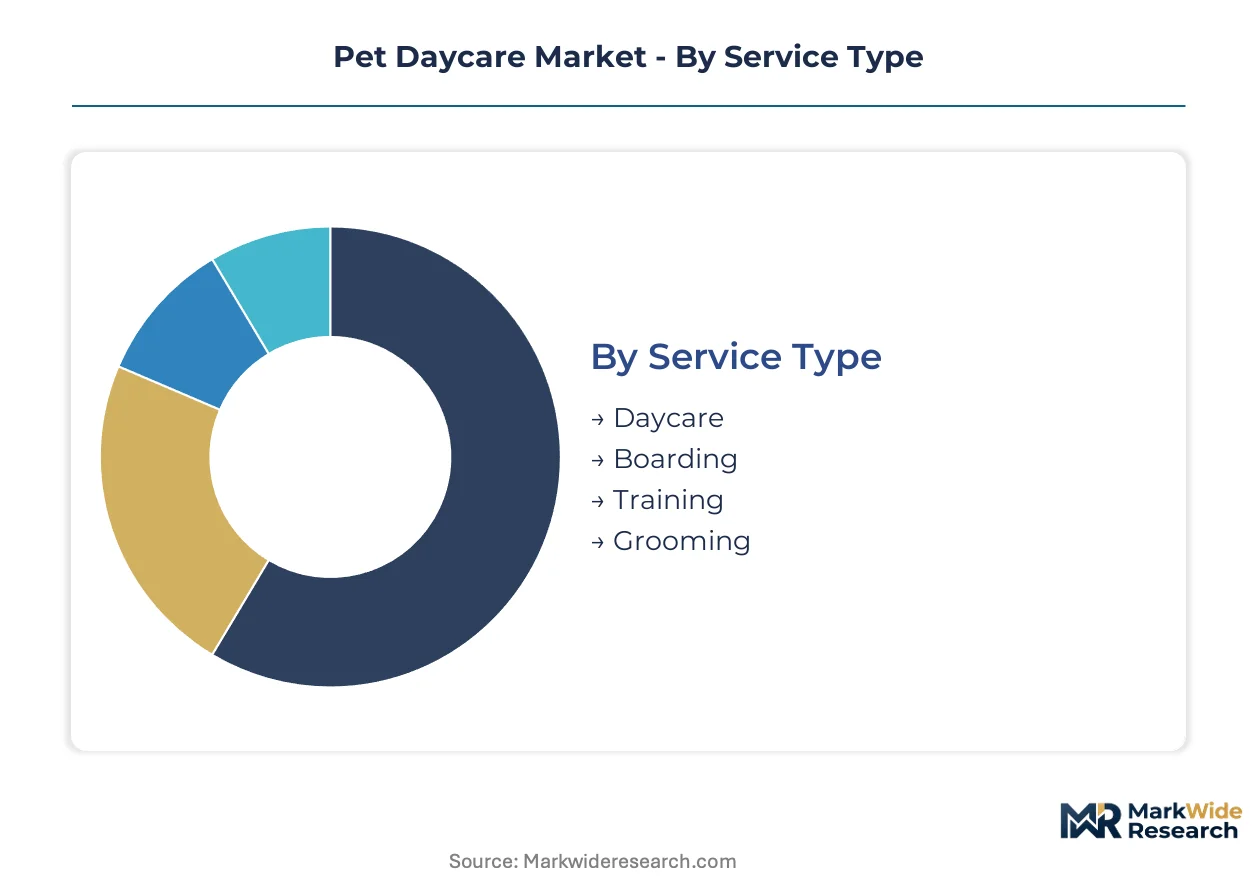
Service differentiation and facility economics create distinct competitive arenas within pet daycare. Each segmentation dimension reveals divergent margin structures, capital requirements, and regulatory exposure that shape operator strategy.
Service Type:
Recurring frequency and per-session duration separate profitable service lines from marginal revenue streams.
- Daycare:Supervised daytime supervision with structured play sessions and rest rotations. Urban dual-income households in Tokyo and Los Angeles drive weekly recurring bookings; OSHA-aligned handler protocols enable franchise standardization across state lines.
- Boarding:Overnight accommodation with extended supervision periods and feeding routines. Holiday travel peaks in metropolitan corridors generate disproportionate margin pools; climate-controlled kennel infrastructure imposes fixed overhead regardless of seasonal occupancy swings.
- Training:Behavioral modification and obedience instruction delivered by certified specialists.
- Grooming:Hygiene maintenance including bathing, coat trimming, and nail care.
Daycare leads volumes today; boarding is gaining share fastest.
Animal Type:
Species-specific handling protocols and facility design requirements fragment operational capabilities.
- Dogs:Canine care dominates facility capacity planning with mandated staff ratios of one handler per ten to fifteen animals. Municipal zoning in Germany and Japan restricts dog daycare placement to industrial corridors distant from residential clusters.
- Cats:Feline boarding requires separate ventilation systems and reduced noise environments. Tokyo operators report climbing demand for cat-exclusive facilities as apartment-dwelling professionals seek holiday care solutions.
- Birds:Avian care demands specialized climate control and noise isolation.
- Rabbits:Small mammal supervision requires predator-separation protocols and dietary precision.
Dogs anchor revenue today; cats are expanding most quickly.
Facility Type:
Capital intensity and real estate access determine which facility models survive in constrained urban markets.
- Home-Based:Residential conversion with neighborhood accessibility and minimal overhead. Solo entrepreneurs across the United States exploit lower entry barriers to capture proximity-sensitive demand; local animal control ordinances vary by municipality, complicating licensing standardization.
- Luxury Boarding:Premium facilities with webcam monitoring, personalized play programs, and spa services. Cloud-connected camera arrays accessible through mobile applications command subscription premiums from anxious pet owners during work hours.
- Indoor Facility:Purpose-built climate-controlled environments with designated rest zones.
- Outdoor Facility:Open-air exercise compounds with weather protection infrastructure.
Indoor facilities lead volumes today; home-based operations are climbing the fastest.
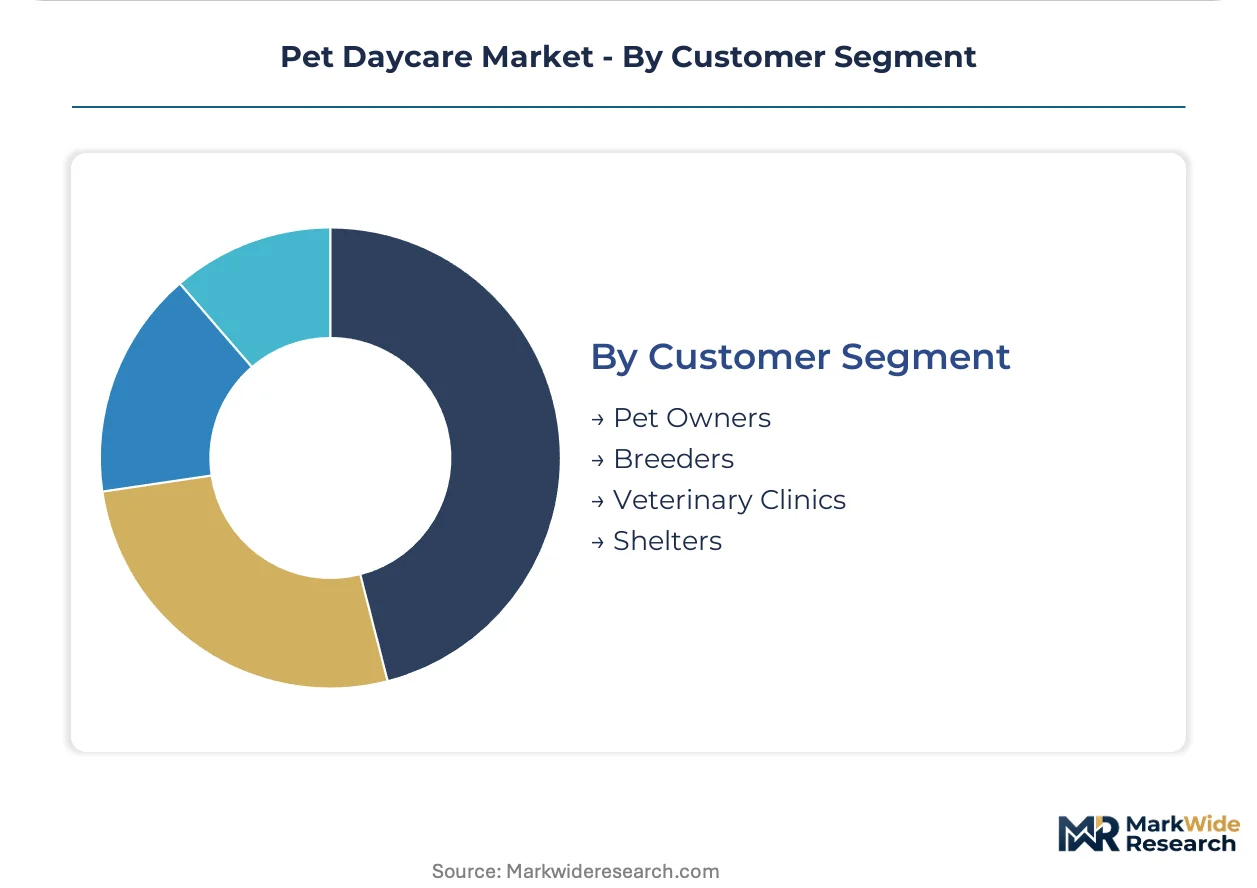
Customer Segment:
Purchasing authority and volume predictability separate stable revenue bases from transactional demand.
- Pet Owners:Individual households booking services directly. Corporate benefits programs in technology sector employment clusters now include pet daycare allowances, redirecting individual purchasing decisions through employer channels.
- Veterinary Clinics:Referral partnerships and post-operative care arrangements. Licensed animal health professionals command wages that small operators struggle to match, constraining partnership scalability.
- Breeders:Commercial breeding operations requiring temporary holding and socialization services.
- Shelters:Municipal and nonprofit organizations needing overflow capacity and behavioral rehabilitation.
Pet owners dominate revenue today; veterinary clinic partnerships are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban dual-income households in Japan generate higher per-capita daycare utilization than their counterparts in Germany, though both markets face tightening municipal zoning constraints that compress facility availability in residential corridors.
United States
Corporate benefits programs at technology sector employers in Seattle and Austin now include pet daycare allowances, redirecting individual purchasing decisions through employer channels. OSHA workplace safety rules and state-level Department of Agriculture kennel licensing requirements shape operational compliance costs across jurisdictions. Los Angeles operators prioritize new construction over retrofitting legacy buildings lacking modern HVAC infrastructure mandated by local animal control ordinances.
Germany
Metropolitan density in Berlin and Munich combines with limited residential square footage to create captive demand for supervised daytime care services. Municipal zoning boards restrict facility placement to industrial corridors distant from residential demand clusters, tightening site availability. KBA transport safety protocols intersect with local animal welfare licensing requirements to elevate facility design standards and operational compliance costs.
Japan
Apartment-dwelling professionals in Tokyo drive climbing demand for cat-exclusive facilities as holiday care solutions for feline companions. METI industrial standards and local animal control ordinances mandate enhanced ventilation and surface sanitation protocols across facility types. Urban operators in Tokyo respond to regulatory pressure by prioritizing new construction over retrofitting aging building stock.
United Kingdom
Remote-work hybrid schedules in London and Manchester technology clusters create irregular but consistent demand patterns for flexible daycare booking structures. The country's national animal welfare regulator enforces kennel licensing requirements that vary by municipality, complicating franchise standardization efforts. Greater London operators exploit neighborhood accessibility through home-based facility conversions to capture proximity-sensitive demand segments.
Australia
High pet ownership rates in Sydney and Melbourne combine with subtropical climate conditions to elevate year-round HVAC requirements for designated rest zones. TGA veterinary product regulations intersect with state-level animal welfare licensing to shape operational compliance frameworks. New South Wales operators deploy sensor networks and automation to reduce labor dependency while meeting tightening welfare standards.
Pet Daycare Market Competitive Environment
Top-tier vendors anchor premium facility networks with integrated veterinary and grooming services, while home-based independent operators compete on neighborhood proximity and cost structures. The market exhibits tiered fragmentation with franchise systems, corporate retail chains, and digital marketplaces occupying distinct competitive spaces. Three strategic archetypes dominate: facility-based operators with co-located services, asset-light digital platforms connecting owners with caregivers, and home-based solo entrepreneurs exploiting low entry barriers. Competitive moves concentrate on geographic expansion through franchise development and technology integration for remote monitoring capabilities.
Within the franchise-system tier, Dogtopia Enterprises and Propelled Brands exemplify scalable facility networks with standardized handler protocols enabling cross-state operations. Among digital marketplace operators, Rover.com occupies a position representing the asset-light platform model that connects pet owners with vetted independent caregivers without captive facility investment. PetSmart LLC anchors the corporate retail chain archetype through co-location strategies in high-traffic commercial corridors.
| Leading Market Players |
|---|
| PetSmart LLC |
| Rover.com (A Place for Rover, Inc.) |
| Dogtopia Enterprises |
| Propelled Brands (Camp Bow Wow) |
| Best Friends Pet Care |
| Paradise 4 Paws, LLC |
| Fetch! Pet Care |
| Come Sit Stay |
| Wag Hotels |
| Others |
Value Chain & Pricing Dynamics
Commercial real estate price indices in metropolitan corridors cascade through facility economics to stratify service tiers across the pet daycare market. Zoning-constrained land costs in Tokyo, Los Angeles, and Berlin compress margins for brick-and-mortar operators while amplifying pricing power for home-based entrants with minimal overhead.
Pricing Analysis
Capacity additions in home-based facilities across United States residential neighborhoods are reshaping price floors for standard daycare services. Three-tier pricing structure across premium, standard, and economy levels dominates the market, with differentiation driven by staff-to-animal ratios and webcam integration depth. Cost compression in the economy tier is intensifying because solo entrepreneurs undercut franchise overhead structures. Corporate benefits recipients show lowest price sensitivity; budget-conscious individual pet owners exhibit highest elasticity.
Supply Chain Analysis
Local animal welfare licensing mandates in municipalities across Germany, Japan, and the United States are reshaping sourcing requirements for facility infrastructure and equipment. Supply concentrates in China for HVAC components, the United States for specialized kennel manufacturing, and Germany for precision ventilation systems. Raw material dependencies include climate-control equipment, antimicrobial surface materials, and cloud-connected camera arrays. Single-source vulnerability sits with specialized veterinary-grade HVAC suppliers. Distribution runs through regional equipment distributors serving franchise networks and independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet daycare market functions as a stable compounder anchored by irreversible pet humanization trends among urban dual-income households. Recurring subscription revenue and employer-sponsored benefits create defensive cash flow characteristics.
For Market Incumbents: Anchor market position through co-location density in high-traffic commercial corridors and backward integration into captive veterinary services. Franchise standardization across state lines defends against home-based entrants exploiting licensing arbitrage. OSHA-aligned handler protocols enable scalable replication while regulatory compliance costs burden smaller competitors.
For New Entrants and Emerging Players: Enter via cat-exclusive facilities in Tokyo and other dense Asian metropolitan markets where apartment-dwelling professionals generate underserved demand. Home-based conversions in Greater London and Australian suburbs offer lowest capital barriers. Corporate benefits program integration provides sticky customer acquisition channel.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional franchise systems possessing multi-jurisdictional licensing expertise and proven unit economics. Five-to-ten-year viability hinges on regulatory compliance capabilities rather than price competition. Watch municipal zoning liberalization in residential corridors as inflection signal for brick-and-mortar expansion viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Franchise Network Expansion | Dogtopia Enterprises leverages standardized OSHA protocols to replicate units across state lines. |
| Corporate Benefits Integration | Employer-sponsored pet daycare allowances redirect purchasing decisions through Seattle technology clusters. |
| Home-Based Facility Conversion | Solo entrepreneurs exploit neighborhood accessibility to capture proximity-sensitive demand segments. |
| Webcam Infrastructure Deployment | Cloud-connected camera arrays command subscription premiums from anxious pet owners during work hours. |
| Cat-Exclusive Facility Development | Tokyo operators address climbing demand from apartment-dwelling professionals seeking holiday care solutions. |
Study Parameters
Multiple input streams — facility operator interviews, municipal licensing database reviews, and corporate benefits program filings — were reconciled to construct market estimates. Primary discussions with franchise development executives, animal welfare licensing officers, veterinary clinic partnership managers, and employer benefits administrators informed operational economics and demand drivers. Secondary validation drew from OSHA workplace safety filings, state Department of Agriculture kennel licensing records, METI industrial standards documentation, and municipal zoning board decisions. Bottom-up facility counts and top-down household expenditure patterns were triangulated for cross-verification.
Historical transaction volumes were cross-referenced against panel input from multi-unit operators to anchor growth trajectories across the analysis window. Segmentation modeling incorporated service type, animal species, facility architecture, and customer purchasing authority. CAGRs were derived from reconciling macro pet ownership trends with micro facility utilization data. Forecast inputs included urban household formation patterns, remote-work hybrid schedule persistence, and municipal zoning ordinance evolution.
The model holds under stable regulatory enforcement intensity; deviation in municipal zoning liberalization or federal animal welfare classification expansion would shift facility economics. Forecasts reflect documented assumptions about employer benefits program adoption and pet humanization trajectory persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
South Africa Pet Training Services Market
Pet Care Products
North America Dog Food Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Pet Care Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
Aquarium and Fish Bowls Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Pet Toys Market
Pet Care Products
Electric Pet Clippers Market
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
Germany Pet Food Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Cat Massage Comb Market