
 Peeled Garlic Market | 2026-2036
Peeled Garlic Market Size, Share, and Industry Trends Forecast 2026-2036
Peeled Garlic Market Insights
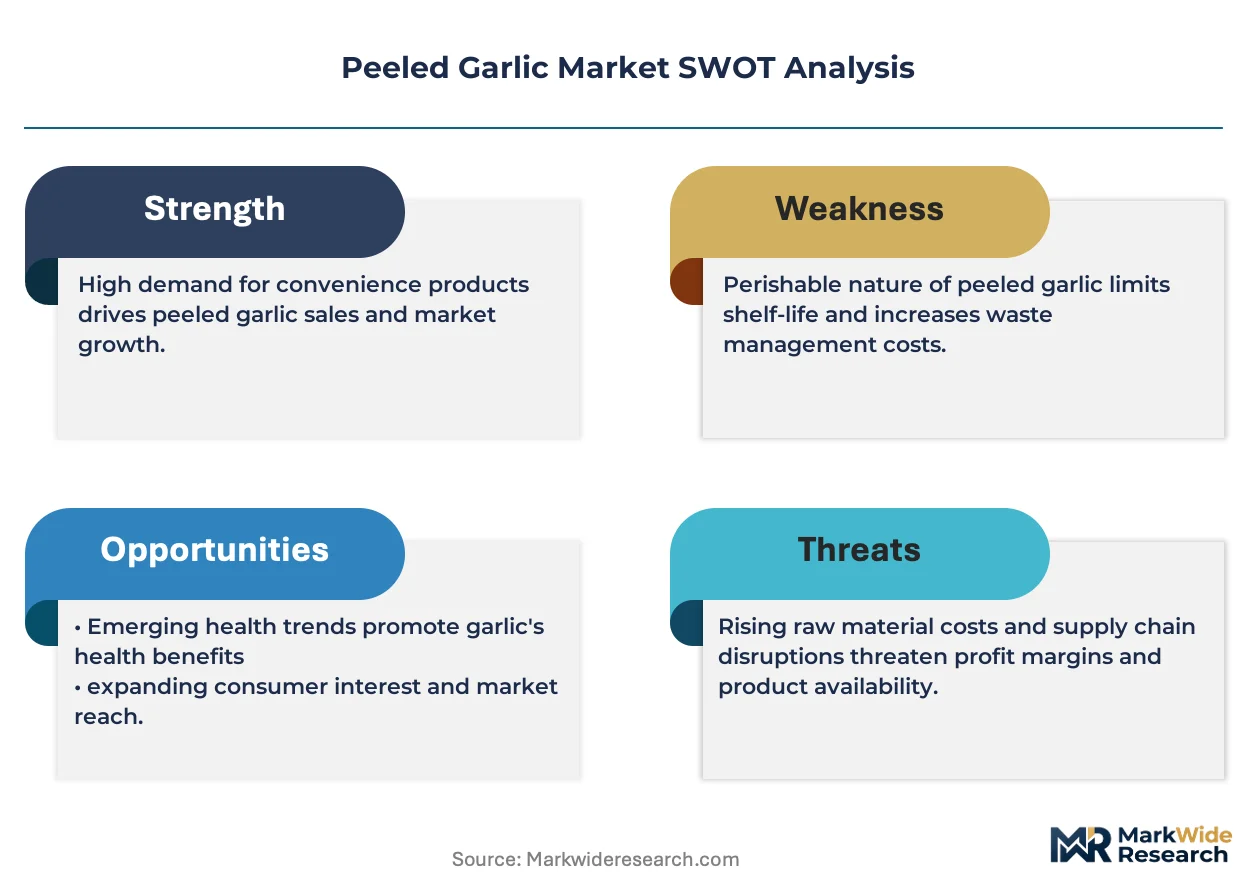
Grade A peeled garlic with zero sprout tolerance and sub-3% moisture variance is redrawing quality benchmarks across the category. Christopher Ranch leverages its Salinas Valley growing base to sustain year-round supply consistency for North American retail chains. Shandong Liancheng Garlic Industry anchors bulk export volumes through integrated peeling, grading, and vacuum-sealing operations out of Pizhou.
Peeled garlic comprises fresh bulbs that have undergone mechanical or manual removal of outer papery skins, followed by washing, sanitization, and preservation steps that retain allicin potency above minimum thresholds for flavor and antimicrobial function; the product serves commercial kitchens and food manufacturers seeking to eliminate labor-intensive prep while ensuring batch-to-batch consistency. Fresh garlic occupies the dominant share of product type value given its use in raw and lightly cooked applications, though frozen garlic is gaining traction among industrial kitchens prioritizing extended shelf life without chemical preservatives. Vacuum-sealed packaging commands margin premiums by reducing oxidation and refrigerated spoilage risk during extended distribution cycles.
FDA food safety modernization rules and USDA organic certification requirements shape product standards and market access for peeled garlic entering the United States, while China's GB standards and SAMR oversight govern domestic processing hygiene and export eligibility. Stakeholders must monitor evolving pesticide maximum residue limits across destination markets and assess backward integration into controlled-atmosphere storage to protect margin structures against input volatility.
Market Dynamics
Food manufacturers and restaurant chains are consolidating procurement around value-added garlic formats to eliminate labor-intensive prep while meeting tightening residue limits across destination markets.
Growth Catalysts
- EU EFSA residue protocols:Tighter maximum residue limits for pesticides are accelerating compliance investments among exporters, favoring processors with integrated cold-chain and traceability systems.
- Mechanical peeling automation:Advances in pneumatic and water-jar peeling technologies are reducing labor dependency and yield loss in high-volume operations.
- Shandong Province cluster concentration:Integrated peeling, grading, and vacuum-sealing infrastructure in Pizhou and surrounding districts is anchoring export fulfillment capacity for Asian and European buyers.
Market Restraints
- Input cost volatility:Fresh bulb prices fluctuate with planting-area cycles and weather events in Shandong, compressing processor margins during low-yield seasons.
- Single-region supply concentration:Overreliance on Chinese peeled garlic exposes buyers to SAMR export licensing delays and geopolitical trade friction.
- Allicin degradation limits:Enzymatic potency loss during extended cold storage constrains shelf-life claims for fresh formats without frozen or acidified alternatives.
Strategic Opportunities
- USDA organic certification gap:Premium-priced organic peeled garlic remains underpenetrated in North American retail, creating white space for certified processors.
- Frozen garlic industrial adoption:Blast-freezing technology is opening extended-shelf-life segments among ready-meal manufacturers seeking preservative-free inputs.
- Direct-to-foodservice platforms:Digital procurement channels are disintermediating traditional import-distributor layers for mid-scale restaurant chains.
Industry Challenges
- Sanitation protocol capex:FDA Food Safety Modernization Act compliance requires continuous washing, sanitization, and environmental monitoring infrastructure upgrades.
- Allicin standardization:Batch-to-batch potency variance complicates flavor-profile guarantees for food manufacturers with rigid formulation specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peeled Garlic Market |
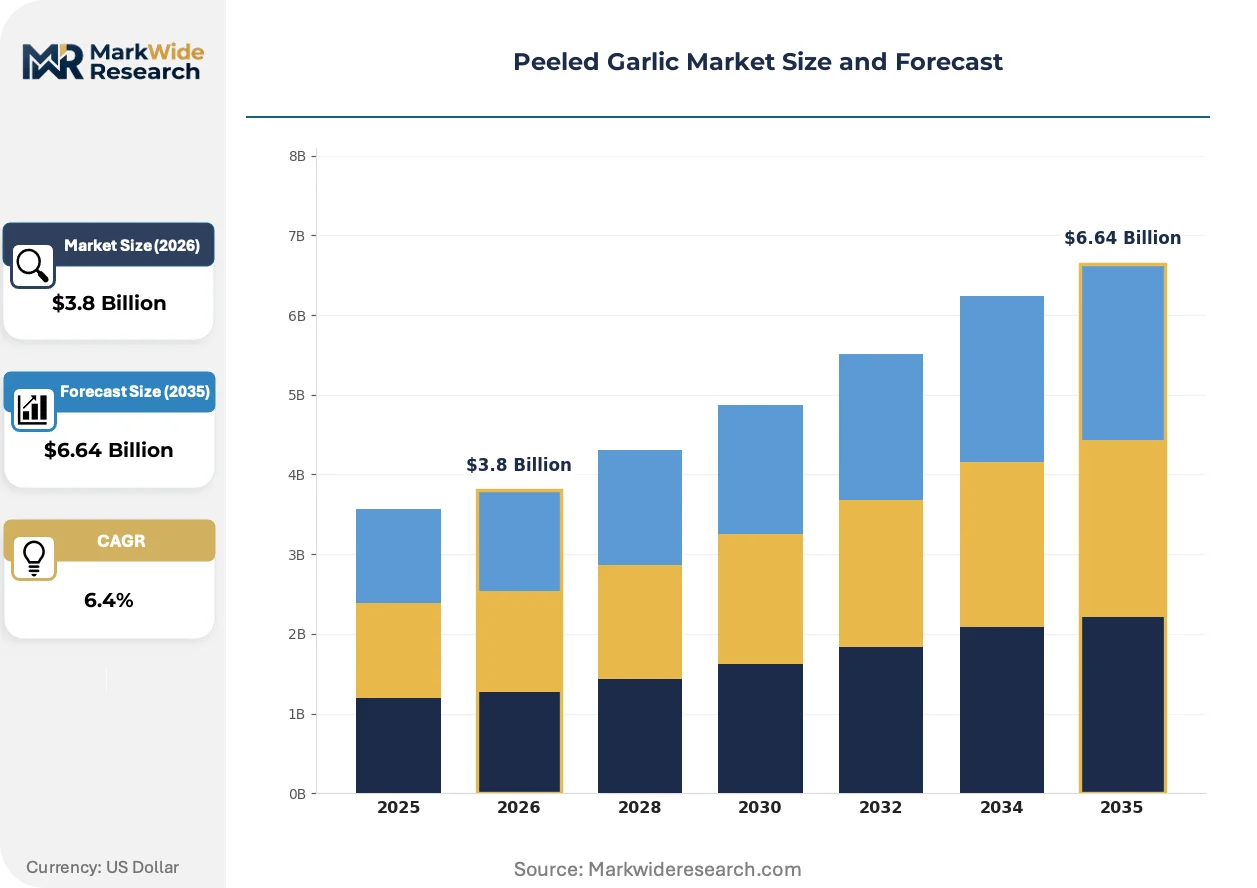
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Garlic, Frozen Garlic, Dehydrated Garlic, Pickled Garlic Packaging Type: Bags, Jars, Bulk Packaging, Vacuum Sealed Distribution Channel: Supermarkets, Wholesale Markets, Online Retail, Food Service End User: Households, Restaurants, Food Manufacturers, Industrial Kitchens |
| Companies Covered | Pizhou Tianyuan Garlic Co., Ltd, Huerta Nature, Imperio Garlic, Christopher Ranch, Spice World, The Garlic Company, Garlic Solutions, Shandong Liancheng Garlic Industry Co., Ltd, GAB Operations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peeled Garlic Market Trends and Innovations
Processing technology and packaging formats are diverging between premium fresh segments and industrial frozen applications, reshaping capital allocation across the supply base.
Modified-atmosphere packaging is bifurcating the fresh peeled garlic segment. Retail chains in North America and Western Europe are adopting high-barrier film with nitrogen flush to extend refrigerated shelf life beyond 30 days. This technology is displacing traditional perforated packaging in premium private-label programs while compressing margin structures for processors lacking vacuum-sealing capabilities.
China's SAMR is tightening GB standards for agricultural product processing hygiene and export registration. Domestic processors must now document HACCP-equivalent systems and residue testing protocols to maintain eligibility for EU and North American markets. Small and mid-scale peeling operations in Shandong are consolidating or exiting as compliance costs rise.
Foodservice distributors are unbundling prep services from traditional broadline contracts. Large restaurant chains are sourcing peeled garlic directly from processors with captive cold-chain logistics, bypassing regional distributors. This pattern is most visible in the United States, where Chipotle, Panera, and similar fast-casual operators specify direct-processor relationships in procurement tenders.
Peeled Garlic Market Segmentation
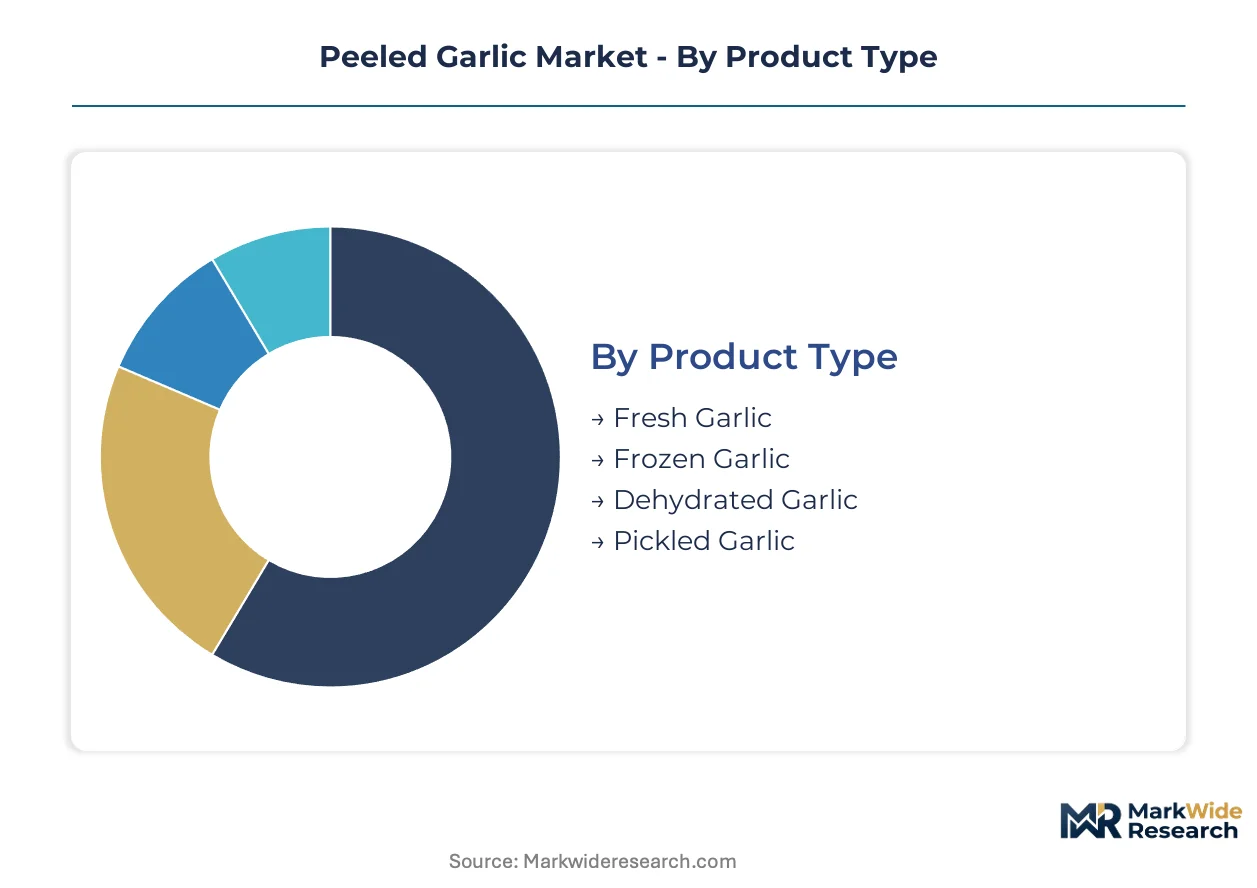
Peeled garlic procurement patterns diverge sharply between foodservice bulk buyers and retail consumers, with each channel demanding distinct packaging formats, shelf-life specifications, and residue documentation. Understanding these segment boundaries clarifies where processors must invest in automation versus cold-chain infrastructure.
Product Type:
Fresh garlic dominates supermarket and foodservice procurement, while frozen formats capture industrial kitchens seeking extended stability without chemical preservatives.
- Fresh Garlic:Bulbs retain enzymatic allicin activity above flavor thresholds through controlled-atmosphere storage and rapid cold-chain transit. Restaurant chains in North America specify Grade A with sub-3% moisture variance for raw applications. Demand concentrates in Shandong Province processing clusters serving export markets.
- Frozen Garlic:Blast-freezing at -40°C arrests enzymatic degradation, yielding 18-24 month shelf life for ready-meal manufacturers. Industrial kitchens across the United States are adopting this format to eliminate prep labor while meeting clean-label requirements.
- Dehydrated Garlic:Low-moisture flakes and granules serve seasoning manufacturers with ambient distribution economics.
- Pickled Garlic:Acidified brine formulations target specialty retail and ethnic foodservice channels.
By volume, fresh garlic leads. By growth pace, frozen garlic is climbing the fastest as industrial buyers prioritize labor reduction.
Packaging Type:
Margin structures stratify sharply: vacuum-sealed formats command premiums for oxidation protection, while bulk packaging serves price-sensitive foodservice procurement.
- Vacuum Sealed:High-barrier films with nitrogen flush extend refrigerated shelf life beyond 30 days, displacing perforated alternatives in premium private-label programs. Retail chains specify this format for reduced spoilage write-offs.
- Bulk Packaging:Poly-lined cartons and totes serve restaurant distributors and food manufacturers with high-throughput, rapid-turn inventory models. Procurement concentrates in Pizhou-based processors with integrated peeling and grading lines.
- Bags:Perforated polyethylene dominates economy retail tiers.
- Jars:Brined and acidified products occupy specialty shelf-stable segments.
By margin contribution, vacuum sealed leads. By shipment volume, bulk packaging dominates export flows.
Distribution Channel:
Digital procurement is disintermediating traditional import-distributor layers for mid-scale restaurant chains, while supermarkets retain SKU breadth requirements.
- Food Service:Direct-processor relationships are displacing broadline distributors for chains like Chipotle and Panera, with captive cold-chain logistics specified in tenders. This channel demands residue documentation and HACCP-equivalent traceability.
- Supermarkets:Private-label programs require 30-day minimum shelf life and consistent bulb sizing for retail display economics. North American chains source through consolidated importers with SAMR-registered Shandong suppliers.
- Wholesale Markets:Traditional import-distributor networks serve smaller foodservice operators.
- Online Retail:E-commerce platforms are gaining traction for specialty and organic formats.
By revenue concentration, food service leads. By channel expansion rate, online retail is gaining share fastest.
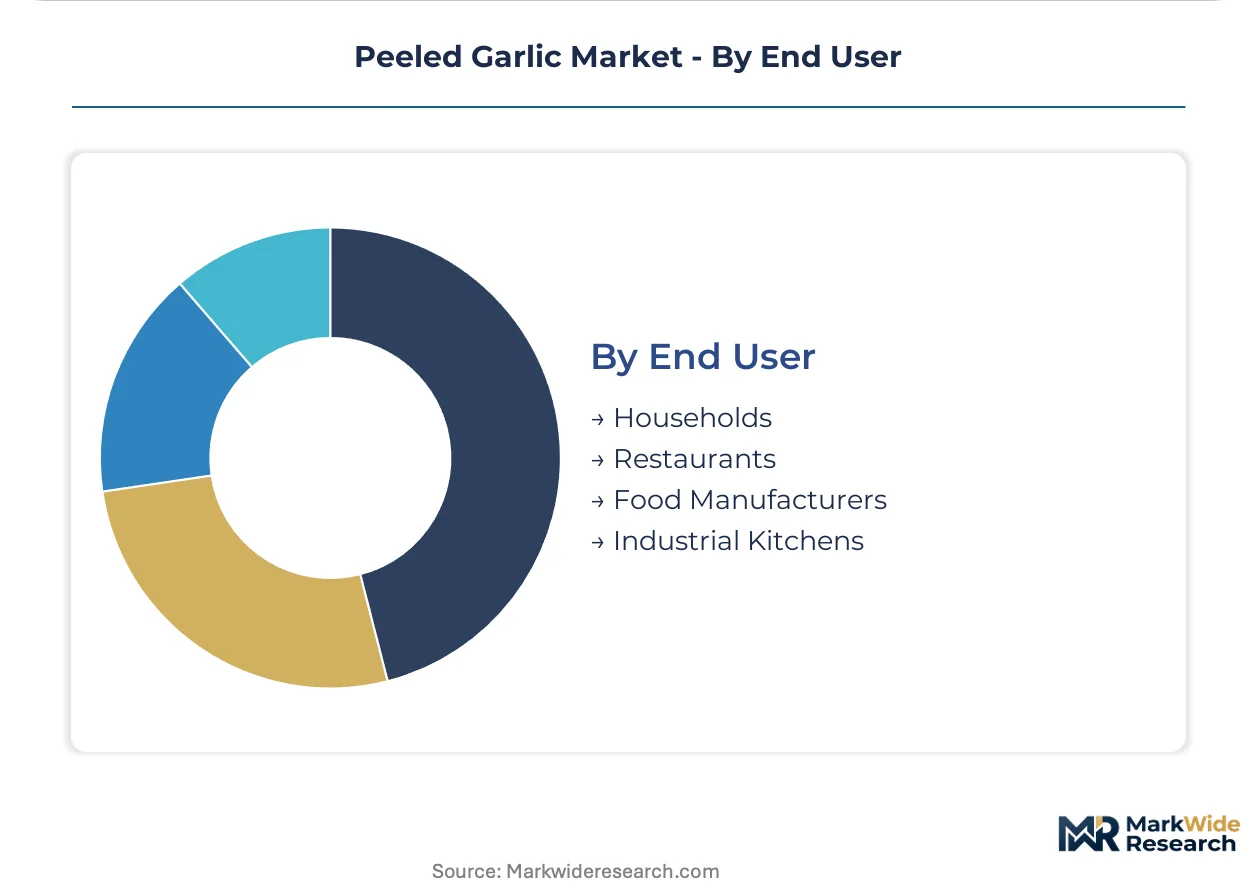
End User:
Procurement specifications diverge between formulation-driven manufacturers and prep-intensive restaurant operations.
- Restaurants:Fast-casual and casual-dining chains specify zero-sprout tolerance and direct-processor relationships to eliminate kitchen labor. FDA Food Safety Modernization Act compliance is mandatory for US-serving suppliers.
- Food Manufacturers:Ready-meal and sauce producers require batch-to-batch allicin standardization for rigid formulation specifications, favoring frozen formats with potency guarantees.
- Households:Retail-packaged fresh garlic serves convenience-oriented consumers.
- Industrial Kitchens:Institutional feeders prioritize cost-optimized bulk procurement.
By specification stringency, food manufacturers lead. By volume growth, restaurants are expanding most quickly as labor costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Shandong Province dominate global peeled garlic trade, while import demand concentrates in North American and European foodservice channels. Regulatory divergence between FDA residue protocols and EU EFSA limits is fragmenting compliance requirements across destination markets. Processing infrastructure clusters in specific agricultural regions anchor supply reliability for international buyers.
China
Shandong Province generates the majority of global peeled garlic export volume, with Pizhou and Jinxiang hosting integrated peeling, grading, and vacuum-sealing operations. SAMR tightened GB standards for agricultural product processing hygiene, requiring HACCP-equivalent documentation for export registration. Cold-chain infrastructure investments in Shandong's processing clusters now support direct fulfillment to European and North American buyers.
United States
Fast-casual restaurant chains drive procurement of Grade A fresh peeled garlic with zero-sprout tolerance for raw applications. FDA Food Safety Modernization Act rules mandate continuous washing, sanitization, and environmental monitoring for imported garlic processors. Christopher Ranch maintains year-round supply from its Salinas Valley growing base, serving retail chains across California and the Pacific Northwest.
Spain
Domestic consumption and re-export demand to other EU member states support processing operations in Castilla-La Mancha and Andalusia. EFSA guidance on tightened pesticide maximum residue limits is accelerating compliance investments among Spanish importers sourcing from third countries. Valencia-based distributors are consolidating procurement around vacuum-sealed formats for extended shelf-life requirements.
Germany
Industrial food manufacturers in Bavaria and North Rhine-Westphalia specify batch-to-batch allicin standardization for ready-meal formulations. REACH compliance and EU organic certification requirements shape import specifications for processed garlic entering German distribution. Hamburg's port infrastructure handles bulk refrigerated shipments from Chinese processors for redistribution across Central Europe.
Japan
Premium retail channels in Tokyo and Osaka demand sub-3% moisture variance and extended refrigerated shelf life for fresh peeled garlic. METI food import standards and JIS quality specifications govern acceptance criteria for Chinese-origin products. Kansai-region foodservice distributors are adopting direct-processor relationships to reduce intermediary costs.
Peeled Garlic Market Competitive Landscape
Listed leaders compete with private specialists across integrated processing capabilities, creating a tiered structure where scale-driven exporters face regional specialists with captive cold-chain assets. The vendor base fragments between Shandong-based bulk processors and North American branded suppliers with controlled growing operations. Three archetypes dominate: integrated Chinese exporters with peeling-to-port infrastructure, California-based year-round suppliers with vertical growing control, and European specialists in organic and value-added formats. Competitive moves center on backward integration into controlled-atmosphere storage and direct-to-foodservice platform development.
Within the integrated export tier, Shandong Liancheng Garlic Industry Co., Ltd and Pizhou Tianyuan Garlic Co., Ltd exemplify the Shandong cluster model of combined peeling, grading, and vacuum-sealing operations. Christopher Ranch occupies a position representing North American supply consistency through captive Salinas Valley production. These three anchors illustrate the geographic bifurcation between Chinese volume exporters and US-based branded suppliers.
| Leading Market Players |
|---|
| Pizhou Tianyuan Garlic Co., Ltd |
| Huerta Nature |
| Imperio Garlic |
| Christopher Ranch |
| Spice World |
| The Garlic Company |
| Garlic Solutions |
| Shandong Liancheng Garlic Industry Co., Ltd |
| GAB Operations |
| Others |
Pricing and Supply Chain Analysis
Mechanical peeling automation replacing manual labor in Shandong Province simultaneously compresses unit processing costs and concentrates pricing power among integrated exporters with capital-intensive grading and vacuum-sealing lines. This substitution dynamic redraws margin structures across fresh and frozen formats as buyers trade labor savings for residue documentation premiums.
Pricing Analysis
Industrial food manufacturers anchor contract pricing around batch-to-batch allicin standardization requirements, with three-tier pricing structure across premium, standard, and economy levels separating vacuum-sealed Grade A from bulk-packaged formats. Price differentiation rests on certification tier (USDA organic, EU organic) and volume scale, with pricing pressure intensifying as SAMR compliance capex filters through to export quotations. Quick-service restaurant chains exhibit lowest price sensitivity, prioritizing zero-sprout tolerance and direct-processor relationships over per-unit cost.
Supply Chain Analysis
China, Spain, and the United States anchor global peeled garlic supply, with Shandong Province generating dominant export volumes through integrated peeling-to-port infrastructure in Pizhou and Jinxiang. Raw material flows draw from fresh bulb cultivation cycles, cold-chain logistics networks, and nitrogen-flush packaging materials, with single-region concentration in China exposing buyers to SAMR export licensing delays. Distribution runs through direct-processor relationships displacing traditional import-distributor layers for mid-scale restaurant chains, particularly in North American foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU EFSA residue protocol tightening constitutes a regulatory inflection accelerating compliance investments and consolidating processing capacity among integrated exporters with traceability systems. This disruption favors capital-intensive operators over fragmented peelers.
For Market Incumbents: Shield margin structures by deepening backward integration into controlled-atmosphere storage in Shandong and securing USDA organic certification for North American retail penetration. SAMR licensing delays and allicin degradation during extended cold storage represent dual threats requiring environmental monitoring infrastructure upgrades and frozen format diversification to arrest enzymatic potency loss.
For New Entrants and Emerging Players: Lead with blast-freezing technology targeting ready-meal manufacturers seeking preservative-free inputs with 18-24 month shelf life stability. The organic peeled garlic segment in North American retail offers the most penetrable white space, with digital procurement platforms enabling disintermediated foodservice access as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed California growing operations seeking geographic diversification beyond Salinas Valley seasonality. Long-term viability hinges on captive cold-chain logistics and direct-to-foodservice platform development; monitor EFSA maximum residue limit enforcement stringency as the signal indicating consolidation acceleration among Shandong processors unable to absorb compliance capex.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Atmosphere Storage | Shandong processors protect margin volatility against fresh bulb price swings from planting-area cycles. |
| USDA Organic Certification Investment | North American retail chains command premium private-label placement with residue-free documentation. |
| Blast-Freezing Capacity Expansion | Ready-meal manufacturers adopt frozen formats meeting clean-label requirements without chemical preservatives. |
| Direct-to-Foodservice Platform Development | Chipotle and Panera-style chains bypass distributors through captive cold-chain logistics specifications. |
| Modified-Atmosphere Packaging Upgrade | High-barrier nitrogen-flush films extend refrigerated shelf life beyond 30 days for retail chains. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAMR export registration databases, EU EFSA residue limit guidance, FDA Food Safety Modernization Act compliance records, and customs trade flows. Interviews with Shandong-based processing plant managers, North American quick-service restaurant procurement directors, European food manufacturer R&D leads, and cold-chain logistics operators combined with bottom-up volume triangulation against top-down trade value estimates.
Segmentation dimensions modeled span product type (fresh, frozen, dehydrated, pickled), packaging format (vacuum-sealed, bulk, bags, jars), distribution channel (foodservice, supermarkets, wholesale, online retail), and end user (restaurants, food manufacturers, households, industrial kitchens) across the analysis window. CAGRs derive from historical trade flow trajectories, planting-area cycle patterns, and penetration assumptions for automation-enabled processing capacity, with allicin potency retention curves and residue compliance cost curves as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU EFSA enforcement stringency, stable Shandong cultivation yields, or frozen format adoption rates among ready-meal manufacturers would require recalibration. Forecasts reflect documented assumptions regarding SAMR licensing velocity, mechanical peeling automation diffusion, and nitrogen-flush packaging cost curves. Recalibration cycles align with material shifts in residue limit enforcement, planting-area reporting from Chinese agricultural authorities, and blast-freezing technology adoption trajectories among industrial kitchen operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Dehydrated Garlic Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Paprika Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Acacia Concinna Extracts Market