
 Asia-Pacific Dehydrated Onion Market | 2026-2036
Asia-Pacific Dehydrated Onion Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dehydrated Onion Market Outlook
Air-drying technology is narrowing the quality gap between artisanal and industrial dehydrated onion output. Kings Dehydrated Foods Pvt. Ltd. leverages captive sourcing from Nashik to sustain cost leadership across flake and powder grades. Jain Farm Fresh Foods Ltd. anchors its position through backward integration into cold-chain onion storage, while Olam International competes on export logistics scale into Southeast Asian processing hubs.
Asia-Pacific dehydrated onion comprises Allium cepa bulbs processed through convective air-drying or freeze-drying to below seven percent moisture, yielding shelf-stable forms for seasoning blends and industrial food manufacturing. Powder and granule formats dominate volume throughput owing to their dispersion properties in dry soup and snack seasoning applications, while vacuum-sealed packaging commands premium positioning among HoReCa buyers seeking extended ambient storage without flavor degradation. Flakes retain share in retail cooking segments where visual texture matters, though diced formats face margin pressure from mechanized chopping alternatives in prepared meals.
FSSAI in India enforces maximum moisture thresholds and microbial limits that determine export eligibility to Middle Eastern and European destinations, while BIS certification for dehydrated vegetables shapes domestic procurement standards. China's SAMR and GB standards for dried agricultural products create parallel compliance tracks for suppliers accessing its food processing sector. Buyers must monitor evolving PLI scheme incentives for food processing infrastructure in India and traceability mandates that will reshape supplier qualification criteria across the region.
Market Dynamics
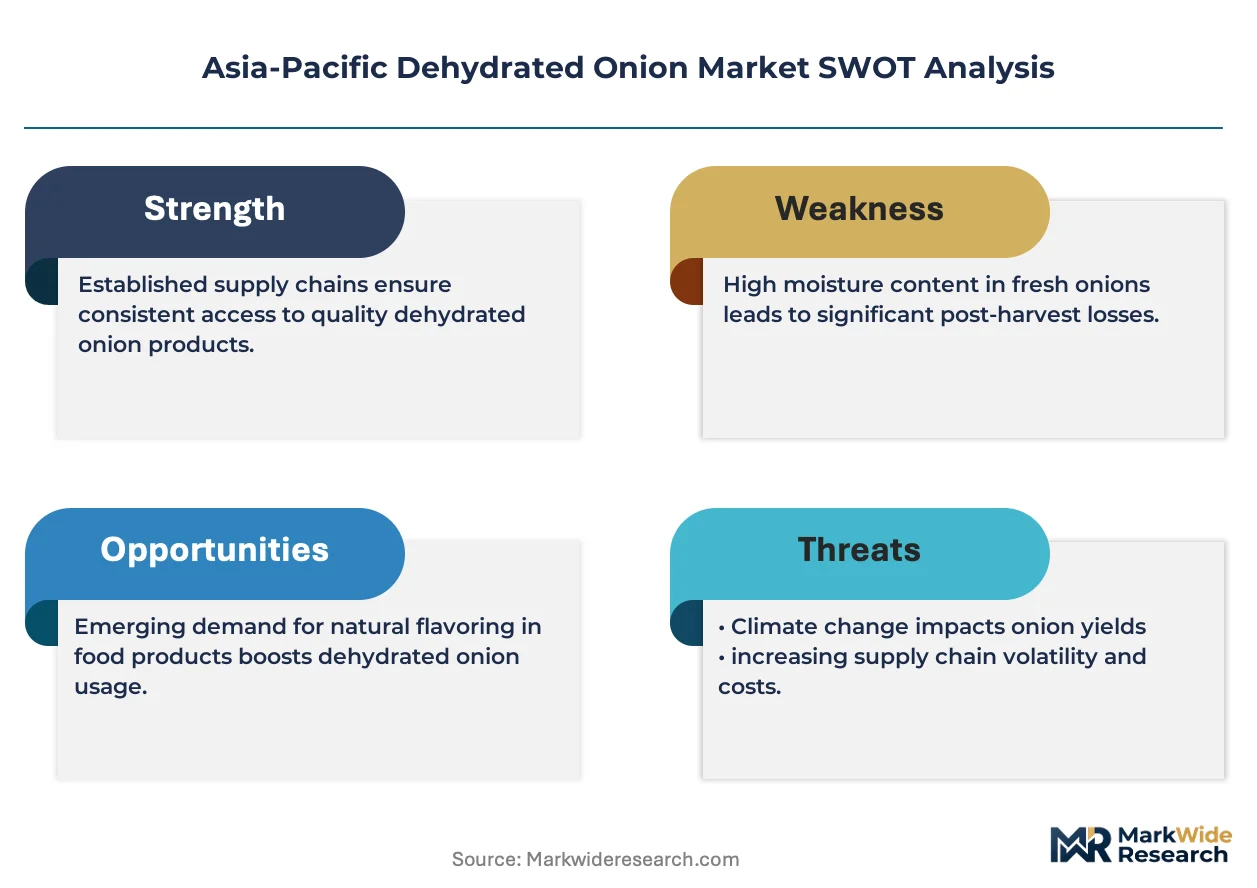
India's FSSAI moisture-content thresholds and microbial limits are compressing supplier margins while concentrating export qualification among dehydration units with laboratory-grade testing infrastructure.
Growth Catalysts
- Ready-meal formulation demand:Food processing industries across Southeast Asia are scaling purchases of dehydrated onion powder and granules for instant noodle and soup seasoning applications.
- PLI scheme incentives:India's Production Linked Incentive scheme for food processing infrastructure is lowering capital barriers for dehydration capacity expansion in Maharashtra and Gujarat.
- Air-drying technology maturation:Convective drying systems are narrowing quality differentials between artisanal and industrial output, enabling mid-tier suppliers to access HoReCa channels previously gated by flavor-consistency requirements.
Market Restraints
- Raw material concentration:Gujarat's onion belt supplies the bulk of feedstock to regional dehydration units, creating geographic supply vulnerability during monsoon disruptions.
- Freeze-drying cost premium:Energy-intensive lyophilization processes limit adoption to premium spice blends, constraining volume penetration in mass-market seasoning applications.
- Substitution by fresh-chilled alternatives:Cold-chain infrastructure expansion in Vietnam and Thailand is enabling food manufacturers to substitute rehydrated flakes with minimally processed fresh onion in high-turnover production lines.
Strategic Opportunities
- Vietnam processing hub emergence:Underdeveloped dehydration capacity relative to onion cultivation volumes creates first-mover positioning for integrated sourcing-processing operations.
- Traceability mandate preparation:India's evolving PLI-linked traceability requirements will reshape supplier qualification criteria, rewarding early investments in blockchain-enabled batch tracking.
- Freeze-dried premium tier:Convergence of vacuum-sealed packaging with freeze-dried texture retention is opening ambient-stable formats for premium retail and airline catering channels.
Industry Challenges
- Microbiology laboratory capacity:FSSAI export certification requires pathogen testing infrastructure that smaller dehydration units in Nashik lack, forcing outsourcing delays.
- Cold-chain integration complexity:Backward integration into controlled-atmosphere onion storage demands refrigeration capex that conflicts with seasonal cash flow patterns of agricultural processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dehydrated Onion Market |
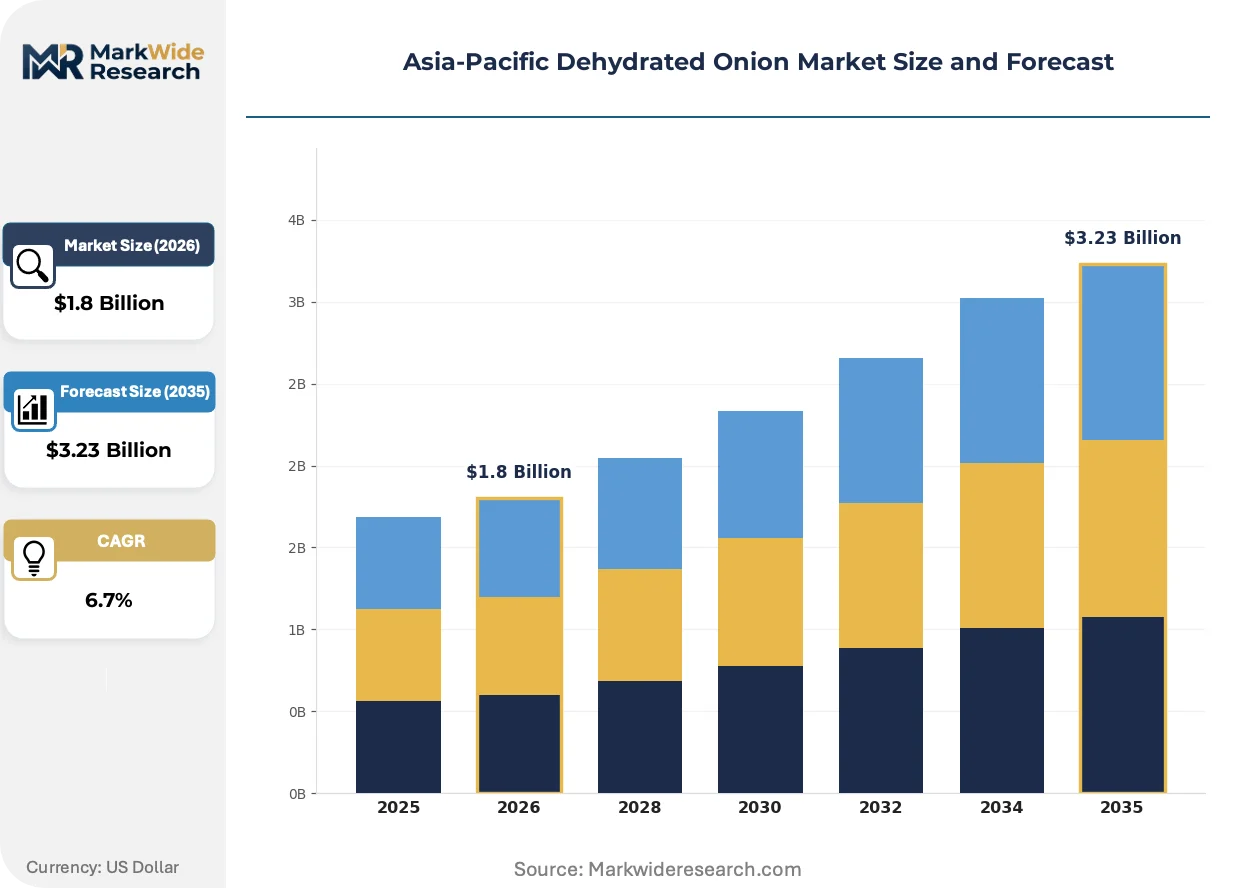
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diced, Flakes, Powder, Granules Packaging Type: Bags, Jars, Cans, Vacuum Sealed End User: Food Processing, HoReCa, Retail, Prepared Meals Distribution Channel: Online, Supermarkets, Wholesale, Grocery Stores |
| Companies Covered | Jiyan Food Ingredients, Kings Dehydrated Foods Pvt. Ltd., Jain Farm Fresh Foods Ltd., B.K. Dehy Foods, Natural Dehydrated Vegetables Pvt. Ltd., Daksh Foods Pvt. Ltd., Earth Expo Company, Olam International, Murtuza Foods Pvt. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dehydrated Onion Market Strategic Shifts
Processing technology convergence and regulatory stringency are reconfiguring competitive advantage around quality-assurance infrastructure rather than raw material access alone.
Hybrid convective-microwave drying systems are reducing dehydration cycle times while preserving volatile sulfur compounds responsible for flavor intensity. Mid-scale processors in Gujarat are retrofitting existing air-drying lines with microwave finish stages to meet FSSAI microbial limits without full freeze-drying capex. This capital-efficient upgrade path is rendering obsolete the traditional trade-off between throughput volume and export-grade certification.
FSSAI's tightening enforcement of maximum moisture thresholds for dehydrated vegetables is disqualifying sun-dried product from formal export channels. The regulation is compressing informal sector participation while concentrating volume among integrated processors with in-house laboratory facilities. Maharashtra-based suppliers are responding by consolidating toll-drying relationships into captive processing arrangements.
HoReCa buyers are consolidating procurement around single-source contracts with integrated dehydration-cold chain operators, displacing spot-market purchasing from commodity traders. This preference shift favors Jain Farm Fresh Foods and similar backward-integrated players in India's western states. The concentration is most visible in quick-service restaurant chains expanding across Indonesia and the Philippines, where supply assurance outweighs price minimization in vendor selection criteria.
Asia-Pacific Dehydrated Onion Market Segmentation
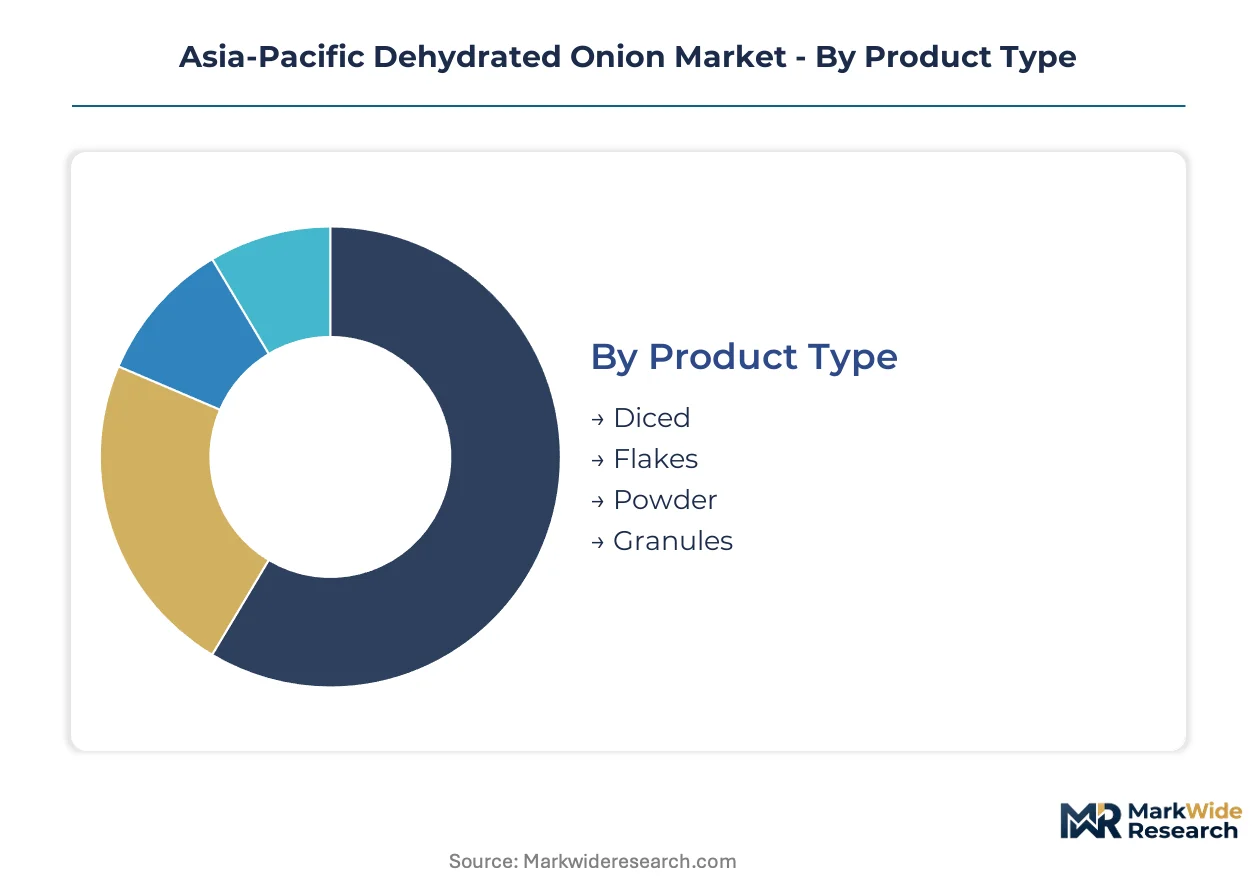
Segmentation in the Asia-Pacific dehydrated onion market reveals how processing technology and packaging innovation create distinct competitive arenas. Buyers select formats based on rehydration speed, shelf stability requirements, and procurement scale rather than commodity pricing alone.
Product Type:
After-sales service intensity varies sharply across product types, with powder and granule buyers demanding technical support for dispersion optimization in seasoning blends while flake purchasers prioritize consistent rehydration ratios.
- Flakes:Thin, irregular sheets of dehydrated onion retain visual texture and rehydrate rapidly in hot liquids. HoReCa buyers in Indonesia and the Philippines specify flake size grading for consistent presentation in finished dishes, with supply contracts now mandating moisture variance below two percent.
- Powder:Fine-ground dehydrated onion below 80 mesh integrates uniformly into dry soup bases and snack seasonings without visible particles. Food processors in Vietnam's instant noodle sector are consolidating procurement around single-source powder suppliers with FSSAI-compliant laboratory infrastructure.
- Diced:Cubed dehydrated onion pieces suit prepared meal applications requiring distinct vegetable identity post-rehydration.
- Granules:Intermediate particle size between powder and flakes offers controlled dispersion in industrial seasoning applications.
Powder holds the largest share; momentum sits with granules as mid-scale processors seek format flexibility.
Packaging Type:
Packaging cost tiers separate commodity bulk buyers from premium channel operators, with vacuum-sealed formats commanding three to four times the per-kilogram packaging investment of standard bags.
- Vacuum Sealed:Oxygen-excluded barrier packaging extends ambient shelf life beyond twenty-four months while preserving volatile sulfur compounds responsible for flavor intensity. Premium HoReCa distributors in Singapore and Malaysia specify vacuum-sealed formats for ambient storage in high-humidity climates.
- Bags:Multi-layer polymer bags with moisture barriers dominate industrial procurement for food processing applications where rapid throughput minimizes storage duration.
- Jars:Rigid container packaging targets retail consumers seeking visible product quality assessment before purchase.
- Cans:Metal container formats serve institutional buyers requiring mechanical durability in high-volume kitchen environments.
Bags carry the volume base; vacuum sealed is climbing the fastest as climate-resilient supply chains gain priority.
End User:
Application maturity separates established industrial buyers from emerging channel segments, with food processing representing decades of specification refinement while prepared meals represent a relatively new demand vector.
- Food Processing:Industrial manufacturers of instant noodles, soup bases, and snack seasonings constitute the foundational demand pool, with procurement governed by FSSAI additive labeling compliance and moisture specification adherence.
- HoReCa:Hotels, restaurants, and catering operations are consolidating procurement around integrated dehydration-cold chain operators in India's western states, displacing spot-market purchasing from commodity traders.
- Retail:Packaged consumer formats face margin pressure from fresh onion availability in modern trade formats.
- Prepared Meals:Ready-meal manufacturers represent an emerging specification segment with distinct rehydration ratio requirements.
Food processing maintains dominant share; prepared meals is gaining share fastest as Southeast Asian ready-meal production scales.
Distribution Channel:
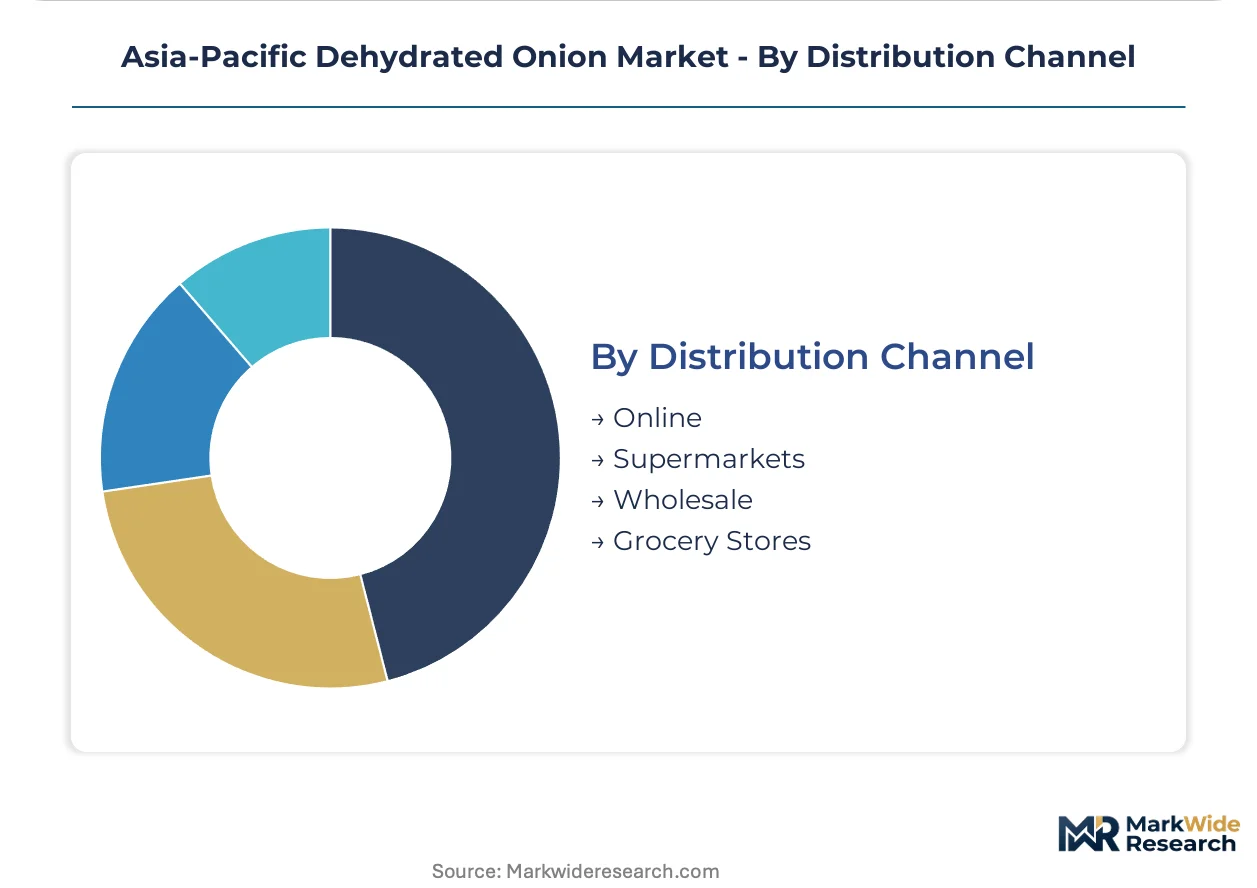
Customer type fragmentation across channel structures creates divergent service requirements, with wholesale buyers negotiating annual contracts while online purchasers demand smaller lot flexibility.
- Wholesale:Bulk procurement channels serving food manufacturers and institutional buyers concentrate volume in Maharashtra and Gujarat, with Nashik-based dehydration units leveraging geographic proximity to raw material belts.
- Supermarkets:Modern retail formats in Thailand and Vietnam are expanding shelf space for vacuum-sealed retail packs targeting urban consumers.
- Online:E-commerce platforms enable direct access for small-scale food processors and specialty buyers seeking non-standard lot sizes.
- Grocery Stores:Traditional trade channels retain relevance for flake and powder formats in secondary cities across India.
Wholesale commands volume leadership; online is expanding most quickly as procurement digitization penetrates mid-tier processing operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processors in Southeast Asia and institutional buyers in India are concentrating procurement around dehydration units with FSSAI-compliant laboratory infrastructure. HoReCa chains expanding across Indonesia and the Philippines prioritize supply assurance over spot-market pricing. Cold-chain integration in Vietnam and Thailand is reshaping substitution dynamics between dehydrated and fresh-chilled formats.
India
Maharashtra and Gujarat dominate dehydration capacity, with Nashik-based units leveraging proximity to the onion belt. FSSAI moisture thresholds and microbial limits are compressing margins among smaller processors lacking in-house testing infrastructure. Jain Farm Fresh Foods anchors its position through backward integration into controlled-atmosphere storage facilities in western states.
China
Instant noodle manufacturers in Shandong and Henan provinces are scaling powder procurement for seasoning base formulations. SAMR and GB standards for dried agricultural products create parallel compliance tracks distinct from Indian export requirements. Zhengzhou-based dehydration clusters are retrofitting air-drying lines with microwave finish stages to reduce cycle times.
Vietnam
Ready-meal production lines in Ho Chi Minh City and Hanoi are driving granule demand for rehydration-controlled applications. Underdeveloped dehydration capacity relative to onion cultivation volumes creates positioning opportunities for integrated sourcing-processing operations. Cold-chain infrastructure expansion is enabling substitution of rehydrated flakes with minimally processed fresh onion in high-turnover facilities.
Indonesia
Quick-service restaurant chains expanding across Java and Sumatra are consolidating procurement around single-source contracts with integrated operators. Local food processors favor flake formats for visual texture in finished dishes, with supply contracts mandating moisture variance below two percent. Traceability mandates are reshaping supplier qualification criteria for export-oriented processing hubs.
Thailand
Modern retail formats in Bangkok and Chiang Mai are expanding shelf space for vacuum-sealed retail packs targeting urban consumers. BIS-influenced procurement standards from Indian suppliers govern industrial purchasing for snack seasoning applications. E-commerce platforms are enabling direct access for small-scale food processors seeking non-standard lot sizes.
Asia-Pacific Dehydrated Onion Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct procurement tiers. The market exhibits moderate concentration, with integrated dehydration-cold chain operators capturing HoReCa volume while commodity traders retain spot-market relevance. Three archetypes dominate: backward-integrated agricultural processors with captive raw material access, export-logistics specialists leveraging scale into Southeast Asian hubs, and mid-tier retrofitters of hybrid drying technology. Competitive moves center on laboratory-grade testing infrastructure investment and toll-drying consolidation into captive processing arrangements.
Within the integrated processor tier, Jain Farm Fresh Foods Ltd. and Kings Dehydrated Foods Pvt. Ltd. exemplify backward-integrated positioning through western India storage and sourcing infrastructure. Olam International occupies the export-logistics specialist archetype, anchoring scale-driven penetration into Southeast Asian processing hubs. Among mid-tier retrofitters, Daksh Foods Pvt. Ltd. and Natural Dehydrated Vegetables Pvt. Ltd. represent capital-efficient upgrade paths combining convective and microwave drying stages.
| Leading Market Players |
|---|
| Jiyan Food Ingredients |
| Kings Dehydrated Foods Pvt. Ltd. |
| Jain Farm Fresh Foods Ltd. |
| B.K. Dehy Foods |
| Natural Dehydrated Vegetables Pvt. Ltd. |
| Daksh Foods Pvt. Ltd. |
| Earth Expo Company |
| Olam International |
| Murtuza Foods Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Gujarat's onion belt concentration upstream feeds margin compression downstream into dehydration units lacking captive sourcing. Nashik-based processors absorb spot-market volatility while integrated operators with western India storage infrastructure extract cost-plus premiums from HoReCa buyers.
Pricing Analysis
Cost-plus contracts with onion futures indexation dominate procurement between Gujarat farmers and Maharashtra dehydration units. Price differentiation rests on FSSAI certification grade and cold-chain integration depth, with laboratory-equipped processors commanding premiums over toll-drying operators. Pricing pressure stems from freeze-drying energy costs constraining mass-market penetration. Food manufacturers in Vietnam's instant noodle sector exhibit highest price sensitivity, while Singapore premium HoReCa buyers prioritize supply assurance over unit economics.
Supply Chain Analysis
Upstream feedstock from Gujarat, Maharashtra, and Madhya Pradesh onion belts supplies regional dehydration capacity. Raw material flows depend on seasonal harvest timing, monsoon disruption patterns, and cold-chain storage availability. Single-source vulnerability concentrates during July-September monsoon flooding across western India. Distribution runs through Nashik-based wholesale channels serving industrial food processors, with vacuum-sealed formats bypassing traditional commodity traders for direct HoReCa contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among quick-service restaurant chains consolidating procurement around single-source dehydration-cold chain operators across Indonesia and the Philippines.
For Market Incumbents: Entrench laboratory-grade testing infrastructure to defend FSSAI export qualification against mid-tier retrofitters. Deepen backward integration into controlled-atmosphere onion storage in Nashik and Gujarat to offset raw material concentration risk. Capture HoReCa channel control before traceability mandates reshape supplier qualification criteria. For New Entrants and Emerging Players: Build out integrated sourcing-processing operations in Vietnam where dehydration capacity lags onion cultivation volumes. Target ready-meal manufacturers in Ho Chi Minh City with granule formats offering rehydration ratio control. Establish direct procurement relationships with farmers outside Gujarat's onion belt to bypass incumbent toll-drying networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier dehydration units in Maharashtra lacking captive cold-chain infrastructure. Long-term viability over the next decade hinges on traceability compliance and HoReCa channel penetration rather than commodity scale alone. Watch for FSSAI enforcement intensity as the inflection signal separating integrated operators from laboratory-deficient competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Infrastructure Investment | FSSAI microbial testing capability determines export eligibility to Middle Eastern and European destinations. |
| Backward Integration into Cold Storage | Controlled-atmosphere onion facilities in Nashik anchor supply assurance for HoReCa contract consolidation. |
| Hybrid Drying Technology Retrofit | Convective-microwave systems reduce cycle times while preserving volatile sulfur compounds for flavor intensity. |
| Traceability System Deployment | Blockchain-enabled batch tracking prepares suppliers for evolving PLI-linked qualification requirements. |
| Vietnam Processing Hub Establishment | Integrated sourcing-processing operations capture first-mover positioning in underdeveloped dehydration capacity. |
Study Parameters
Cross-validation between dehydration unit production records and FSSAI export certification databases anchors the qualitative findings. Primary interviews with plant managers at Maharashtra and Gujarat processing facilities, procurement leads at Vietnam instant noodle manufacturers, and HoReCa supply chain directors across Indonesia and the Philippines combined with secondary validation from customs trade data, BIS dehydrated vegetable standards, and PLI scheme disclosure filings. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Calibration against historical moisture-content compliance rates and cold-chain infrastructure buildout trajectories shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, packaging format, end-user application, and distribution channel, with regional regulatory cluster as an additional dehydration-specific dimension. CAGRs derive from fitted trend extrapolation moderated by technology adoption S-curves for hybrid drying systems and freeze-drying cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by export-logistics specialists or integrated agricultural processors would shift outcomes. Material shifts in FSSAI enforcement intensity, monsoon disruption frequency, or PLI scheme eligibility criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Dehydrated Garlic Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Culinary Powder Market
Spices and Condiments
Gravy Mixes Market