
 Middle East and Africa Dehydrated Onion Market | 2026-2036
Middle East and Africa Dehydrated Onion Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Dehydrated Onion Market Foresight
Food processing is decoupling from traditional fresh-onion dependency across the Middle East and Africa as manufacturers seek shelf-stable inputs. Olam Food Ingredients anchors supply security through integrated sourcing networks spanning multiple African onion-growing belts. Egyptian French Company leverages its proximity to Nile Delta cultivation zones to sustain cost-competitive flake and powder output for North African buyers.
Dehydrated onion comprises fresh Allium cepa subjected to controlled thermal reduction to moisture levels typically below seven percent, yielding shelf-stable granules, flakes, powder, or whole rings for industrial and consumer kitchens. Powder formats dominate bulk procurement by seasoning blenders and soup manufacturers due to homogeneous dispersibility and reduced storage footprint. Flakes retain structural integrity in baked and fried applications, commanding premium positioning within snack and restaurant supply chains where texture differentiation matters.
Saudi Food and Drug Authority standards, Egypt's EOS conformity requirements, and South African Department of Health labeling regulations collectively shape import documentation, pesticide residue thresholds, and moisture-content certification for dehydrated onion traded across the region. Compliance costs favor established processors with in-house laboratory capabilities over opportunistic traders. Stakeholders must monitor evolving Gulf Cooperation Council technical harmonization timelines, as unified standards would reshape cross-border qualification requirements and consolidate procurement toward pre-certified suppliers.
Market Dynamics
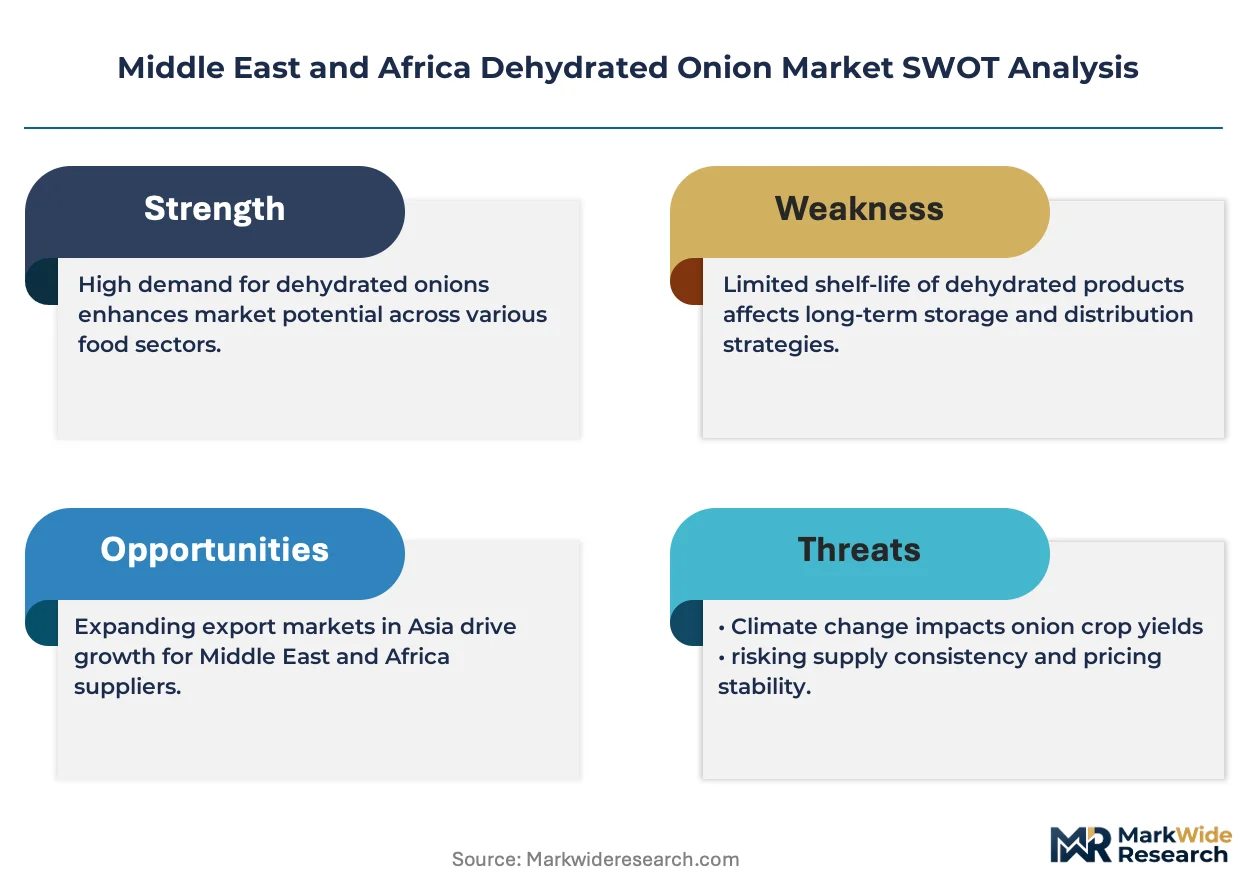
GCC food safety harmonization is compressing import qualification timelines, forcing processors to consolidate procurement toward pre-certified suppliers with in-house laboratory capabilities.
Growth Catalysts
- Ready-meal formulation expansion:Food manufacturers across Egypt and Saudi Arabia are embedding dehydrated onion into shelf-stable meal kits, displacing fresh Allium cepa in industrial kitchens.
- EOS conformity alignment:Egyptian Organization for Standardization certification requirements are filtering out informal traders, concentrating volume through established dehydration facilities in the Nile Delta.
- Solar thermal drying adoption:Egyptian processors are deploying photovoltaic-powered dehydration tunnels to reduce natural gas dependency and stabilize operating margins.
Market Restraints
- Raw onion price volatility:Nile Delta harvest fluctuations and irrigation cost spikes transmit directly into dehydrated onion input costs, compressing processor margins.
- Single-origin supply risk:Egyptian production clusters account for dominant regional dehydration capacity, exposing buyers to localized climate shocks and port congestion.
- Fresh substitute preference:Premium restaurant chains in Dubai and Riyadh maintain specifications for fresh onion in signature dishes, capping dehydrated penetration in foodservice.
Strategic Opportunities
- Moroccan export corridor development:Underutilized dehydration infrastructure in Souss-Massa could serve European buyers seeking non-Egyptian origin diversification.
- Halal-certified ingredient positioning:Saudi Food and Drug Authority recognition of dedicated processing lines opens Gulf retail and institutional channels for certified Egyptian suppliers.
- E-commerce bulk procurement platforms:B2B marketplaces connecting Ethiopian smallholder onion farmers to regional processors are disintermediating traditional commodity brokers.
Industry Challenges
- Moisture-content certification delays:Laboratory backlogs at Egyptian export inspection points are extending shipment release timelines by two to three weeks.
- Technical operator scarcity:Dehydration facility managers with expertise in continuous-belt thermal control systems command premium wages, constraining facility expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Dehydrated Onion Market |
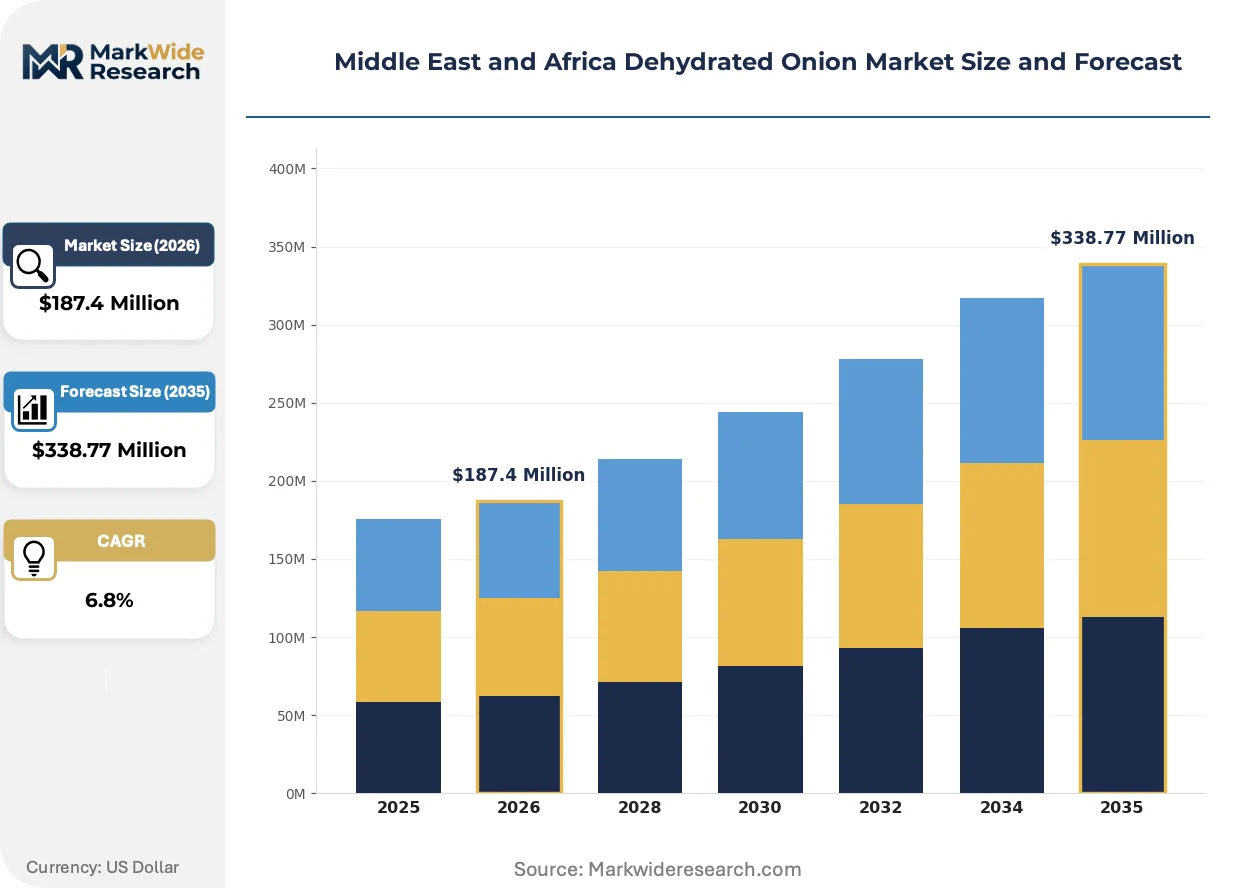
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Flakes, Powder, Whole Packaging Type: Bags, Jars, Vacuum Packs, Bulk Containers End Use: Food Processing, Snacks, Households, Restaurants Distribution Channel: Online Retail, Supermarkets, Wholesale, Specialty Stores |
| Companies Covered | Al Ghurair Foods LLC, Egyptian French Company, Al-Amir Dehydration Factory, Giza Seeds & Herbs Co., Future Foods, Kings Dehydrated Foods Pvt. Ltd., Olam Food Ingredients, Jain Farm Fresh Foods Limited, Sensient Natural Ingredients, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Dehydrated Onion Market Shifts & Advancements
Processing technology and procurement protocols across the Middle East and Africa are converging toward traceability-verified, energy-efficient dehydration systems that satisfy tightening Gulf import standards.
Low-temperature vacuum microwave dehydration is electrifying quality benchmarks in Egyptian processing plants. High-value seasoning blenders in Jeddah and Amman are specifying vacuum-dried flakes for color retention and volatile oil preservation. This thermal approach is electrifying premium-tier procurement, compressing conventional hot-air dried volumes into commodity positioning.
Saudi Food and Drug Authority import documentation requirements are tightening pesticide residue thresholds for dried vegetable shipments. Industrial buyers must now submit third-party laboratory certificates for every container crossing King Abdulaziz Port. Food manufacturers in Riyadh are responding by qualifying Egyptian suppliers with captive testing facilities, disqualifying traders reliant on external laboratories.
Long-term offtake contracting is displacing spot market purchasing among North African seasoning compounders. Three-year supply agreements with fixed volume floors and price collars now dominate procurement between major Cairo-based dehydrators and Gulf retail packers. This shift is most visible in UAE-based central kitchen operations serving quick-service restaurant chains, where supply security outweighs marginal cost savings from opportunistic buying.
Middle East and Africa Dehydrated Onion Market Segmentation
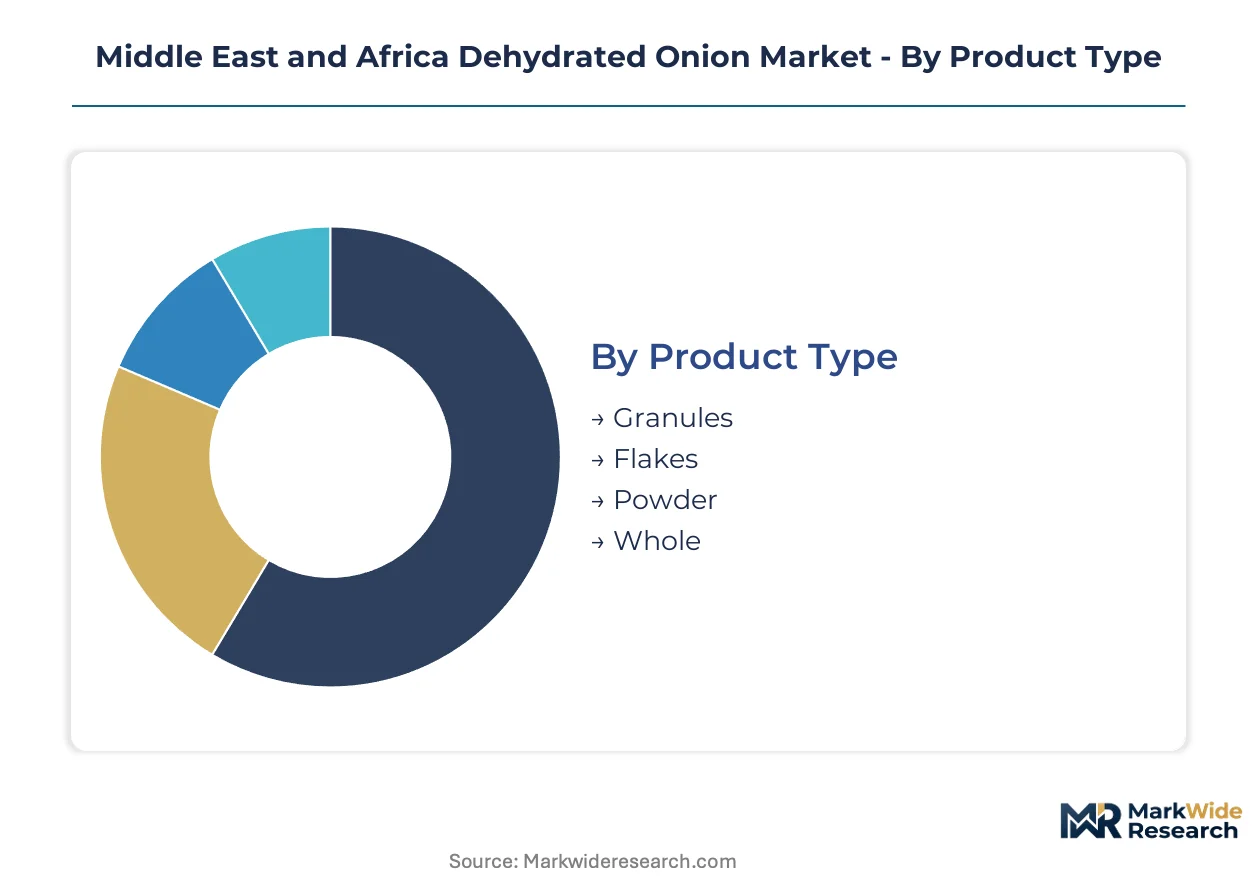
Dehydrated onion procurement across the Middle East and Africa fragments across four structural dimensions. Each dimension carries distinct certification burdens, packaging specifications, and channel economics that reshape supplier qualification requirements.
Product Type:
Powder and flake formats face divergent regulatory pathways under Saudi Food and Drug Authority import protocols, with powder requiring more stringent moisture-content documentation.
- Granules:Intermediate particle size between flakes and powder, optimized for dry soup mixes and seasoning blends where rapid hydration matters. Egyptian processors in the Nile Delta cluster dominate supply, with granule output flowing primarily to North African food manufacturers seeking uniform dissolution in reconstituted products.
- Flakes:Structural integrity survives thermal dehydration, preserving the layered morphology of fresh Allium cepa. Quick-service restaurant chains in Dubai and Riyadh specify flakes for toppings where visual recognition of onion pieces enhances perceived authenticity, constraining substitution by powder in premium foodservice applications.
- Powder:Homogeneous dispersibility drives procurement by industrial seasoning compounders. Fine milling to sub-500-micron particle size enables seamless integration into dry rubs and broth bases.
- Whole:Rings and sliced bulbs retain maximum volatile oil content, commanding niche positioning in gourmet retail channels. Limited dehydration throughput in the region restricts availability.
Powder sits at the top of the volume ranking, with flakes climbing the fastest as Gulf foodservice chains upgrade from commodity powder to texture-differentiated formats.
Packaging Type:
Packaging economics split sharply between industrial-scale procurement favoring bulk formats and retail channels demanding shelf-ready presentation with Arabic labeling compliance.
- Bags:Multi-layer polymer laminates dominate mid-volume industrial shipments, balancing moisture barrier performance against unit cost. Egyptian export facilities increasingly specify metallized films to satisfy extended Gulf transit timelines.
- Jars:Glass packaging penetrates premium retail shelves in UAE hypermarkets, where visibility and resealability support household repurchase rates. Higher freight costs from Cairo-based packers limit jar format competitiveness in distant African markets.
- Vacuum Packs:Oxygen exclusion extends shelf stability for high-value flake grades destined for European re-export through Moroccan processing hubs. Souss-Massa dehydration facilities are expanding vacuum line capacity to capture this arbitrage.
- Bulk Containers:Food-totes and fiber drums serve central kitchen operations and seasoning blenders with monthly throughput exceeding twenty metric tons. Direct procurement from Nile Delta processors bypasses distributor markups.
Bulk containers anchor procurement tonnage, though vacuum packs are gaining share fastest as Moroccan exporters target quality-sensitive European buyers.
End Use:
Application-driven segmentation reveals diverging technical specifications, with food processing demanding batch-to-batch consistency while restaurants prioritize sensory attributes.
- Food Processing:Industrial buyers in Saudi Arabia and Egypt embed dehydrated onion into shelf-stable meal kits, soup bases, and seasoning compounds. Procurement contracts specify maximum moisture thresholds and microbial load limits enforced through third-party laboratory certification.
- Snacks:Flake applications in baked and fried products emphasize color retention and volatile oil stability. Saudi snack manufacturers source vacuum-dried grades for premium positioning in domestic retail channels.
- Households:Consumer-packaged formats in 50-200 gram retail units serve home cooks seeking convenience without fresh onion preparation. UAE supermarket chains drive private-label development in this segment.
- Restaurants:Foodservice procurement splits between cost-optimized powder for sauce bases and premium flakes for garnish applications. Dubai-based fine dining maintains fresh onion specifications, capping dehydrated penetration.
Food processing commands the largest volume position, with snacks demonstrating the steepest expansion trajectory as regional savory snack production scales.
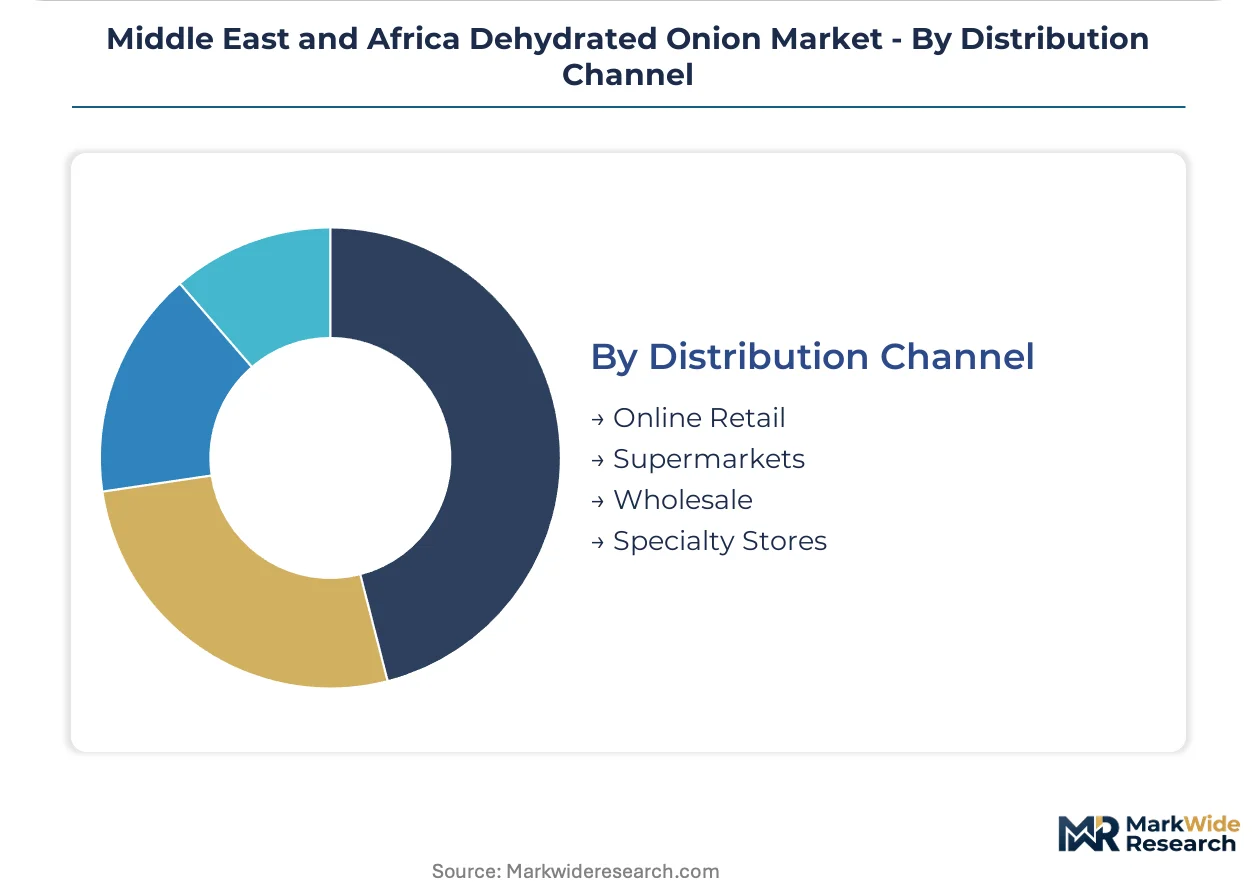
Distribution Channel:
Channel configuration determines supplier margin capture, with wholesale and direct industrial procurement compressing distributor layers while retail channels absorb higher logistics costs.
- Online Retail:B2B platforms connecting Ethiopian smallholder clusters to Egyptian processors are fragmenting traditional commodity broker dominance. Digital procurement reduces information asymmetry on quality grading.
- Supermarkets:Carrefour and Lulu Hypermarket chains across the GCC stock consumer-packaged dehydrated onion in dedicated spice aisles. Private-label penetration is rising as retailers consolidate supplier bases.
- Wholesale:Traditional spice souks and centralized produce markets in Cairo, Casablanca, and Riyadh handle commodity-grade powder and flake redistribution to smaller food manufacturers. Cash-based transactions persist alongside formal invoicing.
- Specialty Stores:Gourmet retailers in Johannesburg and Lagos curate premium vacuum-dried and organic-certified grades for expatriate and affluent local consumers. Limited shelf space constrains SKU breadth.
Wholesale channels retain volume leadership, though online retail is expanding most quickly as platform infrastructure matures across East African supply corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting dehydration investment toward Egyptian facilities where EOS conformity costs undercut Gulf certification burdens. Nile Delta processors leverage proximity to raw material clusters while serving re-export demand across Saudi Arabia and UAE import channels.
Egypt
Domestic food manufacturers and Gulf-facing exporters drive dehydrated onion absorption through integrated Nile Delta dehydration corridors. Egyptian Organization for Standardization certification requirements filter informal traders, concentrating volume through established facilities with captive laboratory capabilities. Cairo-based processors anchor regional supply security through photovoltaic-powered drying tunnels reducing natural gas dependency.
Saudi Arabia
Central kitchen operations and quick-service restaurant chains embed dehydrated onion into shelf-stable meal formulations across Riyadh and Jeddah. Saudi Food and Drug Authority import documentation tightens pesticide residue thresholds, forcing industrial buyers toward pre-certified Egyptian suppliers with third-party laboratory certificates. King Abdulaziz Port inspection protocols favor established processors over opportunistic traders.
United Arab Emirates
UAE hypermarket chains and foodservice distributors serve as re-export hubs for dehydrated onion flowing to African and South Asian markets. Dubai-based fine dining maintains fresh onion specifications, capping dehydrated penetration in premium foodservice segments. Carrefour and Lulu private-label development concentrates procurement toward bulk-container shipments from Nile Delta processors.
Morocco
Souss-Massa dehydration infrastructure targets European buyers seeking non-Egyptian origin diversification amid single-origin supply risk concerns. Vacuum pack capacity expansion captures quality-sensitive export demand through Moroccan processing hubs serving seasoning blenders in France and Spain. Underutilized thermal drying tunnels offer cost-competitive flake output for North African regional buyers.
South Africa
Department of Health labeling regulations shape import documentation for dehydrated onion entering Johannesburg and Cape Town distribution channels. Gourmet retailers curate premium vacuum-dried grades for expatriate and affluent local consumers with limited SKU breadth constraints. Specialty store positioning favors certified organic and halal-compliant product differentiation.
Middle East and Africa Dehydrated Onion Market Competitive Landscape
Long-term offtake contracting dominates the current landscape as Gulf buyers displace spot market purchasing with three-year supply agreements. The vendor base stratifies across integrated multinational ingredient suppliers, Nile Delta dehydration specialists, and regional trading houses. Two archetypes anchor procurement decisions: scale-driven processors with captive laboratory capabilities and proximity-focused operators leveraging raw material clusters. Competitive moves concentrate on strategic partnerships with food manufacturers and geographic expansion through Moroccan export corridor development.
Within the integrated multinational tier, Olam Food Ingredients anchors supply security through sourcing networks spanning multiple African onion-growing belts. Egyptian French Company occupies a position exemplifying proximity-driven cost competitiveness through Nile Delta cultivation zone access. Al Ghurair Foods LLC represents Gulf-based procurement consolidation serving UAE and Saudi re-export channels. These three entities illustrate how certification readiness and geographic positioning determine supplier qualification under tightening SFDA and EOS frameworks.
| Leading Market Players |
|---|
| Al Ghurair Foods LLC |
| Egyptian French Company |
| Al-Amir Dehydration Factory |
| Giza Seeds & Herbs Co. |
| Future Foods |
| Kings Dehydrated Foods Pvt. Ltd. |
| Olam Food Ingredients |
| Jain Farm Fresh Foods Limited |
| Sensient Natural Ingredients |
| Others |
Supply & Pricing Matrix
Captive laboratory integration at Egyptian dehydration facilities anchors both supply security and pricing power against opportunistic traders lacking in-house testing capabilities. Nile Delta processors with photovoltaic-powered drying tunnels command premium positioning through SFDA pre-certification, while non-integrated brokers face margin compression from extended inspection timelines at King Abdulaziz Port.
Pricing Analysis
Distributor margin layers in Cairo-based commodity markets absorb fifteen to twenty percent before bulk containers reach Gulf seasoning blenders, compressing net-back prices for Nile Delta dehydrators. Three-tier pricing structure across premium vacuum-dried, standard hot-air flakes, and economy powder grades differentiates procurement by end-use sophistication. Pricing pressure stems from raw onion harvest volatility in the Delta, where irrigation cost spikes transmit directly into processor margins. Quick-service restaurant chains in Riyadh demonstrate highest price sensitivity, while European buyers seeking Moroccan origin diversification accept elevated freight costs for supply security.
Supply Chain Analysis
Freight cost differentials between Alexandria-Jeddah container routes and Casablanca-Algeciras corridors shape procurement arbitrage for European seasoning compounders. Supply concentrates in Egypt, Morocco, and Ethiopia, with Ethiopian smallholder clusters feeding B2B platform disintermediation. Raw material dependencies center on Nile Delta Allium cepa cultivation, natural gas or photovoltaic thermal energy, and metallized film packaging laminates. Single-origin vulnerability from Egyptian production dominance exposes buyers to localized climate shocks and port congestion at Alexandria. Distribution runs through wholesale spice souks in Cairo, direct industrial procurement from dehydration facilities, and emerging B2B platforms connecting East African farmers to regional processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa dehydrated onion market functions as a geographic-arbitrage play where Egyptian EOS conformity costs undercut Gulf SFDA certification burdens, enabling Nile Delta processors to capture re-export margins into Saudi Arabia and UAE channels.
For Market Incumbents: Deploy captive laboratory capabilities as a qualification moat against opportunistic traders facing extended King Abdulaziz Port inspection delays. Consolidate procurement relationships through three-year offtake contracting with fixed volume floors, displacing spot market purchasing among North African seasoning compounders. Expand photovoltaic drying tunnel capacity to reduce natural gas dependency and stabilize operating margins against input cost volatility. For New Entrants and Emerging Players: Capture underutilized dehydration infrastructure in Morocco's Souss-Massa region to serve European buyers seeking non-Egyptian origin diversification. Target halal-certified ingredient positioning for Saudi Food and Drug Authority recognition, opening Gulf retail and institutional channels. Leverage B2B e-commerce platforms to disintermediate traditional commodity brokers connecting Ethiopian smallholder onion farmers to regional processors. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap dehydration specialists with captive laboratory capabilities because SFDA harmonization is filtering out informal traders and concentrating volume through pre-certified suppliers. The five-to-ten year viability window favors processors with backward integration into Nile Delta cultivation zones and photovoltaic energy infrastructure. Monitor Gulf Cooperation Council technical harmonization timelines as the inflection indicator for cross-border qualification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Drying Tunnel Deployment | Egyptian processors reduce natural gas dependency and stabilize margins against energy price volatility. |
| SFDA Pre-Certification Investment | Captive laboratory capabilities disqualify opportunistic traders at King Abdulaziz Port inspection points. |
| Moroccan Export Corridor Development | Souss-Massa vacuum pack capacity captures European buyers seeking origin diversification beyond Egypt. |
| Halal-Certified Processing Line Segregation | Dedicated production lines open Saudi retail and institutional channels for Egyptian suppliers. |
| B2B Platform Infrastructure Buildout | Digital procurement connecting Ethiopian smallholders to processors fragments traditional broker dominance. |
Research Methodology
Bottom-up food processing and foodservice demand modeling reconciled against top-down dehydration capacity and trade flow tracking forms the analytical core of this study. Primary interviews with dehydration facility managers, procurement leads at Gulf seasoning blenders, SFDA regulatory affairs specialists, and Nile Delta agricultural cooperative representatives combined with secondary validation from Egyptian Organization for Standardization conformity databases, Saudi Food and Drug Authority import documentation filings, customs and trade statistics, and industry association capacity surveys. Triangulation between consumption-side absorption estimates and supply-side production volumes ensures coherence across the analytical framework.
Historical trendline analysis of dehydrated onion trade flows, processing capacity utilization, and raw material price indices established baseline growth trajectories across the projection horizon. The forecast framework segments volume and value outputs by product type, packaging format, end-use application, and distribution channel, with additional granularity around certification tier and energy source for thermal dehydration. CAGRs derive from regression analysis against food processing industry expansion, quick-service restaurant chain penetration, and solar thermal drying adoption curves. Key inputs include Nile Delta harvest yield variability, GCC import documentation processing timelines, and European buyer origin diversification preferences.
Raw onion harvest shocks, regulatory harmonization delays, and logistics chokepoint congestion at Alexandria and King Abdulaziz Port are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about EOS and SFDA compliance cost evolution, photovoltaic adoption rates among Egyptian processors, and Moroccan infrastructure utilization. Stakeholders should weight assumptions against their own operating context and supply security requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Dehydrated Garlic Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Asia-Pacific Prepared Mustard Market
Spices and Condiments
Gravy Mixes Market
Spices and Condiments
Gourmet Salts Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Middle East and Mediterranean Tahini Market