
 Gourmet Salts Market | 2026-2036
Gourmet Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Gourmet Salts Market Analysis
REACH compliance is consolidating the cost-of-entry calculus for European gourmet salt importers, forcing smaller traders to invest in traceability documentation and third-party testing. SaltWorks, Inc. leverages its direct-source relationships with coastal evaporative farms to sustain supply consistency across premium sea salt grades. Maldon Crystal Salt Company Ltd. anchors its competitive position through controlled geographic branding of Essex-harvested pyramid crystals. Cargill Inc. competes by extending bulk logistics infrastructure into foodservice distribution channels that demand kosher and organic certifications.
Gourmet salts comprise minimally processed sodium chloride crystals harvested from evaporated seawater, underground mineral deposits, or saline lakes, typically retaining trace minerals such as magnesium, calcium, and potassium that influence flavor profile, moisture retention, and crystalline structure; these salts serve primarily as flavor-enhancing ingredients, finishing elements, and preservative agents across commercial kitchens and packaged food manufacturing. Sea salt and Himalayan pink salt together command the dominant share of premium shelf space, with Himalayan pink salt extracting higher per-unit margins due to its distinctive iron-oxide coloration and wellness-positioned marketing. Flavored salt represents the fastest-expanding product category as smoked, infused, and herb-blended variants capture experimentation-driven demand from home cooks and restaurant chefs seeking differentiated seasoning solutions.
The FDA governs food-grade salt labeling and anticaking additive thresholds in the United States, while the EFSA and EU Green Deal frameworks shape sustainable harvesting disclosure requirements across European supply chains. BIS standards in India and FSSAI packaging mandates are tightening quality benchmarks for imported specialty salts entering the country's expanding urban retail networks. Stakeholders must monitor evolving mineral-content disclosure rules and carbon-footprint tracking obligations that will determine which sourcing regions retain market access.
Market Dynamics
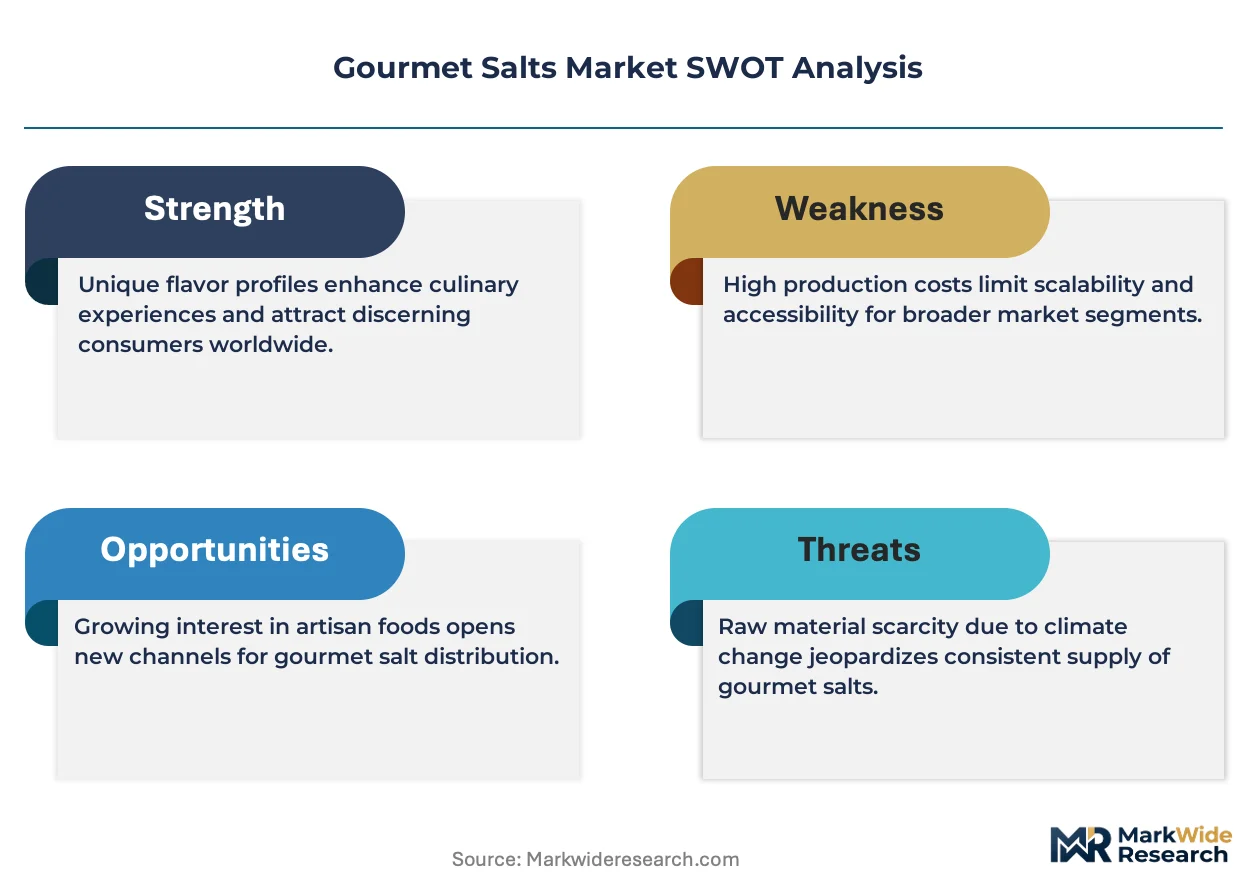
REACH compliance and EU F-Gas Regulation enforcement are consolidating European import requirements, forcing traceability investments that favor established processors with direct coastal sourcing relationships over smaller traders lacking documentation infrastructure.
Growth Catalysts
- Specialty restaurant expansion:Fine-dining establishments across France, Italy, and Spain are expanding artisanal salt procurement for finishing applications, creating steady demand for fleur de sel and sel gris varieties with documented provenance.
- EU Green Deal frameworks:Sustainable harvesting disclosure mandates are rewarding European salt processors who invest in carbon-footprint tracking, giving compliant producers preferential access to retail and foodservice channels.
- Himalayan deposit extraction:Controlled mining expansion in Pakistan's Khewra Salt Mine is stabilizing supply of iron-oxide-colored crystals for wellness-positioned consumer segments in North American and European markets.
Market Restraints
- Evaporative climate dependency:Coastal sea salt harvests in the Camargue and Guérande regions face yield volatility from irregular precipitation patterns and temperature fluctuations affecting evaporation pond productivity.
- Third-party testing costs:REACH-mandated mineral-content verification and heavy-metal screening impose fixed compliance burdens that disproportionately constrain small-volume importers lacking in-house laboratory capabilities.
- Iodized salt substitution:Government-mandated iodization programs in developing markets continue to displace unfortified gourmet varieties in household consumption, limiting category penetration outside premium urban retail networks.
Strategic Opportunities
- Indian urban retail expansion:FSSAI packaging mandate enforcement is professionalizing import channels for specialty salts entering Mumbai, Delhi, and Bangalore, creating first-mover advantages for compliant foreign suppliers.
- Smoked and infused variants:Cold-smoking and herb-infusion processing techniques are opening experimentation-driven demand from home cooks seeking differentiated seasoning solutions beyond commodity sea salt.
- Direct-to-chef distribution:Bypassing traditional wholesale intermediaries through specialized foodservice platforms allows premium producers to capture margin and build brand loyalty with restaurant decision-makers.
Industry Challenges
- Mineral-content standardization:Absence of harmonized international standards for trace element disclosure creates friction between producer claims and retailer verification requirements across US, EU, and Asian markets.
- Artisan credential authentication:Proliferation of mass-produced salts marketed with artisanal positioning complicates consumer trust-building and requires investment in protected geographic indication documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gourmet Salts Market |
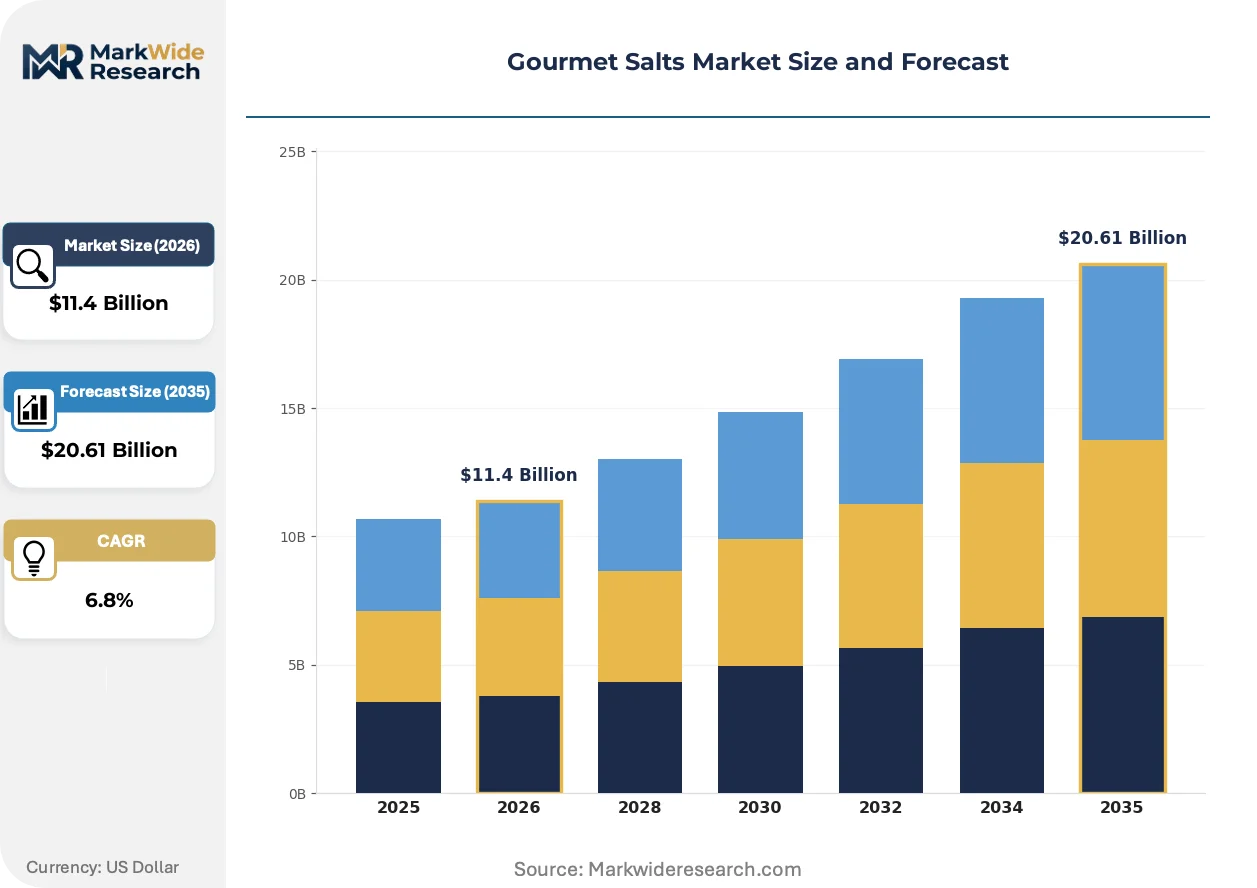
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sea Salt, Rock Salt, Himalayan Pink Salt, Flavored Salt Application: Culinary, Food Processing, Seasoning, Garnishing Packaging Type: Pouches, Jars, Bulk Bags, Sachets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | SaltWorks, Inc., Maldon Crystal Salt Company Ltd., Jacobsen Salt Co., Cargill Inc., Morton Salt, Inc., Celtic Sea Salt, Murray River Salt, Redmond Real Salt, Halen Môn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gourmet Salts Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are reshaping competitive positioning, with automation investments separating scalable producers from traditional harvesters while carbon-tracking mandates reward transparent supply chains.
Membrane filtration and controlled crystallization systems are modularizing production flexibility for mid-scale processors, allowing rapid grade switching between coarse, flake, and fine crystal outputs. Specialty food manufacturers and private-label retailers are adopting these systems to reduce minimum order quantities and compress new product introduction cycles. Equipment modularity is enabling regional processors to serve fragmented demand without sacrificing crystalline consistency.
EFSA mineral-content disclosure rules are tightening label accuracy requirements for sodium, magnesium, and potassium declarations on European retail packaging. Processors must now maintain batch-level testing records or risk market withdrawal, elevating laboratory partnerships from cost center to competitive necessity. French and Italian importers are responding by consolidating supplier relationships to reduce documentation complexity.
Chef-direct purchasing through specialized foodservice platforms is displacing traditional distributor intermediaries for premium salt procurement in North American and European urban markets. Restaurant groups with centralized procurement functions are negotiating annual contracts directly with coastal evaporative farms, capturing price transparency and origin documentation unavailable through conventional wholesale channels. This disintermediation is most advanced in California, New York, and London metropolitan areas.
Gourmet Salts Market Segmentation
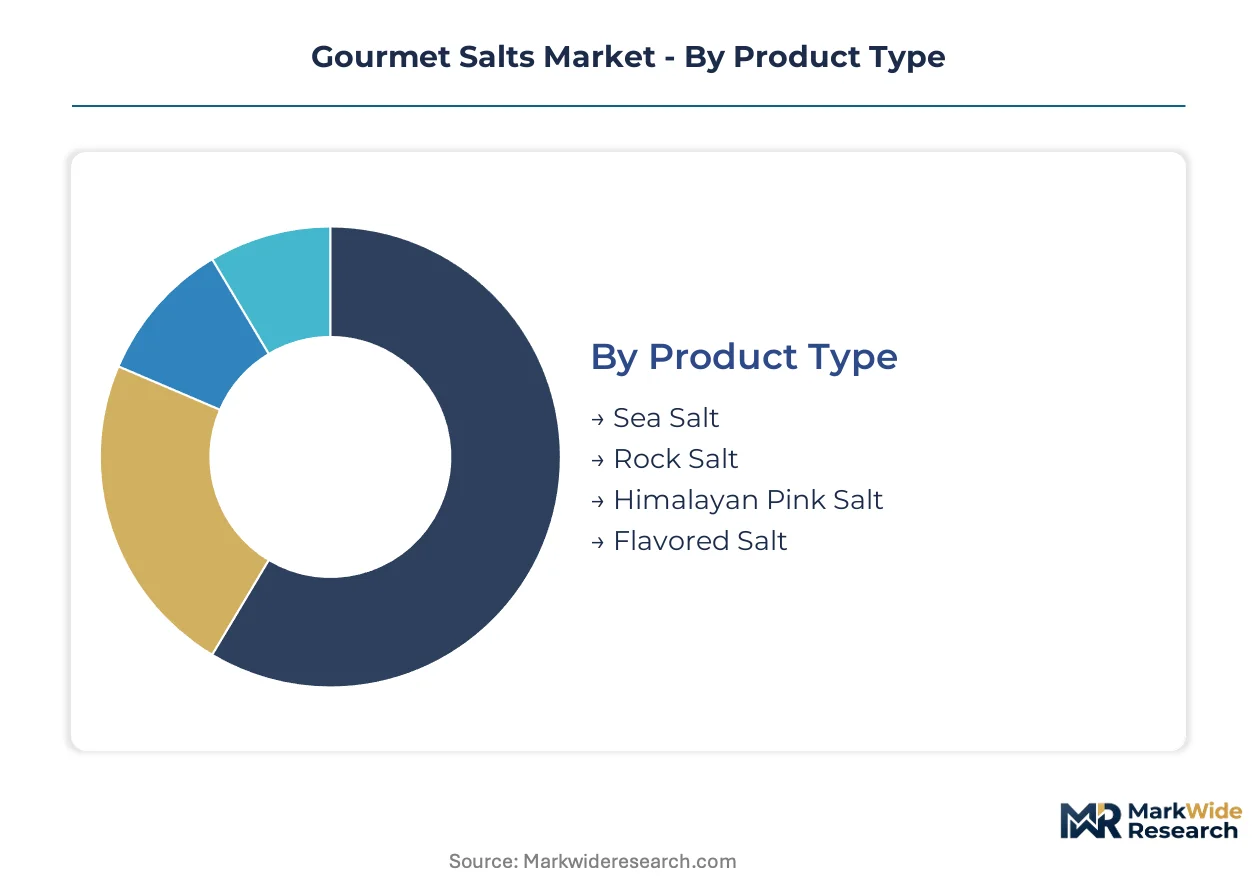
Gourmet salt segmentation reveals how capital deployment, regulatory exposure, and channel economics fragment opportunity across crystalline grades and end-use applications. Processors must align production infrastructure with specific segment requirements to capture margin.
Product Type:
Evaporative pond infrastructure and controlled mining operations demand the heaviest capital commitments, with crystallization technology investments determining scale feasibility across grades.
- Sea Salt:Harvested through solar evaporation of seawater in coastal ponds, retaining trace minerals that influence moisture retention and dissolution rate. Demand concentrates in French and Spanish fine-dining procurement for finishing applications, where documented Camargue or Guérande provenance commands price premiums. Climate volatility in Mediterranean evaporative zones constrains yield predictability.
- Himalayan Pink Salt:Extracted from Pakistan's Khewra Salt Mine, distinguished by iron-oxide-derived coloration and wellness-positioned mineral content claims. North American natural foods retail channels absorb the dominant volume, with direct-to-consumer subscription models capturing repeat purchase loyalty. Controlled mining expansion is stabilizing supply for export-grade crystal sorting.
- Rock Salt:Underground mineral deposits processed through mechanical crushing and screening, serving industrial-scale food manufacturing with consistent granulometry. Lower per-unit margins reflect commodity positioning.
- Flavored Salt:Cold-smoked, herb-infused, or spice-blended variants requiring secondary processing infrastructure. Home cook experimentation and chef-driven menu differentiation are expanding SKU proliferation fastest.
Most installed capacity flows through Sea Salt. Expansion is steepest in Flavored Salt.
Application:
End-use segmentation separates premium positioning from volume throughput, with culinary and garnishing applications capturing margin while food processing absorbs scale.
- Culinary:Restaurant kitchen deployment for cooking-stage seasoning, requiring consistent crystal size for dissolution control. Italian and Spanish specialty restaurant expansion is elevating procurement of documented-origin sel gris.
- Garnishing:Finishing-salt presentation at point of service, demanding distinctive crystalline structure and moisture content. Fleur de sel pyramid flakes dominate plating applications in Paris and London metropolitan fine-dining.
- Food Processing:Ingredient-scale supply to packaged food manufacturers, governed by kosher and organic certification requirements. Cargill's bulk logistics infrastructure serves this segment through foodservice distribution channels.
- Seasoning:Retail table-salt replacement and specialty blend components, competing with iodized commodity substitutes in household penetration.
Culinary applications command the highest per-kilogram pricing. Garnishing is gaining share fastest among premium-positioned producers.
Packaging Type:
Packaging segmentation reflects channel economics and consumer usage occasion, with format selection directly determining shelf placement and reorder velocity.
- Jars:Glass or ceramic containers supporting premium positioning and moisture protection. Specialty retail and gift-channel placement in urban Indian markets through FSSAI-compliant import channels.
- Pouches:Flexible film packaging for refill and pantry-stock occasions. Lower unit economics enable trial-size distribution in online retail.
- Bulk Bags:Foodservice and manufacturing procurement format, minimizing per-kilogram packaging cost. Chef-direct purchasing platforms are consolidating this channel in California and New York.
- Sachets:Single-serve hospitality and airline catering portions, governed by portion-control specifications.
Jars dominate retail shelf presence. Bulk Bags are expanding most quickly through disintermediated foodservice procurement.
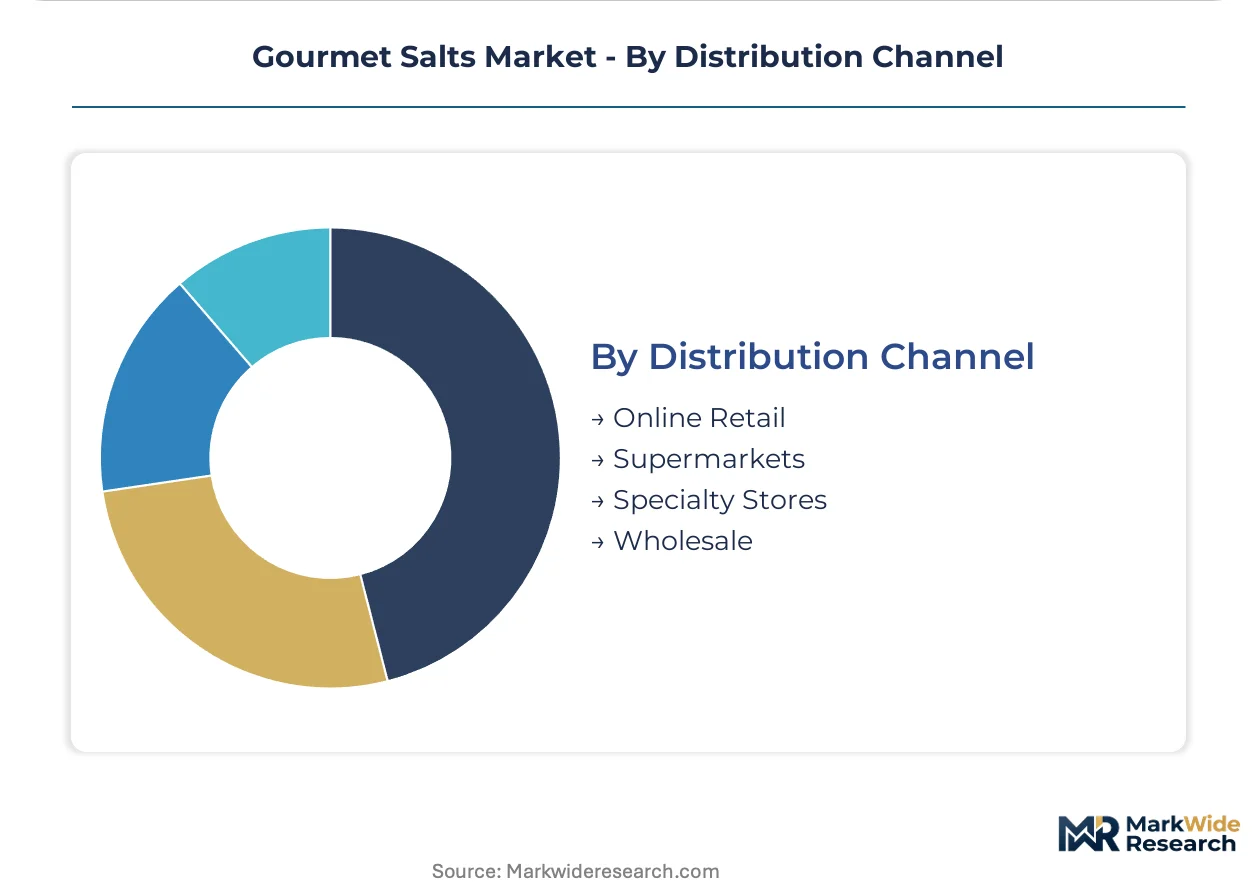
Distribution Channel:
Channel segmentation determines margin capture and brand control, with direct and specialty formats rewarding provenance documentation while mass retail rewards scale.
- Specialty Stores:Curated assortments emphasizing geographic indication and harvest method storytelling. Parisian épicerie fine and London deli networks anchor European premium placement.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription replenishment and wellness-positioned content marketing. Himalayan pink salt subscription models show strongest repeat rates.
- Supermarkets:Mass retail placement requiring slotting fee investment and private-label competitive pressure. Sea salt and rock salt dominate mainstream shelf space.
- Wholesale:Traditional distributor intermediaries serving fragmented foodservice accounts, losing share to chef-direct platforms in metropolitan clusters.
Specialty Stores retain the highest margin structure. Online Retail is climbing the fastest as subscription mechanics reduce customer acquisition cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal evaporative salt harvesters and underground mining workforces in France, Pakistan, and the United States anchor production capacity for premium crystalline grades.
France
Fleur de sel and sel gris traditions in the Guérande and Camargue marshlands sustain artisanal harvesting employment for seasonal pond workers. EU F-Gas Regulation and REACH compliance requirements elevate documentation burdens for coastal processors exporting crystalline finishing salts. Parisian fine-dining procurement clusters concentrate demand for pyramid-flake and grey-harvest varieties with protected geographic indication status.
United States
FDA food-grade labeling mandates govern anticaking additive thresholds for imported specialty salts entering natural foods retail channels. Himalayan pink salt distribution concentrates in California and New York metropolitan areas through direct-to-consumer subscription platforms. Chef-direct purchasing networks in Los Angeles and Brooklyn bypass traditional wholesale intermediaries for documented-origin sea salt procurement.
Pakistan
Controlled mining expansion at the Khewra Salt Mine stabilizes extraction employment for iron-oxide-colored crystal sorting and export-grade processing. National mineral export policies and provincial labor regulations shape workforce conditions for Himalayan pink salt production. Punjab-based processing clusters feed wellness-positioned demand in North American and European natural foods retail.
India
FSSAI packaging mandates and BIS quality standards professionalize import channels for specialty salts entering Mumbai, Delhi, and Bangalore urban retail networks. Traceability documentation requirements favor established foreign suppliers with laboratory partnerships over smaller traders. Maharashtra and Karnataka distribution hubs concentrate premium salt placement in specialty retail and hospitality procurement.
Australia
Murray River basin salt harvesting employs controlled evaporation techniques for distinctive peach-colored flake production. National food safety standards and state environmental regulations govern saline lake extraction permits and mineral-content disclosure. Victorian and South Australian processing facilities serve Asia-Pacific export demand through documented provenance supply chains.
Gourmet Salts Market Vendor Landscape
The competitive structure tilts toward geographically anchored specialists with direct coastal sourcing relationships rather than diversified commodity processors. Three archetypes dominate: evaporative pond harvesters with protected origin documentation, underground mining operators with wellness-positioned mineral claims, and diversified food-ingredient distributors with bulk logistics infrastructure. Capacity expansion through automated crystallization systems and backward integration into coastal leaseholds represent the dominant competitive moves.
Among North American coastal specialists, Jacobsen Salt Co. and SaltWorks, Inc. occupy positions within the direct-source archetype, while Cargill Inc. exemplifies the diversified infrastructure tier with foodservice distribution reach. Maldon Crystal Salt Company Ltd. represents the protected-origin model through Essex-harvested pyramid crystal branding. These four entities illustrate how geographic concentration, regulatory compliance depth, and channel access separate scalable competitors from fragmented local harvesters.
| Leading Market Players |
|---|
| SaltWorks, Inc. |
| Maldon Crystal Salt Company Ltd. |
| Jacobsen Salt Co. |
| Cargill Inc. |
| Morton Salt, Inc. |
| Celtic Sea Salt |
| Murray River Salt |
| Redmond Real Salt |
| Halen Môn |
| Others |
Supply Flow & Price Mechanics
Seasonal pond workers in France's Guérande and Camargue marshlands anchor labor-cost differentials that widen pricing spreads between fleur de sel pyramid crystals and commodity evaporative grades. REACH-mandated documentation and third-party mineral testing elevate European processing costs, compressing margins for importers lacking direct coastal leaseholds while rewarding backward-integrated harvesters with captive supply chains.
Pricing Analysis
Bundled certification-and-origin documentation separates premium fleur de sel pricing from unbundled commodity sea salt transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by crystalline grade, geographic indication status, and kosher or organic certification tier. Pricing pressure stems from REACH compliance cost absorption disproportionately burdening small-volume traders without in-house laboratory capabilities. Food processing buyers exhibit highest price sensitivity due to bulk volume procurement and substitute availability, while fine-dining establishments demonstrate lowest sensitivity where documented provenance commands menu pricing power.
Supply Chain Analysis
Container freight differentials between Mediterranean and Asia-Pacific lanes concentrate margin pressure on Pakistani exporters serving North American wellness retail channels. Supply concentrates in France, Pakistan, and Australia, with Khewra Salt Mine extraction, Guérande evaporative ponds, and Murray River basin harvesting feeding distinct crystalline grades. Raw material dependencies center on saline water access, controlled climate evaporation infrastructure, and iron-oxide mineral deposit quality. Single-source vulnerability from Pakistan's Khewra Mine dominance in Himalayan pink salt creates geopolitical and logistics chokepoint exposure. Distribution runs through chef-direct platforms displacing wholesale intermediaries in California and New York metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specialty restaurant procurement is shifting toward documented-origin finishing salts with protected geographic indication status. Premium crystalline grades now outpace commodity volume growth as chef-driven menu differentiation elevates provenance requirements.
For Market Incumbents: Lock in coastal evaporative leaseholds through long-term pond access agreements before regulatory consolidation restricts new entrant harvesting permits. Invest in automated crystallization systems to reduce batch-to-batch mineral-content variance that EFSA disclosure rules now penalize. Defend against chef-direct platform disintermediation by building proprietary foodservice distribution relationships with documented traceability dashboards.
For New Entrants and Emerging Players: Enter via smoked and infused salt processing where secondary manufacturing infrastructure requirements create lower capital barriers than evaporative pond establishment. Target Indian urban retail expansion through FSSAI-compliant import channels where professionalizing quality standards favor first-mover laboratory partnerships. Deploy direct-to-consumer subscription mechanics with wellness-positioned content marketing to capture Himalayan pink salt repeat purchase loyalty.
For Investors and Strategic Acquirers: Food-ingredient distributors with bulk logistics infrastructure are the most active acquirer in this space, seeking backward integration into coastal harvesting capacity. Long-term viability centers on carbon-footprint tracking compliance rewarding transparent supply chains with preferential retail access. Monitor EU Green Deal sustainable harvesting disclosure enforcement as the inflection signal determining which sourcing regions retain market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Coastal Leasehold Acquisition | Secures evaporative pond access ahead of REACH documentation requirements tightening supply. |
| Automated Crystallization Deployment | Enables rapid grade switching between fleur de sel and sel gris outputs for restaurant demand. |
| Carbon-Footprint Tracking Implementation | Meets EU Green Deal disclosure mandates for preferential retail channel positioning. |
| Chef-Direct Platform Launch | Bypasses wholesale intermediaries to capture margin in California and New York procurement clusters. |
| Laboratory Partnership Consolidation | Reduces REACH-mandated mineral-content verification costs through batch-level testing scale. |
Methodological Framework
Bottom-up foodservice procurement modeling reconciled against top-down evaporative harvest tracking forms the analytical core of this study. Primary interviews with coastal salt harvesters, specialty restaurant procurement directors, FSSAI compliance officers, and natural foods retail category buyers combined with secondary validation from customs trade records, EFSA mineral-content disclosure filings, and EU F-Gas Regulation enforcement reports. Triangulation between supply-side capacity surveys and demand-side channel audits ensures segmentation integrity across crystalline grades and end-use applications.
Historical trendline analysis of fleur de sel and sel gris pricing trajectories anchored the projection framework across the analysis window. Segmentation modeling incorporated product type, application, packaging format, and distribution channel dimensions with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to documented-origin premium salt procurement volumes and wellness-positioned retail absorption rates. Forecast inputs included climate volatility indices for Mediterranean evaporative zones and controlled mining expansion schedules at Pakistan's Khewra Salt Mine.
Inputs from customs databases and regulatory filing repositories were available through the study window; gaps in real-time chef-direct platform transaction data introduce uncertainty bands around foodservice channel share estimates. Forecasts reflect assumptions regarding EU Green Deal enforcement timing and FSSAI packaging mandate implementation pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Asia-Pacific Dehydrated Onion Market
Spices and Condiments
Middle East and Mediterranean Tahini Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Paprika Market
Spices and Condiments
Global Pickles and Pickle Products Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Gravy Mixes Market
Spices and Condiments
Japanese Curry Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market
Spices and Condiments
Rosemary Extracts Market