
 In-Flight Advertising Market | 2026-2036
In-Flight Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
In-Flight Advertising Market Insights
Buyer concentration across airline groups is broadening as legacy carriers fragment media procurement across low-cost subsidiaries and alliance partners. Panasonic Avionics Corporation leverages its seatback screen dominance to anchor long-term hardware-plus-content contracts with full-service airlines. Spafax competes through specialized lifestyle magazine and digital content curation for premium cabin segments. JCDecaux extends its airport-to-aircraft advertising continuity across major European hub operations.
In-flight advertising comprises paid promotional content delivered through cabin-installed media channels including seatback displays, overhead monitors, tray table surfaces, Wi-Fi login portals, and ambient branding elements within aircraft interiors. These systems operate on aviation-certified hardware meeting DO-160G environmental standards for electromagnetic interference, vibration tolerance, and altitude pressure cycling. Video commercials and interactive content command premium rates due to passenger captivity and dwell time, while banner ads and sponsored content scale efficiently across narrow-body fleets with lighter digital infrastructure. Business travelers and frequent flyers represent concentrated value pools for financial institutions and luxury goods advertisers, whereas leisure passengers and family units attract travel services and food and beverage campaigns through destination-targeted messaging.
The FAA governs portable electronic device transmission protocols that determine when passengers may access Wi-Fi portals serving advertising content, while EASA's cabin equipment certification under CS-25 shapes screen installation timelines for European-registered aircraft. The UAE's General Civil Aviation Authority coordinates with hub carriers based in Dubai and Abu Dhabi to harmonize passenger experience standards with advertising integration. Stakeholders must monitor evolving cybersecurity requirements for connected cabin systems as regulators tighten data governance over passenger-facing digital platforms.
Market Dynamics
Airlines are retrofitting narrow-body fleets with lightweight streaming hardware, fragmenting advertising procurement across legacy carriers and their low-cost subsidiaries. This hardware transition is compressing contract timelines and forcing media buyers to negotiate across incompatible cabin technology stacks.
Growth Catalysts
- DO-160G Certification Pathways:The FAA's streamlined electromagnetic interference testing for portable electronic devices accelerates Wi-Fi portal deployment timelines. Airlines now install advertising-serving connectivity hardware during scheduled maintenance windows rather than dedicated groundings.
- Hub Carrier Fleet Expansion:Full-service airlines in the United Arab Emirates and China are adding twin-aisle aircraft with factory-installed seatback screens. These platforms command premium advertising rates through captive passenger dwell time.
- Programmatic Ad Insertion:Real-time bidding systems are replacing static content loops on overhead monitors. This technology enables destination-targeted campaigns that rotate based on flight route and passenger demographics.
Market Restraints
- Aviation-Grade Display Supply Concentration:Three specialized manufacturers control production of cabin-certified screens meeting altitude pressure cycling requirements. This concentration creates procurement bottlenecks during fleet-wide retrofit programs.
- FAA Transmission Protocol Limitations:Portable electronic device restrictions govern when passengers may access Wi-Fi portals below 10,000 feet. These rules compress the advertising impression window during short-haul segments.
- Content Localization Costs:Multi-language dubbing and cultural adaptation for premium cabin magazines inflate production budgets. Advertisers absorb these costs or accept reduced relevance across diverse route networks.
Strategic Opportunities
- India Domestic Route Penetration:Low-cost carriers operate the world's fastest-growing narrow-body fleet without seatback screens. Streaming-to-device advertising models bypass hardware installation entirely.
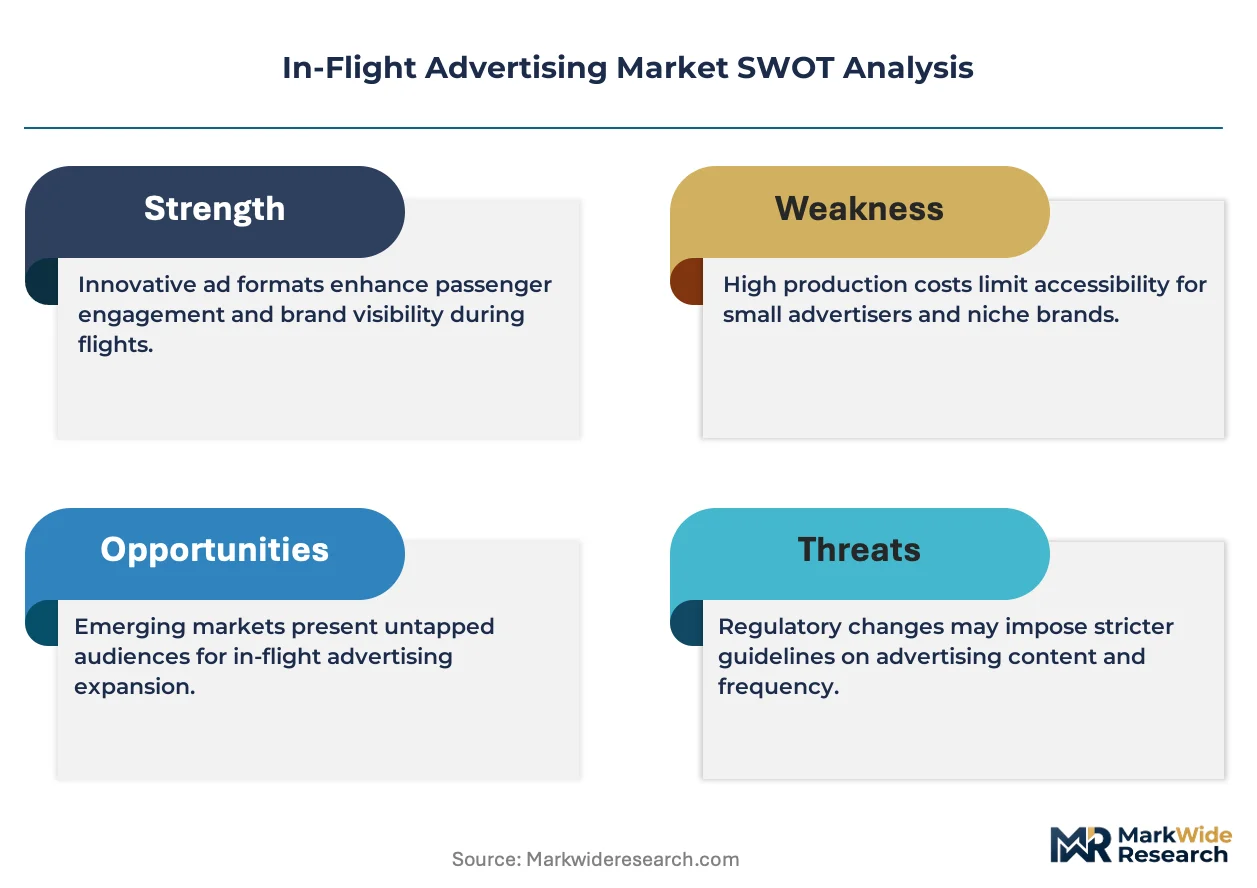
- EASA Cybersecurity Mandates:The EU's incoming connected cabin data governance rules will favor vendors with pre-certified secure content delivery architectures. Early compliance creates vendor lock-in advantages.
- Ambient Branding Integration:LED mood lighting systems and galley surface treatments now accept programmable brand color schemes. These placements capture attention during boarding and deplaning sequences.
Industry Challenges
- Legacy IFE System Interoperability:Airlines operate mixed fleets with seatback screens from multiple generations. Advertisers must transcode content across incompatible file formats and aspect ratios.
- Cybersecurity Certification Timelines:Connected cabin platforms require airworthiness authority approval for passenger data handling. These reviews extend campaign launch schedules by 6-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Flight Advertising Market |
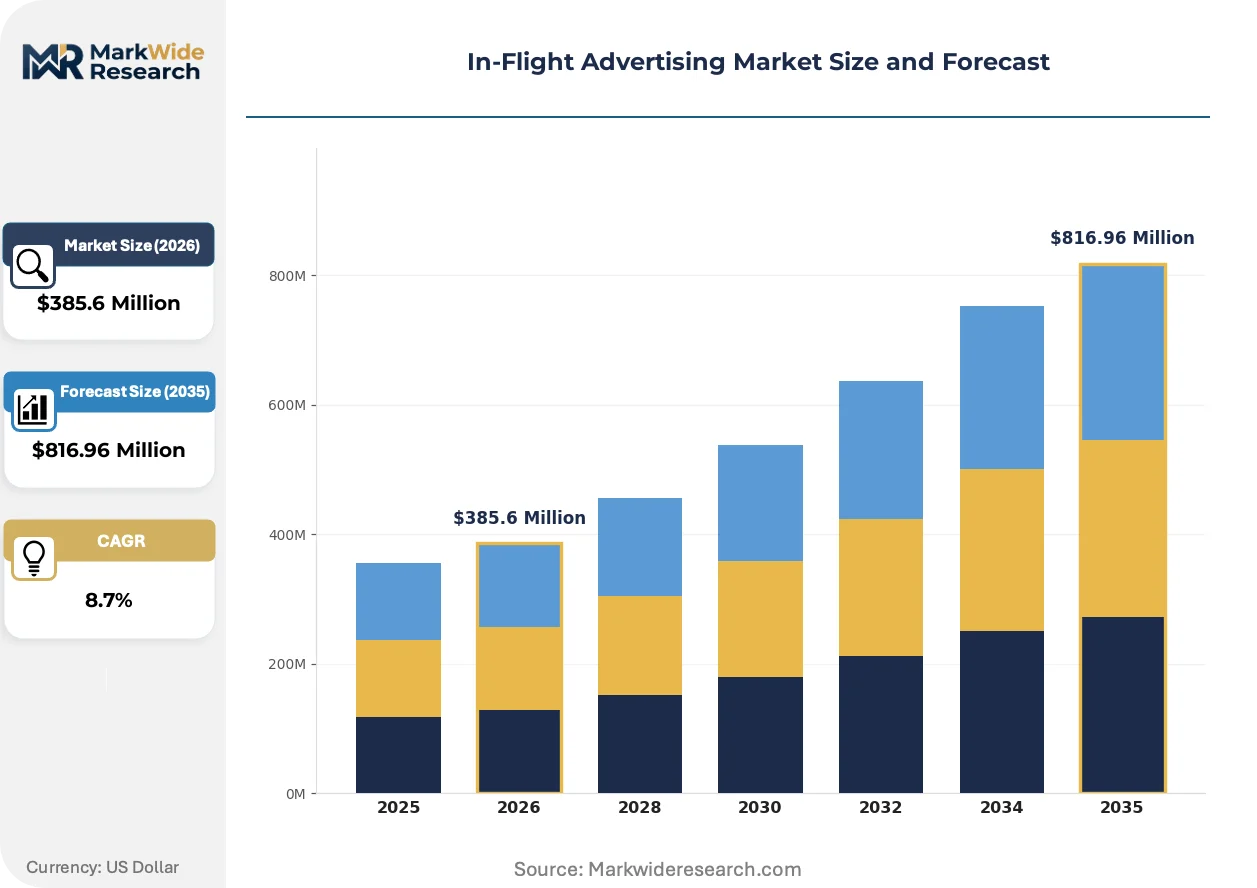
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Seatback Screens, Overhead Displays, In-Cabin Magazines, Tray Table Ads, Wi-Fi Portals, Ambient Media Ad Format: Video Commercials, Banner Ads, Interactive Content, Audio Announcements, Sponsored Content, Digital Coupons Target Audience: Business Travelers, Leisure Passengers, Frequent Flyers, First-Time Flyers, Corporate Clients, Family Units Advertiser Type: Consumer Electronics, Luxury Goods, Travel Services, Financial Institutions, Entertainment Media, Food & Beverage |
| Companies Covered | Panasonic Avionics Corporation, IMM International, EAM Advertising LLC, In-flight Media, Global Eagle, JCDecaux, Spafax, INK, MaXposure Media Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Flight Advertising Market Trends and Innovations
Streaming-to-device architectures are displacing seatback hardware as the primary advertising delivery mechanism. This shift fragments technical standards while opening inventory on previously unreachable narrow-body aircraft.
Edge computing nodes installed within aircraft cabins are decentralizing content storage and ad serving decisions. Low-cost carriers without legacy in-flight entertainment infrastructure adopt these systems fastest. The technology is decentralizing campaign management away from ground-based servers toward localized decision engines that function during satellite connectivity gaps.
EASA's forthcoming CS-25 amendments for connected cabin equipment will mandate encrypted passenger data pathways. Airlines operating European-registered aircraft face hardware upgrade costs or fleet re-registration decisions. Narrow-body operators with mixed registrations are consolidating procurement under EASA-compliant vendors to simplify compliance.
Media buyers now unbundle campaign commitments across alliance partner networks rather than contracting with individual carriers. This aggregation compresses rate negotiation cycles and shifts performance risk to advertising agencies. The practice is most visible in transatlantic route clusters where joint ventures coordinate passenger experience standards.
In-Flight Advertising Market Segmentation
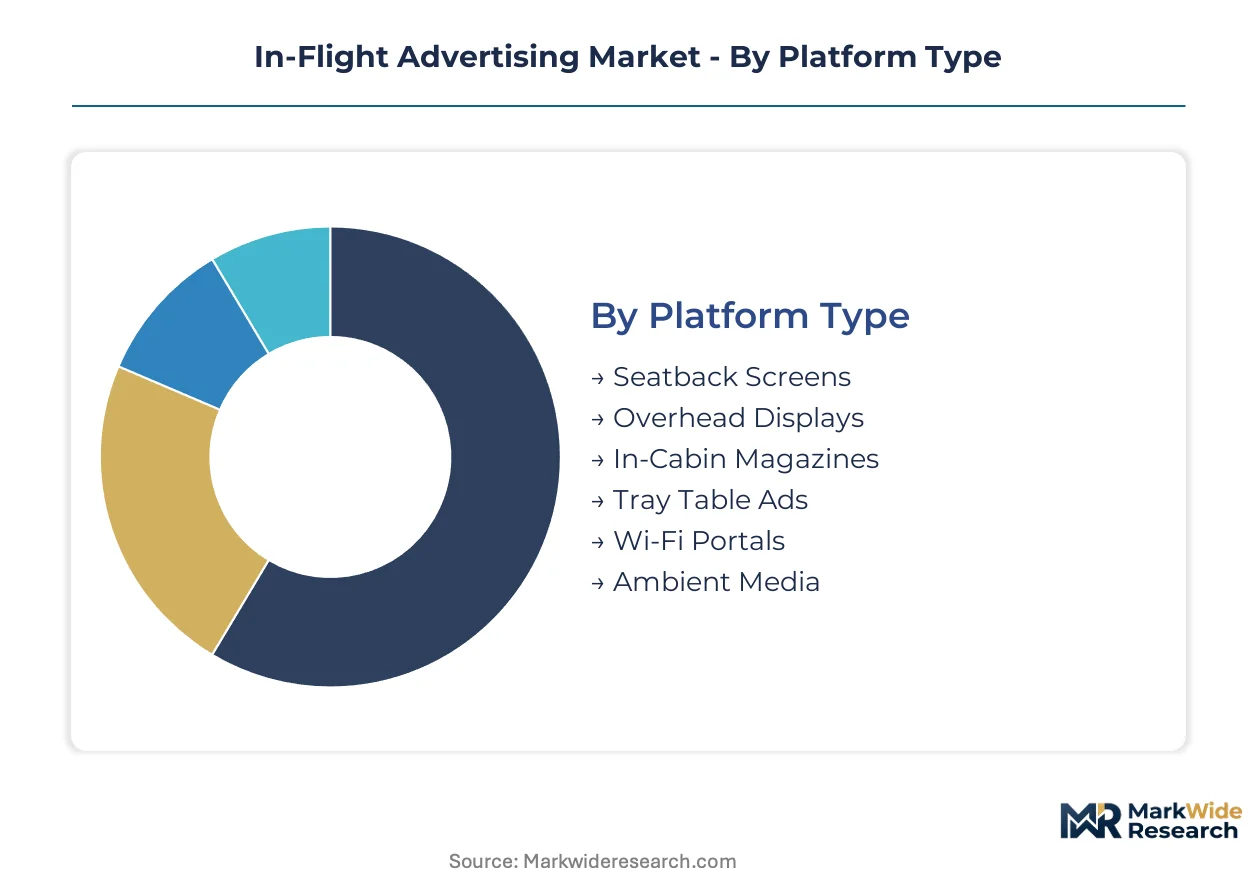
Platform type determines hardware investment requirements and captive engagement duration. Ad format shapes production budgets and real-time personalization capabilities. Advertiser type and target audience alignment dictate rate premiums across cabin classes and route networks.
Platform Type:
Standalone systems operate independently of passenger devices, while embedded platforms integrate with airline infrastructure and connectivity stacks.
- Seatback Screens:Dedicated aviation-grade displays installed at each passenger position, meeting DO-160G standards for electromagnetic interference and altitude pressure cycling. Full-service carriers in the United States and the United Arab Emirates command premium rates through guaranteed dwell time and interactive capabilities. Supply bottlenecks from three specialized manufacturers constrain fleet-wide deployment timelines.
- Wi-Fi Portals:Advertising-serving login gateways accessed through passenger smartphones and tablets, bypassing hardware installation entirely. Low-cost carriers across India and Southeast Asia adopt this model fastest, though FAA transmission protocols below 10,000 feet compress impression windows on short-haul segments.
- Overhead Displays:Cabin-mounted monitors delivering synchronized video loops to economy sections.
- In-Cabin Magazines:Printed lifestyle publications stowed in seatback pockets, requiring multi-language localization.
- Tray Table Ads:Laminated surface branding on folding meal trays, common on narrow-body fleets.
- Ambient Media:LED mood lighting and galley surface treatments programmable with brand color schemes.
Seatback screens lead volumes today; Wi-Fi portals are gaining share fastest.
Ad Format:
Production complexity and personalization potential separate premium formats from scalable inventory.
- Video Commercials:High-definition motion content delivered through seatback or overhead displays, commanding rate premiums due to passenger captivity and audio-visual engagement. Hub carriers in China and the United Arab Emirates prioritize factory-installed screen infrastructure to anchor these placements on long-haul routes.
- Interactive Content:Touch-enabled or QR-code-activated experiences requiring passenger device integration. Real-time bidding systems now rotate destination-targeted campaigns based on flight route data, though cybersecurity certification timelines extend campaign launches by 6-18 months.
- Banner Ads:Static or lightly animated display units scaling efficiently across lighter digital infrastructure.
- Audio Announcements:Sponsored pre-flight safety or destination messaging delivered through cabin PA systems.
- Sponsored Content:Editorial-style placements within in-flight magazines or streaming libraries.
- Digital Coupons:QR-code offers redeemable at destination retailers or airport concessions.
Video commercials dominate revenue; interactive content shows the steepest expansion trajectory.
Target Audience:
Value concentration and messaging relevance vary sharply across passenger behavioral segments.
- Business Travelers:Premium cabin frequent flyers with concentrated purchasing power for financial services and luxury goods. Airlines segment this pool through loyalty program data, though privacy regulations constrain personalization depth in European-registered aircraft under EASA's incoming connected cabin rules.
- Family Units:Leisure passengers traveling with children, attracting destination-targeted travel services and food and beverage campaigns. Low-cost subsidiaries of legacy groups fragment procurement to reach this segment across incompatible technology stacks.
- Leisure Passengers:Price-sensitive travelers prioritizing experience over cabin class.
- Frequent Flyers:High-mileage program members with established brand relationships.
- First-Time Flyers:Passengers requiring introductory messaging and simplified navigation.
- Corporate Clients:Contracted enterprise travelers with negotiated route commitments.
Business travelers anchor rate premiums; family units are expanding most quickly as narrow-body fleet growth penetrates leisure routes.
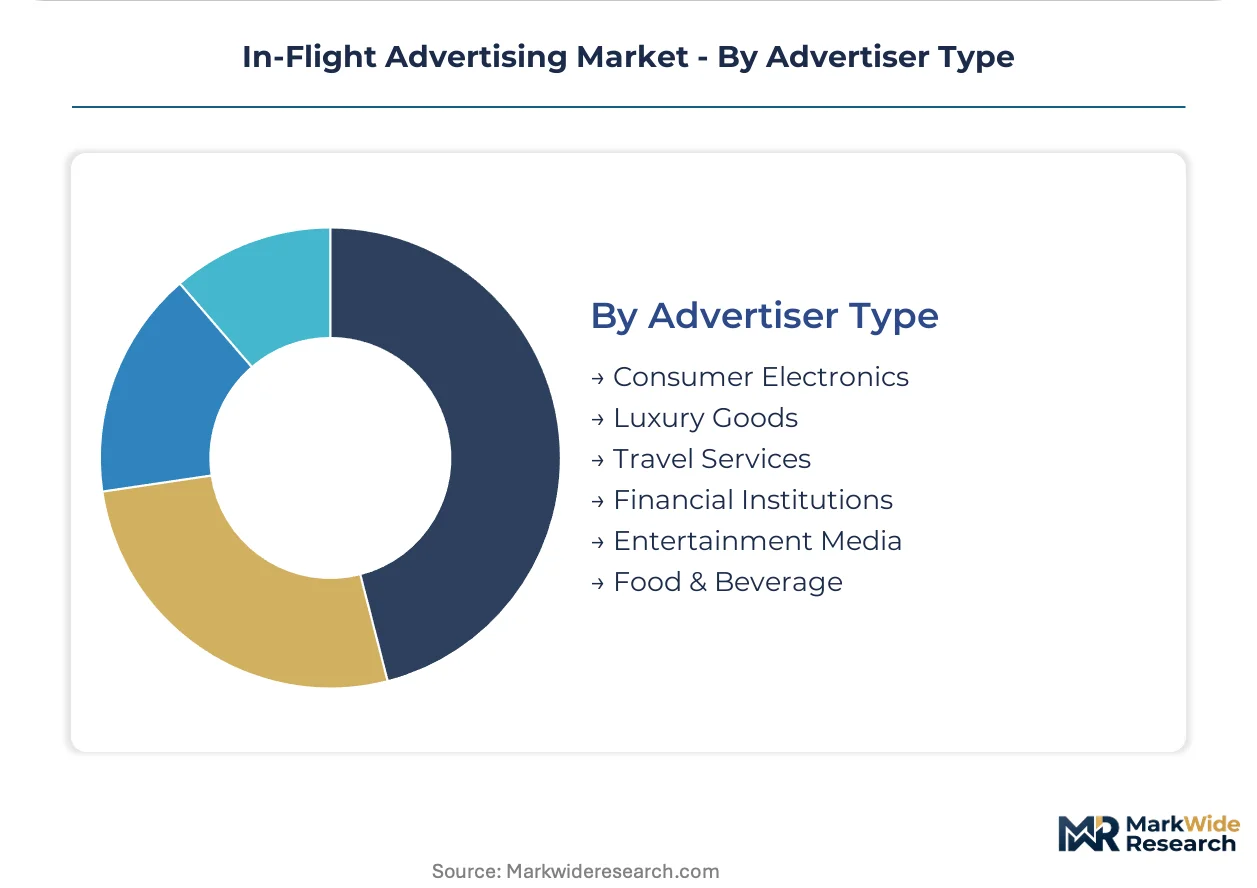
Advertiser Type:
Category concentration shapes creative production standards and campaign renewal cycles.
- Financial Institutions:Banks, insurance providers, and wealth managers targeting premium cabin business travelers with high-net-worth product suites. These advertisers accept multi-language localization costs to maintain relevance across diverse hub-and-spoke networks operated by alliance partners.
- Travel Services:Hotels, car rental firms, and experience platforms leveraging destination-targeted messaging. Programmatic insertion enables real-time rotation based on arrival city, though content adaptation inflates production budgets for multi-route campaigns.
- Consumer Electronics:Device manufacturers promoting new releases through video and interactive formats.
- Luxury Goods:High-end retailers and fashion houses prioritizing premium cabin placements.
- Entertainment Media:Streaming services and studios promoting destination-relevant content libraries.
- Food & Beverage:Restaurant chains and packaged goods brands targeting family and leisure segments.
Financial institutions commit the longest contract terms; travel services are climbing the fastest as programmatic targeting matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace engineering talent clusters in Seattle, Toulouse, and Hamburg anchor the industry's geographic footprint. Regulatory divergence between the FAA, EASA, and China's CAAC shapes hardware deployment timelines across major aviation hubs.
United States
Full-service carriers in Dallas-Fort Worth and Atlanta retrofit narrow-body fleets with streaming-to-device architectures. The FAA's DO-160G certification pathways compress installation schedules during scheduled maintenance windows. Chicago-based media buyers now unbundle commitments across alliance partner networks to reach fragmented fleet configurations.
China
Hub carriers in Beijing and Shanghai add twin-aisle aircraft with factory-installed seatback screens at accelerating rates. CAAC harmonizes cabin connectivity standards with international norms while maintaining domestic certification autonomy. The Yangtze River Delta concentration supports specialized display manufacturing for aviation-grade hardware.
United Arab Emirates
Dubai and Abu Dhabi-based carriers command premium advertising rates through guaranteed dwell time on long-haul routes. The General Civil Aviation Authority coordinates passenger experience standards with advertising integration across hub operations. Emirates' fleet expansion drives demand for synchronized content delivery across mixed aircraft generations.
Germany
Lufthansa Group's Frankfurt and Munich hubs anchor European premium cabin inventory. EASA's CS-25 amendments for connected cabin equipment mandate encrypted passenger data pathways, favoring pre-certified vendors. Hamburg's aerospace cluster supplies aviation-grade display systems meeting altitude pressure cycling requirements.
India
Low-cost carriers operating from Mumbai and Delhi deploy streaming-to-device models that bypass hardware installation entirely. The Directorate General of Civil Aviation oversees rapid fleet expansion without seatback screen infrastructure. Domestic route density creates scalable inventory for destination-targeted campaigns through passenger-owned devices.
In-Flight Advertising Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across incompatible technology stacks. The market structure concentrates around aviation-certified hardware vendors and specialized media agencies serving distinct cabin segments. Three archetypes dominate: seatback screen manufacturers anchoring long-term contracts, content curators targeting premium demographics, and airport-to-aircraft continuity providers. Competitive moves center on strategic partnerships bridging hardware and media procurement, plus programmatic technology licensing to enable real-time bidding.
Within the hardware-plus-content tier, Panasonic Avionics Corporation represents the integrated systems archetype, while Spafax exemplifies specialized lifestyle curation for premium cabin segments. JCDecaux occupies a position bridging airport and aircraft advertising continuity across European hub operations.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| IMM International |
| EAM Advertising LLC |
| In-flight Media |
| Global Eagle |
| JCDecaux |
| Spafax |
| INK |
| MaXposure Media Group |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up media agencies now control advertising procurement for major airline groups, compressing rate negotiations while pushing hardware vendors toward longer-term bundled service contracts. This ownership concentration tightens pricing discipline across seatback screen deployments and Wi-Fi portal integrations, linking financing structures directly to fleet retrofit timelines.
Pricing Analysis
Bundled hardware-plus-content contracts dominate full-service carrier relationships, while unbundled programmatic access gains traction among low-cost operators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with DO-160G-compliant seatback inventory commanding substantial premiums over streaming-to-device alternatives. Cost compression in narrow-body retrofit tiers is intensifying because procurement fragmentation across alliance networks forces vendors to absorb integration complexity. Low-cost subsidiaries exhibit highest price sensitivity, whereas hub carriers in the United Arab Emirates and China demonstrate lowest sensitivity due to guaranteed dwell-time premiums.
Supply Chain Analysis
Aviation-grade display certification under DO-160G and EASA CS-25 gates supplier entry, restricting qualified manufacturing to specialized operations in the United States, Germany, and Japan. Production draws from gallium nitride semiconductors, optical-grade polarizing films, and electromagnetic shielding composites. Single-source vulnerability concentrates in cabin-certified screen substrates, where three manufacturers control altitude pressure cycling validation. Distribution runs through airline procurement departments and fleet management divisions, with hardware vendors maintaining direct technical integration relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through streaming-to-device architectures that eliminate seatback hardware capital intensity while preserving advertising yield. The shift from installed-base to passenger-owned delivery reduces fleet-specific certification burdens and accelerates inventory scaling.
For Market Incumbents: Extend programmatic technology licensing to low-cost carrier networks before streaming-native competitors establish platform standards. Consolidate content transcoding capabilities across mixed-generation seatback fleets to defend against specialist agencies fragmenting procurement. Vertical integration into edge computing node manufacturing secures vendor lock-in as EASA cybersecurity mandates tighten.
For New Entrants and Emerging Players: Edge computing nodes for ad serving decentralization offer immediate white-space entry, bypassing ground-based server dependencies that incumbent platforms maintain. India's domestic narrow-body fleet without seatback infrastructure represents the most penetrable geography, with streaming-to-device models eliminating hardware installation barriers entirely. Partner with low-cost carrier technology procurement teams on revenue-share arrangements rather than upfront licensing fees.
For Investors and Strategic Acquirers: Valuations sit cheapest among content curation specialists with premium cabin magazine franchises and digital adaptation capabilities. Long-term viability hinges on regulatory compliance breadth across FAA, EASA, and CAAC jurisdictions, favoring vendors with pre-certified secure delivery architectures. Watch EASA's CS-25 amendment implementation timeline as the critical inflection signal for connected cabin hardware upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Ad Insertion Platform Launch | Enables real-time bidding across overhead monitors and Wi-Fi portals, displacing static content loops. |
| EASA Cybersecurity Pre-Certification Investment | Creates vendor lock-in advantage as European-registered aircraft face encrypted data pathway mandates. |
| Streaming-to-Device Architecture Deployment | Bypasses aviation-grade display supply bottlenecks while accessing India's rapidly expanding narrow-body fleet. |
| Alliance Network Procurement Consolidation | Compresses rate negotiation cycles across joint venture route clusters like transatlantic operations. |
| Ambient Branding Technology Integration | Captures boarding and deplaning attention through programmable LED mood lighting and galley surface treatments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airline procurement directors, IFE system engineers, media agency account leads, and aviation hardware certification specialists with secondary validation. FAA certification databases, EASA CS-25 amendment drafts, airline fleet configuration filings, and customs records for aviation-grade display imports anchored the data foundation. Bottom-up fleet retrofit projections and top-down advertising spend allocation models triangulated market sizing.
Segment-weighting approaches distributed value across platform types, ad formats, and target audience categories, with seatback screen and Wi-Fi portal shares calibrated against actual airline fleet configurations. CAGRs derived from hardware deployment timelines, programmatic technology adoption curves, and route network expansion patterns across the analysis window. Forecast inputs incorporated DO-160G certification queue lengths, satellite connectivity bandwidth pricing trends, and alliance network joint venture coordination intensity.
The model holds under stable regulatory certification timelines and continued airline fleet expansion; deviation in EASA cybersecurity mandate acceleration or FAA transmission protocol relaxation would shift hardware procurement priorities materially. Deviation in low-cost carrier streaming-to-device adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Middle East and Africa Programmatic Advertising Market
Advertising and Marketing Media
United States Marketing Agencies Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Europe Digital OOH Advertising Market