
 Big Data Pharmaceutical Advertising Market | 2026-2036
Big Data Pharmaceutical Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Pharmaceutical Advertising Market Analysis
Performance-based media buying and subscription SaaS licensing are reshaping capital deployment across pharmaceutical advertising, lowering entry barriers for mid-size agencies. Klick Health leverages proprietary analytics stacks to sustain margin-rich engagements with top-ten drug makers. Publicis Health anchors its competitive position through deep CRM integrations that span prescriber databases and patient journey mapping. Omnicom Health Group competes via centralized data lakes that unify clinical, claims, and digital behavioral signals for campaign optimization.
Big Data Pharmaceutical Advertising denotes the application of large-scale data processing, statistical modeling, and automated segmentation to plan, execute, and measure promotional activities for prescription and over-the-counter therapies, typically integrating real-world evidence streams with digital channel telemetry to improve targeting precision and return on marketing spend. Digital Marketing leads current revenue contribution as regulatory comfort with programmatic healthcare advertising matures, while Machine Learning represents the fastest-expanding technology layer as predictive models for physician prescribing behavior achieve measurable lift over conventional segmentation. Data Visualization commands disproportionate margin pools by converting complex epidemiological and claims data into client-facing strategic narratives that justify premium agency fees.
FDA oversight of promotional claims and off-label communication constrains message architecture and demands rigorous substantiation workflows, while HIPAA governs the de-identification thresholds that determine whether patient-level data may enter targeting algorithms. The EU AI Act and GDPR jointly restrict automated profiling for healthcare decisions in European jurisdictions, fragmenting technology deployment across regulatory zones. Stakeholders must monitor whether emerging FDA guidance on artificial intelligence in drug marketing will mandate pre-clearance for algorithm-generated creative or audience selection.
Market Dynamics
Real-world evidence integration with programmatic ad platforms is compressing campaign optimization cycles and forcing agencies to rebuild workflows around HIPAA-compliant data lakes rather than conventional media planning.
Growth Catalysts
- FDA Guidance on AI-Generated Promotional Content:Draft frameworks for algorithmic creative review are legitimating automated personalization in physician outreach, expanding addressable spend pools for data-rich agencies.
- Real-World Evidence Mandates:Post-market safety surveillance requirements under the 21st Century Cures Act are pulling pharmaceutical marketers toward integrated data ecosystems that combine claims, EHR, and digital behavioral signals.
- Programmatic Healthcare Advertising:Privacy-preserving targeting protocols are maturing, enabling impression-level optimization against prescriber propensity scores without individual-level data exposure.
Market Restraints
- De-identification Engineering Costs:HIPAA Safe Harbor and Expert Determination pathways require specialized statistical labor and legal review, inflating fixed costs for audience segmentation projects.
- Platform Concentration Risk:Healthcare-specific demand-side platforms number fewer than five viable vendors, creating single-point-of-failure exposure for campaign execution infrastructure.
- Off-Label Promotion Liability:FDA enforcement actions against algorithmically amplified messaging create existential legal exposure when machine learning models extrapolate beyond approved indications.
Strategic Opportunities
- Patient Journey Orchestration:Unification of diagnosed-but-untreated patient identification with adherence-triggered messaging represents greenfield service expansion for data-integrated agencies.
- EU Regulatory Arbitrage:Switzerland and the United Kingdom maintain less restrictive health data processing frameworks than EU AI Act jurisdictions, enabling test-bed deployments for predictive targeting models.
- Voice-Activated Search Optimization:Smart speaker prescription queries are growing 40% annually, creating first-mover advantage for agencies building natural language processing capabilities around drug information.
Industry Challenges
- Cross-Functional Talent Scarcity:Professionals combining pharmaceutical regulatory knowledge, statistical modeling, and programmatic media execution command premium compensation and exhibit high turnover.
- Legacy CRM Integration Friction:Decades-old prescriber databases at major manufacturers resist API connectivity with modern data lakes, forcing expensive middleware development.
- Consent Architecture Complexity:State-level health privacy laws in California, Connecticut, and Washington impose divergent opt-in requirements that fragment national campaign deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Pharmaceutical Advertising Market |
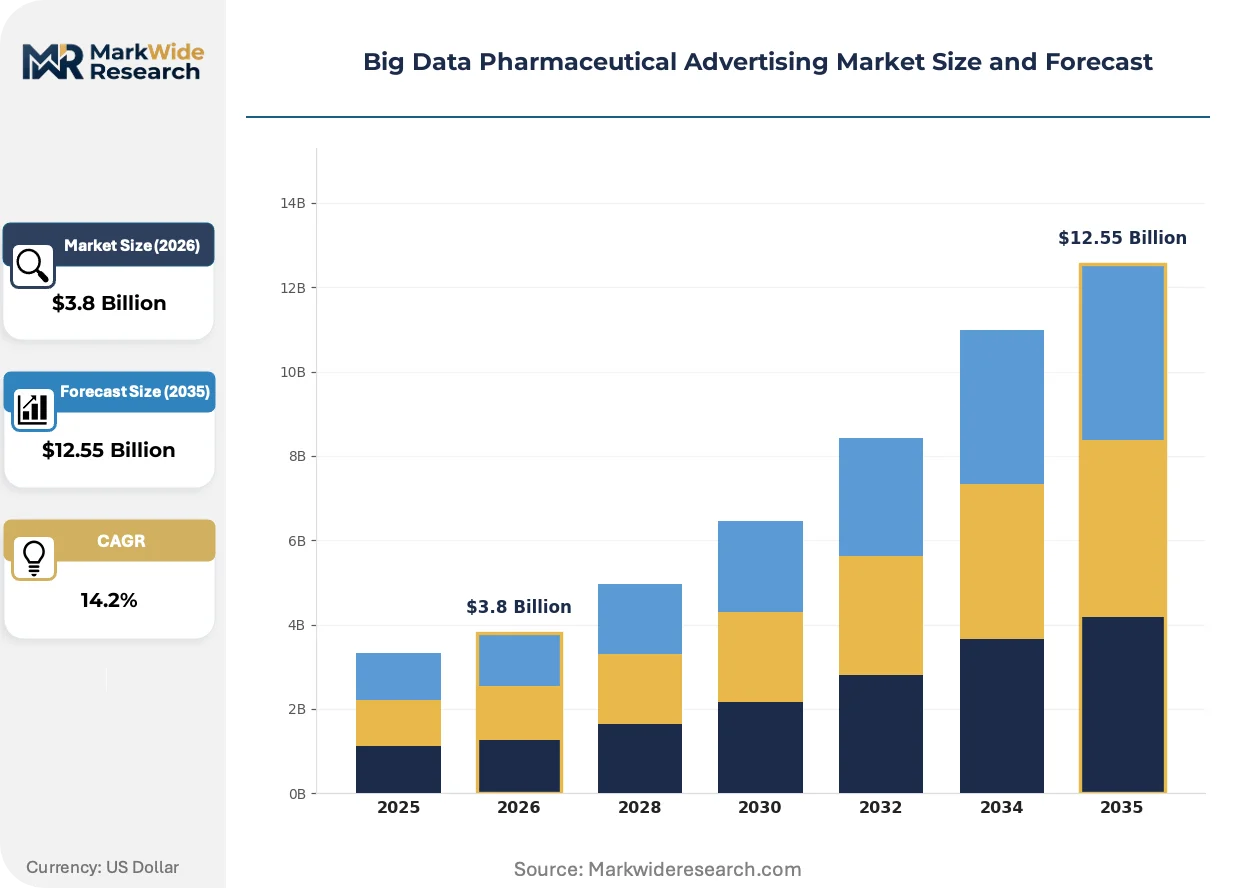
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Advertising Type: Digital Marketing, Social Media, Email Campaigns, Mobile Advertising Data Source: Clinical Trials, Prescription Records, Patient Surveys, Market Research End User: Pharmaceutical Companies, Advertising Agencies, Healthcare Providers, Researchers Technology: Analytics Tools, Data Visualization, Machine Learning, CRM Software |
| Companies Covered | Klick Health, Ogilvy Health, Real Chemistry, Supreme Optimization, Publicis Health, IPG Health, Inizio Evoke, Clarity Quest, Omnicom Health Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Pharmaceutical Advertising Market Emerging Trajectories
Federated learning architectures and privacy-enhancing computation are redrawing competitive boundaries between agencies that control data infrastructure and those that merely access it.
Machine learning for physician prescribing prediction is hybridizing clinical trial outcomes with longitudinal claims data to generate indication-specific propensity scores. Mid-size pharmaceutical manufacturers lacking in-house analytics capabilities are licensing these models through SaaS platforms rather than building captive data science teams. The technology is hybridizing what were historically separate budget lines for market research and media buying into unified optimization engines.
The EU AI Act's risk classification system for health-related algorithmic decision-making is forcing European deployments to maintain human-in-the-loop review for audience selection above defined scale thresholds. Pharmaceutical advertisers operating across Atlantic markets are bifurcating technology stacks to accommodate stricter continental requirements. Germany and France are experiencing the most acute compliance engineering demand as national regulators issue supplementary guidance on automated profiling in therapeutic areas.
Subscription-based agency compensation is displacing traditional commission structures tied to media spend. Procurement functions at top-ten drug manufacturers are unbundling strategy, creative, and analytics into separate vendor relationships with outcome-linked fee components. The United States exhibits the most advanced procurement transformation, with several manufacturers piloting shared-risk arrangements where agency fees partially depend on formulary placement metrics rather than impression delivery.
Big Data Pharmaceutical Advertising Market Segmentation
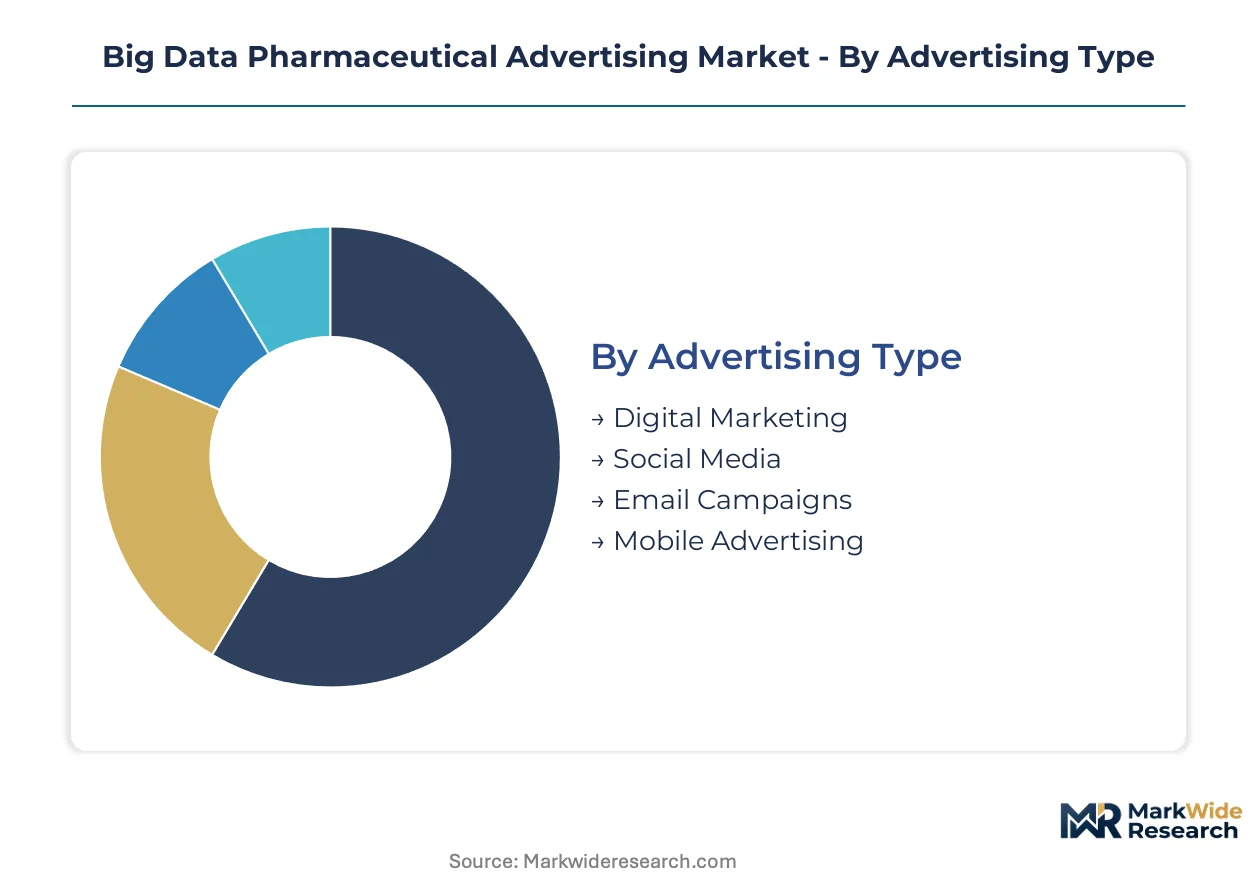
Segmentation in pharmaceutical advertising determines how data infrastructure investments align with regulatory constraints and channel-specific measurement requirements. Distinct technology stacks and compliance protocols apply to each dimension, forcing vendors to specialize rather than generalize.
Advertising Type:
Service intensity varies sharply across channels, with programmatic platforms demanding continuous algorithmic tuning and creative adaptation cycles.
- Digital Marketing:Programmatic display and search advertising dominate current spend allocation, with HIPAA-compliant audience segmentation requiring specialized demand-side platforms. United States deployments lead in impression-level optimization against prescriber propensity scores, though FDA promotional claim review creates workflow friction.
- Social Media:Platform-specific content moderation policies intersect with FDA off-label promotion restrictions, forcing pharmaceutical marketers to maintain human-in-the-loop approval chains for all sponsored content. LinkedIn and Twitter/X concentrate professional physician outreach, while patient-facing campaigns face stricter platform restrictions.
- Email Campaigns:Direct-to-physician deployment relies on verified prescriber databases with state-level consent architecture compliance.
- Mobile Advertising:In-app and SMS channels require explicit opt-in frameworks under evolving state privacy laws.
Digital Marketing holds the largest share; momentum sits with Social Media as platform targeting precision improves.
Data Source:
Cost tiers stratify sharply based on de-identification engineering requirements and longitudinal data completeness.
- Clinical Trials:Randomized controlled trial outcomes provide the highest-evidence-grade messaging substantiation for FDA promotional review. Integration with real-world evidence streams is expanding utility beyond traditional regulatory submissions into campaign creative development.
- Prescription Records:Claims and pharmacy dispensing data enable physician-level prescribing pattern analysis with HIPAA Safe Harbor compliance pathways. United States market concentration reflects the country's permissive data aggregation environment relative to GDPR jurisdictions.
- Patient Surveys:Primary research captures treatment satisfaction and unmet need signals for messaging refinement.
- Market Research:Syndicated epidemiology and competitive intelligence services support strategic planning workflows.
Prescription Records command the deepest integration with media buying workflows; Patient Surveys are climbing fastest as experience data gains regulatory recognition.
End User:
Customer type determines procurement sophistication and outcome-linked contracting appetite.
- Pharmaceutical Companies:Top-ten drug manufacturers unbundle strategy, creative, and analytics into separate vendor relationships with shared-risk fee structures. Procurement functions pilot formulary-placement-linked compensation models that displace traditional commission arrangements.
- Advertising Agencies:Mid-size agencies license predictive analytics through SaaS platforms to compete with vertically integrated holding company capabilities. Subscription-based compensation models lower capital barriers for technology access.
- Healthcare Providers:Hospital systems and physician networks deploy targeted recruitment for clinical trial enrollment.
- Researchers:Academic and contract research organizations utilize advertising data for epidemiological and health services investigations.
Pharmaceutical Companies anchor revenue concentration; Advertising Agencies are expanding most quickly as SaaS analytics democratize capabilities.
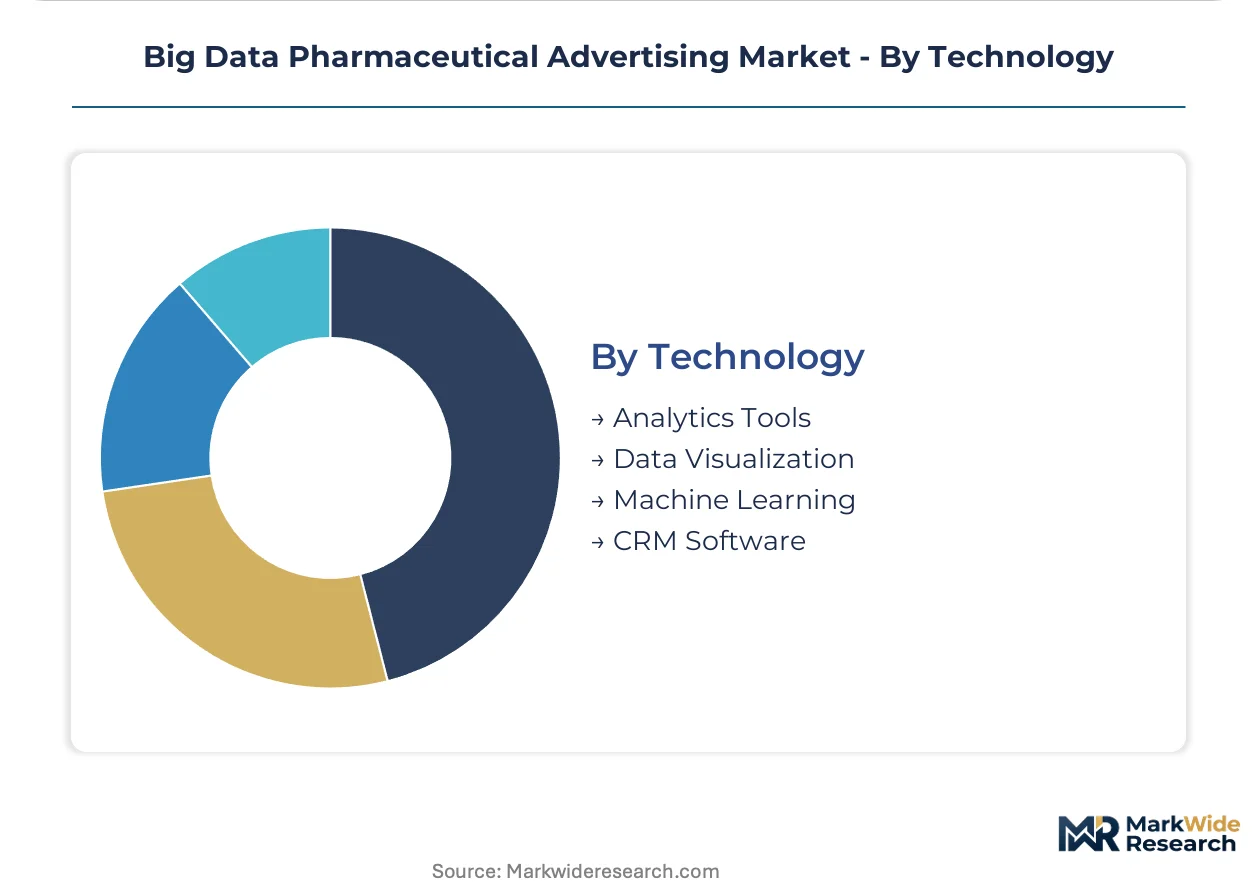
Technology:
Maturity curves diverge between established infrastructure and emerging predictive layers.
- Analytics Tools:Cross-channel measurement platforms unify digital telemetry with offline prescribing data to demonstrate return on marketing spend. United States deployments lead in identity resolution and attribution modeling sophistication.
- Data Visualization:Client-facing dashboards convert complex epidemiological and claims data into strategic narratives that justify premium agency fees. Margin concentration reflects the scarcity of professionals combining pharmaceutical domain knowledge with design capabilities.
- Machine Learning:Predictive models for physician prescribing behavior achieve measurable lift over conventional segmentation approaches.
- CRM Software:Legacy prescriber databases resist API connectivity with modern data lakes, forcing expensive middleware development.
Analytics Tools maintain the broadest deployment base; Machine Learning exhibits the steepest expansion trajectory as predictive capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on AI-generated promotional content and permissive direct-to-consumer advertising rules position the United States as the most advanced deployment environment for data-driven pharmaceutical marketing.
United States
Integrated data ecosystems and programmatic healthcare advertising maturity drive demand concentration. HIPAA Safe Harbor and Expert Determination pathways govern de-identification thresholds for patient-level targeting algorithms. The Boston-Cambridge corridor anchors prescriber database and real-world evidence integration services for top-ten drug manufacturers.
Germany
Stringent EU AI Act compliance requirements and national supplementary guidance on automated profiling create acute demand for human-in-the-loop review systems. The country's pharmaceutical regulator enforces risk classification thresholds for health-related algorithmic decision-making. The Rhine-Ruhr and Munich clusters concentrate agencies serving European pharmaceutical headquarters with bifurcated technology stacks.
Switzerland
Less restrictive health data processing frameworks relative to EU AI Act jurisdictions enable test-bed deployments for predictive targeting models. Swissmedic oversight maintains proportionate promotional claim review without pre-clearance mandates for algorithmic creative. The Basel-Zurich corridor hosts mid-size pharmaceutical manufacturers licensing SaaS analytics platforms for physician outreach optimization.
United Kingdom
Post-Brexit regulatory divergence permits flexible health data processing for advertising analytics outside EU AI Act constraints. The Medicines and Healthcare products Regulatory Agency maintains evolving guidance on real-world evidence integration with digital promotion. London concentrates subscription-based agency compensation pilots and shared-risk fee structures tied to formulary placement metrics.
Japan
PMDA oversight of digital health promotion and real-world evidence utilization accelerates compliance investments for multinational pharmaceutical advertisers. METI industrial policy supports privacy-preserving targeting protocol development for programmatic healthcare advertising. The Tokyo-Osaka corridor anchors demand for cross-functional talent combining pharmaceutical regulatory knowledge with statistical modeling capabilities.
Big Data Pharmaceutical Advertising Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated holding companies and SaaS-enabled mid-size specialists competing through predictive analytics licensing. Three strategic archetypes dominate: data infrastructure controllers maintaining proprietary analytics stacks, CRM integrators spanning prescriber databases and patient journey mapping, and centralized data lake operators unifying clinical and digital behavioral signals. Competitive moves concentrate on strategic partnerships with healthcare-specific demand-side platforms and subscription-based compensation model expansion.
Within the integrated holding company tier, Publicis Health and Omnicom Health Group exemplify archetypes competing through deep CRM integrations and centralized data lake architectures respectively. Klick Health occupies a position representing the data infrastructure controller archetype with proprietary analytics capabilities. These three entities anchor the competitive structure through differentiated technology deployment strategies rather than scale alone.
| Leading Market Players |
|---|
| Klick Health |
| Ogilvy Health |
| Real Chemistry |
| Supreme Optimization |
| Publicis Health |
| IPG Health |
| Inizio Evoke |
| Clarity Quest |
| Omnicom Health Group |
| Others |
Supply Flow & Price Mechanics
Healthcare-specific demand-side platform concentration in the United States concentrates upstream data infrastructure control, directing margin capture toward agencies maintaining proprietary analytics stacks and HIPAA-compliant data lake architectures rather than execution-only service providers.
Pricing Analysis
Certification level (FDA-grade compliance and HIPAA Safe Harbor validation) creates the primary spread between premium and standard service tiers. Subscription SaaS licensing dominates pricing models, with differentiation driven by de-identification engineering sophistication and prescriber database integration depth. Cost compression in mid-tier analytics services is intensifying because SaaS democratization lowers technology access barriers. Mid-size pharmaceutical manufacturers exhibit highest price sensitivity, while top-ten drug makers prioritize outcome-linked fee structures over unit pricing.
Supply Chain Analysis
Raw data feeds from United States claims aggregators, European EHR systems, and Japanese prescribing databases anchor upstream supply. The supply chain draws from de-identified prescription records, real-world evidence streams, and digital behavioral telemetry as core inputs. Single-source vulnerability concentrates in healthcare-specific demand-side platforms, where fewer than five viable vendors create execution infrastructure risk. Distribution runs through centralized data lakes unifying clinical, claims, and digital signals for campaign optimization workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around HIPAA compliance and FDA promotional review creates durable defensive moats for established players, as switching costs for pharmaceutical manufacturers escalate with each integrated data ecosystem deployment.
For Market Incumbents: Build switching-cost moats through deeper prescriber database API integration that locks in pharmaceutical manufacturer workflows. Deepen vertical integration into privacy-preserving computation infrastructure to defend against SaaS-enabled challengers. Expand human-in-the-loop review capabilities ahead of EU AI Act threshold expansions to preempt compliance-driven displacement. For New Entrants and Emerging Players: Switzerland and the United Kingdom offer underpenetrated test-bed environments for predictive targeting models outside EU AI Act constraints. Voice-activated search optimization for smart speaker prescription queries represents the most penetrable white-space segment with 40% annual query growth. License federated learning architectures through outcome-linked fee arrangements to bypass capital-intensive data lake construction. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-size specialists combining proprietary analytics with healthcare-specific regulatory expertise. Long-term viability hinges on agencies controlling data infrastructure rather than accessing it through third-party licenses. Watch FDA guidance finalization on AI-generated promotional content as the inflection signal for algorithmic creative pre-clearance mandates.| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA-Compliant Data Lake Construction | Builds proprietary infrastructure moats that pharmaceutical manufacturers cannot easily replicate internally. |
| Federated Learning Architecture Deployment | Enables privacy-preserving model training across fragmented European regulatory zones without data centralization. |
| Human-in-the-Loop Review System Investment | Satisfies EU AI Act risk classification thresholds for health-related algorithmic decision-making at scale. |
| Voice-Activated Search Optimization Capability | Captures first-mover advantage in smart speaker prescription queries growing 40% annually. |
| Outcome-Linked Compensation Model Pilot | Aligns agency fees with formulary placement metrics rather than impression delivery, transforming procurement relationships. |
Methodological Framework
A standing panel of pharmaceutical marketing executives, regulatory affairs specialists, formulary access directors, and healthcare data scientists provided ongoing calibration throughout the study. Primary interviews with demand-side platform operators and agency analytics leads combined with secondary validation against FDA guidance documents, EMA promotional code filings, ClinicalTrials.gov records, and healthcare privacy statute databases. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing around regulatory guidance timelines and AI adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include advertising type, data source provenance, end-user procurement sophistication, and technology maturity tier. CAGRs derived from historical spend pattern analysis and technology diffusion curve fitting, with real-world evidence integration mandates and programmatic healthcare advertising maturity serving as primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical R&D budgets, healthcare privacy litigation trends, or FDA enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about regulatory guidance finalization schedules and technology adoption elasticity. Cross-checking against agency compensation structure disclosures and healthcare advertising spend audits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Europe Programmatic Advertising Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Multiscreen Advertising Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
United States OOH and DOOH Market
Advertising and Marketing Media
Austria OOH and DOOH Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Adtech Market