
 Sun Protection Spray Market | 2026-2036
Sun Protection Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Sun Protection Spray Market Analytics
The gap between premium dermatological-grade formulations and mass-market commodity sprays is repositioning how brands allocate R&D budgets and shelf space. Neutrogena leverages its clinical heritage to command pharmacy channel placement, while La Roche-Posay anchors its positioning around thermal spring water bases and minimal allergen profiles. Coppertone competes through heritage brand recognition and broad retail distribution, though its portfolio spans both tiers without full commitment to either.
Sun protection spray denotes a topical photoprotective product delivered through pressurized or pump-actuated aerosolized dispersion, typically formulated with organic UV filters such as avobenzone and octocrylene or mineral oxides in micronized suspension, designed for uniform skin coverage without manual rubbing. The SPF Rating dimension stratifies margin pools, with SPF 50 and SPF 60 segments capturing premium positioning as consumers equate higher numerical ratings with superior protection, while SPF 15 maintains volume relevance in daily-use and cosmetic-combination products. The Usage Type dimension reveals structural divergence: water-resistant and sports variants command formulation complexity and regulatory testing investment, whereas daily-use sprays compete on texture, scent, and cosmetic elegance rather than performance claims alone.
FDA sunscreen monograph compliance, EU Cosmetics Regulation (EC) No 1223/2009 ingredient restrictions, and Hawaii's oxybenzone/octinoxate reef-safe bans collectively reshape permissible actives and labeling requirements across major markets. These frameworks elevate compliance costs for multi-market portfolios while creating openings for mineral-only and reef-safe formulations. Stakeholders must monitor pending FDA final rulemakings on GRASE determinations and emerging state-level environmental restrictions to anticipate reformulation cycles and geographic market access conditions.
Market Dynamics
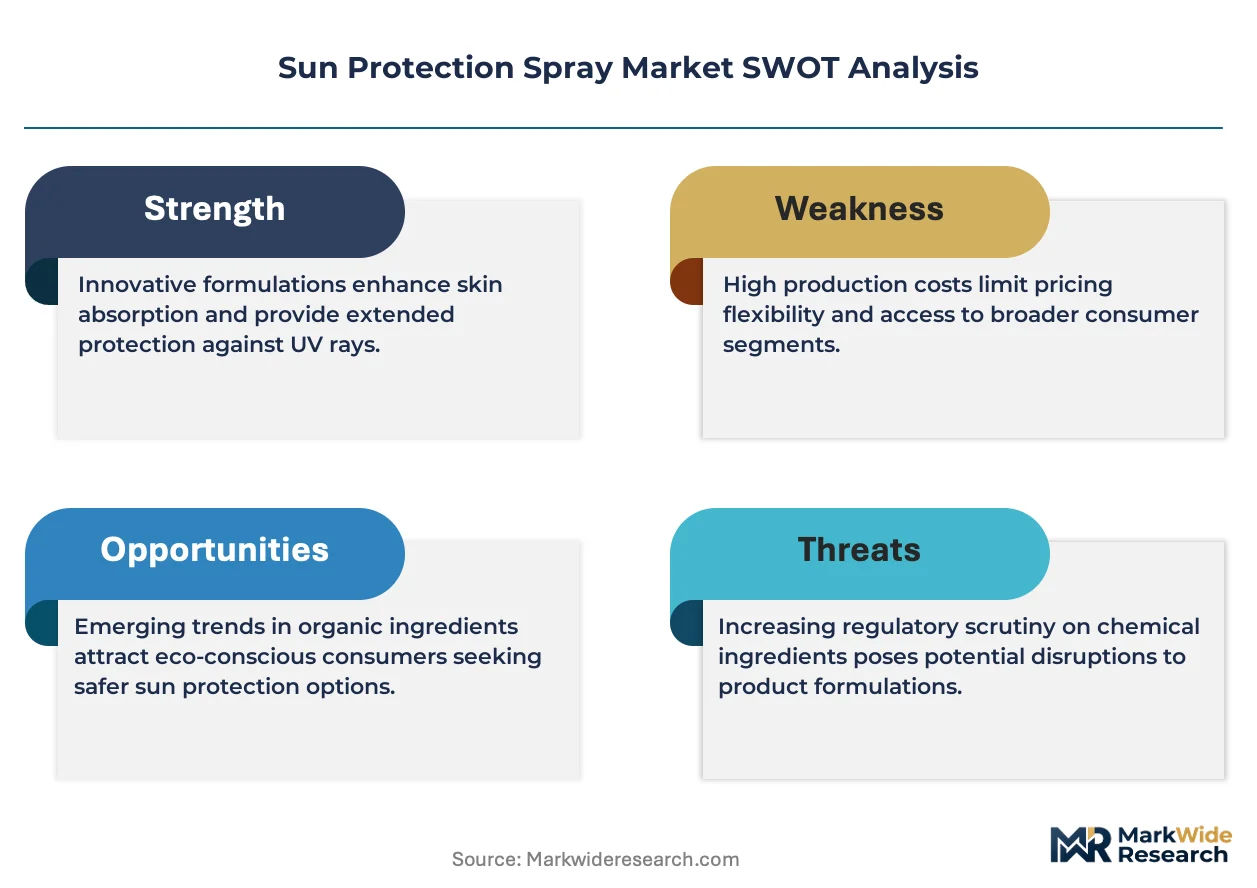
FDA's pending GRASE determinations for organic UV filters are compressing formulation timelines while Hawaii's reef-safe bans force mineral oxide substitution, creating simultaneous pressure on R&D budgets and active ingredient sourcing strategies.
Growth Catalysts
- Outdoor Sports Expansion:Marathon running, triathlon, and beach volleyball participation rates in Australia and the United States are elevating reapplication frequency and format preference for spray dispensers over lotions.
- REACH Annex VI Updates:The European Chemicals Agency's tightening restrictions on certain organic filters are accelerating mineral-only formulation development, opening premium positioning for zinc oxide and titanium dioxide specialists.
- Dermatologist Channel Penetration:Clinical recommendation networks in Germany and South Korea are converting prescription-adjacent sun protection into over-the-counter spray adoption among rosacea and post-procedure patient populations.
Market Restraints
- Propellant Cost Volatility:Hydrocarbon and dimethyl ether propellant prices track crude oil indices, compressing margin stability for aerosol-format manufacturers dependent on petrochemical feedstocks.
- Active Ingredient Concentration Risk:Chinese suppliers dominate micronized zinc oxide production, creating geographic single-point-of-failure exposure for brands pursuing mineral-only portfolios.
- Inhalation Toxicology Data Gaps:The FDA's incomplete guidance on spray particle size thresholds and lung deposition risks delays new product clearances and restricts marketing claims.
Strategic Opportunities
- Brazilian Pharmacy Channel:ANVISA's streamlined cosmetic registration pathways and rising melanoma awareness in São Paulo and Rio de Janeiro create first-mover positioning for SPF 50+ spray launches.
- Scalp and Hair Formulations:Baldness aesthetics and hair-part sunburn concerns among male outdoor workers are driving untapped demand for non-greasy, non-staining spray variants.
- Connected Dispensers:Integration of UV index sensors with Bluetooth-enabled spray bottles is rewriting adherence tracking for pediatric and immunocompromised user segments.
Industry Challenges
- Photostability Testing Capacity:ISO 24443 UVA-PF validation requires specialized solar simulators and trained technicians, creating bottlenecks for brands accelerating reformulation cycles.
- Cross-Border Label Harmonization:Divergent SPF testing protocols between FDA, COLIPA, and JIS standards force portfolio fragmentation and inventory complexity for multi-market brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sun Protection Spray Market |
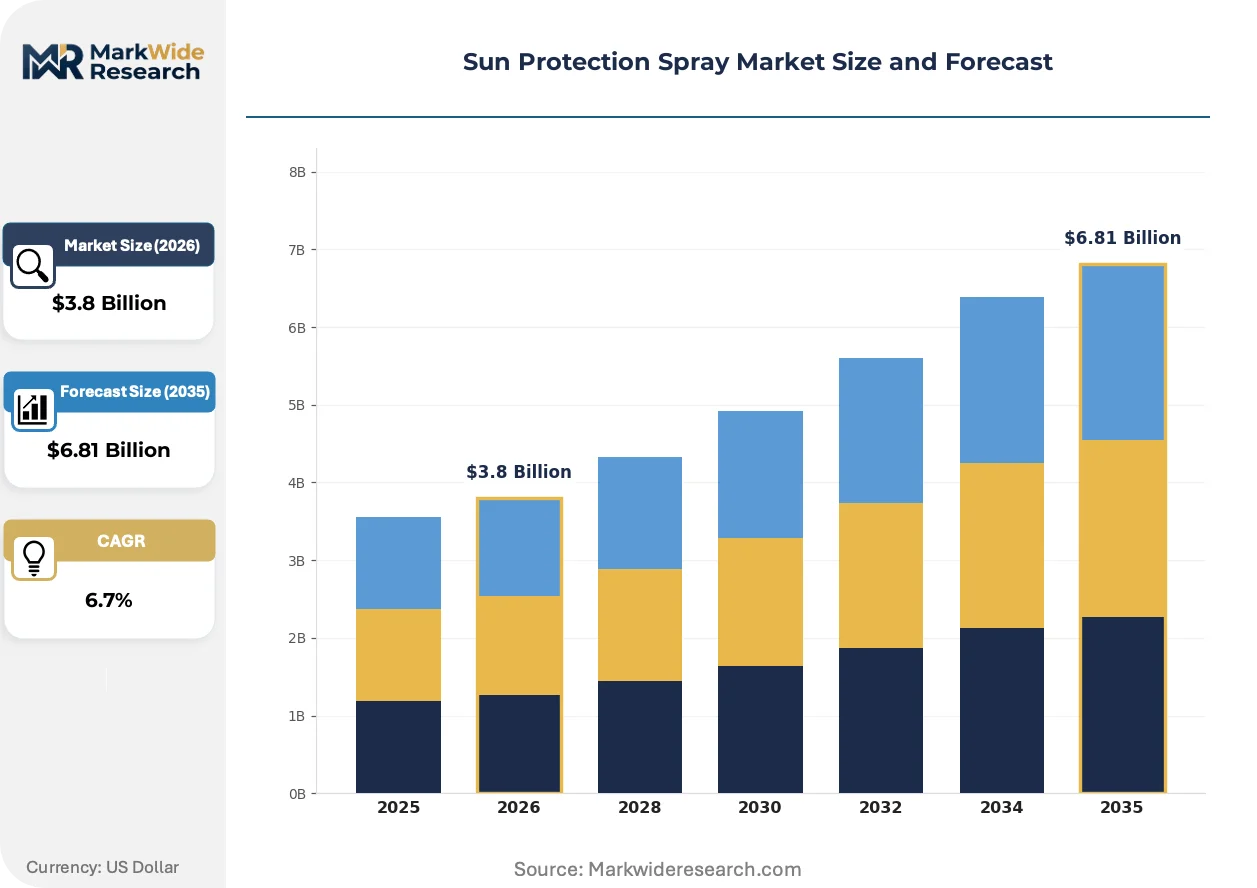
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Gels, Oils, Sprays SPF Rating: 15, 30, 50, 60 Usage Type: Daily Use, Sports, Water-Resistant, Kids Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Neutrogena, Coppertone, Banana Boat, La Roche-Posay, Avene, Sun Bum, Coola, EltaMD, L'Oréal Paris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sun Protection Spray Market Evolving Landscape
Reformulation chemistry, regulatory science, and application behavior are converging to redefine product architecture and go-to-market assumptions for spray-format photoprotection.
Encapsulated organic UV filters using silica shell technology are rewriting photostability performance benchmarks. Premium skincare brands in Japan and France are adopting these systems for SPF 60+ claims without the white cast of mineral alternatives. The technology is compressing the historical trade-off between cosmetic elegance and broad-spectrum efficacy.
REACH authorization requirements for nanomaterial titanium dioxide are forcing disclosure and risk assessment investments across EU supply chains. Manufacturers must now submit full safety dossiers to ECHA for particle sizes below 100 nanometers, elevating compliance costs but also creating defensible positioning for verified non-nano mineral brands. German and French regulators are enforcing these provisions most stringently, pushing reformulation toward larger particle suspensions.
Subscription replenishment models through dermatology clinic portals are displacing retail impulse purchases for daily-use spray segments. Patients with photosensitivity conditions in the United States and Australia are opting into automated 90-day delivery cycles tied to prescription management platforms. This channel shift concentrates lifetime value capture with clinical gatekeepers rather than mass-market retailers.
Sun Protection Spray Market Segmentation
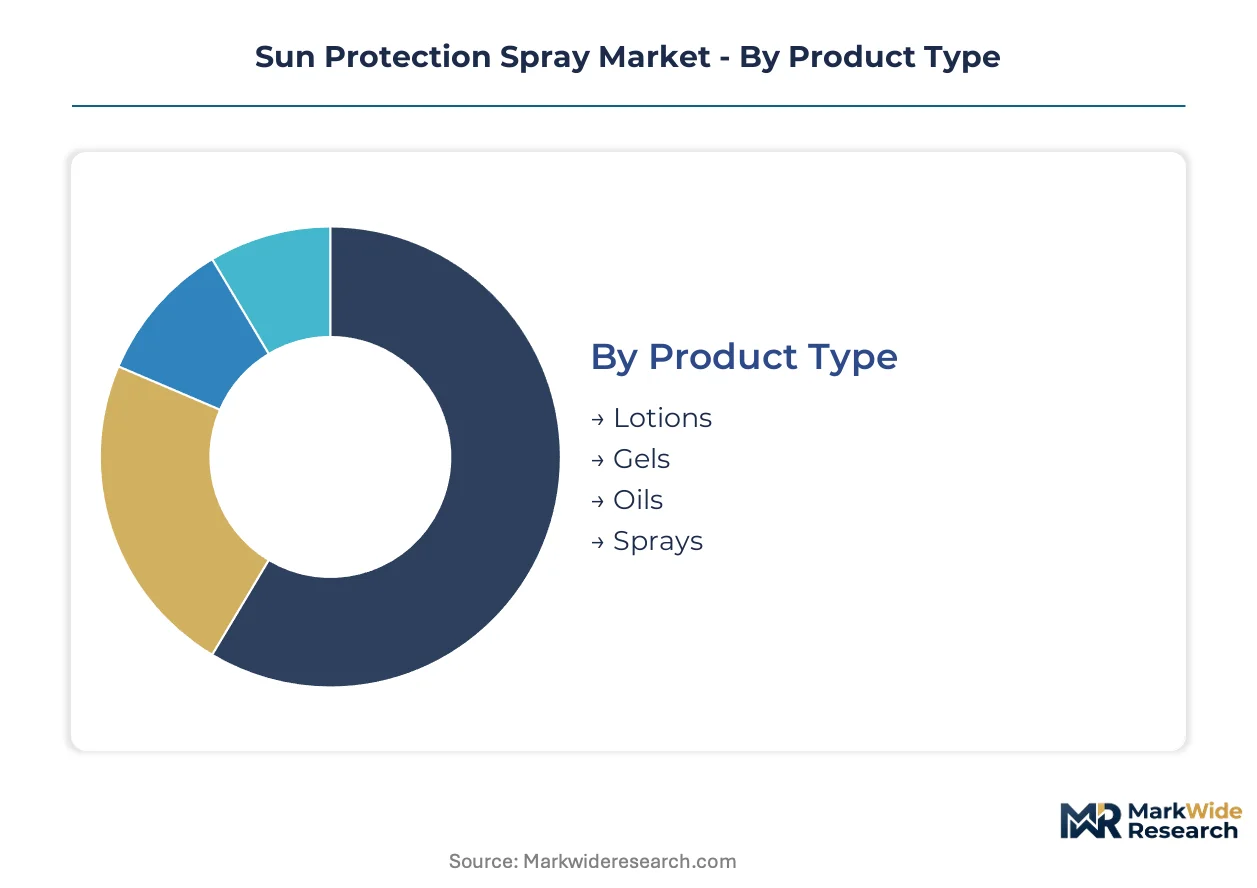
Sun protection spray formulations diverge sharply across performance tiers and purchase occasions. Upgrade cycles from lotions to sprays, and from lower to higher SPF ratings, now define how manufacturers allocate formulation R&D and channel marketing budgets.
Product Type:
Replacement dynamics favor spray formats where convenience overrides cost sensitivity in reapplication scenarios.
- Sprays:Pressurized or pump-actuated aerosolized delivery systems deposit micronized mineral oxides or organic UV filters without manual rubbing. Marathon runners in Australia and beach volleyball athletes in the United States are elevating reapplication frequency and driving pharmacy and specialty retail placement for sport-specific spray variants.
- Lotions:Traditional emulsion-based photoprotection remains the volume baseline for daily facial and full-body application, particularly among dermatology-recommended regimens in Germany where cosmetic elegance and rub-in control outweigh speed of application.
- Gels:Alcohol-based or aqueous gel matrices offer rapid drying and non-staining properties for hair-bearing areas and scalp protection among male outdoor workers.
- Oils:Silicone and ester-based oil formulations deliver water-resistant film formation for extended aquatic exposure, though regulatory scrutiny on inhalation risks constrains spray-format oil expansion.
Volume placements concentrate in Lotions; the faster expansion belongs to Sprays.
SPF Rating:
Margin stratification follows the numerical hierarchy as consumers equate higher ratings with superior photoprotection.
- SPF 50:The clinical standard for extended outdoor exposure, SPF 50 formulations balance UVB filtration with formulation stability. Dermatologist networks in South Korea and the United States are converting prescription-adjacent recommendations into over-the-counter pharmacy purchases for rosacea and post-procedure patient populations.
- SPF 60:Encapsulated organic filter technologies enable SPF 60+ claims without mineral white cast, commanding premium positioning in Japanese and French prestige skincare channels where photostability and cosmetic elegance converge.
- SPF 30:The baseline for daily incidental exposure, SPF 30 maintains volume relevance in cosmetic-combination products and workplace compliance programs where cost-per-application drives procurement decisions.
- SPF 15:Minimal protection tier retains presence in daily-use moisturizers and tinted formulations, though regulatory pressure in the European Union and United States is compressing its market relevance.
Revenue concentration tilts toward SPF 50; steepest expansion trajectory attaches to SPF 60.
Usage Type:
Application occasion determines formulation complexity, testing investment, and permissible marketing claims.
- Sports:Sweat-resistant and friction-stable film formers withstand marathon running and triathlon conditions in Australia and the United States. ISO 24443 UVA-PF validation requirements elevate testing costs but create defensible positioning for performance-certified brands.
- Water-Resistant:Immersion testing under FDA and COLIPA protocols mandates 40-minute and 80-minute substantiation, restricting formulation flexibility to hydrophobic resin systems and mineral oxide suspensions that resist wash-off.
- Daily Use:Texture, scent, and cosmetic elegance dominate purchase criteria for commuter and office-worker segments, with subscription replenishment models through dermatology clinic portals displacing retail impulse purchases in the United States.
- Kids:Pediatric formulations face heightened scrutiny on inhalation toxicity and eye irritation, with mineral-only positioning gaining preference among parents in Germany and France where ECHA nanomaterial disclosure requirements elevate transparency expectations.
Formulation investment pools in Sports; subscription-driven retention is climbing fastest in Daily Use.
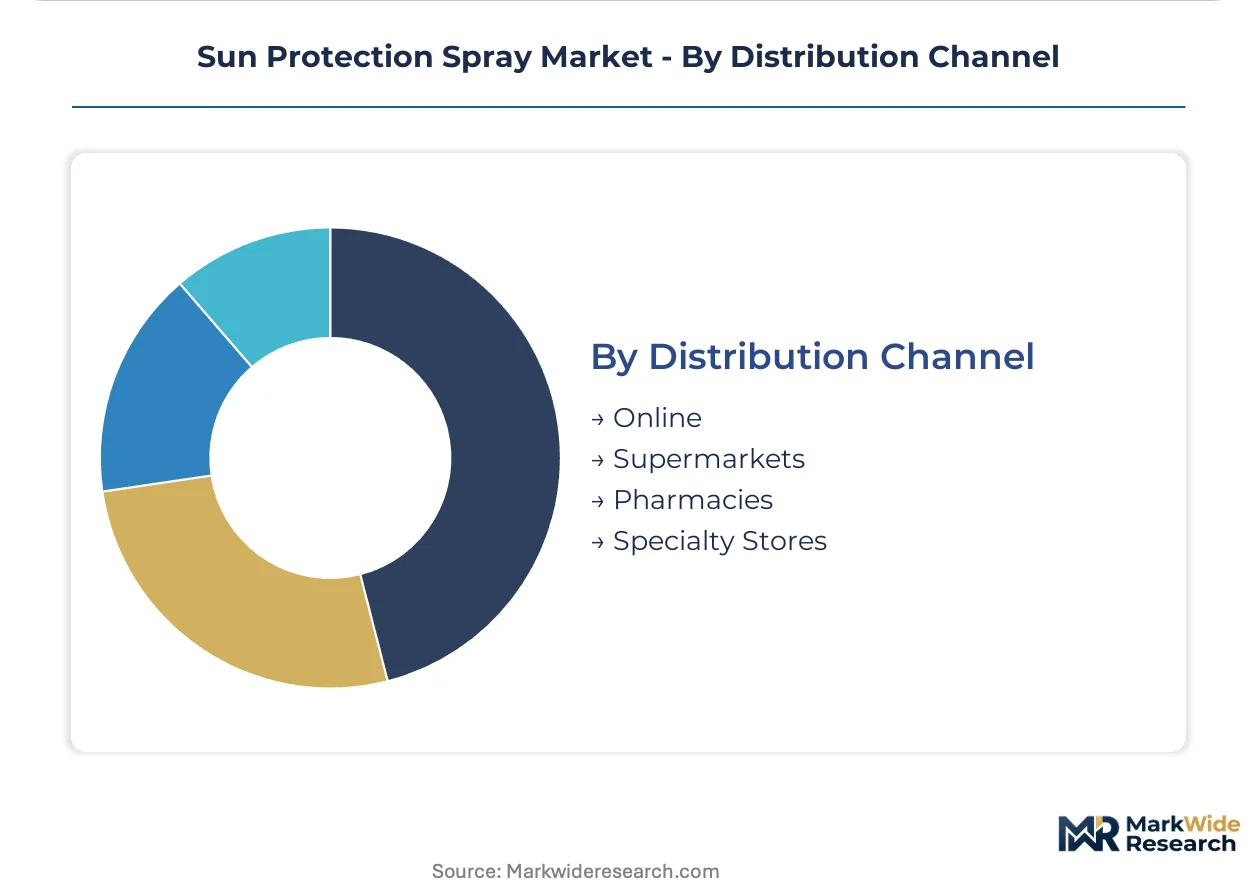
Distribution Channel:
Channel selection determines margin capture, customer data access, and compliance with pharmacy-specific labeling requirements.
- Pharmacies:Clinical recommendation networks and SPF education campaigns elevate pharmacy placement for dermatological-grade formulations in Germany, South Korea, and Brazil where ANVISA registration pathways reward first-mover SPF 50+ launches.
- Online:Direct-to-consumer platforms enable subscription replenishment and UV index-linked dispenser integration, concentrating lifetime value capture with clinical gatekeepers rather than mass-market retailers in the United States and Australia.
- Supermarkets:Mass-market volume placement depends on heritage brand recognition and promotional frequency, with Coppertone and similar heritage brands competing through broad retail distribution and price-promotion cycles.
- Specialty Stores:Prestige skincare boutiques and outdoor recreation retailers anchor premium mineral-only and reef-safe positioning, particularly in Hawaii and California where state-level oxybenzone bans force active ingredient substitution.
Transaction volume aggregates in Supermarkets; customer lifetime value expansion is gaining share fastest in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors North American sun protection spray innovation through its concentration of dermatology clinic networks and outdoor lifestyle marketing headquarters. The metropolitan area hosts formulation labs serving pharmacy and specialty retail channels nationwide.
United States
Marathon running participation and beach volleyball leagues in Florida and California elevate reapplication frequency for sport-specific sprays. FDA's pending GRASE determinations for organic UV filters compress reformulation timelines for domestic manufacturers. Miami-Dade County retailers stock reef-safe mineral formulations ahead of state-level environmental restrictions.
Germany
Rosacea patient populations and post-procedure skincare protocols drive pharmacy channel penetration for SPF 50+ sprays. ECHA nanomaterial disclosure requirements under REACH Annex VI force transparency investments for titanium dioxide suppliers. The Rhine-Ruhr industrial corridor concentrates contract manufacturing for mineral-only formulations serving EU markets.
Australia
Triathlon participation rates and outdoor worker safety mandates sustain elevated per-capita consumption of water-resistant variants. TGA alignment with ISO 24443 UVA-PF testing standards elevates validation costs for imported brands. Sydney and Melbourne dermatology networks convert clinical recommendations into subscription replenishment models for photosensitivity patients.
Brazil
ANVISA streamlined cosmetic registration pathways accelerate SPF 50+ product launches in São Paulo and Rio de Janeiro pharmacy chains. Rising melanoma awareness campaigns elevate consumer education and clinical channel placement. The Southeast industrial belt houses aerosol propellant suppliers serving regional spray manufacturers.
Japan
Prestige skincare consumers demand SPF 60+ claims without mineral white cast, driving encapsulated organic filter adoption. METI oversight of quasi-drug sunscreen classifications creates regulatory complexity for reformulation cycles. Osaka-based formulation houses specialize in silica-shell photostability technologies for export markets.
Sun Protection Spray Market Competitive Landscape
Premium-margin players sit above commodity-margin players across SPF rating tiers and distribution channel access. The market structures around three archetypes: dermatology-endorsed clinical brands, heritage mass-market labels with broad retail presence, and mineral-only specialists capitalizing on reef-safe regulatory tailwinds. Consolidation pressure concentrates among mid-tier players lacking distinct channel positioning or formulation differentiation. Dominant competitive moves include portfolio diversification into scalp-specific variants and geographic expansion through ANVISA-registered launches in Brazilian pharmacy channels.
Within the clinical-endorsed tier, Neutrogena and La Roche-Posay exemplify pharmacy-channel positioning built on dermatologist recommendation networks. Coppertone occupies a position bridging heritage mass-market recognition with sport-specific line extensions. These three anchors demonstrate how margin capture depends on whether brand equity converts into subscription replenishment models or remains trapped in promotional price cycles at supermarket retailers.
| Leading Market Players |
|---|
| Neutrogena |
| Coppertone |
| Banana Boat |
| La Roche-Posay |
| Avene |
| Sun Bum |
| Coola |
| EltaMD |
| L'Oréal Paris |
| Others |
Value Network & Pricing Analysis
Dimethyl ether propellant price indices, tracking crude oil benchmarks, cascade through aerosol-format manufacturing into three-tier pricing structure across premium, standard, and economy levels. Mineral oxide sourcing from Chinese micronized zinc oxide suppliers concentrates cost leverage upstream, while reef-safe formulation premiums in Hawaii and California markets widen spreads between mineral-only and organic-filter tiers.
Pricing Analysis
SPF performance ratings anchor value-based pricing, with SPF 60+ encapsulated organic filter formulations commanding dermatology-channel premiums against SPF 30 mass-market baselines. Price differentiation separates ISO 24443 UVA-PF certified sports variants from uncertified daily-use sprays, while brand heritage and pharmacy placement drive additional tier separation. Pricing pressure stems from REACH Annex VI nanomaterial compliance investments elevating European production costs. Mass-market supermarket buyers exhibit highest price sensitivity; pharmacy-channel rosacea and post-procedure patient populations demonstrate lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Los Angeles, São Paulo, and Sydney anchor hub-and-spoke patterns serving pharmacy and specialty retail channels. Manufacturing concentrates in China for micronized mineral oxides, the United States for aerosol propellant blending, and Germany for REACH-compliant formulation finishing. Raw material dependencies include hydrocarbon propellants, titanium dioxide from Australian and Chinese suppliers, and silica-shell encapsulation chemicals from Japanese specialty chemical houses. Single-source vulnerability in Chinese zinc oxide production creates geographic concentration risk. Distribution runs through pharmacy wholesalers in Germany and South Korea, direct-to-consumer platforms in the United States and Australia, and supermarket retail networks for mass-market volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA pending GRASE determinations for organic UV filters erect compliance barriers that favor incumbent mineral-only specialists with established testing infrastructure and pharmacy-channel relationships.
For Market Incumbents: To counter mineral oxide supply concentration in China, secure dual-source agreements with Australian and European titanium dioxide suppliers while expanding in-house photostability testing capacity under ISO 24443 protocols. Backward integration into encapsulated organic filter technology through Osaka-based formulation partnerships defends premium positioning against white-cast-free mineral alternatives. For New Entrants and Emerging Players: Launch via Brazilian pharmacy direct-distribution models leveraging ANVISA streamlined registration pathways for SPF 50+ mineral-only entrants in São Paulo and Rio de Janeiro. Target scalp-specific spray formulations for male outdoor worker segments in Australia and the United States, where baldness aesthetics and hair-part sunburn concerns remain underserved by incumbent portfolios. For Investors and Strategic Acquirers: Distressed-cycle entries favor mineral-only specialists with verified non-nano supply chains in Germany and France, where REACH Annex VI disclosure investments have already been absorbed. Long-term viability hinges on subscription replenishment platform integration with dermatology clinic portals. Monitor FDA final GRASE rulemaking as inflection signal for organic filter portfolio write-downs and mineral-only acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Reef-Safe Formulation Transition | Hawaii's oxybenzone ban forces mineral oxide substitution across California and Florida retail networks. |
| Encapsulated Filter Technology Licensing | Silica-shell photostability patents from Osaka laboratories enable SPF 60+ claims without mineral white cast. |
| Pharmacy Channel Expansion | ANVISA registration in São Paulo and Rio de Janeiro captures rising melanoma awareness-driven demand. |
| Subscription Platform Integration | Dermatology clinic portal tie-ins in the United States and Australia lock in photosensitivity patient lifetime value. |
| Scalp-Specific Variant Development | Non-greasy, non-staining sprays address baldness aesthetics among male outdoor workers in Australia. |
Research Methodology
Trade publications, customs import records, and ANVISA registration filings formed the secondary backbone, cross-referenced against primary interviews with aerosol formulation chemists, pharmacy category buyers in São Paulo and Seoul, dermatology clinic procurement managers, and mineral oxide supplier technical directors. Bottom-up unit economics modeling triangulated against top-down market sizing from regulatory filing volumes and retail audit data.
Bottom-up volume builds aggregated SPF rating tier shipments, usage type application frequencies, and channel-specific price points across the projection horizon. Segmentation dimensions modeled include product format, SPF performance tier, usage occasion, and distribution channel cluster. CAGRs derived from regression analysis of historical propellant cost trajectories, regulatory event impacts, and sport participation rate correlations. Forecast inputs incorporated FDA GRASE determination timelines and REACH Annex VI enforcement intensity variations.
The model assumes a particular technology adoption path; alternative pathways for encapsulated organic filter versus mineral-only mineral formulation would alter the outlook. Forecasts reflect base-case assumptions on regulatory implementation schedules, raw material supply continuity, and pharmacy channel conversion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
DIY Eyelash Extension Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
United Kingdom Cosmetics Products Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
Women Intimate Care Products Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Herbal Shampoo Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Hair and Nail Accessories Market