
 US Sustainable Personal Care Market | 2026-2036
US Sustainable Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
US Sustainable Personal Care Market Insights
Market Context
Plant-derived surfactants are expanding their cost-competitive position against petroleum-based alternatives across mass-market formulations. Procter & Gamble Company leverages captive agricultural partnerships to secure consistent feedstock volumes for its sustainable hair care lines. Unilever PLC anchors its North American portfolio with concentrated refill formats that reduce per-use plastic intensity. Estée Lauder Companies, Inc. differentiates through biotech-derived active ingredients sourced from fermentation platforms rather than traditional botanical extraction.
Technical Definition and Segments
US Sustainable Personal Care encompasses cosmetic and hygiene products formulated with renewable, minimally processed ingredients and packaged in closed-loop material systems, where biodegradability testing under OECD 301 standards and carbon footprint verification form core quality parameters. The segment serves consumers seeking reduced ecological impact without compromising dermatological safety or sensorial performance. Biodegradable ingredient sourcing commands the fastest volume expansion as formulators replace ethoxylated compounds with sugar-based alternatives. Refillable packaging formats capture disproportionate margin pools due to repeat purchase mechanics and brand loyalty lock-in. Eco-conscious consumers drive premium price realization, while professional salon channels sustain higher per-unit spending on organic-certified conditioners.
Regulatory Frame and Outlook
EPA Safer Choice certification and California's Toxic-Free Cosmetics Act jointly reshape permissible preservative chemistries and disclosure depth across interstate commerce. FDA oversight of cosmetic safety claims intersects with FTC Green Guides enforcement on environmental marketing, creating dual compliance exposure for national brands. The USDA BioPreferred program confers federal procurement preference on biobased personal care items, opening institutional channels. Stakeholders must monitor state-level ingredient bans spreading beyond California to determine whether centralized formulation strategies or regional SKU proliferation delivers lower compliance cost.
Market Dynamics
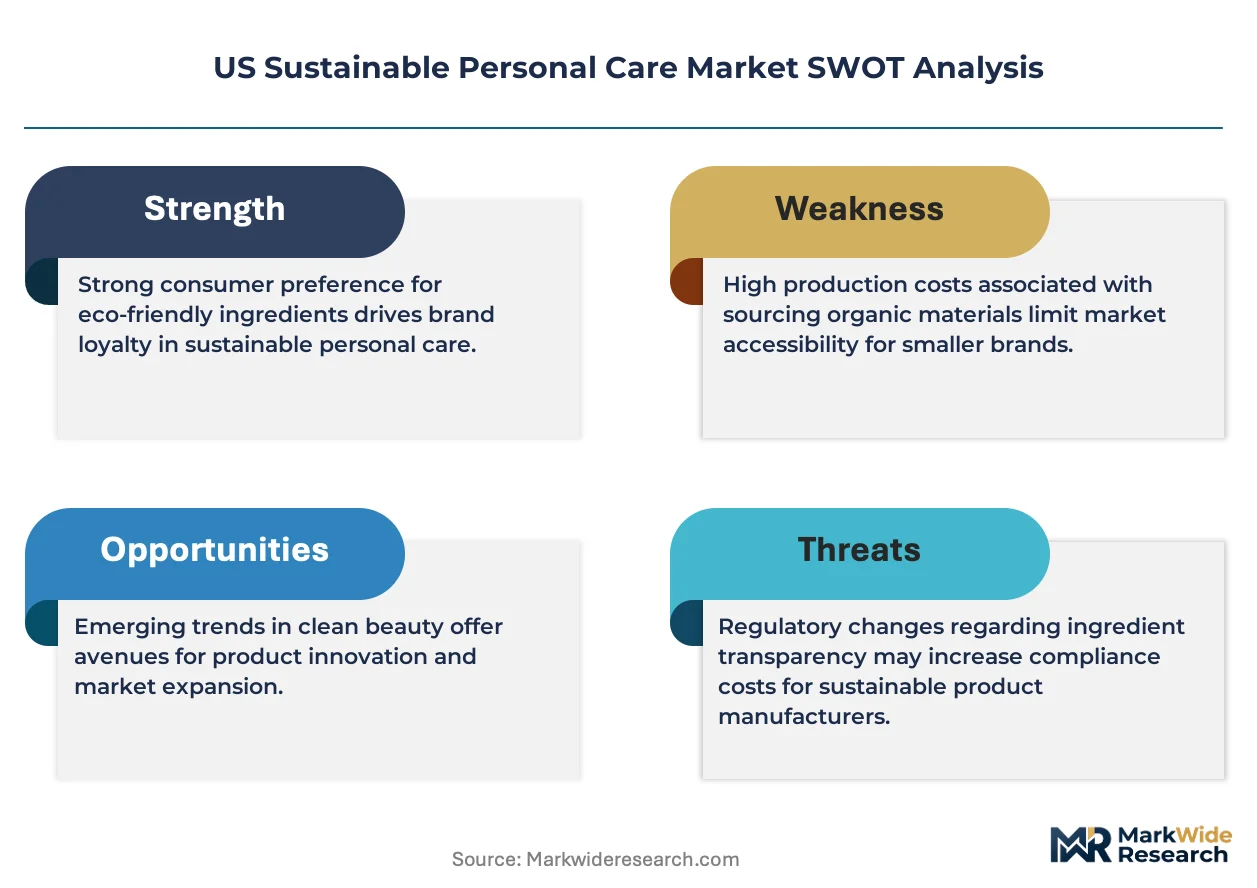
California's Toxic-Free Cosmetics Act and the EPA Safer Choice program are forcing simultaneous reformulation across preservative systems and surfactant chemistries, compressing product development timelines while opening premium positioning for early certifiers.
Growth Catalysts
- EPA Safer Choice Certification:Federal procurement preference under the USDA BioPreferred program opens institutional channels for biobased personal care items, creating volume anchors beyond retail.
- Millennial Household Penetration:This demographic segment drives fastest-expanding demand for refillable formats and biodegradable shampoo across Northeast and Pacific Coast urban corridors.
- Sugar-Based Surfactant Substitution:Formulators replace ethoxylated compounds with minimally processed alternatives, satisfying OECD 301 biodegradability standards without performance trade-offs.
Market Restraints
- Agricultural Feedstock Volatility:Plant-derived ingredient costs fluctuate with crop yields and commodity pricing, compressing margin stability for mass-market sustainable lines.
- Interstate Regulatory Fragmentation:State-level ingredient bans spreading beyond California force SKU proliferation or lowest-common-denominator formulation strategies.
- Petroleum-Based Surfactant Cost Advantage:Conventional alternatives retain price competitiveness at scale, slowing conversion in price-sensitive distribution channels.
Strategic Opportunities
- Professional Salon Channel Expansion:Organic-certified conditioners command sustained per-unit premium spending in this underpenetrated B2B segment.
- Fermentation-Derived Actives:Biotechnology platforms enable novel active ingredient sourcing independent of agricultural extraction constraints.
- Concentrated Refill Economics:Repeat purchase mechanics and brand loyalty lock-in create disproportionate margin pools in direct-to-consumer subscription models.
Industry Challenges
- OECD 301 Testing Bottlenecks:Biodegradability verification timelines extend product launch schedules, requiring parallel-track development protocols.
- FTC Green Guides Compliance:Environmental marketing claims face dual enforcement exposure alongside FDA cosmetic safety oversight, demanding specialized legal review.
- Closed-Loop Packaging Infrastructure:Regional collection and reprocessing capacity gaps limit refillable format scalability outside coastal metropolitan areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sustainable Personal Care Market |
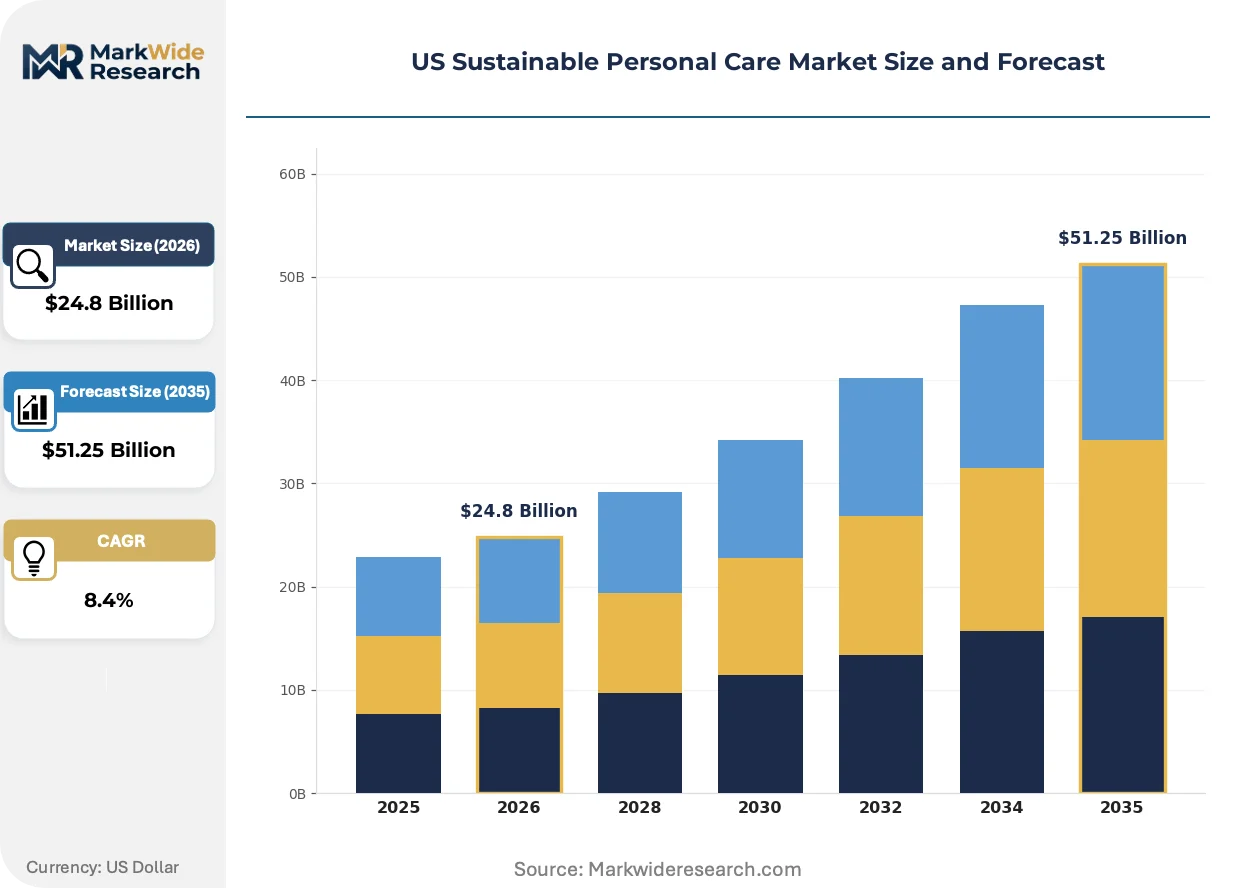
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Soap, Moisturizer Ingredient Source: Organic, Natural, Synthetic-Free, Biodegradable Packaging Type: Recyclable, Refillable, Compostable, Bioplastic Customer Type: Eco-Conscious Consumers, Millennials, Professionals, Families |
| Companies Covered | Colgate-Palmolive Company, Estée Lauder Companies, Inc., L'Oréal S.A., Coty, Inc., Kao Corporation, Procter & Gamble Company, Johnson & Johnson, Weleda AG, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sustainable Personal Care Market Trends and Innovations
Biotechnology fermentation platforms and state-level chemical disclosure mandates are converging to redefine ingredient sourcing transparency and active compound production economics.
Fermentation-derived biotech actives are integrating into premium skincare formulations, replacing traditional botanical extraction. Millennial and Gen Z buyers adopt these products at accelerating velocity through direct-to-consumer channels. This technology is integrating supply chain resilience by decoupling active ingredient production from agricultural seasonality and geographic concentration.
California's Toxic-Free Cosmetics Act mandates expanded preservative disclosure and restricts specific chemistries across interstate commerce. Formulators face compressed reformulation timelines to maintain national distribution efficiency. Professional salon channels and premium retail SKUs absorb compliance costs most readily, while mass-market lines risk margin compression.
Subscription-based refill purchasing is displacing conventional single-use retail cycles among eco-conscious urban households. Direct-to-consumer platforms and specialty retailers capture this behavioral shift, consolidating brand relationships through recurring revenue mechanics. This pattern concentrates in Pacific Coast and Northeast metropolitan markets where packaging waste reduction carries highest perceived value.
US Sustainable Personal Care Market Segmentation
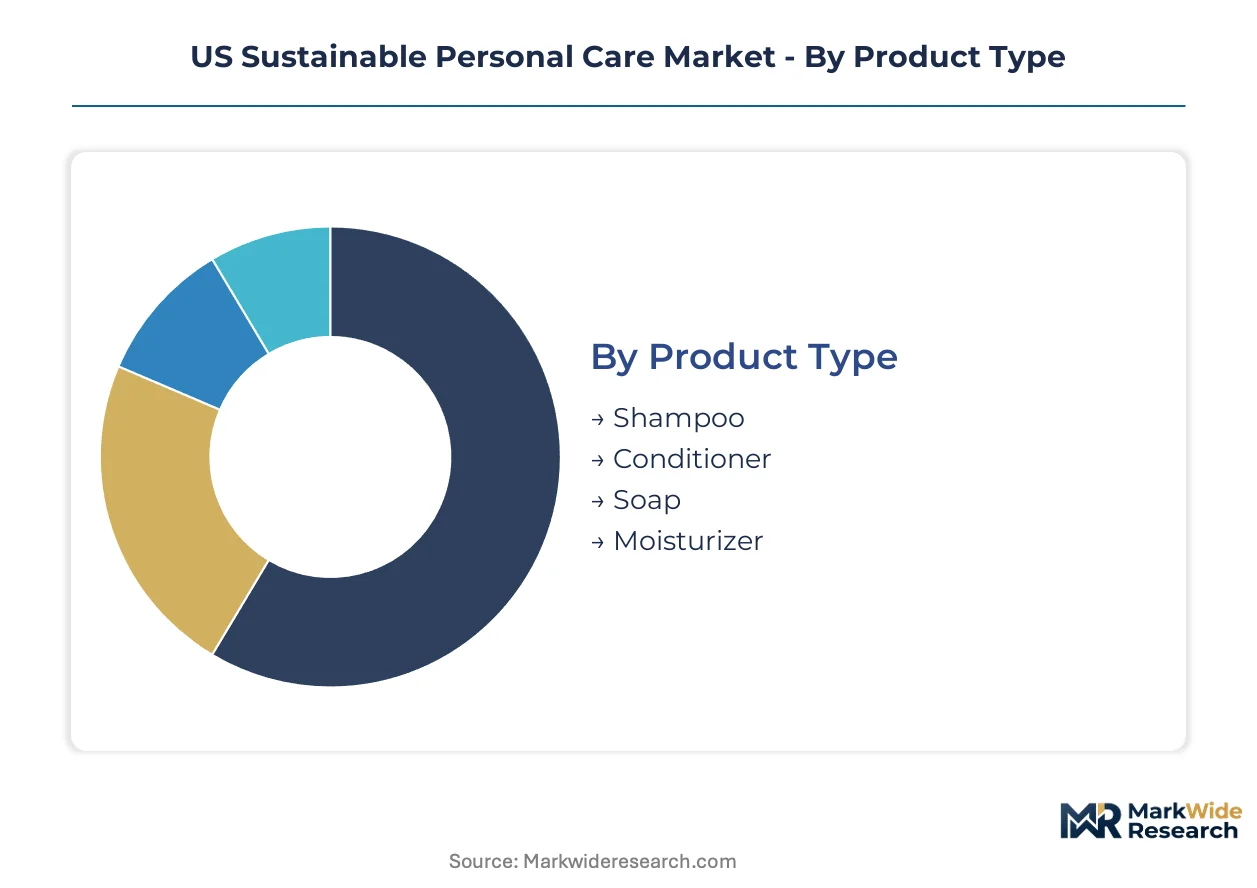
Segmentation in the US Sustainable Personal Care Market reveals divergent willingness-to-pay across ingredient sourcing standards and packaging formats. Manufacturers calibrate formulation complexity and material recovery systems to match distinct buyer priorities rather than pursuing uniform premium positioning.
Product Type:
Purchase frequency and per-unit spending vary sharply by personal care routine centrality and replacement cycles.
- Shampoo:Sugar-based surfactant formulations now match petroleum-derived alternatives on lather stability and rinse efficiency. Demand concentrates in Pacific Coast metropolitan markets where municipal water treatment costs amplify biodegradability premiums. Millennial households in Seattle and Portland drive fastest adoption of concentrated refill formats.
- Moisturizer:Biotech-derived active ingredients from fermentation platforms command sustained price premiums over botanical extracts. Northeast urban corridors absorb per-ounce costs exceeding conventional mass-market equivalents. Professional dermatology channels validate clinical efficacy claims for biotech-sourced ceramides and peptides.
- Conditioner:Organic-certified formulations sustain higher per-unit spending in professional salon channels.
- Soap:Bar formats reduce packaging intensity and shipping costs versus liquid alternatives.
Shampoo leads volumes today; moisturizer is gaining share fastest.
Ingredient Source:
Certification depth determines pricing tiers and distribution channel access.
- Biodegradable:OECD 301 testing compliance opens EPA Safer Choice procurement channels and California retail placement. Formulators replace ethoxylated compounds with minimally processed alternatives without sensorial trade-offs. Agricultural feedstock partnerships with Midwest corn and soybean growers secure volume supply.
- Organic:USDA certification mandates multi-year transition periods for botanical suppliers, constraining rapid scale-up. Professional salon and prestige retail channels absorb compliance cost premiums most readily. California's Toxic-Free Cosmetics Act disclosure requirements favor organic supply chains with established traceability systems.
- Natural:Less stringent certification allows faster formulation iteration and broader retail distribution.
- Synthetic-Free:Preservative system reformulation challenges shelf stability claims under FDA cosmetic safety oversight.
Natural formulations dominate current shelf space; biodegradable sourcing climbs the fastest.
Packaging Type:
Material recovery infrastructure availability dictates geographic rollout sequencing.
- Refillable:Direct-to-consumer subscription mechanics generate repeat purchase revenue and brand loyalty lock-in. Pacific Coast and Northeast metropolitan markets concentrate adoption where packaging waste reduction carries highest perceived value. Closed-loop collection partnerships with TerraCycle and regional reprocessors extend scalability.
- Recyclable:PET and HDPE compatibility with existing municipal sorting infrastructure enables national mass-market distribution. California's extended producer responsibility legislation accelerates post-consumer recycled content mandates. Cost parity with virgin plastics improves with scale procurement.
- Compostable:Industrial composting facility access limits viable geography to coastal metropolitan corridors.
- Bioplastic:Agricultural feedstock costs fluctuate with commodity pricing, compressing margin stability.
Recyclable formats anchor current volumes; refillable systems show steepest expansion trajectory.
Customer Type:
Age cohort and professional identity shape sensitivity to ingredient transparency and environmental claims.
- Millennials:Urban households in Boston, New York, and San Francisco drive concentrated demand for refillable formats and biodegradable shampoo. Digital-native purchase patterns favor direct-to-consumer discovery and subscription retention. FTC Green Guides awareness elevates scrutiny of environmental marketing claims.
- Professionals:Salon and clinical channel access sustains premium per-unit spending on organic-certified and biotech-derived formulations. Continuing education requirements create receptive audiences for ingredient science narratives. B2B procurement relationships reduce price elasticity.
- Eco-Conscious Consumers:Cross-category purchasing extends to household cleaning and apparel, amplifying lifetime value.
- Families:Volume purchasing and sensitivity to pediatric safety claims concentrate demand in mass-market natural segments.
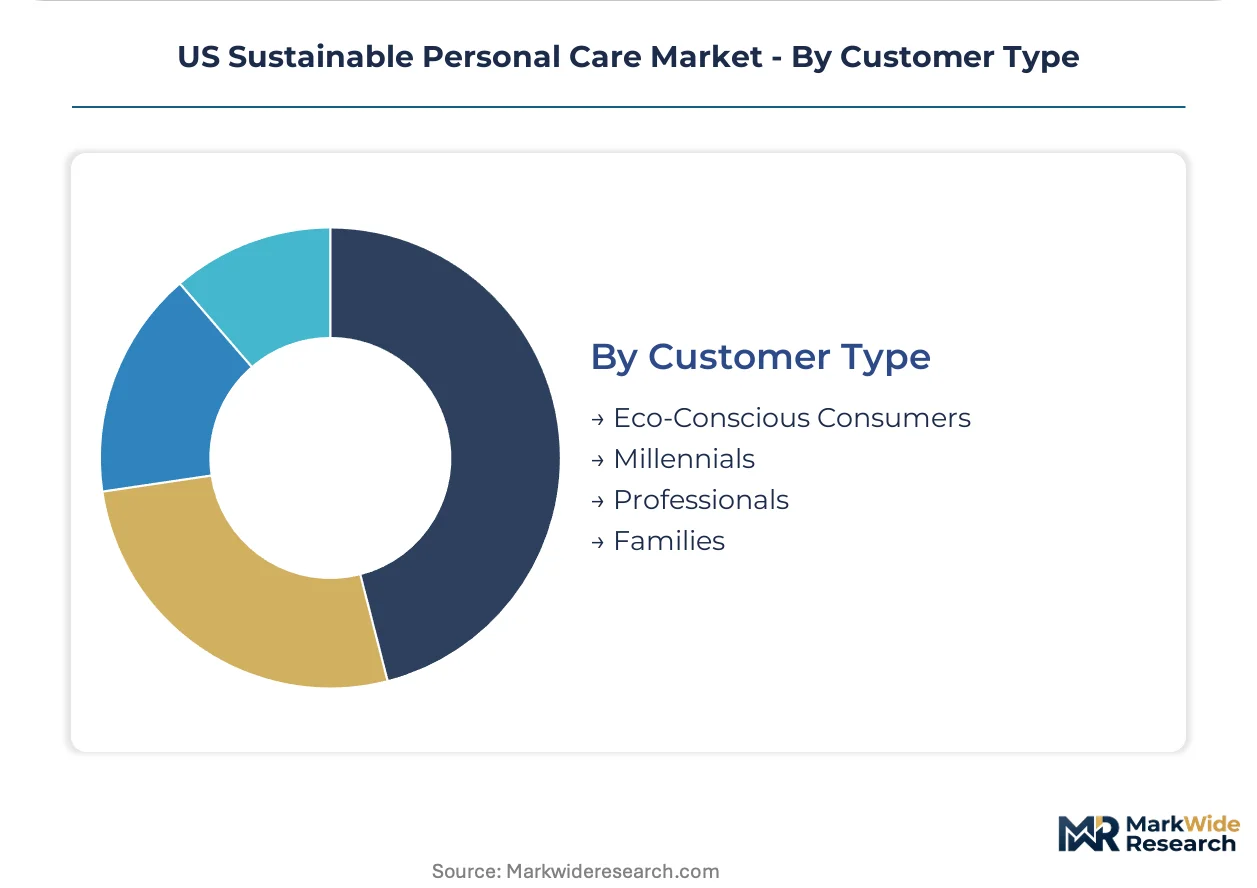
Millennials represent the largest addressable base today; professionals deliver the highest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Coast metropolitan clusters anchor US sustainable personal care demand through concentrated millennial purchasing power and stringent state-level chemical disclosure mandates.
California
Los Angeles and San Francisco metro areas absorb premium pricing for biodegradable shampoo and refillable moisturizer formats. The state's Toxic-Free Cosmetics Act restricts preservative chemistries and mandates expanded ingredient disclosure across interstate commerce. Oakland-based formulation labs accelerate reformulation timelines to maintain national distribution efficiency.
New York
Manhattan and Brooklyn households drive concentrated demand for biotech-derived active ingredients in prestige skincare. The state Department of Environmental Conservation enforces stricter wastewater discharge standards that favor OECD 301-compliant surfactants. Hudson Valley agricultural partnerships supply organic botanical feedstocks to regional formulators.
Massachusetts
Greater Boston's professional demographic sustains per-unit premium spending on organic-certified conditioners through salon channels. State procurement guidelines under the Executive Office of Energy and Environmental Affairs prioritize biobased personal care for institutional contracts. Cambridge biotechnology clusters enable fermentation-derived active ingredient development independent of agricultural extraction.
Washington
Seattle and Portland urban corridors exhibit fastest adoption of concentrated refill formats among millennial households. The state Department of Ecology coordinates with municipal water treatment authorities to amplify biodegradability premiums in consumer messaging. Puget Sound regional reprocessors build closed-loop packaging infrastructure for direct-to-consumer subscription models.
Texas
Dallas and Houston mass-market channels retain price sensitivity toward petroleum-based surfactant alternatives despite coastal premium migration. The Texas Commission on Environmental Quality maintains less restrictive chemical disclosure standards than California or New York counterparts. Austin emerging as secondary hub for clean beauty brand headquarters seeking lower operational costs than coastal metros.
US Sustainable Personal Care Market Competitive Landscape
Global majors compete with regional champions across formulation technology and packaging innovation, producing a tiered structure where scale advantages intersect with agility premiums. Consolidation pressure intensifies as EPA Safer Choice certification and state-level ingredient bans raise compliance fixed costs. Three archetypes dominate: multinational CPG conglomerates with captive agricultural partnerships, prestige beauty houses leveraging biotechnology platforms, and independent clean beauty specialists with direct-to-consumer distribution. Competitive moves concentrate on M&A for biotech capabilities and strategic partnerships for closed-loop packaging infrastructure.
Within the multinational tier, Procter & Gamble Company and Unilever PLC exemplify scale-driven positioning through mass-market sustainable hair care and concentrated refill economics respectively. Estée Lauder Companies, Inc. occupies a distinct biotechnology-forward position emphasizing fermentation-derived actives over traditional botanical extraction. These three entities anchor the competitive spectrum from volume-driven biodegradability compliance to premium-tier ingredient innovation.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Estée Lauder Companies, Inc. |
| L'Oréal S.A. |
| Coty, Inc. |
| Kao Corporation |
| Procter & Gamble Company |
| Johnson & Johnson |
| Weleda AG |
| Unilever PLC |
| Others |
Pricing and Supply Chain Analysis
Midwest corn futures and soybean commodity benchmarks cascade through plant-derived surfactant costs into tiered pricing structures across biodegradable shampoo and refillable moisturizer lines. Agricultural feedstock volatility compresses margin stability for mass-market sustainable personal care brands while premium biotech-derived formulations maintain pricing power through fermentation platform differentiation.
Pricing Analysis
Input-cost pass-through from agricultural commodities and biotech fermentation capacity drives three-tier pricing structure across premium, standard, and economy levels. USDA Organic certification and EPA Safer Choice status command measurable premiums over natural-labeled alternatives. Pricing pressure stems from petroleum-based surfactant cost advantages in Texas and Florida mass-market channels. Millennial urban households on the Pacific Coast show lowest price elasticity, while family buyers in price-sensitive Sun Belt metros resist per-unit premiums.
Supply Chain Analysis
Freight cost differentials between Midwest agricultural hubs and coastal formulation centers amplify regional pricing spreads for plant-derived ingredients. Supply concentration rests on Iowa and Illinois corn processing, Brazilian sugarcane for surfactant feedstocks, and Massachusetts biotechnology clusters for fermentation-derived actives. Single-source vulnerability concentrates in Midwest corn supply contracts subject to drought risk. Distribution runs through direct-to-consumer subscription platforms and professional salon channels alongside conventional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Texas operational costs diverge sharply from California regulatory compliance burdens, rewarding brands that segment formulation strategies by state-level chemical disclosure intensity.
For Market Incumbents: Acquire fermentation platform capabilities and closed-loop packaging infrastructure partnerships to defend against biotech-enabled entrants. Procter & Gamble Company and Unilever PLC should deepen backward integration into Midwest agricultural supply contracts to neutralize feedstock volatility. EPA Safer Choice certification investment locks in federal procurement preference before state-level bans proliferate. For New Entrants and Emerging Players: Professional salon buyers in Massachusetts and Washington represent the most penetrable high-margin segment for organic-certified conditioners. Austin, Texas offers headquarters cost advantages with emerging clean beauty talent pools. Direct-to-consumer subscription mechanics with TerraCycle collection partnerships bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap clean beauty specialists holding EPA Safer Choice certification and proprietary fermentation-derived active pipelines. Five-to-ten year viability hinges on regulatory compliance scalability rather than brand awareness alone. Watch California Toxic-Free Cosmetics Act enforcement intensity as the signal for national reformulation cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Acquisition | Biotech-derived actives decouple supply from agricultural seasonality and geographic concentration. |
| EPA Safer Choice Certification | Federal procurement preference under USDA BioPreferred opens institutional volume anchors beyond retail. |
| Closed-Loop Packaging Partnership | TerraCycle regional reprocessor agreements extend refillable format scalability outside coastal metros. |
| Professional Salon Channel Expansion | B2B procurement relationships in Massachusetts and Washington reduce price elasticity and sustain premiums. |
| Midwest Agricultural Supply Contract | Captive corn and soybean feedstock partnerships neutralize commodity volatility for mass-market lines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at Target and Sephora, supply planners at Procter & Gamble Company, and formulation scientists at Massachusetts biotechnology clusters with secondary validation. Nielsen retail audit data, EPA Safer Choice certified product databases, California Department of Public Health cosmetic filings, and USDA Organic certification records anchored bottom-up demand estimates against top-down market sizing.
Segment-weighting approaches distributed value and volume across product type, ingredient source certification depth, packaging format recovery infrastructure, and customer archetype willingness-to-pay dimensions throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves in biodegradable surfactant substitution and refillable format penetration, calibrated against EPA regulatory timeline assumptions and millennial household formation projections.
Underlying measurement precision varies by segment; refillable packaging adoption and professional salon channel spending carry tighter precision than mass-market natural formulation estimates. Forecasts reflect assumptions about state-level ingredient ban propagation and agricultural commodity stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Facial Rollers Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Europe Beauty and Personal Care Products Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Anti-Acne Facial Serum Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Bath and Body Products Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
Beard Oil Market
Beauty & Personal Care
Men's Personal Care Market