
 Financial Auditing Professional Services Market | 2026-2036
Financial Auditing Professional Services Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Auditing Professional Services Market Intelligence
Asset-light partnership models and distributed talent networks are reshaping competitive economics in financial auditing, allowing mid-tier firms to challenge incumbent scale advantages. Deloitte Touche Tohmatsu Limited leverages its global partnership structure to sustain margin discipline across disparate regulatory environments. BDO Global anchors its competitive position through specialized industry vertical depth rather than breadth of service lines. RSM International Association competes by controlling middle-market access channels that the Big Four historically underinvested.
Financial Auditing Professional Services encompasses independent examination of financial statements, internal controls, and regulatory compliance conducted by qualified accountants under generally accepted auditing standards or international standards on auditing, producing opinions that enable capital allocation decisions by investors, lenders, and regulators. External Audit services dominate fee pools due to mandatory statutory requirements for listed entities, while Forensic Audit represents the fastest-growing service type as fraud detection mandates expand across banking and fintech sectors. The Engagement Model dimension shows Retainer structures capturing predictable revenue streams from multinational corporations, whereas Project-Based arrangements concentrate margin in transaction-heavy verticals such as private equity and real estate.
The SEC and PCAOB in the United States, alongside the FRC in the United Kingdom and ESMA across the European Union, enforce rotation requirements, independence standards, and technology audit protocols that directly determine firm eligibility and pricing power. These frameworks elevate compliance costs while creating structural barriers that favor established networks with capital to absorb regulatory technology investments. Stakeholders must monitor how AI-driven audit automation intersects with evolving liability standards to determine whether efficiency gains translate to margin expansion or commoditization pressure.
Market Dynamics
Artificial intelligence is collapsing traditional audit sampling methodologies across the Big Four and mid-tier firms, compressing engagement timelines while elevating liability exposure under PCAOB scrutiny. Regulatory technology mandates from the SEC and ESMA are forcing capital redeployment toward algorithmic assurance tools.
Growth Catalysts
- SEC Climate Disclosure Rules:Mandatory reporting of Scope 1-3 emissions and climate-related financial risks is expanding attestation requirements for listed registrants, creating new assurance revenue pools.
- Banking Sector Fraud Detection Mandates:Post-SVB regulatory pressure from the Federal Reserve is accelerating forensic audit demand across regional banks and fintech platforms.
- Cross-Border IPO Surge:Technology firms listing on multiple exchanges simultaneously require jurisdictional audit harmonization, driving retainer-based engagement expansion.
Market Restraints
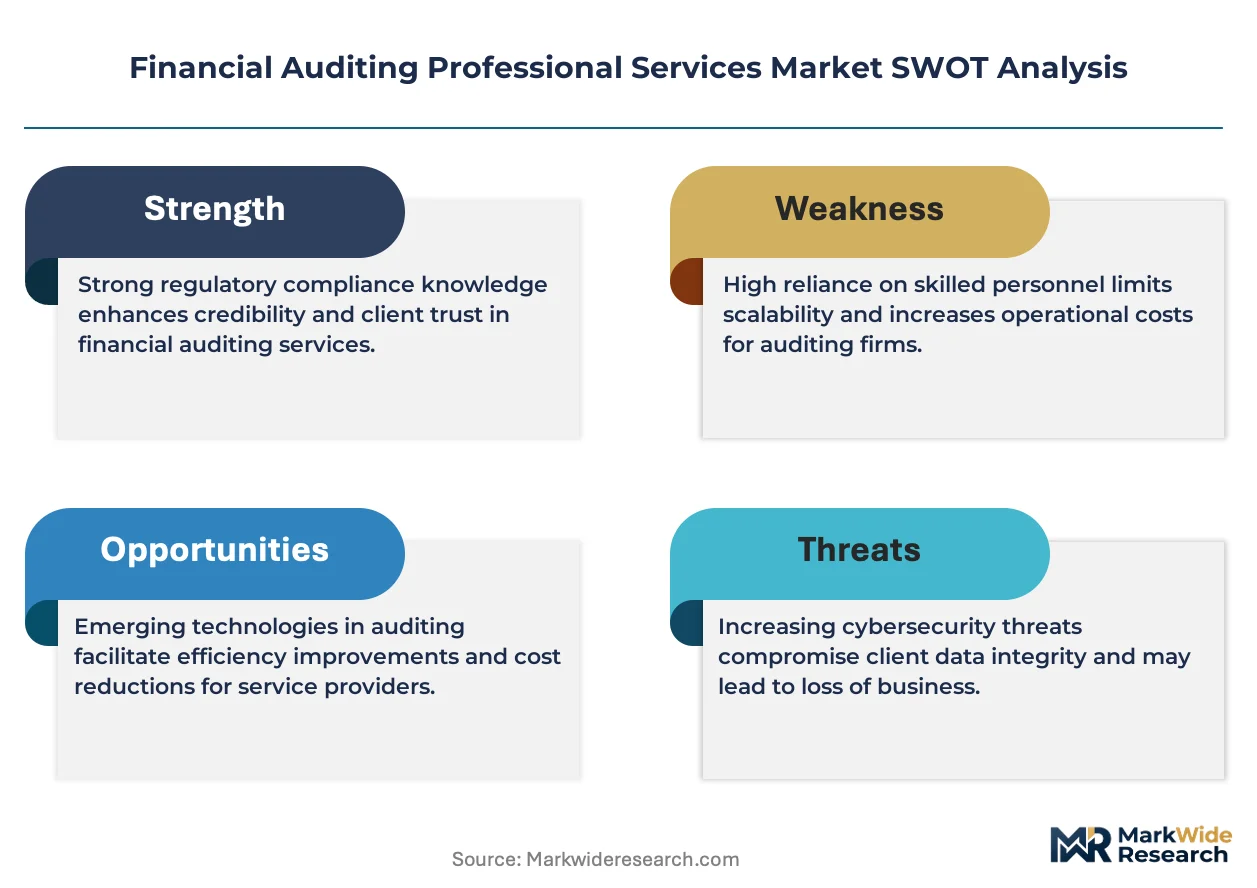
- Partner Talent Scarcity:CPA pipeline contraction and Big Four retention wars are inflating labor costs faster than fee growth can absorb.
- Regulatory Technology Capex Burden:Mandatory AI audit tool validation under PCAOB standards requires non-recoverable infrastructure investment.
- Audit Liability Asymmetry:Class-action exposure under US securities law outpaces insurance capacity, compressing net margins on high-risk engagements.
Strategic Opportunities
- ESG Assurance White Space:CSRD implementation across the European Union is creating first-mover advantage for firms with verified sustainability attestation methodologies.
- Middle-Market Channel Control:Private equity portfolio company density in the US Southeast represents underpenetrated audit demand relative to Fortune 500 saturation.
- Blockchain-Enabled Continuous Auditing:Convergence of distributed ledger technology with automated control testing is collapsing the traditional annual engagement cycle into real-time assurance models.
Industry Challenges
- Algorithmic Audit Defensibility:Courts and regulators have not established liability standards for AI-generated findings, creating professional indemnity ambiguity.
- Legacy ERP Integration Friction:Client systems running on-premise SAP and Oracle architectures resist API-based data extraction, inflating engagement scoping costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Auditing Professional Services Market |
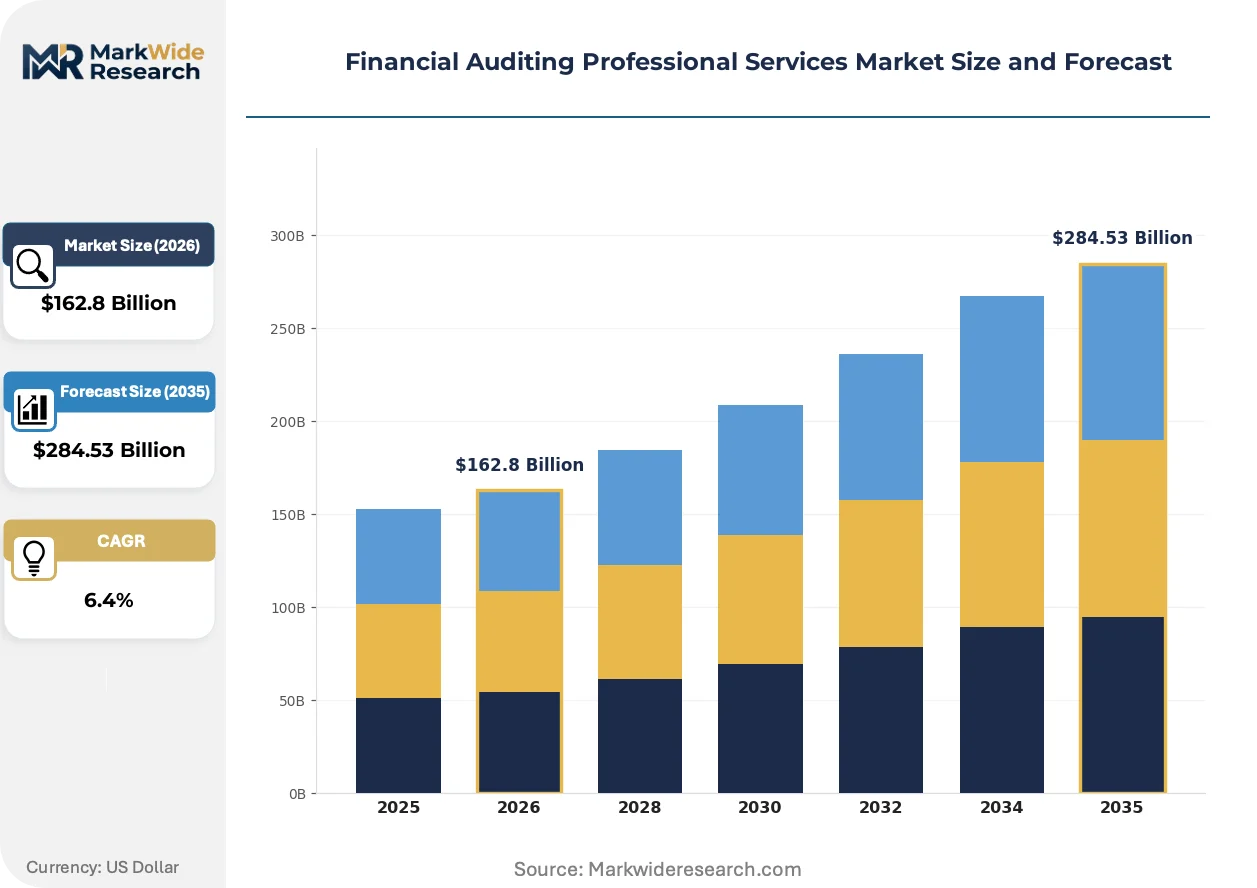
| Market Size in 2026 | $162.8 Billion |
| Market Size in 2035 | $284.53 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Internal Audit, External Audit, Compliance Audit, Forensic Audit Client Type: Corporations, Nonprofits, Government, Startups Industry Vertical: Financial Services, Healthcare, Manufacturing, Real Estate Engagement Model: Retainer, Project-Based, Hourly Billing, Contingency |
| Companies Covered | Deloitte Touche Tohmatsu Limited, PricewaterhouseCoopers (PwC), Ernst & Young (EY), KPMG International, BDO Global, RSM International Association, Grant Thornton International Ltd., Mazars, Moore Stephens International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Auditing Professional Services Market Strategic Shifts & Innovations
Audit execution is fragmenting across human-machine task boundaries, with firms racing to embed predictive analytics without triggering regulatory censure. Three forces are compressing traditional service delivery models.
Natural language processing is collapsing document review cycles in financial statement audits. Mid-tier firms deploying GPT-class tools for contract analysis and anomaly detection are compressing fieldwork duration by half. The structural consequence is fee pressure on standardized engagements while premium pricing concentrates on judgment-intensive sectors.
ESMA's Corporate Sustainability Reporting Directive is mandating double materiality assessments for EU-listed entities. This regulatory architecture is forcing US-domiciled firms with European subsidiaries to build parallel assurance capabilities. Asset managers with cross-border holdings are now requiring unified ESG audit frameworks across their portfolio companies.
Subscription-based audit delivery is displacing project-based procurement in the private equity vertical. General partners running quarterly valuation cycles are demanding continuous access to portfolio company financial data rather than point-in-time opinions. This shift is most visible in US buyout markets where holding periods have extended beyond traditional annual review cycles.
Financial Auditing Professional Services Market Segmentation
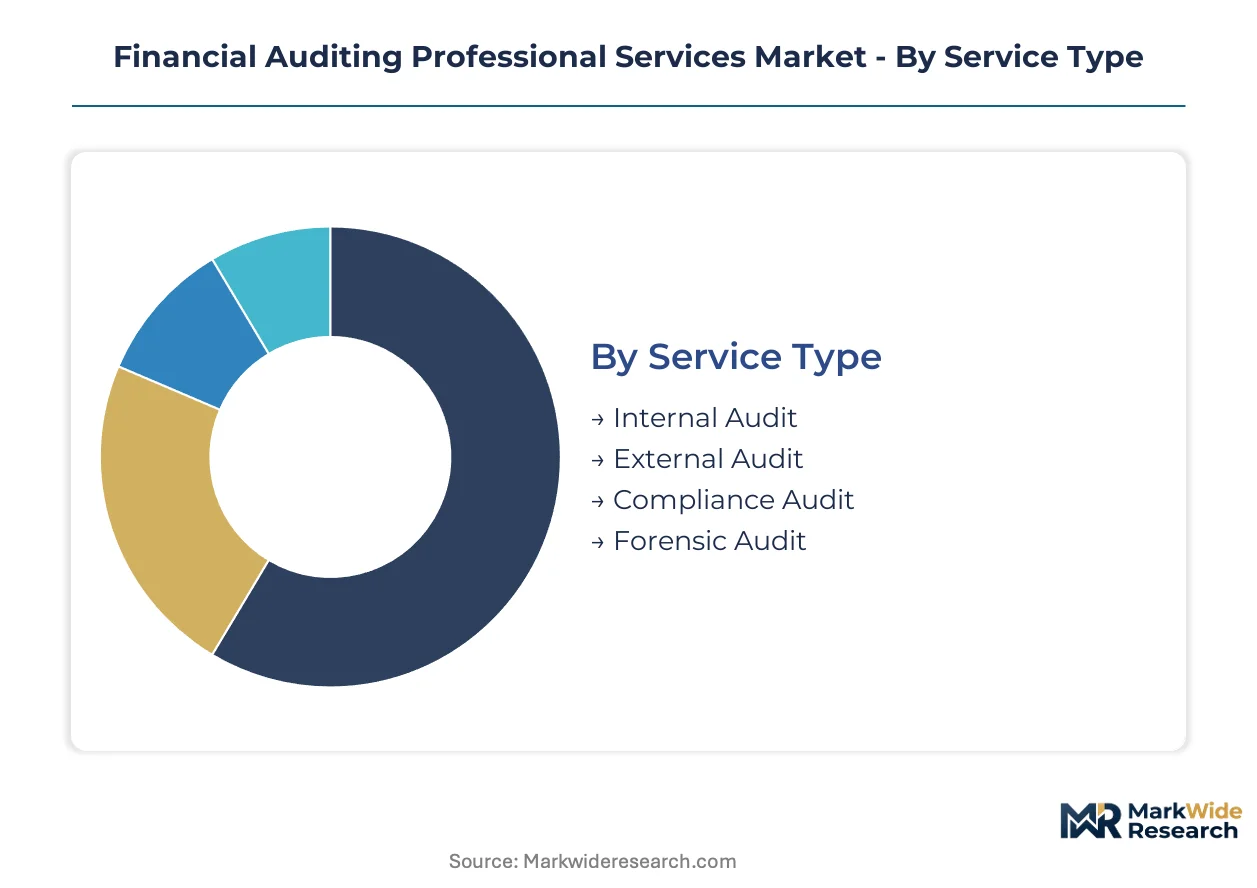
Segmentation in financial auditing professional services determines pricing power, talent allocation, and regulatory compliance architecture. Distinct service types and engagement models command margin premiums based on liability exposure and statutory mandates. Client type and industry vertical selection shapes firm risk profiles and recurring revenue stability.
Service Type:
Use cases span from voluntary governance enhancement to legally mandated assurance, creating divergent margin structures and talent requirements.
- External Audit:Statutory examination of financial statements under PCAOB or ISA standards produces opinions required for securities listings and debt covenants. Publicly traded corporations across the United States and European exchanges sustain premium fee pools through mandatory annual engagement cycles and rotation requirements.
- Forensic Audit:Fraud investigation and litigation support services apply specialized investigative techniques to financial anomalies. Banking regulators in the United States and fintech platforms experiencing rapid transaction growth are accelerating procurement of these services following regional bank failures.
- Internal Audit:Governance-focused control assessments commissioned by boards and audit committees.
- Compliance Audit:Regulatory adherence verification against SEC, FRC, or ESMA standards.
Established volume favors External Audit; emerging adoption favors Forensic Audit.
Client Type:
Procurement sophistication and budget scale vary dramatically across organizational forms, shaping service packaging and partner staffing ratios.
- Corporations:Large enterprises with complex subsidiary structures demand integrated global audit programs. Fortune 500 companies in the United States generate retainer-based revenue stability through multi-year engagement contracts and Sarbanes-Oxley compliance mandates.
- Startups:Venture-backed emerging companies require audit readiness and IPO preparation services. Technology firms pursuing cross-border listings in the United States and European Union are expanding project-based demand for jurisdictional harmonization expertise.
- Government:Federal and state agencies with appropriations-based funding cycles.
- Nonprofits:Mission-driven organizations with donor-imposed audit requirements.
Contract predictability concentrates with Corporations; growth velocity clusters with Startups.
Industry Vertical:
Sector-specific regulatory density and transaction complexity create specialized competency moats that sustain pricing premiums.
- Financial Services:Banking, insurance, and asset management entities face intensified supervisory scrutiny. Regional banks in the United States are expanding forensic and compliance audit spending following Federal Reserve enforcement actions.
- Healthcare:Providers and payers navigate HIPAA privacy mandates and Medicare reimbursement audits. Hospital systems and pharmaceutical manufacturers require specialized clinical revenue cycle expertise.
- Manufacturing:Inventory valuation and cost accounting complexity across global supply chains.
- Real Estate:Investment trust structures and development project financing controls.
Regulatory intensity peaks in Financial Services; margin compression risk concentrates in Real Estate.
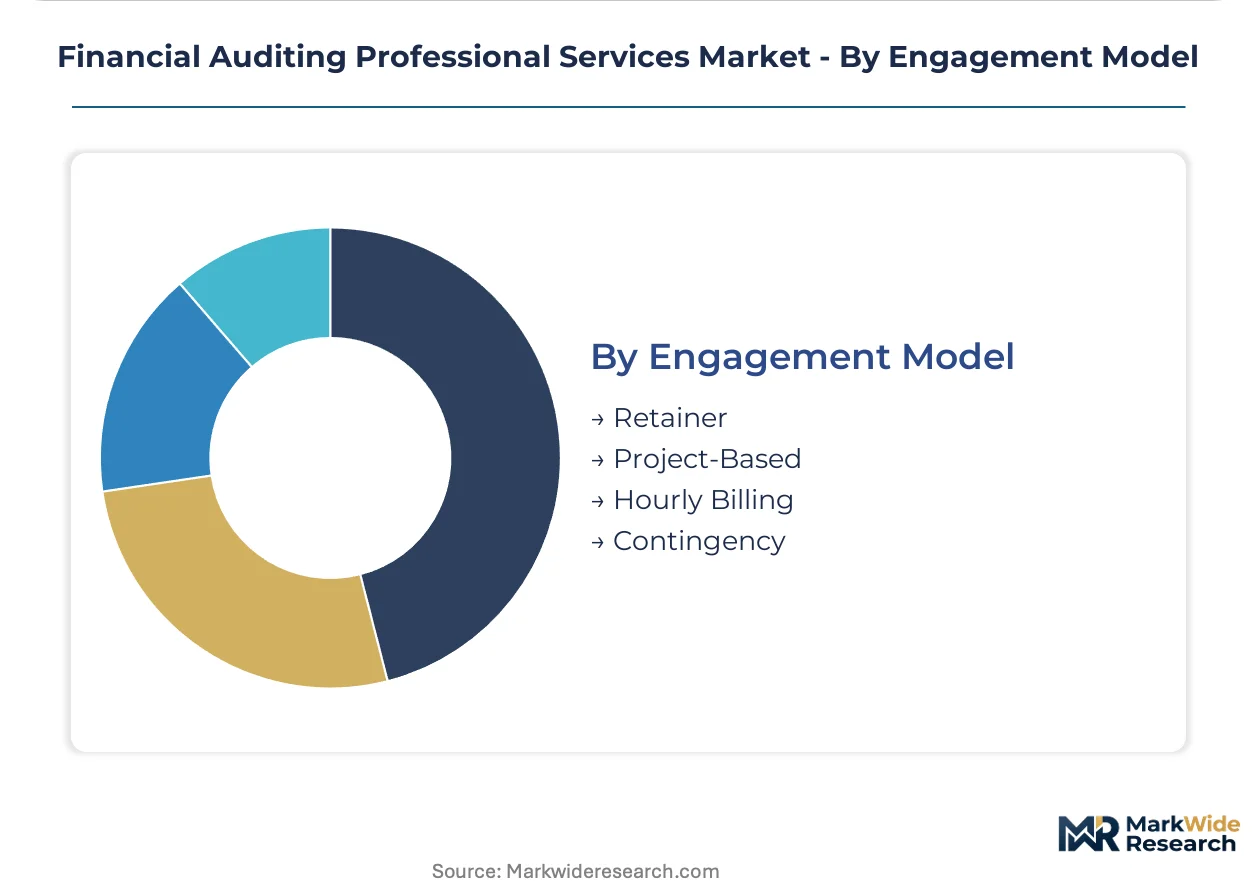
Engagement Model:
Revenue recognition timing and working capital requirements shift materially across contractual structures, altering firm cash flow profiles.
- Retainer:Fixed-fee arrangements providing continuous access to audit partner teams. Multinational corporations with distributed operations favor this structure for budget certainty and relationship continuity.
- Project-Based:Scoped engagements tied to specific transactions or events. Private equity sponsors in the United States deploy this model for quarterly portfolio valuation cycles and acquisition due diligence.
- Hourly Billing:Time-and-materials pricing for ad hoc advisory and investigation services.
- Contingency:Success-fee structures in forensic recovery and claims validation contexts.
Recurring revenue concentrates in Retainer arrangements; margin expansion potential clusters in Project-Based procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 corporations and cross-border technology listings concentrate audit procurement in jurisdictions with stringent securities regulation and deep capital markets. The United States, United Kingdom, Germany, Japan, and Australia represent the dominant geographies where mandatory rotation requirements and climate disclosure mandates sustain premium fee pools.
United States
Sarbanes-Oxley compliance and PCAOB oversight sustain mandatory external audit spending across publicly traded corporations. The SEC's climate disclosure rules for Scope 1-3 emissions are expanding attestation requirements for listed registrants. New York and Chicago anchor the highest partner density, with regional banks in the Southeast accelerating forensic audit procurement following Federal Reserve enforcement actions.
United Kingdom
London's status as a dual-listing venue for technology firms drives demand for jurisdictional audit harmonization expertise. The Financial Reporting Council enforces auditor rotation and independence standards that elevate compliance costs for multinational engagements. The Square Mile and Canary Wharf clusters concentrate Big Four partnership resources serving FTSE 100 and private equity sponsors.
Germany
Industrial conglomerates with complex subsidiary structures require integrated global audit programs under EU statutory mandates. The national implementation of CSRD is forcing US-domiciled firms with German operations to build parallel sustainability assurance capabilities. Frankfurt and Munich host the densest mid-tier firm presence competing for family-owned Mittelstand accounts.
Japan
Cross-border IPO activity from domestic technology ventures is elevating demand for US-GAAP and IFRS reconciliation expertise. The Financial Services Agency enforces audit firm rotation requirements that create recurring engagement cycles for listed entities. Tokyo's Marunouchi district anchors the Big Four's Japanese partnership networks serving TSE Prime Market registrants.
Australia
Superannuation fund governance mandates and ASIC enforcement actions are expanding internal audit and compliance service procurement. The national climate risk disclosure framework for financial institutions is creating new assurance revenue streams. Sydney and Melbourne concentrate mid-tier firm competition for ASX 200 audit rotations and private equity portfolio company engagements.
Financial Auditing Professional Services Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where scale advantages fragment below the largest global networks. The market consolidates around partnership-based entities with capital to absorb regulatory technology investments, while mid-tier associations exploit industry vertical depth and geographic white space. Two strategic archetypes dominate: full-service global networks competing on cross-border coordination, and specialized national or regional firms capturing middle-market access. Competitive moves center on M&A-driven capability expansion and technology licensing arrangements that accelerate AI audit tool deployment.
Within the global network tier, Deloitte Touche Tohmatsu Limited, PricewaterhouseCoopers, and BDO Global exemplify divergent structural approaches to partnership economics. Deloitte's global partnership structure represents the integrated network model sustaining margin discipline across disparate regulatory environments. PwC occupies a position emphasizing technology audit protocols and cross-border coordination for multinational listings. BDO Global exemplifies the specialized vertical strategy, anchoring competitive position through industry depth rather than service line breadth. These three entities collectively illustrate how scale, specialization, and partnership governance create distinct competitive positions within the same regulatory framework.
| Leading Market Players |
|---|
| Deloitte Touche Tohmatsu Limited |
| PricewaterhouseCoopers (PwC) |
| Ernst & Young (EY) |
| KPMG International |
| BDO Global |
| RSM International Association |
| Grant Thornton International Ltd. |
| Mazars |
| Moore Stephens International Limited |
| Others |
Cost & Logistics Intelligence
Regulatory technology capex burden determines both pricing tier spreads and supply chain shape across financial auditing professional services. Mandatory AI audit tool validation under PCAOB standards forces non-recoverable infrastructure investment that stratifies cost structures between global networks and mid-tier associations.
Pricing Analysis
Cost-plus contracts with labor rate indexation dominate engagement structures, particularly for retainer-based multinational corporation relationships. Three-tier pricing structure across premium, standard, and economy levels separates Big Four statutory assurance from mid-tier industry specialization and regional compliance-only offerings. Price differentiation rests on partner seniority grade and cross-border coordination complexity. Pricing pressure stems from AI-driven automation compressing fieldwork duration on standardized engagements. Private equity sponsors exhibit highest price sensitivity due to quarterly valuation cycle density, while Fortune 500 corporations prioritize relationship continuity over rate negotiation.
Supply Chain Analysis
Supply-chain finance facilities and extended payment terms from audit technology vendors are restructuring working capital requirements for mid-tier firms. Talent supply concentrates in the United States, United Kingdom, and India, with CPA pipeline contraction creating recruitment bottlenecks. Raw material dependencies include proprietary audit software licenses, cloud computing infrastructure, and specialized forensic analytics tools. Single-source vulnerability sits with dominant ERP system providers whose on-premise architectures resist API-based data extraction. Distribution runs through partnership networks rather than direct client acquisition, with global networks leveraging referral relationships across jurisdictional boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in ESG assurance and middle-market channel control as climate disclosure mandates and private equity portfolio density create addressable niches beneath Big Four saturation.
For Market Incumbents: Pre-empt mid-tier encroachment by accelerating AI audit tool deployment ahead of PCAOB validation requirements while consolidating middle-market access through targeted lateral partner hiring in the US Southeast. Threat vectors include RSM International's channel control and BDO Global's vertical depth. Vertical integration into proprietary sustainability attestation methodologies offers defensive moat construction. For New Entrants and Emerging Players: Pursue forensic audit specialization targeting regional banks under Federal Reserve enforcement pressure and CSRD implementation advisory for US-domiciled firms with European subsidiaries. White space concentrates in sustainability assurance methodology development where verified frameworks remain scarce. Go-to-market execution should emphasize subscription-based delivery models displacing project-based procurement in private equity verticals. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors algorithmic assurance capability over legacy audit scale. Long-term viability across the projection horizon hinges on regulatory technology absorption capacity rather than historical client relationships. Acquisition target archetype: mid-tier firms with verified ESG attestation methodologies and established private equity channel access. Signal to watch: PCAOB enforcement actions against AI-generated findings establishing liability precedent.| Strategic Initiative | Industry Significance |
|---|---|
| AI Audit Tool Deployment | PCAOB validation requirements force capital redeployment toward algorithmic assurance capabilities. |
| ESG Assurance Methodology Development | CSRD implementation creates first-mover advantage for verified sustainability attestation frameworks. |
| Middle-Market Channel Acquisition | Private equity portfolio density in the US Southeast represents underpenetrated audit demand. |
| Forensic Audit Capability Expansion | Federal Reserve enforcement actions accelerate procurement across regional banking institutions. |
| Subscription-Based Delivery Model | Quarterly valuation cycles demand continuous data access rather than point-in-time opinions. |
Research Approach
Operator-level perspectives from audit partners, regulatory compliance officers, private equity CFOs, and technology procurement leads anchored the qualitative base for this study. Primary fieldwork combined structured interviews across these stakeholder categories with secondary validation from SEC filings, PCAOB inspection reports, ESMA regulatory guidance, and professional association membership data. Bottom-up engagement modeling and top-down market sizing triangulated volume estimates across service type, client category, and geographic clusters.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity analysis applied to AI adoption curves and regulatory enforcement intensity. Segmentation dimensions modeled include service type, engagement model, client scale tier, and industry vertical regulatory density. CAGRs derived from historical fee growth patterns adjusted for technology-driven efficiency gains and liability cost inflation. Forecast inputs incorporated CPA pipeline contraction rates and climate disclosure mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting private equity transaction velocity or regulatory enforcement budgets would shift the trajectory. Forecasts reflect documented assumptions regarding PCAOB technology standards evolution and ESMA CSRD implementation consistency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Middle Office Outsourcing Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Europe B2C Legal Services Market
Financial Services
ATM Outsourcing Services Market
Financial Services
Mobile Notary Public Market
Financial Services
Legal Management Consulting Service Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Mobile Notary Service Market
Financial Services
Reconciliation Software Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
White Glove Services Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Virtual Account Management Software Market