
 Wetting Agents Market | 2026-2036
Wetting Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Wetting Agents Market Analysis
Agricultural adjuvant demand is repositioning wetting agent procurement toward bio-based formulations. BASF SE leverages its crop science division to anchor supply contracts across major agrarian belts. Evonik Industries AG specializes in organomodified siloxane chemistry for high-performance coatings. Croda International Plc extends its natural-derived surfactant portfolio to capture personal care and food-grade specifications.
Wetting agents are surface-active compounds that reduce interfacial tension between liquids and solids, typically functioning at concentrations below critical micelle concentration to enable uniform spreading across hydrophobic substrates. Anionic variants dominate industrial cleaning and agricultural tank-mix applications due to cost efficiency and rapid wetting kinetics. Nonionic wetting agents command premium positioning in paints and coatings where foam control and compatibility with resin systems determine formulation success. The liquid form leads volume throughput across construction and textile processing, while powder grades concentrate in dry agrochemical formulations where storage stability and transport economics matter.
EPA registration requirements under FIFRA govern agricultural wetting agent composition and ecotoxicity labeling in the United States. REACH substance evaluation and the EU Green Deal chemicals strategy are restricting persistent surfactant chemistries across European manufacturing. China's MEE enforces discharge standards that push domestic producers toward biodegradable alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and market access barriers.
Market Dynamics
REACH substance evaluation and EPA FIFRA registration requirements are forcing simultaneous reformulation across multiple wetting agent chemistries, compressing development timelines while elevating purity thresholds for agricultural and industrial applications.
Growth Catalysts
- Precision farming expansion:Brazil and India are deploying variable-rate application systems that require tank-mix compatible wetting agents with defined drift reduction properties.
- EU Green Deal chemicals strategy:The framework's restriction criteria for persistent organic pollutants is accelerating substitution demand for biodegradable surfactant architectures.
- Organomodified siloxane chemistry:High-performance coatings manufacturers are specifying these materials for substrate wetting where foam control and slip resistance must coexist.
Market Restraints
- Ethylene oxide supply concentration:Key feedstock for nonionic surfactant production clusters in Texas and Rotterdam, exposing formulators to price volatility from upstream petrochemical disruptions.
- Biodegradability testing timelines:OECD 301B and 306 protocols extend new product registration by 18-24 months in jurisdictions with mandatory environmental fate data.
- Fluorosurfactant substitution gap:PFAS restrictions under EPA TSCA Section 6 and state-level prohibitions are removing high-performance options before bio-based alternatives achieve equivalent surface tension reduction.
Strategic Opportunities
- Dry agrochemical formulations:Powder wetting agent grades for Southeast Asian contract manufacturers offer transport cost advantages over liquid concentrates.
- Food-grade surfactant specifications:FSSAI and FDA 21 CFR 173 compliance pathways for emulsifier-wetting agent dual-function products open processing aid applications.
- Construction chemical compatibility:Cement admixture formulators in the UAE and Saudi Arabia are specifying wetting agents for self-compacting concrete where flow retention demands precise air entrainment control.
Industry Challenges
- Surfactant synthesis scale-up:Moving from pilot-batch organosilicone modification to commercial-scale continuous processing requires capex commitments that mid-tier specialty chemical producers struggle to finance.
- Multijurisdictional dossier management:Maintaining substance identity consistency across REACH registrations, EPA PMN submissions, and China's MEE new chemical notifications consumes technical regulatory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wetting Agents Market |
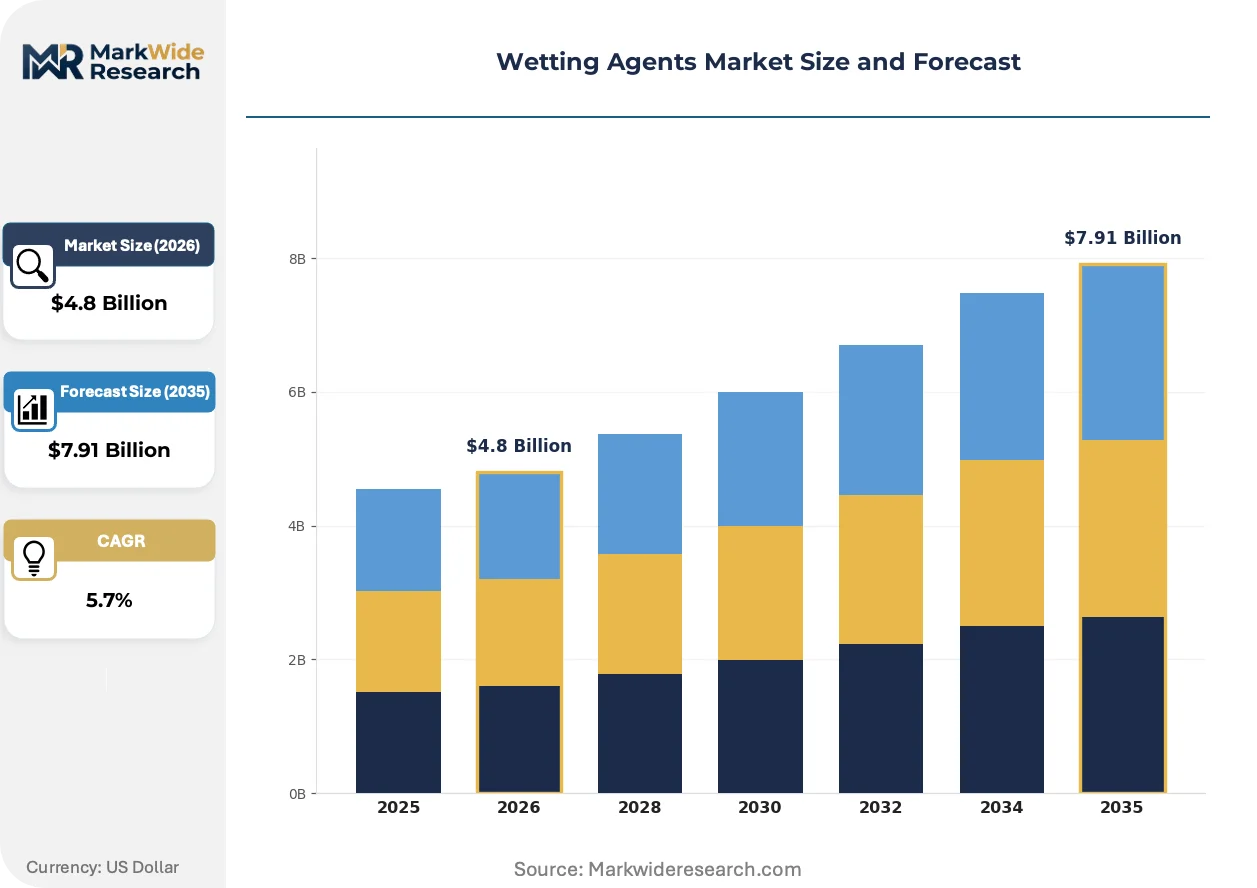
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Anionic, Cationic, Nonionic, Amphoteric Application: Paints, Coatings, Agriculture, Textile End User: Construction, Personal Care, Food & Beverage, Pharmaceuticals Form: Liquid, Powder, Granules, Paste |
| Companies Covered | Clariant AG, AkzoNobel N.V., BASF SE, BYK-Chemie GmbH, Arkema SA, The Dow Chemical Company, Croda International Plc, Ashland Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wetting Agents Market Emerging Trajectories
Bio-based feedstock substitution and digital formulation tools are compressing the traditional surfactant development cycle while regulatory fragmentation forces parallel compliance architectures.
Alkyl polyglucoside synthesis from fatty alcohols and glucose streams is integrating into agricultural adjuvant portfolios as crop protection companies face shareholder pressure to reduce petrochemical dependency. Formulators in the US Corn Belt and Brazilian Cerrado are specifying these materials for pre-emergence herbicide applications where rapid leaf wetting must not compromise crop safety. The technology is integrating tank-mix compatibility testing with drone application parameters, collapsing the historical separation between laboratory screening and field deployment validation.
REACH authorization requirements for substances of very high concern are eliminating nonylphenol ethoxylates from textile processing auxiliaries across European dyehouse operations. Wetting agent suppliers must reformulate with alcohol ethoxylates or glucamide alternatives while maintaining equivalent wetting kinetics on polyester-cotton blends. German and Italian textile machinery OEMs are now specifying surfactant compliance certificates as mandatory bid documentation, transferring regulatory verification burden upstream to chemical suppliers.
Direct procurement relationships between agrochemical multinationals and surfactant manufacturers are displacing traditional distribution intermediaries in Asia-Pacific supply corridors. BASF and Syngenta field technical teams now negotiate specification compliance directly with Zhejiang and Jiangsu surfactant producers, compressing commercial terms and technical service layers that previously flowed through regional distributors. This pattern concentrates most visibly in China's Yangtze River Delta manufacturing clusters where formulation packaging and surfactant synthesis occur within 200-kilometer radii.
Wetting Agents Market Segmentation
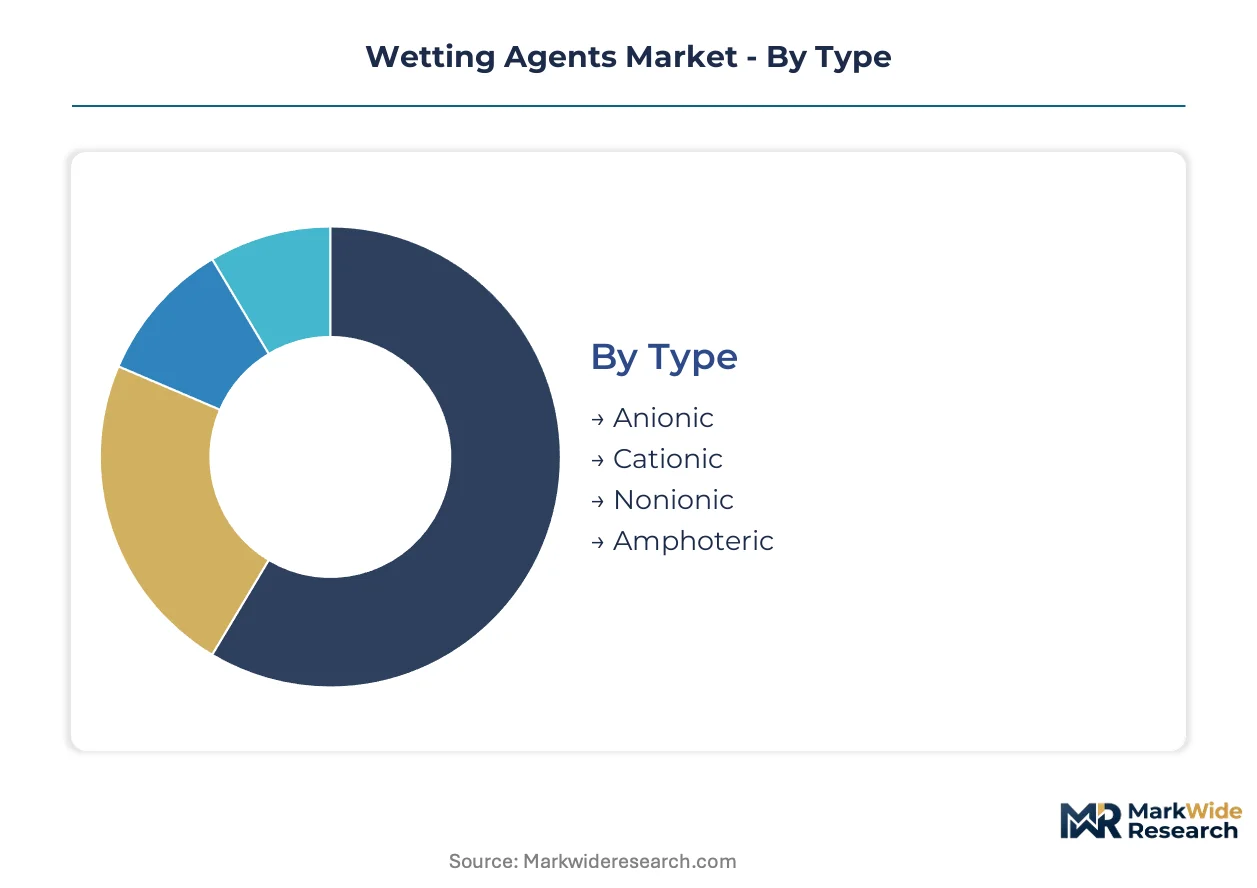
Wetting agent specifications diverge sharply across end-use requirements, with agricultural tank-mix compatibility demanding different surfactant architectures than food-grade emulsifier standards. Formulation chemists select ionic character and physical state based on substrate hydrophobicity, processing temperature, and regulatory jurisdiction.
Type:
Capital intensity clusters around organomodified silicone synthesis and specialized amphoteric production, where multi-step reactions and purification stages demand continuous processing infrastructure.
- Anionic:Sulfate and sulfonate headgroups deliver rapid wetting kinetics at low concentrations. Agricultural tank-mix applications in Brazil and India specify these variants for pre-emergence herbicide compatibility with hard water conditions. Cost efficiency and established supply chains sustain volume leadership despite biodegradability scrutiny under REACH.
- Nonionic:Ethoxylated fatty alcohols and alkylphenol derivatives provide foam control and resin compatibility critical to high-performance coatings. EU Green Deal restrictions on persistent organic pollutants are accelerating substitution toward alcohol ethoxylate architectures in German and Italian textile processing.
- Cationic:Quaternary ammonium compounds serve specialty applications requiring antimicrobial synergy or fabric softening dual-function.
- Amphoteric:Betaine and imidazoline structures command premium positioning in personal care where pH tolerance and mildness specifications dominate formulation decisions.
Anionic variants absorb the bulk of installed capacity; nonionic grades are expanding most quickly as coatings manufacturers specify organosilicone modifications.
Application:
Application selection follows substrate surface energy and processing environment, with agricultural drift reduction properties now specified alongside traditional wetting performance metrics.
- Agriculture:Tank-mix adjuvants require defined spreading coefficients and rainfastness intervals for drone application systems. Precision farming expansion across Brazil's Cerrado and India's Punjab belt is specifying wetting agents with validated compatibility for variable-rate sprayers and glyphosate formulations.
- Paints:Substrate wetting and defoaming dual-function demands drive organomodified siloxane specification in automotive and industrial coating lines. Chinese and German coatings manufacturers are integrating digital formulation tools to compress development cycles for waterborne resin systems.
- Coatings:Slip resistance and leveling control requirements concentrate demand in protective and marine applications.
- Textile:Dyehouse auxiliaries require rapid wetting on synthetic fiber blends with minimum foam generation.
Agriculture commands the largest formulation volume; paints applications are climbing the fastest as waterborne technology penetrates industrial coating segments.
End User:
End-user selection reflects regulatory burden distribution, with food-grade and pharmaceutical specifications imposing the most stringent purity and documentation requirements.
- Construction:Cement admixture formulators in the UAE and Saudi Arabia specify wetting agents for self-compacting concrete where flow retention demands precise air entrainment control. Compatibility with polycarboxylate superplasticizers determines procurement decisions in Gulf Cooperation Council infrastructure projects.
- Personal Care:Natural-derived surfactant demand from European and North American brand owners is repositioning supplier portfolios toward alkyl polyglucoside and glucamide chemistries. FSSAI and FDA 21 CFR 173 compliance pathways for emulsifier-wetting agent dual-function products open processing aid applications.
- Food & Beverage:Food-grade specifications require migration testing and toxicological dossiers that extend registration timelines.
- Pharmaceuticals:USP and EP compliance for excipient-grade wetting agents limits supplier qualification to established pharmaceutical chemical manufacturers.
Construction absorbs the bulk of industrial wetting agent volume; personal care is gaining share fastest as clean-label positioning penetrates mass-market formulations.
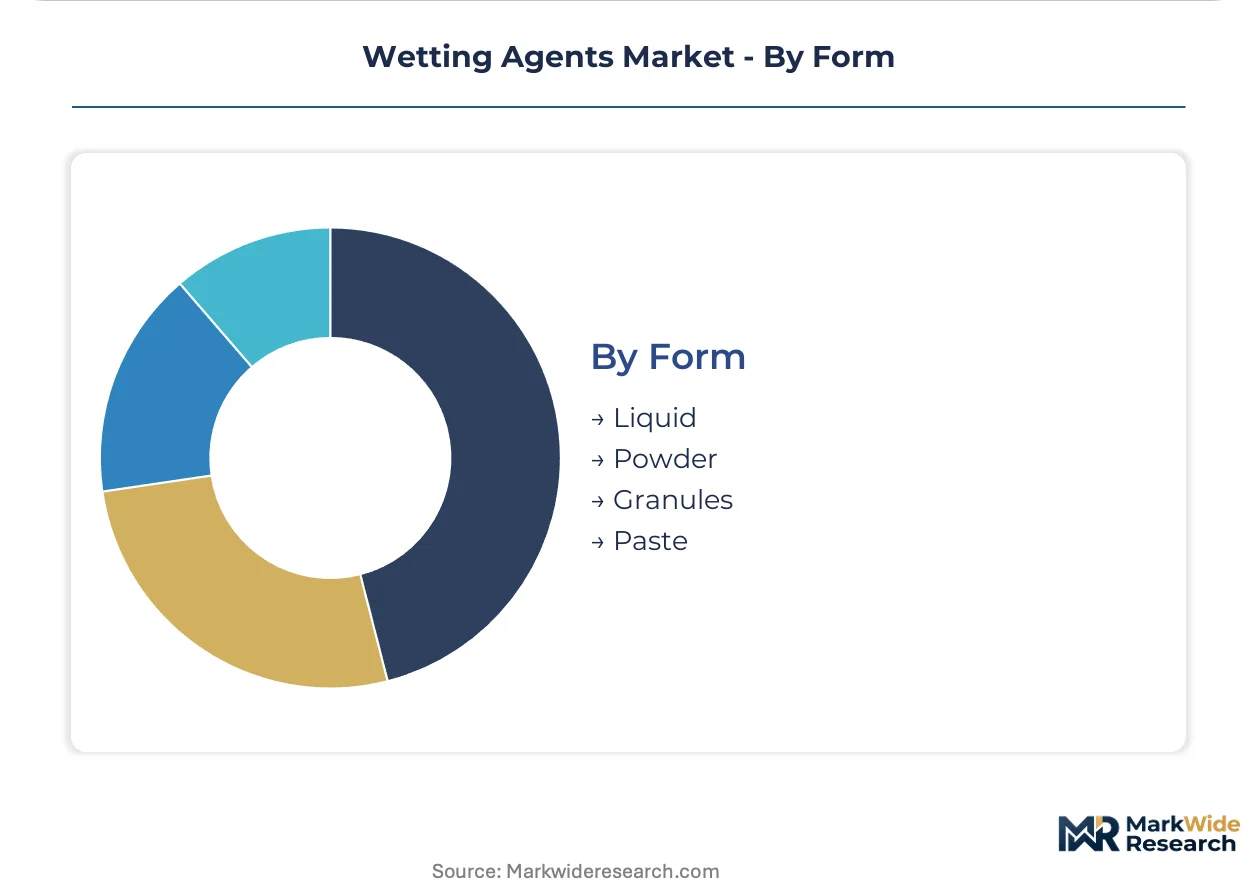
Form:
Physical state selection balances transport economics, storage stability, and dissolution kinetics, with dry formulations offering logistics advantages in distributed agricultural markets.
- Liquid:Ready-to-use concentrates dominate construction and textile processing where metered addition and rapid dispersion are critical. Continuous production lines in China's Yangtze River Delta manufacturing clusters favor liquid delivery for cement admixture and dyehouse auxiliary applications.
- Powder:Spray-dried and agglomerated grades concentrate in dry agrochemical formulations where Southeast Asian contract manufacturers seek transport cost advantages over liquid concentrates. Storage stability in tropical humidity conditions determines specification compliance.
- Granules:Controlled-release architectures serve specialty agricultural applications requiring delayed wetting activation.
- Paste:High-active-content semisolids address niche personal care and pharmaceutical formulation requirements.
Liquid forms hold the majority of production capacity; powder grades are expanding most quickly as dry formulation packaging localizes in regional agricultural markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of nonionic surfactant intermediates, yet Brazil and India absorb the fastest-growing agricultural adjuvant volumes. This production-consumption divide shapes procurement strategies across wetting agent supply chains.
China
Yangtze River Delta clusters in Jiangsu and Zhejiang provinces synthesize ethoxylated fatty alcohols for export markets. MEE discharge standards enforce biodegradable surfactant migration across domestic production. Ningbo and Shanghai port infrastructure enables liquid concentrate exports to Southeast Asian contract manufacturers.
United States
Texas Gulf Coast ethylene oxide capacity feeds nonionic surfactant production for agricultural tank-mix applications. EPA FIFRA registration requirements under Section 3 govern drift reduction properties for drone spray systems. Houston and Baton Rouge petrochemical corridors anchor North American supply security despite hurricane season volatility.
Brazil
Cerrado precision farming expansion specifies wetting agents with validated glyphosate compatibility for variable-rate sprayers. ANVISA agrochemical registration timelines compress formulation development windows. São Paulo state distributors coordinate technical service directly with multinational crop protection companies.
Germany
REACH authorization requirements eliminate nonylphenol ethoxylates from textile processing auxiliaries. EU Green Deal chemicals strategy restricts persistent surfactant architectures across Rhine-Ruhr manufacturing basins. BASF SE leverages Ludwigshafen integration to supply crop science divisions across European agrarian belts.
India
Punjab and Haryana agricultural mechanization drives tank-mix adjuvant procurement for drone application systems. FSSAI food-grade surfactant specifications open processing aid applications for emulsifier-wetting agent dual-function products. Gujarat chemical corridors concentrate alkyl polyglucoside synthesis for domestic agrochemical formulators.
Wetting Agents Market Vendor Landscape
Top-tier vendors anchor integrated petrochemical-surfactant platforms, while mid-tier specialists occupy niche formulation segments. The vendor base stratifies across three tiers: multinational chemical conglomerates with crop science divisions, regional surfactant houses serving single industries, and contract manufacturers producing private-label grades. Two strategic archetypes dominate: backward-integrated feedstock controllers and formulation-technology licensors. Capacity expansion in China's Yangtze Delta and strategic partnerships between agrochemical multinationals and surfactant producers represent the primary competitive vectors.
Among European-headquartered conglomerates, BASF SE, Evonik Industries AG, and Croda International Plc exemplify contrasting archetypes. BASF SE occupies a position spanning petrochemical feedstocks through agricultural end-use applications. Evonik Industries AG represents specialty siloxane chemistry expertise for coatings specifications. Croda International Plc exemplifies natural-derived surfactant positioning for personal care and food-grade compliance pathways.
| Leading Market Players |
|---|
| Clariant AG |
| AkzoNobel N.V. |
| BASF SE |
| BYK-Chemie GmbH |
| Arkema SA |
| The Dow Chemical Company |
| Croda International Plc |
| Ashland Inc. |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Ethylene oxide spot pricing on the US Gulf Coast cascades through nonionic surfactant production economics, stratifying wetting agent procurement across premium organosilicone grades, standard alcohol ethoxylate tiers, and economy sulfate formulations. Formulators in agricultural and coatings sectors absorb these feedstock oscillations through contract structures that vary by volume commitment and technical service bundling.
Pricing Analysis
Margin tightening in standard-grade anionic tiers reflects ethylene oxide volatility from Texas and Rotterdam supply clusters. Three-tier pricing structure across premium organosilicone, standard alcohol ethoxylate, and economy sulfate specifications differentiates by certification grade and volume scale. Pricing pressure stems from REACH-driven reformulation costs that compress development timelines. Agricultural tank-mix buyers exhibit highest price sensitivity; pharmaceutical excipient purchasers tolerate premium positioning for USP compliance.
Supply Chain Analysis
Specialized chemical engineering talent scarcity in Jiangsu and Zhejiang provinces constrains organosilicone modification capacity expansion. Supply concentrates in China for ethoxylated intermediates, the United States for agricultural adjuvant formulation, and Germany for REACH-compliant specialty grades. Feedstock dependencies span ethylene oxide, fatty alcohols, and siloxane precursors. Single-source vulnerability concentrates around Texas Gulf Coast ethylene oxide crackers. Distribution runs through direct procurement relationships between agrochemical multinationals and Yangtze Delta manufacturers, displacing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH authorization requirements for substances of very high concern erect barrier-to-entry moats favoring dossier-capable incumbents with established regulatory affairs infrastructure.
For Market Incumbents: Anchor supply security through backward integration into ethoxylated fatty alcohol production in Yangtze River Delta clusters. Expand organosilicone modification capacity to capture coatings specification demand as fluorosurfactant alternatives face EPA TSCA Section 6 elimination. Defend against mid-tier contract manufacturers by embedding technical service teams directly with Brazilian and Indian precision farming operators. For New Entrants and Emerging Players: Begin with powder-grade wetting agent production for Southeast Asian dry agrochemical formulation packagers, where transport cost advantages over liquid concentrates create white-space opportunity. Target FSSAI-compliant food-grade surfactant specifications in India, where dual-function emulsifier-wetting agent demand outpaces qualified supplier availability. Pursue toll manufacturing arrangements with established Gujarat chemical corridor producers to bypass capital-intensive synthesis scale-up barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European surfactant houses with REACH-compliant portfolios but strained balance sheets from consecutive reformulation cycles. Long-term viability hinges on positioning for biodegradable architecture substitution as EU Green Deal restrictions tighten. Monitor OECD 301B biodegradability testing completion rates as inflection indicator for new product pipeline velocity and regulatory approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethoxylated Intermediates | Captive supply of fatty alcohol ethoxylates insulates margin from Texas Gulf Coast ethylene oxide volatility. |
| REACH-Compliant Portfolio Expansion | Authorization-ready dossiers for alcohol ethoxylate architectures secure textile processing contracts as nonylphenol ethoxylates phase out. |
| Direct Procurement Relationship Development | Technical service embedding with Syngenta and BASF field teams displaces distributor intermediaries in Asia-Pacific corridors. |
| Biodegradability Certification Investment | OECD 301B and 306 protocol completion accelerates registration timelines in jurisdictions with mandatory environmental fate data. |
| Powder Grade Capacity Addition | Spray-dried production for Southeast Asian contract manufacturers captures transport cost advantages in tropical humidity conditions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving agricultural adjuvant formulators, coatings R&D directors, textile processing procurement leads, and surfactant plant managers. Bottom-up volume estimates from ethoxylated fatty alcohol production statistics and top-down demand validation from crop protection company procurement disclosures were reconciled through iterative triangulation.
Data-stream reconciliation across supply-side capacity assessments and demand-side formulation specifications generated segment-level projections. Modeled dimensions span ionic character, physical state, end-use industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted consumption trajectories incorporating precision farming penetration rates and waterborne coatings technology shifts.
Underlying measurement precision varies by segment; agricultural adjuvant volumes carry tighter precision than pharmaceutical excipient specifications due to disclosure granularity differences. Forecasts reflect assumptions on REACH authorization timelines and EPA FIFRA registration velocities. Material deviation in ethylene oxide supply disruptions or OECD testing protocol revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Sodium Cumenesulfonate Market
Surfactants
Secondary Alkane Sulfonate Market
Surfactants
Micellar Water Market
Surfactants
Procream Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Green Surfactants Market
Surfactants
Soy-Based Surfactants Market
Surfactants
Non-Ionic Surfactants Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Alkyl Polyglycoside (APG) Market
Surfactants
Cetanol Market
Surfactants
Sulfosuccinate Market
Surfactants
Cocomonoethanolamide (CMEA) Market
Surfactants
Natural Surfactants Market
Surfactants
Lauramide DEA Market