
 Europe OOH and DOOH Market | 2026-2036
Europe OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Europe OOH and DOOH Market Insights
Digital signage engineering talent is reorganizing how European media owners scale programmatic inventory. JCDecaux Group leverages its street furniture concessions across Paris and London to dominate premium urban inventory. Ströer SE & Co. KGaA anchors Germany's transit advertising ecosystem through exclusive railway and metro contracts. Clear Channel Outdoor Holdings Inc. competes on airport and roadside scale, while Ocean Outdoor Ltd specializes in landmark digital screens that command premium brand budgets.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display surfaces deployed in public spaces, ranging from static paper posters to networked LED arrays with real-time content management and audience measurement capabilities. These installations serve commercial messaging functions across transit hubs, retail environments, and thoroughfares where consumer foot traffic aggregates. Digital screens within the format dimension now capture disproportionate investment flows as programmatic trading and dynamic creative optimization migrate from online channels. Transit advertising retains structural importance in the end user dimension because rail and bus networks deliver captive, demographically profiled audiences that retailers and agencies prize for location-based campaigns.
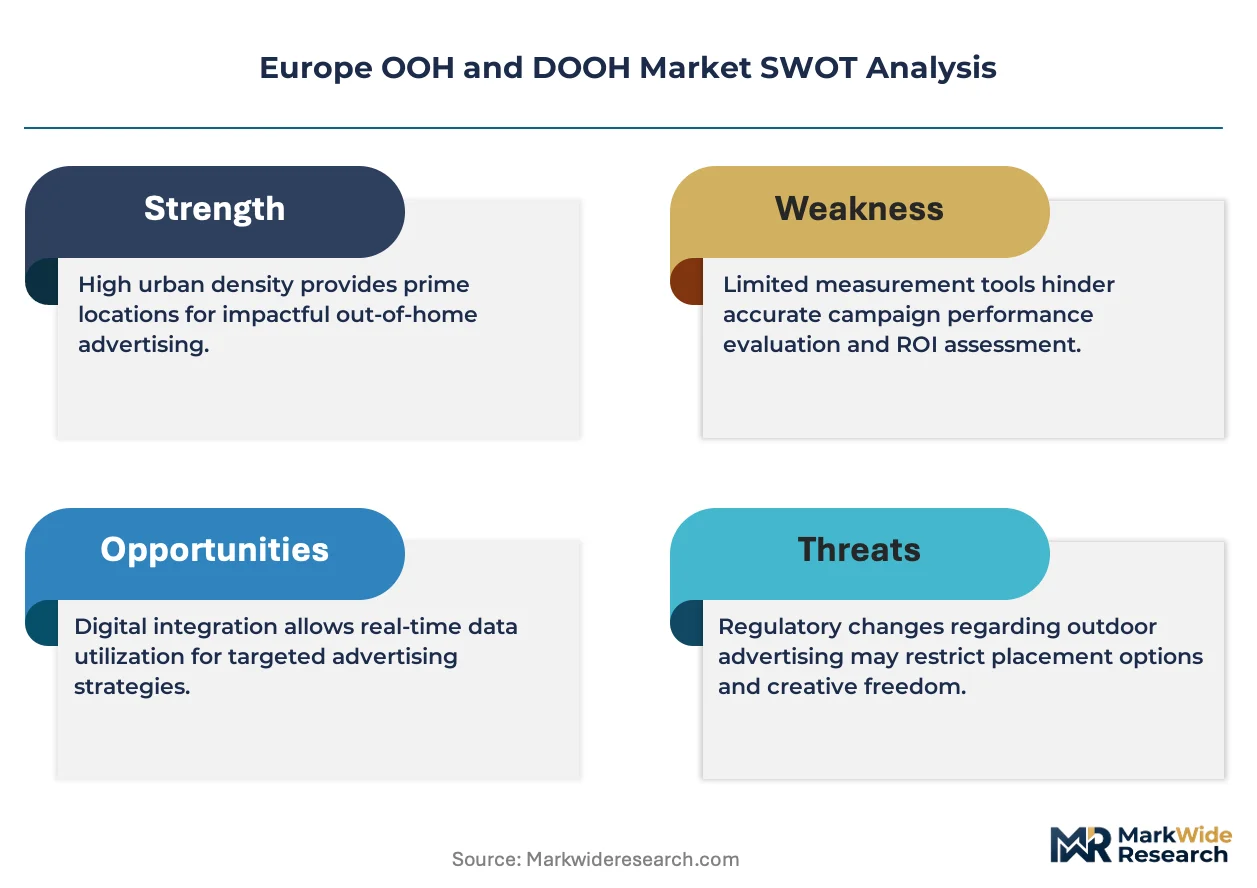
The EU Green Deal and F-Gas Regulation constrain display hardware energy profiles and refrigerant-based cooling systems, while GDPR shapes how audience measurement technologies collect and process viewer data. EASA guidelines on drone and aerial advertising create compliance thresholds for emerging format innovations. Stakeholders must weigh capital allocation between retrofitting analog assets and deploying net-new connected infrastructure as regulatory compliance costs escalate.
Market Dynamics
Programmatic trading infrastructure is decomposing legacy insertion-order workflows across European media owners, forcing capital reallocation toward real-time bidding platforms and audience measurement stacks.
Growth Catalysts
- EU Green Deal digital infrastructure mandates:Energy efficiency requirements for public displays are accelerating LED retrofit cycles across municipal street furniture networks in France and Germany.
- Transit corridor retail targeting:Commuter rail and metro systems in London, Paris, and Berlin deliver captive audiences that fast-moving consumer goods brands prioritize for location-based campaigns.
- Dynamic creative optimization:Real-time content adaptation based on weather, traffic, and audience density is compressing production-to-flight timelines for seasonal advertisers.
Market Restraints
- F-Gas Regulation cooling constraints:Phasedown of hydrofluorocarbon refrigerants limits thermal management options for high-brightness outdoor LED installations in southern European climates.
- GDPR audience measurement friction:Restrictions on biometric data collection constrain camera-based impression verification and demographic profiling technologies.
- Copper and rare earth supply concentration:Dependence on Chinese-processed neodymium and dysprosium for display driver components creates input cost volatility for screen manufacturers.
Strategic Opportunities
- Poland and Romania smart city underpenetration:Eastern European municipalities lag western capitals in connected infrastructure deployment, creating first-mover expansion corridors for digital screen networks.
- Drone and aerial advertising formats:EASA guidelines on unmanned aircraft systems are formalizing compliance pathways for swarm-based aerial display advertising above stadiums and festivals.
- Retail media network convergence:Integration of in-store digital signage with e-commerce data layers enables closed-loop attribution that pure-play outdoor networks cannot replicate.
Industry Challenges
- Programmatic talent scarcity:European media owners compete with ad-tech platforms and financial services for software engineers skilled in real-time bidding architecture and supply-path optimization.
- Legacy analog asset stranding:Municipal concession contracts with static poster minimums constrain rapid digital conversion without renegotiation or penalty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe OOH and DOOH Market |
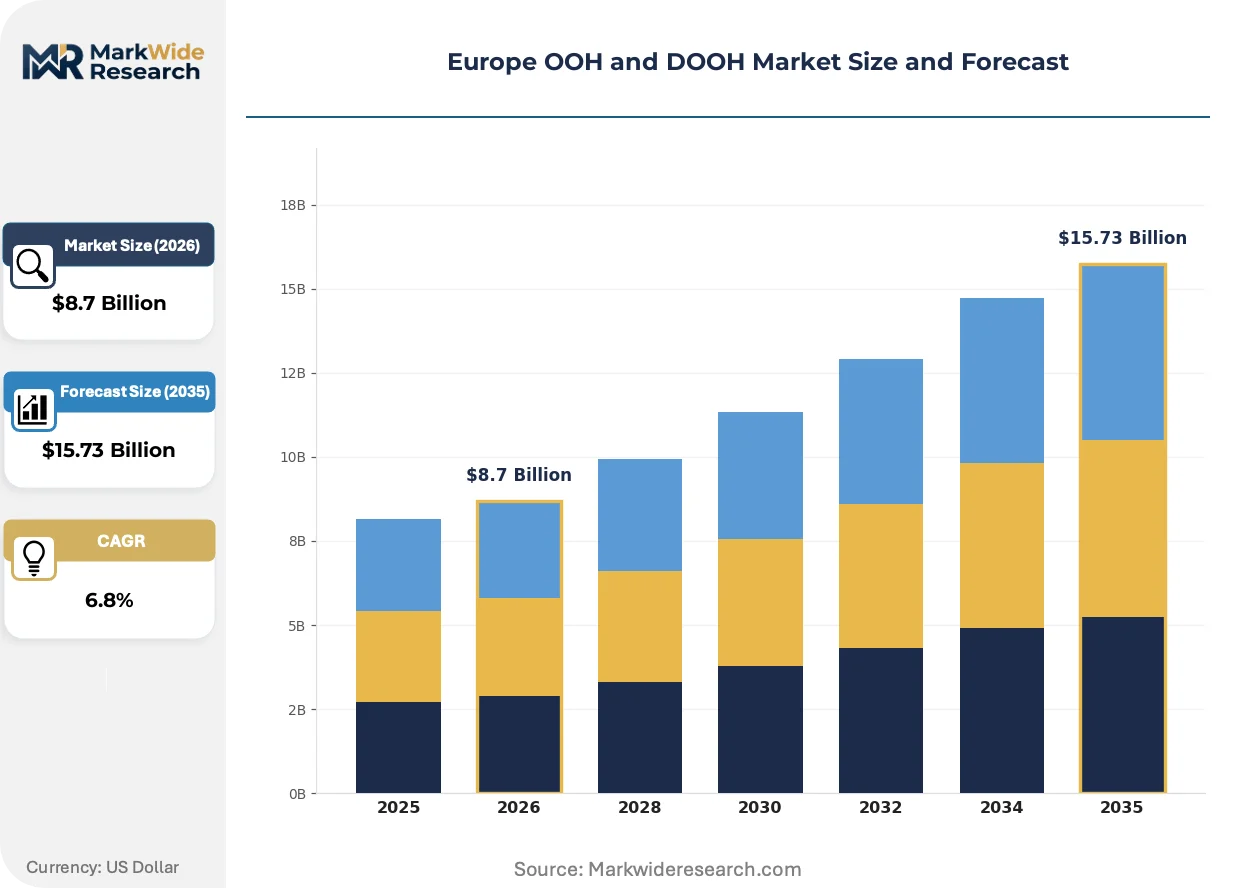
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Format: Billboards, Digital Screens, Posters, Transit Advertising End User: Retailers, Advertisers, Agencies, Brands Technology: LED, LCD, Projection, Analog Distribution Channel: Direct, Programmatic, Resellers, Media Owners |
| Companies Covered | JCDecaux Group, Ströer SE & Co. KGaA, Clear Channel Outdoor Holdings Inc., Ocean Outdoor Ltd, Exterion Media, APG|SGA, Goldbach Group AG, Talon Outdoor Ltd, OUTFRONT Media Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe OOH and DOOH Market Trends and Innovations
Edge computing and 5G connectivity are compressing latency between content management systems and roadside displays, enabling millisecond-responsive creative triggers that static infrastructure cannot match.
Computer vision and anonymized mobile signal fusion is decomposing traditional demographic panel-based audience measurement. JCDecaux and Ströer are deploying camera-and-sensor arrays across Paris and Berlin transit nodes. Real-time impression verification now replaces legacy traffic-count extrapolation, compressing media buyer uncertainty and enabling outcome-based pricing structures.
CSRD disclosure requirements are mandating granular Scope 2 and Scope 3 emissions reporting for outdoor advertising assets. The EU Green Deal's delegated acts specify display energy intensity thresholds that disqualify non-compliant hardware from public procurement. German municipalities in Bavaria and North Rhine-Westphalia are embedding these standards into renewed street furniture concession tenders.
Retailers are consolidating media planning authority into centralized procurement functions that span e-commerce, in-store, and out-of-home channels. Unilever and L'Oréal are dissolving siloed outdoor buying teams into integrated media operations. This concentration is visible most acutely in the United Kingdom, where agency holding groups face margin compression as direct advertiser-platform relationships proliferate.
Europe OOH and DOOH Market Segmentation
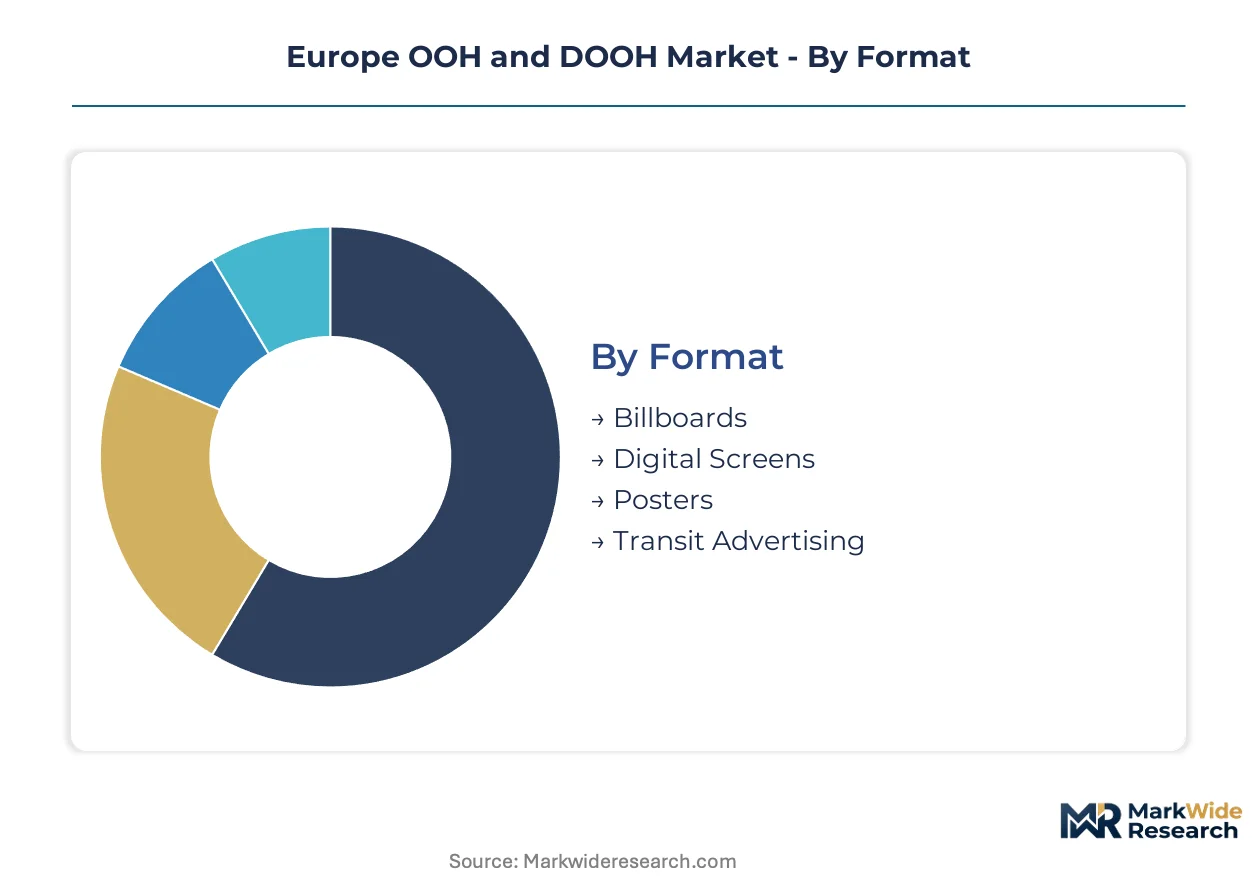
European media owners allocate capital across format, technology, and channel dimensions based on concession contract structures and programmatic trading maturity. Understanding where margin pools concentrate within each category reveals which segments command premium pricing and which face commoditization pressure.
Format:
Margin pools concentrate in inventory with exclusive municipal concessions and real-time content adaptability.
- Billboards:Large-format roadside and highway displays dominate suburban arterial corridors. German autobahn networks and French périphérique circuits generate recurring revenue from automotive and beverage advertisers seeking mass reach.
- Digital Screens:Networked LED arrays with programmatic trading capability capture disproportionate investment flows. London's West End and Berlin's Alexanderplatz clusters command premium CPMs through dynamic creative optimization tied to weather and traffic triggers.
- Posters:Static paper displays on street furniture and transit shelters retain utility in secondary markets. French municipal contracts still mandate minimum poster volumes alongside digital upgrades.
- Transit Advertising:Rail, metro, and bus interior and exterior surfaces deliver captive commuter audiences. Paris Métro and London Underground networks attract FMCG brands targeting daily ridership demographics.
Billboards hold installed capacity. Digital Screens is rotating up the share rankings.
End User:
Customer sophistication varies by procurement centralization and closed-loop attribution requirements.
- Retailers:Grocery chains and fashion brands deploy location-based campaigns near point-of-sale. Tesco and Carrefour consolidate OOH planning with in-store retail media networks for unified measurement.
- Advertisers:Direct brand procurement functions bypass traditional agency markups. Unilever and L'Oréal operate integrated media operations spanning e-commerce, in-store, and outdoor channels.
- Agencies:Holding groups face margin compression as advertiser-platform relationships proliferate. UK-based media buyers increasingly demand outcome-based pricing structures.
- Brands:Luxury and automotive advertisers prioritize landmark inventory for brand-building objectives. Premium digital screens in Milan's Piazza del Duomo and Madrid's Gran Vía attract concentrated luxury spend.
Agencies retain transaction volume. Advertisers is rotating up the share rankings.
Technology:
Display hardware selection hinges on EU Green Deal energy thresholds and thermal management constraints.
- LED:High-brightness diode arrays dominate new outdoor installations. Bavarian and North Rhine-Westphalian municipalities embed energy intensity standards into street furniture tenders that disqualify non-compliant hardware.
- LCD:Liquid crystal displays retain presence in indoor transit and retail environments. Lower brightness requirements suit controlled lighting conditions in Paris RER stations and Berlin S-Bahn corridors.
- Projection:Temporary and architectural mapping applications serve event-based campaigns. Festival and stadium activations in Barcelona and Amsterdam utilize projection for non-permanent installations.
- Analog:Static printed substrates persist where digital retrofit costs exceed concession renewal timelines. Eastern European markets maintain analog share due to infrastructure investment lags.
Analog holds installed capacity. LED is climbing the fastest.
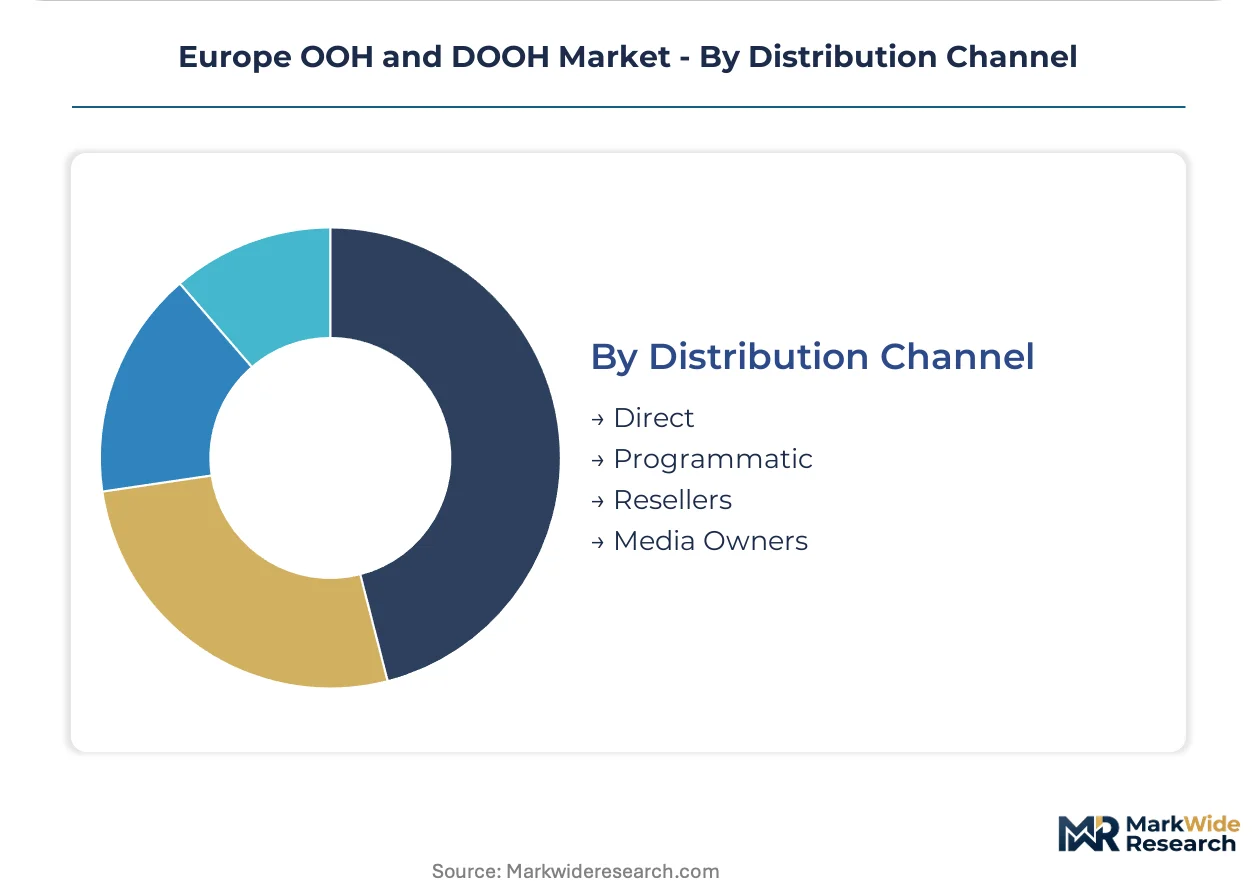
Distribution Channel:
Trading infrastructure investment separates automated inventory from insertion-order workflows.
- Direct:Advertiser-to-media-owner relationships eliminate intermediary fees. Large brands negotiate multi-year commitments for exclusive landmark access in London and Paris.
- Programmatic:Real-time bidding platforms enable audience-based buying across fragmented inventory. JCDecaux and Ströer deploy unified supply-side platforms to aggregate transit and street furniture impressions.
- Resellers:Independent brokers aggregate non-exclusive inventory for smaller advertisers. Regional specialists in Poland and Romania consolidate emerging market supply.
- Media Owners:Vertically integrated operators control inventory and sales functions. Concession-based business models in France and Germany favor owner-operated sales teams.
Direct holds transaction value. Programmatic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates transit advertising investment while France prioritizes street furniture digitization, and the United Kingdom leads programmatic trading infrastructure deployment across European markets.
Germany
Railway and metro networks in Berlin, Munich, and Hamburg drive captive-audience inventory demand from FMCG brands. The EU Green Deal's energy efficiency mandates are accelerating LED retrofit cycles across Bavarian and North Rhine-Westphalian municipal street furniture tenders. Ströer SE & Co. KGaA anchors the transit advertising ecosystem through exclusive Deutsche Bahn and regional metro contracts.
France
Paris Métro and RER corridors attract premium location-based campaigns from luxury and beverage advertisers. CSRD disclosure requirements are mandating granular Scope 2 emissions reporting for outdoor advertising assets across Île-de-France municipalities. JCDecaux Group leverages exclusive street furniture concessions across Paris, Lyon, and Marseille to dominate premium urban inventory.
United Kingdom
London Underground and national rail networks deliver demographically profiled commuter audiences for retail media convergence strategies. GDPR constraints on biometric data collection are reshaping camera-based impression verification technologies deployed by media owners. Ocean Outdoor Ltd specializes in landmark digital screens across London's West End and Birmingham city center that command premium brand budgets.
Italy
Milan's fashion and luxury retail corridor drives demand for high-visibility digital displays in Piazza del Duomo and Corso Buenos Aires. REACH compliance requirements are influencing display hardware material specifications for outdoor LED installations across Lombardy and Veneto. Digital screen networks are expanding through public-private partnerships in Rome and Turin transit hubs.
Poland
Warsaw and Kraków smart city investments are creating first-mover expansion corridors for connected digital infrastructure. F-Gas Regulation phasedown constraints are limiting thermal management options for high-brightness displays in southern European climate conditions. Municipalities lag western capitals in programmatic trading infrastructure, attracting regional specialist consolidation.
Europe OOH and DOOH Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European OOH and DOOH markets. JCDecaux Group, Ströer SE & Co. KGaA, and Clear Channel Outdoor Holdings Inc. dominate through exclusive municipal concessions and transit contracts that create structural barriers to entry. Specialist operators compete on format innovation and landmark inventory access. Competitive dynamics center on concession renewal negotiations and programmatic platform integration rather than price-based rivalry.
Within the integrated leader tier, JCDecaux Group and Ströer SE & Co. KGaA exemplify contrasting geographic anchoring strategies. JCDecaux represents the street furniture and airport concession archetype with deep Paris-rooted infrastructure. Ströer occupies a position as Germany's transit-focused operator with railway and metro exclusivity. Clear Channel Outdoor Holdings Inc. sits within the multi-format scale archetype spanning roadside, airport, and transit inventory across multiple European jurisdictions.
| Leading Market Players |
|---|
| JCDecaux Group |
| Ströer SE & Co. KGaA |
| Clear Channel Outdoor Holdings Inc. |
| Ocean Outdoor Ltd |
| Exterion Media |
| APG|SGA |
| Goldbach Group AG |
| Talon Outdoor Ltd |
| OUTFRONT Media Inc. |
| Others |
Pricing and Supply Chain Analysis
LED diode substitution for legacy LCD backlighting is redistributing manufacturing gravity toward Chinese-processed rare earth supply chains while compressing display hardware pricing premiums across European procurement cycles.
Pricing Analysis
Long-term municipal concession contracts anchor pricing structures across European OOH markets, with exclusive transit and street furniture agreements spanning 10-15 year tenures. Three-tier pricing stratifies across premium landmark digital inventory in London and Paris, standard programmatic-enabled urban screens, and economy-grade static posters retained in secondary markets. Cost compression in economy tiers is intensifying because Eastern European municipalities delay digital retrofit investments. Retail media buyers exhibit highest price sensitivity as they benchmark outdoor CPMs against closed-loop e-commerce attribution, while luxury brands remain least sensitive, prioritizing exclusivity over rate efficiency.
Supply Chain Analysis
Inventory lead times for high-brightness LED modules now stretch 16-24 weeks as semiconductor foundries prioritize automotive and consumer electronics allocations. Display hardware manufacturing concentrates in China, Taiwan, and South Korea, with European assembly limited to final integration and calibration stages. Rare earth magnet dependencies for driver components draw from Chinese-processed neodymium and dysprosium supply chains. Single-source vulnerability in advanced LED chip fabrication creates procurement risk for European media owners scaling programmatic networks. Distribution runs through vertically integrated media owner procurement functions and specialized AV systems integrators serving municipal concession holders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European OOH incumbents face substitution defense against retail media networks and connected TV platforms that capture brand budgets through superior attribution granularity. Survival hinges on concession renewal velocity and programmatic infrastructure deployment.
For Market Incumbents: Fortify exclusive municipal contract positions through accelerated LED retrofit commitments that satisfy EU Green Deal energy thresholds ahead of competitor bids. Deepen backward integration into audience measurement technology stacks to replicate retail media closed-loop capabilities. Threat substitution from Amazon and Tesco retail media networks demands defensive concession renegotiation before 2027 renewal cycles concentrate. For New Entrants and Emerging Players: Anchor in Poland and Romania smart city infrastructure gaps where Western European concession incumbents maintain limited presence. Target Warsaw and Kraków municipal digital screen tenders as first-mover expansion corridors. Go-to-market execution should emphasize programmatic platform partnerships that leapfrog legacy insertion-order workflows entrenched in established markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists in Eastern European markets that lack scale for standalone exit. Long-term viability across the projection horizon depends on concession contract duration and programmatic trading infrastructure maturity. Acquisition target archetype: transit-focused operators with exclusive railway contracts in Tier-2 German or French cities. Signal to watch: municipal tender language embedding CSRD emissions disclosure requirements that disadvantage undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Contract Renewal | Exclusive Paris and Berlin transit agreements lock out competitors for decade-long tenures. |
| Programmatic Platform Integration | Real-time bidding infrastructure enables JCDecaux and Ströer to aggregate fragmented inventory. |
| LED Retrofit Acceleration | Bavarian municipal tenders disqualify non-compliant hardware, favoring early movers. |
| Audience Measurement Stack Investment | Camera-and-sensor arrays replace traffic-count extrapolation with verified impression data. |
| Retail Media Network Convergence | Tesco and Carrefour integration of in-store and outdoor channels threatens pure-play OOH margins. |
Research Methodology
A standing panel of media owner procurement directors, municipal concession managers, programmatic platform engineers, and brand media planners provided ongoing calibration across primary fieldwork. Secondary validation drew from JCDecaux and Ströer annual reports, EASA regulatory filings, EU Green Deal delegated acts, and municipal tender databases. Bottom-up unit economics for display hardware and concession operating costs were triangulated against top-down market sizing from media spend trackers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning format type, technology tier, end-user procurement centralization, and distribution channel automation. CAGRs were derived from installed base expansion curves and replacement cycle assumptions. Industry-specific forecast inputs included EU Green Deal compliance timelines and GDPR audience measurement technology deployment rates.
Material uncertainties — municipal budget austerity, F-Gas Regulation thermal management constraints, and rare earth supply disruption — sit outside the modeled envelope. Forecasts reflect documented assumptions about concession renewal success rates and programmatic trading adoption velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
Programmatic Advertising Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
Magazine Advertising Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Teleshopping Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
Chile OOH and DOOH Market