
 Germany OOH and DOOH Market | 2026-2036
Germany OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Germany OOH and DOOH Market Insights
Modular campaign bundling is decoupling from long-term fixed-site contracts, letting buyers mix static billboards with programmatic digital slots across shorter windows. Ströer SE & Co. KGaA leverages its nationwide street furniture network to anchor urban coverage in Berlin and Hamburg. JCDecaux SA dominates transit advertising through exclusive concessions with Deutsche Bahn and municipal transport authorities. Clear Channel Outdoor Deutschland specializes in roadside billboards along the Autobahn corridor, sustaining reach into automotive-heavy regions.
Germany OOH and DOOH encompasses physical and digital advertising surfaces deployed in public spaces, including LED and LCD screens with brightness ratings exceeding 5,000 nits for daylight visibility, designed to deliver brand messages to mobile audiences in transit corridors and commercial zones. Digital screens within the media type category are capturing the fastest expansion as advertisers shift spend from static formats to programmatically traded inventory with real-time audience measurement. The ad format dimension shows interactive and 3D executions building premium margin pools in entertainment and retail customer segments, while static placements retain volume leadership in automotive roadside campaigns.
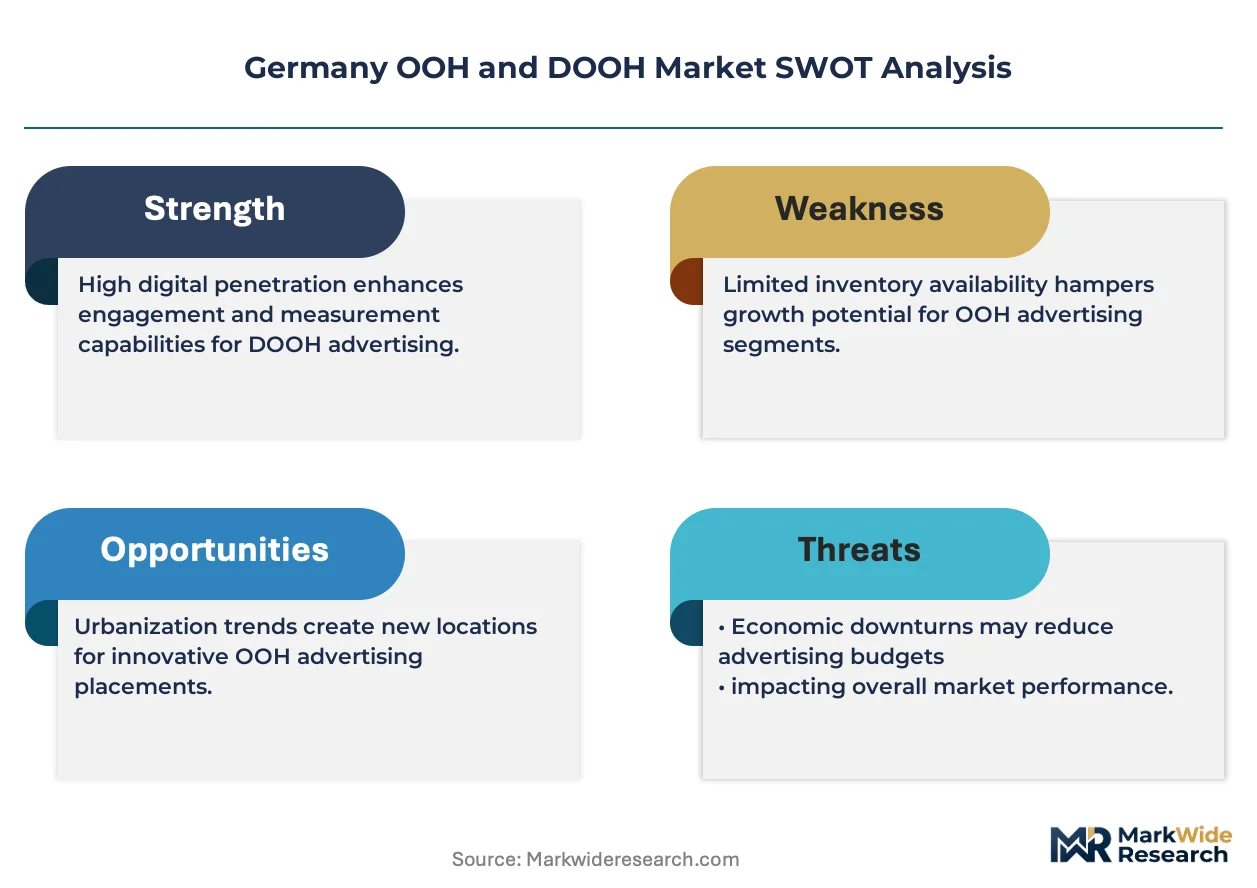
The KBA coordinates with municipal authorities to enforce placement clearances that prevent driver distraction, while the EU Green Deal and national efficiency standards pressure operators toward LED retrofits and lower-energy display technologies. Germany's advertising self-regulation through the Deutscher Werberat adds content-layer compliance costs for brands targeting family audiences. Stakeholders must weigh capital intensity against the shift to data-driven audience targeting as inventory digitizes.
Market Dynamics
The transition from fixed-site contracts to programmatic trading is compressing booking windows and fragmenting buyer relationships across Germany's urban inventory pools.
Growth Catalysts
- EU Green Deal efficiency mandates:The national LED retrofit push is accelerating screen replacements, unlocking energy savings that operators reinvest into expanded digital networks.
- Automotive programmatic demand:German OEMs are redirecting media budgets toward real-time audience targeting on digital roadside inventory, pulling spend from static formats.
- Transit authority concessions:Exclusive agreements with Deutsche Bahn and municipal operators in Berlin and Hamburg are securing captive audience access in high-dwell environments.
Market Restraints
- KBA placement clearance requirements:The federal motor transport authority's strict roadside safety standards limit inventory density along Autobahn corridors, constraining premium supply expansion.
- Capital intensity of LED retrofits:Display hardware with 5,000+ nit daylight visibility commands substantial upfront investment, squeezing mid-tier operators' balance sheets.
- Self-regulatory compliance costs:Deutscher Werberat content review processes add timeline friction for campaigns targeting family demographics, particularly in retail and entertainment verticals.
Strategic Opportunities
- Interactive 3D execution formats:Premium-margin creative technologies are penetrating entertainment and retail segments where dwell time exceeds transit averages.
- Municipal street furniture digitization:City-owned bus shelters and kiosks present untapped inventory for public-private partnership models in secondary urban centers.
- Data-driven audience measurement:Integration of mobile location analytics with screen networks is enabling impression-level verification that static formats cannot match.
Industry Challenges
- Programmatic talent scarcity:The shortage of traders fluent in both outdoor inventory mechanics and real-time bidding platforms is throttling campaign execution speed.
- Legacy contract fragmentation:Long-term fixed-site agreements with municipal landlords complicate the pivot to shorter, flexible booking windows demanded by digital buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany OOH and DOOH Market |
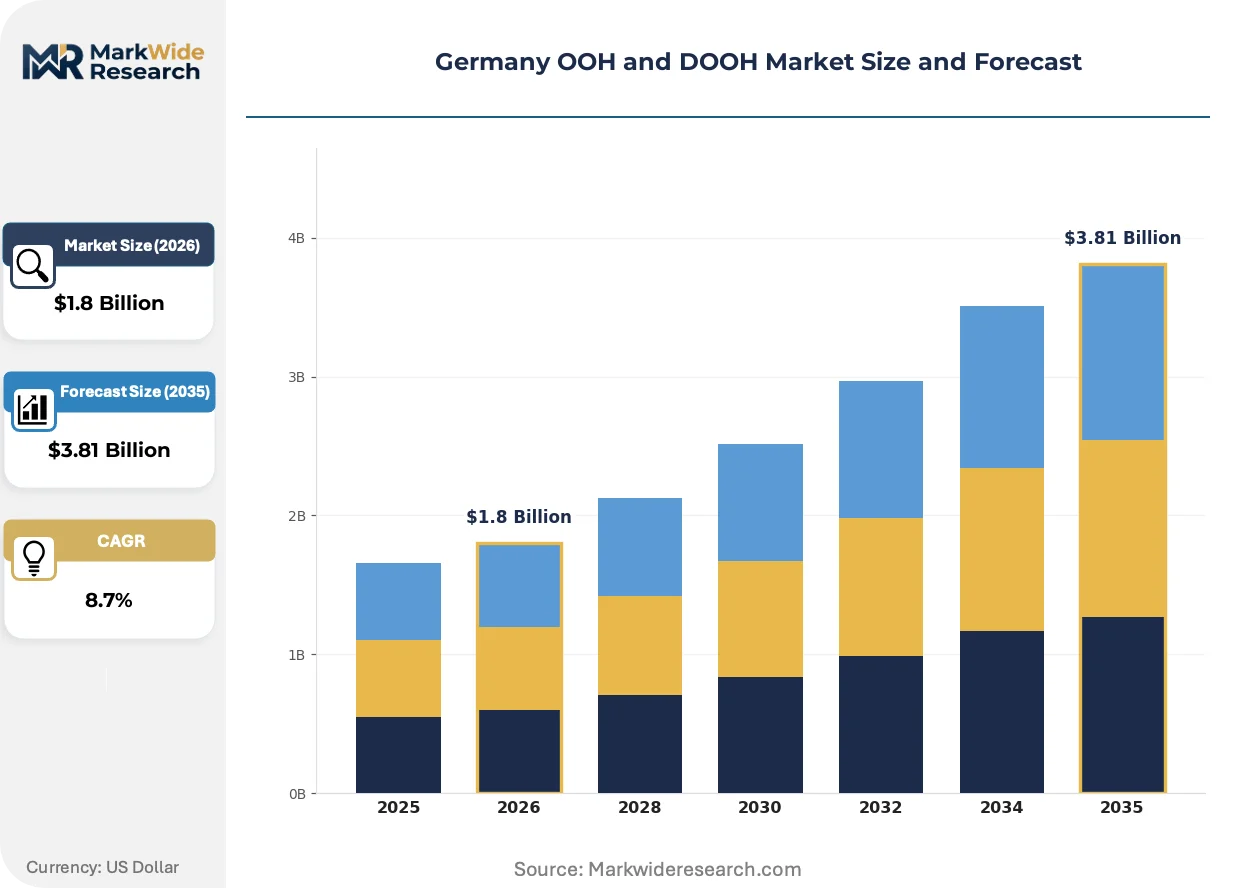
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Billboard, Transit Advertising, Street Furniture, Digital Screens Customer Segment: Retail, Automotive, Entertainment, Telecommunications Ad Format: Static, Digital, Interactive, 3D Technology: LED, LCD, Projection, AR |
| Companies Covered | Ströer SE & Co. KGaA, JCDecaux SA, Clear Channel Outdoor Deutschland, blowUP media GmbH, Goldbach Group AG, Media Frankfurt GmbH, WallDecaux, PosterSelect GmbH, VisionOne GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany OOH and DOOH Market Trends and Innovations
Programmatic infrastructure is rewriting how inventory is priced, traded, and measured across German urban advertising networks.
Dynamic creative optimization is rewriting campaign execution by enabling real-time content adaptation based on weather, traffic, and audience density signals. Automotive advertisers in Stuttgart and Munich are deploying this capability at scale, compressing production-to-flight timelines from weeks to hours. The technology is rewriting margin structures by reducing creative versioning costs while lifting engagement rates in high-velocity roadside environments.
The EU Green Deal's national implementation is mandating LED retrofits across municipal-owned inventory, forcing operators to accelerate hardware refresh cycles. Energy efficiency standards are reshaping procurement specifications, with brightness-per-watt ratios now central to technical evaluations. Transit advertising networks in Hamburg are responding fastest, embedding solar-assisted power systems into shelter-based digital screens.
Buyers are unbundling long-term site commitments in favor of flighted, audience-agnostic campaigns traded through demand-side platforms. This behavior is disrupting the traditional direct-sales channel between operators and brand marketers, with media agencies capturing intermediary value. The shift is most visible in Berlin, where quarterly booking windows now dominate annual contract negotiations for premium digital inventory.
Germany OOH and DOOH Market Segmentation
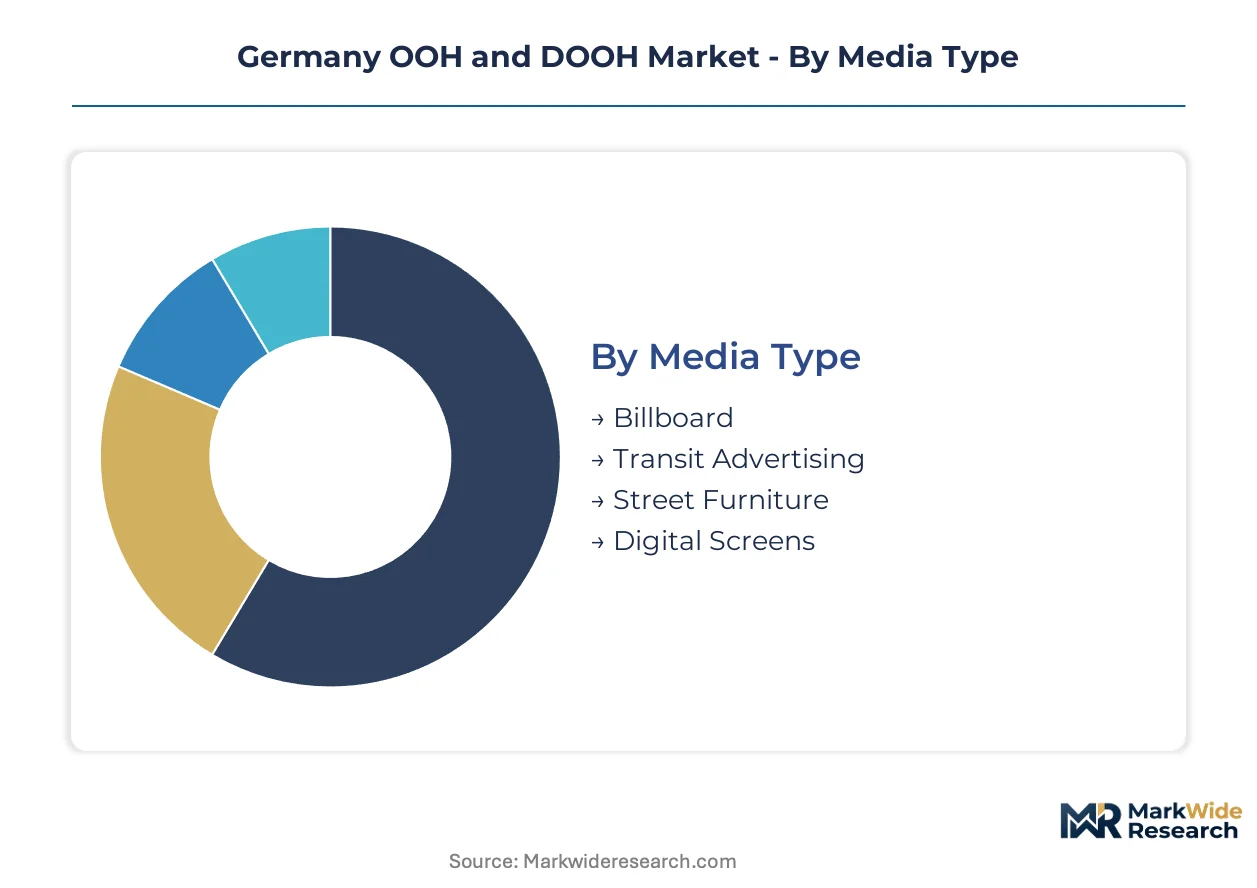
German advertisers fragment budgets across four distinct segmentation axes, each governing different procurement workflows and measurement protocols. Media type determines physical placement rights and regulatory jurisdiction, while ad format governs creative production timelines and dynamic capabilities.
Media Type:
The standardization spectrum runs from municipally regulated street furniture to fully programmatic digital networks, with customization depth expanding toward premium transit concessions.
- Billboard:Large-format roadside structures dominate automotive campaigns along Autobahn corridors, where KBA clearance requirements constrain placement density. Inventory concentrates in Bavaria and Baden-Württemberg, where OEMs maintain regional headquarters and demand sustained visibility.
- Transit Advertising:Exclusive Deutsche Bahn and municipal transport concessions in Berlin and Hamburg deliver captive audiences in high-dwell environments. Premium pricing reflects concession scarcity and verified commuter frequency data.
- Street Furniture:Bus shelters and kiosks offer standardized urban coverage through municipal contracts. Ströer SE & Co. KGaA leverages nationwide agreements to anchor secondary city penetration.
- Digital Screens:Programmatically traded inventory with real-time audience measurement is displacing static commitments in Berlin-Mitte and Hamburg-Altona entertainment districts.
Leading the category by volume: Billboard. Growing fastest: Digital Screens.
Customer Segment:
Cost tier stratification separates mass-market retail flighting from automotive annual commitments and entertainment's event-driven bursts.
- Retail:Seasonal campaigns concentrate in Q4, with grocers and fashion brands dominating Frankfurt and Munich shopping corridors. Dynamic creative optimization enables real-time inventory adjustments based on footfall sensors.
- Automotive:German OEMs anchor the premium tier with programmatic DOOH deployments across digital roadside inventory, pulling budget from static formats toward real-time audience targeting.
- Entertainment:Film studios and streaming platforms drive interactive 3D executions in Berlin's Alexanderplatz and Hamburg's Reeperbahn, where dwell time exceeds transit averages.
- Telecommunications:5G rollout campaigns favor high-frequency digital screen networks in dense urban cores, with shorter booking windows reflecting competitive launch cycles.
Volume leadership sits with Automotive. Steepest expansion trajectory belongs to Entertainment.
Ad Format:
Technology maturity curves separate legacy static production from emerging AR-enabled experiential formats, with margin compression accelerating in the middle tiers.
- Static:Vinyl and paper-based placements retain dominance in rural Autobahn corridors where digital infrastructure remains sparse. Production-to-flight timelines extend to 4-6 weeks.
- Digital:LED and LCD screens with 5,000+ nit daylight visibility command premium rates in Berlin and Hamburg transit hubs. Programmatic trading compresses booking windows to quarterly cycles.
- Interactive:Touch-enabled and motion-sensor formats penetrate retail and entertainment verticals, where engagement metrics justify 40-60% rate premiums over standard digital.
- 3D:Anamorphic executions on curved LED surfaces generate social amplification in high-visibility locations like Munich's Marienplatz, though production costs limit deployment scale.
Static formats still dominate by inventory volume. 3D and interactive combined are climbing the fastest.
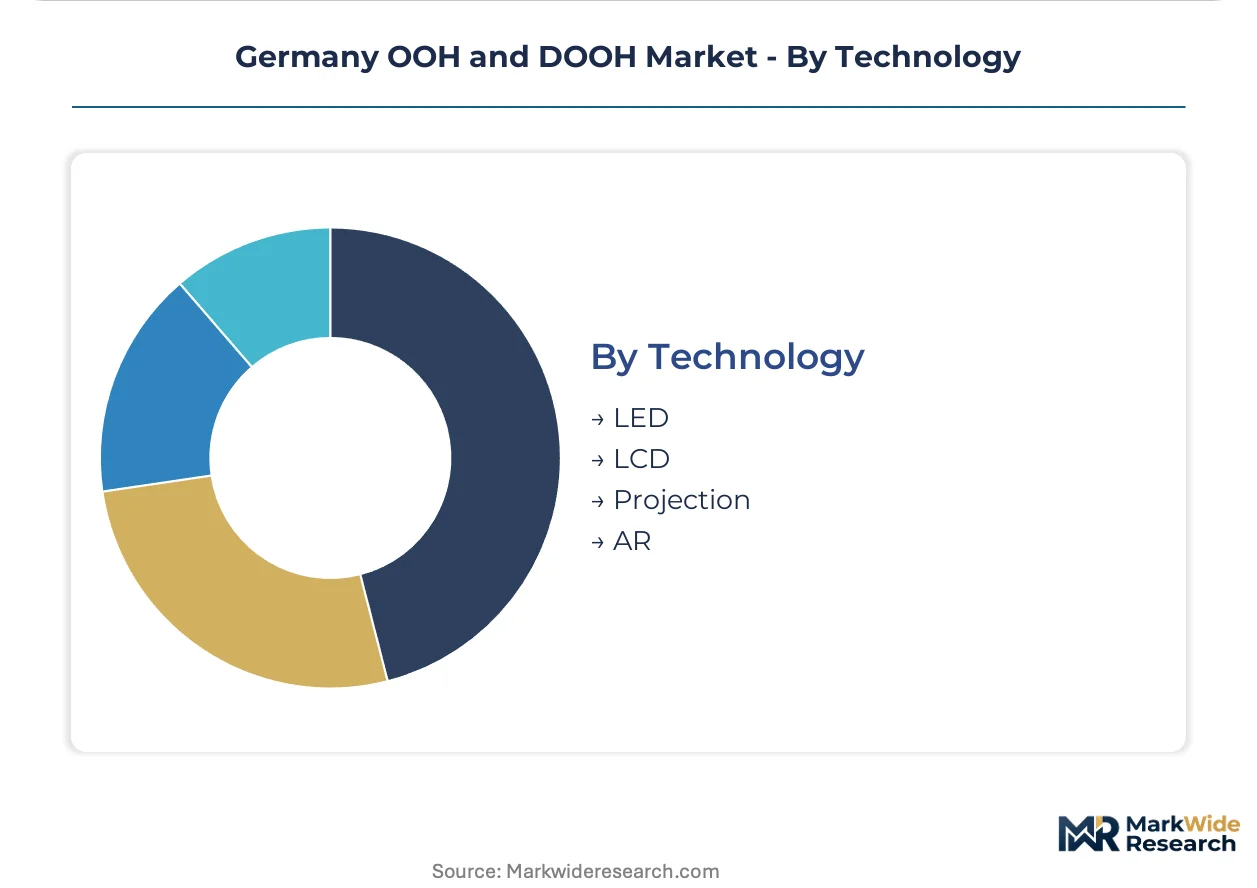
Technology:
Supply concentration varies sharply, with LED module sourcing consolidating among Asian manufacturers while projection systems fragment across European integrators.
- LED:Direct-view displays with high brightness-per-watt ratios dominate new digital installations, driven by EU Green Deal retrofit mandates. Procurement specifications now prioritize energy efficiency alongside luminance.
- LCD:Lower-cost alternative for indoor transit environments where ambient light control permits reduced brightness requirements. Hamburg U-Bahn networks favor this technology for platform-level screens.
- Projection:Temporary and event-based deployments in Cologne and Düsseldorf entertainment districts enable rapid format switching without hardware replacement.
- AR:Smartphone-synchronized overlays remain experimental, with pilot deployments in Berlin retail clusters testing impression-to-visit attribution models.
LED technology leads by installed base. AR represents the nascent frontier with fastest experimental adoption rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's OOH and DOOH market concentrates advertising investment in western industrial corridors while eastern states expand digital infrastructure. Production of display hardware and creative services clusters around major metropolitan advertising hubs. Regional disparities in concession density and transit network maturity shape deployment patterns.
North Rhine-Westphalia
The Rhine-Ruhr metropolitan corridor hosts Germany's densest concentration of roadside digital inventory along Autobahn networks connecting Düsseldorf, Cologne, and Dortmund. The KBA enforces placement clearances that limit screen density near high-speed corridors, constraining premium supply expansion. Automotive advertisers leverage this corridor for sustained visibility between OEM headquarters in Munich-Stuttgart and northern logistics hubs.
Bavaria
Munich anchors premium DOOH demand from automotive and luxury goods advertisers seeking visibility in high-income consumer corridors. Municipal authorities in Bavaria coordinate street furniture digitization through public-private partnerships, accelerating LED retrofit timelines. The city's Marienplatz and central transit nodes host experimental 3D anamorphic executions that generate social amplification.
Baden-Württemberg
Stuttgart's automotive engineering cluster drives programmatic DOOH investment targeting engineering professionals and affluent households. Regional transit authorities in Baden-Württemberg maintain exclusive concession frameworks that limit new entrant access to S-Bahn and U-Bahn networks. Dynamic creative optimization deployments concentrate here, compressing production-to-flight timelines for real-time traffic-responsive campaigns.
Berlin-Brandenburg
Berlin commands the highest transit advertising premiums through exclusive Deutsche Bahn and BVG concessions delivering captive commuter audiences. The EU Green Deal's national implementation pressures municipal operators toward LED retrofits across city-owned bus shelter inventory. Alexanderplatz and Friedrichstraße function as testing grounds for interactive formats targeting entertainment and retail verticals.
Hamburg
Hamburg's port logistics and media industry concentration sustain demand for high-frequency digital screen networks in commercial districts. Transit advertising networks here embed solar-assisted power systems into shelter-based screens, responding fastest to energy efficiency mandates. The Reeperbahn entertainment district hosts premium interactive deployments where dwell time exceeds transit averages.
Germany OOH and DOOH Market Competitive Landscape
The competitive structure tilts toward diversified media conglomerates with nationwide concession portfolios. Three operator archetypes dominate: street furniture specialists holding municipal contracts across secondary cities, transit advertising concessionaires with exclusive railway authority agreements, and roadside billboard operators concentrating on Autobahn corridors. Consolidation pressure intensifies as programmatic trading demands integrated inventory management systems that mid-tier operators struggle to fund.
Among diversified street furniture and digital network operators, Ströer SE & Co. KGaA and JCDecaux SA exemplify contrasting scale strategies. Ströer anchors urban coverage through nationwide municipal agreements, while JCDecaux occupies a position defined by premium transit concessions. Clear Channel Outdoor Deutschland represents the roadside-specialist archetype, sustaining reach into automotive-heavy regions through Autobahn corridor concentration. These three entities collectively illustrate how concession geography and format specialization determine competitive positioning in Germany's regulated OOH environment.
| Leading Market Players |
|---|
| Ströer SE & Co. KGaA |
| JCDecaux SA |
| Clear Channel Outdoor Deutschland |
| blowUP media GmbH |
| Goldbach Group AG |
| Media Frankfurt GmbH |
| WallDecaux |
| PosterSelect GmbH |
| VisionOne GmbH |
| Others |
Pricing and Supply Chain Analysis
Programmatic buying consolidation among German automotive OEMs and retail chains is compressing booking windows and forcing operators to restructure inventory access models, which in turn squeezes margin structures and accelerates capital redeployment toward flexible digital networks.
Pricing Analysis
Cost-down pressure on premium transit inventory accelerates because Deutsche Bahn concession scarcity lets JCDecaux command rate premiums while programmatic trading erodes static roadside margins. Three-tier pricing structure across premium programmatic, standard direct-sold digital, and economy static remnant inventory governs the market. Price differentiation rests on real-time audience verification capabilities and exclusive concession access. Automotive advertisers show lowest price sensitivity; mid-tier regional retailers exhibit highest.
Supply Chain Analysis
EU Green Deal domestic-content mandates for energy-efficient displays are reshaping procurement specifications toward European-assembled LED modules with verified brightness-per-watt ratios. Hardware sourcing concentrates in China, South Korea, and Taiwan for LED modules and driver components. Display assembly draws from aluminum framing, high-nit LED panels, and embedded connectivity chipsets. Single-source vulnerability sits with Asian LED module suppliers. Distribution runs through operator-owned installation networks and municipal concession partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from programmatic infrastructure investments will eliminate mid-tier operators lacking integrated inventory management systems, creating acquisition opportunities for well-capitalized players.
For Market Incumbents: Deepen backward integration into LED module procurement to secure supply continuity and cost control against Asian supplier concentration. Acquire municipal concession portfolios in secondary cities before digitization mandates inflate asset values. Defend against emerging ad-tech platforms by embedding proprietary audience measurement directly into screen networks.
For New Entrants and Emerging Players: Enter via interactive 3D format specialization targeting entertainment and retail verticals where creative premiums offset infrastructure gaps. White-space concentrates in solar-assisted transit shelter deployments responding fastest to EU Green Deal mandates. Go-to-market should anchor on creative technology partnerships rather than concession competition.
For Investors and Strategic Acquirers: The window for entry favors diversified operators with exclusive transit concessions and established programmatic trading infrastructure. Long-term viability hinges on regulatory compliance capabilities and concession renewal track records. Watch for KBA clearance expansion rulings as inflection indicators for premium roadside inventory availability.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Acceleration | EU Green Deal compliance unlocks energy savings reinvestable into expanded digital networks. |
| Programmatic Platform Integration | Real-time audience targeting captures automotive budgets shifting from static formats. |
| Transit Concession Renewal | Exclusive Deutsche Bahn and BVG agreements secure captive commuter access in Berlin. |
| Interactive Format Development | 3D anamorphic executions command 40-60% rate premiums in entertainment districts. |
| Municipal Partnership Expansion | Street furniture digitization in secondary cities builds defensive geographic coverage. |
Research Methodology
Multi-period observation of concession renewal timelines, LED retrofit deployment rates, and programmatic trading penetration anchored the trend analysis, supplemented by interviews with outdoor media network operators, municipal transit authority procurement officers, automotive brand media directors, and retail marketing executives. Secondary validation drew from KBA placement clearance databases, Deutsche Bahn concession disclosures, EU Green Deal implementation reports, and operator financial filings. Bottom-up inventory counts triangulated against top-down advertising spend estimates.
Input-output matrices mapped display hardware costs, concession fee structures, and audience measurement premiums across media type, ad format, customer segment, and regional cluster dimensions. CAGRs derived from fitted growth curves applied to digitization adoption rates and automotive programmatic budget shifts. Forecast inputs included municipal LED retrofit timelines and KBA clearance processing velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU energy mandate enforcement or KBA placement restriction tightening. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
In-Game Advertising Market
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
Philippines OOH and DOOH Market
Advertising and Marketing Media
Teleshopping Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
North America Public Relation Services Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
North America Programmatic Advertisement Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market