
 Piracetam Market | 2026-2036
Piracetam Market Size, Share, and Industry Trends Forecast 2026-2036
Piracetam Market Insights
Post-stroke recovery applications are recalibrating demand patterns across the Piracetam landscape as neurologists integrate the compound into rehabilitation protocols. UCB Pharma anchors European clinical credibility through decades of original research on nootropic mechanisms. CSPC Pharmaceutical Group leverages vertical API manufacturing to control cost positions in Asian supply chains. Hubei Humanwell Pharmaceutical competes on volume scale across domestic hospital tenders.
Piracetam denotes a synthetic derivative of gamma-aminobutyric acid, formulated as a racetam compound with a 2-oxo-1-pyrrolidine acetamide structure, primarily manufactured through cyclization and acetylation processes for cerebral cortex metabolic enhancement. Tablet formulations dominate institutional procurement due to dosing precision and shelf stability, while powder segments attract research institutions requiring protocol flexibility. Cognitive enhancement applications generate premium pricing in direct-to-consumer channels, though treatment of dementia retains the largest volume footprint through healthcare provider networks.
EMA's centralized marketing authorization procedures govern European commercialization, while FDA maintains investigational new drug oversight for any US clinical expansion beyond compounding exemptions. China's NMPA enforces dual carbon-aligned manufacturing audits for API facilities, adding compliance layers for imported materials. India's CDSCO mandates bioequivalence documentation for generic racetam filings, slowing market entry timelines. Stakeholders must monitor evolving nootropic scheduling debates in major economies and pre-position regulatory dossiers ahead of potential reclassification.
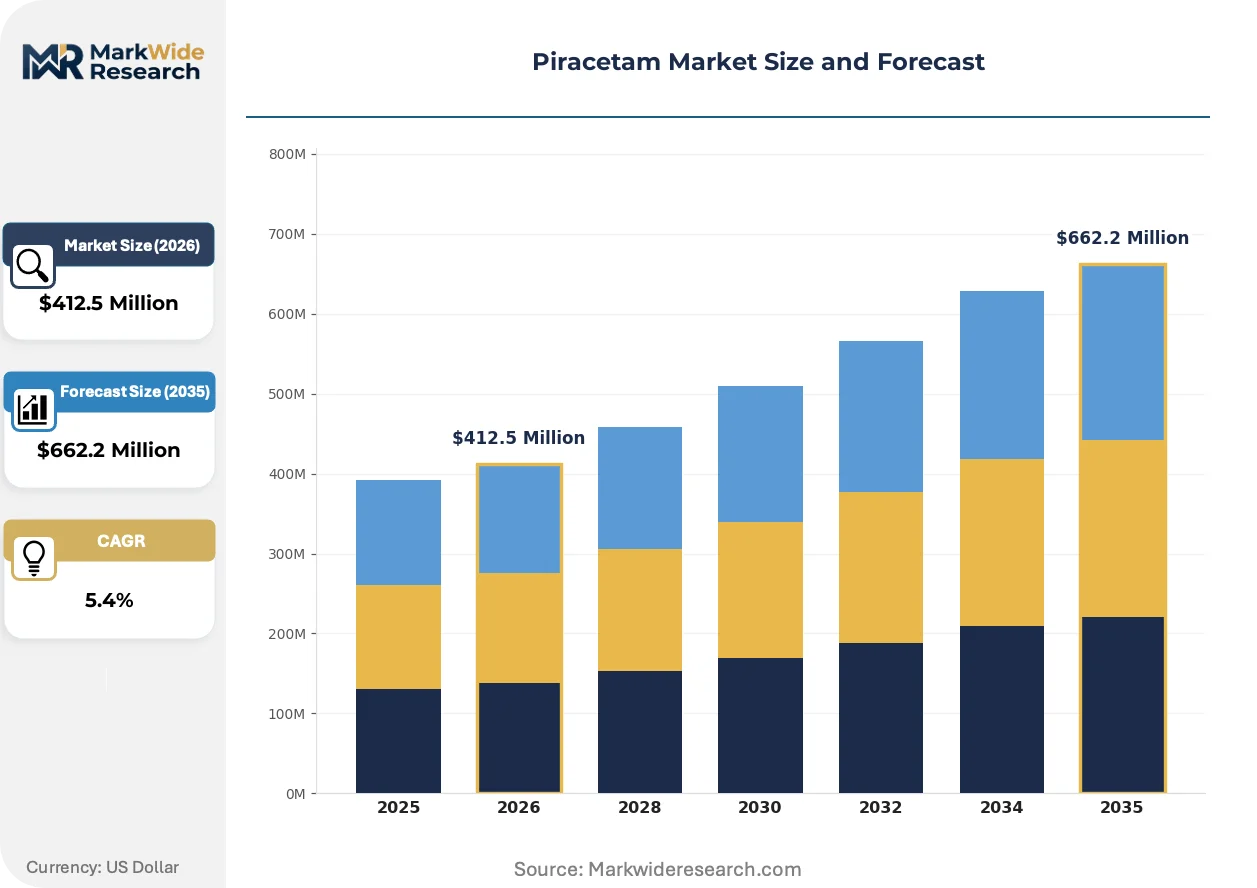
Market Dynamics
Post-stroke rehabilitation protocols are restructuring Piracetam demand as neurologists embed the compound into standardized recovery pathways, while API documentation mandates from China's NMPA and India's CDSCO are elevating compliance costs for cross-border suppliers.
Growth Catalysts
- Post-stroke recovery protocols:Neurology departments in Germany, China, and the United States are integrating Piracetam into rehabilitation guidelines, creating institutional procurement pull through hospital formularies.
- REACH-aligned manufacturing audits:European API facilities completing ECHA registration dossiers gain preferential access to EMA centralized marketing authorization pathways, accelerating commercialization timelines.
- Tablet formulation stability:Extended shelf-life profiles of solid-dose formats reduce hospital inventory carrying costs and minimize cold-chain infrastructure requirements in emerging markets.
Market Restraints
- API concentration in Asian manufacturing clusters:Cyclization and acetylation capacity concentrates in Hubei and Hebei provinces, creating single-source vulnerability for European and North American formulators.
- Bioequivalence documentation burdens:India's CDSCO mandates comparative pharmacokinetic studies for generic racetam filings, extending regulatory review timelines by 18-24 months.
- Off-label prescribing scrutiny:Cognitive enhancement applications face heightened oversight from national pharmacy regulators in France, Germany, and South Korea, constraining direct-to-consumer channel expansion.
Strategic Opportunities
- Dual carbon-aligned facility upgrades:China's NMPA offers expedited review pathways for API manufacturers completing MEE-certified energy efficiency retrofits, creating first-mover advantage for compliant suppliers.
- Powder segment research institutional demand:Academic medical centers in the United States and Switzerland require protocol-flexible bulk formats for investigator-initiated nootropic mechanism studies.
- Hospital tender consolidation:German Krankenhaus procurement alliances are centralizing racetam purchasing through regional pharmacy cooperatives, favoring volume-scale suppliers with GMP-certified documentation packages.
Industry Challenges
- Skilled API synthesis workforce scarcity:Specialized expertise in pyrrolidine cyclization chemistry concentrates at legacy manufacturing sites in Eastern China, constraining capacity expansion at newer facilities.
- Legacy quality management system integration:Mid-scale formulators upgrading from national GMP to PIC/S standards face 12-18 month validation timelines for computerized batch record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piracetam Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Tablet, Capsule, Liquid Application: Cognitive Enhancement, Treatment of Dementia, Anti-Anxiety, Post-Stroke Recovery End User: Healthcare Providers, Research Institutions, Pharmaceuticals, Individual Consumers Distribution Channel: Online Pharmacy, Retail Pharmacy, Healthcare Institutions, Direct Sales |
| Companies Covered | UCB Pharma, CSPC Pharmaceutical Group, Hubei Humanwell Pharmaceutical, Shijiazhuang Pharmaceutical Group, Shanghai Fosun Pharmaceutical, China Resources Sanjiu Medical & Pharmaceutical, Sihuan Pharmaceutical Holdings Group, Yunnan Baiyao Group, Livzon Pharmaceutical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piracetam Market Trends and Innovations
Continuous manufacturing technologies and real-time release testing protocols are compressing production cycles for racetam compounds, while regulatory convergence around carbon-aligned API documentation is reshaping supplier qualification criteria across major economies.
Continuous direct compression systems are unifying granulation, blending, and tableting operations into single-line configurations for Piracetam solid-dose production. European contract manufacturers are adopting these platforms to reduce batch-to-batch variability and shorten release timelines. This technology is unifying quality assurance workflows by embedding near-infrared spectroscopy for at-line potency verification, eliminating traditional wet chemistry hold times.
China's NMPA dual carbon manufacturing audit framework is mandating energy consumption disclosures and renewable power sourcing verification for API facility inspections. Domestic manufacturers in Hebei province are retrofitting steam and electricity systems to meet MEE-aligned efficiency benchmarks ahead of 2025 enforcement windows. Imported materials face heightened scrutiny as NMPA inspectors cross-reference SAMR carbon intensity data against facility energy certificates.
Hospital pharmacy cooperatives in Germany and Switzerland are consolidating racetam purchasing through centralized tender platforms, displacing fragmented wholesaler relationships. These alliances negotiate multi-year supply agreements with API-integrated formulators, prioritizing documentation transparency over unit price. The shift is most visible in Baden-Württemberg and Bavaria, where regional Krankenhausverbände have standardized on EMA-certified suppliers with REACH-registered manufacturing sites.
Piracetam Market Segmentation
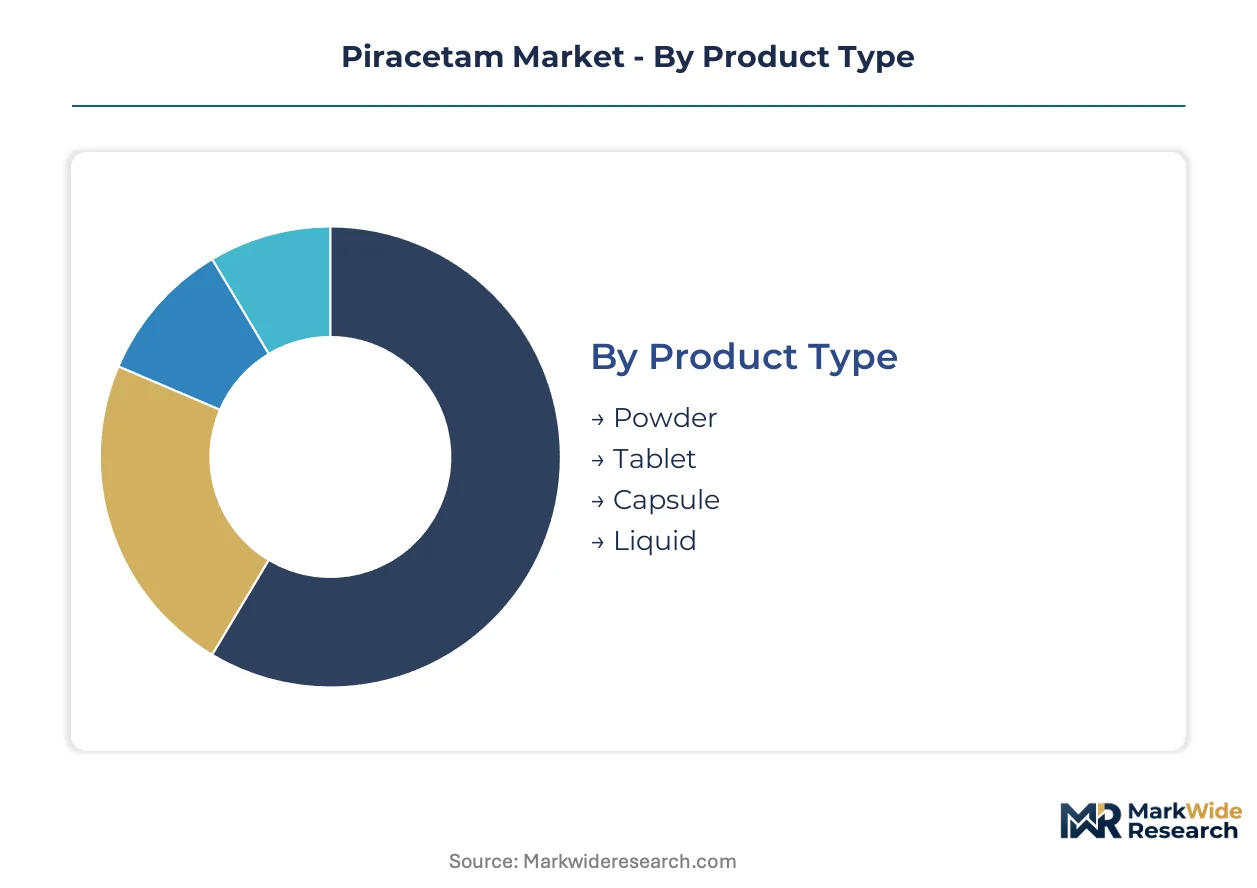
Piracetam procurement patterns diverge sharply across formulation types and buyer categories. Hospital formularies prioritize shelf-stable solid doses, while research protocols demand bulk powder flexibility.
Product Type:
Procurement officers weigh stability against protocol flexibility when selecting formulations for their specific use environments.
- Tablet:Solid-dose formats incorporate precise 400mg and 800mg unit doses with film coatings for gastric protection. German hospital pharmacy cooperatives in Baden-Württemberg and Bavaria standardize procurement on these formats to minimize cold-chain infrastructure and reduce inventory carrying costs through extended stability profiles.
- Powder:Bulk crystalline material offers protocol-flexible dosing for investigator-initiated studies. Academic medical centers in Switzerland and the United States source kilogram-scale quantities for nootropic mechanism research, though this segment faces heightened customs scrutiny at ports of entry.
- Capsule:Gelatin and HPMC shell formats bridge institutional and consumer channels with intermediate stability characteristics.
- Liquid:Aqueous and ethanol-based solutions serve pediatric and dysphagia patient populations with modified dosing precision.
Volume sits with Tablet; growth tilts toward Powder.
Application:
Clinical reimbursement pathways determine which indications attract manufacturing investment and regulatory dossier preparation.
- Post-Stroke Recovery:Neurology departments embed Piracetam into standardized rehabilitation protocols for cerebral metabolism enhancement. Hospital formularies in Germany, China, and the United States drive institutional procurement through evidence-based guideline integration.
- Treatment of Dementia:Prescribing for vascular and mixed dementia subtypes generates the largest absolute volume through healthcare provider networks. EMA centralized marketing authorization pathways govern European commercialization for this indication.
- Cognitive Enhancement:Off-label nootropic use attracts premium pricing in direct-to-consumer channels. ANSM in France and MFDS in South Korea impose heightened pharmacy oversight, constraining expansion.
- Anti-Anxiety:Adjunctive racetam prescribing for GAD and social anxiety protocols remains limited to specialized psychiatric practices.
Revenue concentrates in Treatment of Dementia; Cognitive Enhancement commands the steepest expansion trajectory.
End User:
Documentation requirements and purchasing scale separate institutional buyers from fragmented consumer demand.
- Healthcare Providers:Hospital systems and neurology clinics generate predictable volume through tender-based procurement with multi-year supply agreements.
- Research Institutions:Academic medical centers require GMP-certified materials with batch-specific certificates of analysis for IRB-approved protocols.
- Pharmaceuticals:Generic formulators and CMOs source API for in-house finished-dose production.
- Individual Consumers:Direct-to-patient channels face regulatory friction from national pharmacy regulators limiting nootropic accessibility.
Procurement scale favors Healthcare Providers; Research Institutions are gaining share fastest.
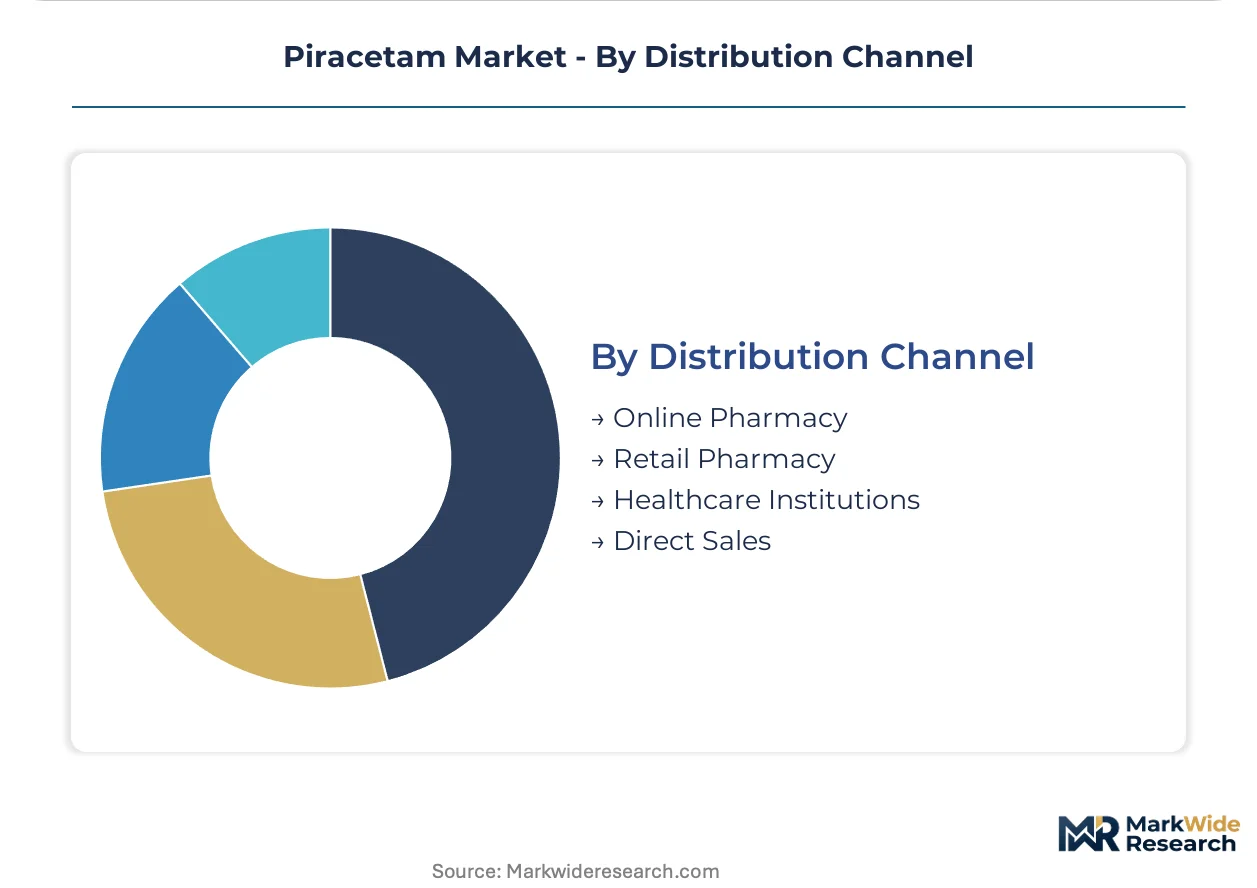
Distribution Channel:
Channel selection determines compliance burden and margin capture for suppliers navigating divergent regulatory environments.
- Healthcare Institutions:Direct contracting with hospital pharmacy cooperatives eliminates wholesaler markups. German Krankenhausverbände centralize racetam purchasing through regional tender platforms.
- Retail Pharmacy:Community pharmacies dispense against neurologist prescriptions with national reimbursement code variations.
- Online Pharmacy:Cross-border e-commerce faces customs classification challenges and API documentation requirements from China's NMPA and India's CDSCO.
- Direct Sales:Manufacturer-to-consumer channels concentrate in jurisdictions with permissive nootropic scheduling.
Contract value pools in Healthcare Institutions; Online Pharmacy faces the tightest regulatory compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hebei province's pharmaceutical industrial parks are concentrating cyclization and acetylation capacity under China's dual carbon policy framework, drawing API manufacturers toward MEE-certified zones with expedited NMPA review pathways.
China
Hospital procurement in Jiangsu and Guangdong provinces is absorbing tablet volumes for post-stroke rehabilitation protocols. NMPA enforces dual carbon-aligned manufacturing audits for API facilities, cross-referencing SAMR carbon intensity data against facility energy certificates. Hebei province manufacturers in Shijiazhuang and Baoding are retrofitting steam systems to meet 2025 MEE efficiency benchmarks.
Germany
Baden-Württemberg and Bavaria Krankenhausverbände are consolidating racetam purchasing through regional pharmacy cooperatives. EMA centralized marketing authorization procedures govern commercialization, while ECHA REACH registration dossiers determine API supplier qualification. Stuttgart and Munich hospital systems are standardizing on EMA-certified suppliers with documented carbon footprints.
United States
Academic medical centers in Massachusetts and California are sourcing powder-format Piracetam for investigator-initiated nootropic mechanism studies. FDA maintains investigational new drug oversight for clinical expansion beyond compounding exemptions. Boston and San Francisco research institutions require GMP-certified materials with batch-specific certificates of analysis for IRB-approved protocols.
India
Generic formulators in Gujarat and Maharashtra are navigating CDSCO bioequivalence documentation requirements for racetam filings. CDSCO mandates comparative pharmacokinetic studies, extending regulatory review timelines by 18-24 months. Ahmedabad and Mumbai manufacturing clusters are building in-house bioanalytical capacity to accelerate dossier preparation.
Switzerland
Swissmedic oversight governs hospital pharmacy procurement in Zurich and Geneva cantons for dementia treatment applications. Academic medical centers in Basel are importing powder quantities for nootropic research under strict customs classification protocols. Swiss hospital purchasing alliances are prioritizing suppliers with PIC/S-certified quality management systems.
Piracetam Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with API-integrated formulators capturing hospital tender volumes while pure-play research suppliers serve institutional powder demand. The vendor base organizes around three archetypes: legacy European research originators, vertically integrated Chinese pharmaceutical groups, and mid-scale generic formulators upgrading to international GMP standards. Capacity expansion and regulatory dossier pre-positioning represent the dominant competitive vectors as scheduling debates intensify in major economies.
Within the legacy originator tier, UCB Pharma anchors European clinical credibility through decades of racetam mechanism research. Among Asia-Pacific API-integrated manufacturers, CSPC Pharmaceutical Group exemplifies vertical control over cyclization and acetylation supply chains, while Hubei Humanwell Pharmaceutical occupies a position calibrated to domestic hospital tender scale. These three entities represent distinct strategic postures: research-driven clinical validation, upstream manufacturing integration, and volume-scale procurement responsiveness.
| Leading Market Players |
|---|
| UCB Pharma |
| CSPC Pharmaceutical Group |
| Hubei Humanwell Pharmaceutical |
| Shijiazhuang Pharmaceutical Group |
| Shanghai Fosun Pharmaceutical |
| China Resources Sanjiu Medical & Pharmaceutical |
| Sihuan Pharmaceutical Holdings Group |
| Yunnan Baiyao Group |
| Livzon Pharmaceutical Group |
| Others |
Pricing and Supply Chain Analysis
Cyclization-grade pyrrolidine feedstock costs cascade through Hebei province manufacturing clusters into three distinct procurement tiers for hospital formularies, research institutions, and compounding pharmacies downstream.
Pricing Analysis
Short lead-time premiums of 15-25% apply to spot tablet orders from German Krankenhausverbände facing formulary restocking deadlines, while powder-format contracts with Swiss and US academic centers command standard pricing with 90-day fulfillment windows. Three-tier pricing structure across EMA-certified premium, PIC/S-standard, and domestic-GMP economy levels separates suppliers by documentation depth. Pricing pressure stems from India's CDSCO bioequivalence mandates extending generic racetam approval timelines. Hospital pharmacy cooperatives exhibit lowest price sensitivity due to multi-year tender security; individual consumers in direct channels face highest elasticity.
Supply Chain Analysis
Reverse logistics for expired tablet returns and API batch recalls flow through regional distribution hubs in Stuttgart and Singapore before carbon-intensive destruction or reprocessing at MEE-certified Hebei facilities. Cyclization and acetylation capacity concentrates in China's Hebei and Hubei provinces, with secondary synthesis sites in Gujarat, India. Pyrrolidine feedstock, acetic anhydride, and specialized catalytic reagents constitute critical input dependencies. Single-source vulnerability pervades European and North American formulators dependent on Asian API clusters. Distribution runs through hospital pharmacy cooperatives in Germany, direct institutional contracting in China, and wholesaler networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where China's NMPA dual carbon audit framework erects regulatory moats favoring API-integrated manufacturers with MEE-certified energy retrofits.
For Market Incumbents: Lock in hospital tender volumes through multi-year supply agreements with German Krankenhausverbände and Chinese provincial procurement platforms. Deepen backward integration into pyrrolidine feedstock production to offset cyclization-grade material cost volatility. Pre-position REACH-registered dossiers ahead of potential EMA scheduling reviews for nootropic compounds.
For New Entrants and Emerging Players: Enter via powder-format supply to US and Swiss academic medical centers requiring GMP-certified materials for investigator-initiated protocols. Target research institutional channels where documentation transparency outweighs scale economies. Pursue CDSCO bioequivalence partnerships with established Indian formulators to bypass 18-24 month standalone approval timelines.
For Investors and Strategic Acquirers: NMPA expedited review pathway announcements for MEE-certified facilities signal that API-integrated manufacturers with carbon-aligned operations will capture disproportionate share expansion. Position for 5-10 year consolidation around vertically controlled supply chains. Monitor CDSCO bioequivalence study completion rates as the leading indicator of generic racetam approval velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Carbon Facility Certification | NMPA expedited review pathways reward MEE-certified Hebei manufacturers with 6-12 month approval advantages. |
| Hospital Tender Consolidation | German Krankenhausverbände centralization favors suppliers with REACH-registered manufacturing and EMA marketing authorization. |
| Bioequivalence Capacity Buildout | Indian formulators investing in in-house bioanalytical laboratories accelerate CDSCO dossier preparation timelines. |
| Research Institutional Channel Development | US academic medical centers require GMP-certified powder formats with batch-specific certificates of analysis. |
| Continuous Manufacturing Technology Adoption | European contract manufacturers deploying direct compression systems reduce batch-to-batch variability and release hold times. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving API manufacturing executives, hospital pharmacy procurement directors, regulatory affairs specialists at NMPA and CDSCO, and neurology department formulary managers. FDA investigational new drug databases, EMA centralized marketing authorization registers, ClinicalTrials.gov protocol records, and SAMR carbon intensity disclosures supplied quantitative validation. Bottom-up tablet and powder volume estimates from hospital tender platforms reconciled with top-down API production capacity assessments across Hebei and Gujarat manufacturing clusters.
Data-stream reconciliation combined patient-flow modeling for post-stroke rehabilitation protocols with API manufacturing capacity utilization rates across the projection horizon. Segmentation dimensions encompassed formulation type, clinical application, end-user category, and distribution channel, with regional regulatory cluster overlays for NMPA, EMA, FDA, and CDSCO jurisdictions. CAGRs derived from trend-line extrapolation of hospital procurement volumes and research institutional powder demand, calibrated against cyclization capacity expansion announcements and carbon-aligned facility retrofit timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA scheduling reclassification or EMA nootropic compound review initiation. Practitioners should monitor CDSCO bioequivalence study submission volumes and NMPA MEE certification award rates for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutraceuticals
Global Nicotinamide Mononucleotide (NMN) Market
Nutraceuticals
Middle East and Africa Effervescent Tablet Market
Nutraceuticals
North America OTC Health Products Market
Nutraceuticals
Marine Olive Collagen Hybrid Nutricosmetic Systems Market
Nutraceuticals
Hydrolyzed Bovine Collagen Market
Nutraceuticals
North America Nutraceuticals Market
Nutraceuticals
Chondroitin Sulfate Market
Nutraceuticals
US Collagen Market
Nutraceuticals
Native Collagen Market
Nutraceuticals
Europe Nutricosmetics Market
Nutraceuticals
High Potency Apis Market
Nutraceuticals
Eggshell Membrane Market
Nutraceuticals
Immunostimulants Market
Nutraceuticals
Nattokinase Market
Nutraceuticals
Global Eye Health Supplement Market
Nutraceuticals
Cognitive Health Ingredients Market